Chapter 6 Annual Worth Analysis Lecture slides to
- Slides: 9
Chapter 6 Annual Worth Analysis Lecture slides to accompany Engineering Economy 7 th edition Leland Blank Anthony Tarquin 6 -1 © 2012 by Mc. Graw-Hill, New York, N. Y All Rights Reserved
LEARNING OUTCOMES 1. Advantages of AW 2. CR and AW values 3. AW analysis 4. Perpetual life 5. LCC analysis 6 -2 © 2012 by Mc. Graw-Hill, New York, N. Y All Rights Reserved
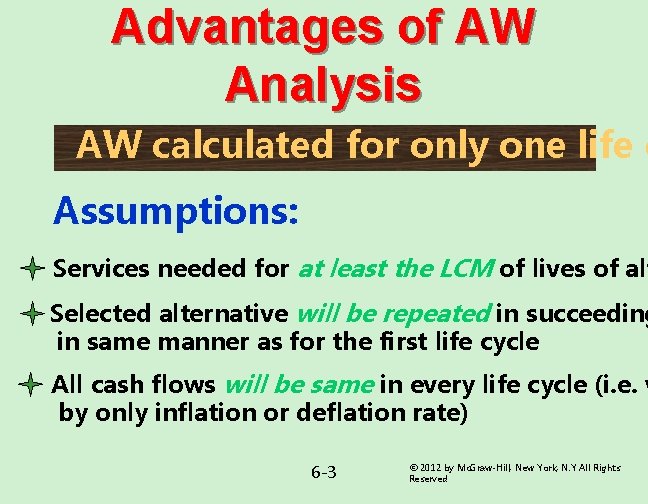
Advantages of AW Analysis AW calculated for only one life c Assumptions: Services needed for at least the LCM of lives of alt Selected alternative will be repeated in succeeding in same manner as for the first life cycle All cash flows will be same in every life cycle (i. e. w by only inflation or deflation rate) 6 -3 © 2012 by Mc. Graw-Hill, New York, N. Y All Rights Reserved
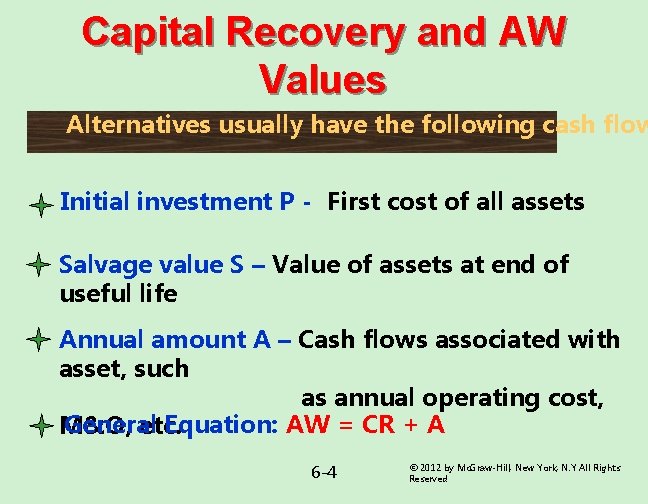
Capital Recovery and AW Values Alternatives usually have the following cash flow Initial investment P - First cost of all assets Salvage value S – Value of assets at end of useful life Annual amount A – Cash flows associated with asset, such as annual operating cost, General Equation: AW = CR + A M&O, etc. 6 -4 © 2012 by Mc. Graw-Hill, New York, N. Y All Rights Reserved
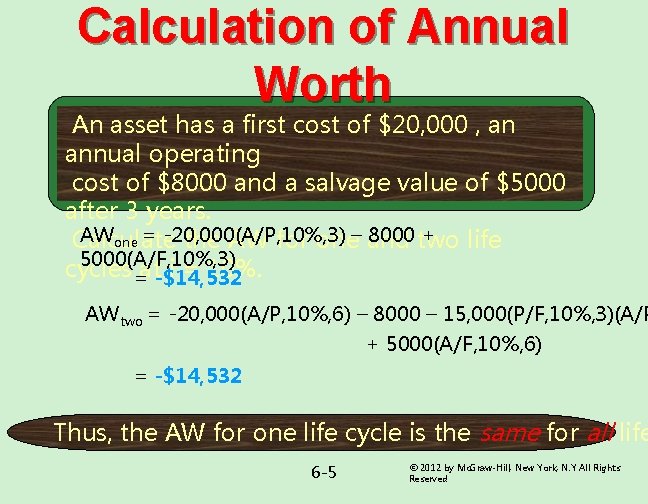
Calculation of Annual Worth An asset has a first cost of $20, 000 , an annual operating cost of $8000 and a salvage value of $5000 after 3 years. AWone = -20, 000(A/P, 10%, 3) 8000 two + Calculate the AW for one– and life 5000(A/F, 10%, 3) cycles i = 10%. =at-$14, 532 AWtwo = -20, 000(A/P, 10%, 6) – 8000 – 15, 000(P/F, 10%, 3)(A/P + 5000(A/F, 10%, 6) = -$14, 532 Thus, the AW for one life cycle is the same for all life 6 -5 © 2012 by Mc. Graw-Hill, New York, N. Y All Rights Reserved
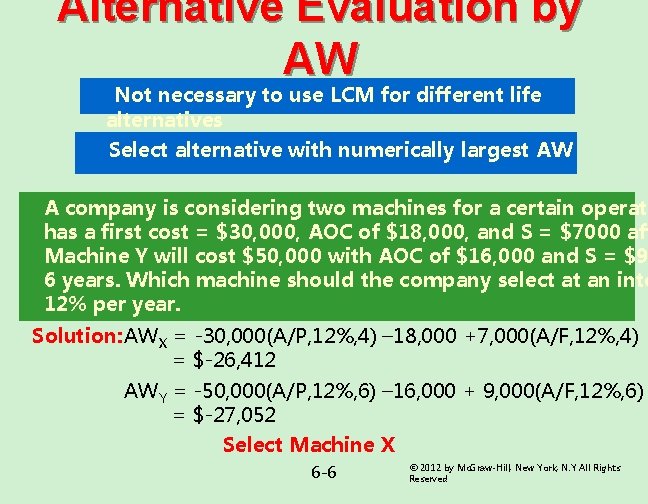
Alternative Evaluation by AW Not necessary to use LCM for different life alternatives Select alternative with numerically largest AW A company is considering two machines for a certain operati has a first cost = $30, 000, AOC of $18, 000, and S = $7000 aft Machine Y will cost $50, 000 with AOC of $16, 000 and S = $9 6 years. Which machine should the company select at an inte 12% per year. Solution: AWX = -30, 000(A/P, 12%, 4) – 18, 000 +7, 000(A/F, 12%, 4) = $-26, 412 AWY = -50, 000(A/P, 12%, 6) – 16, 000 + 9, 000(A/F, 12%, 6) = $-27, 052 Select Machine X 6 -6 © 2012 by Mc. Graw-Hill, New York, N. Y All Rights Reserved
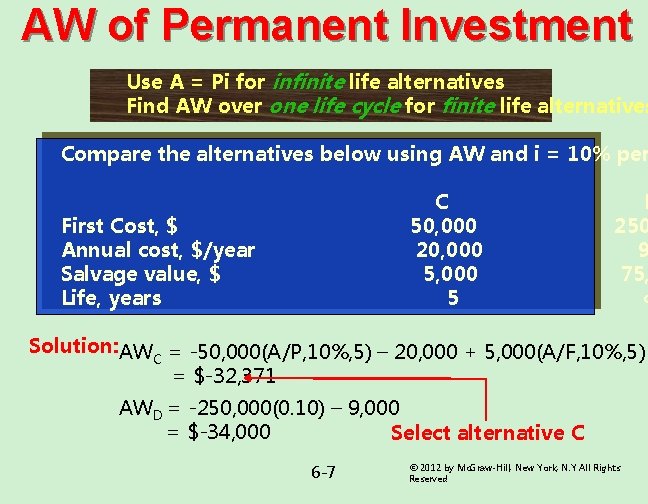
AW of Permanent Investment Use A = Pi for infinite life alternatives Find AW over one life cycle for finite life alternatives Compare the alternatives below using AW and i = 10% per C 50, 000 20, 000 5 First Cost, $ Annual cost, $/year Salvage value, $ Life, years D 250 9 75, ∞ Solution: AW = -50, 000(A/P, 10%, 5) – 20, 000 + 5, 000(A/F, 10%, 5) C = $-32, 371 AWD = -250, 000(0. 10) – 9, 000 = $-34, 000 Select alternative C 6 -7 © 2012 by Mc. Graw-Hill, New York, N. Y All Rights Reserved
Life-Cycle Cost Analysis LCC analysis includes all costs for entire life cycl Best when large percentage of costs are O & M Includes phases of acquisition, operation, & phase 6 -8 © 2012 by Mc. Graw-Hill, New York, N. Y All Rights Reserved
Summary of Important Points AW method converts all cash flows to annual valu Alternatives can be mutually exclusive, independe revenue, or service AW comparison made for only one life cycle of ea For infinite life alts, annualize initial cost as P * i Life-cycle cost analysis includes all costs of projec 6 -9 © 2012 by Mc. Graw-Hill, New York, N. Y All Rights Reserved