Chapter 2 Analysis of Solvency Liquidity and Financial

- Slides: 21
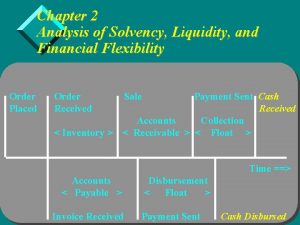
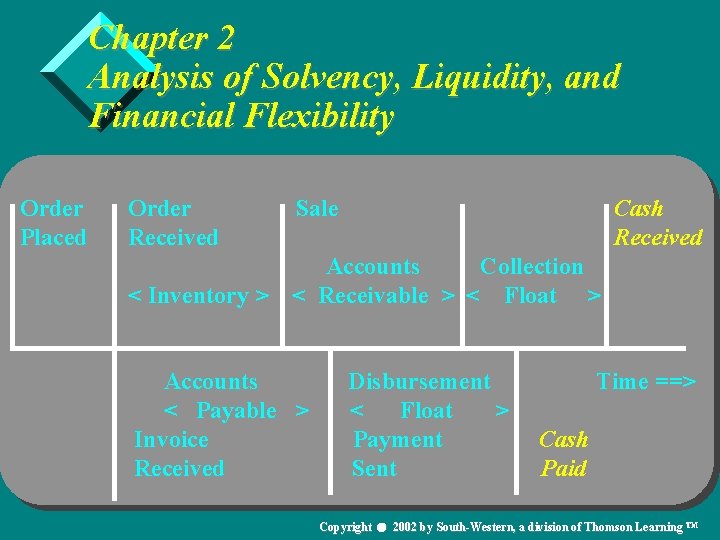
Chapter 2 Analysis of Solvency, Liquidity, and Financial Flexibility Order Placed Order Received Sale Cash Received Accounts Collection < Inventory > < Receivable > < Float > Accounts < Payable > Invoice Received Disbursement < Float > Payment Sent Time ==> Cash Paid Copyright 2002 by South-Western, a division of Thomson Learning TM
Learning Objectives v Differentiate between solvency and liquidity ratios v Conduct a liquidity analysis v Assess a firm’s financial flexibility position Copyright 2002 by South-Western, a division of Thomson Learning TM
Financial Statements - Basic Source of Information v Balance Sheet v Income Statement v Statement of Cash Flows Copyright 2002 by South-Western, a division of Thomson Learning TM
Solvency Measures v Current Ratio v Quick Ratio v Net Working Capital v Net Liquid Balance v Working Capital Requirements Copyright 2002 by South-Western, a division of Thomson Learning TM
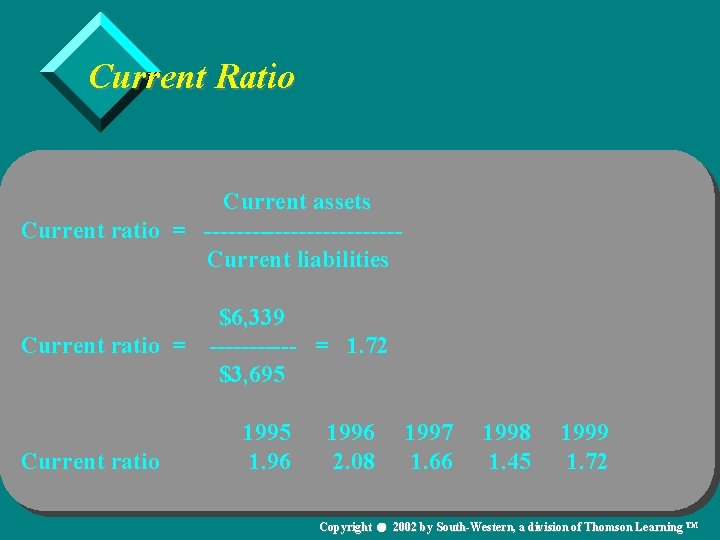
Current Ratio Current assets Current ratio = ------------Current liabilities $6, 339 Current ratio = ------ = 1. 72 $3, 695 Current ratio 1995 1. 96 1996 2. 08 1997 1. 66 1998 1. 45 1999 1. 72 Copyright 2002 by South-Western, a division of Thomson Learning TM
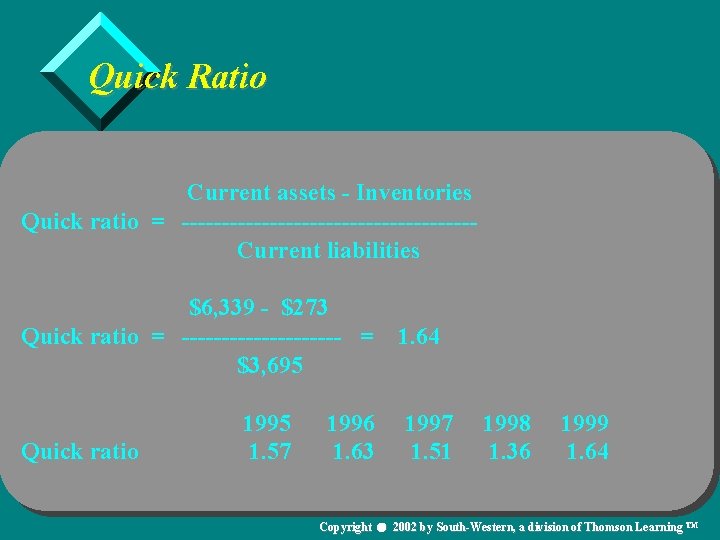
Quick Ratio Current assets - Inventories Quick ratio = ------------------Current liabilities $6, 339 - $273 Quick ratio = ---------- = 1. 64 $3, 695 Quick ratio 1995 1. 57 1996 1. 63 1997 1. 51 1998 1. 36 1999 1. 64 Copyright 2002 by South-Western, a division of Thomson Learning TM
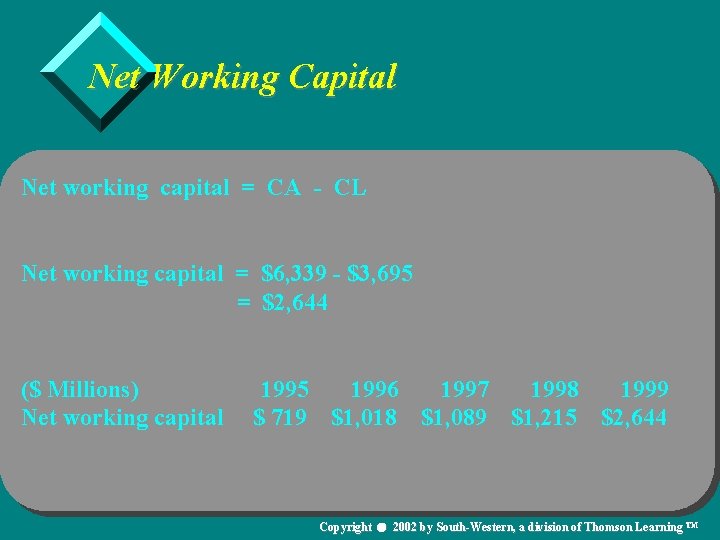
Net Working Capital Net working capital = CA - CL Net working capital = $6, 339 - $3, 695 = $2, 644 ($ Millions) Net working capital 1995 1996 1997 1998 1999 $ 719 $1, 018 $1, 089 $1, 215 $2, 644 Copyright 2002 by South-Western, a division of Thomson Learning TM
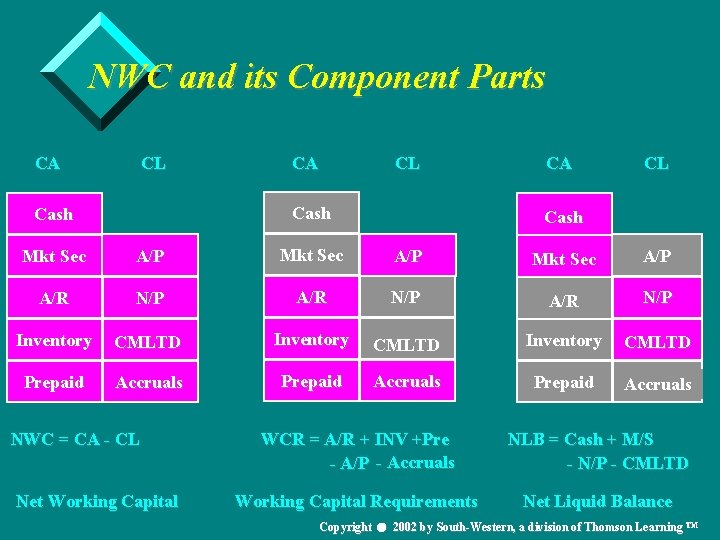
NWC and its Component Parts CA CL Cash Mkt Sec A/P A/R N/P Inventory CMLTD Prepaid Accruals NWC = CA - CL Net Working Capital WCR = A/R + INV +Pre - A/P - Accruals NLB = Cash + M/S - N/P - CMLTD Working Capital Requirements Net Liquid Balance Copyright 2002 by South-Western, a division of Thomson Learning TM
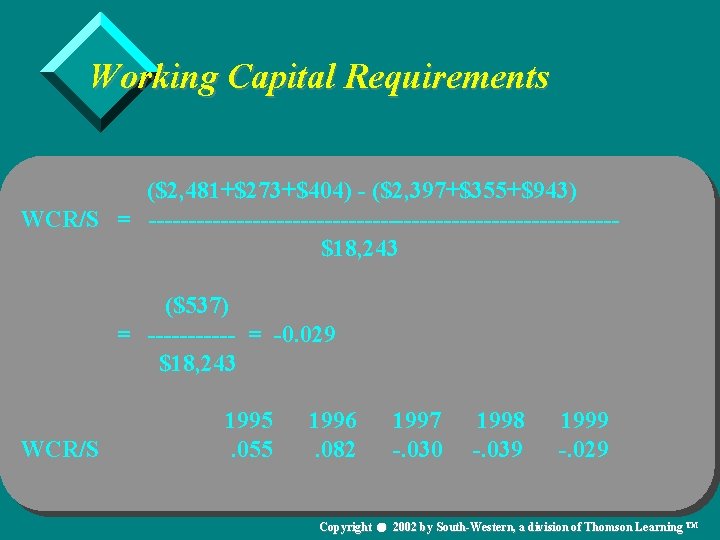
Working Capital Requirements ($2, 481+$273+$404) - ($2, 397+$355+$943) WCR/S = -----------------------------$18, 243 ($537) = ------ = -0. 029 $18, 243 WCR/S 1995. 055 1996. 082 1997 -. 030 1998 -. 039 1999 -. 029 Copyright 2002 by South-Western, a division of Thomson Learning TM
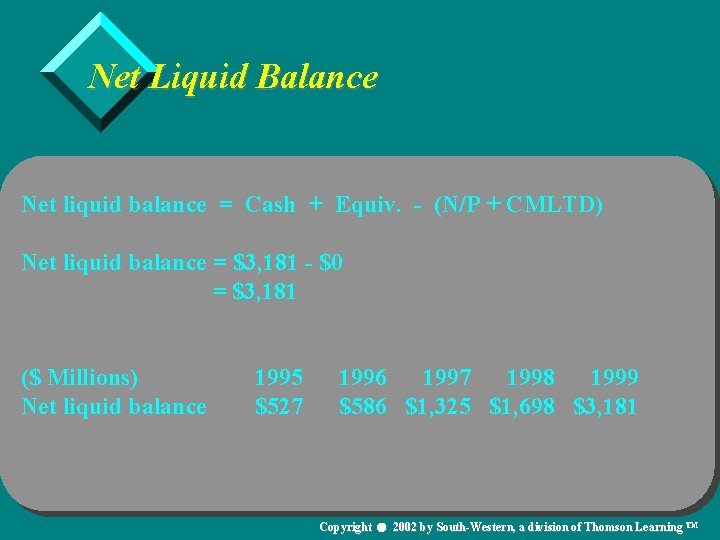
Net Liquid Balance Net liquid balance = Cash + Equiv. - (N/P + CMLTD) Net liquid balance = $3, 181 - $0 = $3, 181 ($ Millions) Net liquid balance 1995 $527 1996 1997 1998 1999 $586 $1, 325 $1, 698 $3, 181 Copyright 2002 by South-Western, a division of Thomson Learning TM
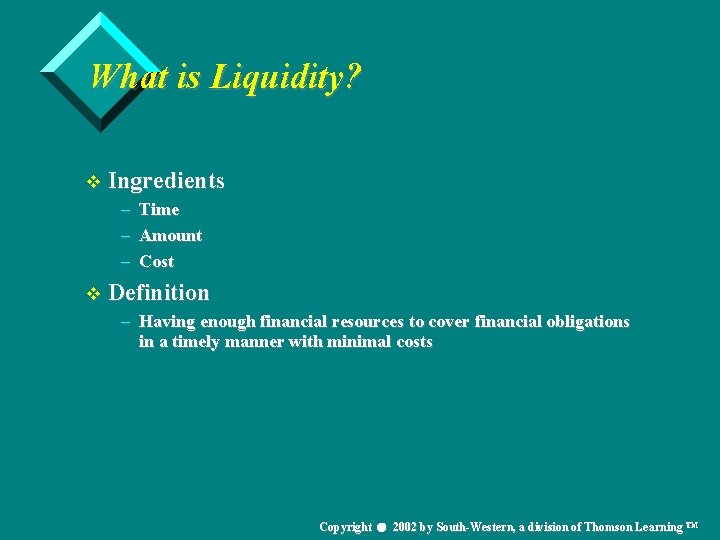
What is Liquidity? v Ingredients – Time – Amount – Cost v Definition – Having enough financial resources to cover financial obligations in a timely manner with minimal costs Copyright 2002 by South-Western, a division of Thomson Learning TM
What is Liquidity - Examples v Amount and trend of internal cash flow v Aggregate available credit lines v Attractiveness of firm’s commercial paper and other financial instruments v Overall expertise of management Copyright 2002 by South-Western, a division of Thomson Learning TM
Liquidity Measures v Cash Flow From Operations v Cash Conversion Period v Current Liquidity Index v Lambda Copyright 2002 by South-Western, a division of Thomson Learning TM
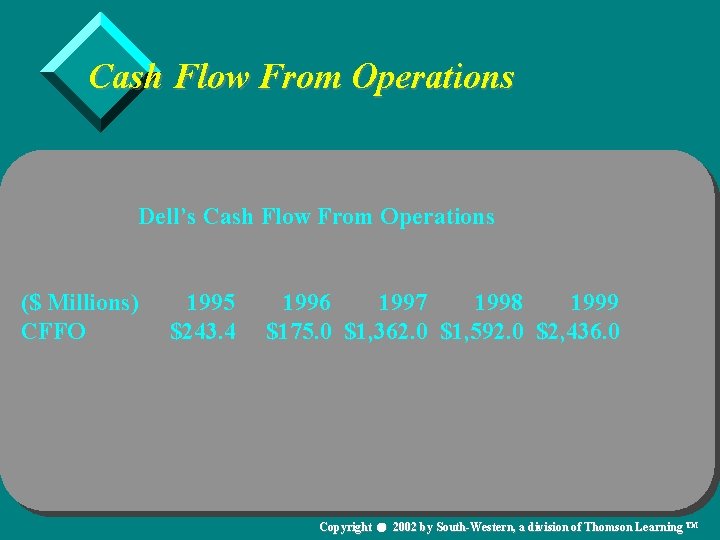
Cash Flow From Operations Dell’s Cash Flow From Operations ($ Millions) CFFO 1995 $243. 4 1996 1997 1998 1999 $175. 0 $1, 362. 0 $1, 592. 0 $2, 436. 0 Copyright 2002 by South-Western, a division of Thomson Learning TM
Cash Conversion Chart Inventory stocked Inventory sold Days inventory held Days payables outstanding Cash received Days sales outstanding Cash conversion period Cash disbursed Copyright 2002 by South-Western, a division of Thomson Learning TM
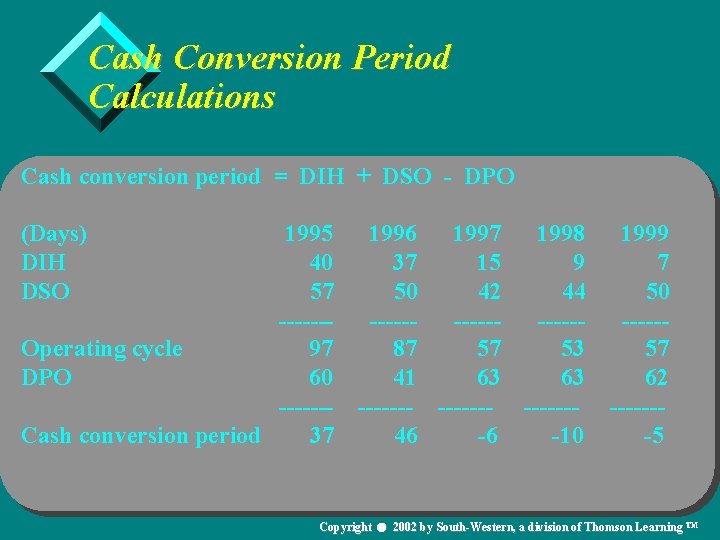
Cash Conversion Period Calculations Cash conversion period = DIH + DSO - DPO (Days) DIH DSO 1995 1996 1997 1998 1999 40 37 15 9 7 57 50 42 44 50 -------------Operating cycle 97 87 57 53 57 DPO 60 41 63 63 62 ------- ------Cash conversion period 37 46 -6 -10 -5 Copyright 2002 by South-Western, a division of Thomson Learning TM
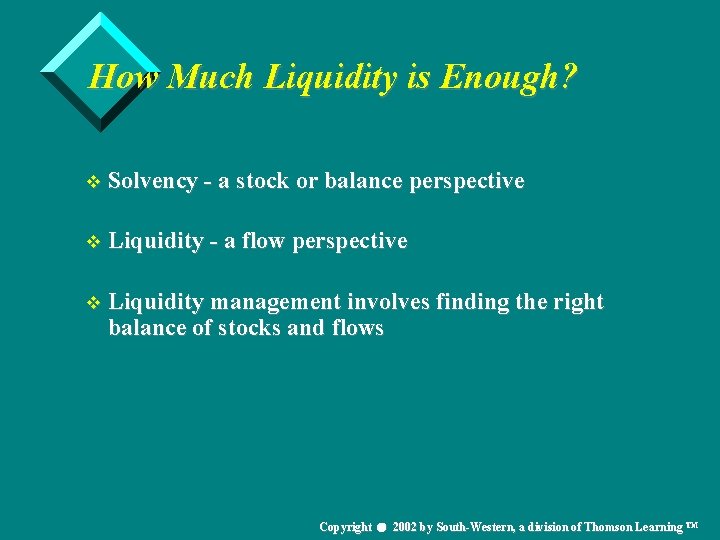
How Much Liquidity is Enough? v Solvency - a stock or balance perspective v Liquidity - a flow perspective v Liquidity management involves finding the right balance of stocks and flows Copyright 2002 by South-Western, a division of Thomson Learning TM
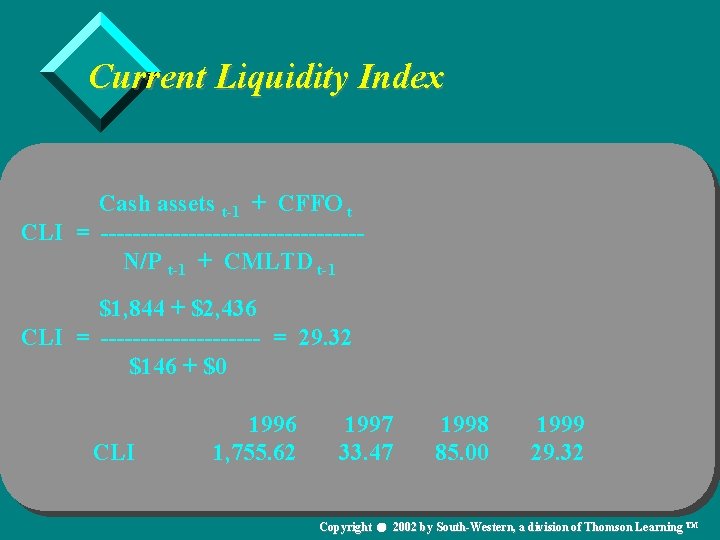
Current Liquidity Index Cash assets t-1 + CFFO t CLI = ----------------N/P t-1 + CMLTD t-1 $1, 844 + $2, 436 CLI = ---------- = 29. 32 $146 + $0 CLI 1996 1, 755. 62 1997 33. 47 1998 85. 00 1999 29. 32 Copyright 2002 by South-Western, a division of Thomson Learning TM
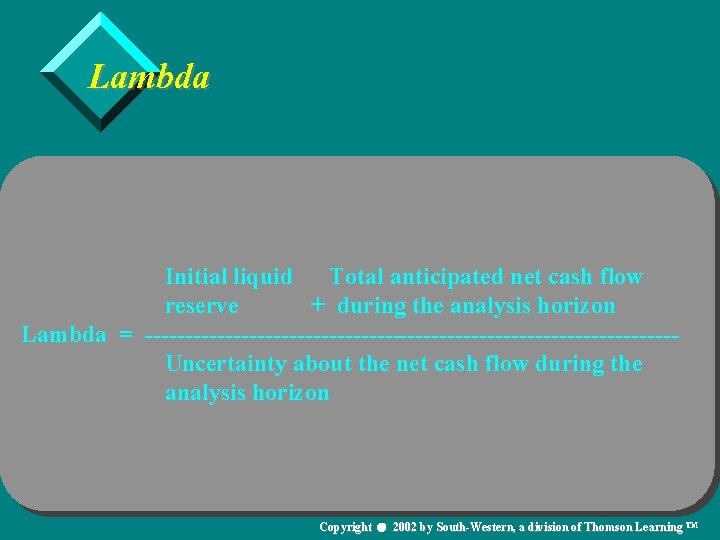
Lambda Initial liquid Total anticipated net cash flow reserve + during the analysis horizon Lambda = ---------------------------------Uncertainty about the net cash flow during the analysis horizon Copyright 2002 by South-Western, a division of Thomson Learning TM
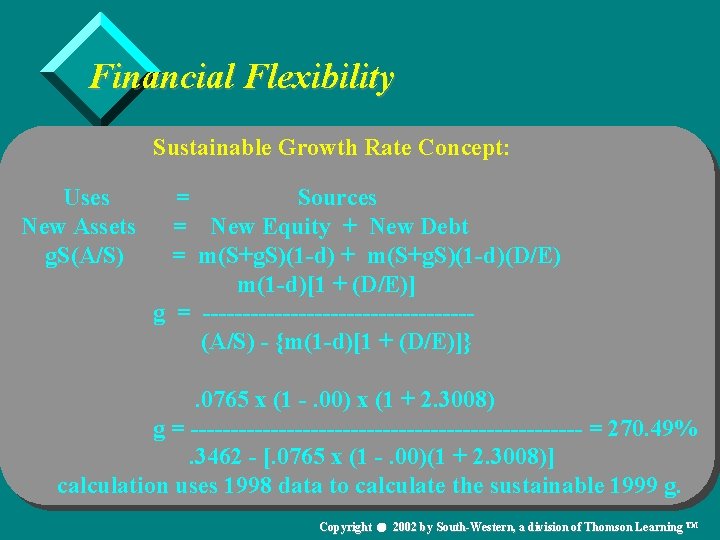
Financial Flexibility Sustainable Growth Rate Concept: Uses New Assets g. S(A/S) = Sources = New Equity + New Debt = m(S+g. S)(1 -d) + m(S+g. S)(1 -d)(D/E) m(1 -d)[1 + (D/E)] g = -----------------(A/S) - {m(1 -d)[1 + (D/E)]} . 0765 x (1 -. 00) x (1 + 2. 3008) g = ------------------------- = 270. 49%. 3462 - [. 0765 x (1 -. 00)(1 + 2. 3008)] calculation uses 1998 data to calculate the sustainable 1999 g. Copyright 2002 by South-Western, a division of Thomson Learning TM
Summary v Chapter introduced basic concepts of: – solvency – liquidity – financial flexibility v Solvency: an accounting concept comparing assets to liabilities v Liquidity: related to a firm’s ability to pay for its current obligations in a timely fashion with minimal costs v Financial flexibility: related to a firm’s overall financial structure and if financial policies allow firm enough flexibility to take advantage of unforeseen opportunities. Copyright 2002 by South-Western, a division of Thomson Learning TM