
www pwc ro The EU VAT ecommerce package
- Slides: 14
www. pwc. ro The EU VAT e-commerce package 28 September 2018 Alex Antonescu Manager, Indirect Taxation, Pw. C in Romania
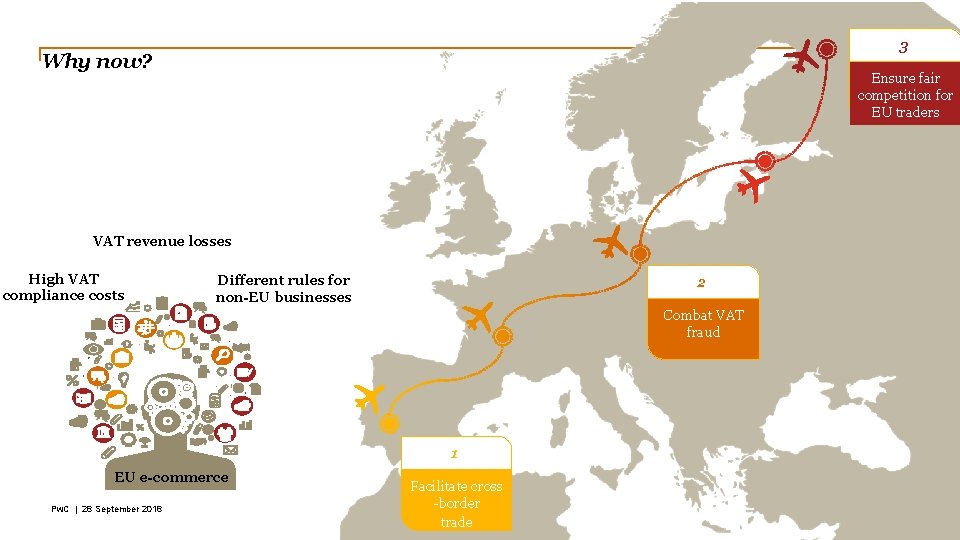
3 Why now? Ensure fair competition for EU traders VAT revenue losses High VAT compliance costs Different rules for non-EU businesses 2 Combat VAT fraud 1 EU e-commerce Pw. C | 28 September 2018 Facilitate cross -border trade
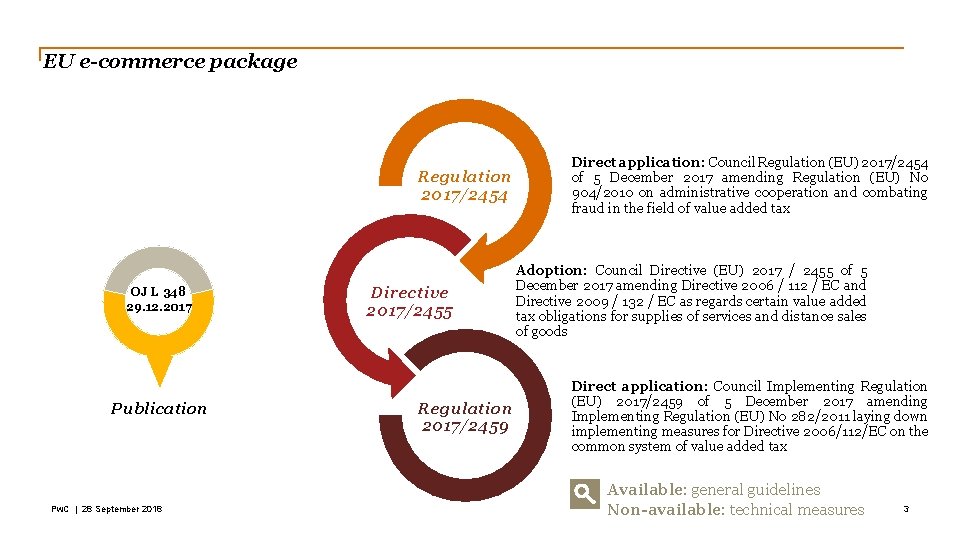
EU e-commerce package Regulation 2017/2454 OJ L 348 29. 12. 2017 Publication Pw. C | 28 September 2018 Directive 2017/2455 Regulation 2017/2459 Direct application: Council Regulation (EU) 2017/2454 of 5 December 2017 amending Regulation (EU) No 904/2010 on administrative cooperation and combating fraud in the field of value added tax Adoption: Council Directive (EU) 2017 / 2455 of 5 December 2017 amending Directive 2006 / 112 / EC and Directive 2009 / 132 / EC as regards certain value added tax obligations for supplies of services and distance sales of goods Direct application: Council Implementing Regulation (EU) 2017/2459 of 5 December 2017 amending Implementing Regulation (EU) No 282/2011 laying down implementing measures for Directive 2006/112/EC on the common system of value added tax Available: general guidelines Non-available: technical measures 3
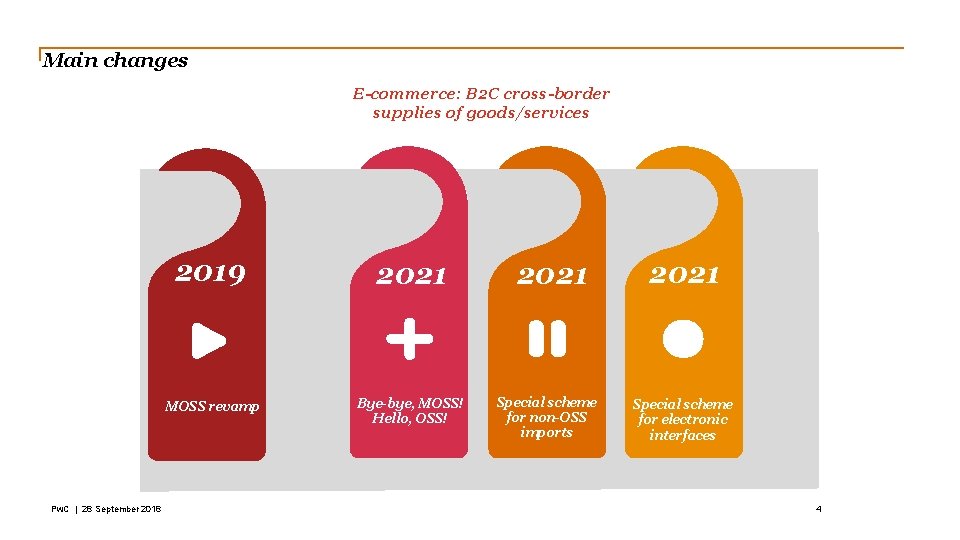
Main changes E-commerce: B 2 C cross-border supplies of goods/services Pw. C | 28 September 2018 2019 2021 MOSS revamp Bye-bye, MOSS! Hello, OSS! 2021 Special scheme for non-OSS imports 2021 Special scheme for electronic interfaces 4
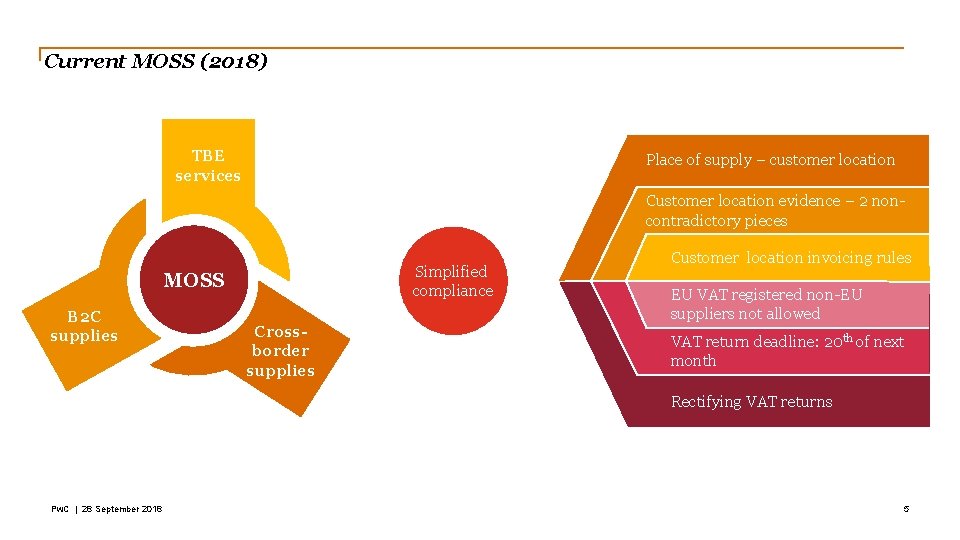
Current MOSS (2018) TBE services Place of supply – customer location Customer location evidence – 2 noncontradictory pieces Simplified compliance MOSS B 2 C supplies Crossborder supplies Customer location invoicing rules EU VAT registered non-EU suppliers not allowed VAT return deadline: 20 th of next month Rectifying VAT returns Pw. C | 28 September 2018 5
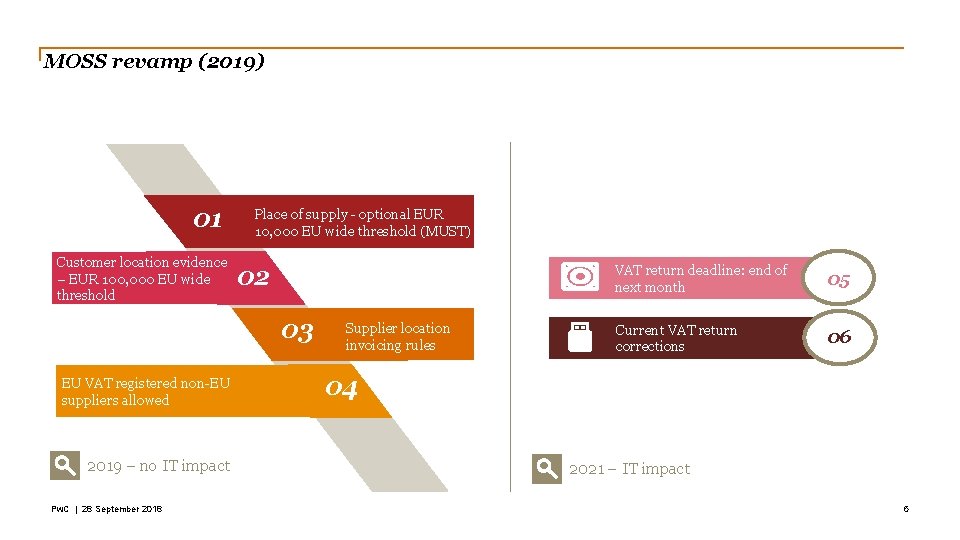
MOSS revamp (2019) 01 Customer location evidence – EUR 100, 000 EU wide threshold Place of supply - optional EUR 10, 000 EU wide threshold (MUST) 02 03 EU VAT registered non-EU suppliers allowed 2019 – no IT impact Pw. C | 28 September 2018 Supplier location invoicing rules 04 VAT return deadline: end of next month 05 Current VAT return corrections 06 Text to go here to go here to 2021 – IT impact 6
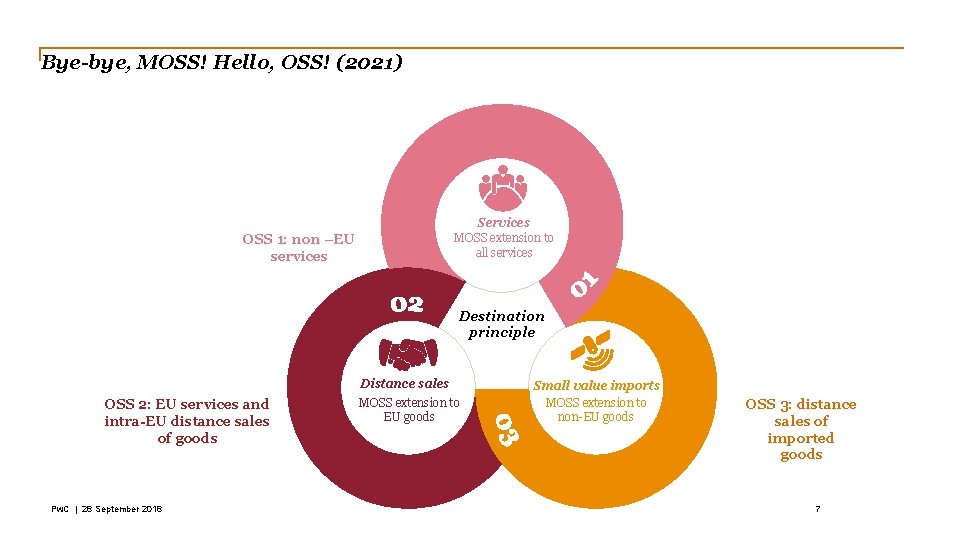
Bye-bye, MOSS! Hello, OSS! (2021) Services MOSS extension to all services OSS 1: non –EU services Destination principle Distance sales OSS 2: EU services and intra-EU distance sales of goods Pw. C | 28 September 2018 MOSS extension to EU goods Small value imports MOSS extension to non-EU goods OSS 3: distance sales of imported goods 7
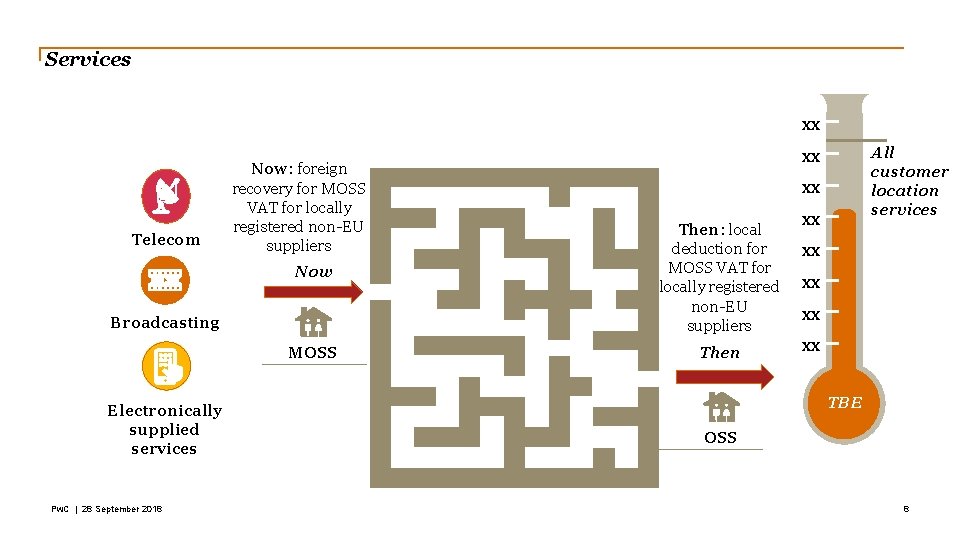
Services xx Telecom Now: foreign recovery for MOSS VAT for locally registered non-EU suppliers Broadcasting Now Broadcasting Electronically supplied services Pw. C | 28 September 2018 MOSS All customer location services xx xx Then: local deduction for MOSS VAT for locally registered non-EU suppliers Then xx xx xx TBE OSS 8
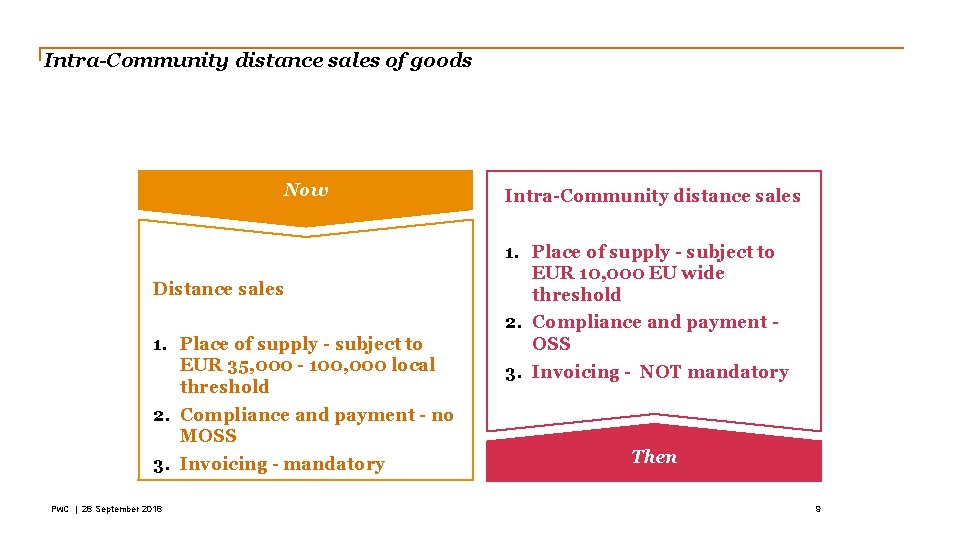
Intra-Community distance sales of goods Now Distance sales 1. Place of supply - subject to EUR 35, 000 - 100, 000 local threshold 2. Compliance and payment - no MOSS 3. Invoicing - mandatory Pw. C | 28 September 2018 Intra-Community distance sales 1. Place of supply - subject to EUR 10, 000 EU wide threshold 2. Compliance and payment OSS 3. Invoicing - NOT mandatory Then 9
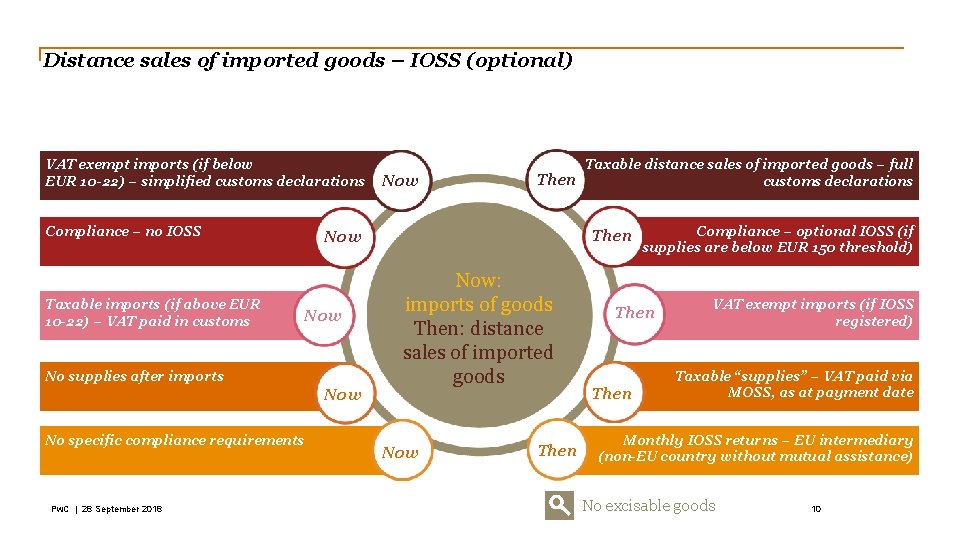
Distance sales of imported goods – IOSS (optional) VAT exempt imports (if below EUR 10 -22) – simplified customs declarations Compliance – no IOSS Taxable imports (if above EUR 10 -22) – VAT paid in customs Then Now No supplies after imports Now No specific compliance requirements Pw. C | 28 September 2018 Now Taxable distance sales of imported goods – full Then customs declarations Now: imports of goods Then: distance sales of imported goods Now Then Compliance – optional IOSS (if supplies are below EUR 150 threshold) Then VAT exempt imports (if IOSS registered) Taxable “supplies” – VAT paid via MOSS, as at payment date Monthly IOSS returns – EU intermediary (non-EU country without mutual assistance) No excisable goods 10
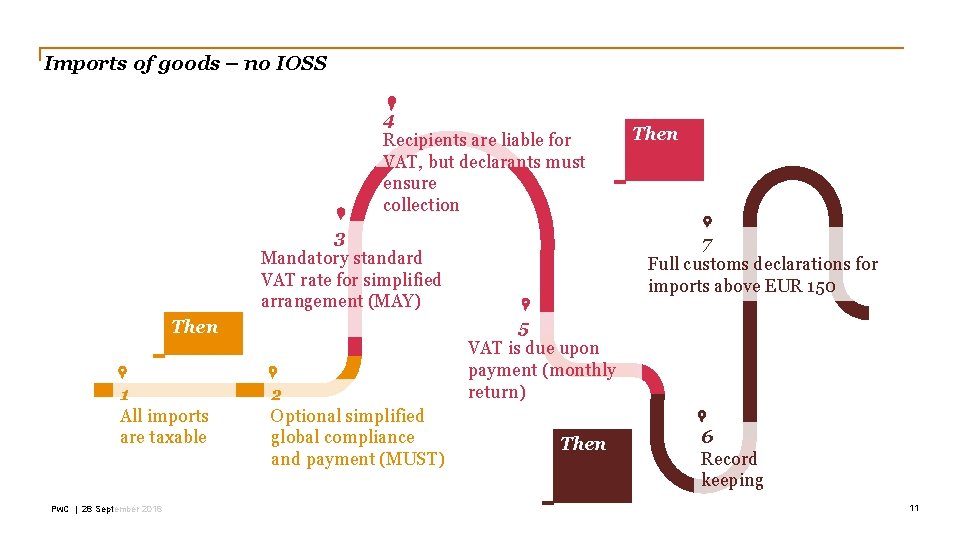
Imports of goods – no IOSS 4 Recipients are liable for VAT, but declarants must ensure collection 3 Mandatory standard VAT rate for simplified arrangement (MAY) Then 1 All imports are taxable Pw. C | 28 September 2018 2 Optional simplified global compliance and payment (MUST) Then 7 Full customs declarations for imports above EUR 150 5 VAT is due upon payment (monthly return) Then 6 Record keeping 11
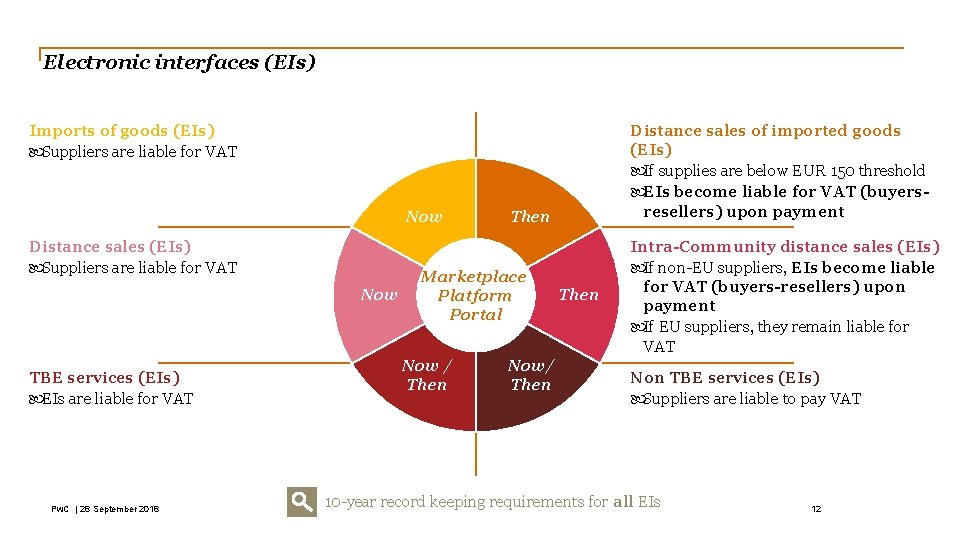
Electronic interfaces (EIs) Imports of goods (EIs) Suppliers are liable for VAT Now Distance sales (EIs) Suppliers are liable for VAT Now TBE services (EIs) EIs are liable for VAT Pw. C | 28 September 2018 Then Marketplace Platform Portal Now / Then Distance sales of imported goods (EIs) If supplies are below EUR 150 threshold EIs become liable for VAT (buyersresellers) upon payment Now/ Then Intra-Community distance sales (EIs) If non-EU suppliers, EIs become liable for VAT (buyers-resellers) upon payment If EU suppliers, they remain liable for VAT Non TBE services (EIs) Suppliers are liable to pay VAT 10 -year record keeping requirements for all EIs 12
www. pwc. ro Alex Antonescu Office: +40 21 225 3178 | Mobile: +40 720 028 979 | Fax: +40 21 225 3600 Email: alexandru. antonescu@pwc. com Pricewaterhouse. Coopers Tax Advisors & Accountants S. R. L. Lakeview Office, 301 -311 Barbu Vacarescu Street, RO - 020276, Bucharest, Romania Pricewaterhouse. Coopers Tax Advisors & Accountants SRL Clădirea Lakeview, etaj 7/1, Strada Barbu Văcărescu 301 -311, Sect. 2, Bucureşti 020276, România Tel: (40) 21 225 3000, Fax: (40) 21 225 3600, www. pwc. com/ro Nr. inreg. Reg. Com. : J 40/1784/1995, Cod Fiscal: RO 7108710
Thank you! This publication has been prepared for general guidance on matters of interest only, and does not constitute professional advice. You should not act upon the information contained in this publication without obtaining specific professional advice. No representation or warranty (express or implied) is given as to the accuracy or completeness of the information contained in this publication, and, to the extent permitted by law, Pricewaterhouse. Coopers Tax Advisors and Accountants, its members, employees and agents do not accept or assume any liability, responsibility or duty of care for any consequences of you or anyone else acting, or refraining to act, in reliance on the information contained in this publication or for any decision based on it. © 2017 Pricewaterhouse. Coopers Tax Advisors and Accountants. All rights reserved. In this document, “Pw. C” refers to Pricewaterhouse. Coopers Tax Advisors and Accountants which is a member firm of Pricewaterhouse. Coopers International Limited, each member firm of which is a separate legal entity.