
WPASGL Small Business Lending Conference Seven Springs Mountain

WPASGL Small Business Lending Conference Seven Springs Mountain Resort March 13, 2014 SBA Office of Financial Assistance Linda Rusche, Director 1
SBA Loan Programs • Tools that enable lenders to meet the needs of their small entrepreneurs • Public/private partnership • Creating jobs • Stimulating economic activity 2
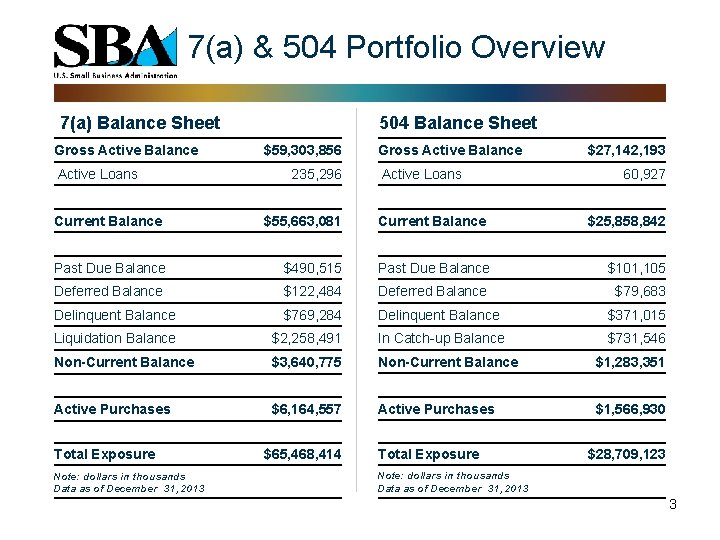
7(a) & 504 Portfolio Overview 7(a) Balance Sheet Gross Active Balance Active Loans Current Balance 504 Balance Sheet $59, 303, 856 235, 296 $55, 663, 081 Gross Active Balance Active Loans Current Balance $27, 142, 193 60, 927 $25, 858, 842 Past Due Balance $490, 515 Past Due Balance $101, 105 Deferred Balance $122, 484 Deferred Balance $79, 683 Delinquent Balance $769, 284 Delinquent Balance $371, 015 Liquidation Balance $2, 258, 491 In Catch-up Balance $731, 546 Non-Current Balance $3, 640, 775 Non-Current Balance Active Purchases Total Exposure Note: dollars in thousands Data as of December 31, 2013 $1, 283, 351 $6, 164, 557 $65, 468, 414 Active Purchases Total Exposure $1, 566, 930 $28, 709, 123 Note: dollars in thousands Data as of December 31, 2013 3
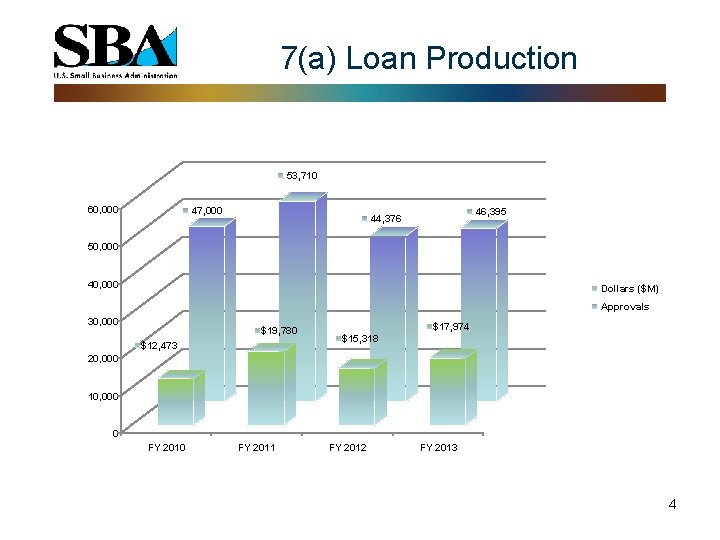
7(a) Loan Production 53, 710 60, 000 47, 000 46, 395 44, 376 50, 000 40, 000 Dollars ($M) Approvals 30, 000 $19, 780 $12, 473 $17, 974 $15, 318 20, 000 10, 000 0 FY 2011 FY 2012 FY 2013 4
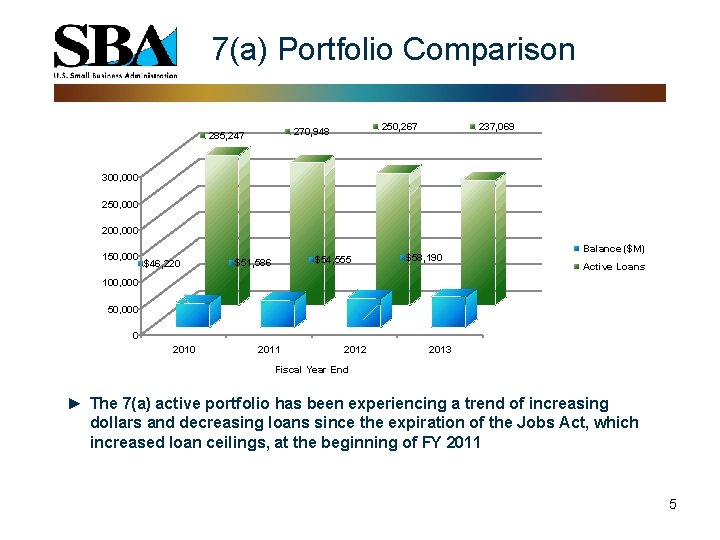
7(a) Portfolio Comparison 250, 267 270, 948 285, 247 237, 069 300, 000 250, 000 200, 000 150, 000 $46, 220 $54, 555 $51, 586 $58, 190 Balance ($M) Active Loans 100, 000 50, 000 0 2011 2012 2013 Fiscal Year End ► The 7(a) active portfolio has been experiencing a trend of increasing dollars and decreasing loans since the expiration of the Jobs Act, which increased loan ceilings, at the beginning of FY 2011 5
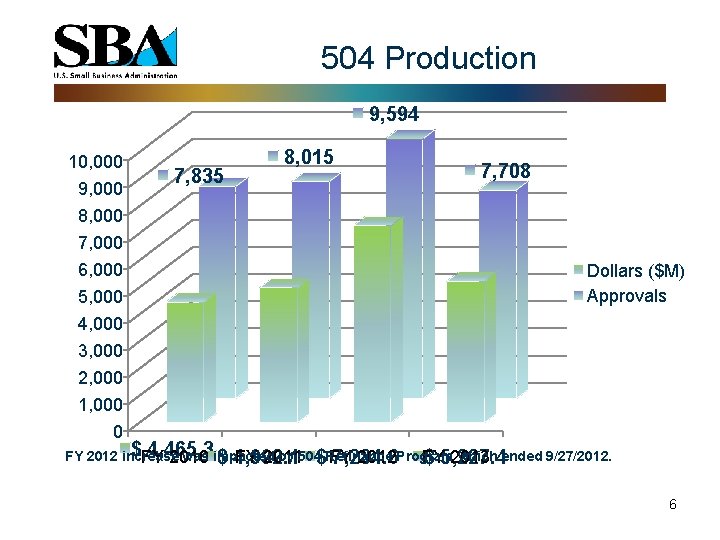
504 Production 9, 594 10, 000 9, 000 8, 000 7, 000 6, 000 5, 000 4, 000 3, 000 2, 000 1, 000 0 7, 835 8, 015 7, 708 Dollars ($M) Approvals $FY 2010 4, 465. 3 FY 2012 increase was impacted by 504$Refinance which ended 9/27/2012. FY 2011 FY 2012 FY 2013 $ 4, 992. 1 7, 284. 6 Program $ 5, 227. 4 6
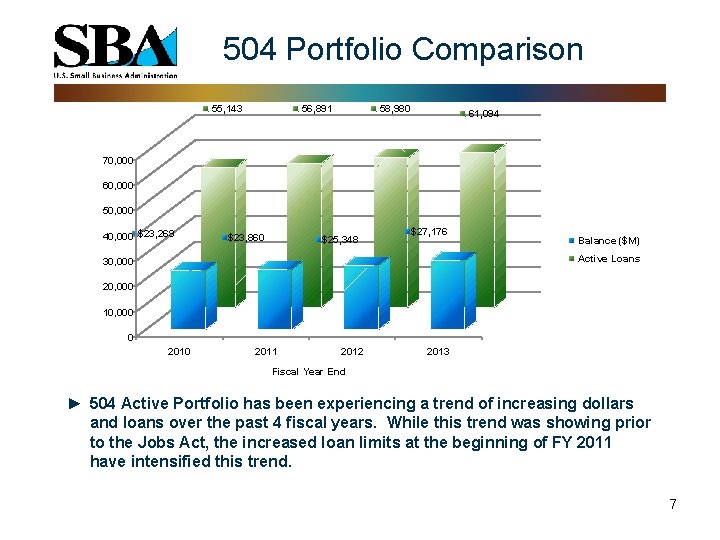
504 Portfolio Comparison 55, 143 56, 891 58, 980 61, 094 70, 000 60, 000 50, 000 40, 000 $23, 269 $23, 860 $25, 348 $27, 176 Balance ($M) Active Loans 30, 000 20, 000 10, 000 0 2011 2012 2013 Fiscal Year End ► 504 Active Portfolio has been experiencing a trend of increasing dollars and loans over the past 4 fiscal years. While this trend was showing prior to the Jobs Act, the increased loan limits at the beginning of FY 2011 have intensified this trend. 7
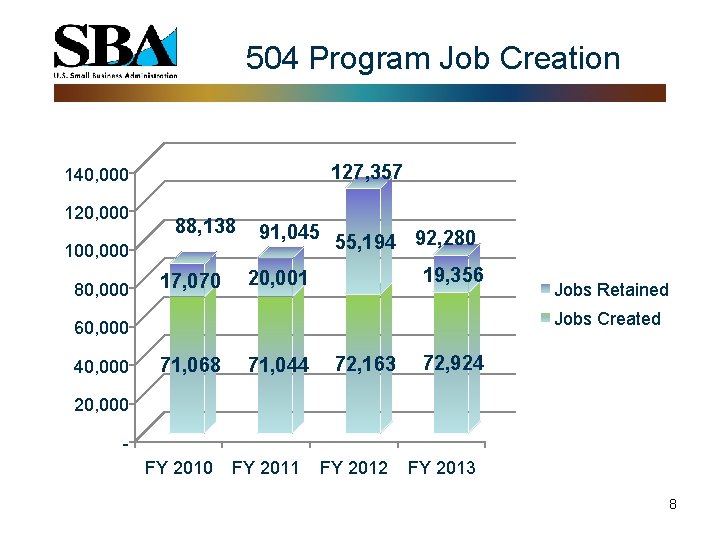
504 Program Job Creation 127, 357 140, 000 120, 000 88, 138 100, 000 80, 000 17, 070 91, 045 55, 194 92, 280 19, 356 20, 001 Jobs Created 60, 000 40, 000 Jobs Retained 71, 068 71, 044 72, 163 72, 924 20, 000 FY 2011 FY 2012 FY 2013 8
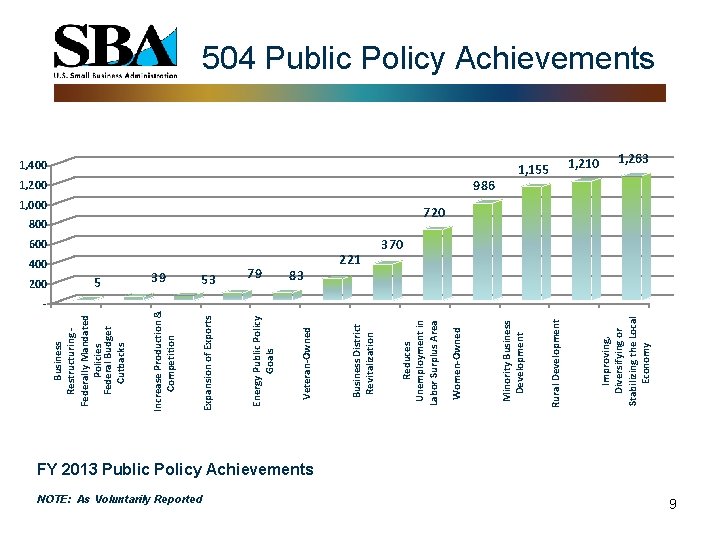
200 5 - 53 NOTE: As Voluntarily Reported 986 800 1, 155 Improving, Diversifying or Stabilizing the Local Economy 1, 200 Rural Development 1, 400 Minority Business Development 1, 000 Women-Owned 83 221 Reduces Unemployment in Labor Surplus Area 600 Business District Revitalization 79 Veteran-Owned Energy Public Policy Goals 39 Expansion of Exports 400 Increase Production & Competition Business Restructuring - Federally Mandated Policies Federal Budget Cutbacks 504 Public Policy Achievements 1, 210 1, 263 720 370 FY 2013 Public Policy Achievements 9
What's New? ? • SOP 50 10 5 (f) Effective January 1, 2014 • Streamlined small loan program underwriting • Clarified collateral requirements • 1919/1920 replaces former form 4/4 -I for larger loans • 504 forms also revised to align • 504 and 7(a) Regulation to be published soon 10
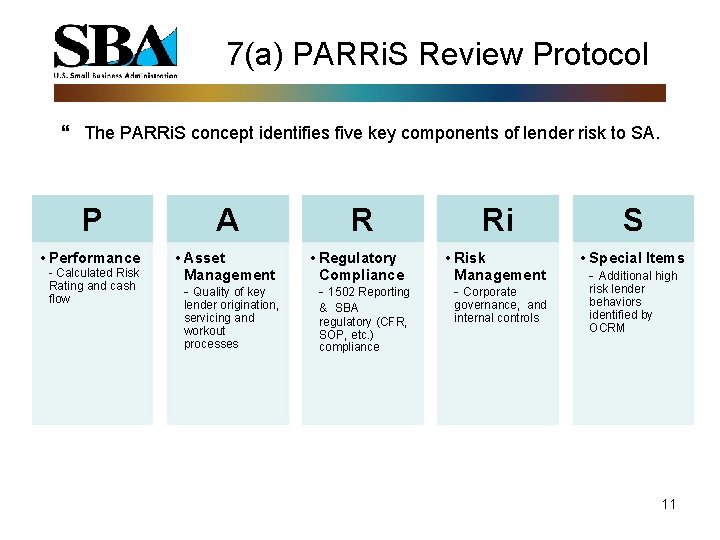
7(a) PARRi. S Review Protocol The PARRi. S concept identifies five key components of lender risk to SA. P A R Ri S • Performance • Asset Management - Quality of key • Regulatory Compliance - 1502 Reporting & SBA • Risk Management - Corporate • Special Items - Additional high - Calculated Risk Rating and cash flow lender origination, servicing and workout processes regulatory (CFR, SOP, etc. ) compliance governance, and internal controls risk lender behaviors identified by OCRM 11
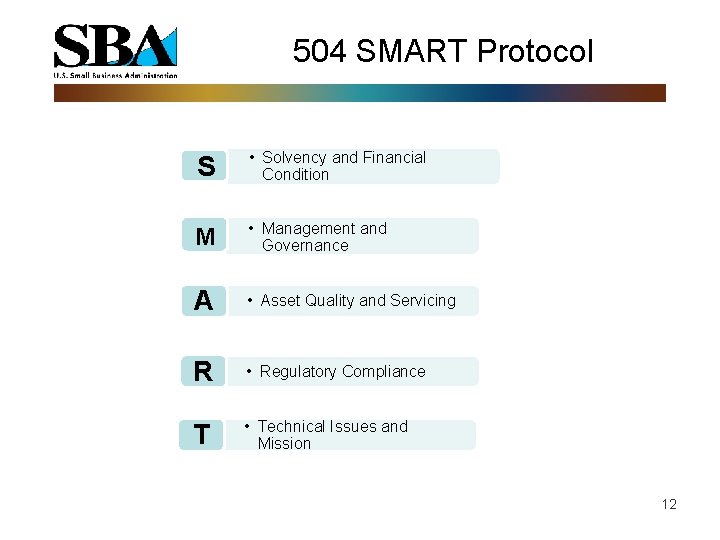
504 SMART Protocol S S • Solvency and Financial Condition M • Management and Governance A • Asset Quality and Servicing R • Regulatory Compliance T • Technical Issues and Mission 12
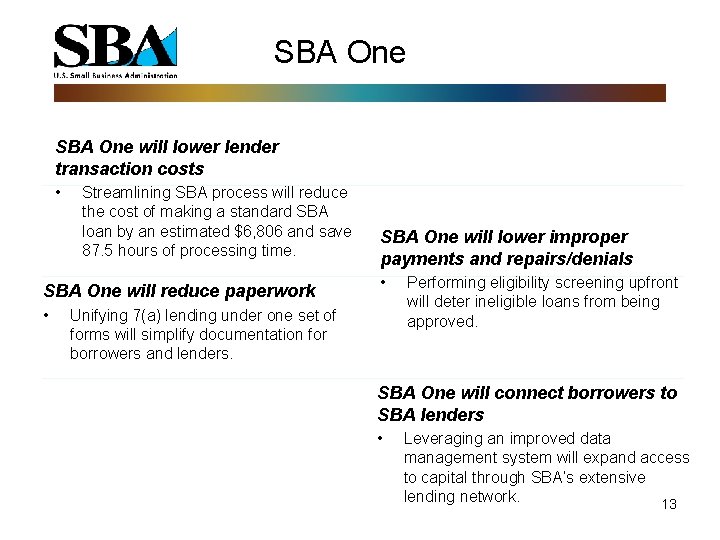
SBA One will lower lender transaction costs • Streamlining SBA process will reduce the cost of making a standard SBA loan by an estimated $6, 806 and save 87. 5 hours of processing time. SBA One will reduce paperwork • SBA One will lower improper payments and repairs/denials • Unifying 7(a) lending under one set of forms will simplify documentation for borrowers and lenders. Performing eligibility screening upfront will deter ineligible loans from being approved. SBA One will connect borrowers to SBA lenders • Leveraging an improved data management system will expand access to capital through SBA’s extensive lending network. 13
SBA Veterans Advantage Effective January 1, 2014 Express loan product Veterans, spouses and related individuals (see SOP) Zero fees on all loans $350, 000 and less See SBA Notice 5000 -1299 14
Community Advantage • The Community Advantage Network has 79 mission-based lenders across the country providing 7(a) loans to underserved markets – CA Lenders have had success partnering with national and local banks for capitalization support and also deal referrals – doing loans the banks won’t due, providing borrowers with necessary technical assistance, etc. – 3 CA Lenders are in PA: The Progress Fund, Regional Development Funding Corporation, Washington County Council on Economic Development – 3 Nationwide CA Lenders: Empire State CDC, CDC Small Business Finance, and Local Initiative Support Corporation – Program currently has $84 million in loan approvals since it was initially created in FY 11 15
Community Advantage • CDCs are an eligible organization which may be approved as a Community Advantage Lender – New Program Guide to be published shortly • 7(a) loans of $150, 000 or less are up in FY 14 versus the same time period in FY 13 – Up 7. 6% in numbers of approvals and 11. 3% in dollars approved • 7(a) loans to minorities are also up in FY 14 across all categories/ethnicities • HQ Contact: Grady Hedgespeth, Director, Office of Economic Opportunity – 202 -205 -7562 – grady. hedgespeth. sba. gov 16
7(a) Program Contacts 7(a) Loan Program Branch Dianna Seaborn, Chief 202 -205 -3645 Sloan Coleman, Financial Analyst 202 -205 -7737 Justine Alston, Financial Analyst 202 -205 -7623 Meghan Milloy, P(202) 619 -1654 202 -619 -1654 SBA Sacramento Loan Processing Center (SLPC) Frank Pucci, Center Director 916 -735 -1969 dianna. seaborn@sba. gov w. coleman@sba. gov justine. alston@sba. gov meghan. milloy@sba. gov robert. pucci@sba. gov 17
504 Program Contacts 504 Loan Program Branch Linda Reilly, Chief Warren Boyd, Financial Analyst Bob Carpenter, Financial Analyst Eric Wall, Financial Analyst 202 -205 -9949 202 -205 -7534 202 -205 -7654 202 -619 -1825 linda. reilly@sba. gov warren. boyd@sba. gov robert. carpenter@sba. gov eric. wall@sba. gov SBA Sacramento Loan Processing Center (SLPC) Richard Taylor, Center Director 916 -735 -1221 richard. taylor@sba. gov 18
- Slides: 18