
Venture Capital and the Internet Bubble Facts Fundamentals
Venture Capital and the Internet Bubble: Facts, Fundamentals and Food for Thought Thomas Hellmann and Manju Puri
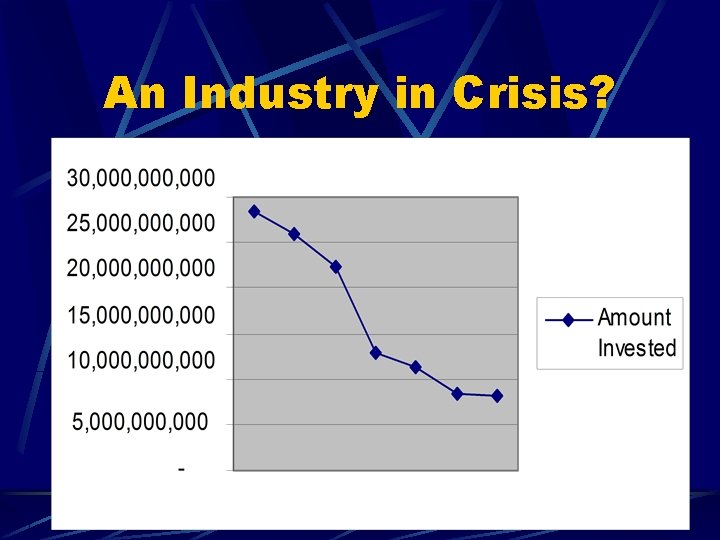
An Industry in Crisis?
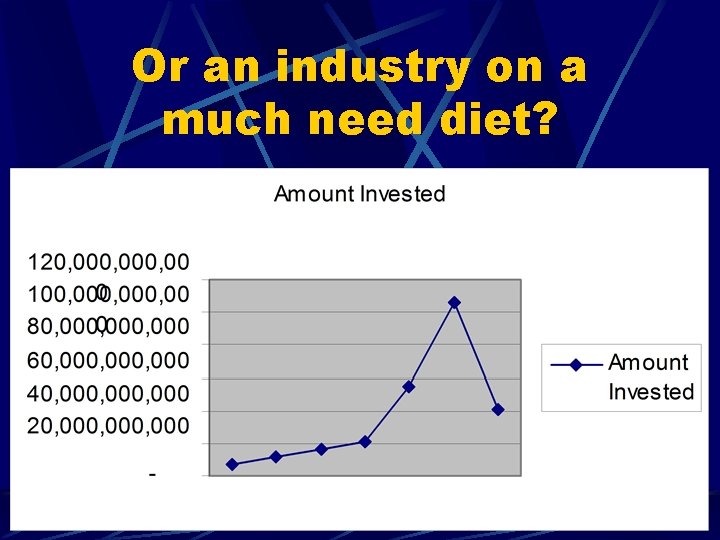
Or an industry on a much need diet?
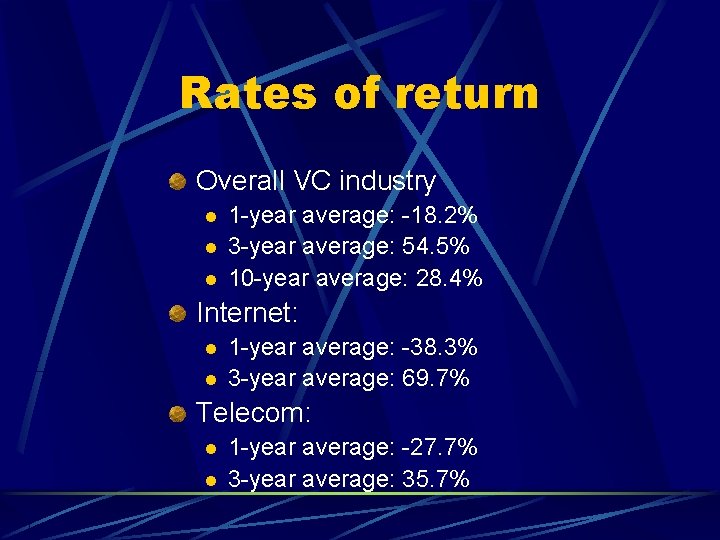
Rates of return Overall VC industry l l l 1 -year average: -18. 2% 3 -year average: 54. 5% 10 -year average: 28. 4% Internet: l l 1 -year average: -38. 3% 3 -year average: 69. 7% Telecom: l l 1 -year average: -27. 7% 3 -year average: 35. 7%
What are the fundamentals of venture capital? Alternative Investment Class Real Estate versus Venture Capital? l VC = Value-added investors? l Stanford Project on Emerging Companies Interdisciplinary project l 170 Silicon Valley high tech start-ups l Data on whether and when companies get VC l No dotcoms! l
SPEC: The external product market effect of VC Obtaining VC associated with faster time to market l hazard rate increase by factor of 1. 79 Larger effect for innovator companies Innovators self-select into VC Time-to-market effects does not driven seem to be driven by selection alone
SPEC: The internal professionalization effect of VC Founder replacement l Support or Control With VC: 61% of founders replaced Without VC: 36% of founders replaced VC gives shorter time-to-replacement Friendly or hostile? l l In 40% founder remains involved Effect same for VC and non-VC replacements VC effect part of a broader pattern of professionalization l Executive team building
A brief history of the structure of VC industry Old days: l Tight collusive networks Post 1979 evolution: Differentiated competitors l Unique skills and proprietary deal-flow l Returns justify “expensive” GP contracts l
The Internet rocks the VC industry New opportunities: Big and visible l Low barriers to entry l Winners materialize faster than losers l Steady state: see mix of new winners and older losers Wrong extrapolations create feeding frenzy
The VC industry responds New entrants with little relevant experience l Wall Street types Effect on experienced VCs l l l Danger of defying trend Temptation of increasing fund size Change in VC business model: l l l Invest in more companies Place more money => less syndication More later stage Increase in diversity of VC structures l Incubators, corporate VCs, bank VCs, angel networks
How can the VC industry recover now? Can VCs live by their own medicine? l Defensible value-proposition l l Accountability l l Inconsistent reporting Governance l l Value-adding component Competitive differentiation Building a franchise Legal constraints Reasonable valuations l Revisiting GP terms Implications for public policy! l Focus on enabling public goods
- Slides: 11