
VAT ecommerce package 2 COM2018819 COM2018821 VAT Expert
- Slides: 10
VAT e-commerce package 2 COM(2018)819 COM(2018)821 VAT Expert Group – 11 February 2019
VAT ecommerce package 2 COM (2018) 819 – Amendments to VAT Directive 2006/112/EC COM (2018) 821 – Amendments to Council Implementing Regulation 282/2011 2
1. Amendements to the VAT Directive 2006/112/EC COM (2018) 819 3
VAT Directive proposal No changes to the principles agreed by Council on 5 December 2017 Changes to support the agreed principles and which could not be made in implementing rules Provisions for the application of Article 14 a of VAT Directive Adjust certain discrepancies in legal text 4
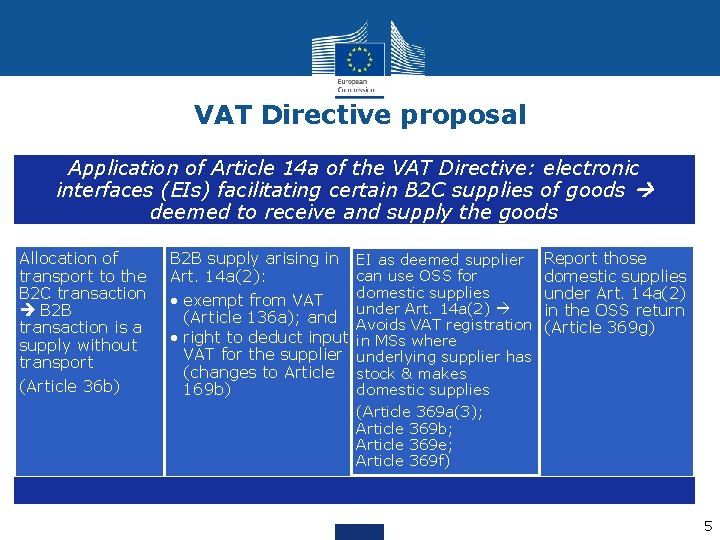
VAT Directive proposal Application of Article 14 a of the VAT Directive: electronic interfaces (EIs) facilitating certain B 2 C supplies of goods deemed to receive and supply the goods Allocation of transport to the B 2 C transaction B 2 B transaction is a supply without transport (Article 36 b) B 2 B supply arising in EI as deemed supplier can use OSS for Art. 14 a(2): domestic supplies • exempt from VAT under Art. 14 a(2) (Article 136 a); and Avoids VAT registration • right to deduct input in MSs where VAT for the supplier underlying supplier has (changes to Article stock & makes domestic supplies 169 b) Report those domestic supplies under Art. 14 a(2) in the OSS return (Article 369 g) (Article 369 a(3); Article 369 b; Article 369 e; Article 369 f) 5
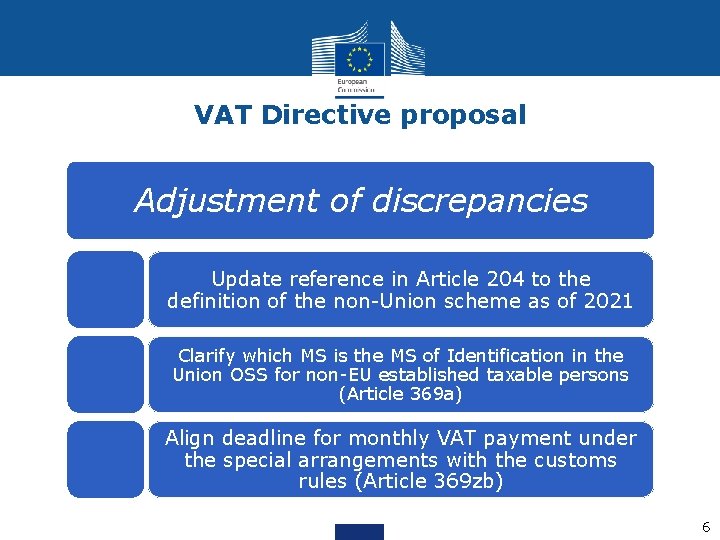
VAT Directive proposal Adjustment of discrepancies Update reference in Article 204 to the definition of the non-Union scheme as of 2021 Clarify which MS is the MS of Identification in the Union OSS for non-EU established taxable persons (Article 369 a) Align deadline for monthly VAT payment under the special arrangements with the customs rules (Article 369 zb) 6
2. Amendments to Council Implementing Regulation 282/2011 COM (2018) 821 7
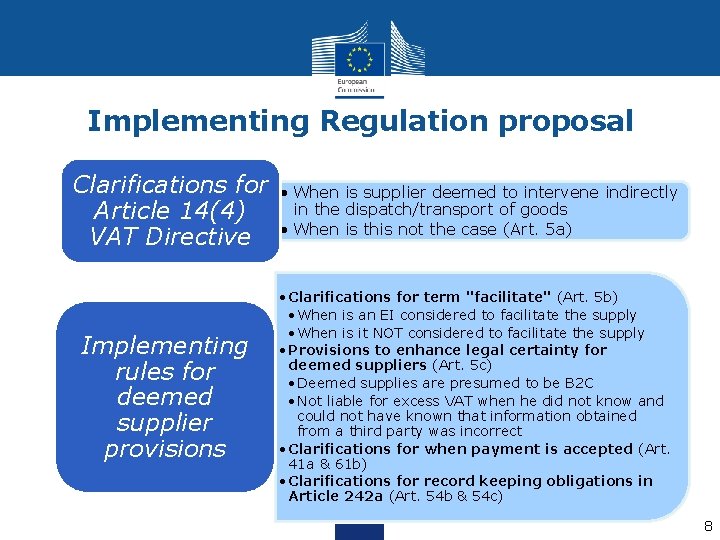
Implementing Regulation proposal Clarifications for Article 14(4) VAT Directive Implementing rules for deemed supplier provisions • When is supplier deemed to intervene indirectly in the dispatch/transport of goods • When is this not the case (Art. 5 a) • Clarifications for term "facilitate" (Art. 5 b) • When is an EI considered to facilitate the supply • When is it NOT considered to facilitate the supply • Provisions to enhance legal certainty for deemed suppliers (Art. 5 c) • Deemed supplies are presumed to be B 2 C • Not liable for excess VAT when he did not know and could not have known that information obtained from a third party was incorrect • Clarifications for when payment is accepted (Art. 41 a & 61 b) • Clarifications for record keeping obligations in Article 242 a (Art. 54 b & 54 c) 8
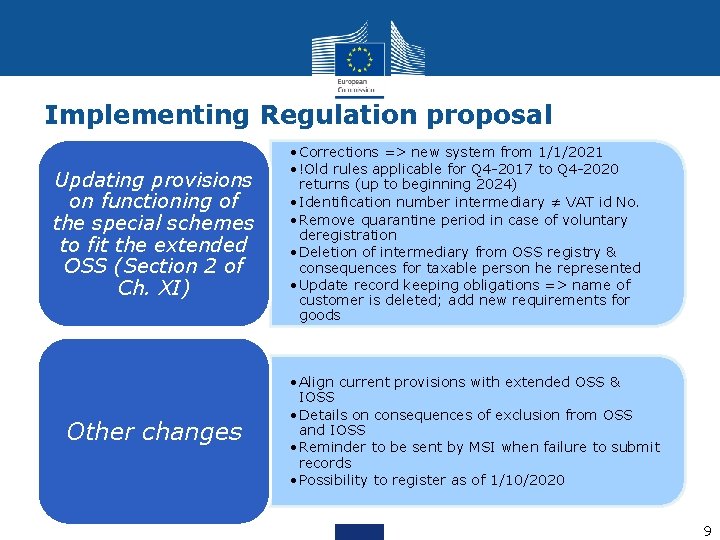
Implementing Regulation proposal Updating provisions on functioning of the special schemes to fit the extended OSS (Section 2 of Ch. XI) Other changes • Corrections => new system from 1/1/2021 • !Old rules applicable for Q 4 -2017 to Q 4 -2020 returns (up to beginning 2024) • Identification number intermediary ≠ VAT id No. • Remove quarantine period in case of voluntary deregistration • Deletion of intermediary from OSS registry & consequences for taxable person he represented • Update record keeping obligations => name of customer is deleted; add new requirements for goods • Align current provisions with extended OSS & IOSS • Details on consequences of exclusion from OSS and IOSS • Reminder to be sent by MSI when failure to submit records • Possibility to register as of 1/10/2020 9
DG TAXUD – Unit C 1 E-mail: TAXUD-C 1 -SECTOR-A@ec. europa. eu 10