
VALUE BASED MANAGEMENT Chapter 3 12 SFM Value
VALUE BASED MANAGEMENT Chapter 3 & 12, SFM
Value Measures ■ ■ ■ ■ ■ Return on Invested Capital Economic Value Added Market Value Added Cash Flow Return On Investment Cash Value Added Market – to – Capital Ratio Total Shareholders’ Return Future Growth Value Wealth Added Index ■ ■ ■ ■ ■ ROIC EVA MVA CFROI CVA MCR TSR FGV WAI
RETURN ON INVESTED CAPITAL (ROIC) ROIC is an indicator of Operating performance of the company.

Return on Invested Capital (ROIC) ■ ROIC is a indicator of Operating performance of the company. ■ ROIC = NOPLAT / Invested Capital ■ Where, ■ NOPLAT or NOPAT = Net EBIT – Taxes on Net EBIT ■ Net EBIT = EBIT – NOI* + NOE* ■ (*EBIT need to be adjusted for NOI/E if they are already included in EBIT) ■ ‘Invested Capital’ is also called as ‘Operating Invested Capital’ ■ OIC = Total Operating Assets ■ Or, OIC = Total Assets – Non Operating Assets – Excess Cash & Mktbl. Secs. ■ Or, OIC = NFA + NCA

Return on Invested Capital (ROIC) ■ ROIC = NOPLAT / Invested Capital ■ A company has an EBIT of Rs. 2 cr. It included interest income Rs. 0. 1 cr. And non operating expenses of Rs. 0. 2 cr. The total assets of the company is Rs. 5 cr. The company has capital work in progress worth Rs. 1 cr; Marketaable securities of Rs. 0. 5 cr. and Cash worth Rs. 0. 25 cr. In excess of working capital requirement. Tax 30%. Find out ROIC. ■ Net EBIT = 2 – 0. 1 + 0. 2 = Rs. 2. 1 cr. ■ NOPLAT = 2. 1 – (2. 1*0. 3) = Rs. 1. 47 cr. ■ OIC = 5 – 1 – 0. 5 – 0. 25 = Rs. 3. 25 cr. ■ ROIC = 1. 47 / 3. 25 = 45%
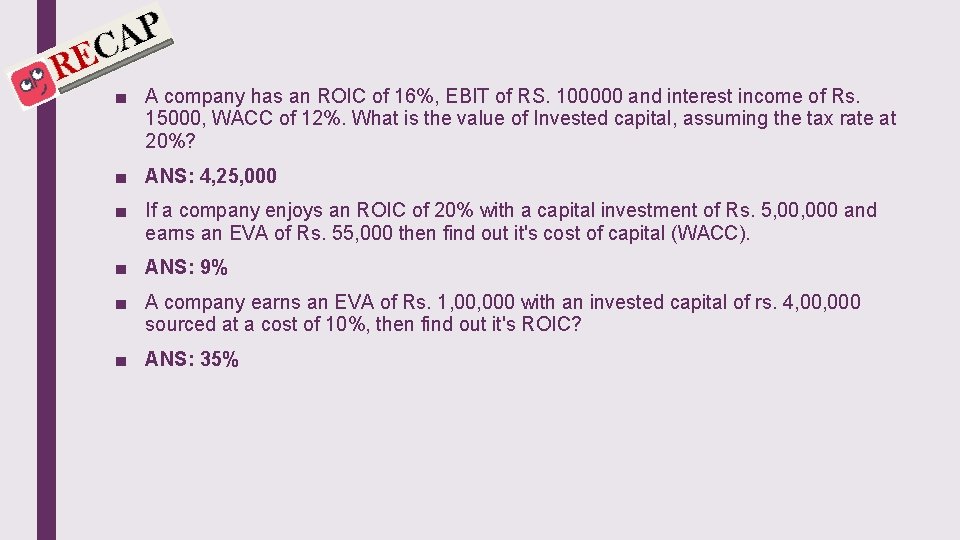
■ A company has an ROIC of 16%, EBIT of RS. 100000 and interest income of Rs. 15000, WACC of 12%. What is the value of Invested capital, assuming the tax rate at 20%? ■ ANS: 4, 25, 000 ■ If a company enjoys an ROIC of 20% with a capital investment of Rs. 5, 000 and earns an EVA of Rs. 55, 000 then find out it's cost of capital (WACC). ■ ANS: 9% ■ A company earns an EVA of Rs. 1, 000 with an invested capital of rs. 4, 000 sourced at a cost of 10%, then find out it's ROIC? ■ ANS: 35%
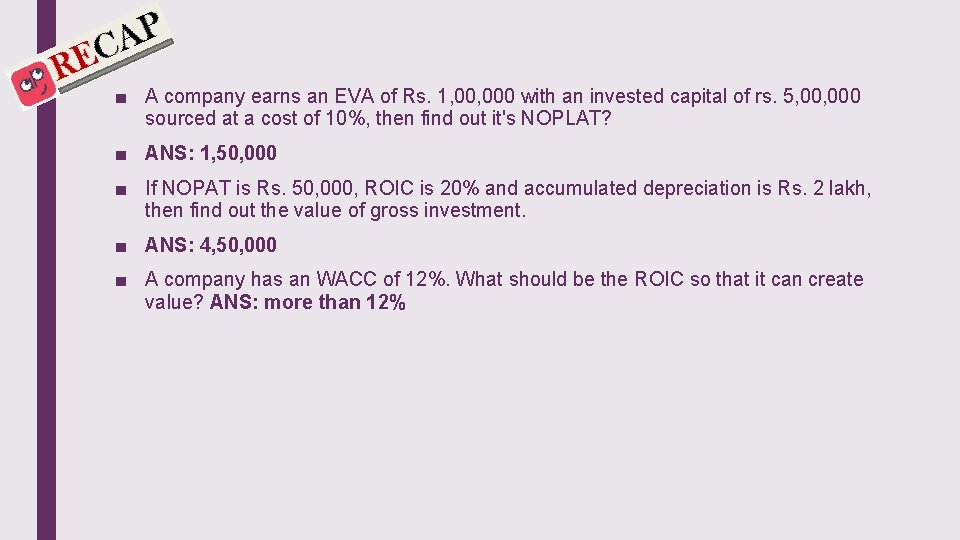
■ A company earns an EVA of Rs. 1, 000 with an invested capital of rs. 5, 000 sourced at a cost of 10%, then find out it's NOPLAT? ■ ANS: 1, 50, 000 ■ If NOPAT is Rs. 50, 000, ROIC is 20% and accumulated depreciation is Rs. 2 lakh, then find out the value of gross investment. ■ ANS: 4, 50, 000 ■ A company has an WACC of 12%. What should be the ROIC so that it can create value? ANS: more than 12%
ECONOMIC VALUE ADDED (EVA) Economic Value Added is a measure of economic profit.
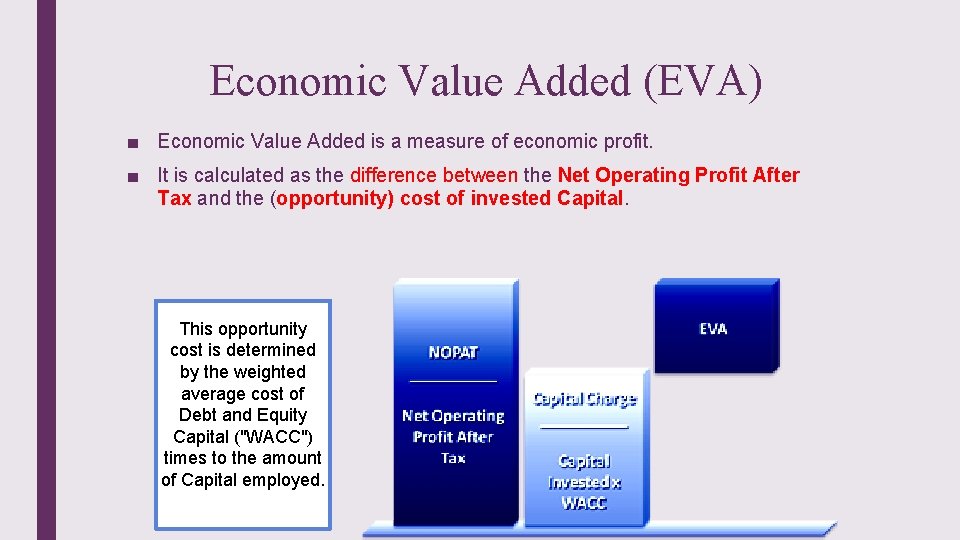
Economic Value Added (EVA) ■ Economic Value Added is a measure of economic profit. ■ It is calculated as the difference between the Net Operating Profit After Tax and the (opportunity) cost of invested Capital. This opportunity cost is determined by the weighted average cost of Debt and Equity Capital ("WACC") times to the amount of Capital employed.

Economic Value Added (EVA) ■ EVA = (ROIC – Kc) * OIC. ■ Or EVA = NOPAT – Capital Charge on Invested Capital ■ If EVA is +ve, the firm’s unlevered pool of profits (NOPAT) available for all investors is in excess of what the firm has to pay for employing funds in the business (Capital Charge).
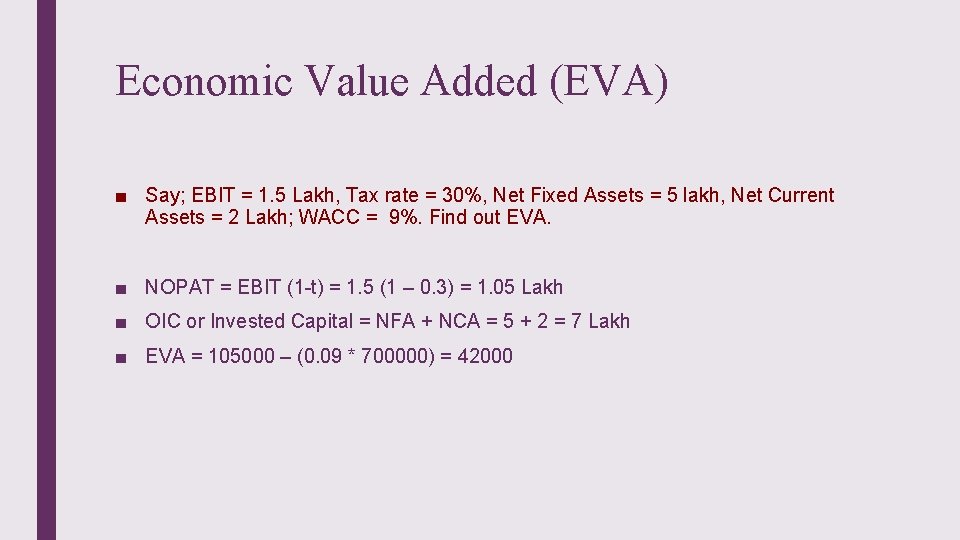
Economic Value Added (EVA) ■ Say; EBIT = 1. 5 Lakh, Tax rate = 30%, Net Fixed Assets = 5 lakh, Net Current Assets = 2 Lakh; WACC = 9%. Find out EVA. ■ NOPAT = EBIT (1 -t) = 1. 5 (1 – 0. 3) = 1. 05 Lakh ■ OIC or Invested Capital = NFA + NCA = 5 + 2 = 7 Lakh ■ EVA = 105000 – (0. 09 * 700000) = 42000
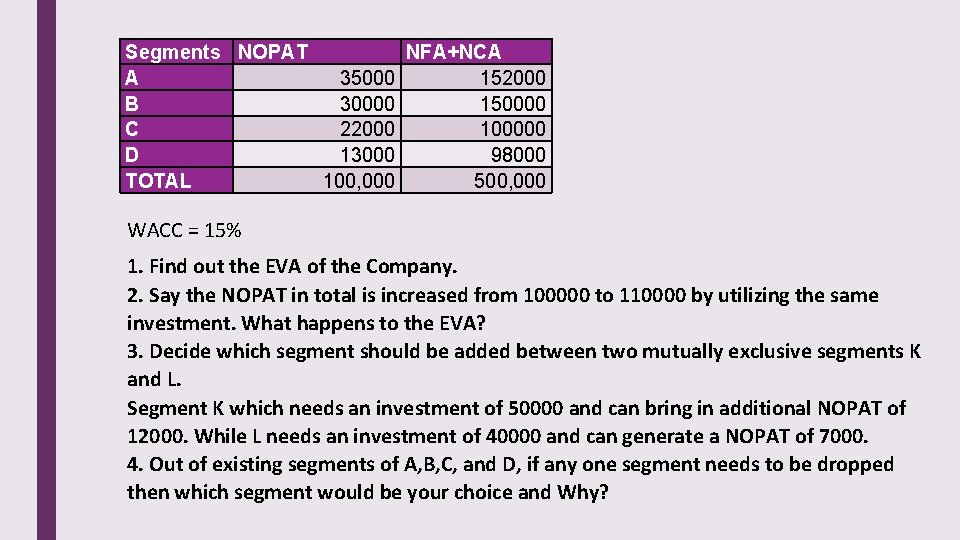
Segments NOPAT NFA+NCA A 35000 152000 B 30000 150000 C 22000 100000 D 13000 98000 TOTAL 100, 000 500, 000 WACC = 15% 1. Find out the EVA of the Company. 2. Say the NOPAT in total is increased from 100000 to 110000 by utilizing the same investment. What happens to the EVA? 3. Decide which segment should be added between two mutually exclusive segments K and L. Segment K which needs an investment of 50000 and can bring in additional NOPAT of 12000. While L needs an investment of 40000 and can generate a NOPAT of 7000. 4. Out of existing segments of A, B, C, and D, if any one segment needs to be dropped then which segment would be your choice and Why?
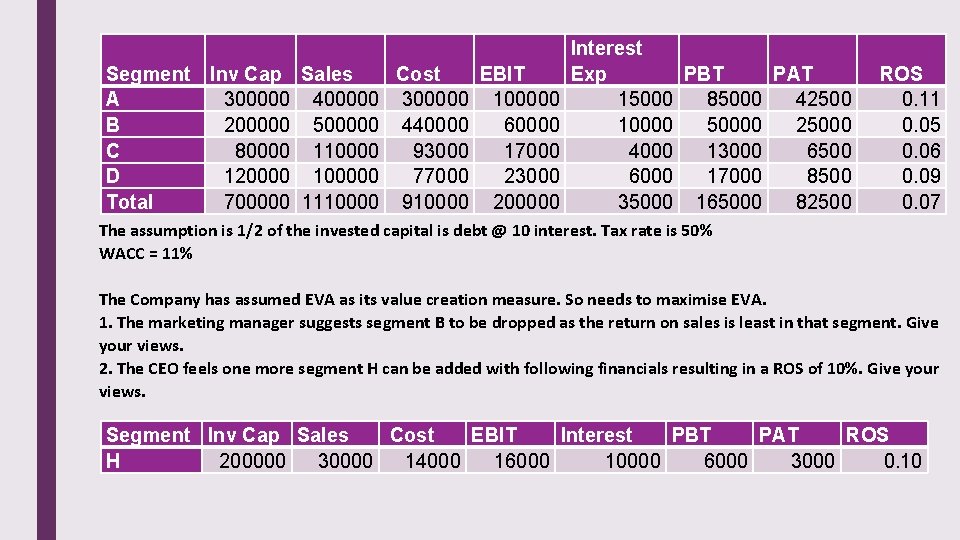
Segment Inv Cap Sales Cost EBIT A 300000 400000 300000 100000 B 200000 500000 440000 60000 C 80000 110000 93000 17000 D 120000 100000 77000 23000 Total 700000 1110000 910000 200000 Interest Exp PBT PAT 15000 85000 42500 10000 50000 25000 4000 13000 6500 6000 17000 8500 35000 165000 82500 ROS 0. 11 0. 05 0. 06 0. 09 0. 07 The assumption is 1/2 of the invested capital is debt @ 10 interest. Tax rate is 50% WACC = 11% The Company has assumed EVA as its value creation measure. So needs to maximise EVA. 1. The marketing manager suggests segment B to be dropped as the return on sales is least in that segment. Give your views. 2. The CEO feels one more segment H can be added with following financials resulting in a ROS of 10%. Give your views. Segment Inv Cap Sales Cost EBIT Interest PBT PAT ROS H 200000 30000 14000 16000 10000 6000 3000 0. 10
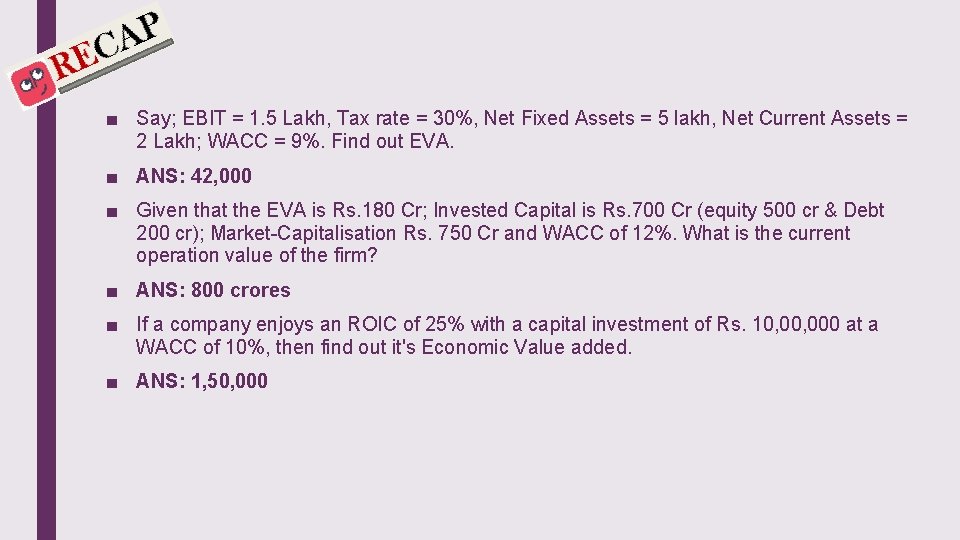
■ Say; EBIT = 1. 5 Lakh, Tax rate = 30%, Net Fixed Assets = 5 lakh, Net Current Assets = 2 Lakh; WACC = 9%. Find out EVA. ■ ANS: 42, 000 ■ Given that the EVA is Rs. 180 Cr; Invested Capital is Rs. 700 Cr (equity 500 cr & Debt 200 cr); Market-Capitalisation Rs. 750 Cr and WACC of 12%. What is the current operation value of the firm? ■ ANS: 800 crores ■ If a company enjoys an ROIC of 25% with a capital investment of Rs. 10, 000 at a WACC of 10%, then find out it's Economic Value added. ■ ANS: 1, 50, 000
MARKET VALUE ADDED (MVA) MVA is the value addition through capital market operations.

Market Value Added (MVA) ■ Market Value Added measures the difference between the market value of the firm (Mkt Value of Debt and Equity) and the amount of Capital invested. ■ MVA is the excess of market value of capital over and above the book value of capital (as sourced from equity and debt providers). Equivalently, MVA equals the present value of future expected EVA when discounted @ wacc.

Market Value Added (MVA) ■ MVA = Market Value of Equity & Debt – Invested Capital ■ If MVA is +ve, Business has created a market value of firm more than what it sourced from the equity & debt holders ■ The Book Value of Equity and Debt are 5 Cr. And 4 Cr. respectively. The market price of equity is Rs. 2100 and there are 30, 000 equities outstanding. Find out the MVA of the Company. MVE = 2100 * 30000= 6. 3 Cr. MVA = (6. 3 + 4) – (5 + 4) = 1. 3 Cr
■ The Book Value of Equity and Debt are 5 Cr. And 4 Cr. respectively. The market price of equity is Rs. 2100 and there are 30, 000 equities outstanding. Find out the MVA of the Company. ■ ANS: 1. 3 crores.
CASH FLOW RETURN ON INVESTMENT (CFROI) CFROI is a relative measure of sustainable value creation by the business.
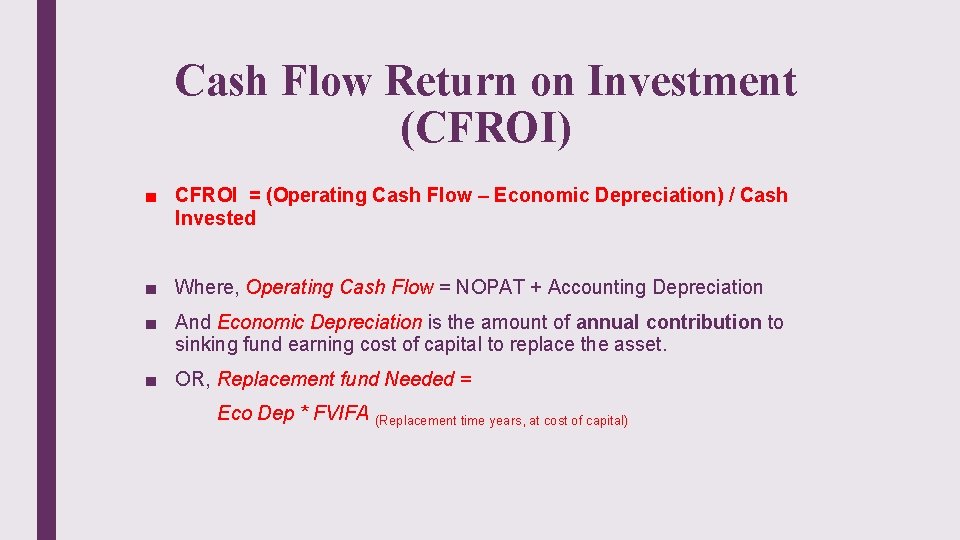
Cash Flow Return on Investment (CFROI) ■ CFROI = (Operating Cash Flow – Economic Depreciation) / Cash Invested ■ Where, Operating Cash Flow = NOPAT + Accounting Depreciation ■ And Economic Depreciation is the amount of annual contribution to sinking fund earning cost of capital to replace the asset. ■ OR, Replacement fund Needed = Eco Dep * FVIFA (Replacement time years, at cost of capital)
Cash Flow Return on Investment (CFROI) ■ If CFROI > Kc, the business is earning cash in excess of capital charge, ■ even after making provision for asset replacement at the end of asset life ■ i. e. Business seems to be sustainable for long time.
■ A company earns operating cash flow worth Rs. 50, 000 by investing cash of Rs. 8, 000. If the economic depreciation is Rs. 10, 000, then find out the cash flow return on investment (CFROI). ■ ANS: 5% ■ What shall be the value of cash flow return on investment (CFROI) for a firm with a cash value added (CVA) of Rs. 20, 000, Operating cash flow of Rs. 1, 000, Economic depreciation of Rs. 20, 000 and WACC of 6%. ■ ANS: 8%
CASH VALUE ADDED (CVA) CVA is an absolute measure of sustainable value creation by the business.

Cash Value Added (CVA) ■ CVA= Operating Cash Flow – Economic Depreciation – Capital charge on Gross Investment ■ Where, Operating Cash Flow = NOPAT + Accounting Depreciation ■ Eco Dep * FVIFA (Replacement time years, at cost of capital) = Replacement fund Needed ■ Capital charge on Gross Investment = WACC * Cash Invested Originally.
Cash Value Added (CVA) ■ If CVA is +ve, the business is earning cash in excess of capital charge, even after making provision for asset replacement at the end of asset life i. e. Business seems to be sustainable for long time. ■ While CFROI is a relative measure, CVA is an absolute measure of Business sustainability. ■ EXAMPLE
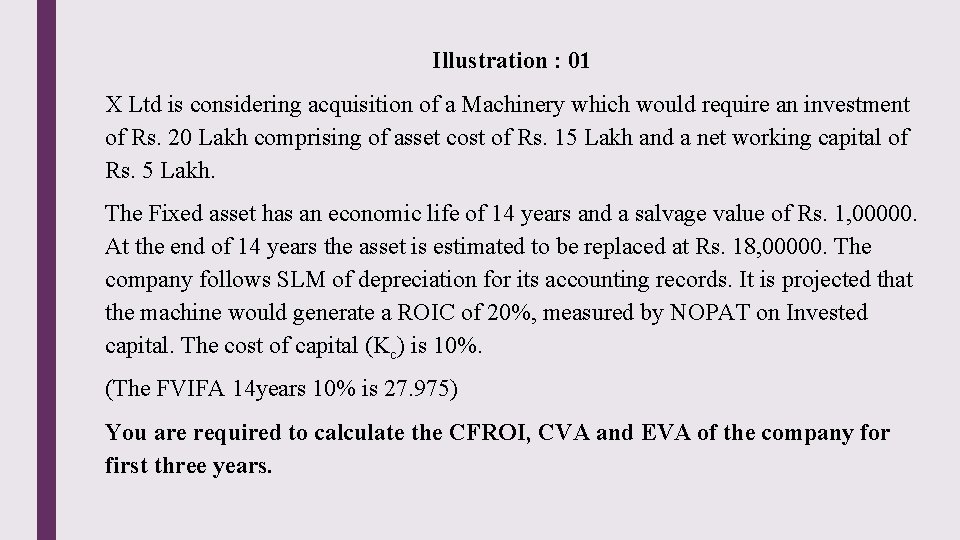
Illustration : 01 X Ltd is considering acquisition of a Machinery which would require an investment of Rs. 20 Lakh comprising of asset cost of Rs. 15 Lakh and a net working capital of Rs. 5 Lakh. The Fixed asset has an economic life of 14 years and a salvage value of Rs. 1, 00000. At the end of 14 years the asset is estimated to be replaced at Rs. 18, 00000. The company follows SLM of depreciation for its accounting records. It is projected that the machine would generate a ROIC of 20%, measured by NOPAT on Invested capital. The cost of capital (Kc) is 10%. (The FVIFA 14 years 10% is 27. 975) You are required to calculate the CFROI, CVA and EVA of the company for first three years.
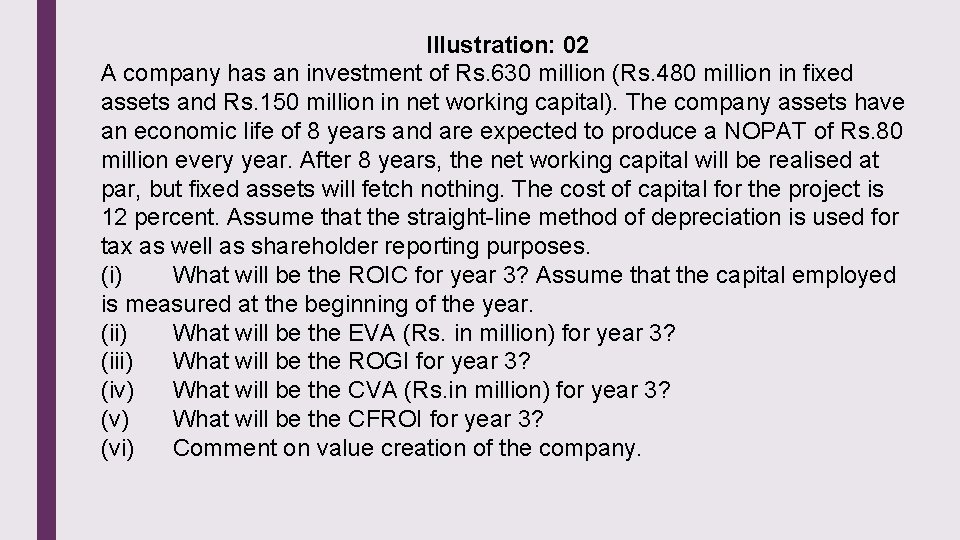
Illustration: 02 A company has an investment of Rs. 630 million (Rs. 480 million in fixed assets and Rs. 150 million in net working capital). The company assets have an economic life of 8 years and are expected to produce a NOPAT of Rs. 80 million every year. After 8 years, the net working capital will be realised at par, but fixed assets will fetch nothing. The cost of capital for the project is 12 percent. Assume that the straight-line method of depreciation is used for tax as well as shareholder reporting purposes. (i) What will be the ROIC for year 3? Assume that the capital employed is measured at the beginning of the year. (ii) What will be the EVA (Rs. in million) for year 3? (iii) What will be the ROGI for year 3? (iv) What will be the CVA (Rs. in million) for year 3? (v) What will be the CFROI for year 3? (vi) Comment on value creation of the company.
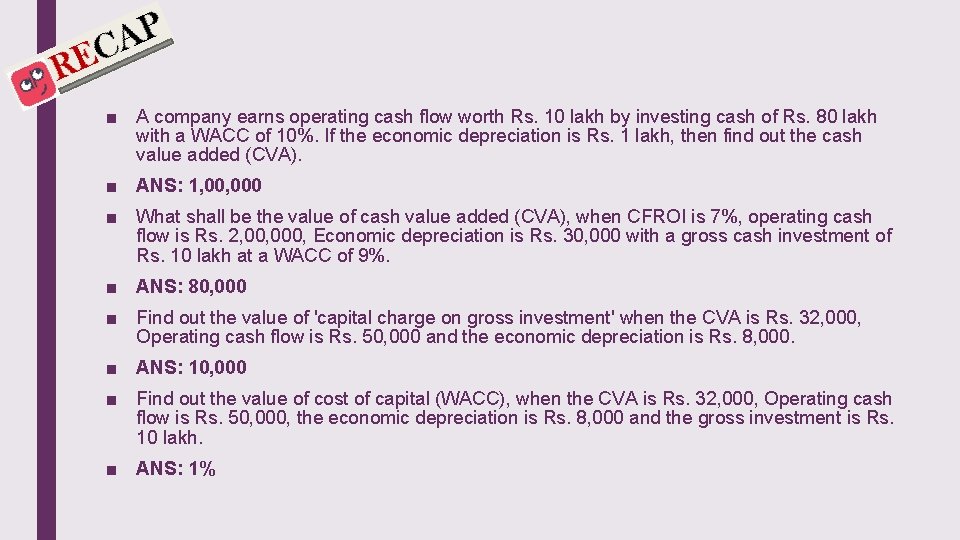
■ A company earns operating cash flow worth Rs. 10 lakh by investing cash of Rs. 80 lakh with a WACC of 10%. If the economic depreciation is Rs. 1 lakh, then find out the cash value added (CVA). ■ ANS: 1, 000 ■ What shall be the value of cash value added (CVA), when CFROI is 7%, operating cash flow is Rs. 2, 000, Economic depreciation is Rs. 30, 000 with a gross cash investment of Rs. 10 lakh at a WACC of 9%. ■ ANS: 80, 000 ■ Find out the value of 'capital charge on gross investment' when the CVA is Rs. 32, 000, Operating cash flow is Rs. 50, 000 and the economic depreciation is Rs. 8, 000. ■ ANS: 10, 000 ■ Find out the value of cost of capital (WACC), when the CVA is Rs. 32, 000, Operating cash flow is Rs. 50, 000, the economic depreciation is Rs. 8, 000 and the gross investment is Rs. 10 lakh. ■ ANS: 1%
MARKET-TOCAPITAL RATIO (MCR OR MBR) MCR measures value added to equity through capital market operations.
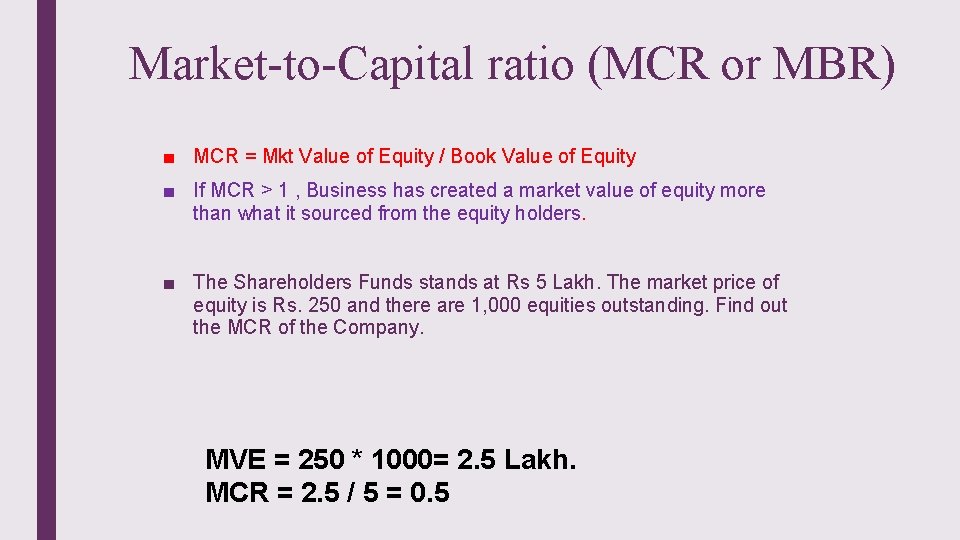
Market-to-Capital ratio (MCR or MBR) ■ MCR = Mkt Value of Equity / Book Value of Equity ■ If MCR > 1 , Business has created a market value of equity more than what it sourced from the equity holders. ■ The Shareholders Funds stands at Rs 5 Lakh. The market price of equity is Rs. 250 and there are 1, 000 equities outstanding. Find out the MCR of the Company. MVE = 250 * 1000= 2. 5 Lakh. MCR = 2. 5 / 5 = 0. 5
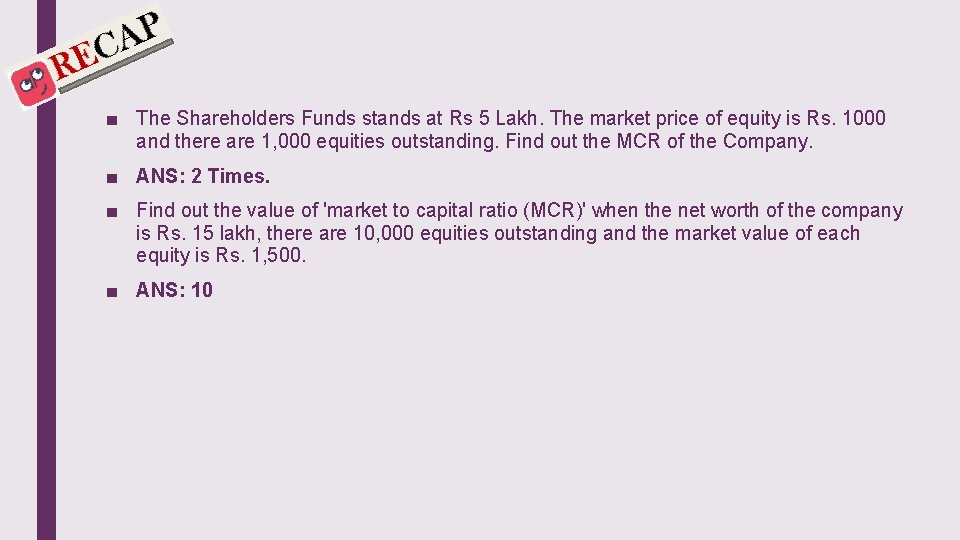
■ The Shareholders Funds stands at Rs 5 Lakh. The market price of equity is Rs. 1000 and there are 1, 000 equities outstanding. Find out the MCR of the Company. ■ ANS: 2 Times. ■ Find out the value of 'market to capital ratio (MCR)' when the net worth of the company is Rs. 15 lakh, there are 10, 000 equities outstanding and the market value of each equity is Rs. 1, 500. ■ ANS: 10

TOTAL RETURN TO SHAREHOLDERS (TRS) TRS is a comprehensive measure of returns earned by the shareholders.
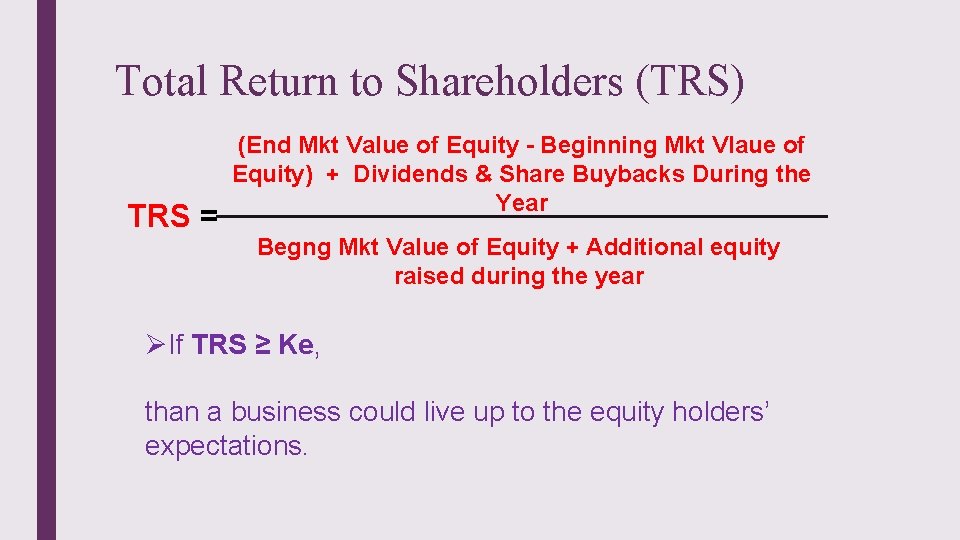
Total Return to Shareholders (TRS) TRS = (End Mkt Value of Equity - Beginning Mkt Vlaue of Equity) + Dividends & Share Buybacks During the Year Begng Mkt Value of Equity + Additional equity raised during the year ØIf TRS ≥ Ke, than a business could live up to the equity holders’ expectations.
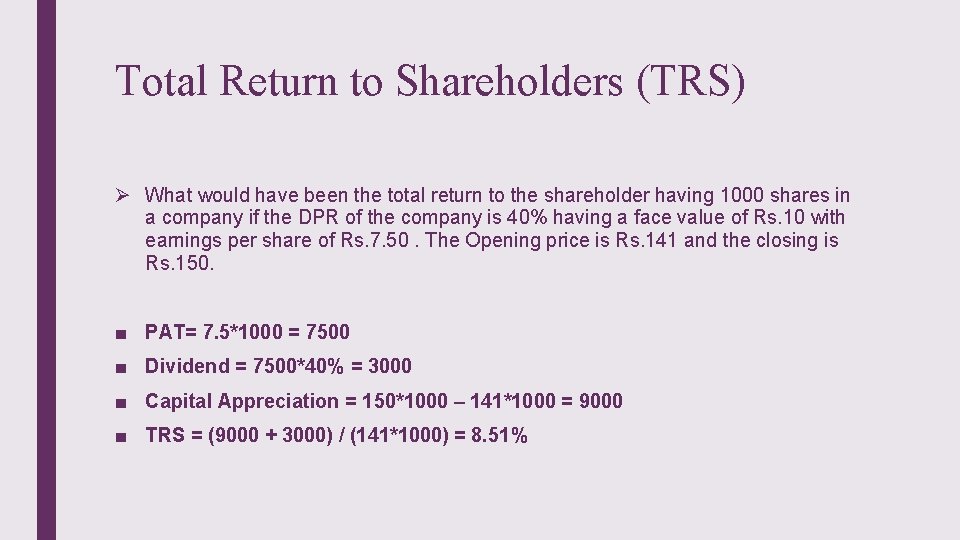
Total Return to Shareholders (TRS) Ø What would have been the total return to the shareholder having 1000 shares in a company if the DPR of the company is 40% having a face value of Rs. 10 with earnings per share of Rs. 7. 50. The Opening price is Rs. 141 and the closing is Rs. 150. ■ PAT= 7. 5*1000 = 7500 ■ Dividend = 7500*40% = 3000 ■ Capital Appreciation = 150*1000 – 141*1000 = 9000 ■ TRS = (9000 + 3000) / (141*1000) = 8. 51%
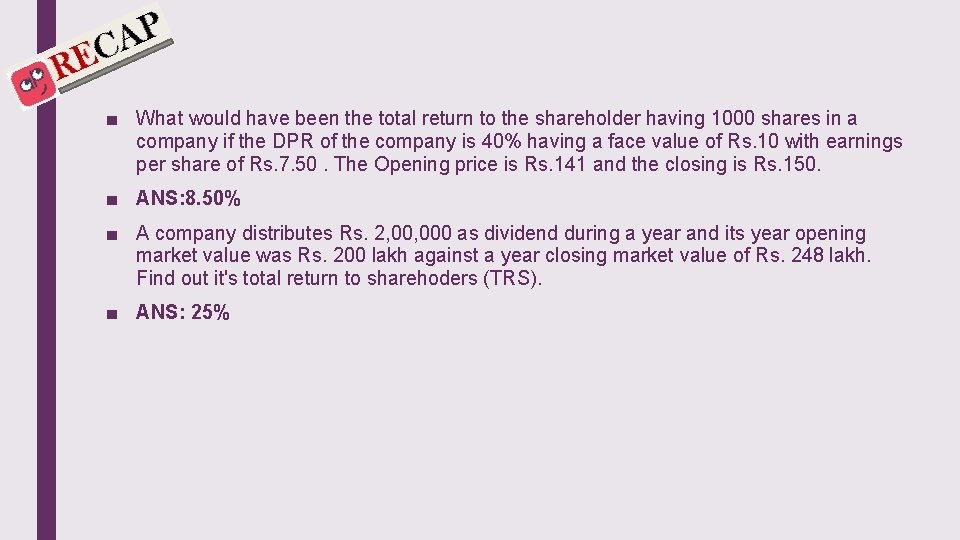
■ What would have been the total return to the shareholder having 1000 shares in a company if the DPR of the company is 40% having a face value of Rs. 10 with earnings per share of Rs. 7. 50. The Opening price is Rs. 141 and the closing is Rs. 150. ■ ANS: 8. 50% ■ A company distributes Rs. 2, 000 as dividend during a year and its year opening market value was Rs. 200 lakh against a year closing market value of Rs. 248 lakh. Find out it's total return to sharehoders (TRS). ■ ANS: 25%
FUTURE GROWTH VALUE (FGV) FGV measures the portion of market value attributed to EVA growth.
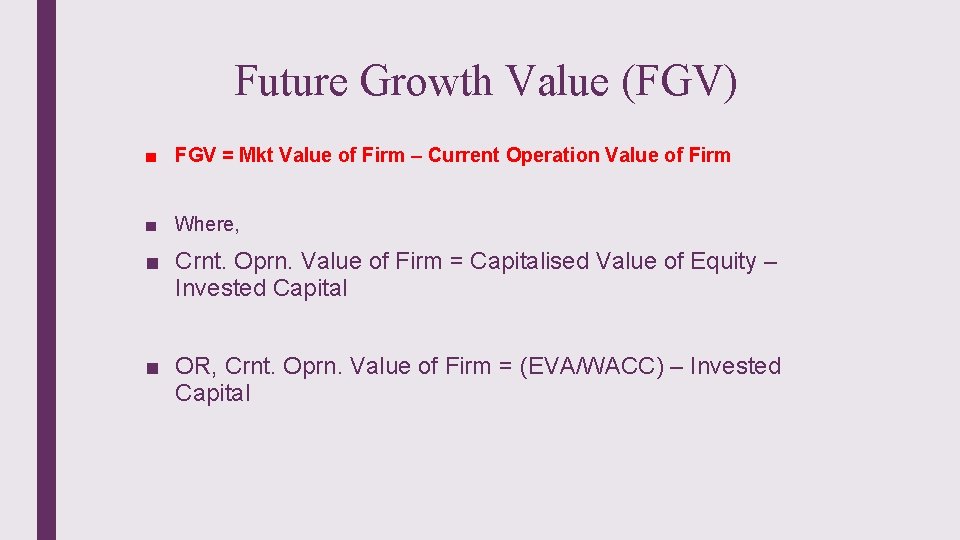
Future Growth Value (FGV) ■ FGV = Mkt Value of Firm – Current Operation Value of Firm ■ Where, ■ Crnt. Oprn. Value of Firm = Capitalised Value of Equity – Invested Capital ■ OR, Crnt. Oprn. Value of Firm = (EVA/WACC) – Invested Capital
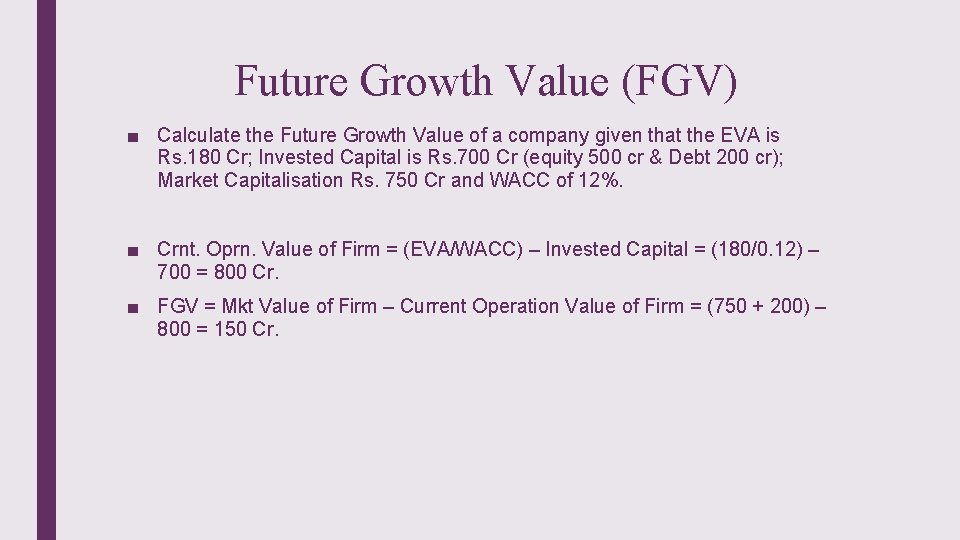
Future Growth Value (FGV) ■ Calculate the Future Growth Value of a company given that the EVA is Rs. 180 Cr; Invested Capital is Rs. 700 Cr (equity 500 cr & Debt 200 cr); Market Capitalisation Rs. 750 Cr and WACC of 12%. ■ Crnt. Oprn. Value of Firm = (EVA/WACC) – Invested Capital = (180/0. 12) – 700 = 800 Cr. ■ FGV = Mkt Value of Firm – Current Operation Value of Firm = (750 + 200) – 800 = 150 Cr.
FGV_Future Growth Value ■ Future Growth Value measures the portion of market value attributed to EVA growth. ■ FGV can be driven by market expectations of productivity improvements, organic growth, and value-creating acquisitions. ■ FGV component can be a useful tool in evaluating investors' assessment of the wealth creation potential of new strategies and opportunities.
■ Given that the EVA is Rs. 180 Cr; Invested Capital is Rs. 700 Cr (equity 500 cr & Debt 200 cr); Market-Capitalisation Rs. 750 Cr and WACC of 12%. Find out the Future Growth Value (FGV). ■ ANS: 150 crores
WEALTH ADDED INDEX (WAI) WAI measures the excess wealth generated above expectations
Wealth Added Index_ WAI ■ WAI is the excess wealth generated above expectations based on the perceived risk of the shares. ■ It is important to recognize that Wealth Added reflects returns for all equity investors, no matter when they bought their shares. ■ WAI = (Total Shareholder Return - Required Return) x Opening Market Cap
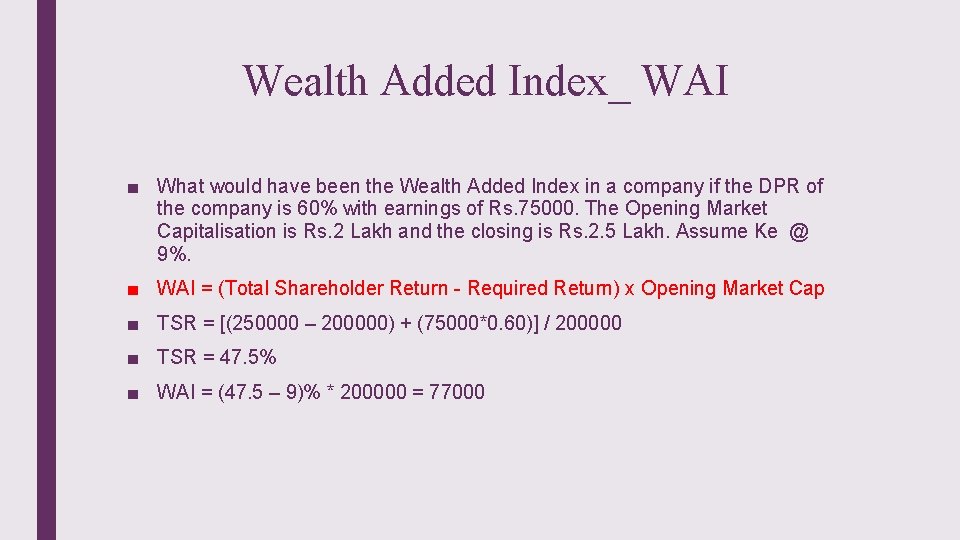
Wealth Added Index_ WAI ■ What would have been the Wealth Added Index in a company if the DPR of the company is 60% with earnings of Rs. 75000. The Opening Market Capitalisation is Rs. 2 Lakh and the closing is Rs. 2. 5 Lakh. Assume Ke @ 9%. ■ WAI = (Total Shareholder Return - Required Return) x Opening Market Cap ■ TSR = [(250000 – 200000) + (75000*0. 60)] / 200000 ■ TSR = 47. 5% ■ WAI = (47. 5 – 9)% * 200000 = 77000
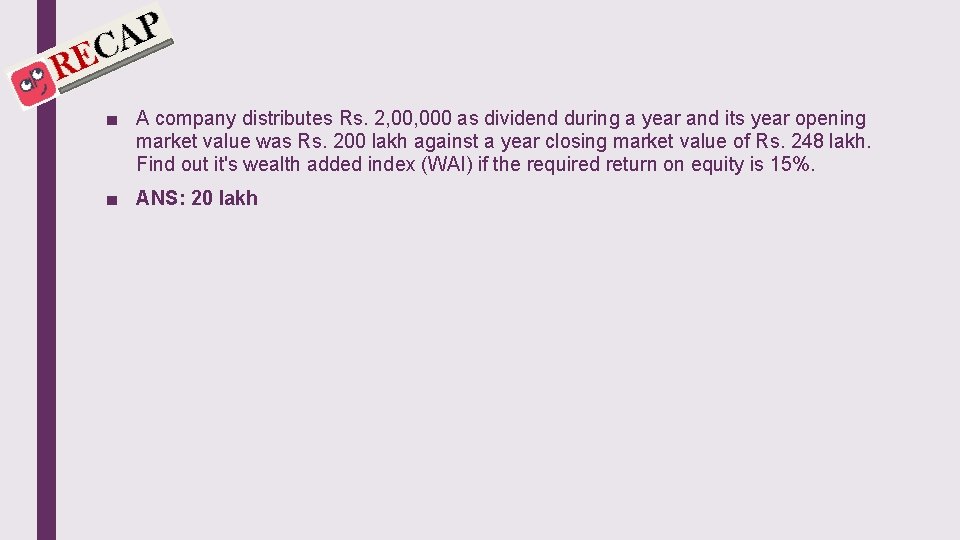
■ A company distributes Rs. 2, 000 as dividend during a year and its year opening market value was Rs. 200 lakh against a year closing market value of Rs. 248 lakh. Find out it's wealth added index (WAI) if the required return on equity is 15%. ■ ANS: 20 lakh
APPROACHES TO VBM
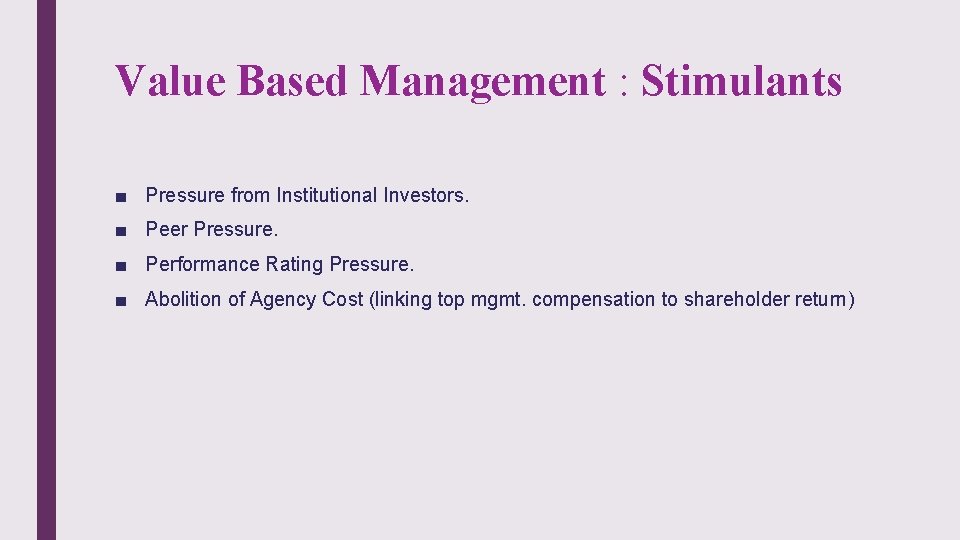
Value Based Management : Stimulants ■ Pressure from Institutional Investors. ■ Peer Pressure. ■ Performance Rating Pressure. ■ Abolition of Agency Cost (linking top mgmt. compensation to shareholder return)
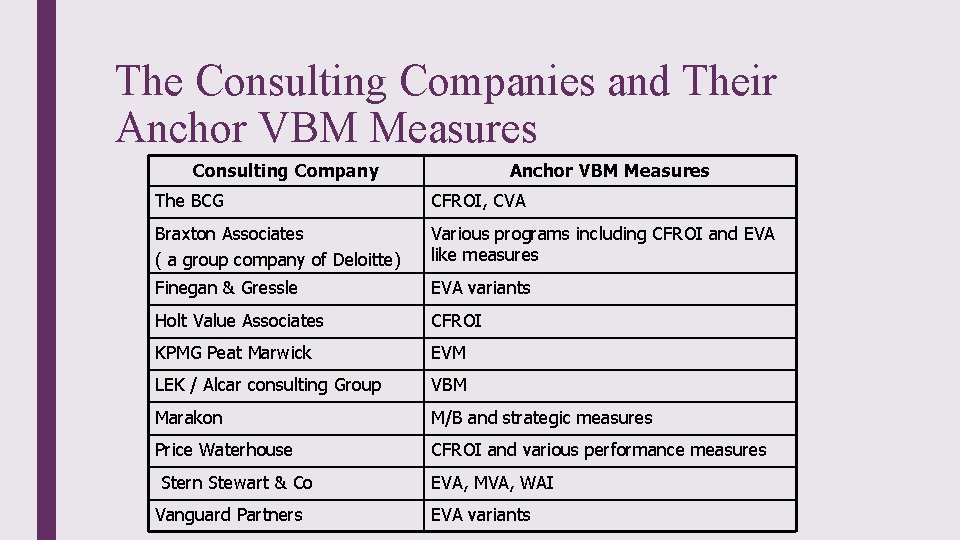
The Consulting Companies and Their Anchor VBM Measures Consulting Company Anchor VBM Measures The BCG CFROI, CVA Braxton Associates ( a group company of Deloitte) Various programs including CFROI and EVA like measures Finegan & Gressle EVA variants Holt Value Associates CFROI KPMG Peat Marwick EVM LEK / Alcar consulting Group VBM Marakon M/B and strategic measures Price Waterhouse CFROI and various performance measures Stern Stewart & Co Vanguard Partners EVA, MVA, WAI EVA variants
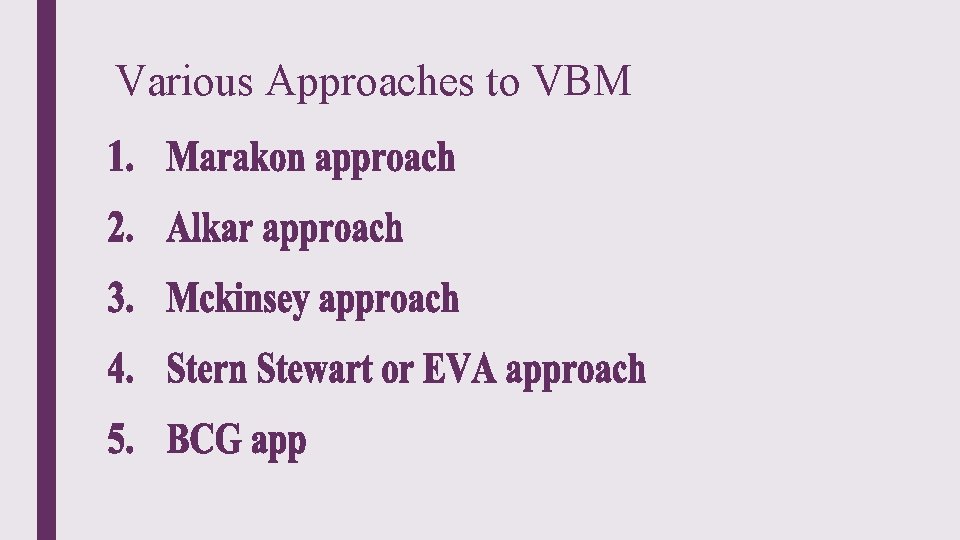
Various Approaches to VBM
MARAKON APPROACH
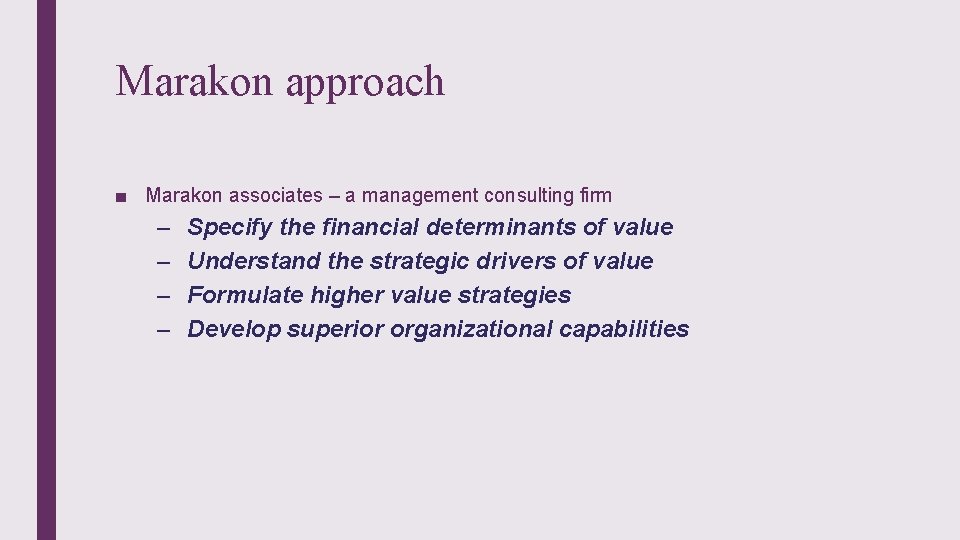
Marakon approach ■ Marakon associates – a management consulting firm – – Specify the financial determinants of value Understand the strategic drivers of value Formulate higher value strategies Develop superior organizational capabilities
Marakon approach…. contd ■ 1. Specify financial determinants of value – Based on market to book ratio model – Shareholder wealth creation is the difference between market value (M) and book value (B) of a firms equity
Marakon approach…. contd ■ The Book value of equity, measures approximately the capital contributed by the shareholders ■ The Market value of equity reflects how productively the firm has employed the capital contributed by the shareholders, as assessed by the stock market – Hence if M > B value is created and – if M < B value is destroyed
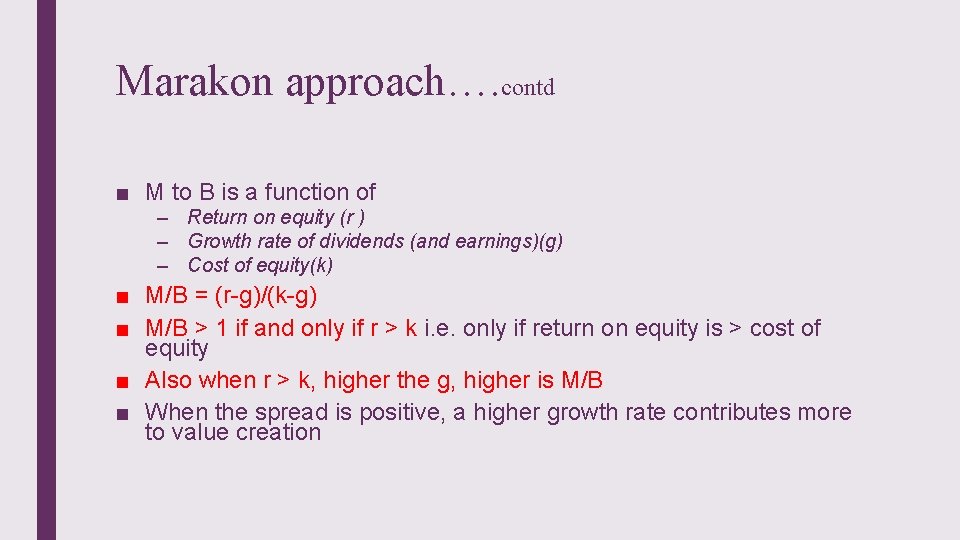
Marakon approach…. contd ■ M to B is a function of – Return on equity (r ) – Growth rate of dividends (and earnings)(g) – Cost of equity(k) ■ M/B = (r-g)/(k-g) ■ M/B > 1 if and only if r > k i. e. only if return on equity is > cost of equity ■ Also when r > k, higher the g, higher is M/B ■ When the spread is positive, a higher growth rate contributes more to value creation
Marakon approach…. contd (illustration) 1. If the ROE is 20%, cost of equity is 12% and growth rate of dividends is 7% then find out the M/B. i. If the ROE increases to 25% what would be the new M/B? ii. If the growth rate of dividend increases to 10%, what would be the new M/B? iii. How does the cost of equity and Growth rate of dividends affect the Value of the firm?
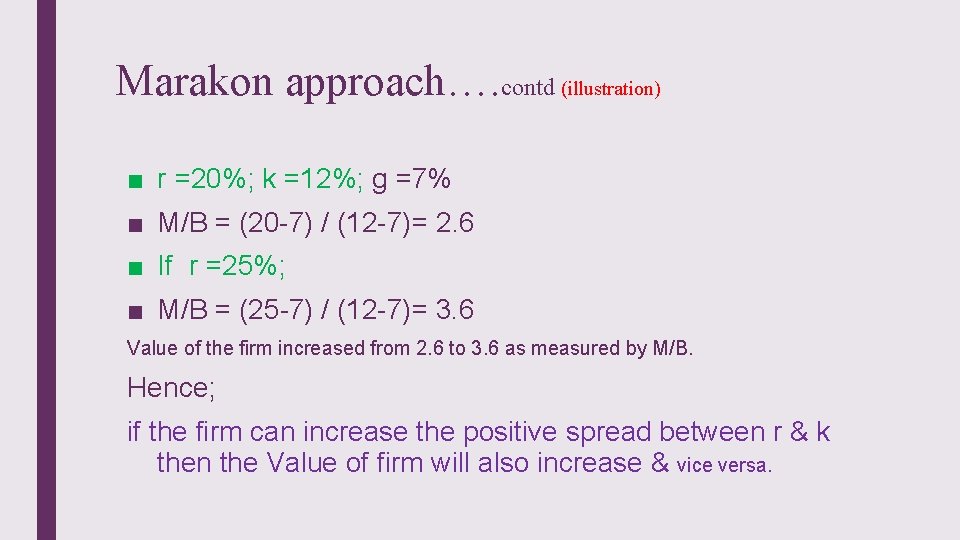
Marakon approach…. contd (illustration) ■ r =20%; k =12%; g =7% ■ M/B = (20 -7) / (12 -7)= 2. 6 ■ Iff r =25%; ■ M/B = (25 -7) / (12 -7)= 3. 6 Value of the firm increased from 2. 6 to 3. 6 as measured by M/B. Hence; if the firm can increase the positive spread between r & k then the Value of firm will also increase & vice versa.
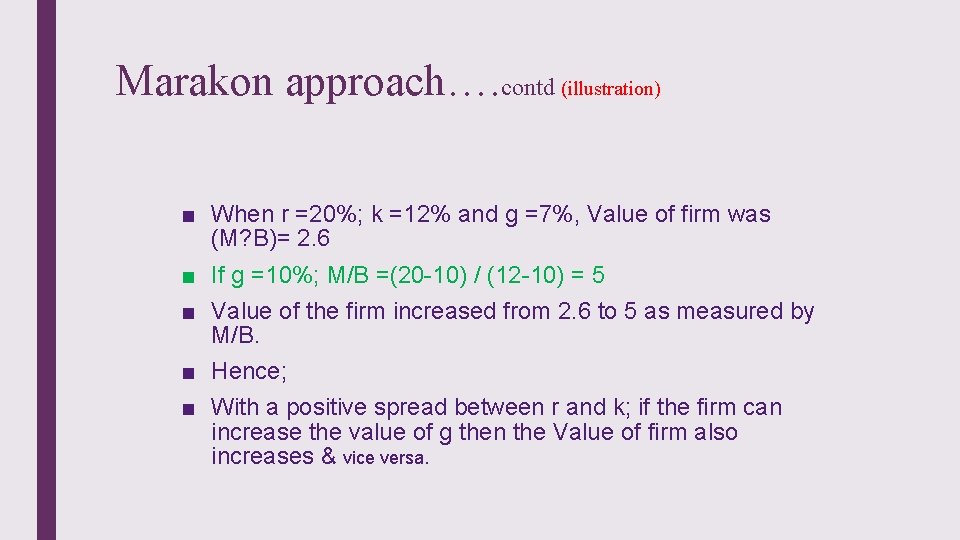
Marakon approach…. contd (illustration) ■ When r =20%; k =12% and g =7%, Value of firm was (M? B)= 2. 6 ■ If g =10%; M/B =(20 -10) / (12 -10) = 5 ■ Value of the firm increased from 2. 6 to 5 as measured by M/B. ■ Hence; ■ With a positive spread between r and k; if the firm can increase the value of g then the Value of firm also increases & vice versa.
Marakon approach…. contd ■ 2. Understand the strategic drivers of value ■ HOW to Increase the +ve Spread b/w r and k; and How to Increase g – Market economics or Profitability ■ Refers to structural factors which determine the average equity spread as well as the growth rate applicable to all competitors in a particular market segment – – – Intensity of direct / indirect competition Threat of entry Supplier pressures Regulatory pressures Customer pressures
Marakon approach…. contd – Competitive position – – Product differentiation (customers willing to pay a premium) Economic cost position (lower total economic costs per unit than the market average) ■ Economic cost = operating cost + charge for capital employed ■ Access to cheaper raw materials ■ Efficient process technology ■ Access to low cost distribution channels ■ Superior management ■ Economies of scale in some markets
Marakon approach…. contd ■ 3. Formulate higher value strategies – Participation strategy ■ Corporate level – – Which new business the firm will enter Which existing business the firm will exit ■ Business unit level – – Which unserved market/ segment will the firm enter Which served market/ segment will the firm exit – Competitive Strategy – – – Differentiate the products Manage the business unit costs Pricing the product
Marakon approach…. contd – 4. Develop superior organizational capabilities by overcoming internal barriers ■ Top management team fully committed to the goal of Value maximization ■ Corporate governance that promotes highest degree of accountability for creation or destruction of value ■ Top management compensation plan guided by the principle of ‘relative pay for relative performance’ ■ Proper Resource allocation system ■ Well laid out performance management system which is founded on two basic principles of – – Performance targets driven by plans Performance contracts should be fully honored by both sides
Marakon approach…. contd ■ Limitations of Marakon approach – The spread between ROE and Ke are not comparable as one is an accounting measure and the other is market based. – The positive spread may be due to accounting policies. ■ Advantages of Marakon approach – ROE, Ke are widely used parameters. – Intuitively appealing valuation theory – MV of the firm is an external scorecard
Marakon Approach_Problems 2. The return on equity is 20% and cost of equity is 14%. If the retention ratio is 60% and the book value per share is Rs. 50, then – What is the growth rate of the firm? – What is the Market value of equity as per marakon model? – What is the value creation index of the firm?
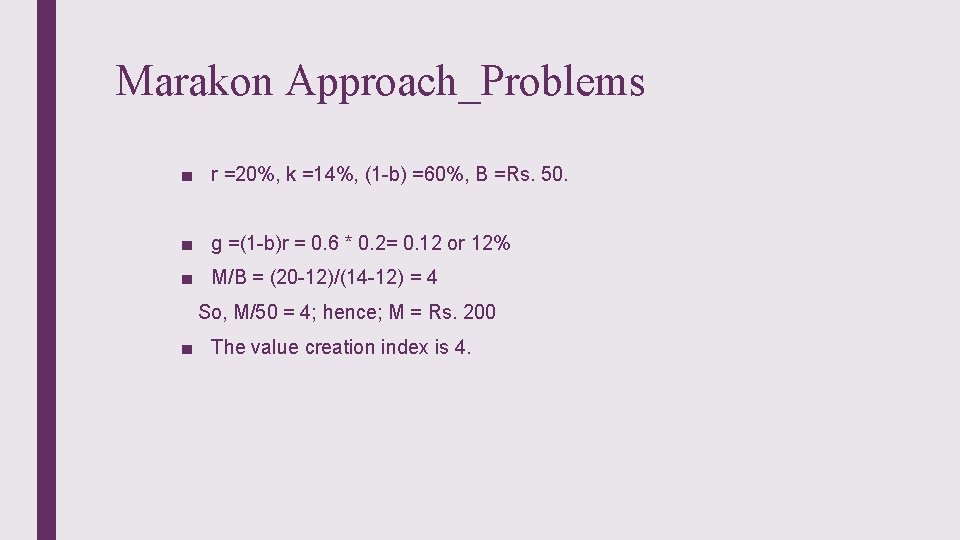
Marakon Approach_Problems ■ r =20%, k =14%, (1 -b) =60%, B =Rs. 50. ■ g =(1 -b)r = 0. 6 * 0. 2= 0. 12 or 12% ■ M/B = (20 -12)/(14 -12) = 4 So, M/50 = 4; hence; M = Rs. 200 ■ The value creation index is 4.
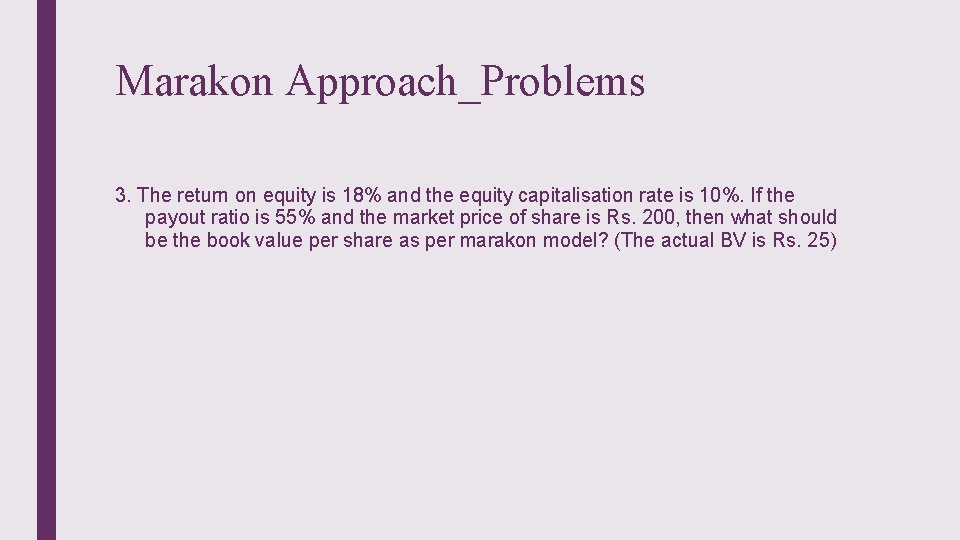
Marakon Approach_Problems 3. The return on equity is 18% and the equity capitalisation rate is 10%. If the payout ratio is 55% and the market price of share is Rs. 200, then what should be the book value per share as per marakon model? (The actual BV is Rs. 25)
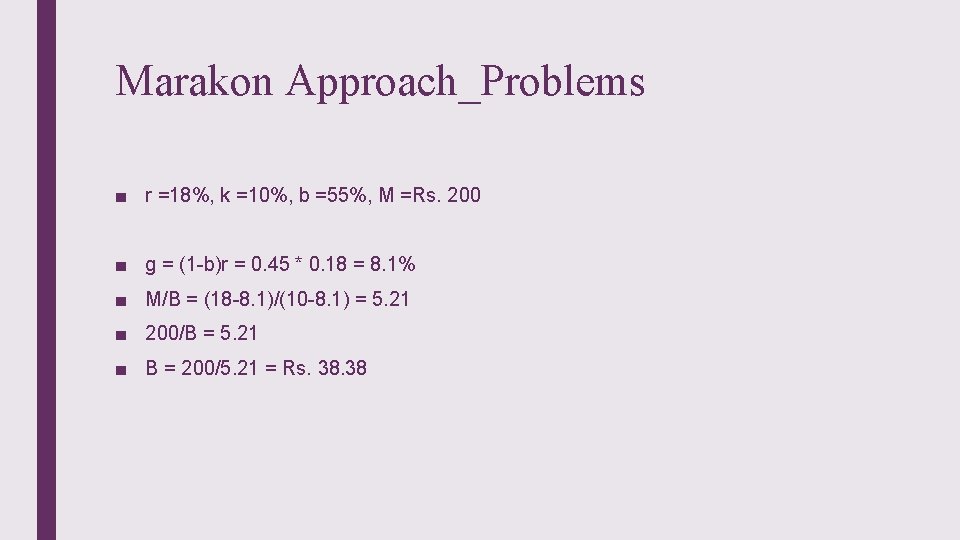
Marakon Approach_Problems ■ r =18%, k =10%, b =55%, M =Rs. 200 ■ g = (1 -b)r = 0. 45 * 0. 18 = 8. 1% ■ M/B = (18 -8. 1)/(10 -8. 1) = 5. 21 ■ 200/B = 5. 21 ■ B = 200/5. 21 = Rs. 38
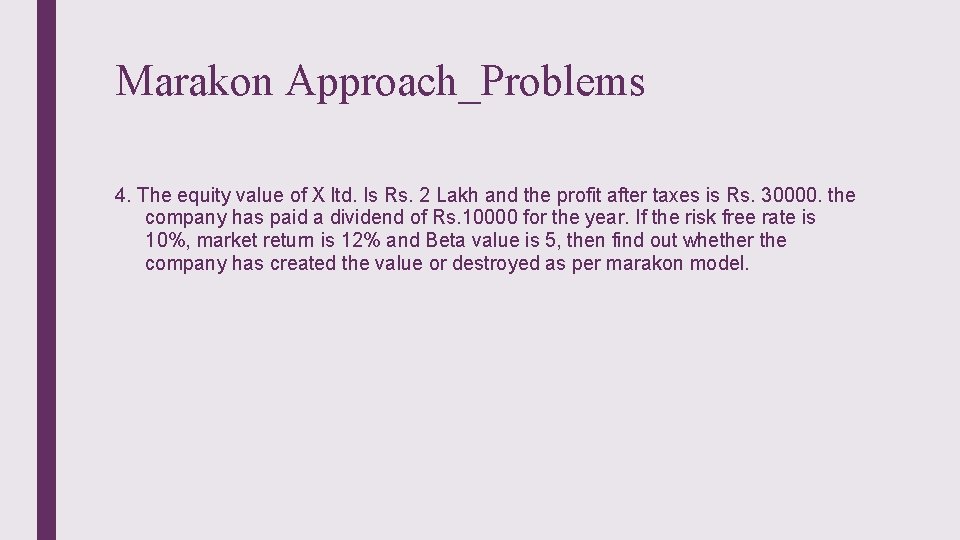
Marakon Approach_Problems 4. The equity value of X ltd. Is Rs. 2 Lakh and the profit after taxes is Rs. 30000. the company has paid a dividend of Rs. 10000 for the year. If the risk free rate is 10%, market return is 12% and Beta value is 5, then find out whether the company has created the value or destroyed as per marakon model.
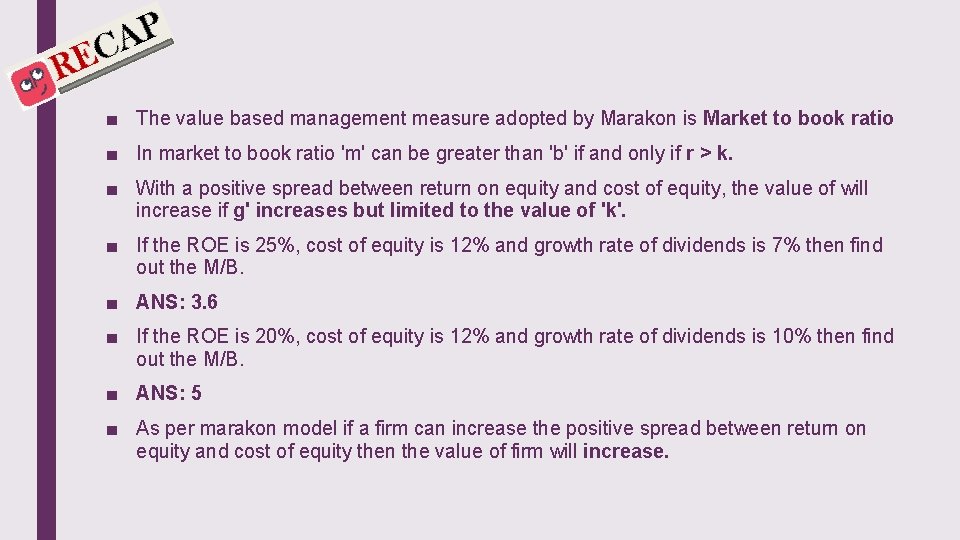
■ The value based management measure adopted by Marakon is Market to book ratio ■ In market to book ratio 'm' can be greater than 'b' if and only if r > k. ■ With a positive spread between return on equity and cost of equity, the value of will increase if g' increases but limited to the value of 'k'. ■ If the ROE is 25%, cost of equity is 12% and growth rate of dividends is 7% then find out the M/B. ■ ANS: 3. 6 ■ If the ROE is 20%, cost of equity is 12% and growth rate of dividends is 10% then find out the M/B. ■ ANS: 5 ■ As per marakon model if a firm can increase the positive spread between return on equity and cost of equity then the value of firm will increase.
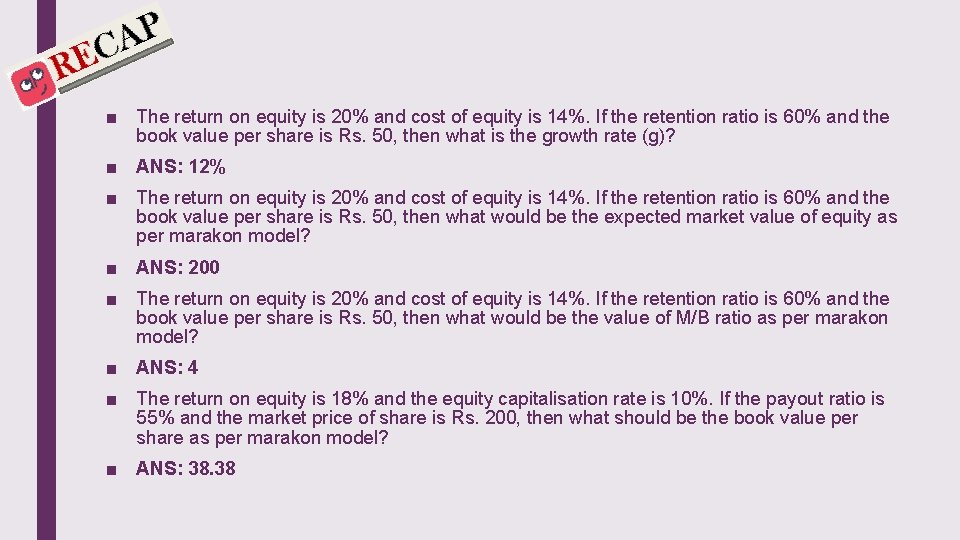
■ The return on equity is 20% and cost of equity is 14%. If the retention ratio is 60% and the book value per share is Rs. 50, then what is the growth rate (g)? ■ ANS: 12% ■ The return on equity is 20% and cost of equity is 14%. If the retention ratio is 60% and the book value per share is Rs. 50, then what would be the expected market value of equity as per marakon model? ■ ANS: 200 ■ The return on equity is 20% and cost of equity is 14%. If the retention ratio is 60% and the book value per share is Rs. 50, then what would be the value of M/B ratio as per marakon model? ■ ANS: 4 ■ The return on equity is 18% and the equity capitalisation rate is 10%. If the payout ratio is 55% and the market price of share is Rs. 200, then what should be the book value per share as per marakon model? ■ ANS: 38. 38
MCKINSEY APPROACH
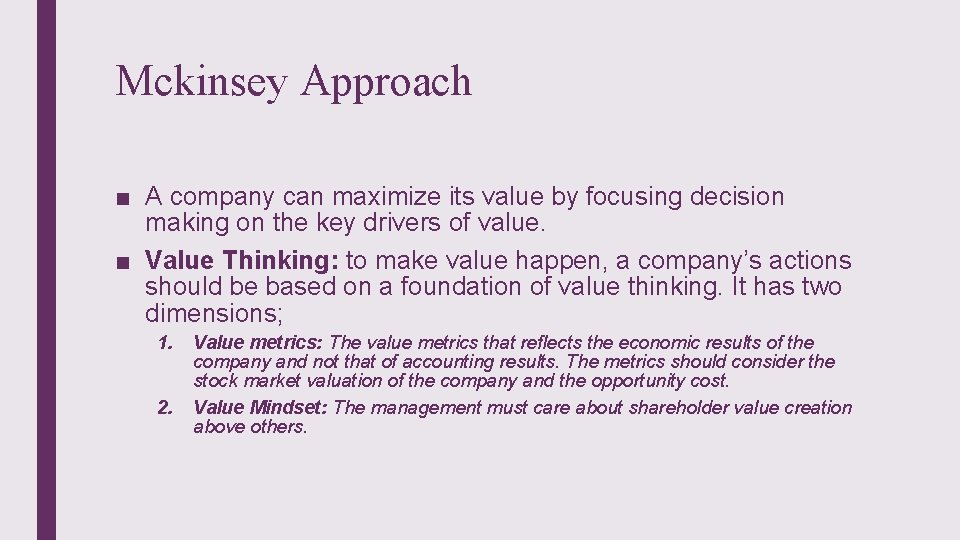
Mckinsey Approach ■ A company can maximize its value by focusing decision making on the key drivers of value. ■ Value Thinking: to make value happen, a company’s actions should be based on a foundation of value thinking. It has two dimensions; 1. 2. Value metrics: The value metrics that reflects the economic results of the company and not that of accounting results. The metrics should consider the stock market valuation of the company and the opportunity cost. Value Mindset: The management must care about shareholder value creation above others.

Mckinsey Approach: Creating SHARE HOLDERS VALUE SHAREHOLDER VALUE Aspirations and targets Portfolio management Organizational design Value driver definition Business performance management Value Metrics Individual performance management Value Thinking Value Mindset
4. STERN STEWART APPROACH EVA® Approach
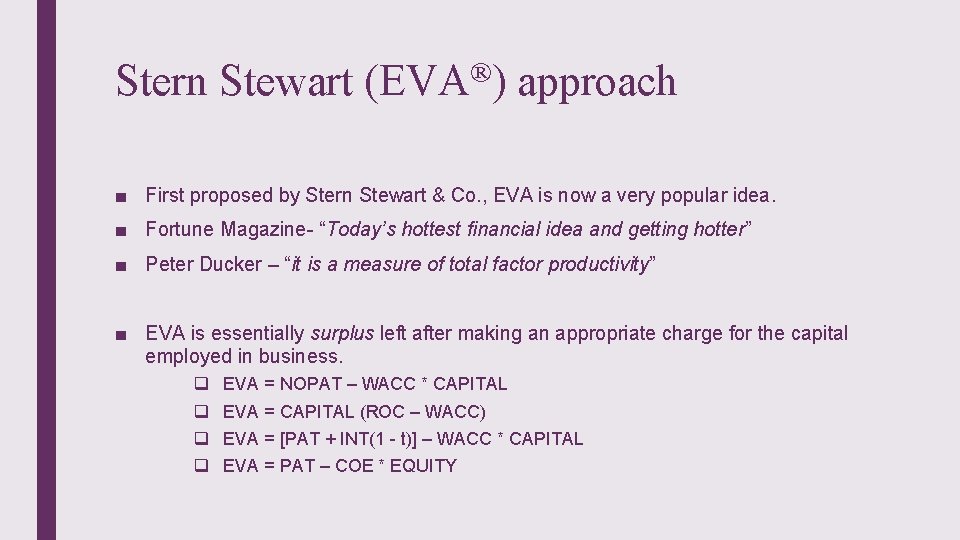
Stern Stewart (EVA®) approach ■ First proposed by Stern Stewart & Co. , EVA is now a very popular idea. ■ Fortune Magazine- “Today’s hottest financial idea and getting hotter” ■ Peter Ducker – “it is a measure of total factor productivity” ■ EVA is essentially surplus left after making an appropriate charge for the capital employed in business. q q EVA = NOPAT – WACC * CAPITAL EVA = CAPITAL (ROC – WACC) EVA = [PAT + INT(1 - t)] – WACC * CAPITAL EVA = PAT – COE * EQUITY
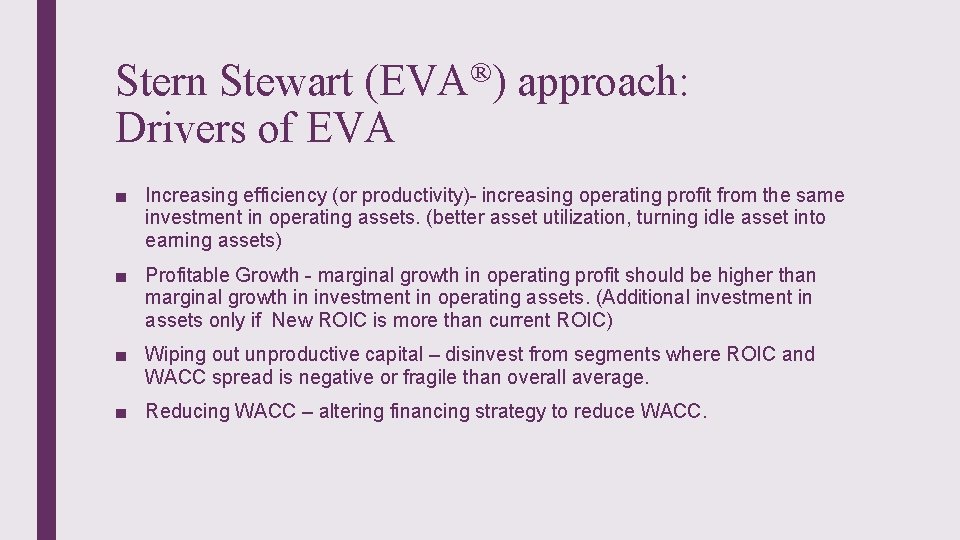
Stern Stewart (EVA®) approach: Drivers of EVA ■ Increasing efficiency (or productivity)- increasing operating profit from the same investment in operating assets. (better asset utilization, turning idle asset into earning assets) ■ Profitable Growth - marginal growth in operating profit should be higher than marginal growth in investment in operating assets. (Additional investment in assets only if New ROIC is more than current ROIC) ■ Wiping out unproductive capital – disinvest from segments where ROIC and WACC spread is negative or fragile than overall average. ■ Reducing WACC – altering financing strategy to reduce WACC.
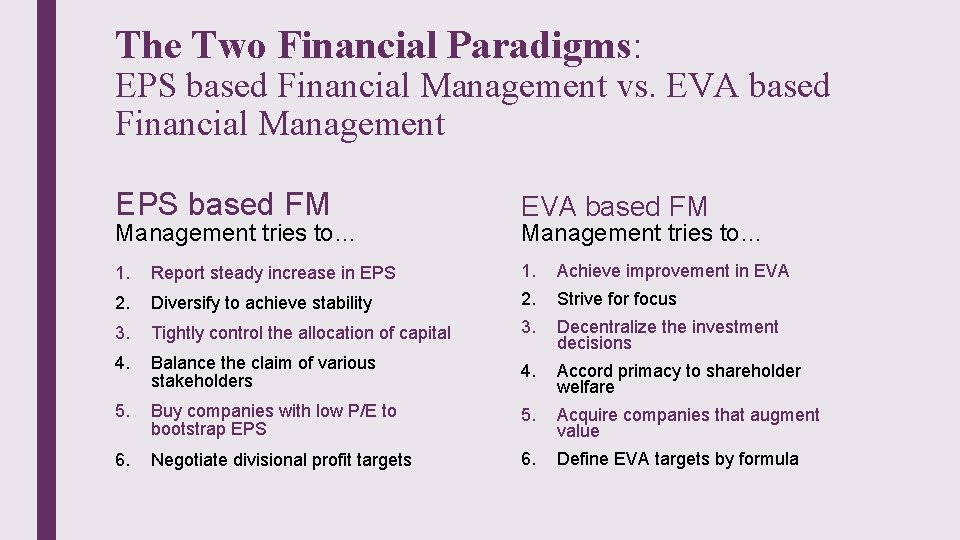
The Two Financial Paradigms: EPS based Financial Management vs. EVA based Financial Management EPS based FM EVA based FM 1. Report steady increase in EPS 1. Achieve improvement in EVA 2. Diversify to achieve stability 2. Strive for focus 3. Tightly control the allocation of capital 3. 4. Decentralize the investment decisions Balance the claim of various stakeholders 4. Accord primacy to shareholder welfare 5. Buy companies with low P/E to bootstrap EPS 5. Acquire companies that augment value 6. Negotiate divisional profit targets 6. Define EVA targets by formula Management tries to…
5. BCG APPROACH
BCG Approach ■ Two Corner concepts; – Total Return to Shareholder(TRS) – Total Business Return (TBR) ■ For applying these concepts Two performance matrices are developed; – Cash Flow Return on Investment (CFROI) – Cash Value Added (CVA)
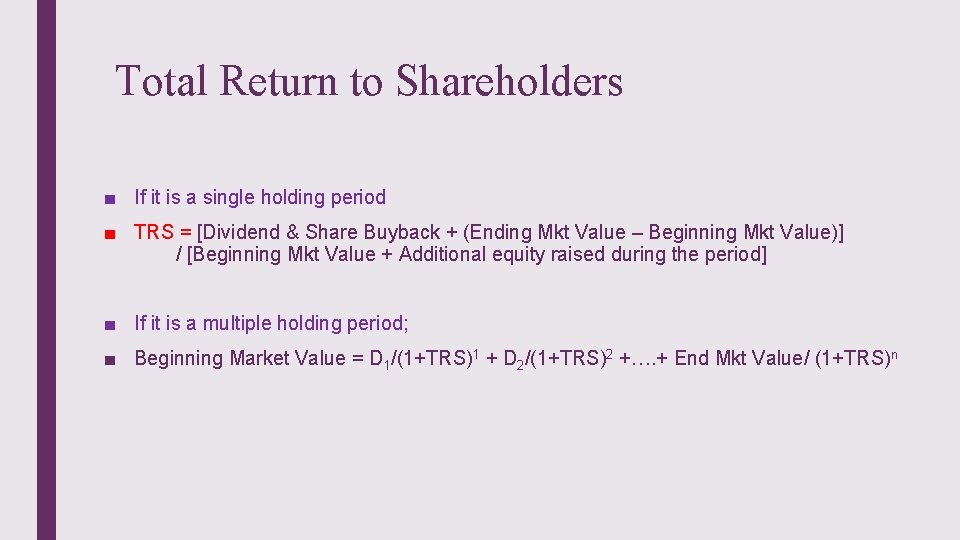
Total Return to Shareholders ■ If it is a single holding period ■ TRS = [Dividend & Share Buyback + (Ending Mkt Value – Beginning Mkt Value)] / [Beginning Mkt Value + Additional equity raised during the period] ■ If it is a multiple holding period; ■ Beginning Market Value = D 1/(1+TRS)1 + D 2/(1+TRS)2 +…. + End Mkt Value/ (1+TRS)n
TRS: Credibility ■ It is comprehensive as it includes both dividends and capital gain. ■ It is widely used by investment community and also required by SEC. ■ TSR can be easily benchmarked against the mkt or peer groups ■ TSR is not biased by size ■ TSR is difficult to manipulate
BCG approach…contd. ■ Drivers of TRS – Profitability, growth and free cash flow ■ ■ Capital gains is driven by the first two Free cash flow drives the dividend payout, buyback of shares. – A TRS > Ke, is a proxy for Return, Earnings and Value added measures for equity holders.
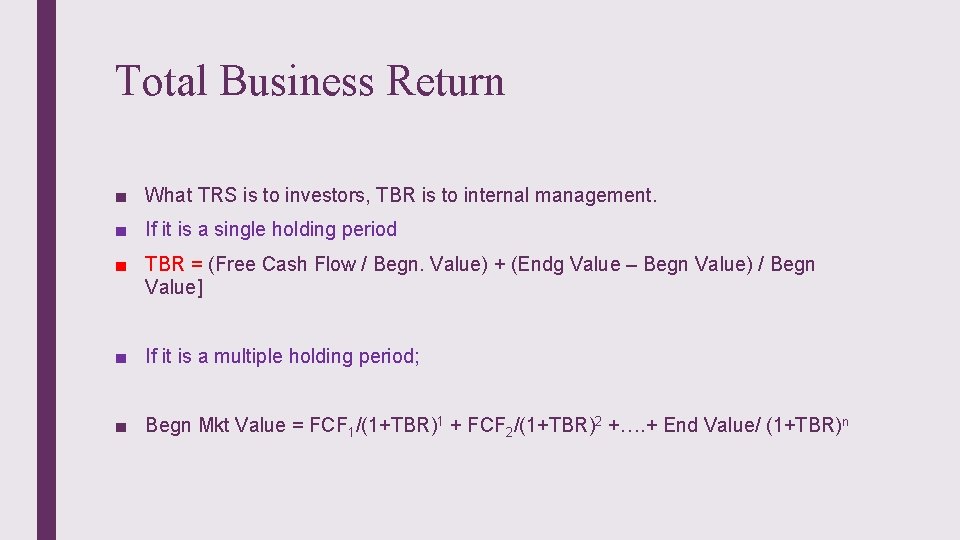
Total Business Return ■ What TRS is to investors, TBR is to internal management. ■ If it is a single holding period ■ TBR = (Free Cash Flow / Begn. Value) + (Endg Value – Begn Value) / Begn Value] ■ If it is a multiple holding period; ■ Begn Mkt Value = FCF 1/(1+TBR)1 + FCF 2/(1+TBR)2 +…. + End Value/ (1+TBR)n
BCG approach…contd. ■ CFROI and CVA ■ CFROI = (Operating Cash Flow – Economic Depreciation) / Cash Invested ■ If CFROI > Kc, the business is earning cash in excess of capital charge, even after making provision for asset replacement at the end of asset life i. e. Business seems to be sustainable for long time. ■ Drivers of CFROI- Efficiency, Profitable growth and wiping out unproductive capital.

BCG approach…contd. ■ CVA= Operating Cash Flow – Economic Depreciation – Capital charge on Gross Investment ■ While CFROI is a relative measure, CVA is an absolute measure of Business sustainability. ■ If CVA is +ve, the business is earning cash in excess of capital charge, even after making provision for asset replacement at the end of asset life i. e. Business seems to be sustainable for long time. – BCG advocates Cash Value Added as superior to EVA. – Drivers of CVA - Efficiency, Profitable growth and wiping out unproductive capital.
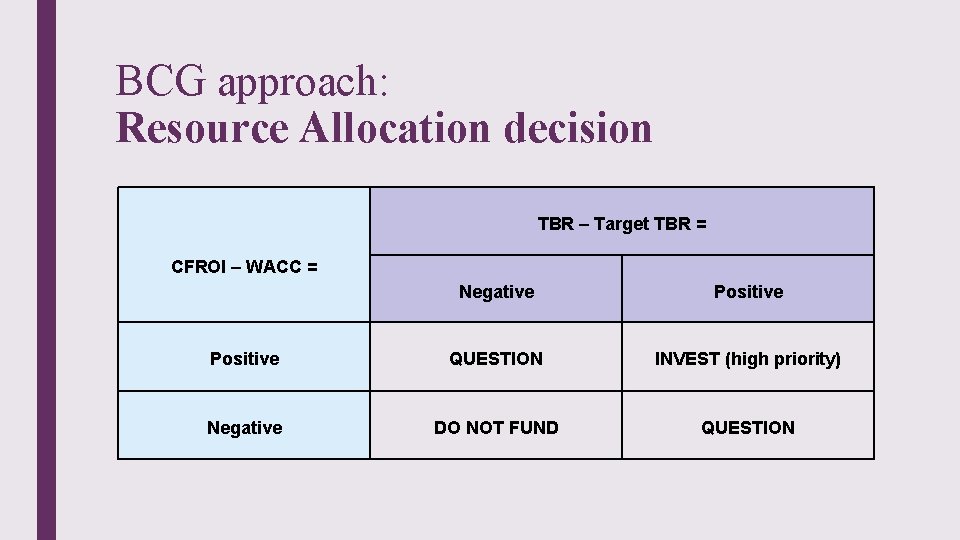
BCG approach: Resource Allocation decision TBR – Target TBR = CFROI – WACC = Negative Positive QUESTION INVEST (high priority) Negative DO NOT FUND QUESTION
Drivers of Value ■ BUT it is interesting to note that drivers of CFROI/ CVA / EVA are same and they are; Ø Efficiency, Ø Profitable growth and Ø Wiping out unproductive capital.
- Slides: 86