
Unit 3 Personal Business Finance Mr Barry Year
Unit 3 Personal & Business Finance Mr. Barry Year 12 Business BTEC
Introduction • It is impossible to truly understand how a business operates without some knowledge of the accounting process • You may be familiar with the expression ‘a picture paints a thousand words’ – in business you can adapt this to ‘numbers paint a thousand words’ • However good a business idea might be, if the owner does not keep a careful eye on the business’s accounts, it is almost certain to be doomed to failure Mr. Barry Year 12 Business BTEC
Purpose of accounting • Accounting involves the recording of financial transactions, planned or actual, and the use of these figures to produce financial information. • In this first section, you will look at a number of reasons why accounting is important to business success Mr. Barry Year 12 Business BTEC
Business Transactions • What does it involve? § Purchasing resources e. g. raw materials, labour, capital equipment, land (can be called factors of production). § Selling goods and services that have been produced or purchased from a supplier § The business needs to keep a record of ALL transactions. The use of till rolls record sales, invoices record purchases which are entered into a Purchases Book. Mr. Barry A-level Accounting Year 12
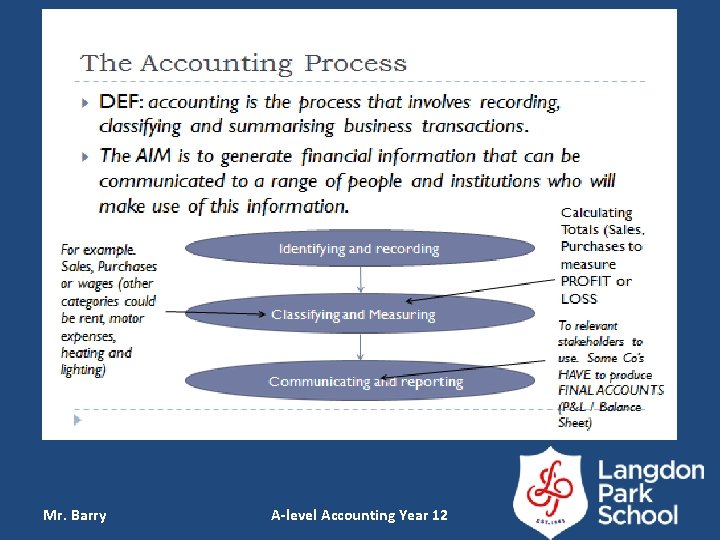
Mr. Barry A-level Accounting Year 12
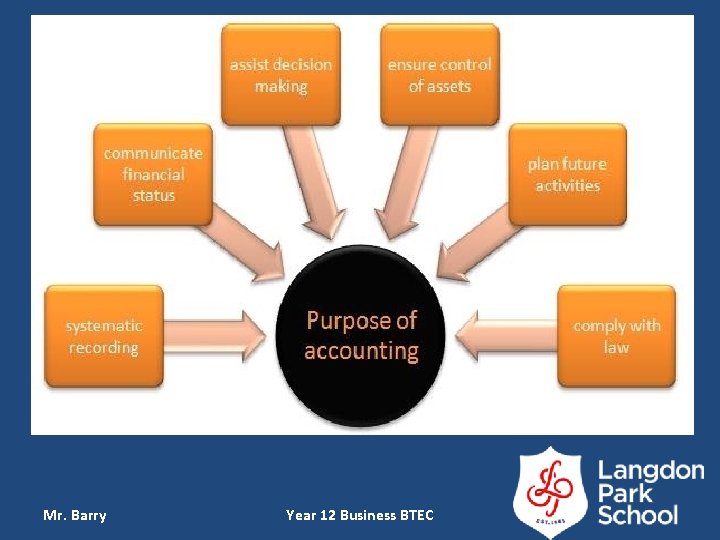
Mr. Barry Year 12 Business BTEC
Systematic recording of transactions • Keeping business records accurate and up to date is important for the smooth running of a business. • The business owner or a bookkeeper must record all of the money coming into the business (from sales) and all of the money going out, such as expenses. • If a business fails to do this it may find itself not chasing payments, forgetting to pay bills or, even more seriously, in trouble with HM Revenue & Customs (HMRC). • If the business does not record its transactions correctly, it cannot report its financial performance accurately and therefore tax payments may be wrong Mr. Barry Year 12 Business BTEC
Management of the business • A manager is responsible for the planning, monitoring and controlling of the resources for which they are responsible. • A manager who clearly understands the business’s accounts will be better able to make informed decisions and plan for the future. • Management of a business involves careful coordination of resources including staff, materials, stock and money. The manager must ensure there are sufficient funds to pay wages, order new stock, pay bills and meet other demands for cash outflows by balancing this with the money coming in from sales. Mr. Barry Year 12 Business BTEC
Compliance • Financial reporting is governed by laws and regulations. This is to ensure that any financial records give a fair and accurate picture of the business. • It is important that businesses comply with these laws and regulations in order to ensure that investors and other stakeholders are not misinformed. • Compliance will also help protect against fraud. • Fraud is when company monies are used inappropriately or acquired by the • wrong person for personal gain. Mr. Barry Year 12 Business BTEC
Question to consider • What are the main purposes of these laws and regulations? • How do the reporting requirements vary between organisations? • Why do you think it is important for financial reporting to be regulated? End Mr. Barry Year 12 Business BTEC
Research • In pairs research the laws and regulations that govern financial reporting in the UK. Some useful websites to get you started are: 1. www. gov. uk/guidance/audit-accounting-andreporting-guidance-for-ukcompanies 2. www. frc. org. uk/ 3. www. icaew. com/en/technical/financialreporting/other-reporting-issues/otherukregulation. 5 minutes Mr. Barry Year 12 Business BTEC
Measuring performance • Without financial records it would be impossible to know if the business was making a profit or a loss, or whether or not the business was owed money or was in debt to others. Mr. Barry Year 12 Business BTEC
Activity What is meant by the following terms: 1. Profit 3 minutes 2. Loss 3. Gross profit 4. Sales revenue 5. Net profit End Mr. Barry Year 12 Business BTEC
Measuring performance • Throughout this unit, you will consider how a business can measure its financial performance and what actions it can take to improve its performance Mr. Barry Year 12 Business BTEC
Performance indicators • Gross profit – this is the amount of profit left after the cost of producing the good or service is deducted from the amount of sales revenue • Net profit – this is the smaller amount of profit made after all other expenses are deducted from the gross profit • Value owed to the business – this is the amount of money owed to the business from sales that have not yet been paid for • Value owed by the business – this is the amount of money the business owes to others for goods or services purchased but not yet paid for. Mr. Barry Year 12 Business BTEC
Why is it important to keep a close eye on a business’s financial affairs? 0: 01 0: 02 0: 03 0: 04 0: 05 0: 06 0: 07 0: 08 0: 09 0: 10 0: 11 0: 12 0: 13 0: 14 0: 15 0: 16 0: 17 0: 18 0: 19 0: 20 0: 21 0: 22 0: 23 0: 24 0: 25 0: 26 0: 27 0: 28 0: 29 0: 30 0: 31 0: 32 0: 33 0: 34 0: 35 0: 36 0: 37 0: 38 0: 39 0: 40 0: 41 0: 42 0: 43 0: 44 0: 45 0: 46 0: 47 0: 48 0: 49 0: 50 0: 51 0: 52 0: 53 0: 54 0: 55 0: 56 0: 57 0: 58 0: 59 2: 00 1: 01 1: 02 1: 03 1: 04 1: 05 1: 06 1: 07 1: 08 1: 09 1: 10 1: 11 1: 12 1: 13 1: 14 1: 15 1: 16 1: 17 1: 18 1: 19 1: 20 1: 21 1: 22 1: 23 1: 24 1: 25 1: 26 1: 27 1: 28 1: 29 1: 30 1: 31 1: 32 1: 33 1: 34 1: 35 1: 36 1: 37 1: 38 1: 39 1: 40 1: 41 1: 42 1: 43 1: 44 1: 45 1: 46 1: 47 1: 48 1: 49 1: 50 1: 51 1: 52 1: 53 1: 54 1: 55 1: 56 1: 57 1: 58 1: 59 End Mr. Barry Year 12 Business BTEC
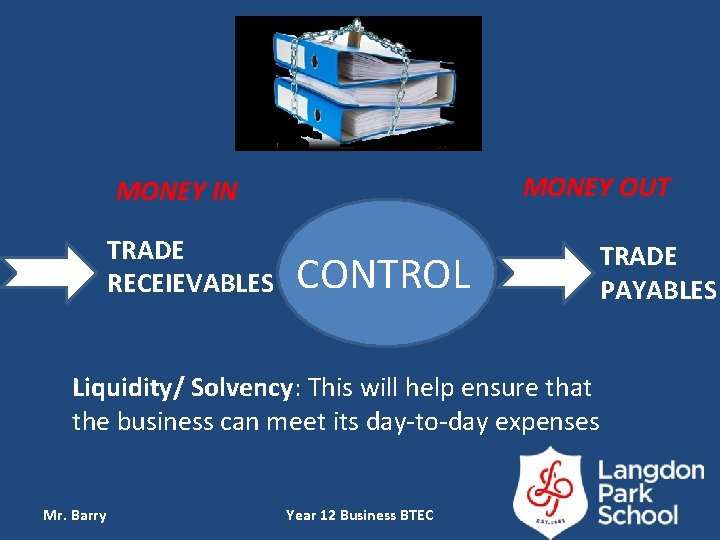
MONEY OUT MONEY IN TRADE RECEIEVABLES CONTROL TRADE PAYABLES Liquidity/ Solvency: This will help ensure that the business can meet its day-to-day expenses Mr. Barry Year 12 Business BTEC
Types of income CAPITAL INCOME • Loans • Mortgages • Shares • Owner’s capital • Debentures Mr. Barry REVENUE INCOME • Sales • Rent received • Commission received • Interest received • Discount received End Year 12 Business BTEC
Pause point • Can you explain, with the use of examples, the difference between capital income and revenue income? • Can you explain how capital income can lead to revenue income in a number of scenarios? End Mr. Barry Year 12 Business BTEC
Key terms • Capital items – assets bought from capital expenditure such as machinery and vehicles that will stay in the business for more than a year. • Statement of financial position – a financial document that shows the net worth of a business by balancing its assets against its liabilities. It is often called a Balance Sheet Mr. Barry Year 12 Business BTEC
- Slides: 20