
Unified Financial Analysis Risk Finance Lab Chapter 5
Unified Financial Analysis Risk & Finance Lab Chapter 5: Counterparty Willi Brammertz / Ioannis Akkizidis © Copyright ARIADNE 2016 October 20 1
Table of Content Introduction Data Credit Exposure Credit Value Adjusted Provisioning (IFRS 9) Stress Scenarios and CVa. R © Copyright ARIADNE 2016
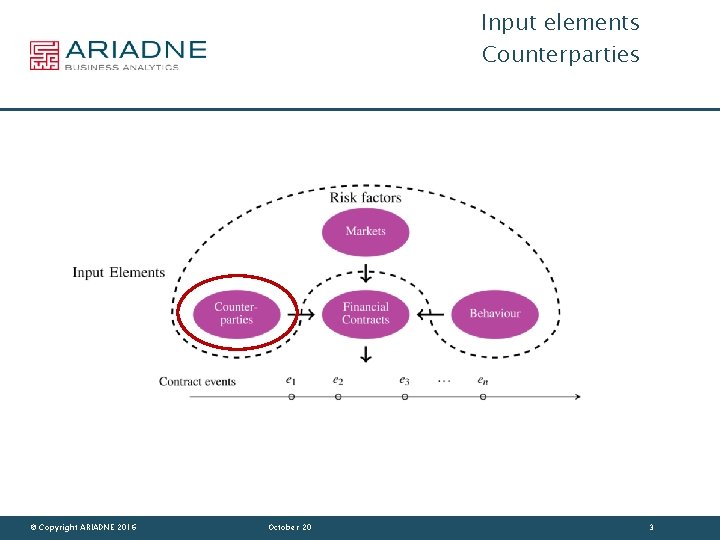
Input elements Counterparties © Copyright ARIADNE 2016 October 20 3
Counterparty and Behavior > Counterparty has descriptive and modeling part > Descriptive part (Data) > Characteristics > Hierarchies > Links to financial contracts > Credit enhancements > Behavioral (statistical nature) > Probability of default > Recovery rates > Recovery patterns > Used at default © Copyright ARIADNE 2016 October 20 4
Table of Content Introduction Data Credit Exposure Credit Value Adjusted Provisioning (IFRS 9) Stress Scenarios and CVa. R © Copyright ARIADNE 2016
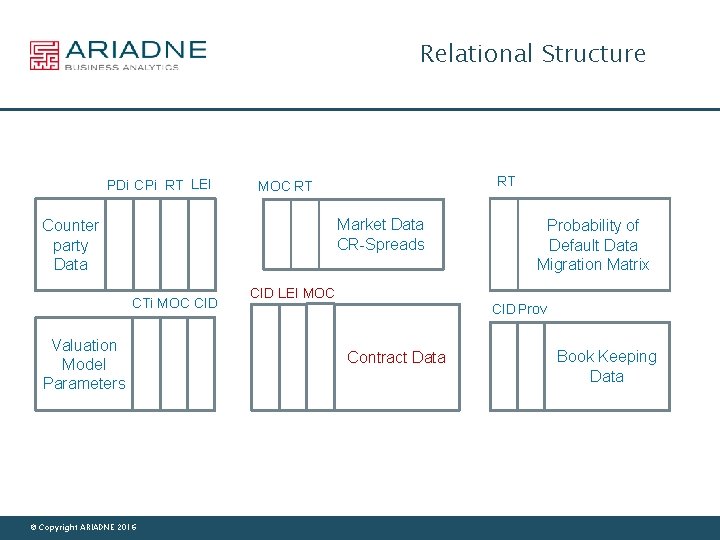
Relational Structure PDi CPi RT LEI RT MOC RT Market Data CR-Spreads Counter party Data CTi MOC CID Valuation Model Parameters © Copyright ARIADNE 2016 Probability of Default Data Migration Matrix CID LEI MOC CID Prov Contract Data Book Keeping Data
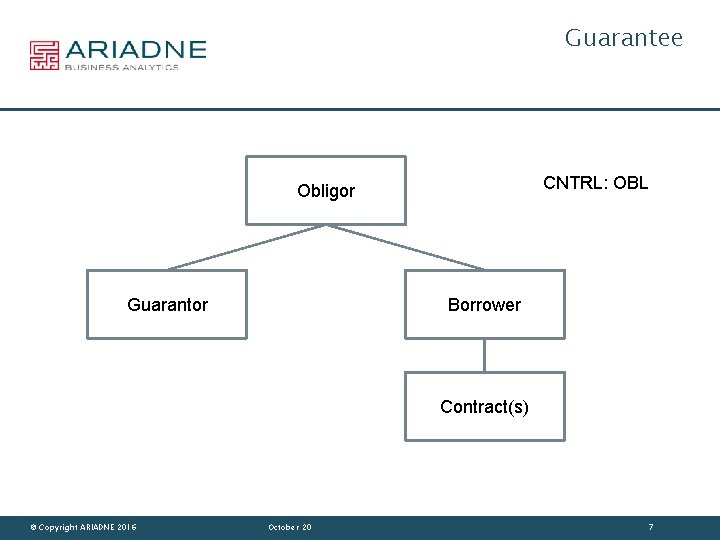
Guarantee CNTRL: OBL Obligor Guarantor Borrower Contract(s) © Copyright ARIADNE 2016 October 20 7
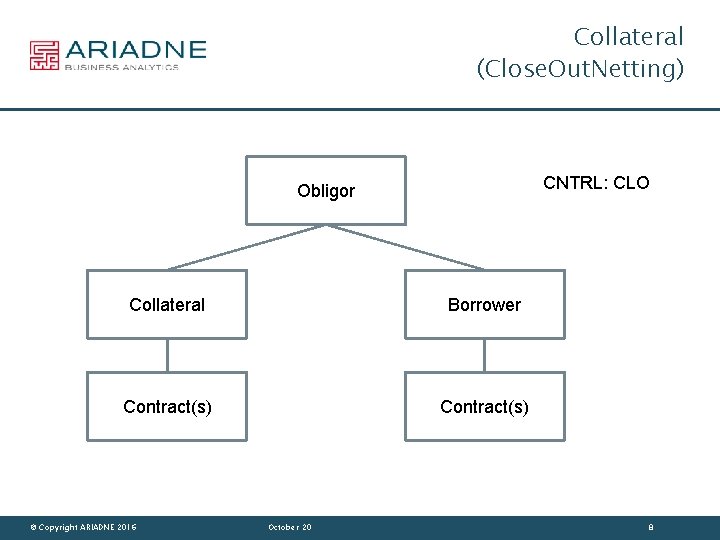
Collateral (Close. Out. Netting) CNTRL: CLO Obligor Collateral Borrower Contract(s) © Copyright ARIADNE 2016 October 20 8
Table of Content Introduction Data Credit Exposure Credit Value Adjusted Provisioning (IFRS 9) Stress Scenarios and CVa. R © Copyright ARIADNE 2016
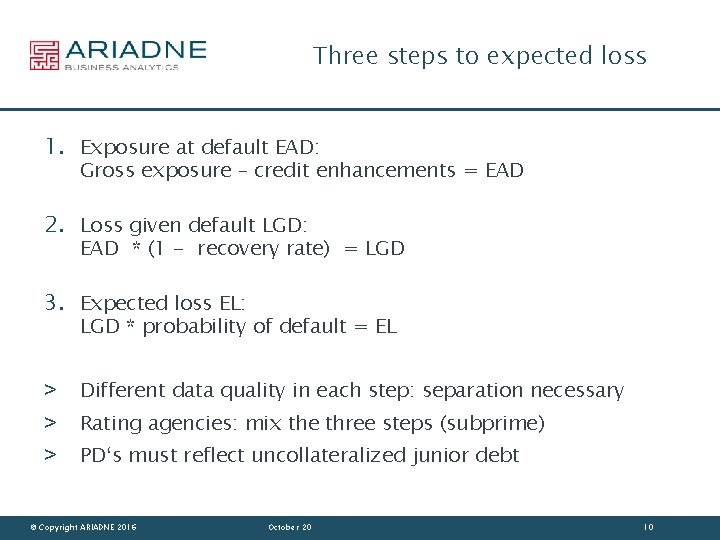
Three steps to expected loss 1. Exposure at default EAD: Gross exposure – credit enhancements = EAD 2. Loss given default LGD: EAD * (1 - recovery rate) = LGD 3. Expected loss EL: LGD * probability of default = EL > > > Different data quality in each step: separation necessary Rating agencies: mix the three steps (subprime) PD‘s must reflect uncollateralized junior debt © Copyright ARIADNE 2016 October 20 10
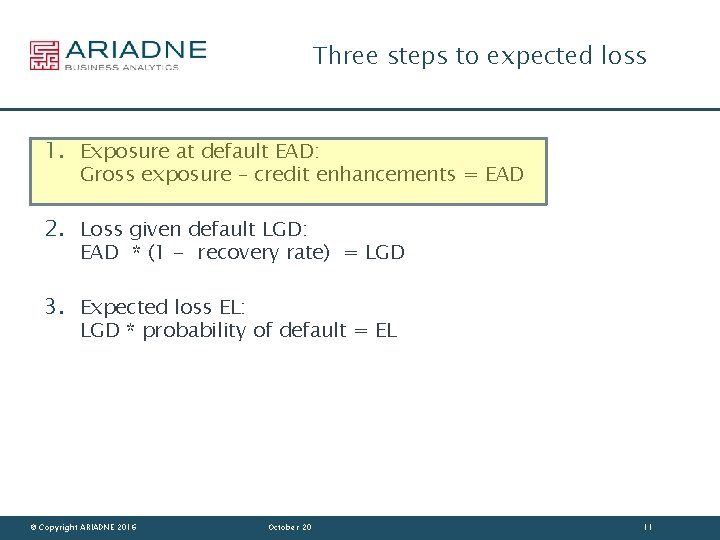
Three steps to expected loss 1. Exposure at default EAD: Gross exposure – credit enhancements = EAD 2. Loss given default LGD: EAD * (1 - recovery rate) = LGD 3. Expected loss EL: LGD * probability of default = EL © Copyright ARIADNE 2016 October 20 11
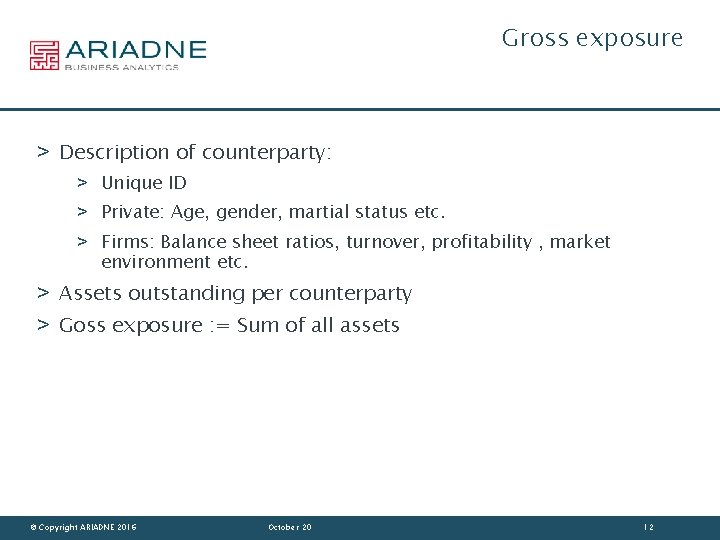
Gross exposure > Description of counterparty: > Unique ID > Private: Age, gender, martial status etc. > Firms: Balance sheet ratios, turnover, profitability , market environment etc. > Assets outstanding per counterparty > Goss exposure : = Sum of all assets © Copyright ARIADNE 2016 October 20 12
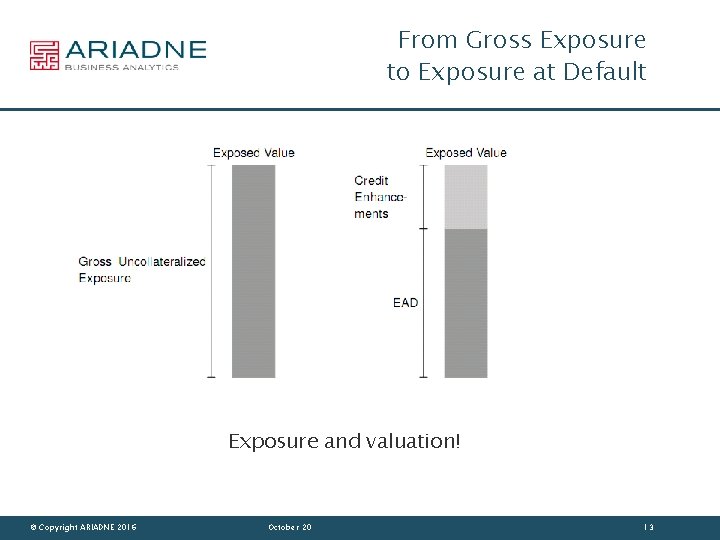
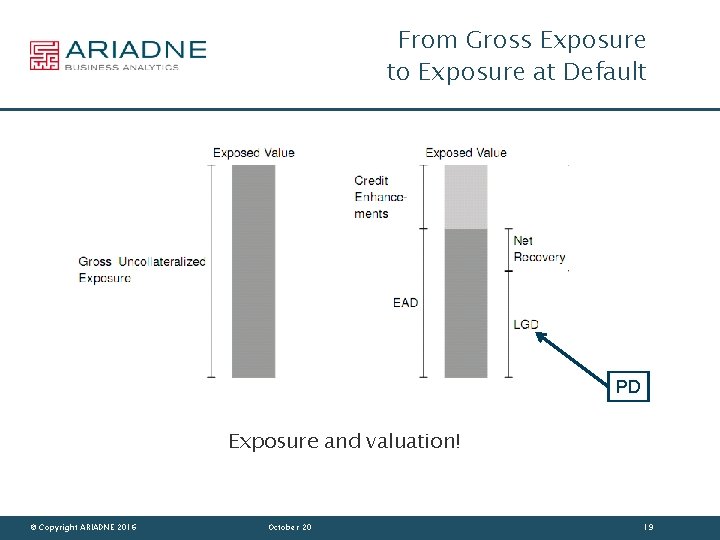
From Gross Exposure to Exposure at Default Exposure and valuation! © Copyright ARIADNE 2016 October 20 13
Three steps to expected loss 1. Exposure at default EAD: Gross exposure – credit enhancements = EAD 2. Loss given default LGD: EAD * (1 - recovery rate) = LGD 3. Expected loss EL: LGD * probability of default = EL © Copyright ARIADNE 2016 October 20 14
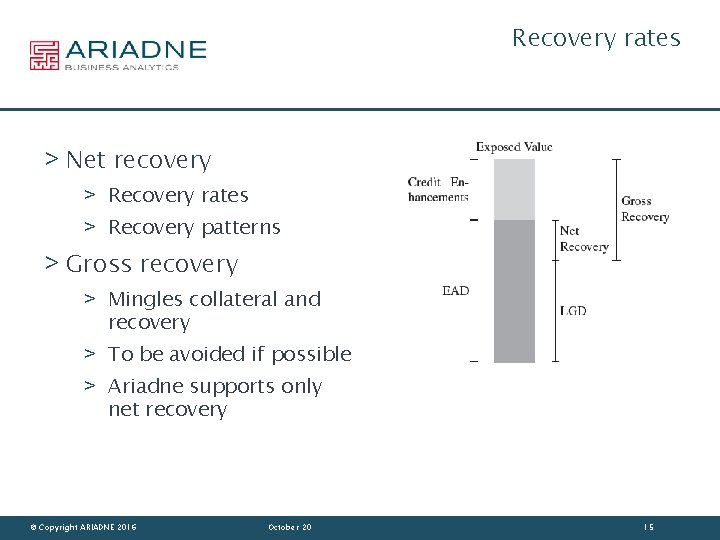
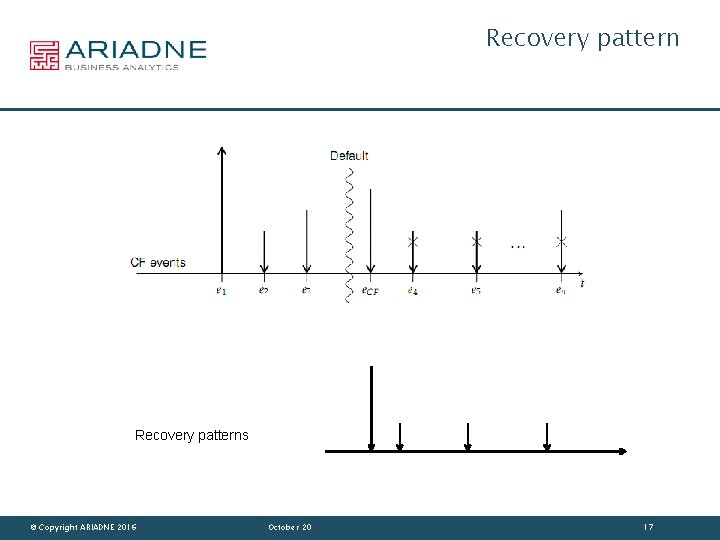
Recovery rates > Net recovery > Recovery rates > Recovery patterns > Gross recovery > Mingles collateral and recovery > To be avoided if possible > Ariadne supports only net recovery © Copyright ARIADNE 2016 October 20 15
Recovery rates > Based on historical experience > Single percentage number © Copyright ARIADNE 2016 October 20 16
Recovery patterns © Copyright ARIADNE 2016 October 20 17
Three steps to expected loss 1. Exposure at default EAD: Gross exposure – credit enhancements = EAD 2. Loss given default LGD: EAD * (1 - recovery rate) = LGD 3. Expected loss EL: LGD * probability of default = EL © Copyright ARIADNE 2016 October 20 18
From Gross Exposure to Exposure at Default PD Exposure and valuation! © Copyright ARIADNE 2016 October 20 19
Table of Content Introduction Data Credit Exposure Credit Value Adjusted Provisioning (IFRS 9) Stress Scenarios and CVa. R © Copyright ARIADNE 2016
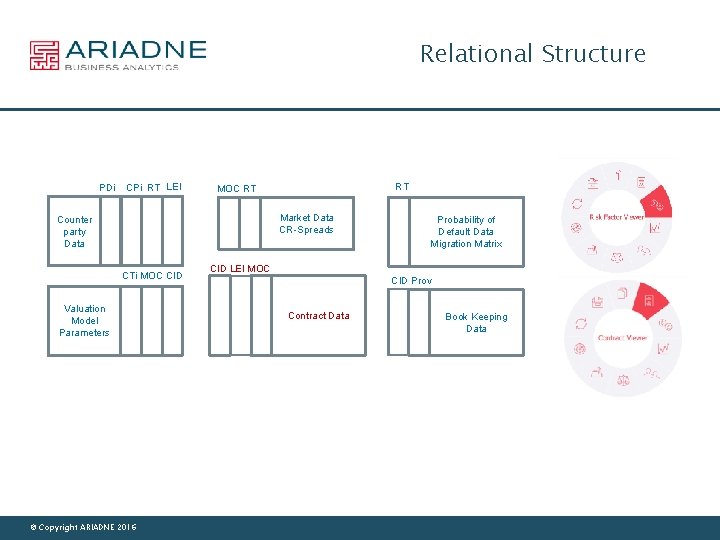
Relational Structure PDi CPi RT LEI RT MOC RT Market Data CR-Spreads Counter party Data CTi MOC CID Valuation Model Parameters © Copyright ARIADNE 2016 Probability of Default Data Migration Matrix CID LEI MOC CID Prov Contract Data Book Keeping Data
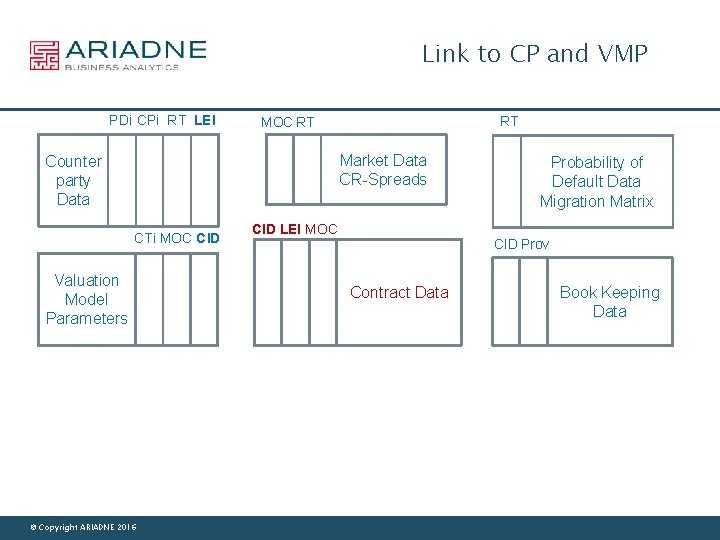
Link to CP and VMP PDi CPi RT LEI RT MOC RT Market Data CR-Spreads Counter party Data CTi MOC CID Valuation Model Parameters © Copyright ARIADNE 2016 CID LEI MOC Probability of Default Data Migration Matrix CID Prov Contract Data Book Keeping Data
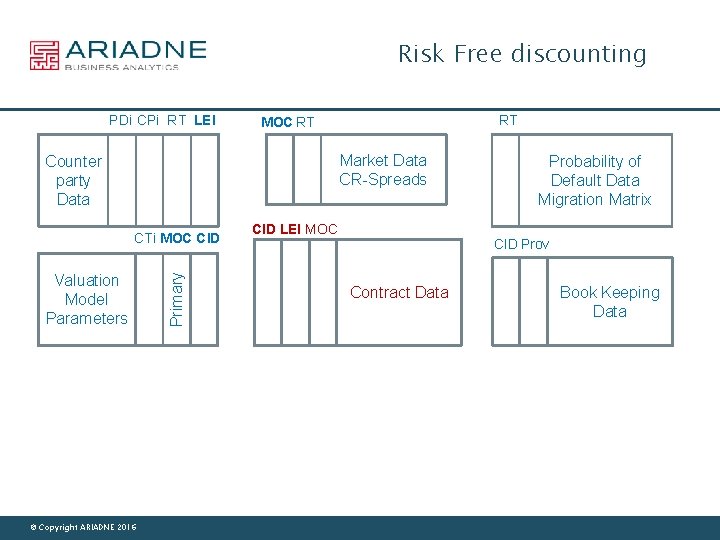
Risk Free discounting PDi CPi RT LEI RT MOC RT Market Data CR-Spreads Counter party Data Valuation Model Parameters © Copyright ARIADNE 2016 Primary CTi MOC CID LEI MOC Probability of Default Data Migration Matrix CID Prov Contract Data Book Keeping Data
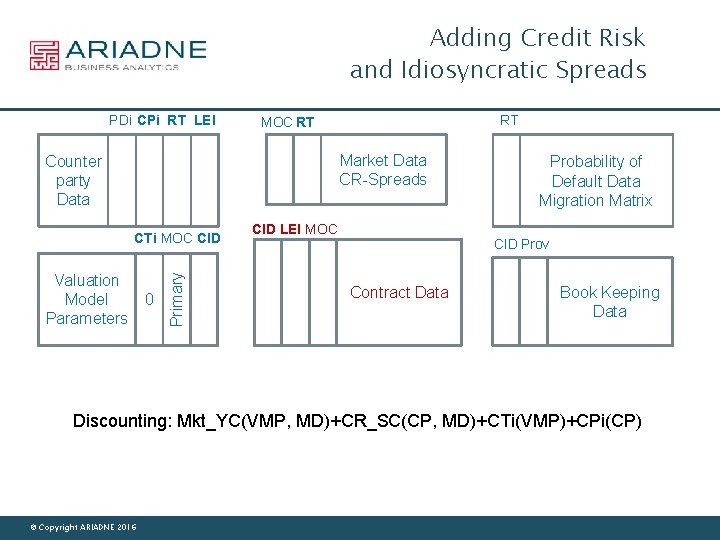
Adding Credit Risk and Idiosyncratic Spreads PDi CPi RT LEI RT MOC RT Market Data CR-Spreads Counter party Data Valuation Model Parameters 0 Primary CTi MOC CID LEI MOC Probability of Default Data Migration Matrix CID Prov Contract Data Book Keeping Data Discounting: Mkt_YC(VMP, MD)+CR_SC(CP, MD)+CTi(VMP)+CPi(CP) © Copyright ARIADNE 2016
Table of Content Introduction Data Credit Exposure Credit Value Adjusted Provisioning (IFRS 9) Stress Scenarios and CVa. R © Copyright ARIADNE 2016
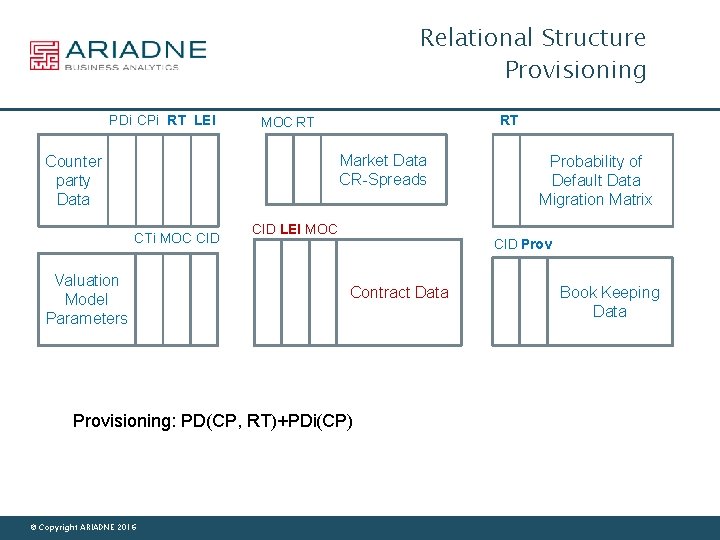
Relational Structure Provisioning PDi CPi RT LEI RT MOC RT Market Data CR-Spreads Counter party Data CTi MOC CID Valuation Model Parameters CID LEI MOC CID Prov Contract Data Provisioning: PD(CP, RT)+PDi(CP) © Copyright ARIADNE 2016 Probability of Default Data Migration Matrix Book Keeping Data
Table of Content Introduction Data Credit Exposure Credit Value Adjusted Provisioning (IFRS 9) Stress Scenarios and CVa. R © Copyright ARIADNE 2016
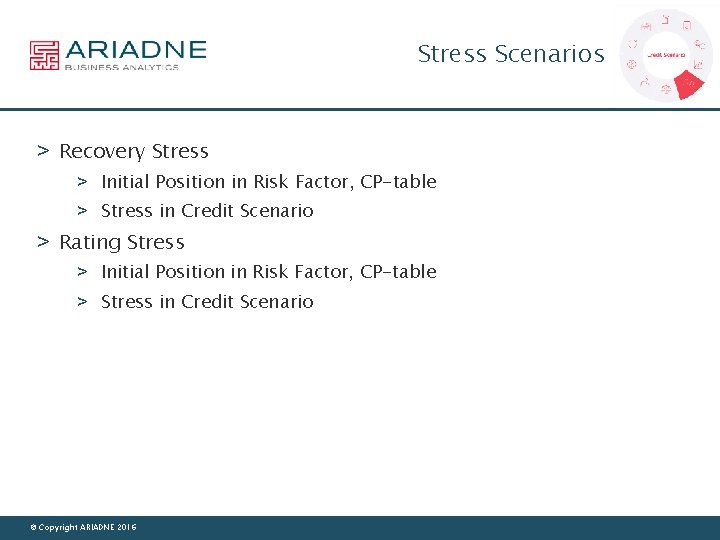
Stress Scenarios > Recovery Stress > Initial Position in Risk Factor, CP-table > Stress in Credit Scenario > Rating Stress > Initial Position in Risk Factor, CP-table > Stress in Credit Scenario © Copyright ARIADNE 2016
Credit Va. R > Part of Market Scenario > Original Position in Risk Factor, Market Table > Va. R > Market Risk > Credit Risk > Combined Risk © Copyright ARIADNE 2016
- Slides: 29