
Todays Content Session 2 5 19 Live Case
- Slides: 31
Today’s Content Session (2 -5 -19): Live Case Interview John S. Kirks Sr. Lecturer Strategy & Innovation
Today’s agenda ■ ■ ■ (Re)Introduction Case Interview Principles M&A Case
Today’s agenda ■ ■ ■ (Re)Introduction Case Interview Principles M&A Case
Who am I? ■ Contact • • information name: office: email: phone: ■ Office John Kirks Questrom – Room #620 A jkirks@bu. edu 978 -886 -7518 hours • THURSDAY, 1. 00 p. m. to 2. 00 p. m. (official hours) • Also by appointment! ■ My teaching schedule (Questrom UG juniors & seniors) • All classes on Tues/Thurs: – SI 422 ‘F 1’: 11. 00 am-12. 15 pm (Room 322) – SI 432 ‘A 1’: 3. 30 pm-4. 45 pm (Room 322) – MSMS Consulting Team Advisor: 9. 00 -10. 30 am (Room 620 A) ■ Other • • roles Head of Undergraduate Strategy & Innovation concentration (Prof. Mc. Manus’s counterpart) Faculty Advisor to BU Consulting Group (BUCG) SI 422 Course Coordinator (S 18 - 10 sections) Previously taught SI 751 to FTMBA & PTMBA sections
Who am I? (Education) ■Undergraduate studies • Stanford University (B. S. , Industrial Engineering) (Honors in Humanities) ■Graduate School • Harvard Business School ■Additional study- one year • Cambridge University- St. Edmund’s College (Philosophy)
Who am I? (Business Career) ■ Investment Banking • Robertson, Stephens & Company • Dain Rauscher Wessels • RBC Capital Markets ■ Management Consulting • Bain & Company ■ Independent Consulting • Marmot Mountain • Community Day Charter Public Schools ■ Subordinated Debt Investing • Sirrom Capital ■ Summer • Walt Disney Company
Today’s agenda ■ ■ ■ (Re)Introduction Case Interview Principles M&A Case
Case Interview Principles ■ In case interviews, you want to take a “structured approach” to problem solving • This is the #1 criteria on which you are being evaluated! (not “golden insight”) • Using a framework structure accomplishes two things: – Makes your thinking visible to the interviewer (and puts them at ease you are considering all possible “levers”) – … and, serves as an organizing construct, or outline, for you as you systematically work your way through the case • We will develop a structured approach today for an M&A case! ■ Most consulting case interview involve a quantitative element (Why? #2) ■ Common Case Types: • Profit Improvement (see brief treatment on next slides) – It covers a huge range of the types of cases you could see (“zoomed” basis) – And as a bonus, it will help you throughout your Questrom and business careers because it’s a broadly applicable framework that never changes!! • Health Care-related interviews: Drug/Med. Tech launch • M&A Case: today’s session
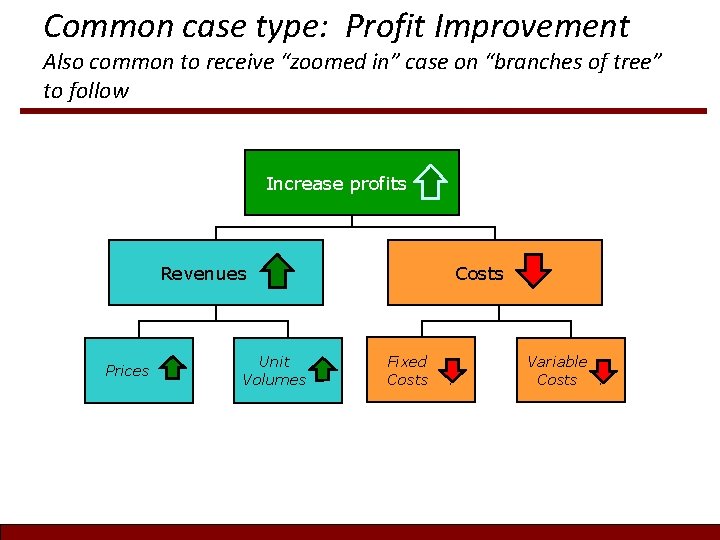
Common case type: Profit Improvement Also common to receive “zoomed in” case on “branches of tree” to follow Increase profits Revenues Prices . Unit. Volumes. Costs Fixed Costs . . Variable. Costs.
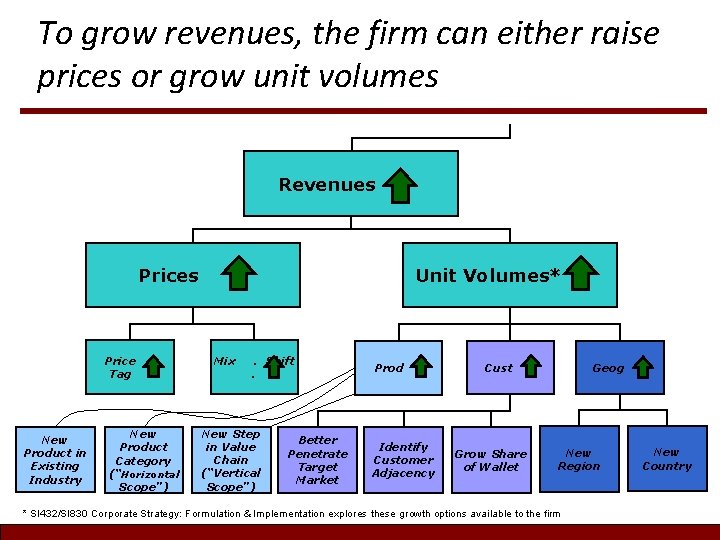
To grow revenues, the firm can either raise prices or grow unit volumes Revenues Price. Tag. New Product in Existing Industry New Product Category (“Horizontal Scope”) Unit Volumes* Mix . Shift. New Step in Value Chain (“Vertical Scope”) Better Penetrate Target Market Prod . Identify Customer Adjacency Cust Grow Share of Wallet . Geog New Region * SI 432/SI 830 Corporate Strategy: Formulation & Implementation explores these growth options available to the firm . New Country
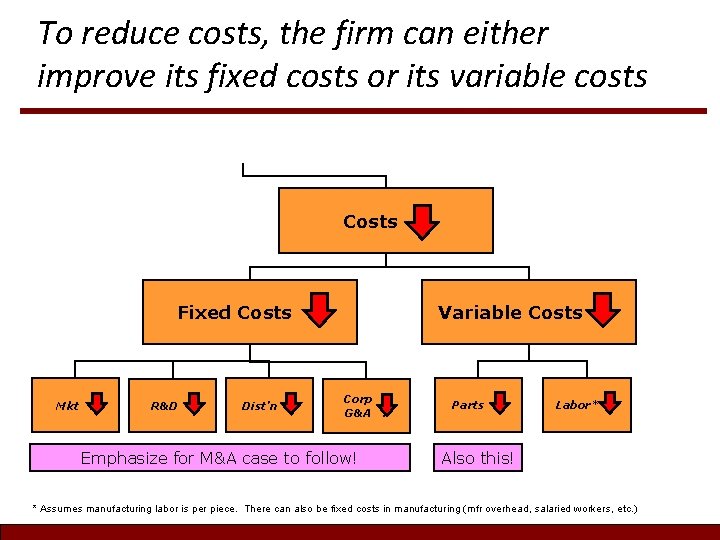
To reduce costs, the firm can either improve its fixed costs or its variable costs Costs Fixed Costs Mkt . R&D . Dist’n Variable Costs . Corp. G&A. Emphasize for M&A case to follow! Parts . Labor* . Also this! * Assumes manufacturing labor is per piece. There can also be fixed costs in manufacturing (mfr overhead, salaried workers, etc. )
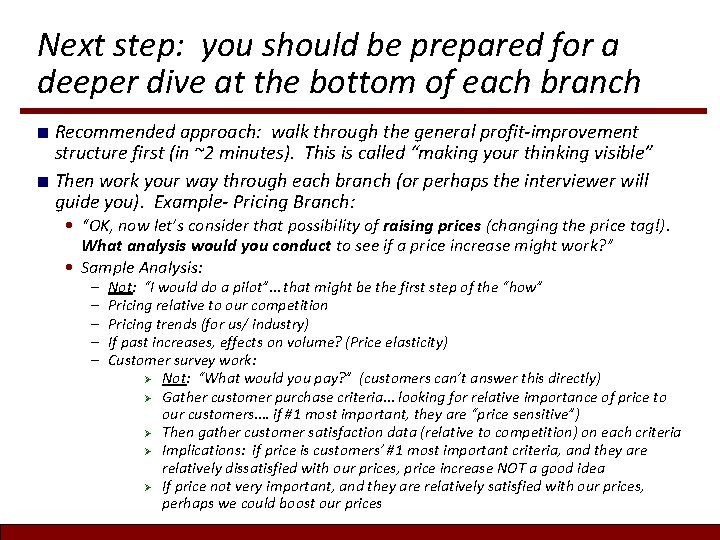
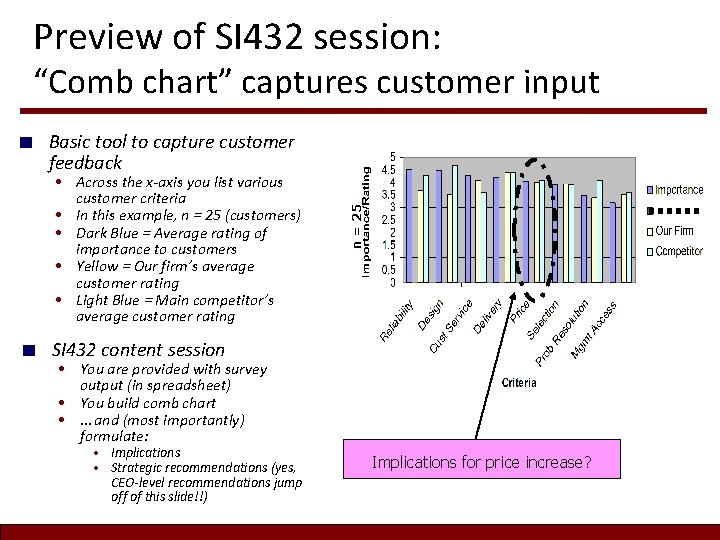
Next step: you should be prepared for a deeper dive at the bottom of each branch ■ Recommended approach: walk through the general profit-improvement structure first (in ~2 minutes). This is called “making your thinking visible” ■ Then work your way through each branch (or perhaps the interviewer will guide you). Example- Pricing Branch: • “OK, now let’s consider that possibility of raising prices (changing the price tag!). What analysis would you conduct to see if a price increase might work? ” • Sample Analysis: – – – Not: “I would do a pilot”… that might be the first step of the “how” Pricing relative to our competition Pricing trends (for us/ industry) If past increases, effects on volume? (Price elasticity) Customer survey work: Ø Not: “What would you pay? ” (customers can’t answer this directly) Ø Gather customer purchase criteria… looking for relative importance of price to our customers…. if #1 most important, they are “price sensitive”) Ø Then gather customer satisfaction data (relative to competition) on each criteria Ø Implications: if price is customers’ #1 most important criteria, and they are relatively dissatisfied with our prices, price increase NOT a good idea Ø If price not very important, and they are relatively satisfied with our prices, perhaps we could boost our prices
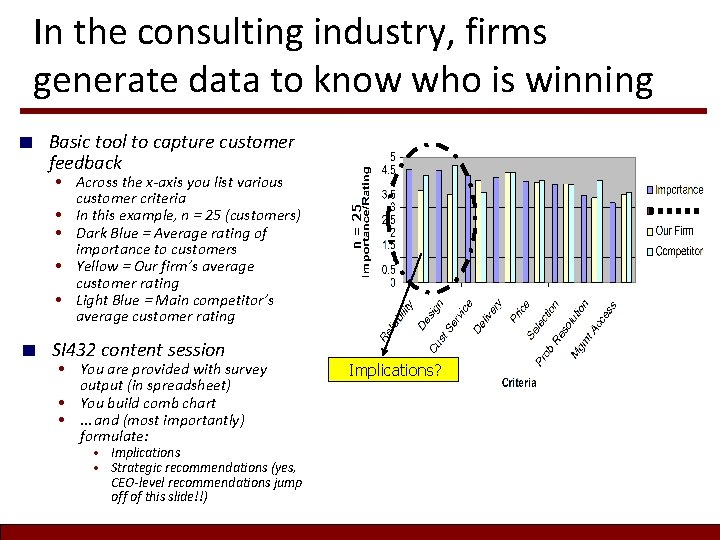
Preview of SI 432 session: “Comb chart” captures customer input Basic tool to capture customer feedback • Across the x-axis you list various customer criteria • In this example, n = 25 (customers) • Dark Blue = Average rating of importance to customers • Yellow = Our firm’s average customer rating • Light Blue = Main competitor’s average customer rating ■ n = 25 ■ SI 432 content session • You are provided with survey output (in spreadsheet) • You build comb chart • … and (most importantly) formulate: • Implications • Strategic recommendations (yes, CEO-level recommendations jump off of this slide!!) Implications for price increase?
Today’s agenda ■ ■ ■ (Re)Introduction Case Interview Principles M&A Case
M&A Case: Which firm should Coca-Cola buy*? SITUATION: Coke is evaluating two different possible acquisitions: Dasani bottled water and Minute Maid Orange Juice. With growth slowing in Coke’s main cola product as consumers shift to healthier options, they are looking at adjacent product markets. How would you think about evaluating the two choices? * This is a fictitious situation. The real Coca-Cola actually owns both of these!!
For an M&A Case, what considerations should we take into account? ■ Assume we only have enough capital to buy ONE of the two options ■ What criteria could be use to evaluate/ compare the two options? Talk to your neighbor
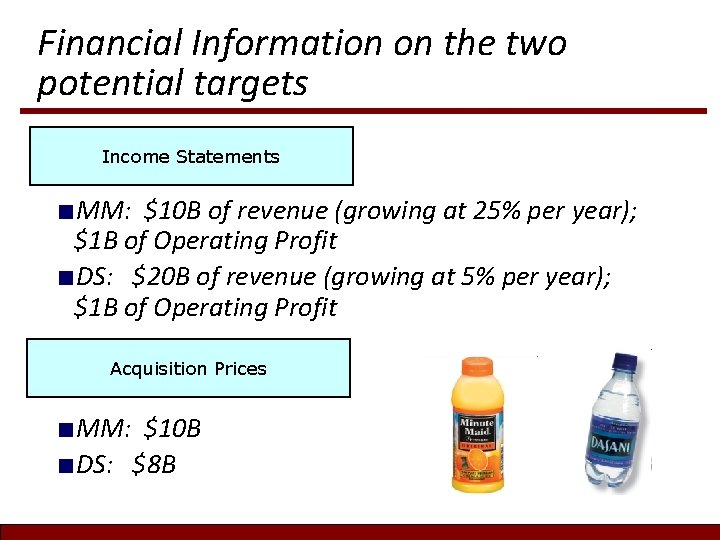
Financial Information on the two potential targets Income Statements ■MM: $10 B of revenue (growing at 25% per year); $1 B of Operating Profit ■DS: $20 B of revenue (growing at 5% per year); $1 B of Operating Profit Acquisition Prices ■MM: $10 B ■DS: $8 B
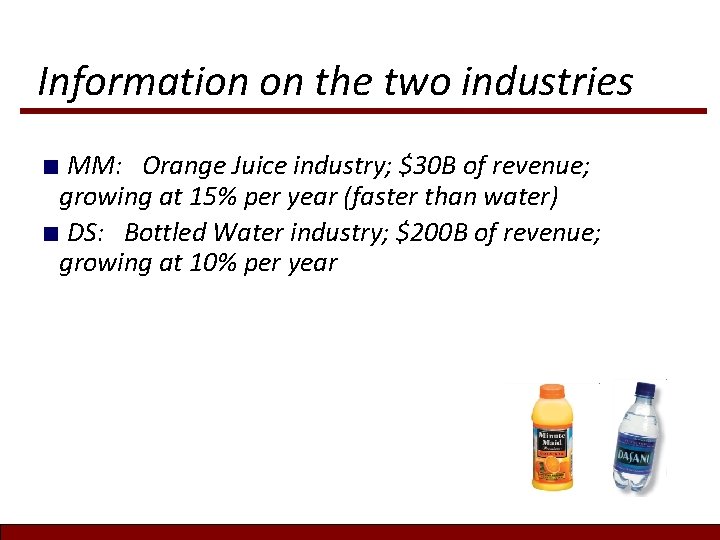
Information on the two industries MM: Orange Juice industry; $30 B of revenue; growing at 15% per year (faster than water) ■ DS: Bottled Water industry; $200 B of revenue; growing at 10% per year ■
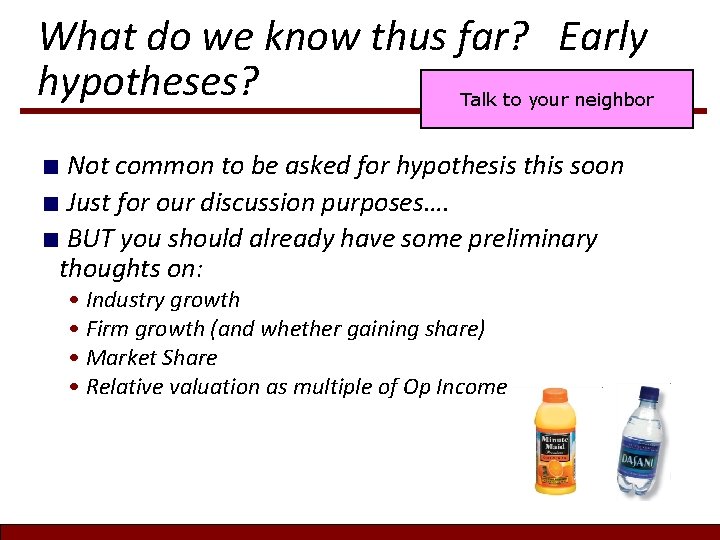
What do we know thus far? Early hypotheses? Talk to your neighbor Not common to be asked for hypothesis this soon ■ Just for our discussion purposes…. ■ BUT you should already have some preliminary thoughts on: ■ • Industry growth • Firm growth (and whether gaining share) • Market Share • Relative valuation as multiple of Op Income
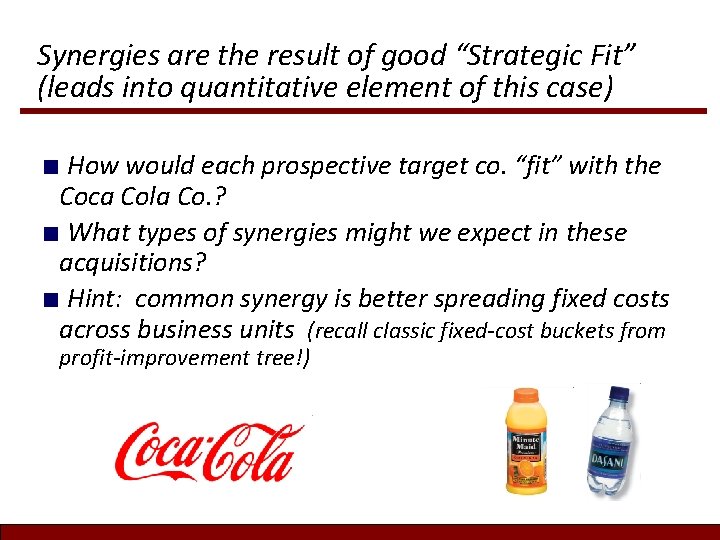
Synergies are the result of good “Strategic Fit” (leads into quantitative element of this case) How would each prospective target co. “fit” with the Coca Cola Co. ? ■ What types of synergies might we expect in these acquisitions? ■ Hint: common synergy is better spreading fixed costs across business units (recall classic fixed-cost buckets from ■ profit-improvement tree!)
Synergies are the result of good “Strategic Fit” (leads into quantitative element of this case) MM: Cost synergies in distribution to grocery ($100 M per year)…. NOT in marketing ■ DS: Cost synergies in distribution to grocery AND convenience stores ($200 M per year)…. . NOT in marketing ■
Quantitative Element: Calculate the Acquisition Multiples for both firms ■ Acq Multiple = Acq Price Op Inc* Calculate base case multiples for each ■ Then revised multiples taking into account synergies ■ * Ideally cash flow. EBITDA is a good proxy. But all that is provided here is Op Inc so using as a simplifying assumption
Quantitative Element: Calculate the Acquisition Multiples for both firms ■ Acq Multiple = Acq Price Op Inc* Calculate base case multiples for each ■ Then revised multiples taking into account synergies ■ Now two years out…. . ■ * Ideally cash flow. EBITDA is a good proxy. But all that is provided here is Op Inc so using as a simplifying assumption
My Calculations: Acquisition Multiples for both firms Taking Synergies into Account ■ MM: $10 B / ($1 B+0. 1 B) = ~9 x ■ DS: $8 B / ($1 B+0. 2 B) = ~7 x (on the surface, Dasani price looks more reasonable) Two Years Out ■ MM: $10 B of revs grows to ~$15 B; assume base cash flow grows by ~30%. . $1. 60 B…. . PP of $10 B / $(1. 6 B+0. 1 B)M = 5. 8 x or ~6 x ■ DS: $20 B of revs grows to ~$22 B (~5% per year); assume base cash flow grows by ~10% per year. . $1. 0 B grows to ~$1. 2 B…. . PP of $8 B / $(1. 2 B+0. 2 B)M = 5. 7 x or ~6 x * Ideally cash flow. EBITDA is a good proxy. But all that is provided here is Op Inc so using as a simplifying assumption
Competitive Positioning tells us which firm is winning (in its respective industry) ■ How can we determine this? Talk to your neighbor
Competitive Positioning: Customer Survey Results MM: Very well positioned on key customer importance criteria: brand, healthiness, taste; so-so positioning on less important customer criteria: price, packaging ■D: Very well positioned on less important customer criteria: taste, brand; so-so positioning on key customer criteria: price, packaging, healthiness ■ Reactions?
In the consulting industry, firms generate data to know who is winning Basic tool to capture customer feedback • Across the x-axis you list various customer criteria • In this example, n = 25 (customers) • Dark Blue = Average rating of importance to customers • Yellow = Our firm’s average customer rating • Light Blue = Main competitor’s average customer rating ■ SI 432 content session • You are provided with survey output (in spreadsheet) • You build comb chart • … and (most importantly) formulate: • Implications • Strategic recommendations (yes, CEO-level recommendations jump off of this slide!!) n = 25 ■ Implications?
M&A Case: Which firm should Coca-Cola buy* Final Answer? * This is a fictitious situation. The real Coca-Cola actually owns both of these!!
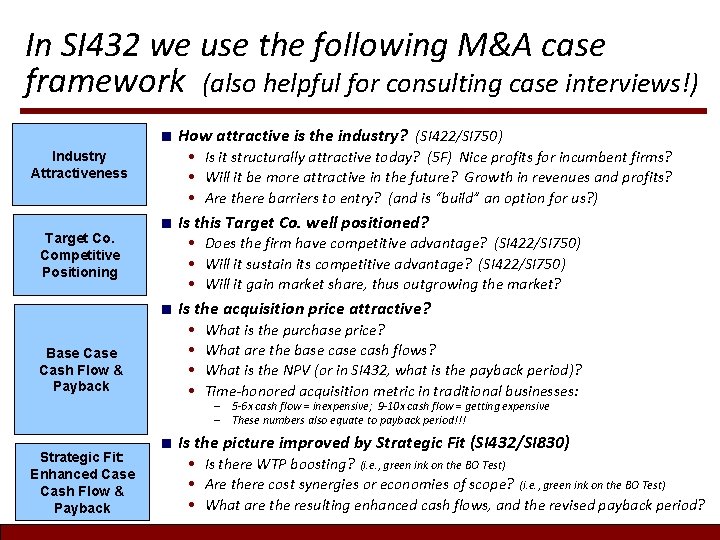
In SI 432 we use the following M&A case framework (also helpful for consulting case interviews!) ■ • Is it structurally attractive today? (5 F) Nice profits for incumbent firms? • Will it be more attractive in the future? Growth in revenues and profits? • Are there barriers to entry? (and is “build” an option for us? ) Industry Attractiveness ■ Target Co. Competitive Positioning Is this Target Co. well positioned? • Does the firm have competitive advantage? (SI 422/SI 750) • Will it sustain its competitive advantage? (SI 422/SI 750) • Will it gain market share, thus outgrowing the market? ■ Is the acquisition price attractive? • • Base Cash Flow & Payback Strategic Fit: Enhanced Case Cash Flow & Payback How attractive is the industry? (SI 422/SI 750) ■ What is the purchase price? What are the base cash flows? What is the NPV (or in SI 432, what is the payback period)? Time-honored acquisition metric in traditional businesses: – 5 -6 x cash flow = inexpensive; 9 -10 x cash flow = getting expensive – These numbers also equate to payback period!!! Is the picture improved by Strategic Fit (SI 432/SI 830) • Is there WTP boosting? (i. e. , green ink on the BO Test) • Are there cost synergies or economies of scope? (i. e. , green ink on the BO Test) • What are the resulting enhanced cash flows, and the revised payback period?
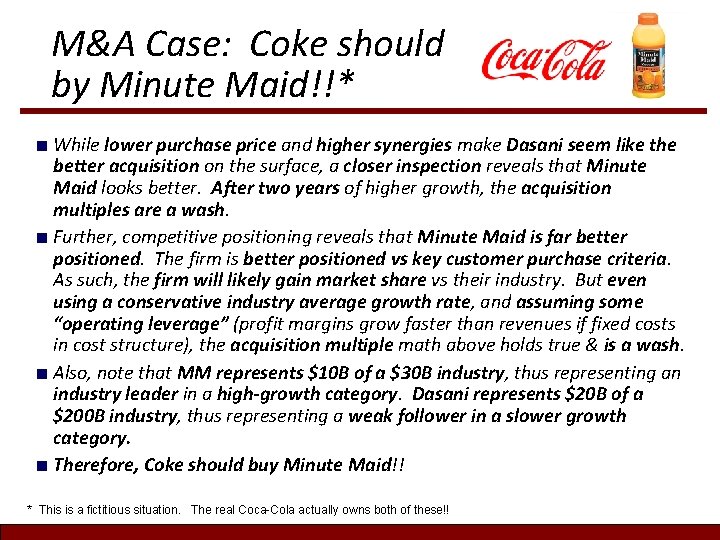
M&A Case: Coke should by Minute Maid!!* ■ While lower purchase price and higher synergies make Dasani seem like the better acquisition on the surface, a closer inspection reveals that Minute Maid looks better. After two years of higher growth, the acquisition multiples are a wash. ■ Further, competitive positioning reveals that Minute Maid is far better positioned. The firm is better positioned vs key customer purchase criteria. As such, the firm will likely gain market share vs their industry. But even using a conservative industry average growth rate, and assuming some “operating leverage” (profit margins grow faster than revenues if fixed costs in cost structure), the acquisition multiple math above holds true & is a wash. ■ Also, note that MM represents $10 B of a $30 B industry, thus representing an industry leader in a high-growth category. Dasani represents $20 B of a $200 B industry, thus representing a weak follower in a slower growth category. ■ Therefore, Coke should buy Minute Maid!! * This is a fictitious situation. The real Coca-Cola actually owns both of these!!
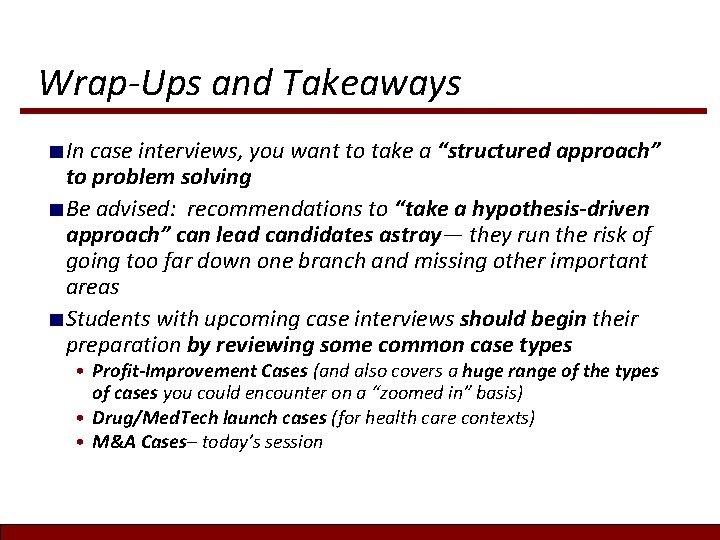
Wrap-Ups and Takeaways ■ In case interviews, you want to take a “structured approach” to problem solving ■ Be advised: recommendations to “take a hypothesis-driven approach” can lead candidates astray— they run the risk of going too far down one branch and missing other important areas ■ Students with upcoming case interviews should begin their preparation by reviewing some common case types • Profit-Improvement Cases (and also covers a huge range of the types of cases you could encounter on a “zoomed in” basis) • Drug/Med. Tech launch cases (for health care contexts) • M&A Cases– today’s session