
The Taiwan SBL Market LiChen Yang Clearing Department
The Taiwan SBL Market Li-Chen, Yang Clearing Department Taiwan Stock Exchange March 13, 2008
Outline SBL market conditions The TSEC SBL system Regulatory updates Future prospects 2
SBL Market Conditions
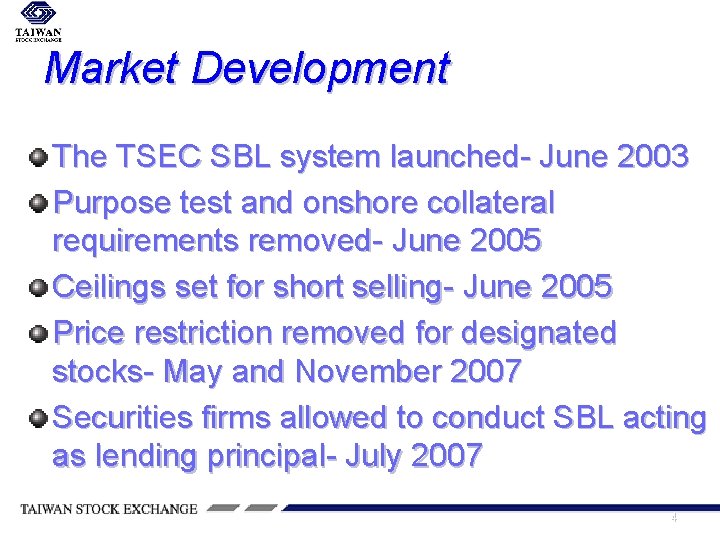
Market Development The TSEC SBL system launched- June 2003 Purpose test and onshore collateral requirements removed- June 2005 Ceilings set for short selling- June 2005 Price restriction removed for designated stocks- May and November 2007 Securities firms allowed to conduct SBL acting as lending principal- July 2007 4
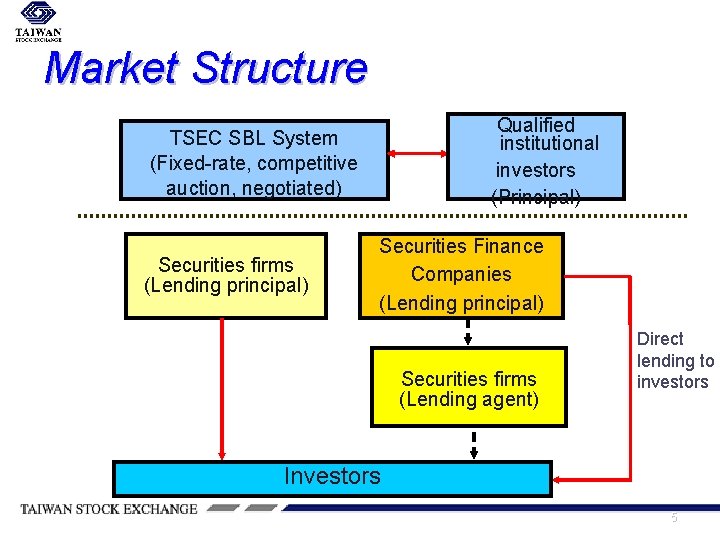
Market Structure Qualified institutional investors (Principal) TSEC SBL System (Fixed-rate, competitive auction, negotiated) Securities firms (Lending principal) Securities Finance Companies (Lending principal) Securities firms (Lending agent) Direct lending to investors Investors 5
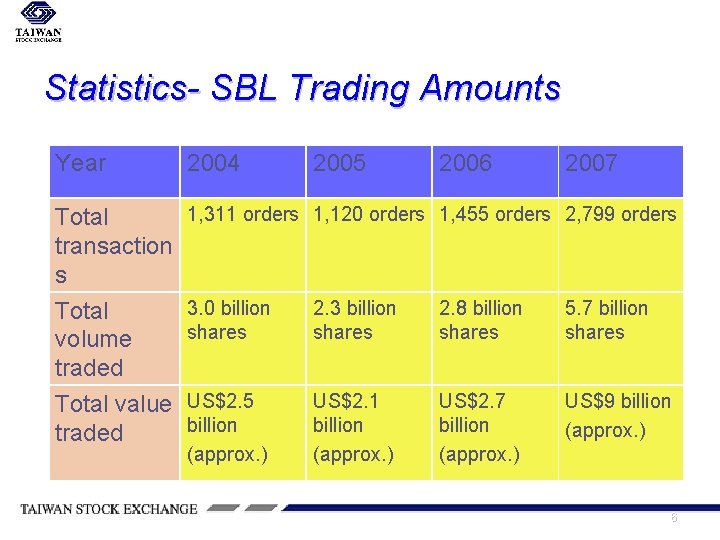
Statistics- SBL Trading Amounts Year 2004 2005 2006 2007 1, 311 orders 1, 120 orders 1, 455 orders 2, 799 orders Total transaction s Total volume traded Total value traded 3. 0 billion shares 2. 3 billion shares 2. 8 billion shares 5. 7 billion shares US$2. 5 billion (approx. ) US$2. 1 billion (approx. ) US$2. 7 billion (approx. ) US$9 billion (approx. ) 6
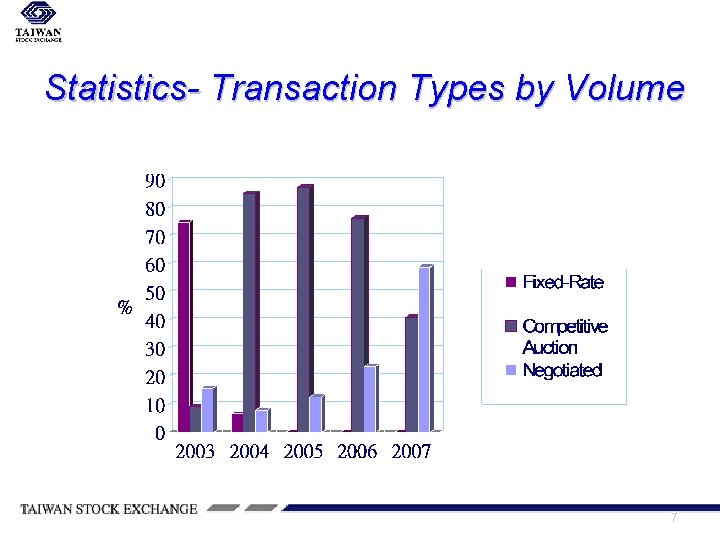
Statistics- Transaction Types by Volume 7
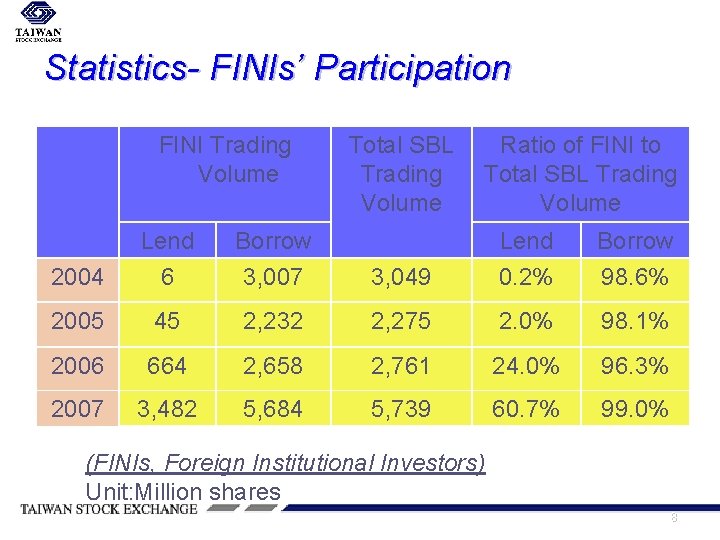
Statistics- FINIs’ Participation FINI Trading Volume Lend Borrow 2004 6 3, 007 2005 45 2006 2007 Total SBL Trading Volume Ratio of FINI to Total SBL Trading Volume Lend Borrow 3, 049 0. 2% 98. 6% 2, 232 2, 275 2. 0% 98. 1% 664 2, 658 2, 761 24. 0% 96. 3% 3, 482 5, 684 5, 739 60. 7% 99. 0% (FINIs, Foreign Institutional Investors) Unit: Million shares 8
The TSEC SBL System
Features of the TSEC SBL System A centralized system, launched in June 2003 Limited to qualified institutional investors Classifies SBL transactions into 3 types: * Fixed-rate - fee rate fixed at 3. 5% p. a. * Competitive auction - fee rate by “bids & offers” * Negotiated - fee rate via negotiations 10
TSEC Roles in the SBL System Provides intermediary services Relays transfer requests to TDCC via network Manages collateral in fixed-rate & competitive auction transactions Acts as a guarantor in fixed-rate & competitive auction transactions 11
Roles of SBL Brokers Act as agents for borrowers and lenders n n n Relaying TSEC SBL system information Applying for SBL trades with TSEC Handling settlement 12

Transaction Types Transaction Fee Rates Types Collateral Rates Fixed-rate 140% of 6 months and loan value one-time rollover permitted TSEC Lender NA 3. 5% Competitive Bids and Auction Offers Negotiated Period Negotiable 6 months and one-time rollover permitted Pledgee Guarantor 13

Market Rules for Short Selling(1) Ceilings set for total short selling volume in the whole market: n Daily maximum for short selling of borrowed stocks cannot exceed 3% of outstanding shares per lending stock n Maximum for short selling of borrowed stocks cannot exceed 10% of outstanding shares per lending stock n The total volume of short selling borrowed stocks and margin short sales cannot exceed 25% of outstanding shares per stock 14
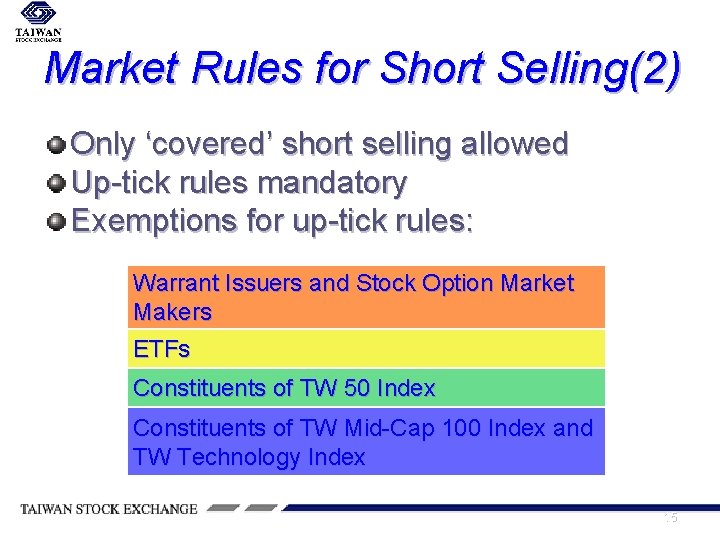
Market Rules for Short Selling(2) Only ‘covered’ short selling allowed Up-tick rules mandatory Exemptions for up-tick rules: Warrant Issuers and Stock Option Market Makers ETFs Constituents of TW 50 Index Constituents of TW Mid-Cap 100 Index and TW Technology Index 15
Regulatory Updates
Major Reforms in 2007 Additional early recall option Price restriction removal SBL taxation reform TSEC SBL service fee revision 17
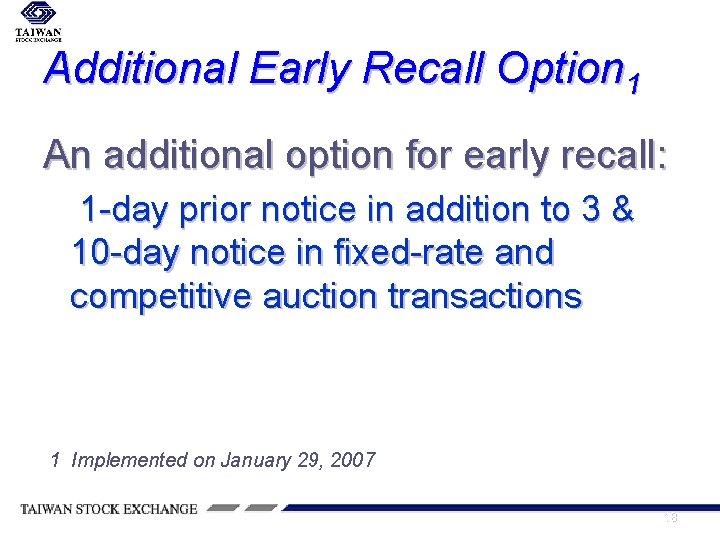
Additional Early Recall Option 1 An additional option for early recall: 1 -day prior notice in addition to 3 & 10 -day notice in fixed-rate and competitive auction transactions 1 Implemented on January 29, 2007 18
Price Restriction Removal Constituents of Taiwan 50 Index exempted 2 Constituents of Taiwan Mid-Cap 100 and Taiwan Technology Index exempted 3 Aforementioned stocks constitute 84% of total market value 2 Effective from May 11, 2007 3 Effective from November 12, 2007 19
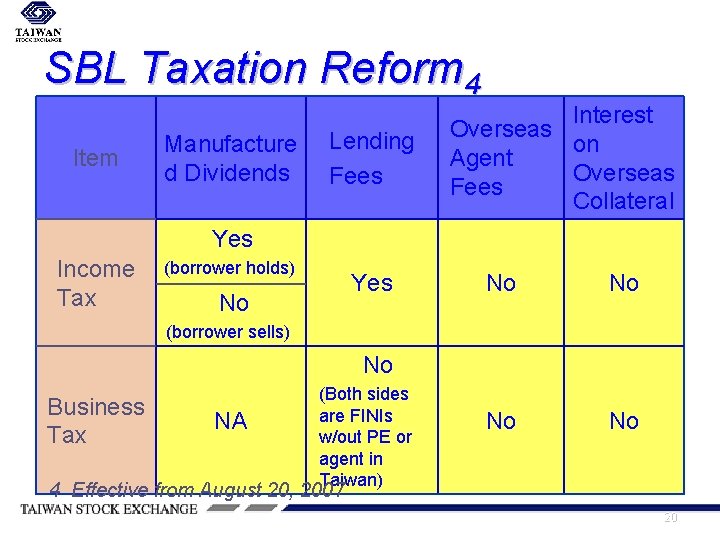
SBL Taxation Reform 4 Item Manufacture d Dividends Lending Fees Interest Overseas on Agent Overseas Fees Collateral Yes Income Tax (borrower holds) Yes No No No (borrower sells) No Business Tax NA (Both sides are FINIs w/out PE or agent in Taiwan) 4 Effective from August 20, 2007 20
TSEC SBL Service Fee Revision 5 Charges both parties in a negotiated transaction at 0. 02% p. a. of borrowed stock’s trading value Switched from per transaction basis to per annum basis Reduces costs to participants for shortterm transactions 5 Effective from December 3, 2007 21
Future Prospects
Future Prospects Pre-arranged negotiated transaction A borrower can short on day T though actual transfer of securities occurs on T+1 Find a method to solve late return of stocks for lenders selling lent stocks Streamlining of pledge procedure TDCC participants can directly get access to the pledge system to carry out the pledge 23
Thank you 24
- Slides: 24