
The Greek Letters Chapter 15 Fundamentals of Futures
- Slides: 46
The Greek Letters Chapter 15 Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 1
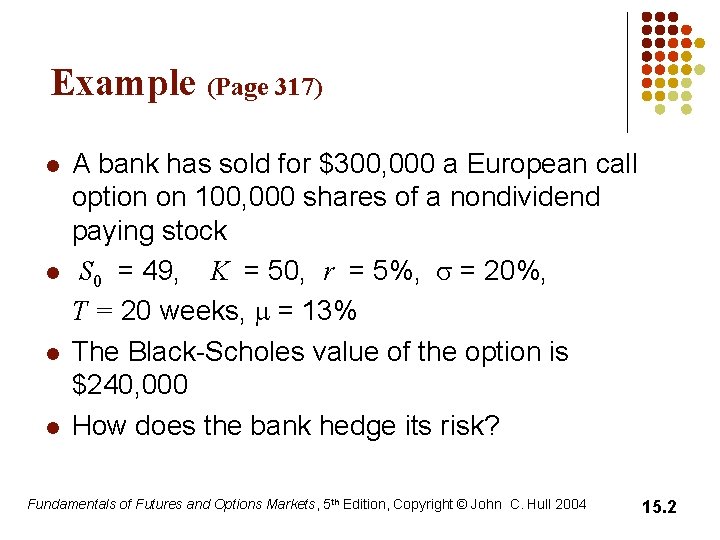
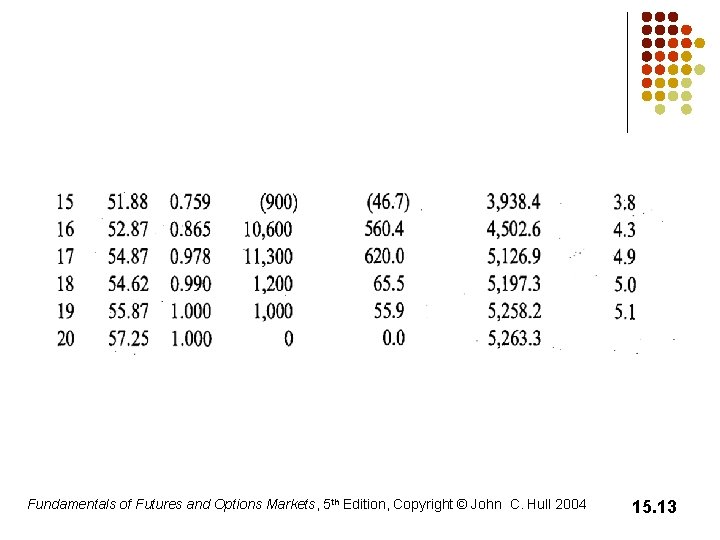
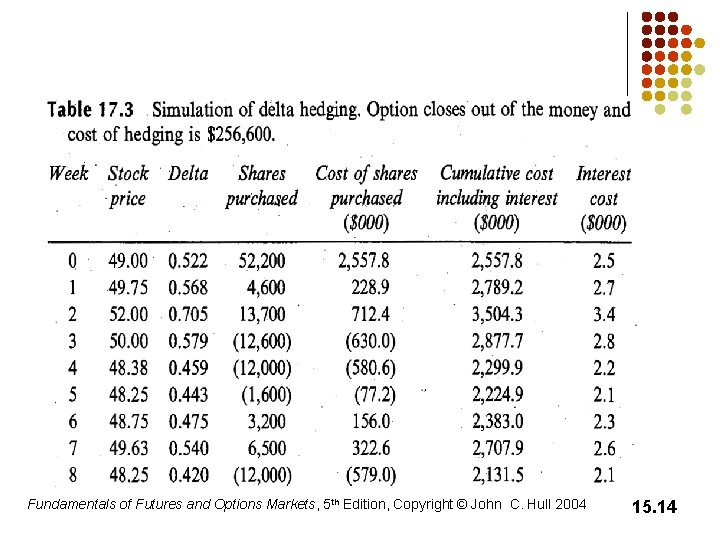
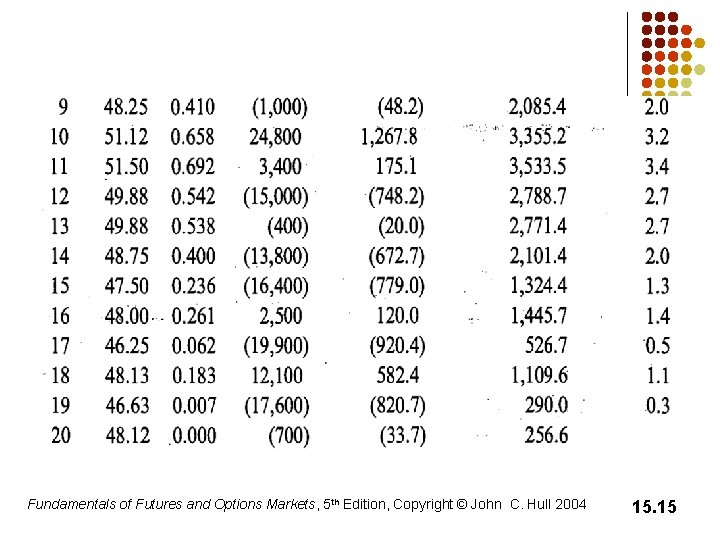
Example (Page 317) l l A bank has sold for $300, 000 a European call option on 100, 000 shares of a nondividend paying stock S 0 = 49, K = 50, r = 5%, = 20%, T = 20 weeks, m = 13% The Black-Scholes value of the option is $240, 000 How does the bank hedge its risk? Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 2
Naked & Covered Positions Naked position Take no action Covered position Buy 100, 000 shares today Both strategies leave the bank exposed to significant risk Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 3
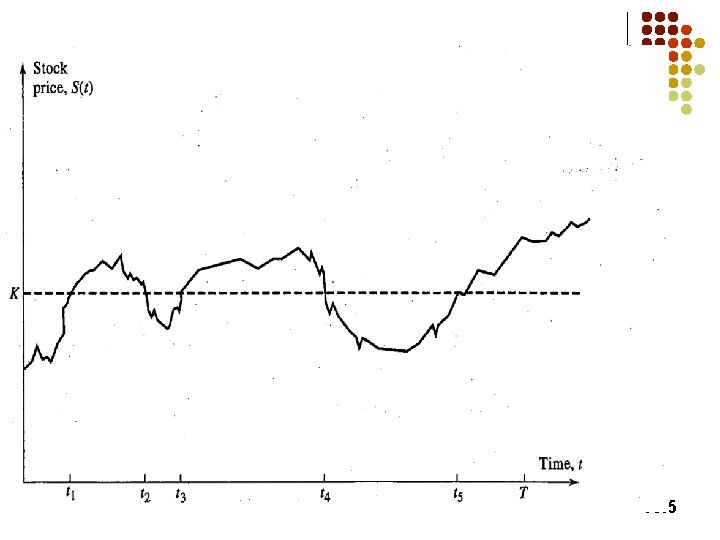
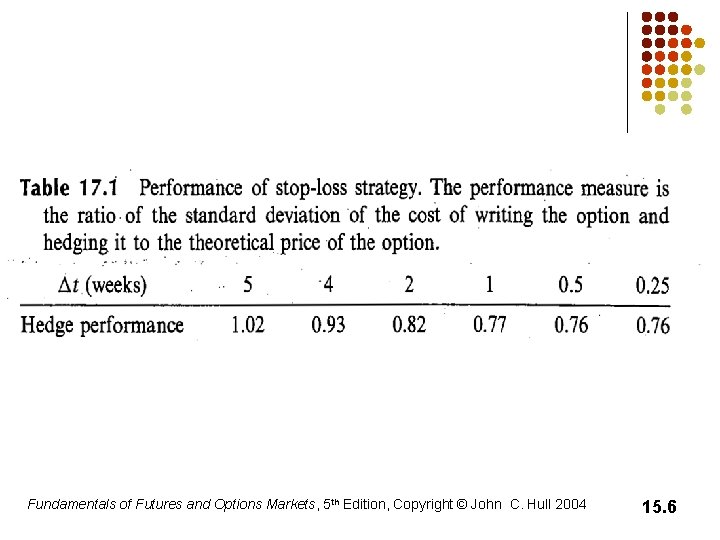
Stop-Loss Strategy l l This involves: Buying 100, 000 shares as soon as price reaches $50 Selling 100, 000 shares as soon as price falls below $50 This deceptively simple hedging strategy does not work well Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 4
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 5
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 6
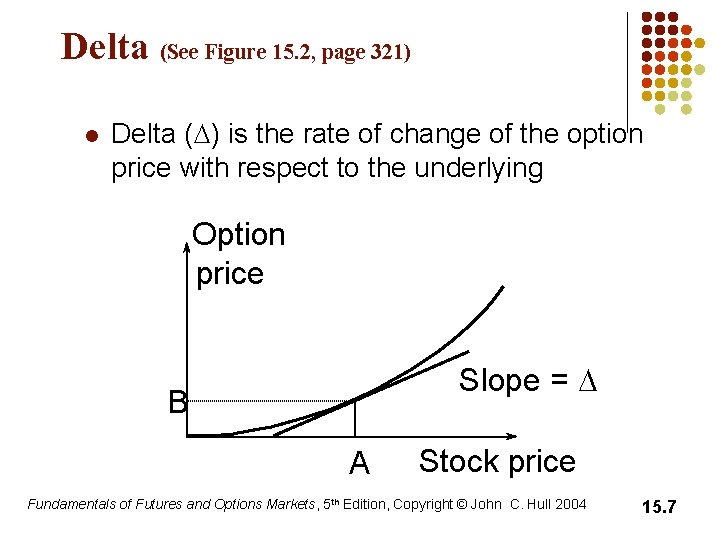
Delta (See Figure 15. 2, page 321) l Delta (D) is the rate of change of the option price with respect to the underlying Option price Slope = D B A Stock price Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 7
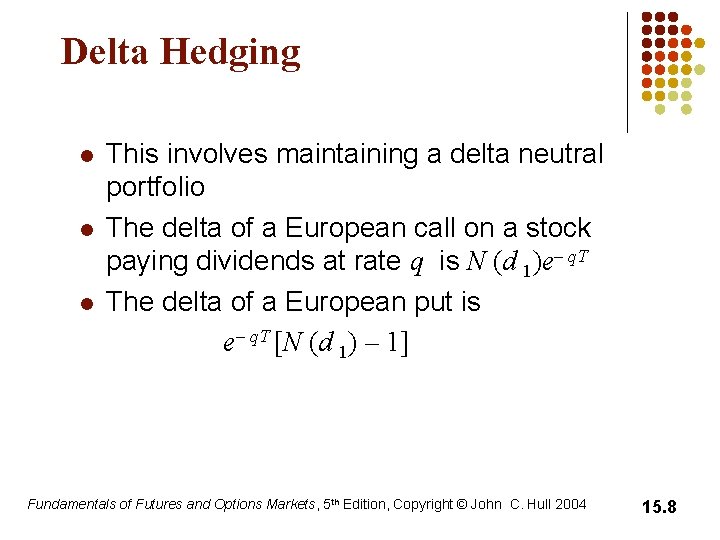
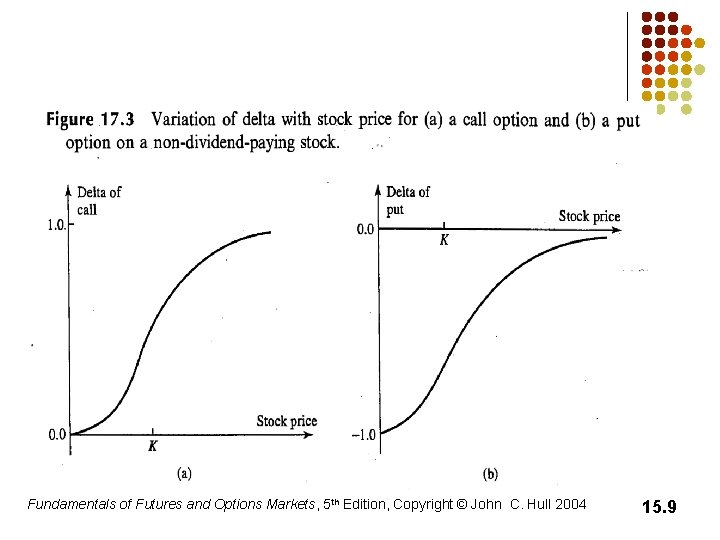
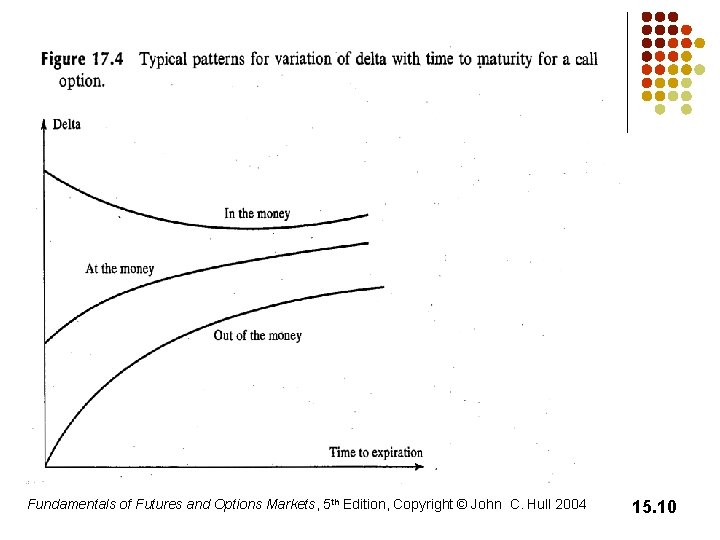
Delta Hedging l l l This involves maintaining a delta neutral portfolio The delta of a European call on a stock paying dividends at rate q is N (d 1)e– q. T The delta of a European put is e– q. T [N (d 1) – 1] Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 8
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 9
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 10
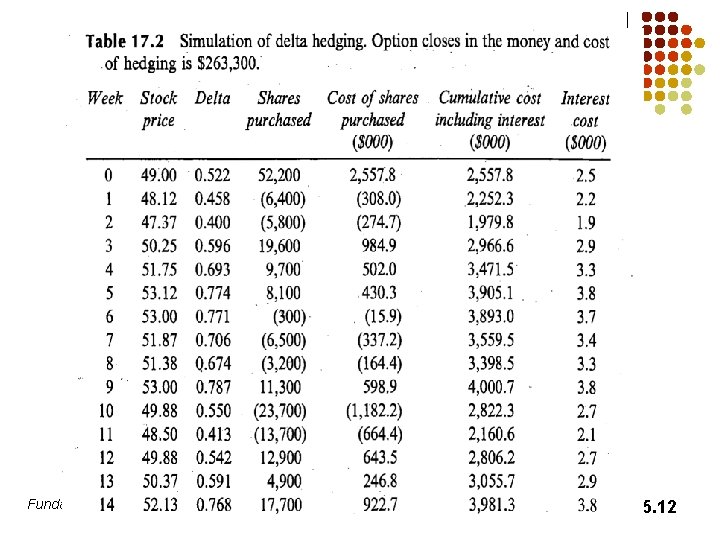
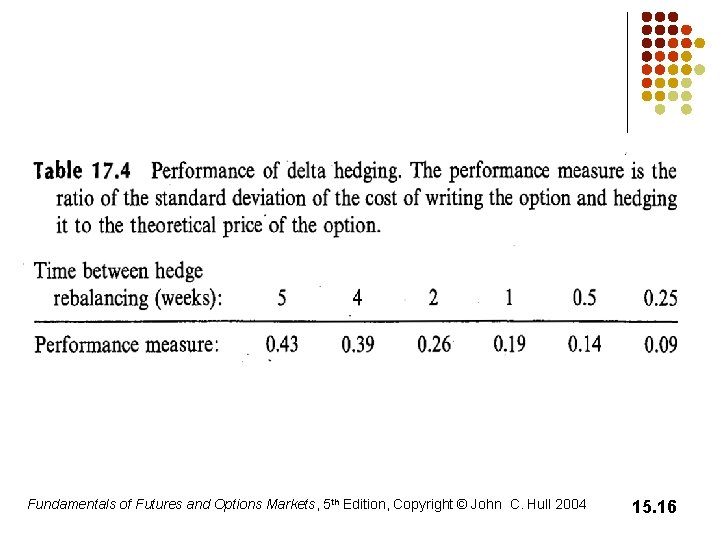
Delta Hedging continued l l The hedge position must be frequently rebalanced Delta hedging a written option involves a “buy high, sell low” trading rule Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 11
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 12
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 13
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 14
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 15
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 16
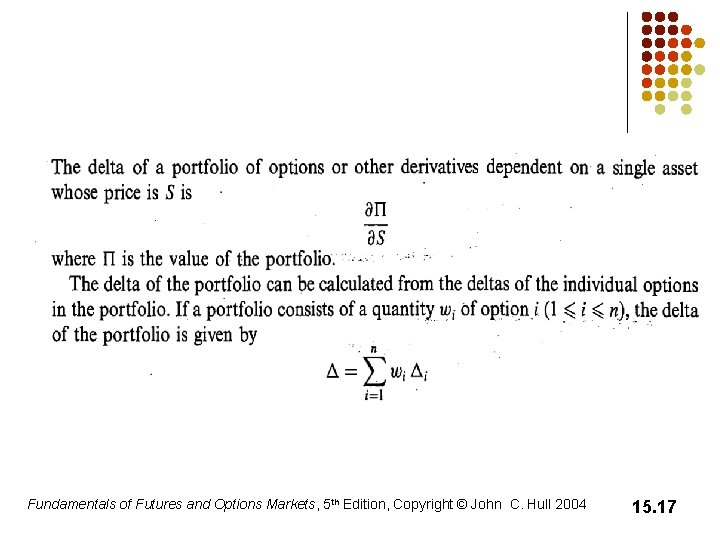
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 17
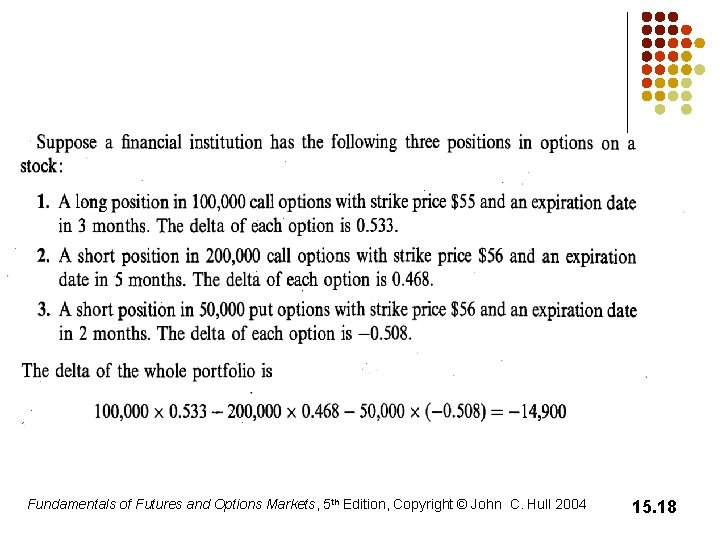
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 18
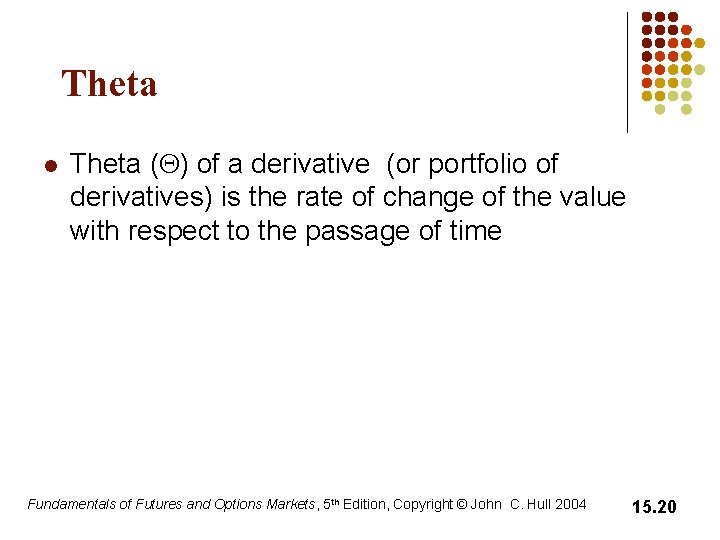
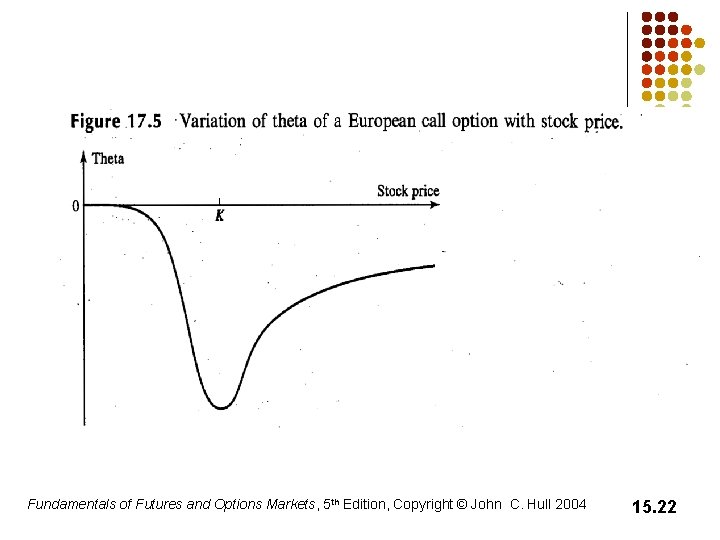
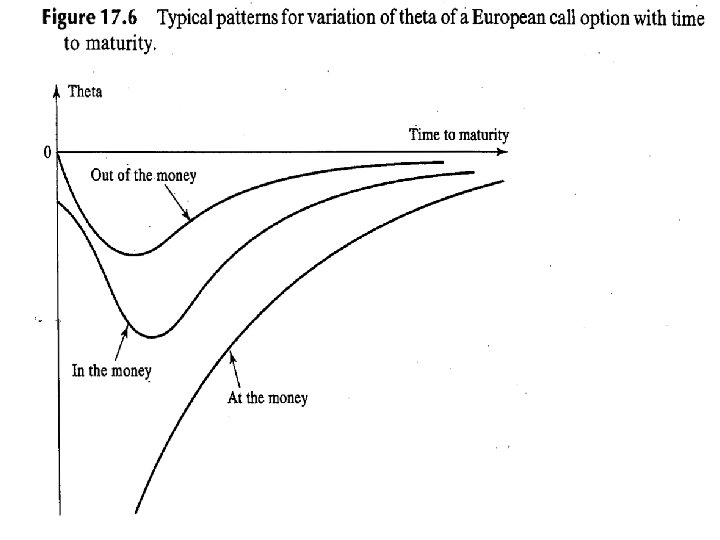
Theta l Theta (Q) of a derivative (or portfolio of derivatives) is the rate of change of the value with respect to the passage of time Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 20
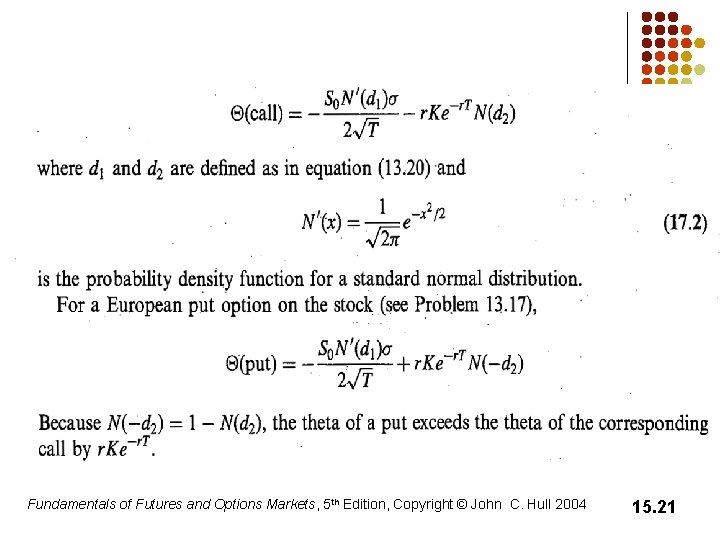
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 21
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 22
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 23
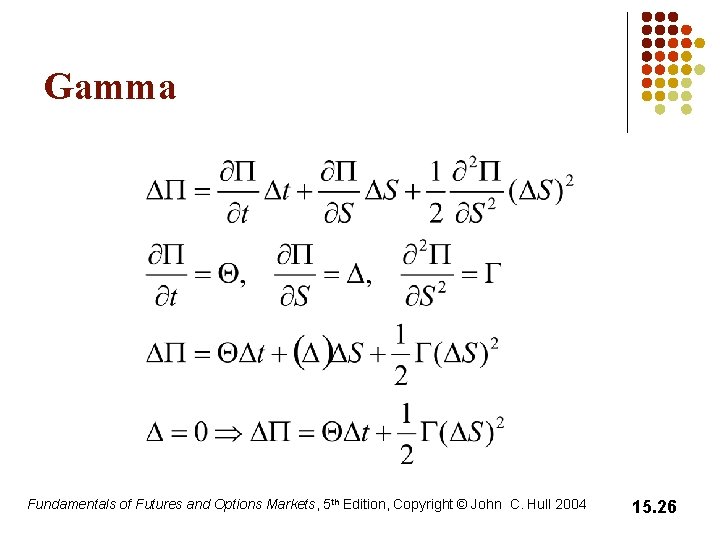
Gamma l Gamma (G) is the rate of change of delta (D) with respect to the price of the underlying asset Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 24
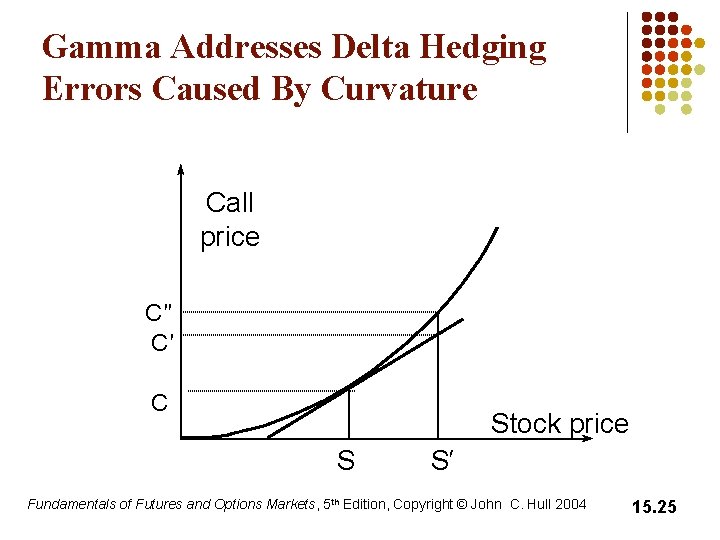
Gamma Addresses Delta Hedging Errors Caused By Curvature Call price C′′ C′ C Stock price S S′ Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 25
Gamma Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 26
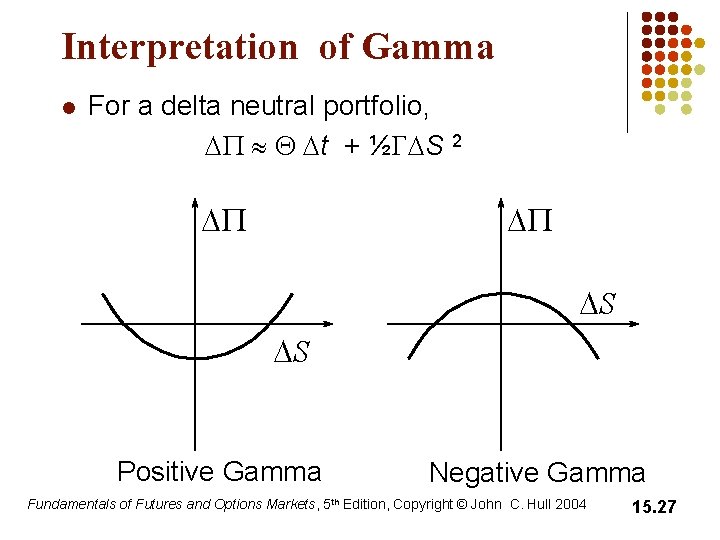
Interpretation of Gamma l For a delta neutral portfolio, DP » Q Dt + ½GDS 2 DP DP DS DS Positive Gamma Negative Gamma Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 27
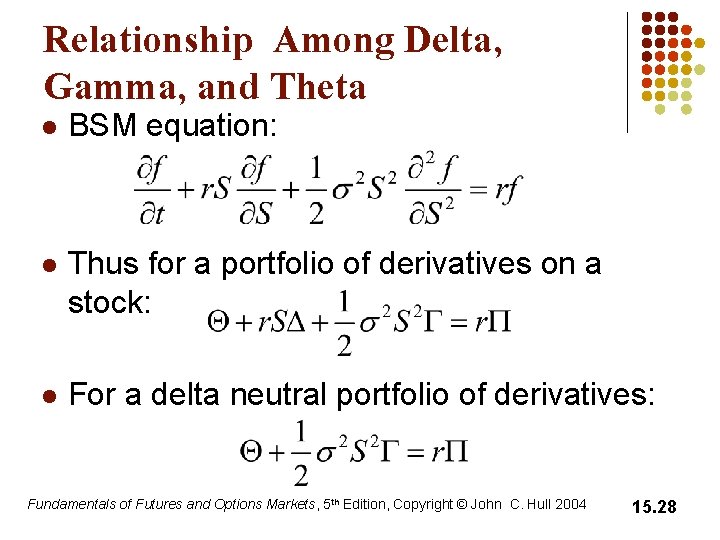
Relationship Among Delta, Gamma, and Theta l BSM equation: l Thus for a portfolio of derivatives on a stock: l For a delta neutral portfolio of derivatives: Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 28
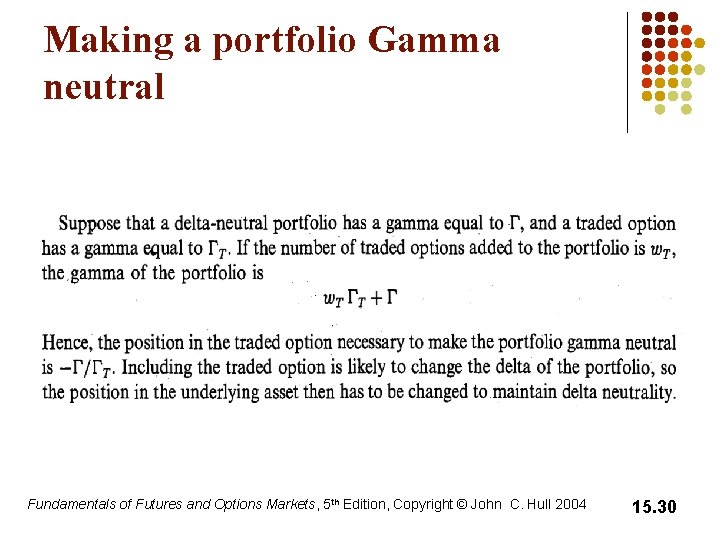
Making a portfolio Gamma neutral Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 30
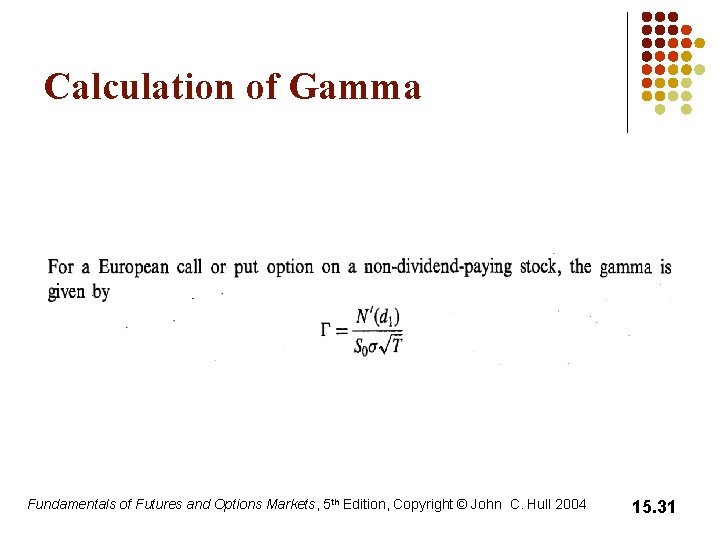
Calculation of Gamma Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 31
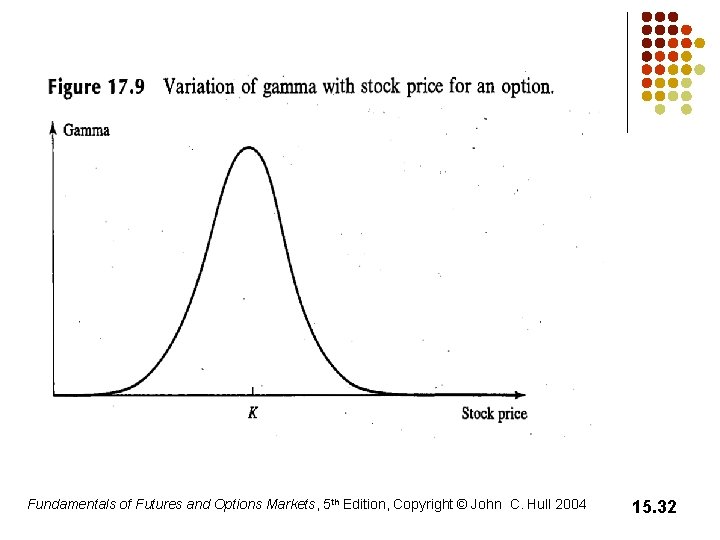
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 32
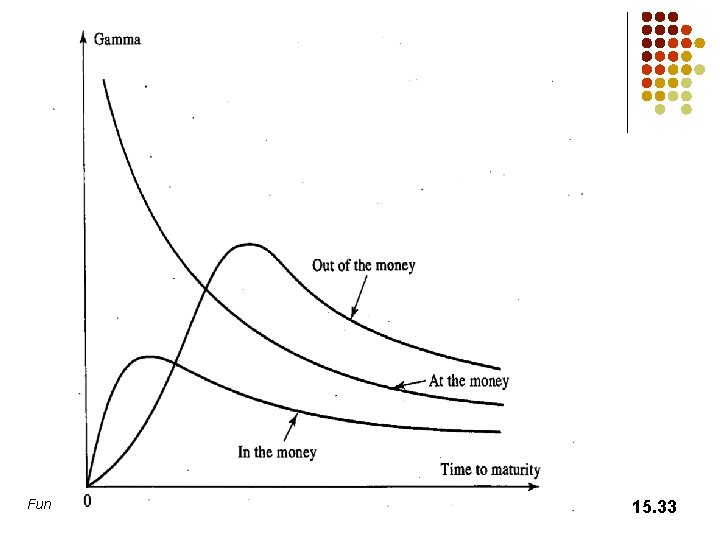
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 33
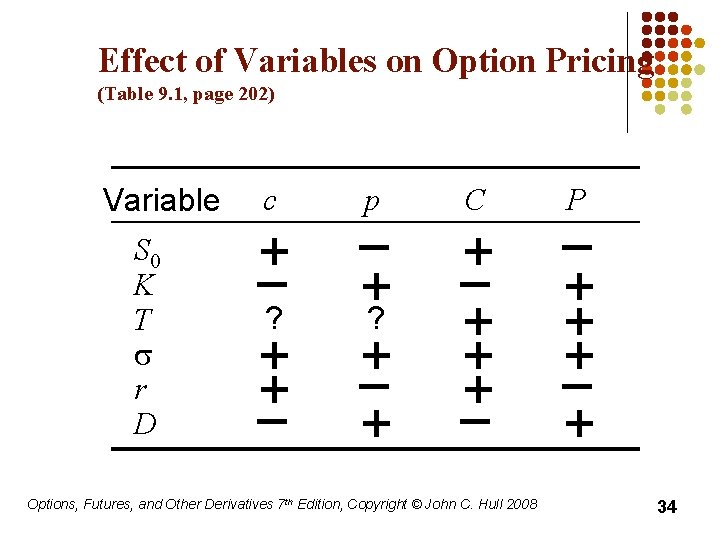
Effect of Variables on Option Pricing (Table 9. 1, page 202) Variable S 0 K T r D c + – ? + + – p – +? + – + C + – + + + – Options, Futures, and Other Derivatives 7 th Edition, Copyright © John C. Hull 2008 P – + + + – + 34
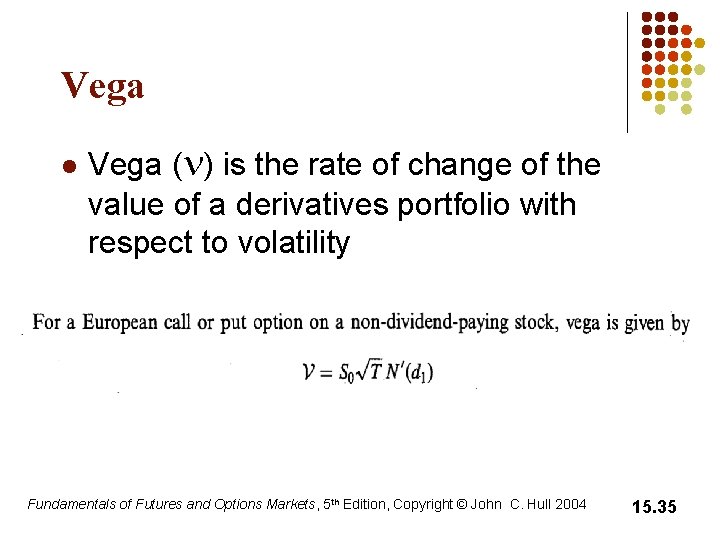
Vega l Vega (n) is the rate of change of the value of a derivatives portfolio with respect to volatility Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 35
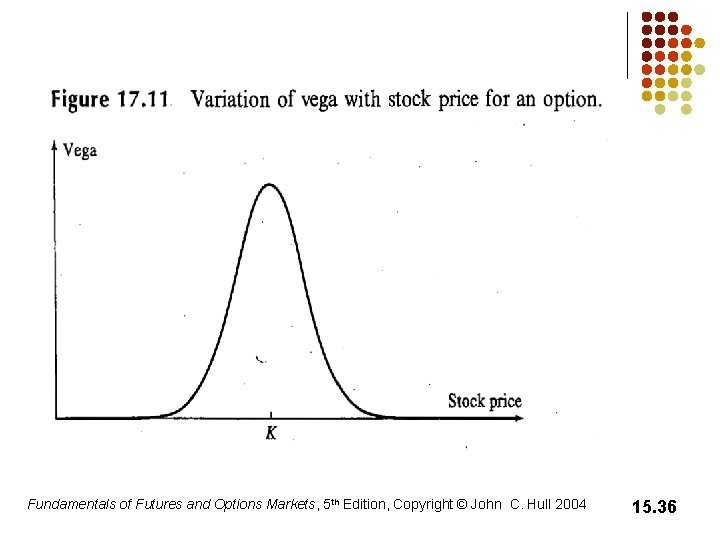
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 36
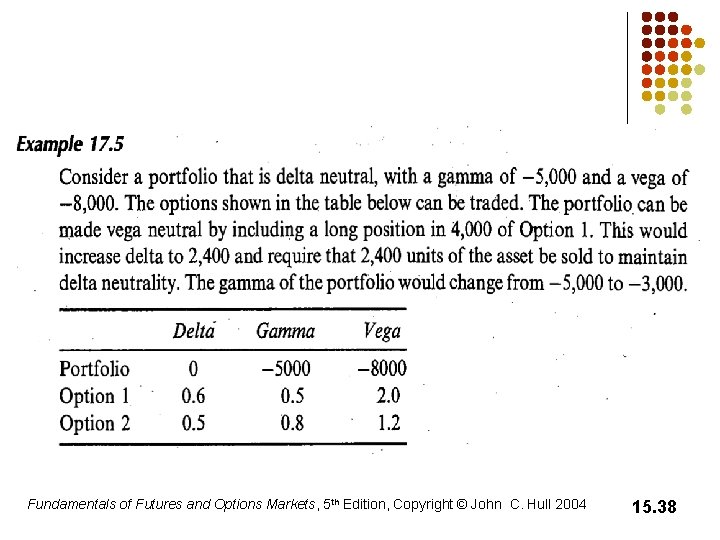
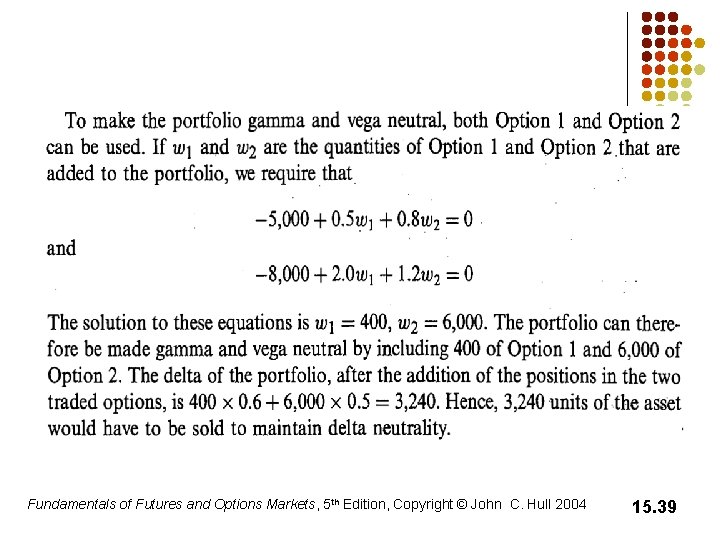
Managing Delta, Gamma, & Vega Delta, D, can be changed by taking a position in the underlying asset l To adjust gamma, G, and vega, n, it is necessary to take a position in an option or other derivative l Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 37
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 38
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 39
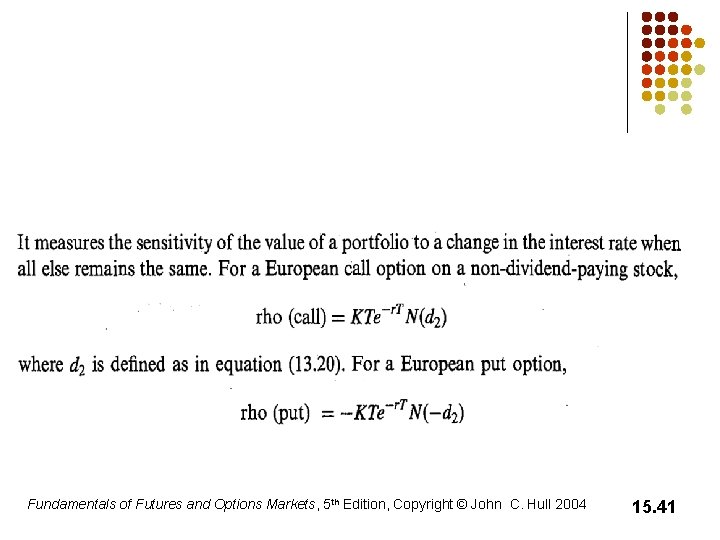
Rho l Rho is the rate of change of the value of a derivative with respect to the interest rate Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 40
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 41
Hedging in Practice l l l Traders usually ensure that their portfolios are delta-neutral at least once a day Whenever the opportunity arises, they improve gamma and vega As portfolio becomes larger hedging becomes less expensive Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 42
Scenario Analysis A scenario analysis involves testing the effect on the value of a portfolio of different assumptions concerning asset prices and their volatilities Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 43
Hedging vs Creation of an Option Synthetically l l When we are hedging we take positions that offset D, G, n, etc. When we create an option synthetically we take positions that match D, G, & n Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 44
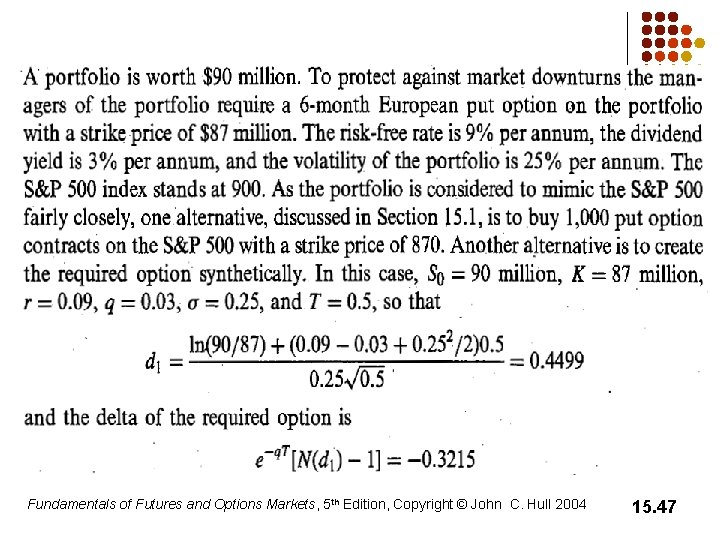
Portfolio Insurance l l Many portfolio managers attempted to create a put option on a portfolio synthetically This involves initially selling enough of the portfolio (or of index futures) to match the D of the put option Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 45
Portfolio Insurance continued l l As the value of the portfolio increases, the D of the put becomes less negative and some of the original portfolio is repurchased As the value of the portfolio decreases, the D of the put becomes more negative and more of the portfolio must be sold Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 46
Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 47
Portfolio Insurance continued The strategy did not work well on October 19, 1987. . . Fundamentals of Futures and Options Markets, 5 th Edition, Copyright © John C. Hull 2004 15. 48