
The Future Supply of Natural Gas Key Trends
- Slides: 11
The Future Supply of Natural Gas: Key Trends and Challenges Report from PGC B, SG 2 World gas Conference, Amsterdam 5 -9 June 2006 Runar Tjersland VP Natural Gas Strategy and Analysis Statoil 30/09/2020 TWP 2003 -2006 1 IGU 2006
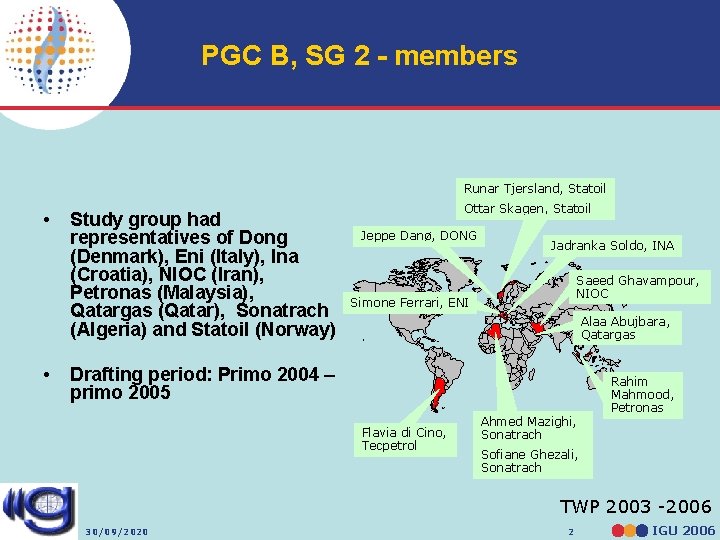
PGC B, SG 2 - members Runar Tjersland, Statoil • • Study group had representatives of Dong (Denmark), Eni (Italy), Ina (Croatia), NIOC (Iran), Petronas (Malaysia), Qatargas (Qatar), Sonatrach (Algeria) and Statoil (Norway) Ottar Skagen, Statoil Jeppe Danø, DONG Jadranka Soldo, INA Saeed Ghavampour, NIOC Simone Ferrari, ENI Alaa Abujbara, Qatargas Drafting period: Primo 2004 – primo 2005 Flavia di Cino, Tecpetrol Ahmed Mazighi, Sonatrach Rahim Mahmood, Petronas Sofiane Ghezali, Sonatrach TWP 2003 -2006 30/09/2020 2 IGU 2006
PGC B, SG 2 - mandates • Study Group 2 mandates: – Examine developments in global gas supply – Summarise and discuss the main long term trends in, and challenges to, gas supply TWP 2003 -2006 30/09/2020 3 IGU 2006
The Report • Outline and briefly analyse key trends in gas supply around the globe • Describe how individual drivers affect gas supply in individual regions and countries, • Spell out the challenges implied by these trends and drivers. • Four parts. 1. 2. 3. 4. gives an overview of gas reserves and gas production trends presents the key drivers and determinants of gas supply. reports on regional gas production developments is a summary of main findings. – In addition, five text boxes briefly addresses gas prices, unconventional gas, LNG, geopolitical initiatives to secure gas supply and demand, and GTL. TWP 2003 -2006 30/09/2020 4 IGU 2006
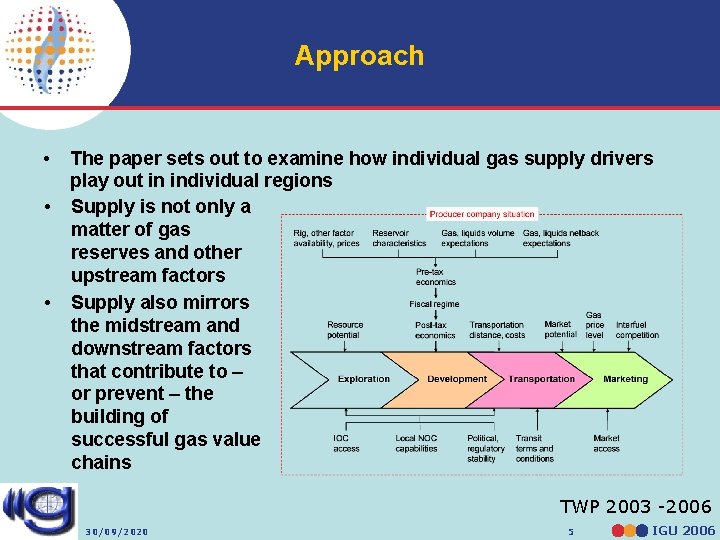
Approach • • • The paper sets out to examine how individual gas supply drivers play out in individual regions Supply is not only a matter of gas reserves and other upstream factors Supply also mirrors the midstream and downstream factors that contribute to – or prevent – the building of successful gas value chains TWP 2003 -2006 30/09/2020 5 IGU 2006
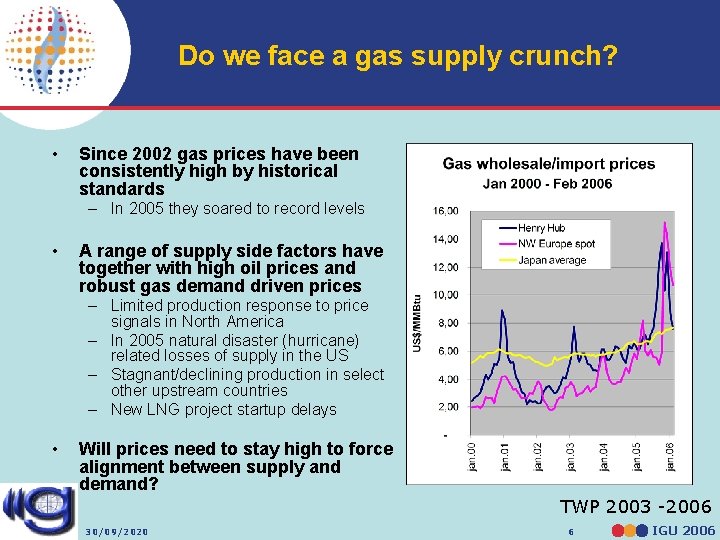
Do we face a gas supply crunch? • Since 2002 gas prices have been consistently high by historical standards – In 2005 they soared to record levels • A range of supply side factors have together with high oil prices and robust gas demand driven prices – Limited production response to price signals in North America – In 2005 natural disaster (hurricane) related losses of supply in the US – Stagnant/declining production in select other upstream countries – New LNG project startup delays • Will prices need to stay high to force alignment between supply and demand? TWP 2003 -2006 30/09/2020 6 IGU 2006
The world is not running out of gas • The global gas reserves to production ratio has since 1980 fluctuated around a gently rising trend • It was 9 years or 16% higher in 2004 than in 1980 – In spite of an 85% increase in annual production • Yet, individual countries and regions struggle to sustain their traditional supply • This calls for further growth in international and interregional gas trade TWP 2003 -2006 30/09/2020 7 IGU 2006
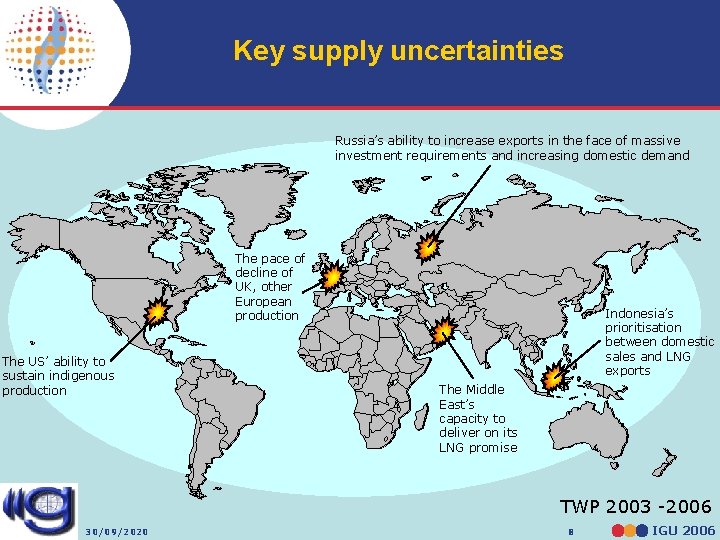
Key supply uncertainties Russia’s ability to increase exports in the face of massive investment requirements and increasing domestic demand The pace of decline of UK, other European production The US’ ability to sustain indigenous production Indonesia’s prioritisation between domestic sales and LNG exports The Middle East’s capacity to deliver on its LNG promise TWP 2003 -2006 30/09/2020 8 IGU 2006
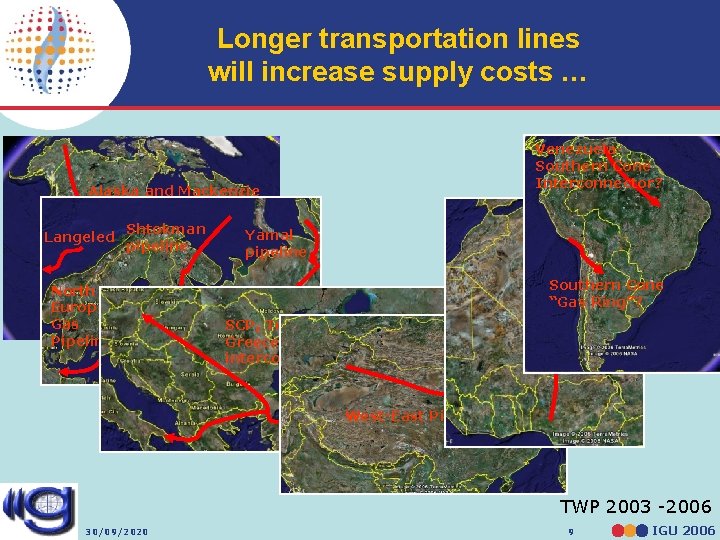
Longer transportation lines will increase supply costs … Venezuela. Southern Cone Interconnector? Alaska and Mackenzie Valley pipelines Langeled Shtokman pipeline North European Gas Pipeline Yamal pipeline SCP, Turkey-Greece and Greece-Italy interconnectors, Nabucco Southern Cone Nigeria“Gas Ring”? Algeria pipeline? West-East Pipeline TWP 2003 -2006 30/09/2020 9 IGU 2006
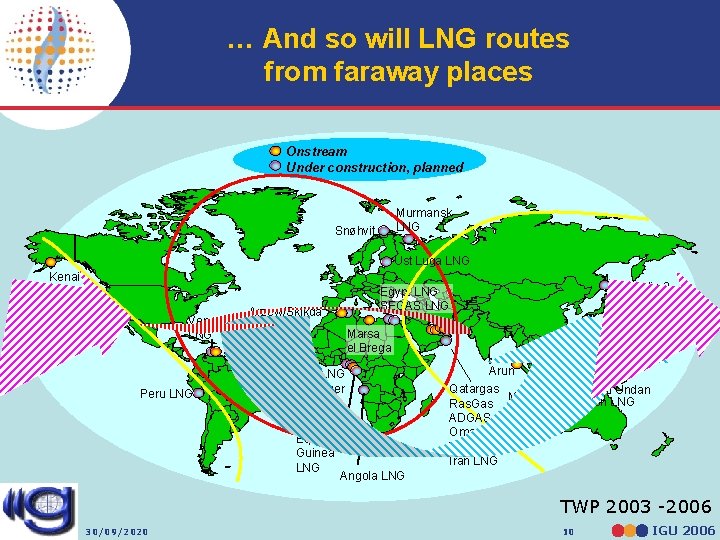
… And so will LNG routes from faraway places Onstream Under construction, planned Murmansk LNG Snøhvit Ust Luga LNG Kenai Arzew/Skikda Venezuela Gassi Touil LNG ALNG Peru LNG Sakhalin 2 Egypt LNG SEGAS LNG Marsa el Brega NLNG Brass River OK LNG Equatorial Guinea LNG Angola LNG Brunei Arun Bontang Tangguh Qatargas Bayu Undan MLNG Gorgon LNG Ras. Gas Pluto NWS ADGAS Oman LNG Yemen LNG Iran LNG TWP 2003 -2006 30/09/2020 10 IGU 2006
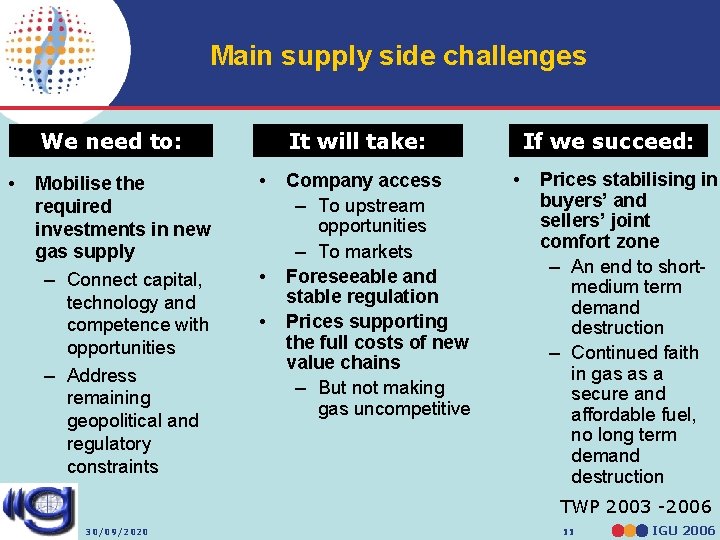
Main supply side challenges We need to: • Mobilise the required investments in new gas supply – Connect capital, technology and competence with opportunities – Address remaining geopolitical and regulatory constraints It will take: • • • Company access – To upstream opportunities – To markets Foreseeable and stable regulation Prices supporting the full costs of new value chains – But not making gas uncompetitive If we succeed: • Prices stabilising in buyers’ and sellers’ joint comfort zone – An end to shortmedium term demand destruction – Continued faith in gas as a secure and affordable fuel, no long term demand destruction TWP 2003 -2006 30/09/2020 11 IGU 2006