
The Big Picture QAD audit webinar Nick Reynolds
The Big Picture – QAD audit webinar Nick Reynolds and Henrietta Thompson 13 May 2014 BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
The Big Picture Ethical standards Understanding the business and audit risk assessment Professional scepticism BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
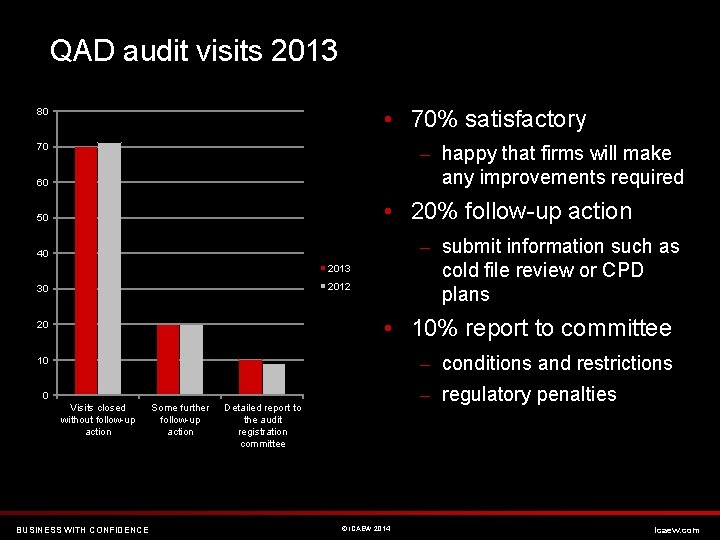
QAD audit visits 2013 • 70% satisfactory 80 70 – happy that firms will make any improvements required 60 • 20% follow-up action 50 – submit information such as cold file review or CPD plans 40 2013 2012 30 20 • 10% report to committee 10 – conditions and restrictions – regulatory penalties 0 Visits closed without follow-up action BUSINESS WITH CONFIDENCE Some further follow-up action Detailed report to the audit registration committee © ICAEW 2014 icaew. com
Ask a question • Participate in today’s webinar – send us a question BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
Ethical standards Financial, business, employment and other personal relationships Long association Fees Non-audit services Documentation BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
Financial, business, employment and other personal relationships • Roles of partners, staff and their immediate and close family members • Trustee shareholdings – Refer to Audit News 52 BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
Long association and fees Listed audit clients Other statutory audits Fee dependency BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
Non-audit services Ethical Standard 5 Prohibited services (particularly listed audit clients) Threats: management, self review, self interest, advocacy Safeguards really can prevent errors BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
Documentation Basic requirements Partner and senior staff involvement Accounts preparation work Audit software BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
Understanding the business and risk assessment BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
Risk assessment The business Accounts and accounting policies Fraud and error Control environment BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
The business • Industry, regulatory and other external factors • Operations, products and services • Ownership and governance • Structure, finance and investment • Objectives and strategies BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
Accounts and accounting policies Turnover Other accounting policies Disclosure BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
Fraud and error • Financial statement manipulation – Revenue recognition • Discussions with client • Discussions within audit team • Management override of controls BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
Control environment ISA 315 Control not process IT controls Design and implementation Operating effectiveness BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
Professional scepticism Central to audit quality Documentation and language used for judgements BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
We discussed the discount rate with management and agreed that 7. 5% was a suitable rate for the goodwill impairment review. There is no risk of fraud in revenue recognition because we have not found indications of fraud at previous audits. BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
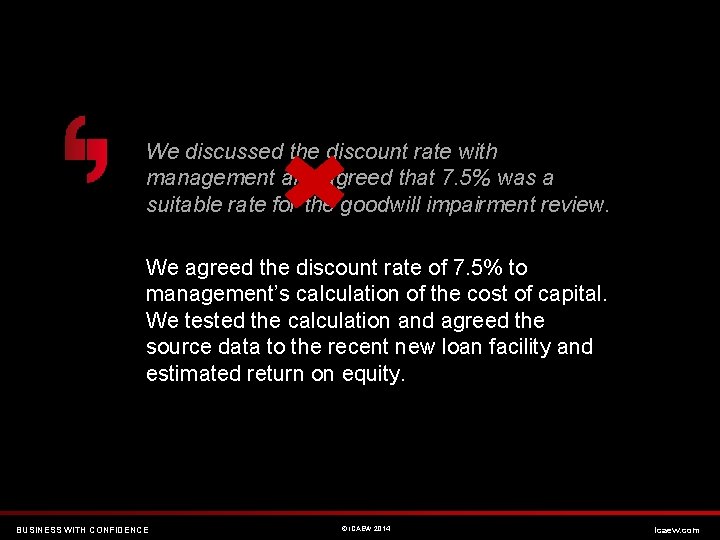
We discussed the discount rate with management and agreed that 7. 5% was a suitable rate for the goodwill impairment review. We agreed the discount rate of 7. 5% to management’s calculation of the cost of capital. We tested the calculation and agreed the source data to the recent new loan facility and estimated return on equity. BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
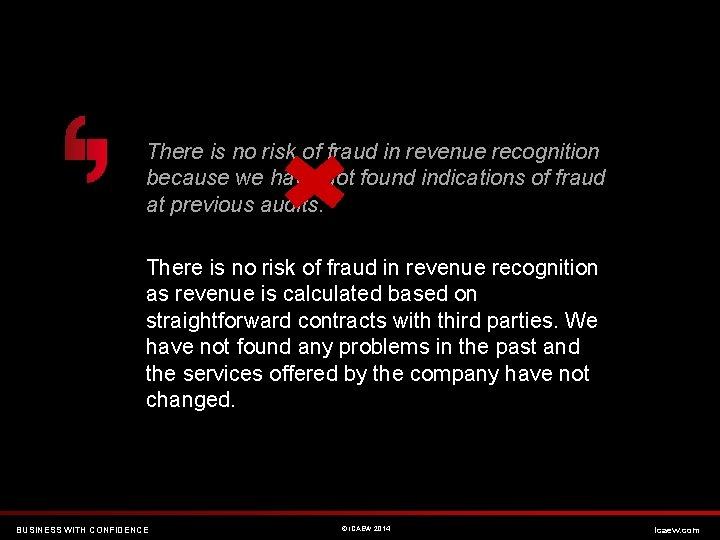
There is no risk of fraud in revenue recognition because we have not found indications of fraud at previous audits. There is no risk of fraud in revenue recognition as revenue is calculated based on straightforward contracts with third parties. We have not found any problems in the past and the services offered by the company have not changed. BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
Professional scepticism Central to audit quality Documentation and language used for judgements Appropriate challenge Consider the big picture BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
Reminders • Documentation • ISQC 1 • Audit compliance reviews BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
Resources and support Audit & Beyond CPD aide memoire Audit News ICAEW Practice Support Services Technical Advisory Services ICAEW website BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
QUESTIONS & ANSWERS BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
A world leader of the accountancy and finance profession BUSINESS WITH CONFIDENCE © ICAEW 2014 icaew. com
- Slides: 24