
The Audit Risk Model Lanfei Gao Michael Andrews
- Slides: 9
The Audit Risk Model Lanfei Gao, Michael Andrews, and Shanaka De. Silva,
Audit Risk • The risk that the auditor may unknowingly fail to appropriately modify the opinion on financial statements that are materially misstated • First fundamental concept of audit procedures
Contents of Audit Risk Detailed level: – Account Balance – Class of Transactions Assertion – Material Misstatement Risk -Inherent risk -Control risk – Detection risk
Engagement Risk • An auditor’s exposure to financial loss and damage to professional reputation. – client and third party lawsuits – negative publicity
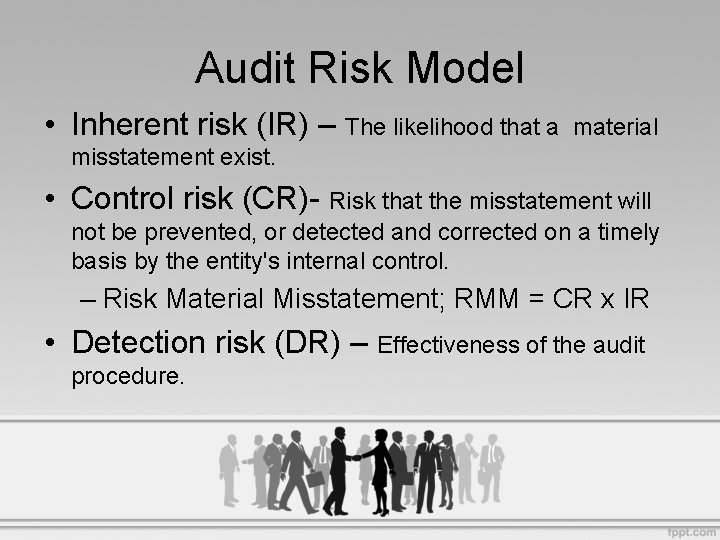
Audit Risk Model • Inherent risk (IR) – The likelihood that a material misstatement exist. • Control risk (CR)- Risk that the misstatement will not be prevented, or detected and corrected on a timely basis by the entity's internal control. – Risk Material Misstatement; RMM = CR x IR • Detection risk (DR) – Effectiveness of the audit procedure.
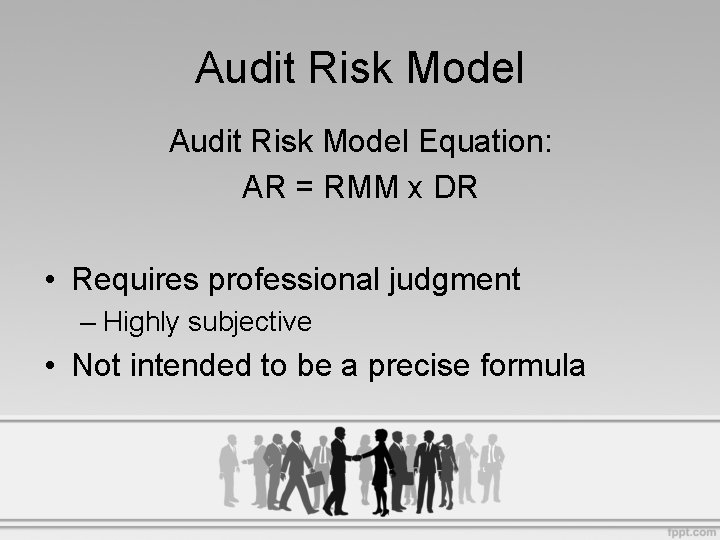
Audit Risk Model Equation: AR = RMM x DR • Requires professional judgment – Highly subjective • Not intended to be a precise formula
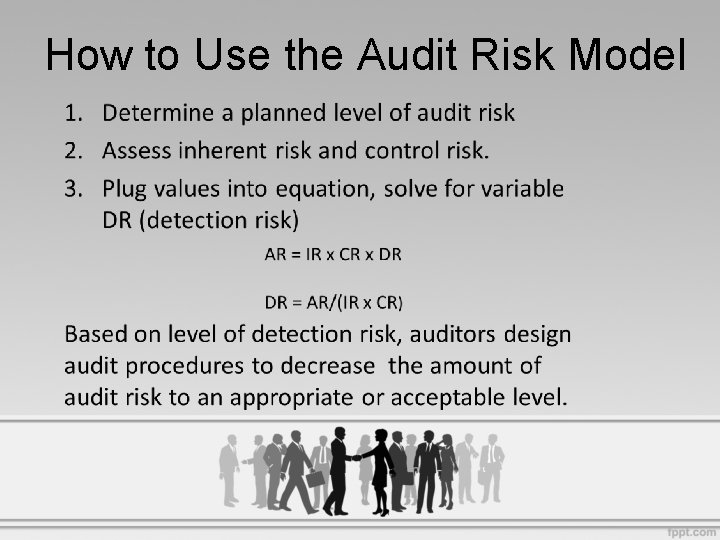
How to Use the Audit Risk Model
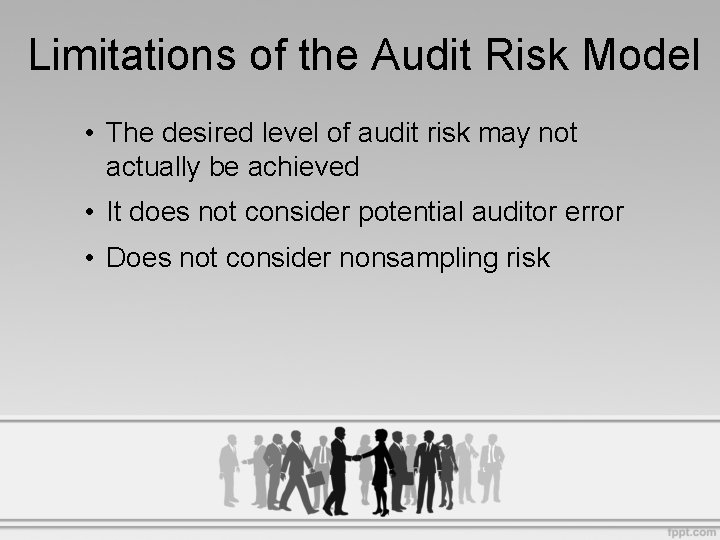
Limitations of the Audit Risk Model • The desired level of audit risk may not actually be achieved • It does not consider potential auditor error • Does not consider nonsampling risk
Thank You! • • What the components the Audit Risk Audit, are Inherent, Detection, of. Control • Model? AR = IR x CR x DR or AR = RMM x DR • • What is the Audit Risk, Risk Model Formula? Determine RMM, • How the. DR Audit Risk Model used? Solveis for • • What Audit Risk Limitations? Audit are Riskthe Level may not. Model’s be achieved, does not consider auditor error, does not consider nonsampling risk