
Telefnica de Espaa Going broadband to build the
Telefónica de España Going broadband to build the future Investor Conference March 2001, Rio de Janeiro.
Safe Harbour This presentation contains statements that constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These statements appear in a number of places in this presentation and include statements regarding the intent, belief or current expectations of the customer base, estimates regarding future growth in the different business lines and the global business, market share, financial results and other aspects of the activities and situation relating to the Company. Such forward looking statements are not guarantees of future performance and involve risks and uncertainties, and actual results may differ materially from those in the forward looking statements as a result of various factors. Analysts are cautioned not to place undue reliance on those forward looking statements, which speak only as of the date of this presentation. Telefónica undertakes no obligation to release publicly the results of any revisions to these forward looking statements which may be made to reflect events and circumstances after the date of this presentation, including, without limitation, changes in Telefónica´s business or acquisition strategy or to reflect the occurrence of unanticipated events. Analysts and investors are encouraged to consult the Company´s Annual Report on Form 20 -F as well as periodic filings made on Form 6 -K, which are on file with the United States Securities and Exchange Commission. Investor Conference March 2001, Rio de Janeiro.
CONTENTS 2000 Results: Exceeding expectations Regulatory outlook: Positive trend Strategic vision going forward: Focus on broadband Main challenges for 2001: Access battle and efficiency Forecasts and commitments Summary: Solid contributor Investor Conference March 2001, Rio de Janeiro.
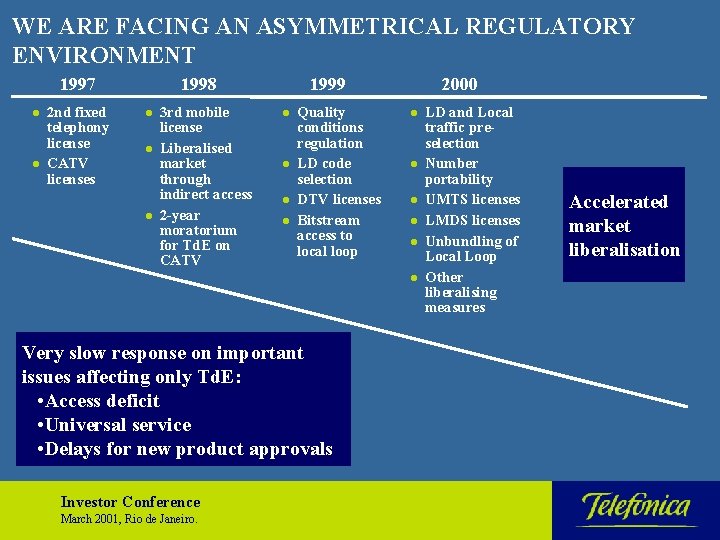
WE ARE FACING AN ASYMMETRICAL REGULATORY ENVIRONMENT 1997 l l 2 nd fixed telephony license CATV licenses 1998 l l l 3 rd mobile license Liberalised market through indirect access 2 -year moratorium for Td. E on CATV 1999 l l Quality conditions regulation LD code selection DTV licenses Bitstream access to local loop 2000 l l l Very slow response on important issues affecting only Td. E: • Access deficit • Universal service • Delays for new product approvals Investor Conference March 2001, Rio de Janeiro. LD and Local traffic preselection Number portability UMTS licenses LMDS licenses Unbundling of Local Loop Other liberalising measures Accelerated market liberalisation
… THAT TOOK US TO AN INTENSIVE COMPETITION IN THE YEAR 2000 l More than 1, 000 licenses granted in Spain l Strong competition in voice traffic from both fixed and mobile players l Fierce competition to gain Internet traffic through bundled voice and Internet services l Cable operators starting to have access to market share l SOHO and SME the most competitive segments Investor Conference March 2001, Rio de Janeiro.
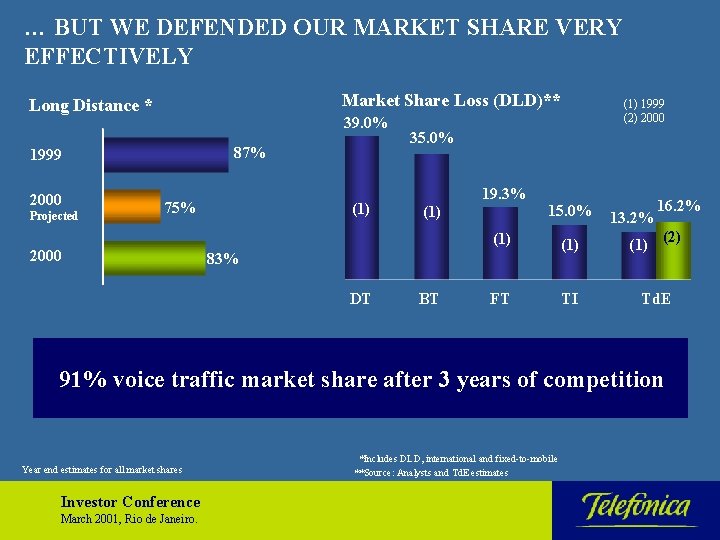
… BUT WE DEFENDED OUR MARKET SHARE VERY EFFECTIVELY Market Share Loss (DLD)** Long Distance * 39. 0% 87% 1999 2000 Projected 75% 2000 (1) 35. 0% 19. 3% (1) 15. 0% BT 13. 2% 16. 2% (1) (1) (2) FT TI Td. E 83% DT (1) 1999 (2) 2000 91% voice traffic market share after 3 years of competition Year end estimates for all market shares Investor Conference March 2001, Rio de Janeiro. *Includes DLD, international and fixed-to-mobile **Source: Analysts and Td. E estimates
AT THE SAME TIME WE ACCOMPLISHED SIGNIFICANT RESULTS IN THREE KEY AREAS Maintained revenues under strong competition Most important achievements Continued improving efficiency Kept rationalizing CAPEX Investor Conference March 2001, Rio de Janeiro. Td. E is one step ahead of European incumbents
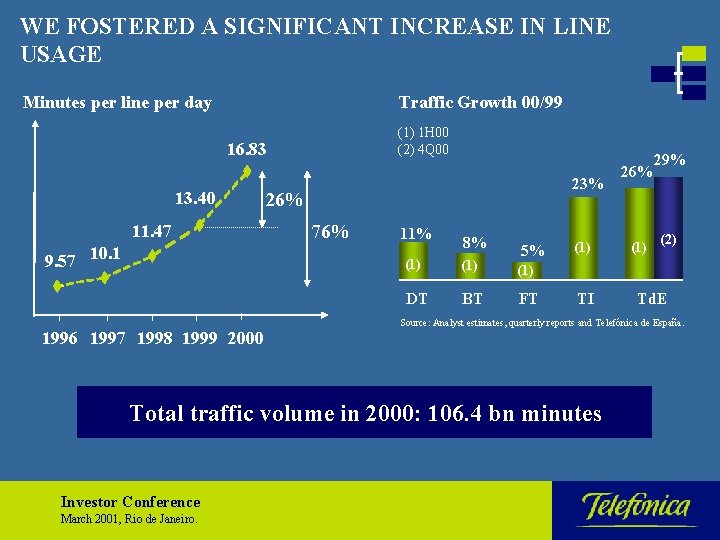
WE FOSTERED A SIGNIFICANT INCREASE IN LINE USAGE Minutes per line per day Traffic Growth 00/99 (1) 1 H 00 (2) 4 Q 00 16. 83 13. 40 11. 47 9. 57 10. 1 1996 1997 1998 1999 2000 23% 26% 76% 11% 8% 5% (1) (1) DT BT FT (1) TI March 2001, Rio de Janeiro. (1) 29% (2) Td. E Source: Analyst estimates, quarterly reports and Telefónica de España. Total traffic volume in 2000: 106. 4 bn minutes Investor Conference 26%
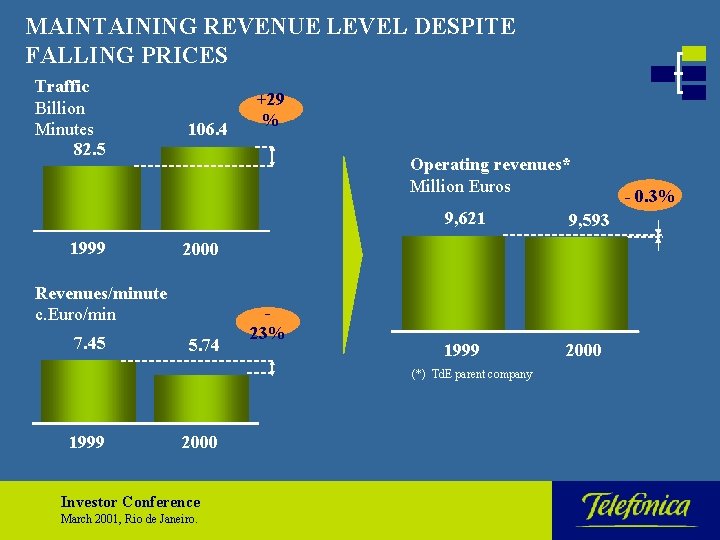
MAINTAINING REVENUE LEVEL DESPITE FALLING PRICES Traffic Billion Minutes 82. 5 1999 106. 4 Operating revenues* Million Euros 9, 621 9, 593 1999 2000 Revenues/minute c. Euro/min 7. 45 +29 % 5. 74 23% (*) Td. E parent company 1999 2000 Investor Conference March 2001, Rio de Janeiro. - 0. 3%
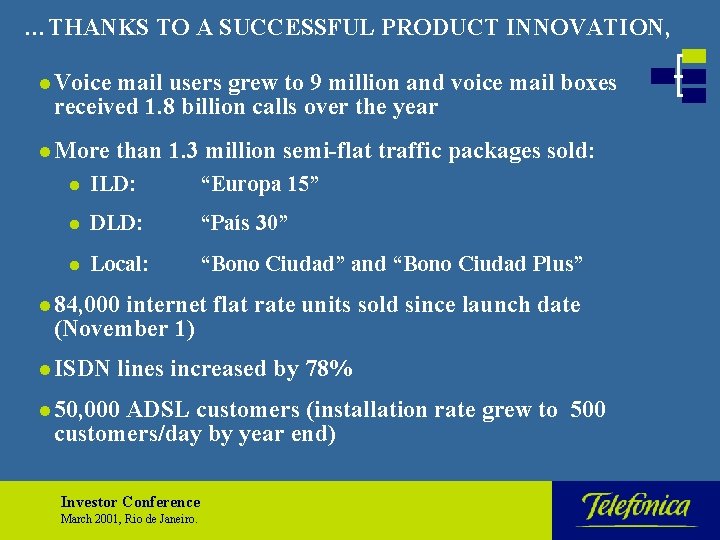
…THANKS TO A SUCCESSFUL PRODUCT INNOVATION, l Voice mail users grew to 9 million and voice mail boxes received 1. 8 billion calls over the year l More than 1. 3 million semi-flat traffic packages sold: l ILD: “Europa 15” l DLD: “País 30” l Local: “Bono Ciudad” and “Bono Ciudad Plus” l 84, 000 internet flat rate units sold since launch date (November 1) l ISDN lines increased by 78% l 50, 000 ADSL customers (installation rate grew to 500 customers/day by year end) Investor Conference March 2001, Rio de Janeiro.
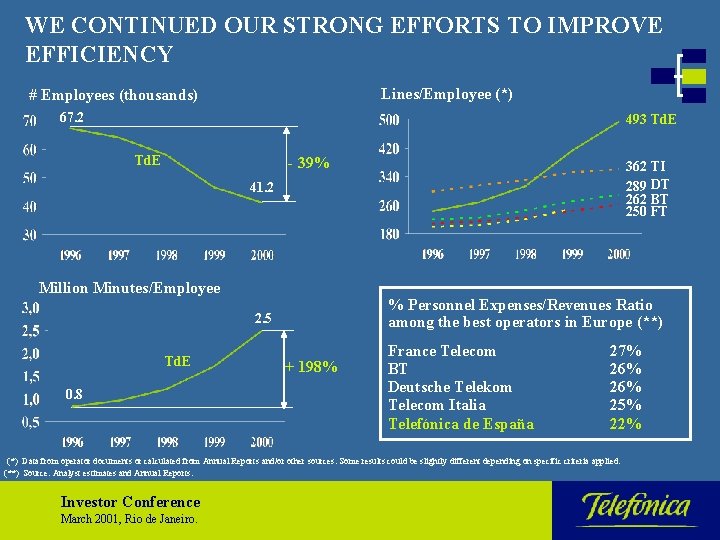
WE CONTINUED OUR STRONG EFFORTS TO IMPROVE EFFICIENCY Lines/Employee (*) # Employees (thousands) 67. 2 493 Td. E - 39% 362 TI 289 DT 262 BT 250 FT 41. 2 Million Minutes/Employee % Personnel Expenses/Revenues Ratio among the best operators in Europe (**) 2. 5 Td. E 0. 8 + 198% France Telecom BT Deutsche Telekom Telecom Italia Telefónica de España 27% 26% 25% 22% (*) Data from operator documents or calculated from Annual Reports and/or other sources. Some results could be slightly different depending on specific criteria applied. (**) Source: Analyst estimates and Annual Reports. Investor Conference March 2001, Rio de Janeiro.
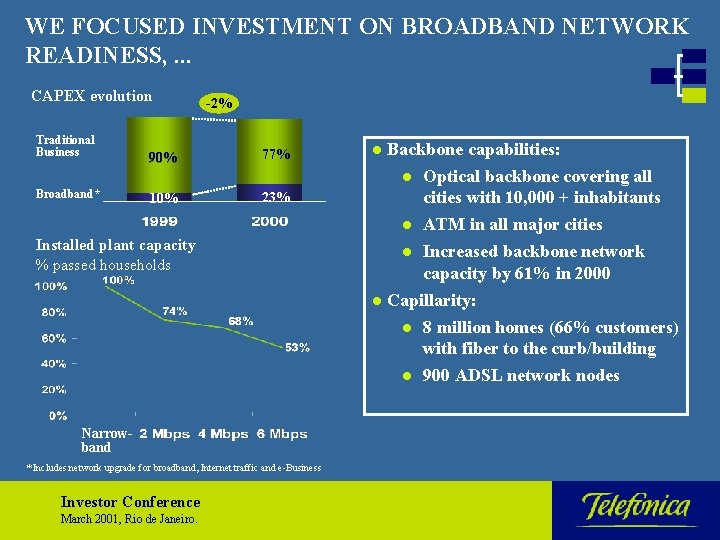
WE FOCUSED INVESTMENT ON BROADBAND NETWORK READINESS, . . . CAPEX evolution Traditional Business 90% -2% 77% l Backbone capabilities: Optical backbone covering all cities with 10, 000 + inhabitants l ATM in all major cities l Increased backbone network capacity by 61% in 2000 l Capillarity: l 8 million homes (66% customers) with fiber to the curb/building l 900 ADSL network nodes l Broadband* 10% 23% Installed plant capacity % passed households Narrowband * Includes network upgrade for broadband, Internet traffic and e-Business Investor Conference March 2001, Rio de Janeiro.
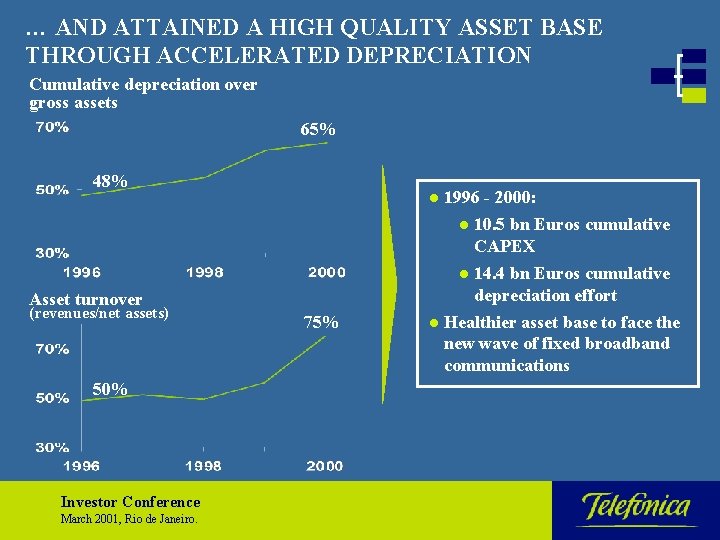
… AND ATTAINED A HIGH QUALITY ASSET BASE THROUGH ACCELERATED DEPRECIATION Cumulative depreciation over gross assets 65% 48% l 1996 - 2000: 10. 5 bn Euros cumulative CAPEX l 14. 4 bn Euros cumulative depreciation effort l Healthier asset base to face the new wave of fixed broadband communications l Asset turnover (revenues/net assets) 50% Investor Conference March 2001, Rio de Janeiro. 75%
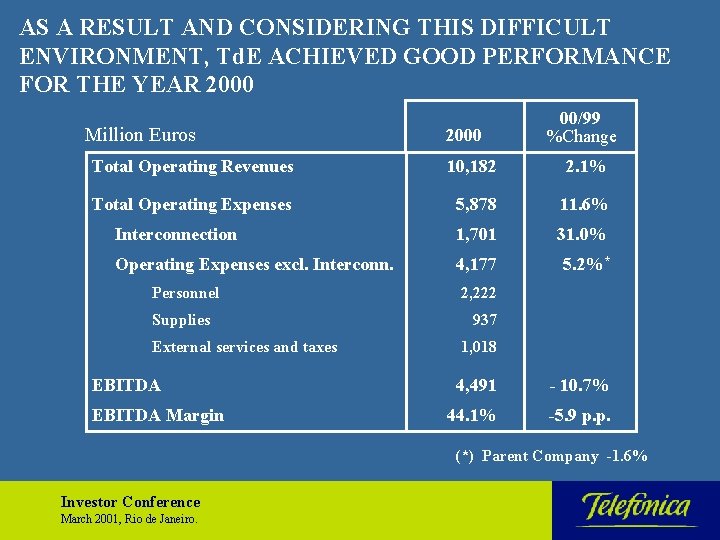
AS A RESULT AND CONSIDERING THIS DIFFICULT ENVIRONMENT, Td. E ACHIEVED GOOD PERFORMANCE FOR THE YEAR 2000 Million Euros 2000 00/99 %Change Total Operating Revenues 10, 182 2. 1% Total Operating Expenses 5, 878 11. 6% Interconnection 1, 701 31. 0% Operating Expenses excl. Interconn. 4, 177 5. 2%* Personnel Supplies External services and taxes EBITDA Margin 2, 222 937 1, 018 4, 491 - 10. 7% 44. 1% -5. 9 p. p. (*) Parent Company -1. 6% Investor Conference March 2001, Rio de Janeiro.
CONTENTS 2000 Results: Exceeding expectations Regulatory outlook: Positive trend Strategic vision going forward: Focus on broadband Main challenges for 2001: Access battle and efficiency Forecasts and commitments Summary: Solid contributor Investor Conference March 2001, Rio de Janeiro.
MOST REGULATORY ISSUES ALREADY SETTLED Price cap: Overall price evolution defined Monthly fee: Increases in 2001 and 2002 already approved ULL*: Price aligned with EU standards (*) Unbundling of the Local Loop Investor Conference March 2001, Rio de Janeiro. Regulatory uncertainty reduced through proactive management
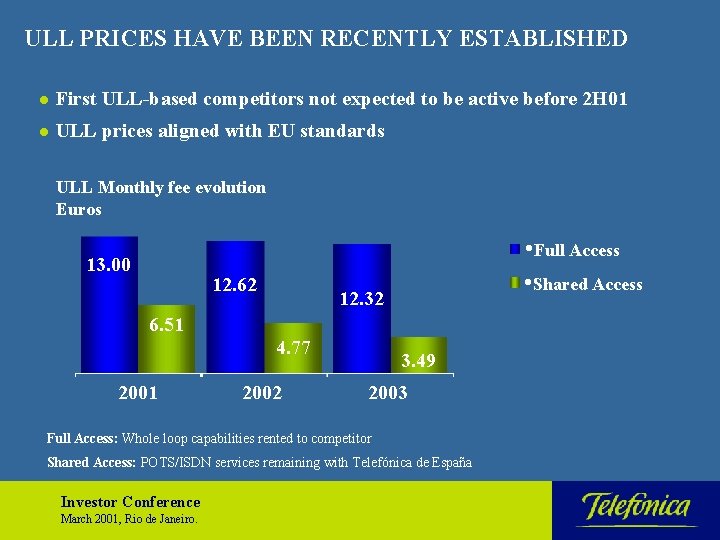
ULL PRICES HAVE BEEN RECENTLY ESTABLISHED l First ULL-based competitors not expected to be active before 2 H 01 l ULL prices aligned with EU standards ULL Monthly fee evolution Euros 13. 00 12. 62 • Full Access • Shared Access 12. 32 6. 51 4. 77 2001 2002 3. 49 2003 Full Access: Whole loop capabilities rented to competitor Shared Access: POTS/ISDN services remaining with Telefónica de España Investor Conference March 2001, Rio de Janeiro.
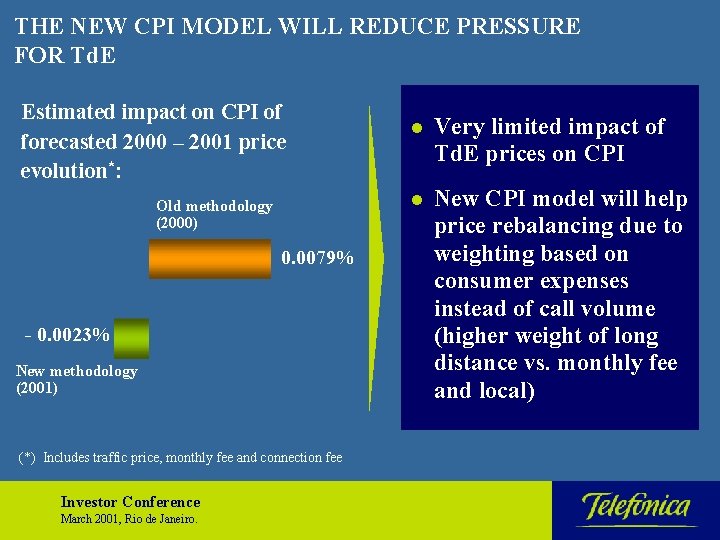
THE NEW CPI MODEL WILL REDUCE PRESSURE FOR Td. E Estimated impact on CPI of forecasted 2000 – 2001 price evolution*: Old methodology (2000) 0. 0079% - 0. 0023% New methodology (2001) (*) Includes traffic price, monthly fee and connection fee Investor Conference March 2001, Rio de Janeiro. l Very limited impact of Td. E prices on CPI l New CPI model will help price rebalancing due to weighting based on consumer expenses instead of call volume (higher weight of long distance vs. monthly fee and local)
AND WE KEEP PROACTIVELY NEGOTIATING THE ACCESS DEFICIT ISSUE Access deficit linked to price rebalancing could have an important positive impact on short-term results: – Cost accounting presented to Regulator – 12. 6% ROIC* already accepted – EC sent reasoned statement to Spanish Government on Telefónica´s request to be answered by March 29 th 2001 (*) Before taxes Investor Conference March 2001, Rio de Janeiro. Positive results are expected
CONTENTS 2000 Results: Exceeding expectations Regulatory outlook: Positive trend Strategic vision going forward: Focus on broadband Main challenges for 2001: Access battle and efficiency Forecasts and commitments Summary: Solid contributor Investor Conference March 2001, Rio de Janeiro.
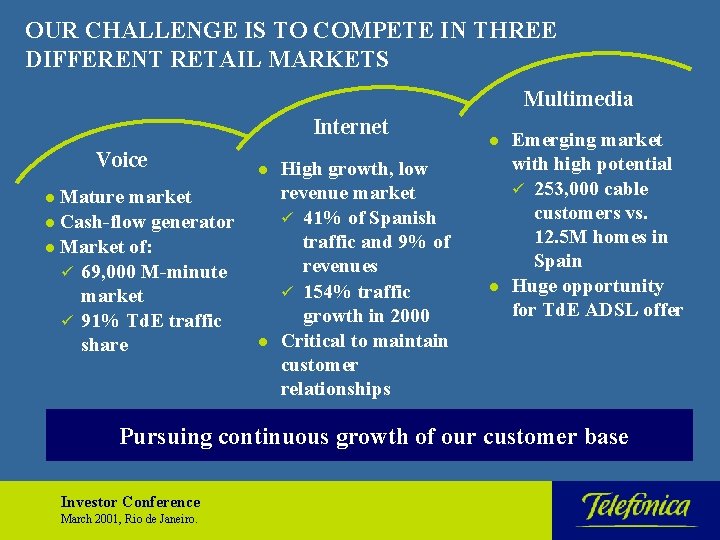
OUR CHALLENGE IS TO COMPETE IN THREE DIFFERENT RETAIL MARKETS Multimedia Internet Voice market l Cash-flow generator l Market of: ü 69, 000 M-minute market ü 91% Td. E traffic share l l Mature l High growth, low revenue market ü 41% of Spanish traffic and 9% of revenues ü 154% traffic growth in 2000 Critical to maintain customer relationships l l Emerging market with high potential ü 253, 000 cable customers vs. 12. 5 M homes in Spain Huge opportunity for Td. E ADSL offer Pursuing continuous growth of our customer base Investor Conference March 2001, Rio de Janeiro.
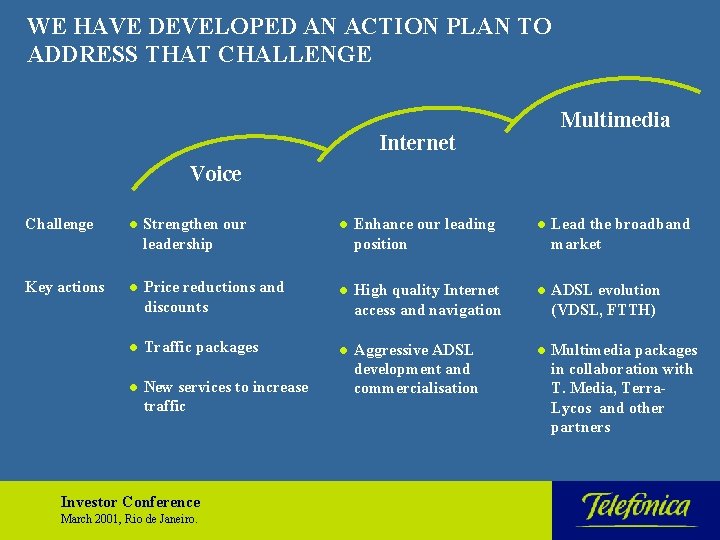
WE HAVE DEVELOPED AN ACTION PLAN TO ADDRESS THAT CHALLENGE Multimedia Internet Voice Challenge l Strengthen our leadership l Enhance our leading position l Lead the broadband market Key actions l Price reductions and discounts l High quality Internet access and navigation l ADSL evolution (VDSL, FTTH) l Traffic packages l l l New services to increase traffic Aggressive ADSL development and commercialisation Multimedia packages in collaboration with T. Media, Terra. Lycos and other partners Investor Conference March 2001, Rio de Janeiro.
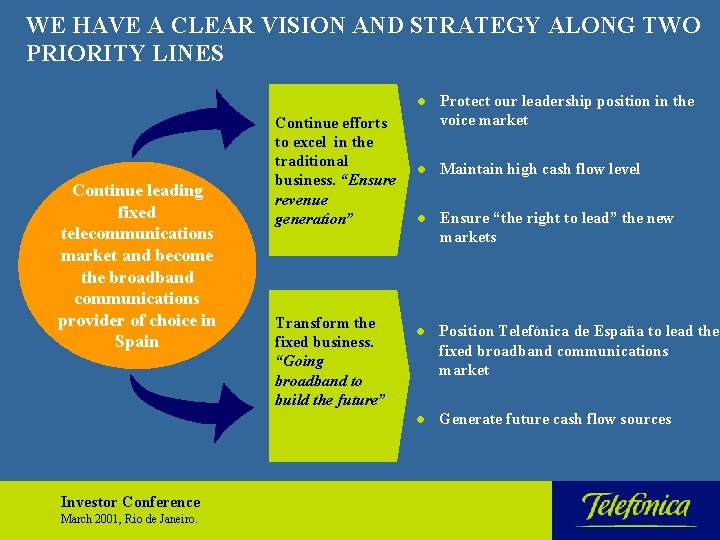
WE HAVE A CLEAR VISION AND STRATEGY ALONG TWO PRIORITY LINES Continue leading fixed telecommunications market and become the broadband communications provider of choice in Spain Investor Conference March 2001, Rio de Janeiro. Continue efforts to excel in the traditional business. “Ensure revenue generation” Transform the fixed business. “Going broadband to build the future” l Protect our leadership position in the voice market l Maintain high cash flow level l Ensure “the right to lead” the new markets l Position Telefónica de España to lead the fixed broadband communications market l Generate future cash flow sources
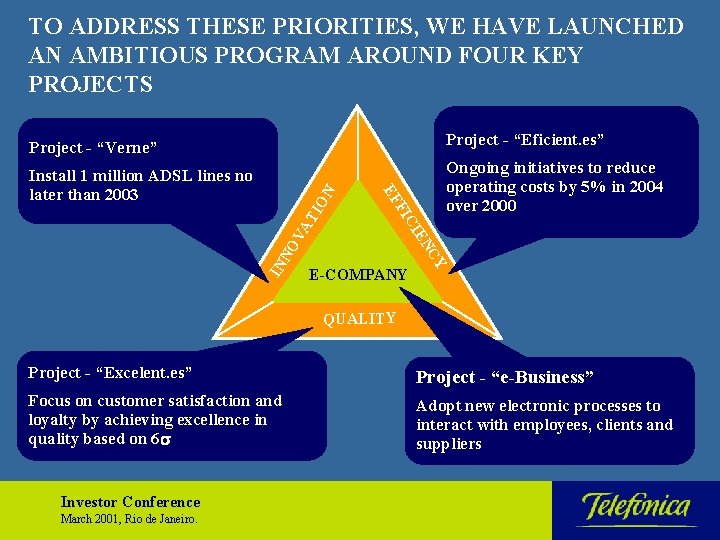
TO ADDRESS THESE PRIORITIES, WE HAVE LAUNCHED AN AMBITIOUS PROGRAM AROUND FOUR KEY PROJECTS Install 1 million ADSL lines no later than 2003 Ongoing initiatives to reduce operating costs by 5% in 2004 over 2000 AT E-COMPANY CY IN EN NO V CI FI IO N Project - “Eficient. es” EF Project - “Verne” QUALITY Project - “Excelent. es” Project - “e-Business” Focus on customer satisfaction and loyalty by achieving excellence in quality based on 6 Adopt new electronic processes to interact with employees, clients and suppliers Investor Conference March 2001, Rio de Janeiro.
CONTENTS 2000 Results: Exceeding expectations Regulatory outlook: Positive trend Strategic vision going forward: Focus on broadband Main challenges for 2001: Access battle and efficiency Forecasts and commitments Summary: Solid contributor Investor Conference March 2001, Rio de Janeiro.
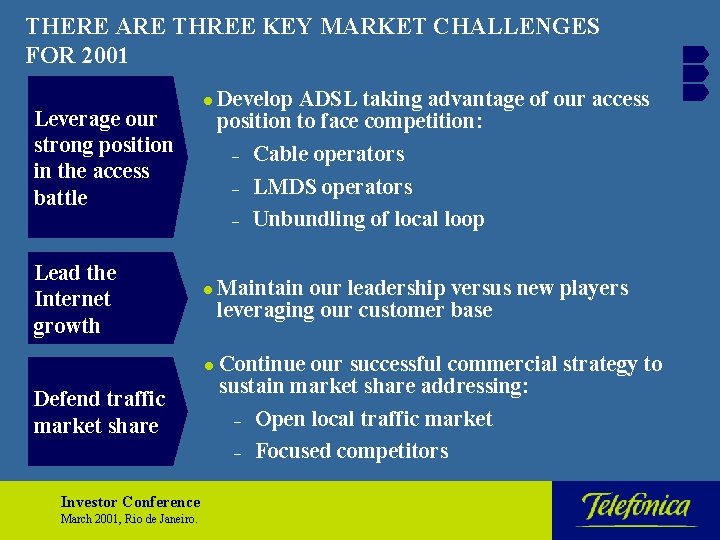
THERE ARE THREE KEY MARKET CHALLENGES FOR 2001 Leverage our strong position in the access battle Lead the Internet growth l l l Defend traffic market share Investor Conference March 2001, Rio de Janeiro. Develop ADSL taking advantage of our access position to face competition: – Cable operators – LMDS operators – Unbundling of local loop Maintain our leadership versus new players leveraging our customer base Continue our successful commercial strategy to sustain market share addressing: – Open local traffic market – Focused competitors
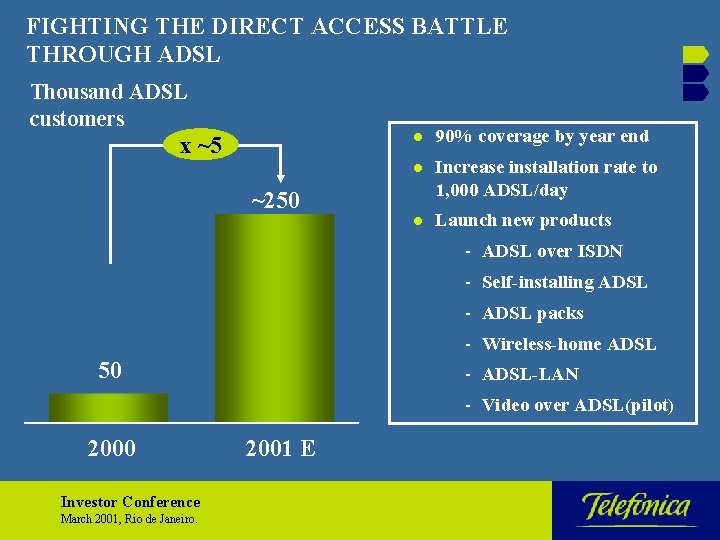
FIGHTING THE DIRECT ACCESS BATTLE THROUGH ADSL Thousand ADSL customers x ~5 l 90% coverage by year end l Increase installation rate to 1, 000 ADSL/day l Launch new products ~250 - ADSL over ISDN - Self-installing ADSL - ADSL packs - Wireless-home ADSL 50 - ADSL-LAN - Video over ADSL(pilot) 2000 Investor Conference March 2001, Rio de Janeiro. 2001 E
STRENGTHENING INTERNET POSITION THROUGH HIGH QUALITY ACCESS AND NAVIGABILITY l Enhance our leadership l position in the Internet market to capture new l growth l Investor Conference March 2001, Rio de Janeiro. Exploit ADSL capabilities – Broadband applications in collaboration with Group companies and other partners Develop new competitive services and offers – Premium quality Internet access – New flat-rate options Foster the Internet in the Small and Medium Enterprise segment: – Customised business application services – VPN over ADSL Expand distribution channels – Flat-rate commercialisation through third parties
DEFENDING VOICE TRAFFIC MARKET SHARE We aim to repeat the success of 2000 by: Managing price policies Fostering services that increase traffic Optimizing marketing and distribution Investor Conference March 2001, Rio de Janeiro. · Price cuts (10%) and selective discounts · New semi-flat rate packages for national and international calls (5 million packs) · Customised billing packages for businesses · · 10 million mail boxes 2 million lines with calling-ID Unified messaging with Internet and mobile Voice portal · Launching aggressive “win-back” campaigns (28% success in 2000) · Improving sales force and call center effectiveness · Enhancing on-line channel and reinforcing thirdchannel capacity
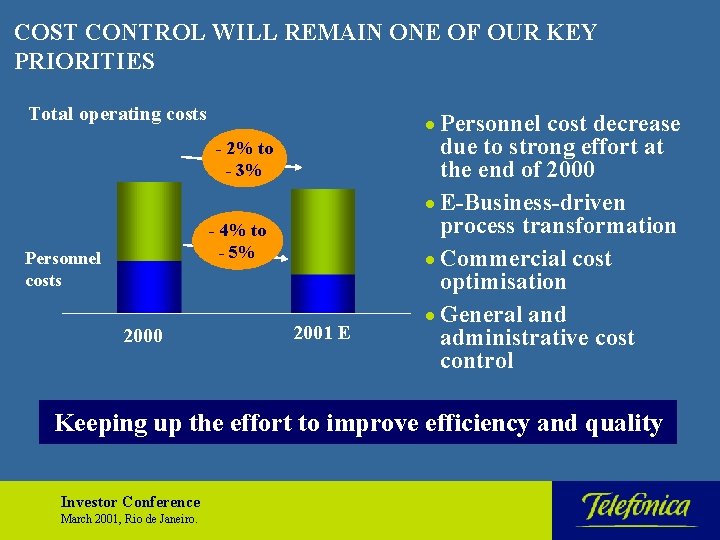
COST CONTROL WILL REMAIN ONE OF OUR KEY PRIORITIES Total operating costs · Personnel cost decrease - 2% to - 3% - 4% to - 5% Personnel costs 2000 2001 E due to strong effort at the end of 2000 · E-Business-driven process transformation · Commercial cost optimisation · General and administrative cost control Keeping up the effort to improve efficiency and quality Investor Conference March 2001, Rio de Janeiro.
WE HAVE STRONG CAPABILITIES TO FACE A MORE DEMANDING ENVIRONMENT IN 2001 Network - High capillarity: 21 M loops - Readiness for broadband evolution: 8 M with FTTC* - High availability of network services (99, 5%) Operations - Massive and widespread operations capacity: presence in 758 cities; 8 M visits to customers per year - Knowledge of customer equipment - Service-oriented culture Commercial - 1, 400 Sales Force and 5, 400 Tele-Marketing agents specialised in different market segments - 90 million commercial contacts in 2000 - 1, 900 Telefónica shops and points of sale - 30 million on-line visits per month - CRM use for “win-back” and new product strategies - Top brand perception (10% ahead of next competitor) * Fiber to the curb Motivated talent through variable incentive schemes Investor Conference March 2001, Rio de Janeiro.
CONTENTS 2000 Results: Exceeding expectations Regulatory outlook: Positive trend Strategic vision going forward: Focus on broadband Main challenges for 2001: Access battle and efficiency Forecasts and commitments Summary: Solid contributor Investor Conference March 2001, Rio de Janeiro.
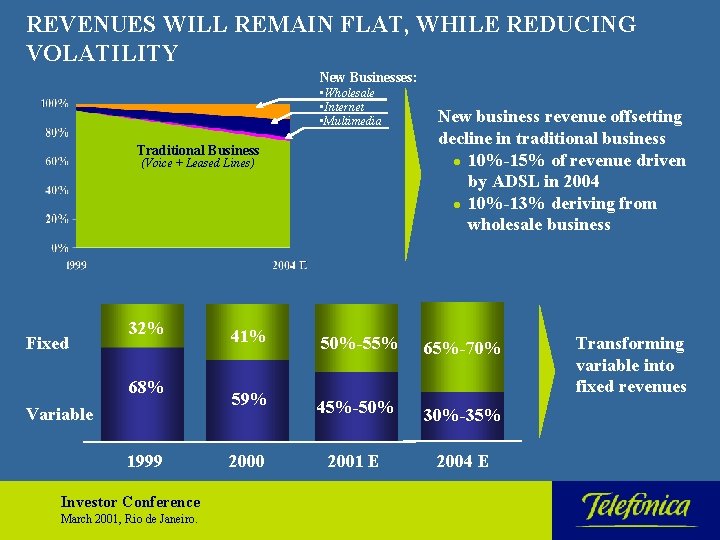
REVENUES WILL REMAIN FLAT, WHILE REDUCING VOLATILITY New Businesses: • Wholesale • Internet • Multimedia Traditional Business (Voice + Leased Lines) Fixed 32% 68% Variable 1999 Investor Conference March 2001, Rio de Janeiro. New business revenue offsetting decline in traditional business l 10%-15% of revenue driven by ADSL in 2004 l 10%-13% deriving from wholesale business 41% 50%-55% 65%-70% 59% 45%-50% 30%-35% 2000 2001 E 2004 E Transforming variable into fixed revenues
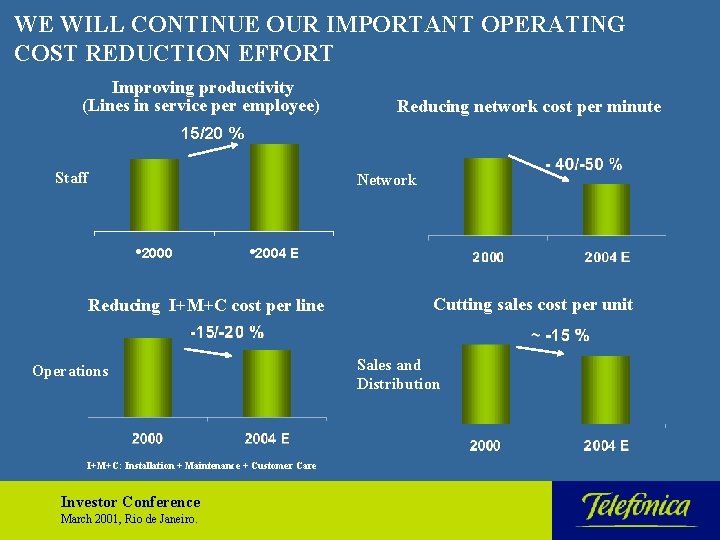
WE WILL CONTINUE OUR IMPORTANT OPERATING COST REDUCTION EFFORT Improving productivity (Lines in service per employee) Reducing network cost per minute 15/20 % Staff Network • 2000 • 2004 E Reducing I+M+C cost per line Operations I+M+C: Installation + Maintenance + Customer Care Investor Conference March 2001, Rio de Janeiro. Cutting sales cost per unit Sales and Distribution
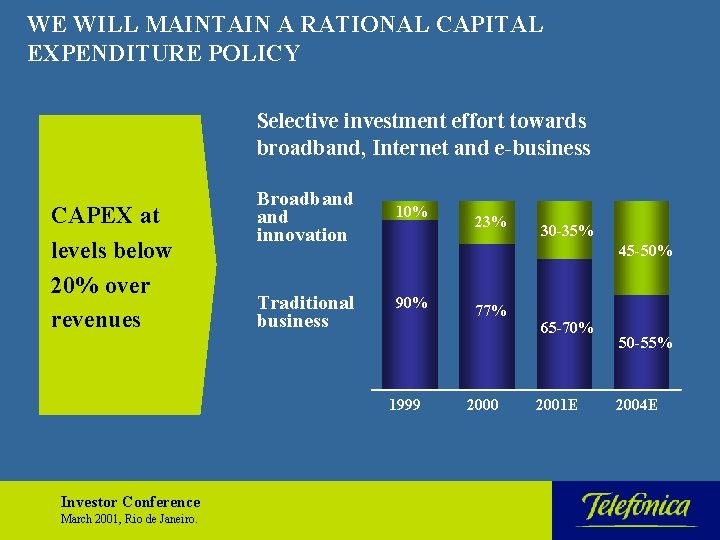
WE WILL MAINTAIN A RATIONAL CAPITAL EXPENDITURE POLICY Selective investment effort towards broadband, Internet and e-business CAPEX at levels below 20% over revenues Broadband innovation Traditional business 10% March 2001, Rio de Janeiro. 30 -35% 45 -50% 90% 1999 Investor Conference 23% 77% 2000 65 -70% 2001 E 50 -55% 2004 E
AS A RESULT… Telefónica de España is committed to pursuing aggressive financial targets for the 2001 -2004 period: l l l Maintain operating revenue CAGR between – 1% and 3%. Improve operating expense performance, with CAGR of 0% to – 4%. Obtain EBITDA margins in the range of 42% to 45% on revenues l Keep investment level below 20% over revenues l Ensure operating cash flow level above 3 bn euros per annum Investor Conference March 2001, Rio de Janeiro.
CONTENTS 2000 Results: Exceeding expectations Regulatory outlook: Positive trend Strategic vision going forward: Focus on broadband Main challenges for 2001: Access battle and efficiency Forecasts and commitments Summary: Solid contributor Investor Conference March 2001, Rio de Janeiro.
IN SUMMARY, TELEFONICA DE ESPAÑA l l l Managed to perform successfully in 2000 exceeding market expectations Settled a solid base and gained an advantage over other European incumbents Developed a clear strategy and launched an action program to face 2001 challenges and to be prepared to exploit future opportunities Ready to lead the broadband challenge to enhance our profitable growth, in a context of lower regulatory pressure and uncertainty Will become an even more solid contributor to Telefónica Group cash flows and EBITDA Investor Conference March 2001, Rio de Janeiro.
Investor Conference March 2001, Rio de Janeiro.
- Slides: 40