
Telecommunications Liberalization and Regulatory Framework in Lebanon Refarming
Telecommunications Liberalization and Regulatory Framework in Lebanon Re-farming for Broadband Lebanon Dr. Imad Y. Hoballah Commissioner, Board Member, Head of Telecommunications Technologies Unit Telecommunications Regulatory Authority (TRA) Lebanon www. tra. gov. lb
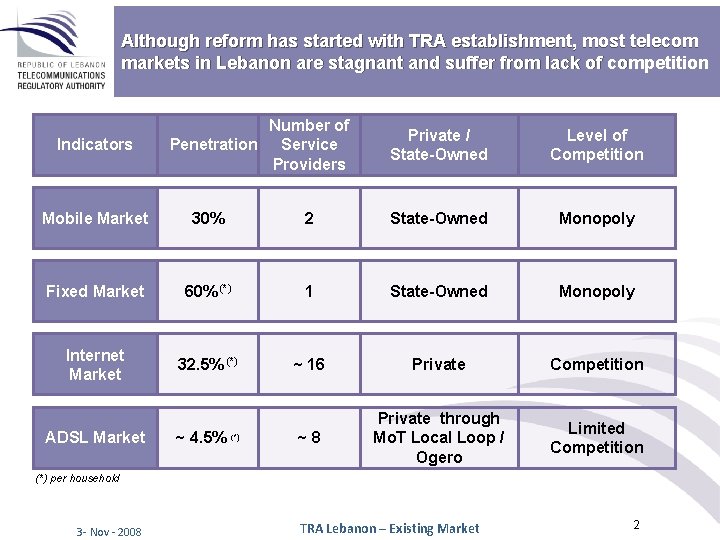
Although reform has started with TRA establishment, most telecom markets in Lebanon are stagnant and suffer from lack of competition Indicators Number of Penetration Service Providers Private / State-Owned Level of Competition Mobile Market 30% 2 State-Owned Monopoly Fixed Market 60% (*) 1 State-Owned Monopoly Internet Market 32. 5% (*) ~ 16 Private Competition ~8 Private through Mo. T Local Loop / Ogero Limited Competition ADSL Market ~ 4. 5% (*) per household 3 - Nov - 2008 TRA Lebanon – Existing Market 2
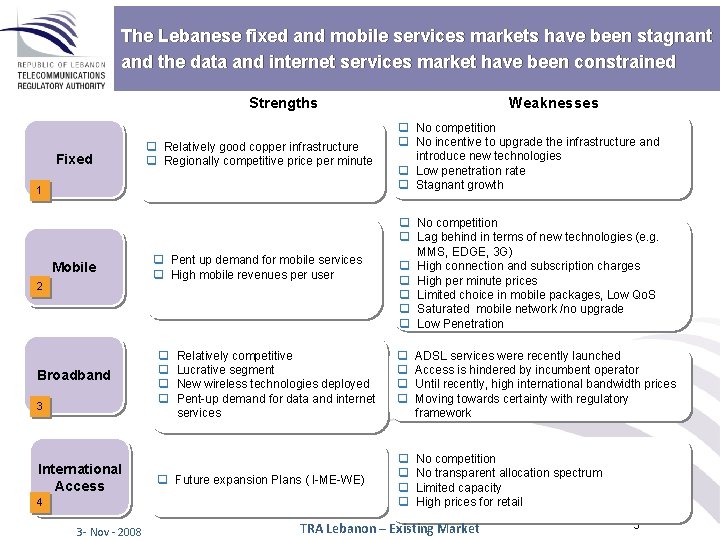
The Lebanese fixed and mobile services markets have been stagnant and the data and internet services market have been constrained Weaknesses Strengths Fixed q Relatively good copper infrastructure q Regionally competitive price per minute q No competition q No incentive to upgrade the infrastructure and introduce new technologies q Low penetration rate q Stagnant growth q Pent up demand for mobile services q High mobile revenues per user q No competition q Lag behind in terms of new technologies (e. g. MMS, EDGE, 3 G) q High connection and subscription charges q High per minute prices q Limited choice in mobile packages, Low Qo. S q Saturated mobile network /no upgrade q Low Penetration 1 Mobile 2 Broadband 3 International Access 4 3 - Nov - 2008 q q Relatively competitive Lucrative segment New wireless technologies deployed Pent-up demand for data and internet services q Future expansion Plans ( I-ME-WE) q q ADSL services were recently launched Access is hindered by incumbent operator Until recently, high international bandwidth prices Moving towards certainty with regulatory framework q q No competition No transparent allocation spectrum Limited capacity High prices for retail TRA Lebanon – Existing Market • 3 3
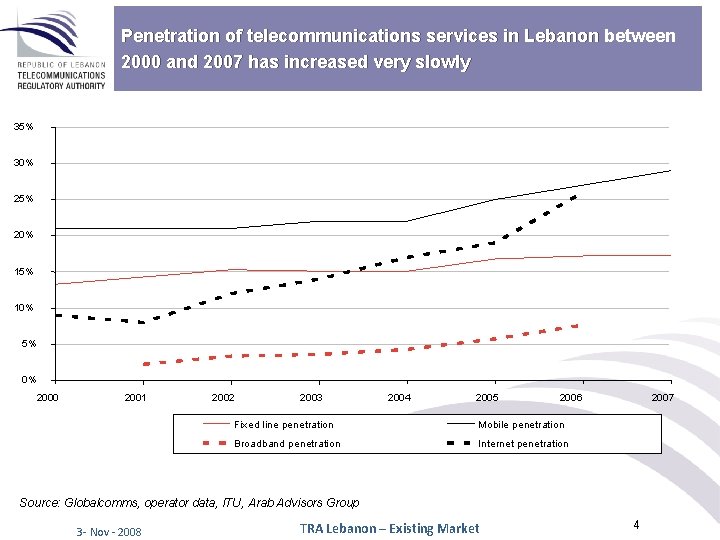
Penetration of telecommunications services in Lebanon between 2000 and 2007 has increased very slowly 35% 30% 25% 20% 15% 10% 5% 0% 2000 2001 2002 2003 2004 2005 2006 Fixed line penetration Mobile penetration Broadband penetration Internet penetration 2007 Source: Globalcomms, operator data, ITU, Arab Advisors Group 3 - Nov - 2008 TRA Lebanon – Existing Market 4
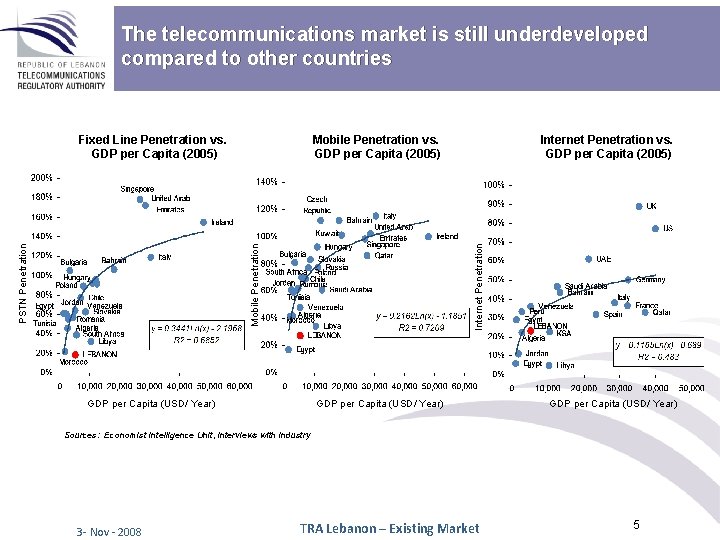
The telecommunications market is still underdeveloped compared to other countries Mobile Penetration vs. GDP per Capita (2005) Mobile Penetration PSTN Penetration Internet Penetration vs. GDP per Capita (2005) Internet Penetration Fixed Line Penetration vs. GDP per Capita (2005) GDP per Capita (USD/ Year) Sources: Economist Intelligence Unit, interviews with industry 3 - Nov - 2008 TRA Lebanon – Existing Market 5
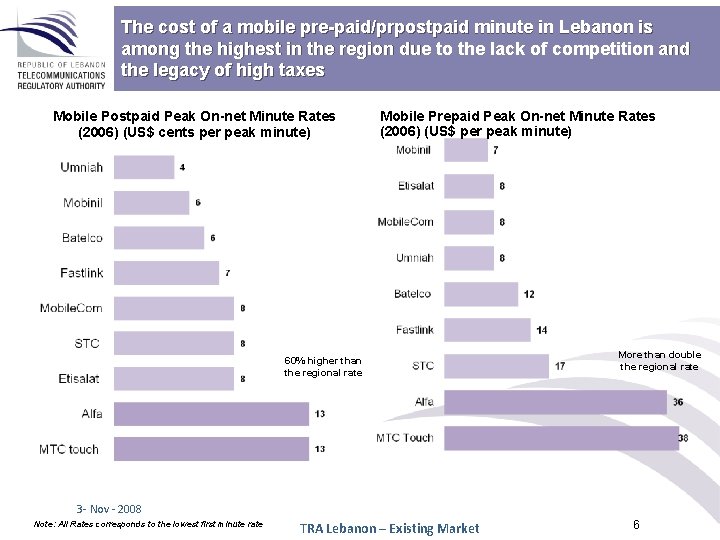
The cost of a mobile pre-paid/prpostpaid minute in Lebanon is among the highest in the region due to the lack of competition and the legacy of high taxes Mobile Postpaid Peak On-net Minute Rates (2006) (US$ cents per peak minute) Mobile Prepaid Peak On-net Minute Rates (2006) (US$ per peak minute) 60% higher than the regional rate More than double the regional rate 3 - Nov - 2008 Note: All Rates corresponds to the lowest first minute rate TRA Lebanon – Existing Market 6
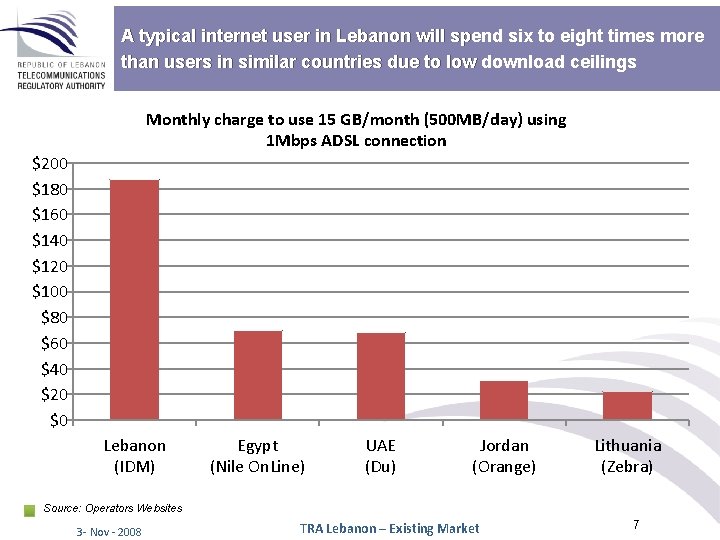
A typical internet user in Lebanon will spend six to eight times more than users in similar countries due to low download ceilings Monthly charge to use 15 GB/month (500 MB/day) using 1 Mbps ADSL connection $200 $180 $160 $140 $120 $100 $80 $60 $40 $20 $0 Lebanon (IDM) Egypt (Nile On. Line) UAE (Du) Jordan (Orange) Lithuania (Zebra) Source: Operators Websites 3 - Nov - 2008 TRA Lebanon – Existing Market 7
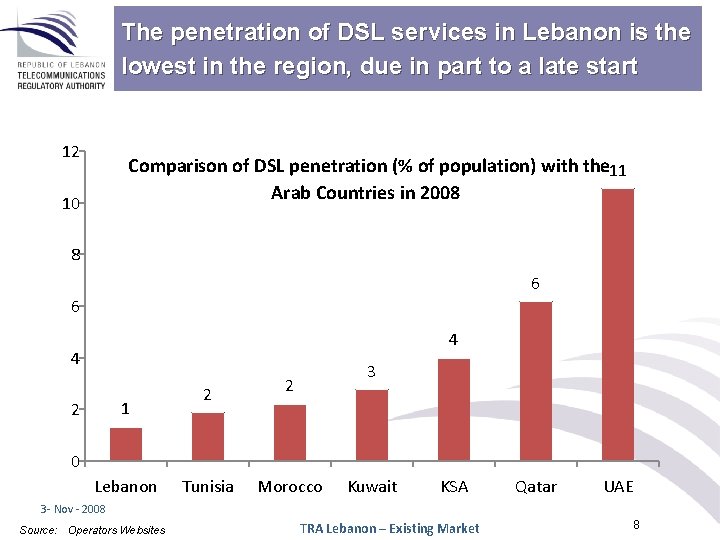
The penetration of DSL services in Lebanon is the lowest in the region, due in part to a late start 12 Comparison of DSL penetration (% of population) with the 11 Arab Countries in 2008 10 8 6 6 4 4 1 2 3 2 2 Tunisia Morocco 0 Lebanon Kuwait KSA Qatar UAE 3 - Nov - 2008 Source: Operators Websites TRA Lebanon – Existing Market 8
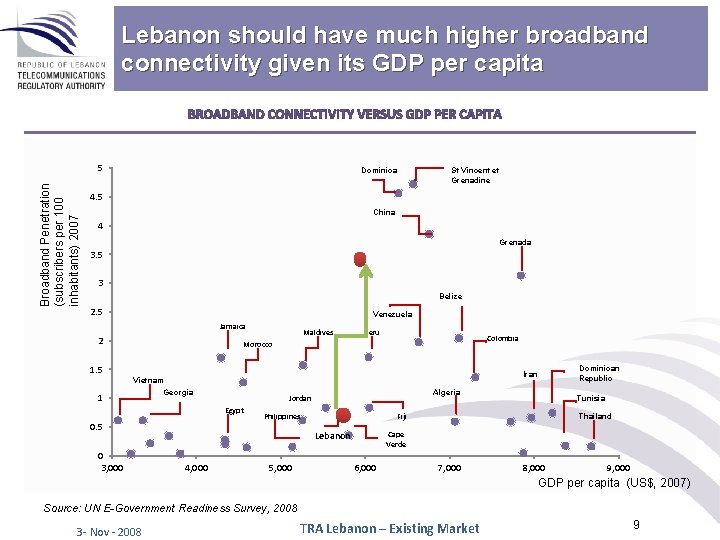
Lebanon should have much higher broadband connectivity given its GDP per capita BROADBAND CONNECTIVITY VERSUS GDP PER CAPITA Broadband Penetration (subscribers per 100 inhabitants) 2007 5 Dominica St Vincent et Grenadine 4. 5 China 4 Grenada 3. 5 3 Belize 2. 5 Venezuela Jamaica 2 Maldives Peru Colombia Morocco 1. 5 1 Iran Vietnam Georgia Egypt 0. 5 0 3, 000 Algeria Jordan Philippines 4, 000 5, 000 Tunisia Fiji Lebanon Dominican Republic Thailand Cape Verde 6, 000 7, 000 8, 000 9, 000 GDP per capita (US$, 2007) Source: UN E-Government Readiness Survey, 2008 3 - Nov - 2008 TRA Lebanon – Existing Market 9
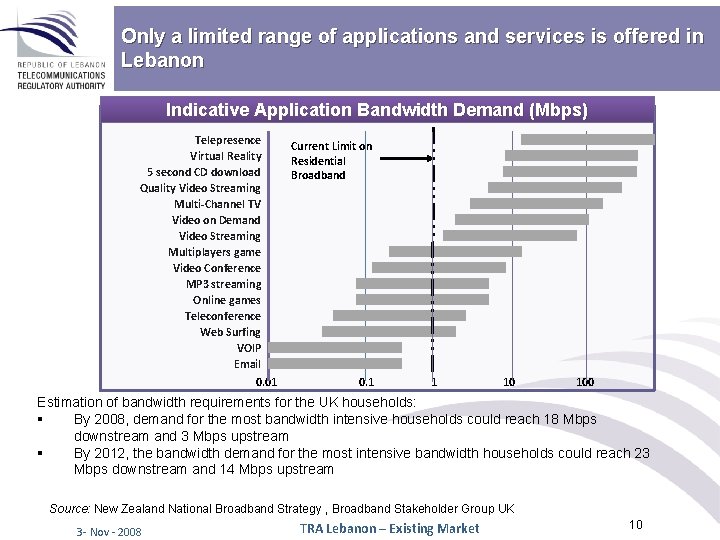
Only a limited range of applications and services is offered in Lebanon Indicative Application Bandwidth Demand (Mbps) Telepresence Virtual Reality 5 second CD download Quality Video Streaming Multi-Channel TV Video on Demand Video Streaming Multiplayers game Video Conference MP 3 streaming Online games Teleconference Web Surfing VOIP Email 0. 01 Current Limit on Residential Broadband 0. 1 1 10 100 Estimation of bandwidth requirements for the UK households: § By 2008, demand for the most bandwidth intensive households could reach 18 Mbps downstream and 3 Mbps upstream § By 2012, the bandwidth demand for the most intensive bandwidth households could reach 23 Mbps downstream and 14 Mbps upstream Source: New Zealand National Broadband Strategy , Broadband Stakeholder Group UK 3 - Nov - 2008 TRA Lebanon – Existing Market 10
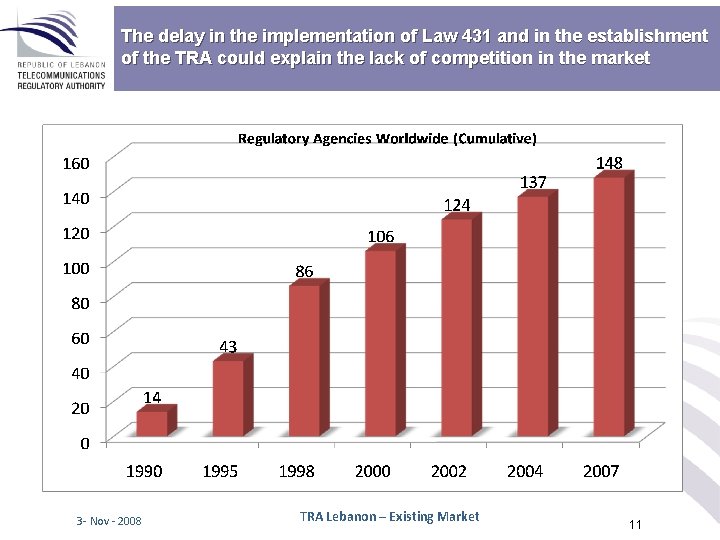
The delay in the implementation of Law 431 and in the establishment of the TRA could explain the lack of competition in the market 3 - Nov - 2008 TRA Lebanon – Existing Market 11
Outline I. The Telecom Market Today – The Urgent Need for Re-from II. Lebanon’s Telecom Reform III. TRA Vision, Roadmap, and Progress IV. Current Broadband Market V. Broadband Spectrum Re-farming VI. Next Steps and the Way Forward 3 - Nov - 2008 TRA Lebanon 12
The Go. L, recognizing the need for reform, has committed to open the telecom sector to competition and has recognized it as an important lever for economic development International Conference for Support to Lebanon” Paris III Conference q “… there is a need to reduce the cost of production resulting mainly from unreliable supply of electricity, the high cost of telecommunication …” q “The Government of Lebanon will implement reforms in order to improve competitiveness and reduce the cost of doing business in Lebanon…” q “The government will seek a greater private sector role in sectors such as telecommunications…” q (§ 56) ﻭﻟﺒﻨﺎﻥ. ﺇﻥ ﻗﻄﺎﻉ ﺍﻻﺗﺼﺎﻻﺕ ﻫﻮ ﻣﺤﻙ ﺃﺴﺎﺳﻲ ﻟﻼﻗﺘﺼﺎﺩ ﺍﻟﻮﻃﻨﻲ ﻭﻫﻮ ﻳﺴﻬﻢ ﻓﻲ ﺗﻌﺰﻳﺰ ﺍﻹﻧﻤﺎﺀ ﺍﻟﻤﺘﻮﺍﺯﻥ ﻳﻌﻤﻞ ﻋﻠﻰ ﺗﻘﺪﻳﻢ ﺭﺅﻴﺔ ﻟﻬﺬﺍ ﺍﻟﻘﻄﺎﻉ ﺗﻬﺪﻑ ﺇﻟﻰ ﺑﻨﺎﺀ ﻣﺠﺘﻤﻊ ﺍﻟﻤﻌﻠﻮﻣﺎﺗﻴﺔ ﻣﻦ ﺃﺠﻞ ﻣﻮﺍﻛﺒﺔ ﺛﻮﺭﺓ ﺍﻻﺗﺼﺎﻻﺕ ﺍﻟﻌﺎﻟﻤﻴﺔ ﻭﺍﻟﺤﻜﻮﻣﺔ ﺍﻟﻠﺒﻨﺎﻧﻴﺔ ﺗﻠﺘﺰﻡ ﻓﻲ ﻫﺬﺍ ﺍﻟﺴﻴﺎﻕ ﺑﺘﺤﺮﻳﺮ ﻗﻄﺎﻉ ﺍﻻﺗﺼﺎﻻﺕ ﻭﻓﺘﺢ ﺍﻟﺴﻮﻕ ﻻﺳﺘﺜﻤﺎﺭﺍﺕ ، ﻭﺭﻳﺎﺩﺗﻬﺎ ﻓﻲ ﺍﻟﻤﻨﻄﻘﺔ ������� 2008 �������� . ﺍﻟﻘﻄﺎﻉ ﺍﻟﺨﺎﺹ ﻭﺍﻟﻤﻨﺎﻓﺴﺔ ﻭﺣﻤﺎﻳﺔ ﺣﻘﻮﻕ ﺍﻟﻤﺴﺘﻬﻠﻚ Telecommunica tions Law 431 / 2002 q The TRA is charged with promoting competition in telecommunications (Telecommunications Law, Art. 5. 1(C)). q The Law provided for the liberalization of the telecommunications market by privatizing state-owned telecommunications entities and opening the market to private sector investments and competition. The Go. L Governmental Declarations in 2005 and 2008 commit the Council of Minister (Co. M) to the liberalization of telecommunications 3 - Nov - 2008 TRA Lebanon – Liberalization Benefits 13
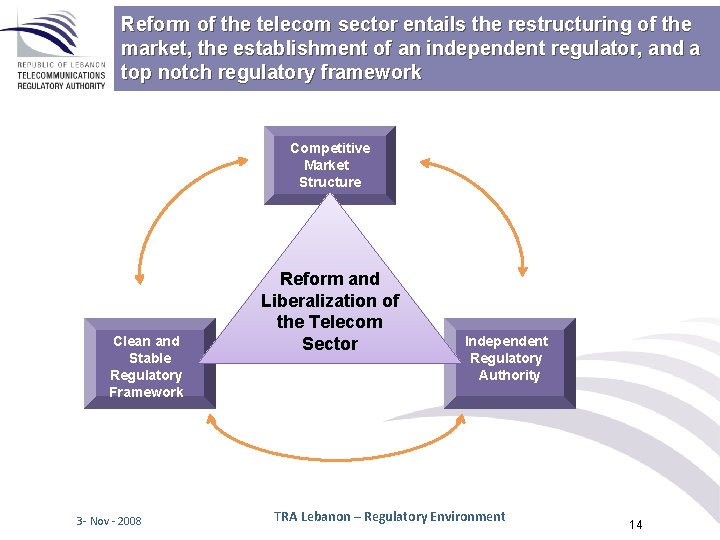
Reform of the telecom sector entails the restructuring of the market, the establishment of an independent regulator, and a top notch regulatory framework Competitive Market Structure Clean and Stable Regulatory Framework 3 - Nov - 2008 Reform and Liberalization of the Telecom Sector Independent Regulatory Authority TRA Lebanon – Regulatory Environment 14
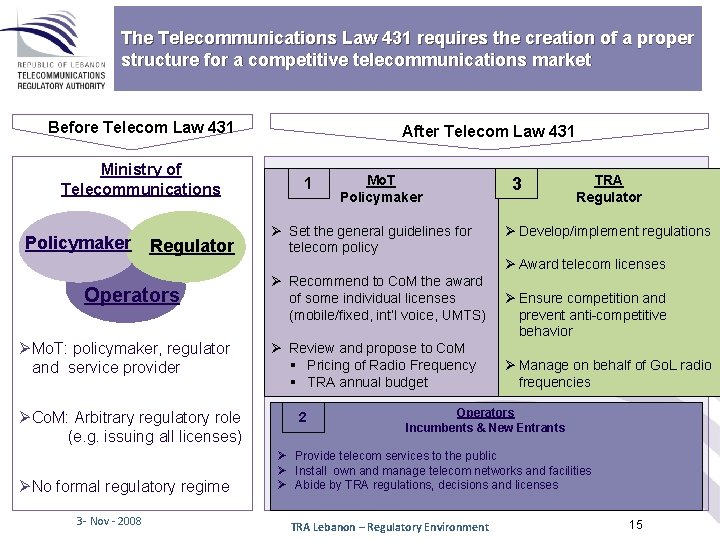
The Telecommunications Law 431 requires the creation of a proper structure for a competitive telecommunications market Before Telecom Law 431 Ministry of Telecommunications Policymaker Regulator Operators After Telecom Law 431 1 Mo. T Policymaker Ø Set the general guidelines for telecom policy 3 Ø Develop/implement regulations Ø Award telecom licenses Ø Recommend to Co. M the award of some individual licenses (mobile/fixed, int’l voice, UMTS) Ø Ensure competition and prevent anti-competitive behavior ØMo. T: policymaker, regulator and service provider Ø Review and propose to Co. M § Pricing of Radio Frequency § TRA annual budget ØCo. M: Arbitrary regulatory role (e. g. issuing all licenses) Operators 2 Incumbents Ø Approve TRA budget & other & New Entrants ØNo formal regulatory regime 3 - Nov - 2008 TRA Regulator Ø Manage on behalf of Go. L radio frequencies TRA documents as per Law 431 Ø Provide telecom services to the public Ø Install own and manage telecom networks and facilities Ø Abide by TRA regulations, decisions and licenses TRA Lebanon – Regulatory Environment 15
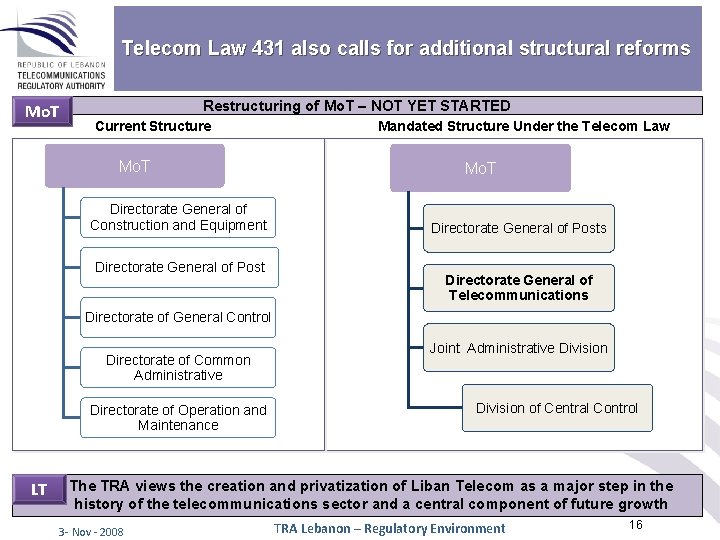
Telecom Law 431 also calls for additional structural reforms Mo. T Restructuring of Mo. T – NOT YET STARTED Current Structure Mo. T Directorate General of Construction and Equipment Directorate General of Post Mandated Structure Under the Telecom Law Mo. T Directorate General of Posts Directorate General of Telecommunications Directorate of General Control Directorate of Common Administrative Directorate of Operation and Maintenance LT Joint Administrative Division of Central Control The TRA views the creation and privatization of Liban Telecom as a major step in the history of the telecommunications sector and a central component of future growth 3 - Nov - 2008 TRA Lebanon – Regulatory Environment 16
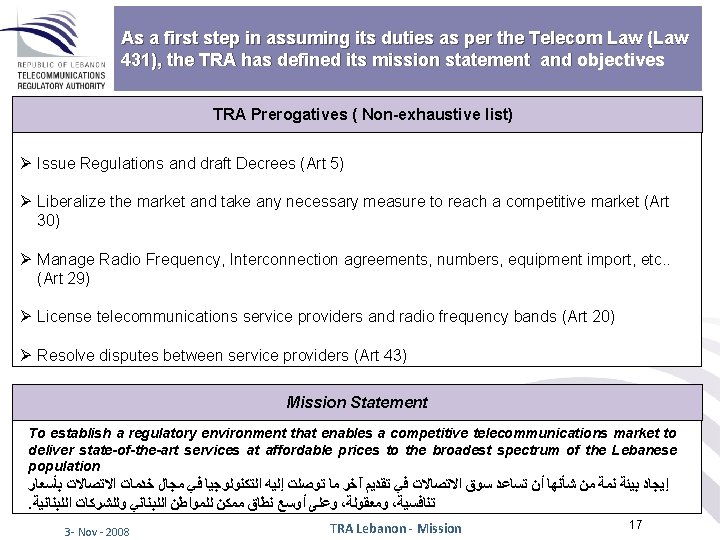
As a first step in assuming its duties as per the Telecom Law (Law 431), the TRA has defined its mission statement and objectives TRA Prerogatives ( Non-exhaustive list) Ø Issue Regulations and draft Decrees (Art 5) Ø Liberalize the market and take any necessary measure to reach a competitive market (Art 30) Ø Manage Radio Frequency, Interconnection agreements, numbers, equipment import, etc. . (Art 29) Ø License telecommunications service providers and radio frequency bands (Art 20) Ø Resolve disputes between service providers (Art 43) Mission Statement To establish a regulatory environment that enables a competitive telecommunications market to deliver state-of-the-art services at affordable prices to the broadest spectrum of the Lebanese population ﺇﻳﺠﺎﺩ ﺑﻴﺌﺔ ﻧﻣﺔ ﻣﻦ ﺷﺄﻨﻬﺎ ﺃﻦ ﺗﺴﺎﻋﺪ ﺳﻮﻕ ﺍﻻﺗﺼﺎﻻﺕ ﻓﻲ ﺗﻘﺪﻳﻢ آﺨﺮ ﻣﺎ ﺗﻮﺻﻠﺖ ﺇﻟﻴﻪ ﺍﻟﺘﻜﻨﻮﻟﻮﺟﻴﺎ ﻓﻲ ﻣﺠﺎﻝ ﺧﺪﻣﺎﺕ ﺍﻻﺗﺼﺎﻻﺕ ﺑﺄﺴﻌﺎﺭ . ﻭﻋﻠﻰ ﺃﻮﺳﻊ ﻧﻄﺎﻕ ﻣﻤﻜﻦ ﻟﻠﻤﻮﺍﻃﻦ ﺍﻟﻠﺒﻨﺎﻧﻲ ﻭﻟﻠﺸﺮﻛﺎﺕ ﺍﻟﻠﺒﻨﺎﻧﻴﺔ ، ﻭﻣﻌﻘﻮﻟﺔ ، ﺗﻨﺎﻓﺴﻴﺔ 3 - Nov - 2008 TRA Lebanon - Mission 17
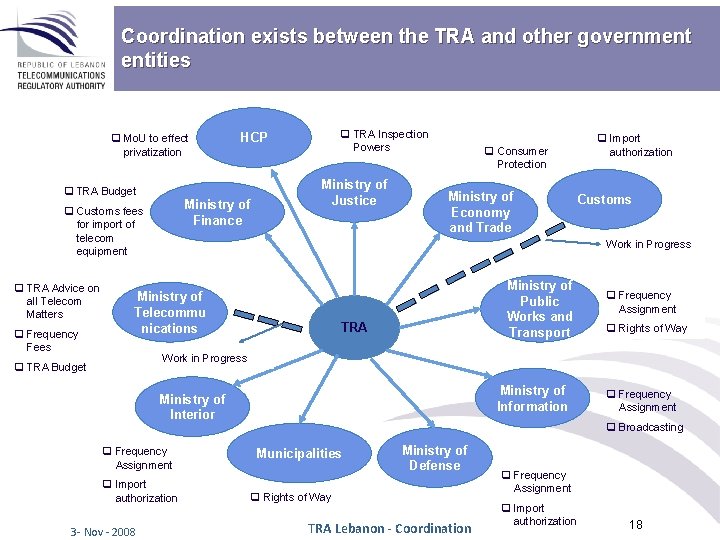
Coordination exists between the TRA and other government entities q Mo. U to effect privatization q TRA Budget Ministry of Finance q Customs fees for import of telecom equipment q TRA Advice on all Telecom Matters q Frequency Fees q TRA Inspection Powers HCP Ministry of Justice q Import authorization q Consumer Protection Ministry of Economy and Trade Customs Work in Progress Ministry of Telecommu nications Ministry of Public Works and Transport TRA q Frequency Assignment q Rights of Way Work in Progress q TRA Budget Ministry of Information Ministry of Interior q Frequency Assignment q Import authorization 3 - Nov - 2008 q Frequency Assignment q Broadcasting Municipalities Ministry of Defense q Rights of Way TRA Lebanon - Coordination q Frequency Assignment q Import 18 authorization 18
Outline I. The Telecom Market Today – The Urgent Need for Re-from II. Lebanon’s Telecom Reform III. TRA Vision, Roadmap, and Progress IV. Current Broadband Market V. Broadband Spectrum Re-farming VI. Next Steps and the Way Forward 3 - Nov - 2008 TRA Lebanon 19
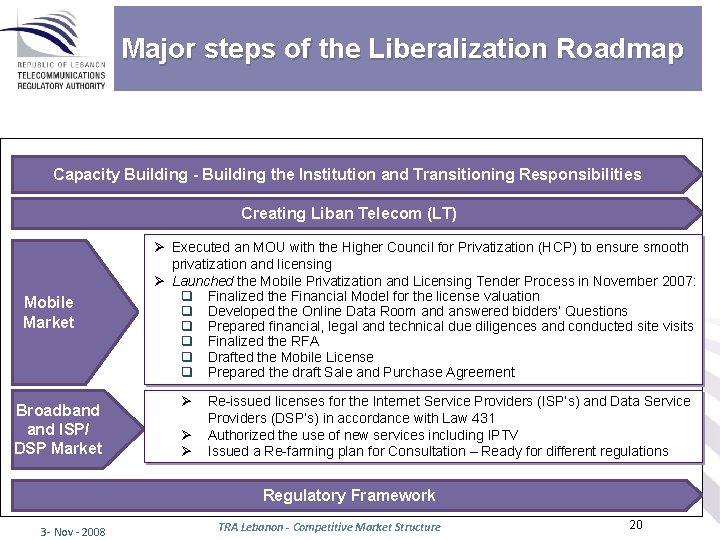
Major steps of the Liberalization Roadmap Capacity Building - Building the Institution and Transitioning Responsibilities Creating Liban Telecom (LT) Mobile Market Broadband ISP/ DSP Market Ø Executed an MOU with the Higher Council for Privatization (HCP) to ensure smooth privatization and licensing Ø Launched the Mobile Privatization and Licensing Tender Process in November 2007: q Finalized the Financial Model for the license valuation q Developed the Online Data Room and answered bidders’ Questions q Prepared financial, legal and technical due diligences and conducted site visits q Finalized the RFA q Drafted the Mobile License q Prepared the draft Sale and Purchase Agreement Ø Ø Ø Re-issued licenses for the Internet Service Providers (ISP’s) and Data Service Providers (DSP’s) in accordance with Law 431 Authorized the use of new services including IPTV Issued a Re-farming plan for Consultation – Ready for different regulations Regulatory Framework 3 - Nov - 2008 TRA Lebanon - Competitive Market Structure 20
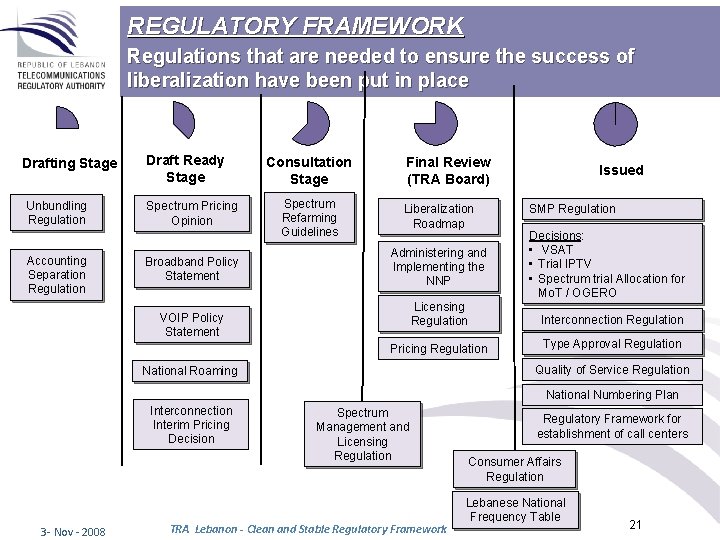
REGULATORY FRAMEWORK Regulations that are needed to ensure the success of liberalization have been put in place Drafting Stage Unbundling Regulation Accounting Separation Regulation Draft Ready Stage Spectrum Pricing Opinion Broadband Policy Statement Consultation Stage Spectrum Refarming Guidelines Final Review (TRA Board) Liberalization Roadmap Administering and Implementing the NNP Issued SMP Regulation Decisions: • VSAT • Trial IPTV • Spectrum trial Allocation for Mo. T / OGERO Licensing Regulation Interconnection Regulation Pricing Regulation Type Approval Regulation VOIP Policy Statement Quality of Service Regulation National Roaming National Numbering Plan Interconnection Interim Pricing Decision 3 - Nov - 2008 Spectrum Management and Licensing Regulation TRA Lebanon - Clean and Stable Regulatory Framework for establishment of call centers Consumer Affairs Regulation Lebanese National Frequency Table 21
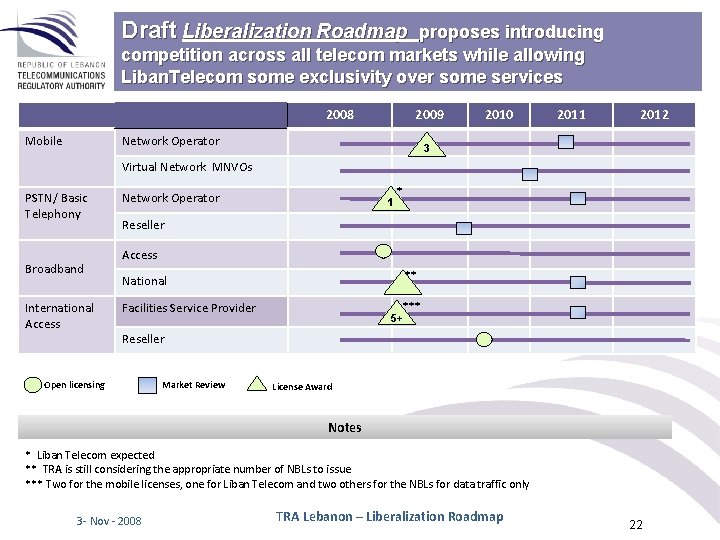
Draft Liberalization Roadmap proposes introducing competition across all telecom markets while allowing Liban. Telecom some exclusivity over some services 2008 Mobile 2009 Network Operator 2010 2011 2012 3 Virtual Network MNVOs PSTN/ Basic Telephony Broadband International Access Network Operator 1 * Reseller Access ** National Facilities Service Provider 5+ Reseller Open licensing Market Review *** License Award Notes * Liban Telecom expected ** TRA is still considering the appropriate number of NBLs to issue *** Two for the mobile licenses, one for Liban Telecom and two others for the NBLs for data traffic only 3 - Nov - 2008 TRA Lebanon – Liberalization Roadmap 22
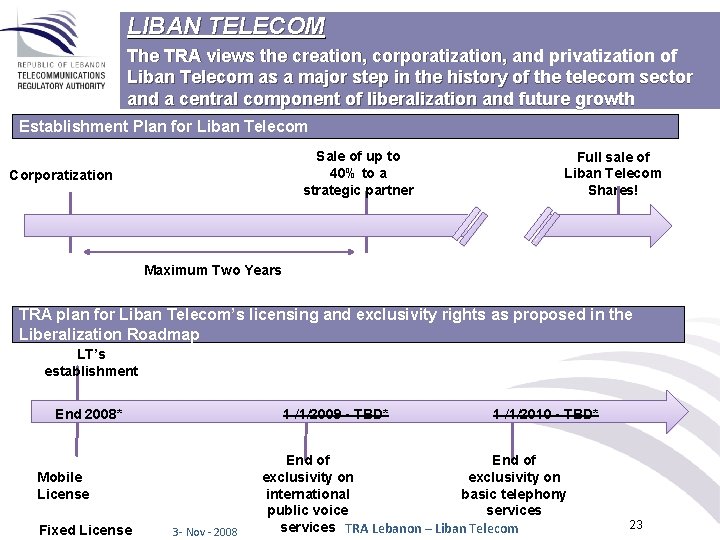
LIBAN TELECOM The TRA views the creation, corporatization, and privatization of Liban Telecom as a major step in the history of the telecom sector and a central component of liberalization and future growth Establishment Plan for Liban Telecom Sale of up to 40% to a strategic partner Corporatization Full sale of Liban Telecom Shares! Undefi ned time Maximum Two Years TRA plan for Liban Telecom’s licensing and exclusivity rights as proposed in the Liberalization Roadmap LT’s establishment End 2008* 1 /1/2009 - TBD* Mobile License Fixed License 3 - Nov - 2008 1 /1/2010 - TBD* End of exclusivity on international basic telephony public voice services TRA Lebanon – Liban Telecom 23
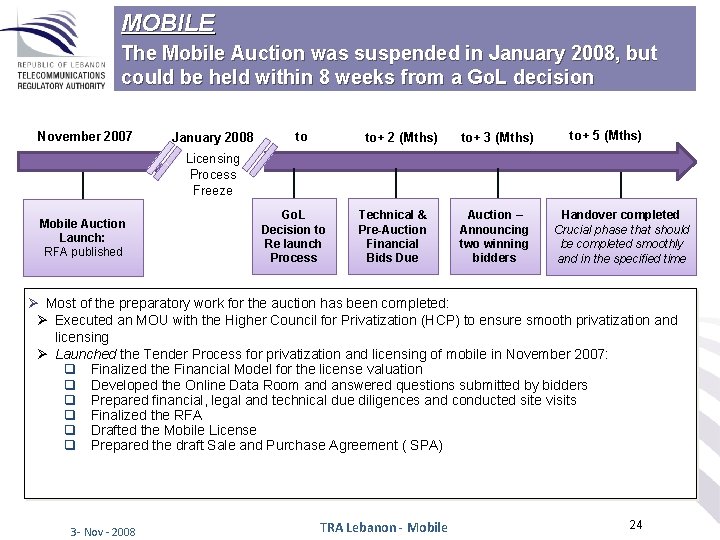
MOBILE The Mobile Auction was suspended in January 2008, but could be held within 8 weeks from a Go. L decision November 2007 January 2008 to to+ 2 (Mths) to+ 3 (Mths) to+ 5 (Mths) Licensing Process Freeze Mobile Auction Launch: RFA published Go. L Decision to Re launch Process Technical & Pre-Auction Financial Bids Due Auction – Announcing two winning bidders Handover completed Crucial phase that should be completed smoothly and in the specified time Ø Most of the preparatory work for the auction has been completed: Ø Executed an MOU with the Higher Council for Privatization (HCP) to ensure smooth privatization and licensing Ø Launched the Tender Process for privatization and licensing of mobile in November 2007: q Finalized the Financial Model for the license valuation q Developed the Online Data Room and answered questions submitted by bidders q Prepared financial, legal and technical due diligences and conducted site visits q Finalized the RFA q Drafted the Mobile License q Prepared the draft Sale and Purchase Agreement ( SPA) 3 - Nov - 2008 TRA Lebanon - Mobile 24
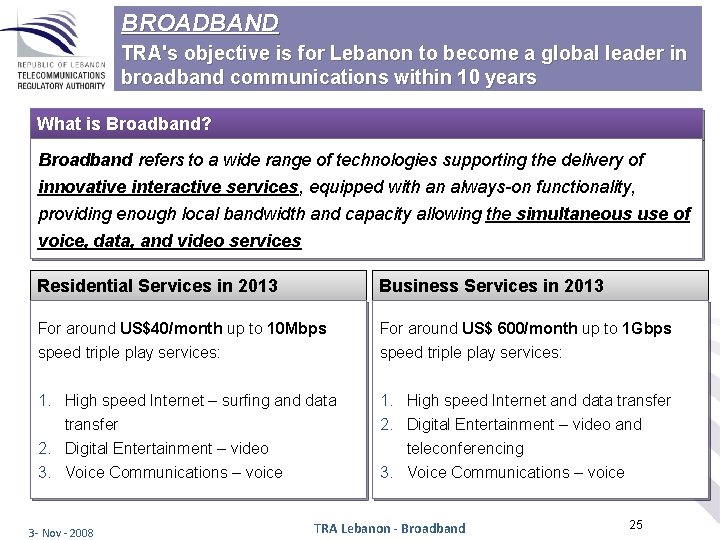
BROADBAND TRA's objective is for Lebanon to become a global leader in broadband communications within 10 years What is Broadband? Broadband refers to a wide range of technologies supporting the delivery of innovative interactive services, equipped with an always-on functionality, providing enough local bandwidth and capacity allowing the simultaneous use of voice, data, and video services Residential Services in 2013 Business Services in 2013 For around US$40/month up to 10 Mbps speed triple play services: For around US$ 600/month up to 1 Gbps speed triple play services: 1. High speed Internet – surfing and data transfer 2. Digital Entertainment – video 3. Voice Communications – voice 1. High speed Internet and data transfer 2. Digital Entertainment – video and teleconferencing 3. Voice Communications – voice 3 - Nov - 2008 TRA Lebanon - Broadband 25
Outline I. The Telecom Market Today – The Urgent Need for Re-from II. Lebanon’s Telecom Reform III. TRA Vision, Roadmap, and Progress IV. Current Broadband Market V. Broadband Spectrum Re-farming VI. Next Steps and the Way Forward 3 - Nov - 2008 TRA Lebanon 26
Broadband Statistics - Middle-East BB penetration in Lebanon is very low – room to expand Source: www. internetworldstats. com/middle. htm, ITU data Sept/2007 Notes: Some figures are probably dated since for example UAE is known to have reported double the penetration by mid-2008 3 - Nov - 2008 Re-farming for Broadband Lebanon 27
Broadband Statistics – Worldwide Lebanon is still 4 times lower than the Average q Existing broadband penetration in Lebanon is low by international benchmark 3 - Nov - 2008 Re-farming for Broadband Lebanon 28
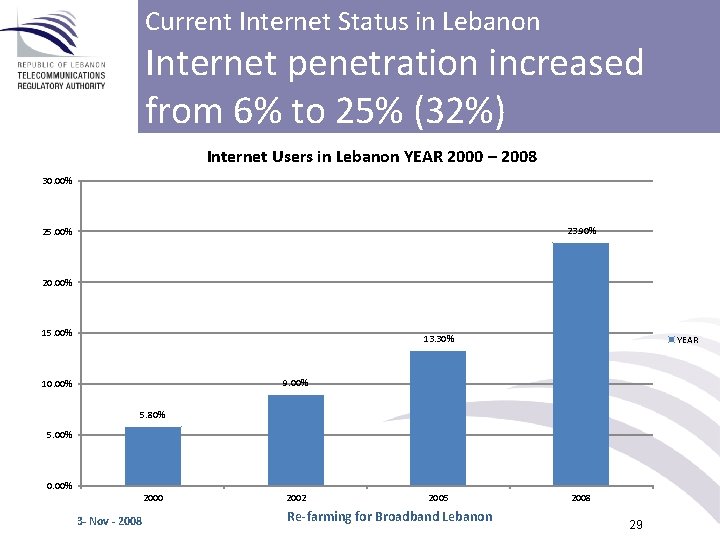
Current Internet Status in Lebanon Internet penetration increased from 6% to 25% (32%) Internet Users in Lebanon YEAR 2000 – 2008 30. 00% 23. 90% 25. 00% 20. 00% 15. 00% 13. 30% YEAR 9. 00% 10. 00% 5. 80% 5. 00% 0. 00% 2000 3 - Nov - 2008 2002 2005 Re-farming for Broadband Lebanon 2008 29
Broadband Background - Lebanon q For 10 years the Mo. T partnered with the private sector to provide data connectivity and internet services q Spectrum was being authorized on an annual basis – no clear licensing policy q Limited ADSL services despite the fast growth with close to 60 K-70 K subscribers served by the incumbent operator/private sector. The incumbent (Ogero) is the only fixed operator with ~70% ADSL market share on the local loop. Unbundling and Bit -Stream models provided. Five private DSPs contributing to ~30% of market share q Wireless BB is provided by 4 private DSPs with end-to-end wireless access and backhauling using microwave – no fiber q Coverage ranging from national in the FWA corporate market to limited urban coverage for personal broadband internet market with “ 3” players offering portable nomadic broadband in a multiplayer ISP-DSP scenario q “ 17” ISP’s, “ 5” DSPs, and “ 1” fixed line operator, and “ 2” mobile (GPRS & limited EDGE) constitute the regulated data & internet market players q Non-regulated market players (incl. WISPs) & illegal local cable operators serving residential users using ISM 2. 4 GHz & some licensed spectrum bands q Mobile broadband (3 G) is not yet available 3 - Nov - 2008 Re-farming for Broadband Lebanon 30
Broadband Wireless Spectrum – Current Status q Spectrum used by DSPs include (same DSPs have large portions of the spectrum): q 1. 9 GHz: TDD UMTS band allocated to provide personal broadband using proprietary technology (I-burst) q 2. 2 GHz (legacy TDMA PMP systems since 1999 but being migrated since 2003) q 2. 5 - 2. 69 GHz: IMT Prime spectrum; allocated by Mo. T for FWA (to evacuate) q 3. 4 - 3. 6 GHz: Prime Spectrum for FWA and BWA including WIMAX q 3. 6 - 3. 7 GHz: Used for some FWA without being authorized q 5 GHz used heavily by unlicensed WISP’s and some DSPs q 24 -26 GHz FWA high capacity PMP backhauling q Limited Residential Broadband Wireless coverage in major cities & GBA q Lack of initiatives to ensure rural access to broadband wireless q A number of unlicensed wireless ISPs serving residential & SOHO internet markets q Occasional interference on some bands from cross boarders and operators and unlicensed WISPs 3 - Nov - 2008 Re-farming for Broadband Lebanon 31
Outline I. The Telecom Market Today – The Urgent Need for Re-from II. Lebanon’s Telecom Reform III. TRA Vision, Roadmap, and Progress IV. Current Broadband Market V. Broadband Spectrum Re-farming VI. Next Steps and the Way Forward 3 - Nov - 2008 TRA Lebanon 32
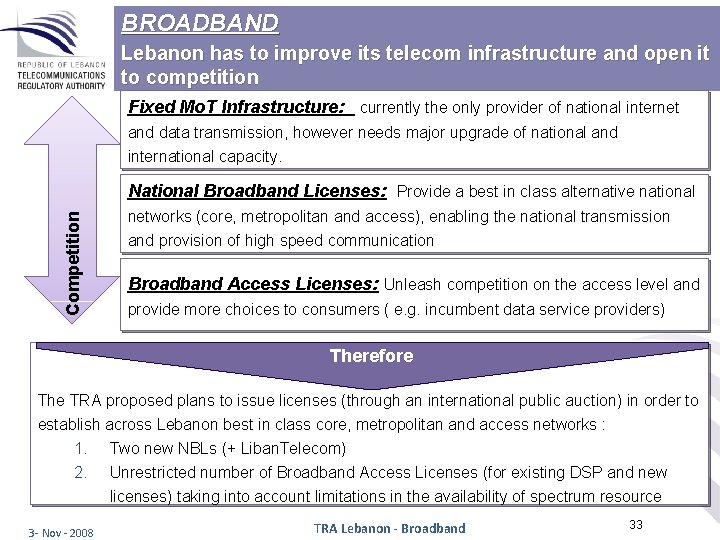
BROADBAND Lebanon has to improve its telecom infrastructure and open it to competition Fixed Mo. T Infrastructure: currently the only provider of national internet and data transmission, however needs major upgrade of national and international capacity. Competition National Broadband Licenses: Provide a best in class alternative national networks (core, metropolitan and access), enabling the national transmission and provision of high speed communication Broadband Access Licenses: Unleash competition on the access level and provide more choices to consumers ( e. g. incumbent data service providers) Therefore The TRA proposed plans to issue licenses (through an international public auction) in order to establish across Lebanon best in class core, metropolitan and access networks : 1. Two new NBLs (+ Liban. Telecom) 2. Unrestricted number of Broadband Access Licenses (for existing DSP and new licenses) taking into account limitations in the availability of spectrum resource 3 - Nov - 2008 TRA Lebanon - Broadband 33
BROADBAND Spectrum The TRA is paving the way to meet a growing spectrum demand Spectrum Planning and Refarming Planning Objectives Ø Efficient spectrum distribution - Optimize the use of spectrum Ø Introduce new national and regional operators to the market Ø Open gates for new technologies and services Ø Reserve spectrum for future needs taking into consideration technology evolution Ø Define frequency bands and bandwidth that can be offered for TV distributors Ø Maintain a smooth migration plan from analog to digital TV transmission Ø Secure minimum committed spectrum to the existing operators Spectrum Re-farming Ø Re-farming plan for the bands 1. 9, 2. 3, 2. 5, 3. 5, 5 and 26 GHz is studied with primary focus on the 2. 5 GHz band that has been designated as extension band to IMT and on the 3. 5 GHz band which may considered in future as an extension to IMT Ø Auction model for broadband networks is being studied by the TRA in order to realize goals defined in the liberalization roadmap by introducing new operators (2 NBLs, 5 -6 BAL) Ø Re-farming for the 12 GHz and 26 GHz bands will be studied as a solution to the cable TV distributors 3 - Nov - 2008 TRA Lebanon - Broadband 34
Questions to Address – Planning What are the policies? q Policies q Government q Telecommunications q TRA q Broadband, Spectrum Policy, Re-farming, Infrastructure and Rights of Way (Ro. W) q Broadband Policy and Licenses q Objectives q Fiber vs. Wireless q Mobile vs. Fixed q Types of Licenses q Types of Services q Number of Licenses/Packages (short and long term) q National vs. Regional Licenses/Packages q Obligations Coverage/ Deployment Re-farming for Broadband Lebanon 35
Questions to Address – Planning How to treat existing operators? q Treatment of existing operators q Basis for decisions (legal, other) q Licenses (type, renewals, and transition) q Bands and spectrum (Smin: number of bands, size, price, issues) q Continuity of services - Ensuring continuity of services/minimum interruption q Transition and Migration - Schedule, dependencies, consumer services, cost, q Interim period - duration per band, per operator, and per service q Pricing (revenue sharing, auction derivatives, AIP, averages, benchmarking) q Technology neutrality vs. ensuring coexistence conditions q Size of the spectrum per operator (DSPs, NBL, etc. ) q Auction(s) - sequencing, design, number, timing, dependencies (LT, Mobile, etc. ) 3 - Nov - 2008 Re-farming for Broadband Lebanon 36
Spectrum Milestones The TRA had to pave the way q A Spectrum Policy harmonizing bands & national interest according to best practices/ITU • Spectrum Policy. Guidelines, Handbook • National Frequency Allocation Table (LNFT-Final version issued) • Spectrum pricing in the different bands (regulations, auction-related, AIP, . . ) q Re-farming for bands of interest ( BWA plan under consultation) • Re-farming bands • Assigned/allocated spectrum per package (minimum, maximum, short and long term) • Reserved spectrum per band q Migration plan from Analog to Digital TV broadcasting (consultation soon) q Clearing as much spectrum sub 6 GHz to be offered for new services or reserved q Develop and implement spectrum licensing regulations - Universal, Technology, infrastructure, service, duration, obligation, treatment of licensing requests (new, renewals) q Establish Enforcement & Inspection Regime - regulations, monitoring, inspection, enforcement, illegal operators & cable providers, etc. q Develop position for Lebanon in ITU activities and working parties q Build capacity and resources 3 - Nov - 2008 Re-farming for Broadband Lebanon 37
Spectrum Management Objectives q Enable liberalization of, and competition for, telecommunications (including radio communications) services and equipment q Boost economic growth, create employment, promote general welfare q Ensure transparency in spectrum award process ensuring best value q Reallocate spectrum to meet new regulations while minimizing impact on services and consumers q Support national security and defense needs q Enable the realization of public policy objectives on enviornmental safety (including emergency services), cultural (including broadcasting), social and economic development q Harmonize spectrum use with international developments & ITU-R q Stimulate technological innovation and competitiveness 3 - Nov - 2008 Re-farming for Broadband Lebanon 38
TRA Spectrum Approach to Broadband Lebanon q. Issue new licenses for long periods and reserve spectrum for future use q Establish a Re-Farming Plan for important bands like 2. 5 GHz and 3. 5 GHz in order to be auctioned for new technologies and services q Technology neutrality principle where possible while ensuring: q Interference management and compliance to technical conditions is met (challenge ) q Equivalent services can be delivered using different technologies. Let the market decide which services to deliver to consumers q Use spectrum ceilings to ensure a minimum of 3 players in the market q Make a distinction in a short term cap (auction period) and long term cap (after M&A) q Give operators sufficient time for transition into the new situation q Reserve sufficient spectrum for future use (LTE) q Keep the auction design and the auction process as simple as possible q Minimize the complexity of the assignment process as much as possible. 3 - Nov - 2008 Re-farming for Broadband Lebanon 39
Proposed Broadband Licensing Framework Accelerating Broadband Lebanon q Substantial investments in broadband access and fiber optic backbones are required to accelerate broadband deployment q The Liberalization Roadmap outlines issuing licenses in 2009 with a view to establishing across Lebanon – in the cities/rural areas – access to high speed core, metropolitan & access networks q National Broadband Licenses - services barring Liban Telecom exclusivity q Up to 2 licenses to be issued with fixed (fiber) and wireless access capabilities q Build own infrastructure to offer BB services using any technology for a core network (linking nodes in the main cities), metropolitan networks (covering towns and cities), and access networks (i. e. , connecting metro and core networks to points of presence (POPs) q Include sufficient amount of ‘access’ spectrum, and int’l gateway rights q Roll-out coverage obligations to provide national coverage over most of the territories q Universal Service Obligation!! q Access obligation is modest due to competition/BALs but core obligation is more stringent q Broadband Access Licenses (National and Regional) q Build access infrastructure q Offer customers the same telecommunications services as the NBLs q Some would be with radio spectrum bands to deploy wireless access technology q This can trigger investments in infrastructure and actual deployment q Competition will help speed up deployment, improve service and reduce prices 3 - Nov - 2008 Re-farming for Broadband Lebanon 40
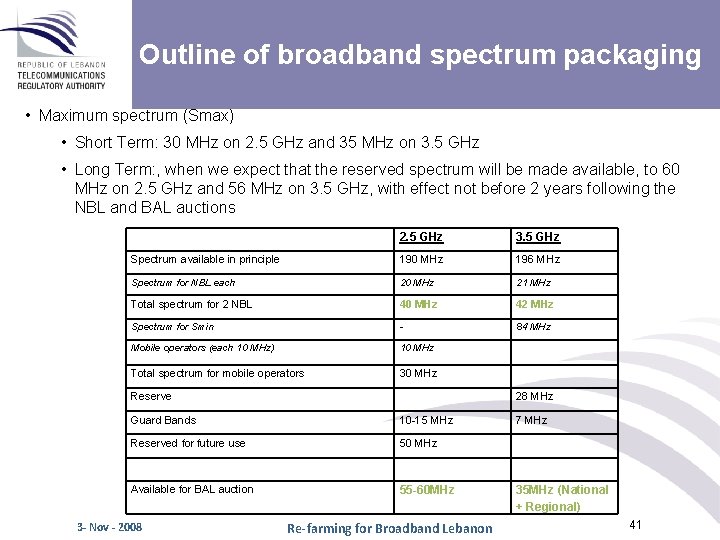
Outline of broadband spectrum packaging • Maximum spectrum (Smax) • Short Term: 30 MHz on 2. 5 GHz and 35 MHz on 3. 5 GHz • Long Term: , when we expect that the reserved spectrum will be made available, to 60 MHz on 2. 5 GHz and 56 MHz on 3. 5 GHz, with effect not before 2 years following the NBL and BAL auctions 2. 5 GHz 3. 5 GHz Spectrum available in principle 190 MHz 196 MHz Spectrum for NBL each 20 MHz 21 MHz Total spectrum for 2 NBL 40 MHz 42 MHz Spectrum for Smin - 84 MHz Mobile operators (each 10 MHz) 10 MHz Total spectrum for mobile operators 30 MHz Reserve 28 MHz Guard Bands 10 -15 MHz Reserved for future use 50 MHz Available for BAL auction 55 -60 MHz 3 - Nov - 2008 Re-farming for Broadband Lebanon 7 MHz 35 MHz (National + Regional) 41
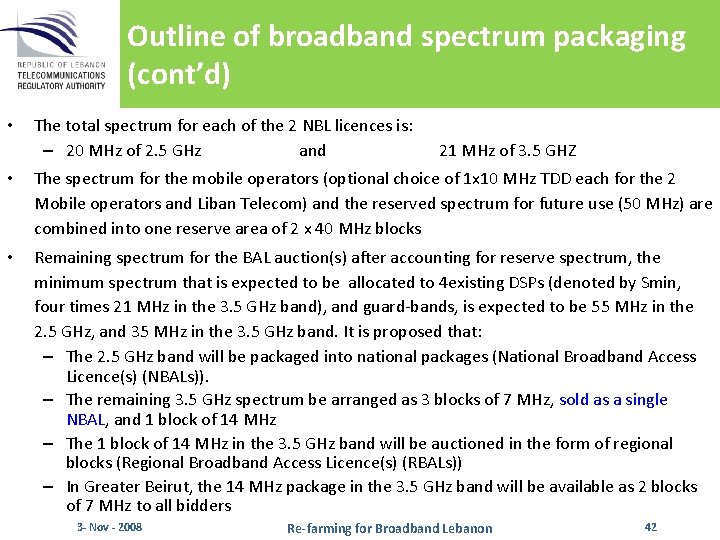
Outline of broadband spectrum packaging (cont’d) • The total spectrum for each of the 2 NBL licences is: – 20 MHz of 2. 5 GHz and 21 MHz of 3. 5 GHZ • The spectrum for the mobile operators (optional choice of 1 x 10 MHz TDD each for the 2 Mobile operators and Liban Telecom) and the reserved spectrum for future use (50 MHz) are combined into one reserve area of 2 x 40 MHz blocks • Remaining spectrum for the BAL auction(s) after accounting for reserve spectrum, the minimum spectrum that is expected to be allocated to 4 existing DSPs (denoted by Smin, four times 21 MHz in the 3. 5 GHz band), and guard-bands, is expected to be 55 MHz in the 2. 5 GHz, and 35 MHz in the 3. 5 GHz band. It is proposed that: – The 2. 5 GHz band will be packaged into national packages (National Broadband Access Licence(s) (NBALs)). – The remaining 3. 5 GHz spectrum be arranged as 3 blocks of 7 MHz, sold as a single NBAL, and 1 block of 14 MHz – The 1 block of 14 MHz in the 3. 5 GHz band will be auctioned in the form of regional blocks (Regional Broadband Access Licence(s) (RBALs)) – In Greater Beirut, the 14 MHz package in the 3. 5 GHz band will be available as 2 blocks of 7 MHz to all bidders 3 - Nov - 2008 Re-farming for Broadband Lebanon 42 42
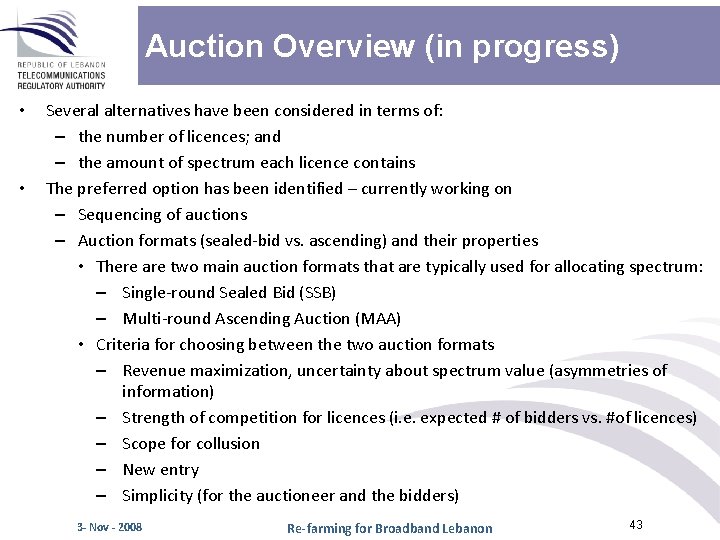
Auction Overview (in progress) • • Several alternatives have been considered in terms of: – the number of licences; and – the amount of spectrum each licence contains The preferred option has been identified – currently working on – Sequencing of auctions – Auction formats (sealed-bid vs. ascending) and their properties • There are two main auction formats that are typically used for allocating spectrum: – Single-round Sealed Bid (SSB) – Multi-round Ascending Auction (MAA) • Criteria for choosing between the two auction formats – Revenue maximization, uncertainty about spectrum value (asymmetries of information) – Strength of competition for licences (i. e. expected # of bidders vs. #of licences) – Scope for collusion – New entry – Simplicity (for the auctioneer and the bidders) 3 - Nov - 2008 Re-farming for Broadband Lebanon 43
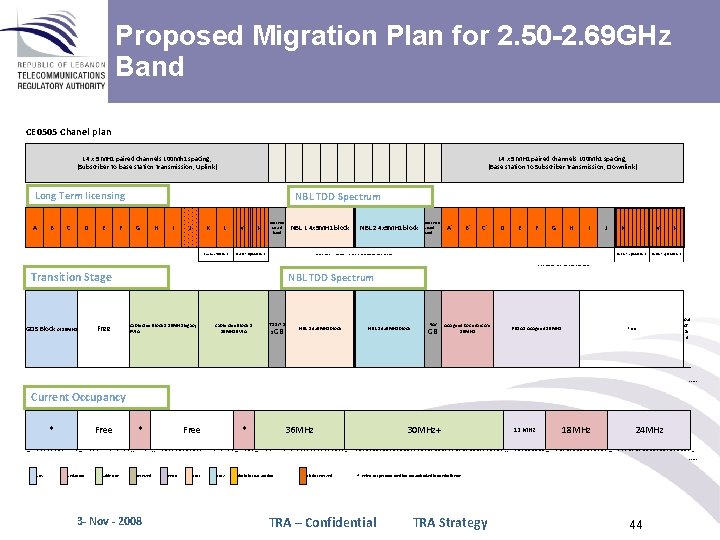
Proposed Migration Plan for 2. 50 -2. 69 GHz Band CE 0505 Chanel plan 14 x 5 MHz paired channels 100 Mhz spacing, (Subscriber to base station transmission, Uplink) 14 x 5 MHz paired channels 100 Mhz spacing, (Base station to Subscriber transmission, Downlink) 10 x 5 MHz (50 Mhz) initial TDD Spectrum 2 x 5 MHz Guard bands between TDD an FDD blocks. Long Term licensing NBL TDD Spectrum Long Term - Scenario A B C D E F G H I J K L M Reserved TDD block TDD/ FDD Guard band N NBL 1 4 x 5 MHz block Mobile 3 Optional block TDD/ FDD Guard band NBL 2 4 x 5 MHz block A' B' C' 10 x 5 MHz (50 Mhz) initial TDD Spectrum 2 x 5 MHz Guard bands between TDD an FDD blocks. D E F G H I J K L M Mobile 2 optional Block N Mobile 1 optional Block Initially planned as 70 x 2 FDD with TRA considering 45 x 2 reserved BEM, Synchronization between TDD operators Transition Stage NBL TDD Spectrum Interim Transitional Period Cable One Block 1 20 MHz legacy FWA Free GDS Block of 15 MHz TDD/FD Cable One Block 2 20 MHz BWA D NBL 1 4 x 5 MHz block GB NA/ NBL 2 4 x 5 MHz block Assigned to Cedarcom 15 MHz GB PESCO Assigned 25 MHz out of ba nd Free End of Band Current Occupancy Current Occupation * '2500 2503 2504 2505 2506 2507 2508 Free 2509 2510 2511 2512 2513 2514 2515 2518 2519 2520 2521 2522 2523 2524 2525 * 2526 2527 2528 2529 2530 2533 Free 2534 2535 2536 2539 2540 2541 2542 2543 2544 2545 2546 2547 2548 2549 2550 * 2552 2553 2554 2555 2556 2557 2558 2559 2560 2563 36 MHz 2564 2565 2566 2569 2570 2571 2572 2573 2574 2575 2576 2577 2578 2579 2580 2581 2582 2583 30 MHz+ 2584 2585 2586 2587 2588 2589 2590 2591 2592 2595 2596 2597 2598 2599 2600 2601 2602 2603 2604 2605 2606 2607 2608 2609 2610 2611 2612 2613 2614 2615 2616 2617 2618 2619 18 MHz 12 MHz 2620 2621 2622 2623 2624 26'25 26'26 2627 2628 2629 2630 2631 2632 2633 2634 2635 2636 2637 2638 2641 2642 2643 2644 2645 2646 2647 2648 2649 2650 2653 2654 2655 2656 2657 2658 2659 2660 2661 2662 2663 24 MHz 2664 2665 2666 2667 2668 2671 2672 2673 2674 2675 2676 2677 2678 2679 2680 2681 2682 2683 2684 2685 2686 2687 2688 2689 2690 2691 2692 End of Band GDS Cedarcom Cable One reserved 3 - Nov - 2008 Pesco NBL 1 NBL 2 Blocks for BAL Auction Blocks reserved * Refers to spectrum used but not authorized in Interim license TRA – Confidential TRA Strategy 44
Outline I. The Telecom Market Today – The Urgent Need for Re-from II. Lebanon’s Telecom Reform III. TRA Vision, Roadmap, and Progress IV. Current Broadband Market V. Broadband Spectrum Re-farming VI. Next Steps and the Way Forward 3 - Nov - 2008 TRA Lebanon 45
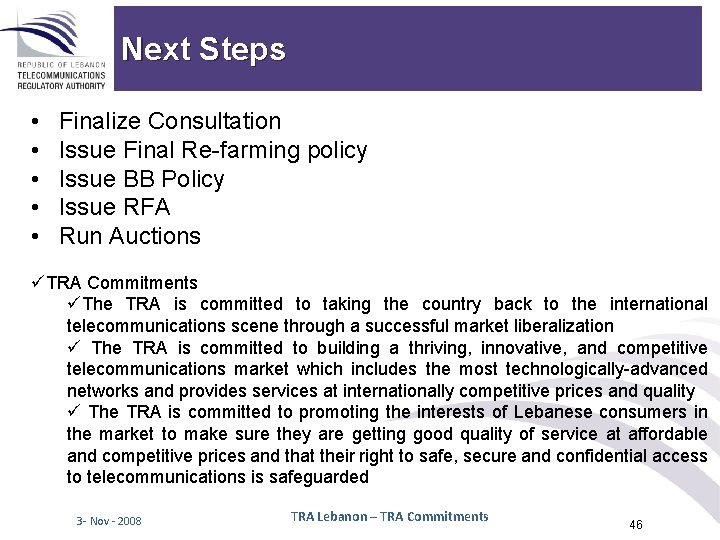
Next Steps • • • Finalize Consultation Issue Final Re-farming policy Issue BB Policy Issue RFA Run Auctions üTRA Commitments üThe TRA is committed to taking the country back to the international telecommunications scene through a successful market liberalization ü The TRA is committed to building a thriving, innovative, and competitive telecommunications market which includes the most technologically-advanced networks and provides services at internationally competitive prices and quality ü The TRA is committed to promoting the interests of Lebanese consumers in the market to make sure they are getting good quality of service at affordable and competitive prices and that their right to safe, secure and confidential access to telecommunications is safeguarded 3 - Nov - 2008 TRA Lebanon – TRA Commitments 46
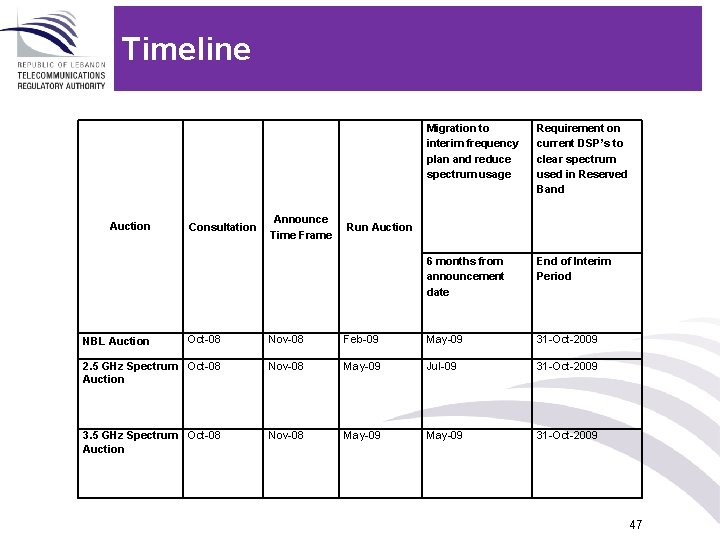
Timeline Auction Consultation Announce Time Frame Migration to interim frequency plan and reduce spectrum usage Requirement on current DSP’s to clear spectrum used in Reserved Band 6 months from announcement date End of Interim Period Run Auction Oct-08 Nov-08 Feb-09 May-09 31 -Oct-2009 2. 5 GHz Spectrum Oct-08 Auction Nov-08 May-09 Jul-09 31 -Oct-2009 3. 5 GHz Spectrum Oct-08 Auction Nov-08 May-09 31 -Oct-2009 NBL Auction 47
- Slides: 47