
TDS AWARENESS PROGRAMME Conference hall Visvesvarya Bhavan Patna
TDS AWARENESS PROGRAMME Conference hall, Visvesvarya Bhavan, Patna
TDS/TCS TAX DEDUCTION/COLLECTION AT SOURCE TDS WING, PATNA
INTRODUCTION • It is not another type of Tax rather a way of collection of Income tax. • A tax paid in advance. • Principle of “pay as you earn” • Onus of compliance is on the Payer, i. e, one who incurs the expenditure instead of actual taxpayer i. e. assessee, under Income Tax Act 1961.
PARTIES INVOLVED • DEDUCTOR / DDO / CDDO [TAN Holder] • DEDUCTEE [ PAN Holder] • DTO / STO / PAO [AIN Holder]
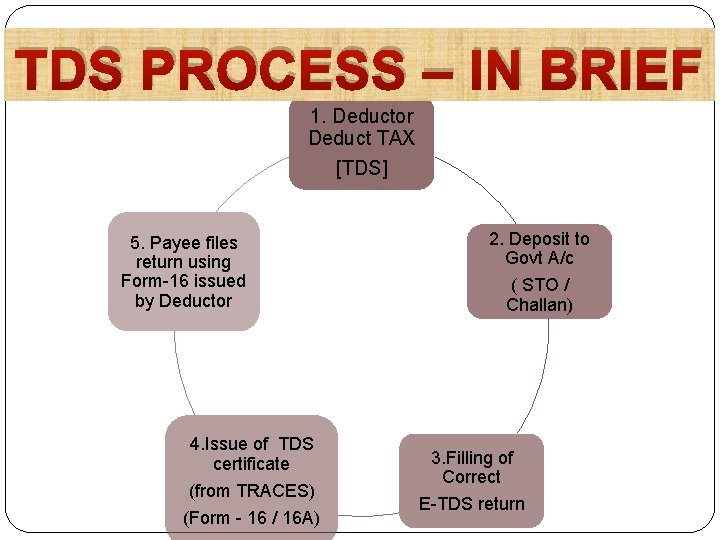
TDS PROCESS – IN BRIEF 1. Deductor Deduct TAX [TDS] 5. Payee files return using Form-16 issued by Deductor 4. Issue of TDS certificate (from TRACES) (Form - 16 / 16 A) 2. Deposit to Govt A/c ( STO / Challan) 3. Filling of Correct E-TDS return
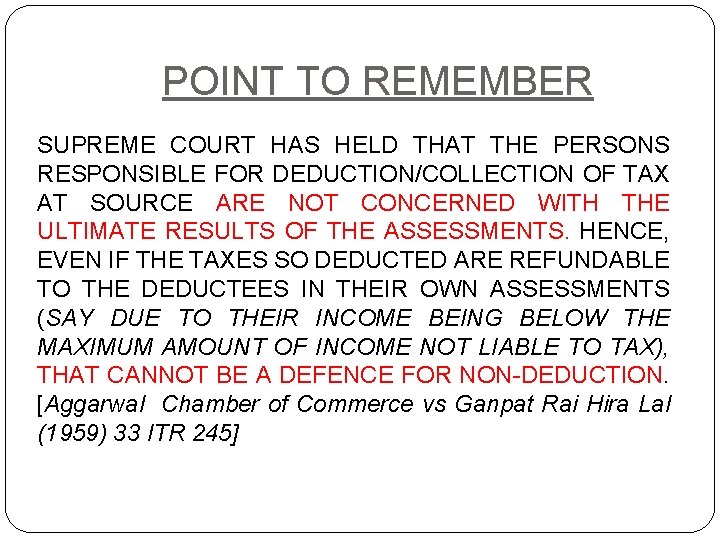
POINT TO REMEMBER SUPREME COURT HAS HELD THAT THE PERSONS RESPONSIBLE FOR DEDUCTION/COLLECTION OF TAX AT SOURCE ARE NOT CONCERNED WITH THE ULTIMATE RESULTS OF THE ASSESSMENTS. HENCE, EVEN IF THE TAXES SO DEDUCTED ARE REFUNDABLE TO THE DEDUCTEES IN THEIR OWN ASSESSMENTS (SAY DUE TO THEIR INCOME BEING BELOW THE MAXIMUM AMOUNT OF INCOME NOT LIABLE TO TAX), THAT CANNOT BE A DEFENCE FOR NON-DEDUCTION. [Aggarwal Chamber of Commerce vs Ganpat Rai Hira Lal (1959) 33 ITR 245]
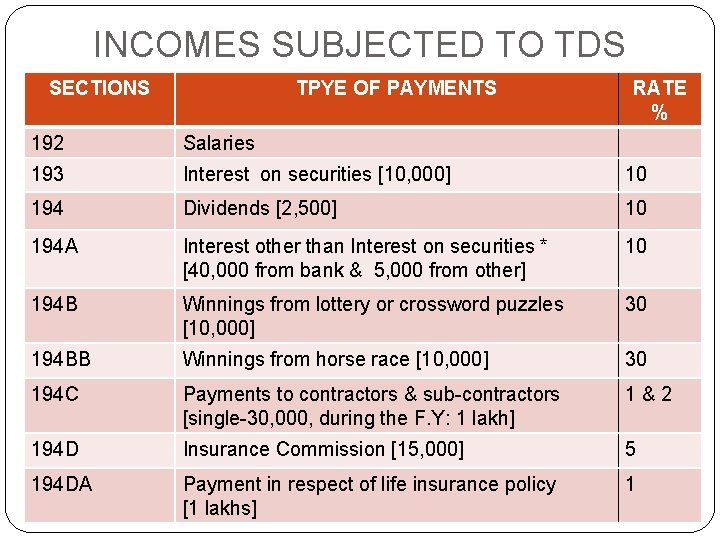
INCOMES SUBJECTED TO TDS SECTIONS TPYE OF PAYMENTS RATE % 192 Salaries 193 Interest on securities [10, 000] 10 194 Dividends [2, 500] 10 194 A Interest other than Interest on securities * [40, 000 from bank & 5, 000 from other] 10 194 B Winnings from lottery or crossword puzzles [10, 000] 30 194 BB Winnings from horse race [10, 000] 30 194 C Payments to contractors & sub-contractors [single-30, 000, during the F. Y: 1 lakh] 1&2 194 D Insurance Commission [15, 000] 5 194 DA Payment in respect of life insurance policy [1 lakhs] 1
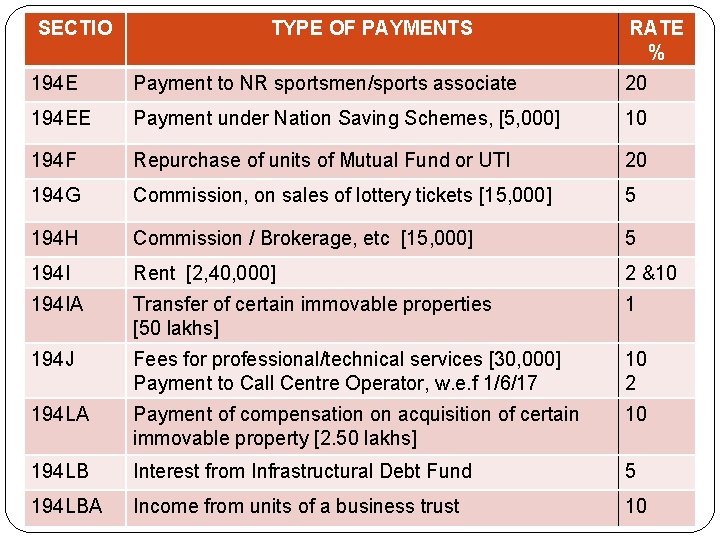
SECTIO TYPE OF PAYMENTS RATE % 194 E Payment to NR sportsmen/sports associate 20 194 EE Payment under Nation Saving Schemes, [5, 000] 10 194 F Repurchase of units of Mutual Fund or UTI 20 194 G Commission, on sales of lottery tickets [15, 000] 5 194 H Commission / Brokerage, etc [15, 000] 5 194 I Rent [2, 40, 000] 2 &10 194 IA Transfer of certain immovable properties [50 lakhs] 1 194 J Fees for professional/technical services [30, 000] Payment to Call Centre Operator, w. e. f 1/6/17 10 2 194 LA Payment of compensation on acquisition of certain immovable property [2. 50 lakhs] 10 194 LB Interest from Infrastructural Debt Fund 5 194 LBA Income from units of a business trust 10
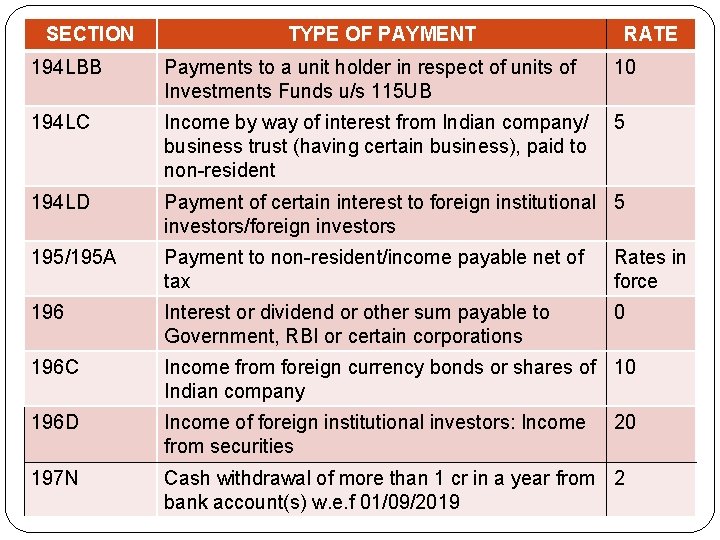
SECTION TYPE OF PAYMENT RATE 194 LBB Payments to a unit holder in respect of units of Investments Funds u/s 115 UB 10 194 LC Income by way of interest from Indian company/ business trust (having certain business), paid to non-resident 5 194 LD Payment of certain interest to foreign institutional 5 investors/foreign investors 195/195 A Payment to non-resident/income payable net of tax Rates in force 196 Interest or dividend or other sum payable to Government, RBI or certain corporations 0 196 C Income from foreign currency bonds or shares of 10 Indian company 196 D Income of foreign institutional investors: Income from securities 197 N Cash withdrawal of more than 1 cr in a year from 2 bank account(s) w. e. f 01/09/2019 20
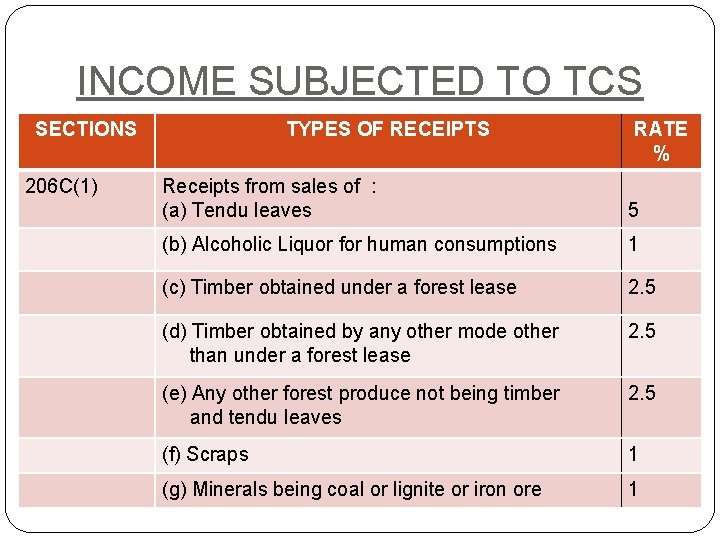
INCOME SUBJECTED TO TCS SECTIONS 206 C(1) TYPES OF RECEIPTS RATE % Receipts from sales of : (a) Tendu leaves 5 (b) Alcoholic Liquor for human consumptions 1 (c) Timber obtained under a forest lease 2. 5 (d) Timber obtained by any other mode other than under a forest lease 2. 5 (e) Any other forest produce not being timber and tendu leaves 2. 5 (f) Scraps 1 (g) Minerals being coal or lignite or iron ore 1
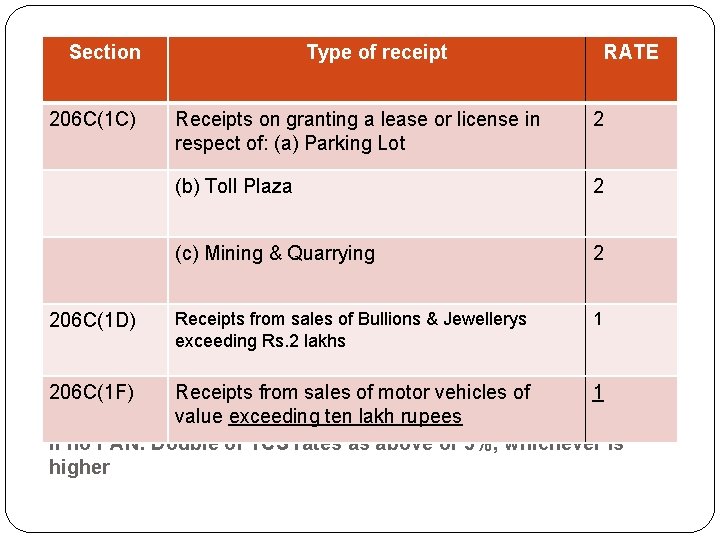
Section 206 C(1 C) 206 C(1 D) 206 C(1 F) Type of receipt RATE Receipts on granting a lease or license in respect of: (a) Parking Lot 2 (b) Toll Plaza 2 (c) Mining & Quarrying 2 Receipts from sales of Bullions & Jewellerys exceeding Rs. 2 lakhs 1 Receipts from sales of motor vehicles of 1 value exceeding ten lakh rupees If no PAN: Double of TCS rates as above or 5%, whichever is higher
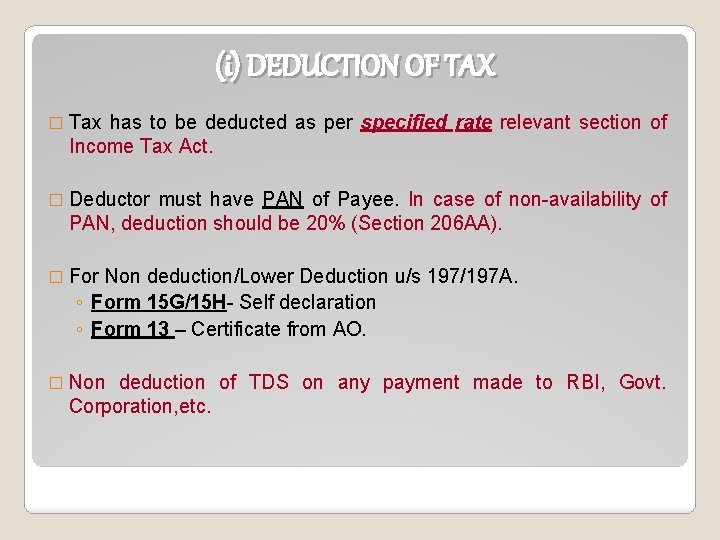
(i) DEDUCTION OF TAX � Tax has to be deducted as per specified rate relevant section of Income Tax Act. � Deductor must have PAN of Payee. In case of non-availability of PAN, deduction should be 20% (Section 206 AA). � For Non deduction/Lower Deduction u/s 197/197 A. ◦ Form 15 G/15 H- Self declaration ◦ Form 13 – Certificate from AO. � Non deduction of TDS on any payment made to RBI, Govt. Corporation, etc.
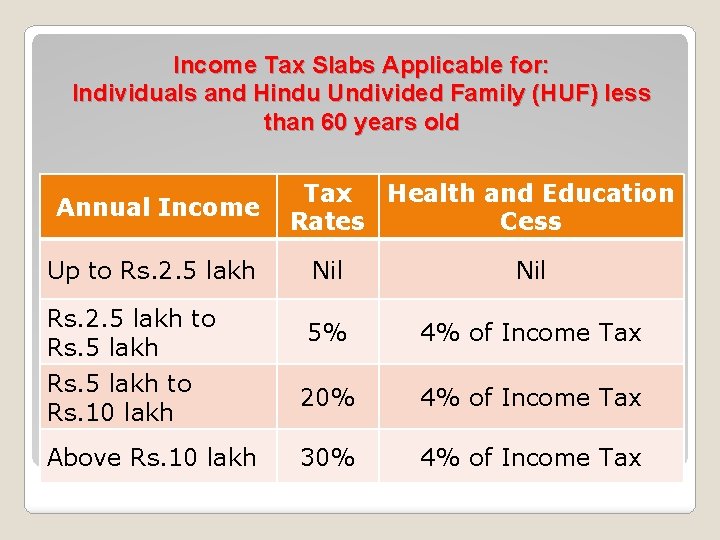
Income Tax Slabs Applicable for: Individuals and Hindu Undivided Family (HUF) less than 60 years old Annual Income Tax Health and Education Rates Cess Up to Rs. 2. 5 lakh Nil Rs. 2. 5 lakh to Rs. 5 lakh 5% 4% of Income Tax Rs. 5 lakh to Rs. 10 lakh 20% 4% of Income Tax Above Rs. 10 lakh 30% 4% of Income Tax
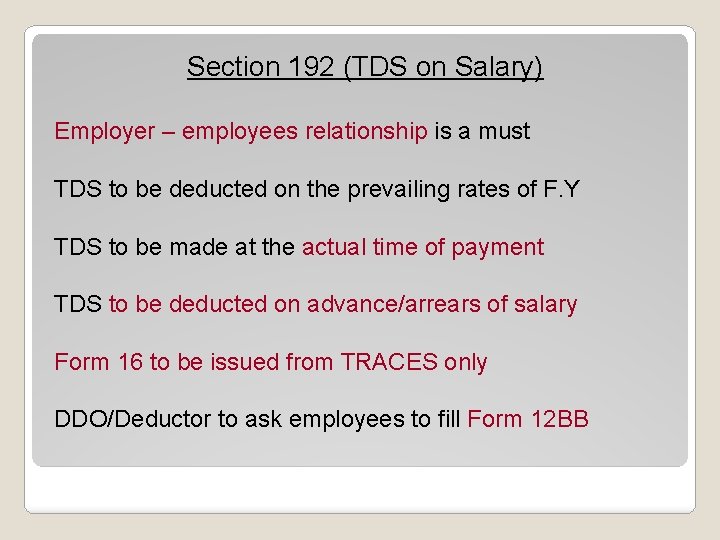
Section 192 (TDS on Salary) Employer – employees relationship is a must TDS to be deducted on the prevailing rates of F. Y TDS to be made at the actual time of payment TDS to be deducted on advance/arrears of salary Form 16 to be issued from TRACES only DDO/Deductor to ask employees to fill Form 12 BB
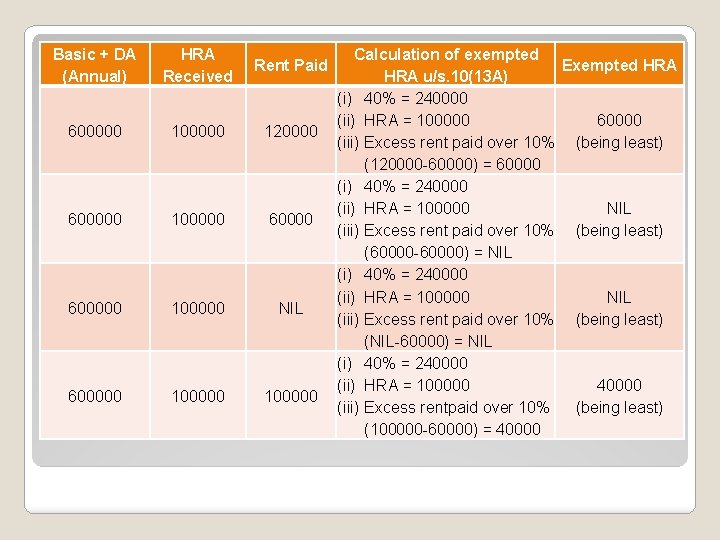
Basic + DA (Annual) HRA Received Rent Paid 600000 120000 600000 100000 NIL 600000 100000 Calculation of exempted Exempted HRA u/s. 10(13 A) (i) 40% = 240000 (ii) HRA = 100000 60000 (iii) Excess rent paid over 10% (being least) (120000 -60000) = 60000 (i) 40% = 240000 (ii) HRA = 100000 NIL (iii) Excess rent paid over 10% (being least) (60000 -60000) = NIL (i) 40% = 240000 (ii) HRA = 100000 NIL (iii) Excess rent paid over 10% (being least) (NIL-60000) = NIL (i) 40% = 240000 (ii) HRA = 100000 40000 (iii) Excess rentpaid over 10% (being least) (100000 -60000) = 40000
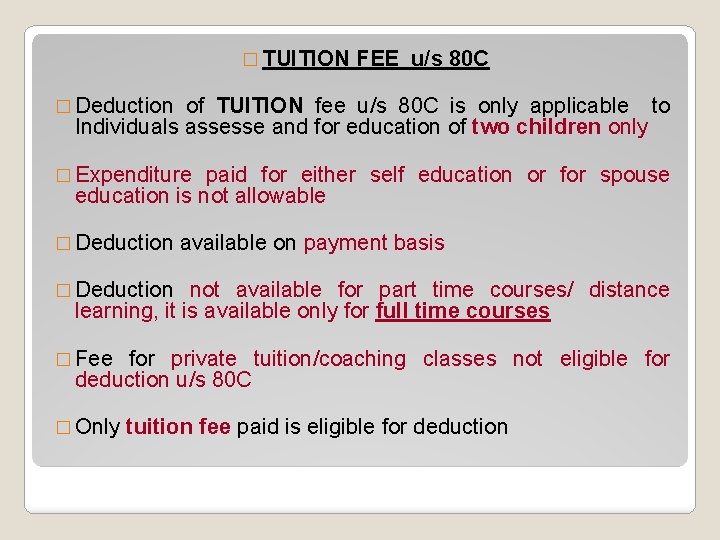
� TUITION FEE u/s 80 C � Deduction of TUITION fee u/s 80 C is only applicable to Individuals assesse and for education of two children only � Expenditure paid for either self education or for spouse education is not allowable � Deduction available on payment basis � Deduction not available for part time courses/ distance learning, it is available only for full time courses � Fee for private tuition/coaching classes not eligible for deduction u/s 80 C � Only tuition fee paid is eligible for deduction
Mode of Remittance & Time limit Remittance (payment into Govt account): • By Challan (No. 281, for the TDS payments) • By Book-adjustment (through Treasury or PAO) Time Limit: • If the tax is to be paid by challan – 7 th of the following month • If the tax adjusted through Book-adjustment – same day
For Payments made through Challan… Points to remember (Very Important) • Use correct Challan (Challan No. 281) • Mention Correct Code of Payment viz. , 92 A-Salary, 94 C – Contract payment etc. , • Enter the correct Assessment Year • Enter the Correct TAN • Enter correct Major Head • Enter Correct Minor Head
Payments made through Bookadjustment / STO / PAO Important Points to remember (i) Deductors must quote Correct TAN and Quantum of payment and Tax deducted thereof and submit the particulars in time to STO / PAO (ii) In return, the STO / PAO files the monthly return in Form No. 24 G within ten days from the end of the month which generates BIN (Book Identification Number). Such BIN is then intimated to the concerned DDO
FILING OF E-TDS RETURNS • The person deducting tax [Deductor] is required to file e-TDS Quarterly Statements / TDS Return, electronically [Directly or through TIN-Facilitation Centers].
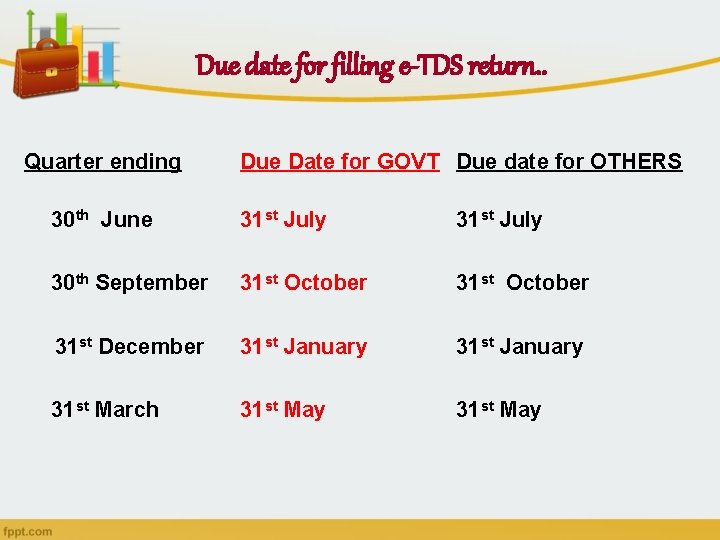
Due date for filling e-TDS return. . Quarter ending Due Date for GOVT Due date for OTHERS 30 th June 31 st July 30 th September 31 st October 31 st December 31 st January 31 st March 31 st May
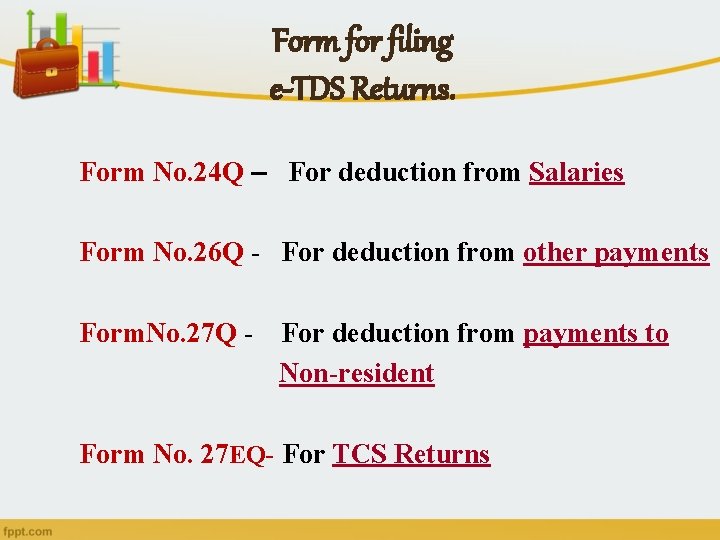
Form for filing e-TDS Returns. Form No. 24 Q – For deduction from Salaries Form No. 26 Q - For deduction from other payments Form. No. 27 Q - For deduction from payments to Non-resident Form No. 27 EQ- For TCS Returns
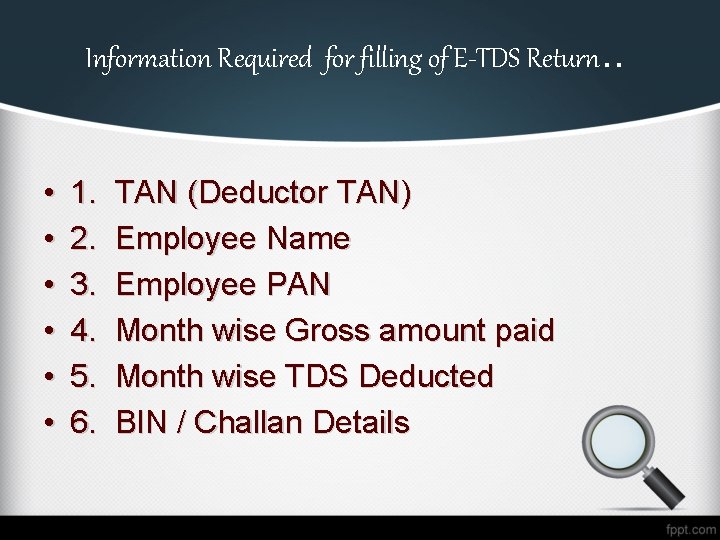
Information Required for filling of E-TDS Return. . • • • 1. 2. 3. 4. 5. 6. TAN (Deductor TAN) Employee Name Employee PAN Month wise Gross amount paid Month wise TDS Deducted BIN / Challan Details
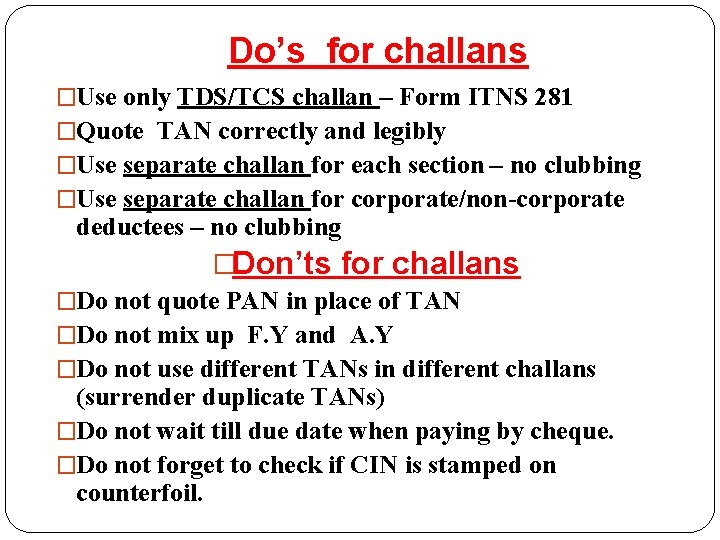
Do’s for challans �Use only TDS/TCS challan – Form ITNS 281 �Quote TAN correctly and legibly �Use separate challan for each section – no clubbing �Use separate challan for corporate/non-corporate deductees – no clubbing �Don’ts for challans �Do not quote PAN in place of TAN �Do not mix up F. Y and A. Y �Do not use different TANs in different challans (surrender duplicate TANs) �Do not wait till due date when paying by cheque. �Do not forget to check if CIN is stamped on counterfoil.
TAN �TAN: Tax deduction/collection Account Number � 10 characters – example: PTNA 01234 A �Every deductor should have/obtain a TAN. �Quote correct TAN in TDS returns, challans and TDS certificates �IF No TAN - Apply in Form 49 B at TIN FC �Surrender duplicate TANs �Not sure of your TAN - Contact TDS officer to know correct TAN �In-case of new DDO/change in address/contact numbers- Please update your TRACES profile regularly
Remedial action for errors • Correction of PAN/TAN, Asst. Year, Amt. – Contact Bank within 7 days from the date of challan deposited. • Correction of Major Head/Minor Head Nature of Payment Contact Bank within 3 months from the date of challan deposited. • File Revised statement.
Issue of TDS certificate �The deductor has to issue Form 16(salary), Form 16 A (Non-salary), Form 27 D ( TCS) to the deductees. �Form 16/16 A/27 D has to be issued only after downloading from TRACES (CBDT Circular No. 4/2013 dated 14/04/2013).
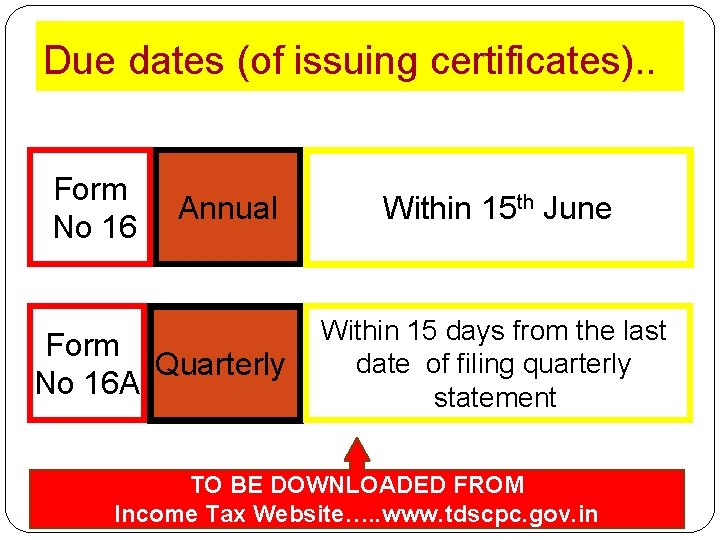
Due dates (of issuing certificates). . Form No 16 Annual Form Quarterly No 16 A Within 15 th June Within 15 days from the last date of filing quarterly statement TO BE DOWNLOADED FROM www. tdscpc. gov. in Income Tax Website…. . www. tdscpc. gov. in
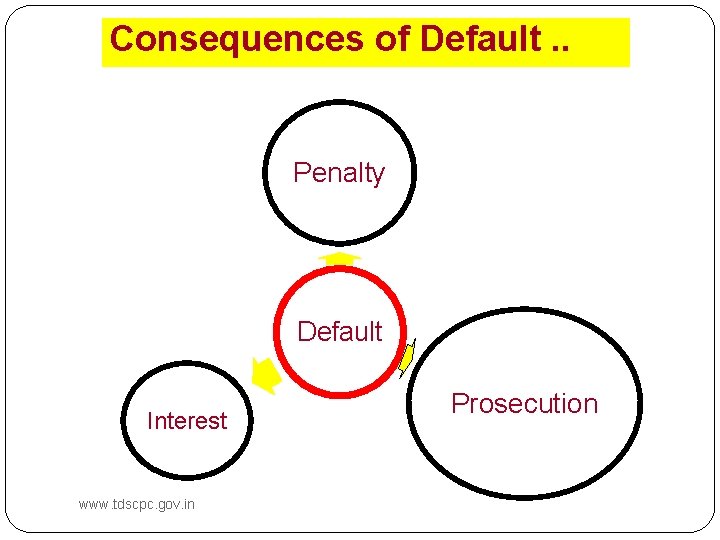
Consequences of Default. . Penalty Default Interest www. tdscpc. gov. in Prosecution
INTEREST LIABILITY Consequences in case of failure to remit / deduct the TDS �In case of failure to remit, Interest at the rate of 1. 5% p. m, from the date of deduction to the date of actual payment, u/s 201(1 A) of IT Act, 1961. �In case of failure to deduct TDS, interest at the rate of 1% p. m or part of the month, from the date on which tax deductable to the date of actual payment u/s 201(1) of the IT Act, 1961.
Fee for late filing of TDS/TCS returns • Failure to file TDS/TCS returns within due date attracts a fee of Rs. 200/- per day till the date of filing the return. However, such fee shall not exceed the amount of tax deductible/ collectible.
Penalty for failure to file TDS/TCS returns • • Penalty for non-filing or furnishing incorrect information of TDS/TCS statements attracts penalty which is not less than Rs. 10, 000/- and not more than Rs. 1, 000/-
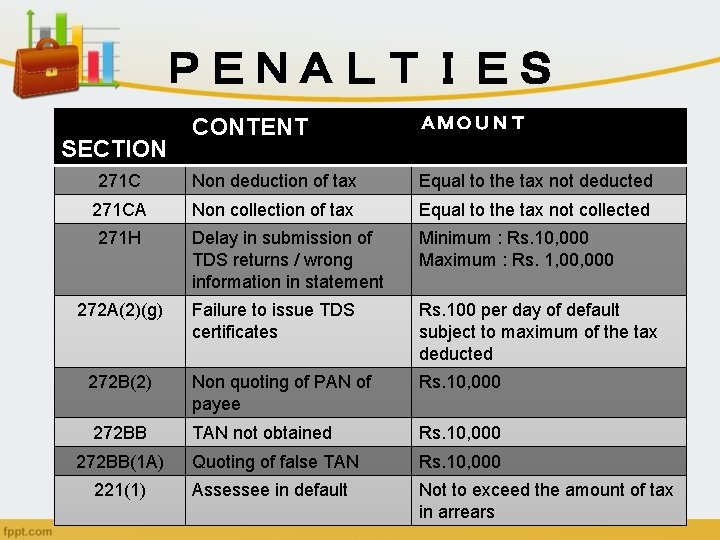
PENALTIES CONTENT AMOUNT 271 C Non deduction of tax Equal to the tax not deducted 271 CA Non collection of tax Equal to the tax not collected Delay in submission of TDS returns / wrong information in statement Minimum : Rs. 10, 000 Maximum : Rs. 1, 000 Failure to issue TDS certificates Rs. 100 per day of default subject to maximum of the tax deducted 272 B(2) Non quoting of PAN of payee Rs. 10, 000 272 BB TAN not obtained Rs. 10, 000 Quoting of false TAN Rs. 10, 000 Assessee in default Not to exceed the amount of tax in arrears SECTION 271 H 272 A(2)(g) 272 BB(1 A) 221(1)
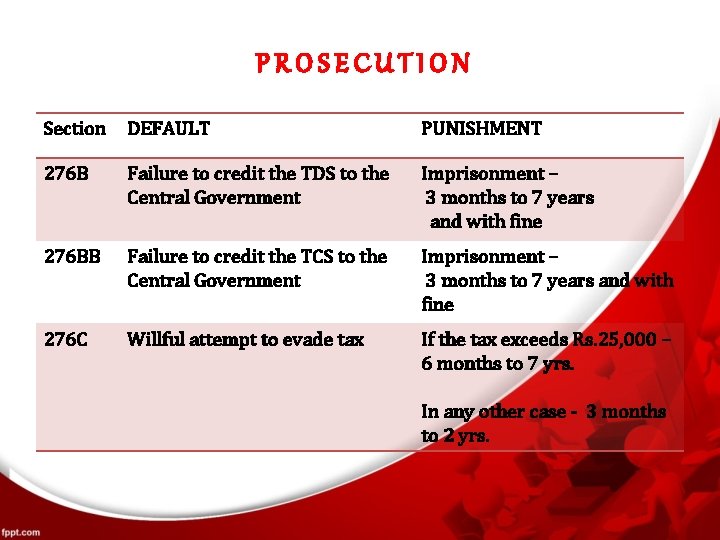
PROSECUTION Section DEFAULT PUNISHMENT 276 B Failure to credit the TDS to the Central Government Imprisonment – 3 months to 7 years and with fine 276 BB Failure to credit the TCS to the Central Government Imprisonment – 3 months to 7 years and with fine 276 C Willful attempt to evade tax If the tax exceeds Rs. 25, 000 – 6 months to 7 yrs. In any other case - 3 months to 2 yrs.
How to avoid Defaults in TDS Statements?
DEDUCT REMIT FILE SMILE
�Patna. dcit. tds@incometax. gov. in �Patna. ito. tds@incometax. gov. in
- Slides: 38