
Subprime Mortgage Crisis Summer 07 MFIN 7011 Tang
Subprime Mortgage Crisis Summer 07, MFIN 7011, Tang Mortgage Backed Securities (MBS) 1
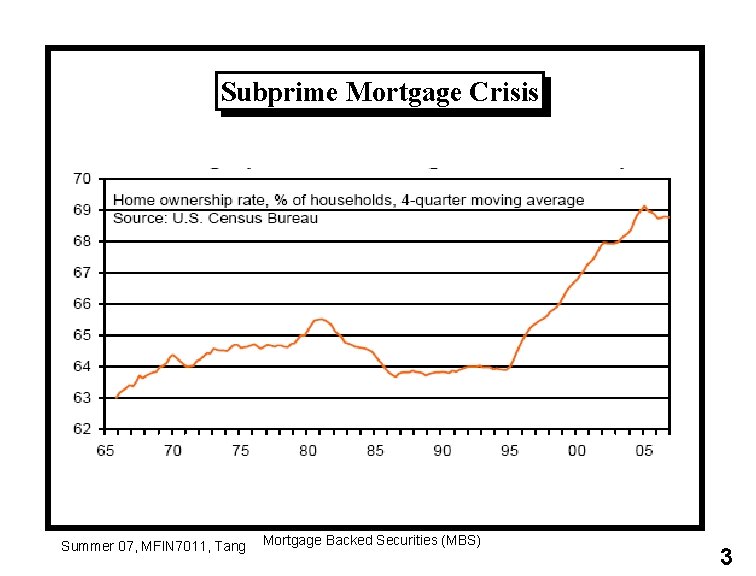
Subprime Mortgage Crisis: The Roadmap Prime Rate: the interest rate commercial banks charge their most creditworthy customers. Subprime loans are characterized by low ‘introductory’ interest rates, usually for the first two or three years. These rates frequently rise rapidly in subsequent years l l l Regulation change: prior to 1992, only commercial banks offered almost exclusively fixed-rate, prime-market mortgages The subprime mortgage market has expanded dramatically in the US, growing at an annual rate of 25 per cent between 1994 and 2005, a tenfold increase in a decade. Homeownership increased 1. 94% per year during Clinton administration, reached 67. 7% in 2000. In 1994, fewer than five percent of mortgages in the US were subprime, but by 2005 nearly 20 percent of new mortgage loans were subprime In the United States today, there is approximately $10 trillion in outstanding mortgages, and of these, about one-quarter are subprime and Alt-A loans (1980 s S&L crisis cost, by comparison, about $240 billion in today's dollars, blamed for the 90 -91 recession) Interest rate rose since 2004 H 2, housing price dropped and mortgage payments increased default rate rose! Summer 07, MFIN 7011, Tang Mortgage Backed Securities (MBS) 2
Subprime Mortgage Crisis Summer 07, MFIN 7011, Tang Mortgage Backed Securities (MBS) 3

Subprime Mortgage Crisis Summer 07, MFIN 7011, Tang Mortgage Backed Securities (MBS) 4

Collateralized Debt Obligation (CDO) • A CDO is an asset backed security (ABS) whose underlying collateral is typically a portfolio of bonds (corporate or sovereign) or bank loans. CDO can be classified according to debt type: – Collateralized loan obligation (CLO); – Collateralized bond obligations (CBO); – Collateralized mortgage obligations (CMO) • The first CDO was created in 1987 by the famous Drexel Burnham Lambert, for a $100 million loan. Summer 07, MFIN 7011, Tang Collateralized Debt Obligations (CDO) 5
Collateralized Debt Obligation (CDO) • A CDO cashflow structure allocates interest income and principal repayments from a collateral pool of different debt instruments to a prioritized collection (tranches) of CDO securities. – First tranche covers x% of notional and absorbs first x% of default losses – Second tranche covers y% of notional and absorbs next y% of default losses – Etc. – A tranche earns a promised yield on remaining principal in the tranche Summer 07, MFIN 7011, Tang Collateralized Debt Obligations (CDO) 6
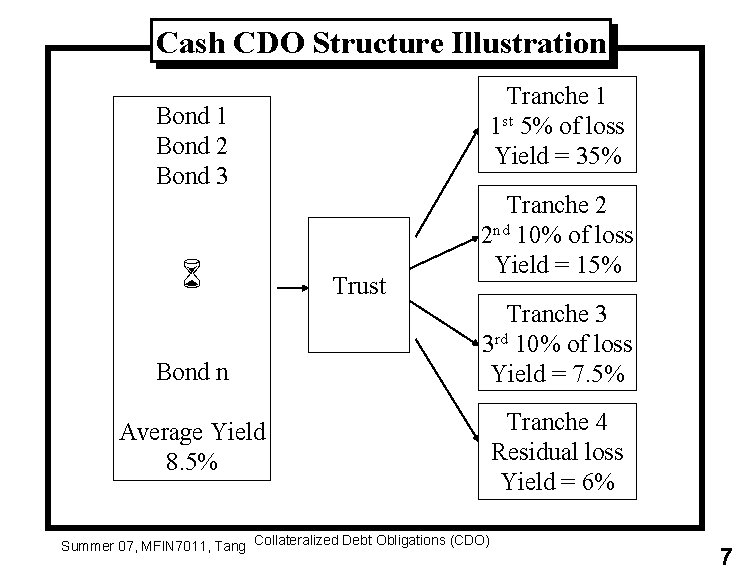
Cash CDO Structure Illustration Tranche 1 1 st 5% of loss Yield = 35% Bond 1 Bond 2 Bond 3 Bond n Trust Tranche 2 2 nd 10% of loss Yield = 15% Tranche 3 3 rd 10% of loss Yield = 7. 5% Average Yield 8. 5% Summer 07, MFIN 7011, Tang Collateralized Debt Obligations (CDO) Tranche 4 Residual loss Yield = 6% 7
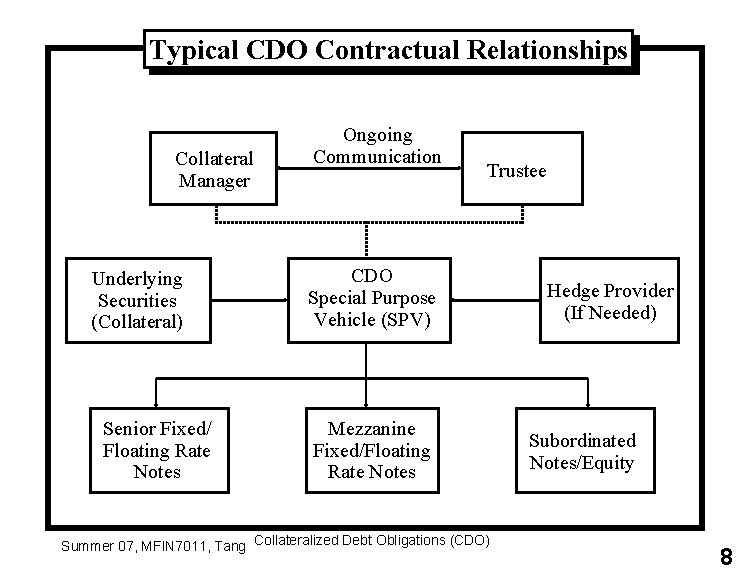
Typical CDO Contractual Relationships Collateral Manager Underlying Securities (Collateral) Senior Fixed/ Floating Rate Notes Ongoing Communication Trustee CDO Special Purpose Vehicle (SPV) Mezzanine Fixed/Floating Rate Notes Summer 07, MFIN 7011, Tang Collateralized Debt Obligations (CDO) Hedge Provider (If Needed) Subordinated Notes/Equity 8
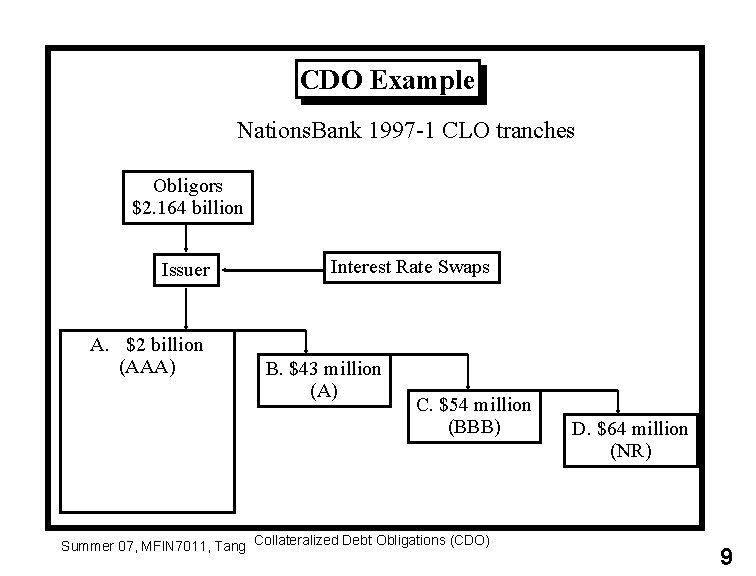
CDO Example Nations. Bank 1997 -1 CLO tranches Obligors $2. 164 billion Issuer A. $2 billion (AAA) Interest Rate Swaps B. $43 million (A) C. $54 million (BBB) Summer 07, MFIN 7011, Tang Collateralized Debt Obligations (CDO) D. $64 million (NR) 9
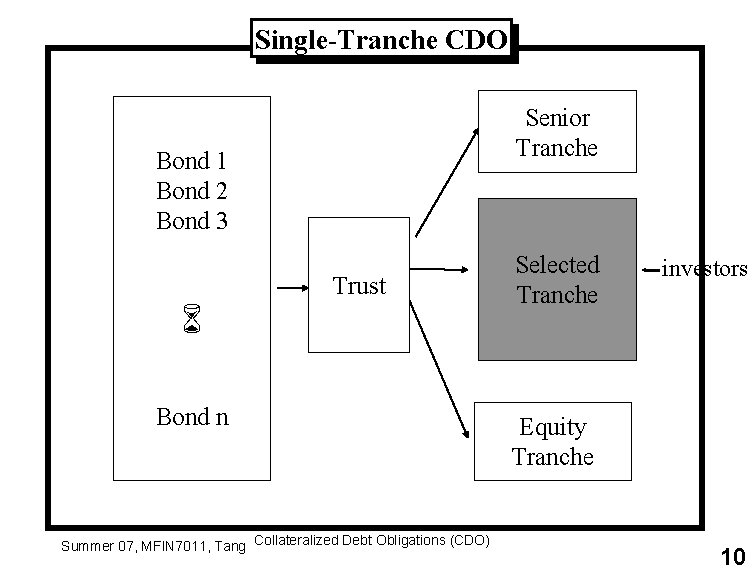
Single-Tranche CDO Senior Tranche Bond 1 Bond 2 Bond 3 Trust Bond n Summer 07, MFIN 7011, Tang Collateralized Debt Obligations (CDO) Selected Tranche investors Equity Tranche 10
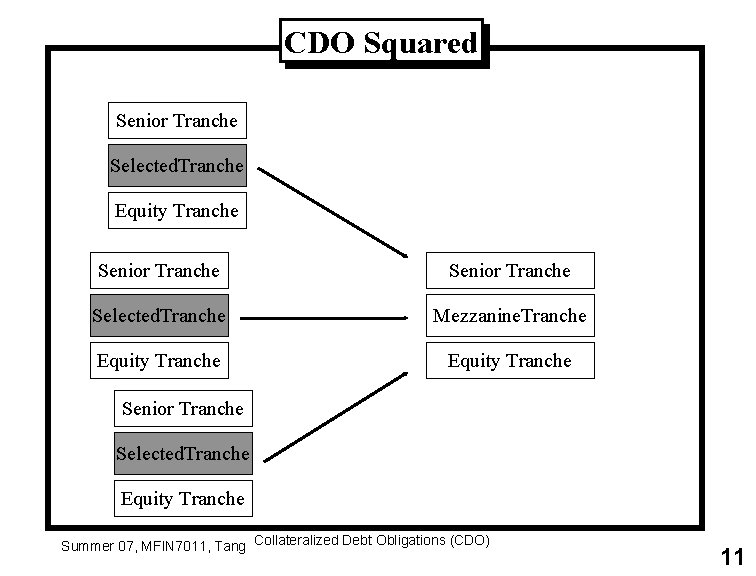
CDO Squared Senior Tranche Selected. Tranche Equity Tranche Senior Tranche Selected. Tranche Mezzanine. Tranche Equity Tranche Senior Tranche Selected. Tranche Equity Tranche Summer 07, MFIN 7011, Tang Collateralized Debt Obligations (CDO) 11
Subprime Mortgage Crisis and CDO l CDOs are the power packs of the late housing boom Ø Hedge funds invest in CDO tranches backed by residential mortgages backed securities (RMBS) with large portion in subprime Ø CDOs have become an important part of the mortgage market because they buy the riskier parts of MBS that others don't want. The higherrated portions, or tranches, of MBS are sold to pension funds and insurers. But if the riskier tranches aren't sold too, the whole deal is off Ø Causes? Reckless lenders; Greedy investors/borrowers l Rating agencies are criticized. Most CDOs had A rating l Effect on baby boomers' retirement Summer 07, MFIN 7011, Tang Mortgage Backed Securities (MBS) 12
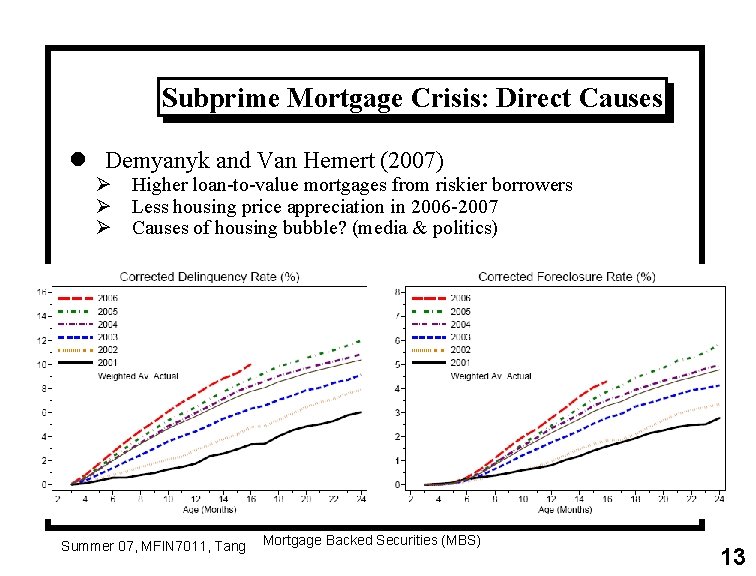
Subprime Mortgage Crisis: Direct Causes l Demyanyk and Van Hemert (2007) Ø Higher loan-to-value mortgages from riskier borrowers Ø Less housing price appreciation in 2006 -2007 Ø Causes of housing bubble? (media & politics) Summer 07, MFIN 7011, Tang Mortgage Backed Securities (MBS) 13
Subprime Mortgage Crisis: Winners and Losers l Winners? (are you kidding me? Yes there are winners such as the first batch investors. ) l Big losers: http: //ml-implode. com/ Ø Bear Stearns: two hedge funds (>$1 billion) Ø Australia: Basis Capital ($1 billion? ); Absolute Capital ($200 million? ); IKB Deutsche Industriebank … Ø May take two more years to completely resolve! l Big losers: Ø Ø Ø Citigroup ($18 B+) Merrill Lynch ($11. 5 B+) UBS ($17. 8 B+) Morgan Stanley ($9. 4 B+) … Bank of China (initial estimate $223 million, now could be $4 -5 B) l Effect on baby boomers' retirement Summer 07, MFIN 7011, Tang Mortgage Backed Securities (MBS) 14
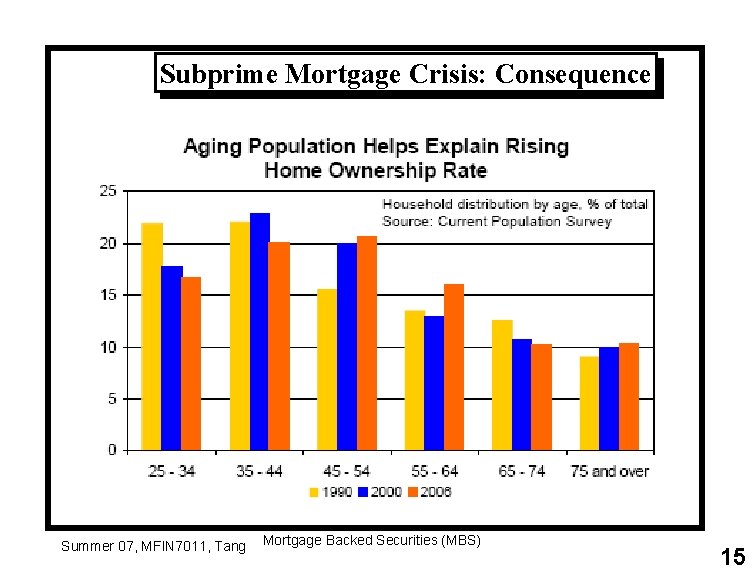
Subprime Mortgage Crisis: Consequence Summer 07, MFIN 7011, Tang Mortgage Backed Securities (MBS) 15
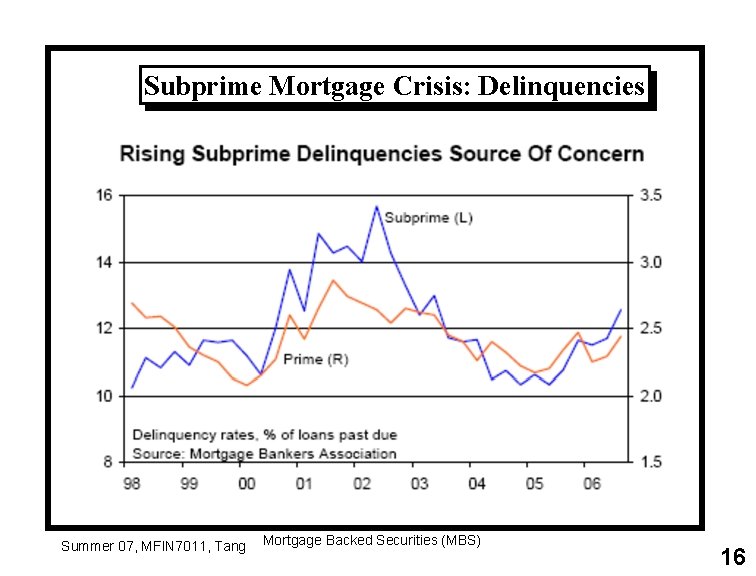
Subprime Mortgage Crisis: Delinquencies Summer 07, MFIN 7011, Tang Mortgage Backed Securities (MBS) 16
- Slides: 16