
Streamlining the Accounts Steven Mair City Treasurer Westminster
- Slides: 10
Streamlining the Accounts Steven Mair, City Treasurer, Westminster Jake Bacchus, Strategic Finance Manager Peter Worth, Technical Advisor
Agenda ØWhy? ØWhat? ØWhen?
Why? Accounts timetable coming forward Reduced staff resources Increasingly complex accounts Lack of understanding amongst practitioners Heightened audit risk arising from complexity Relevance of some disclosures to local government? Added value of Code changes? Clearer assurance/information to stakeholders providing more understandable information than in the past Ø Once established operates at reduced resource requirement from normal practices Ø Ø Ø Ø
Why? Ø Supports development of holistic financial management Ø Frees up Finance resources to then focus on added value Ø Staff experience, motivation & careers enhanced Ø Reputation of the Council and the service likewise Ø An example of Finance leading from the front Ø Sets a standard of quality, aspiration and timeliness, raises the Financial Management “bar” Ø Culture change: • • Can do - and what else can we do? Encouraging transformation and ideas
What? ØLocal authorities ØCIPFA/LASAAC ØDCLG
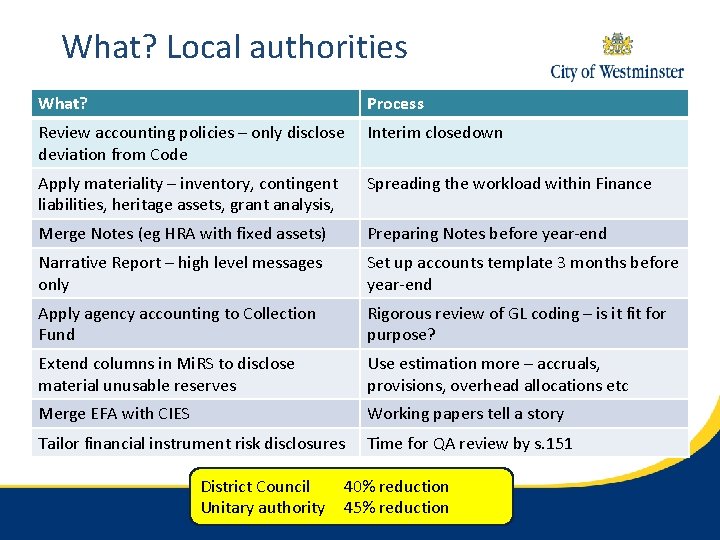
What? Local authorities What? Process Review accounting policies – only disclose deviation from Code Interim closedown Apply materiality – inventory, contingent liabilities, heritage assets, grant analysis, Spreading the workload within Finance Merge Notes (eg HRA with fixed assets) Preparing Notes before year-end Narrative Report – high level messages only Set up accounts template 3 months before year-end Apply agency accounting to Collection Fund Rigorous review of GL coding – is it for purpose? Extend columns in Mi. RS to disclose material unusable reserves Use estimation more – accruals, provisions, overhead allocations etc Merge EFA with CIES Working papers tell a story Tailor financial instrument risk disclosures Time for QA review by s. 151 District Council Unitary authority 40% reduction 45% reduction
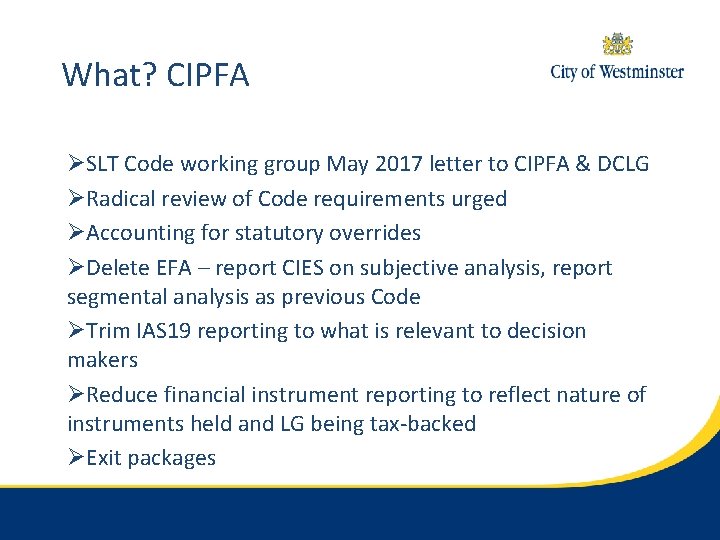
What? CIPFA ØSLT Code working group May 2017 letter to CIPFA & DCLG ØRadical review of Code requirements urged ØAccounting for statutory overrides ØDelete EFA – report CIES on subjective analysis, report segmental analysis as previous Code ØTrim IAS 19 reporting to what is relevant to decision makers ØReduce financial instrument reporting to reflect nature of instruments held and LG being tax-backed ØExit packages
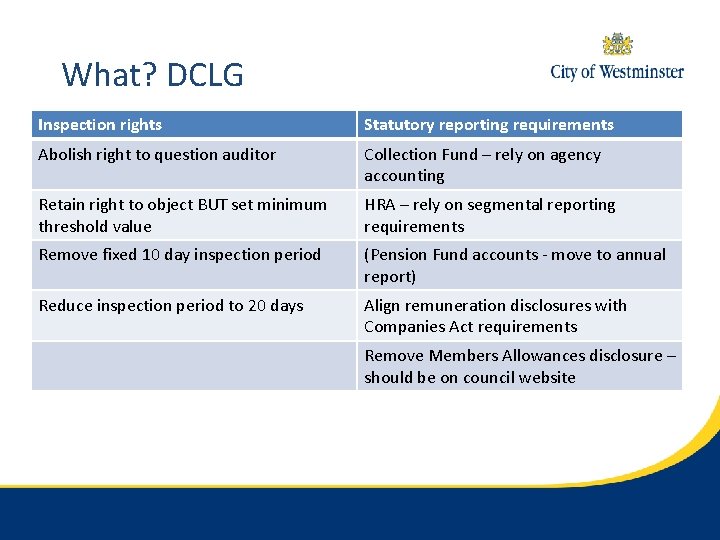
What? DCLG Inspection rights Statutory reporting requirements Abolish right to question auditor Collection Fund – rely on agency accounting Retain right to object BUT set minimum threshold value HRA – rely on segmental reporting requirements Remove fixed 10 day inspection period (Pension Fund accounts - move to annual report) Reduce inspection period to 20 days Align remuneration disclosures with Companies Act requirements Remove Members Allowances disclosure – should be on council website
When? ØCIPFA consulting on 2018/19 Code ØDeadline for responses 6 October 2017 ØResponses do not have to be limited to the questions asked ØDCLG consulting on Accounts and Audit Regulations Ølikely to be Autumn 2017 ØImplementation likely to be for 2018/19
Any questions ?