
Spatial Econometric Analysis 3 KuanPin Lin Portland State
- Slides: 15
Spatial Econometric Analysis 3 Kuan-Pin Lin Portland State University
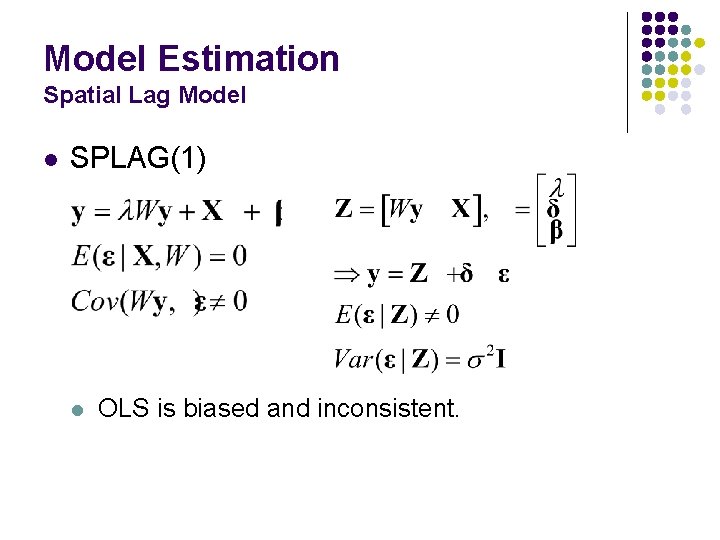
Model Estimation Spatial Lag Model l SPLAG(1) l OLS is biased and inconsistent.
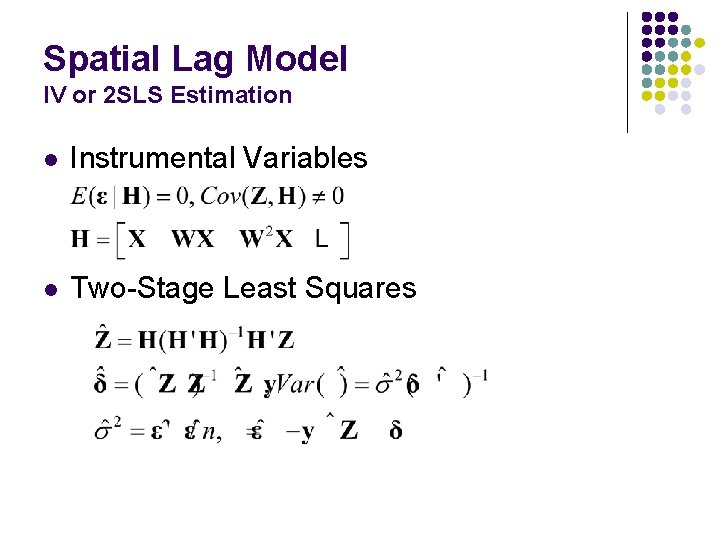
Spatial Lag Model IV or 2 SLS Estimation l Instrumental Variables l Two-Stage Least Squares
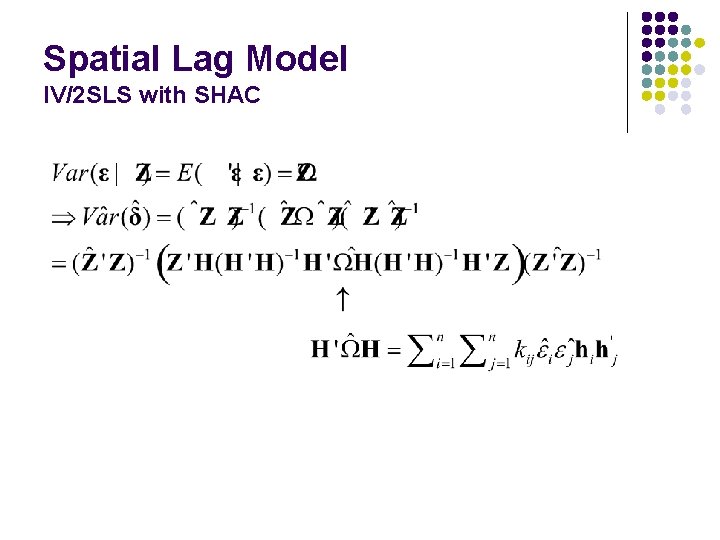
Spatial Lag Model IV/2 SLS with SHAC
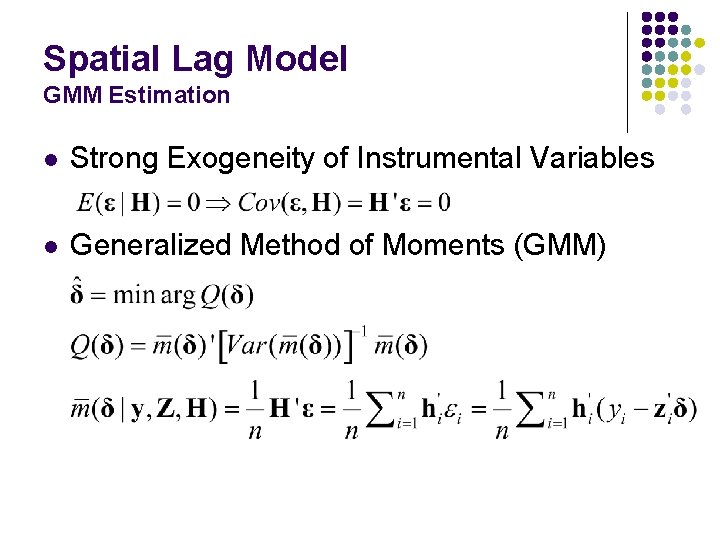
Spatial Lag Model GMM Estimation l Strong Exogeneity of Instrumental Variables l Generalized Method of Moments (GMM)
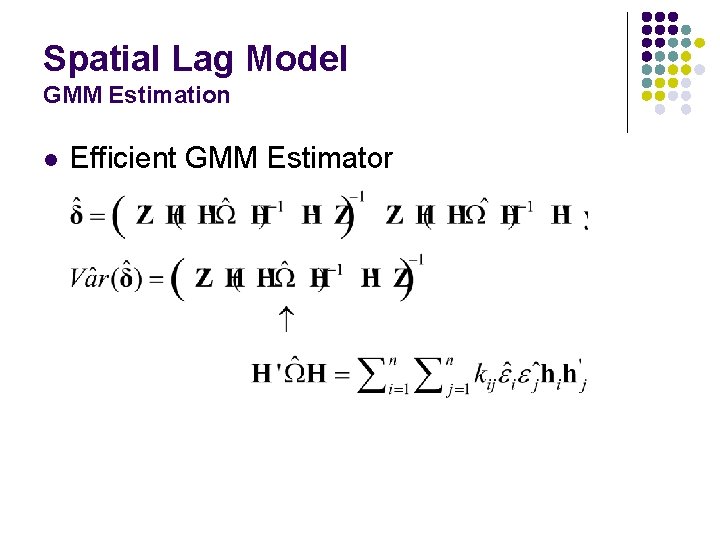
Spatial Lag Model GMM Estimation l Efficient GMM Estimator
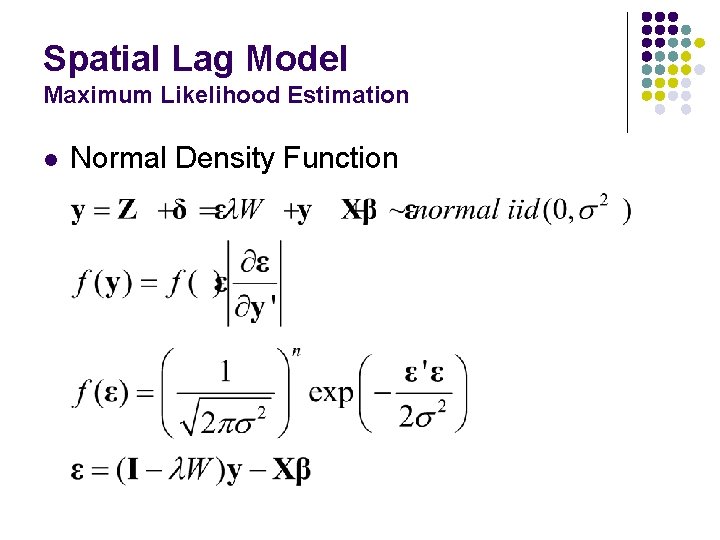
Spatial Lag Model Maximum Likelihood Estimation l Normal Density Function
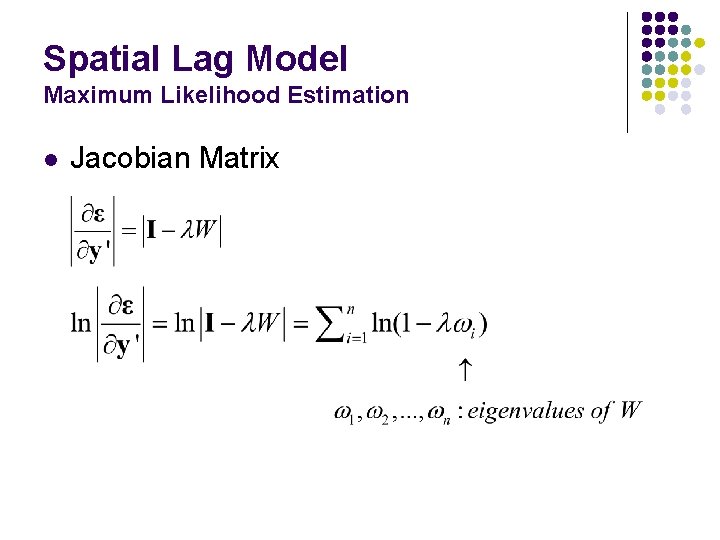
Spatial Lag Model Maximum Likelihood Estimation l Jacobian Matrix
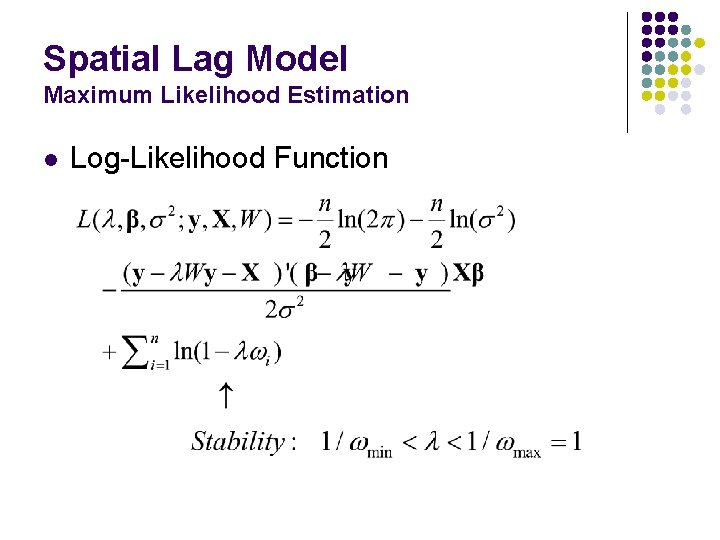
Spatial Lag Model Maximum Likelihood Estimation l Log-Likelihood Function
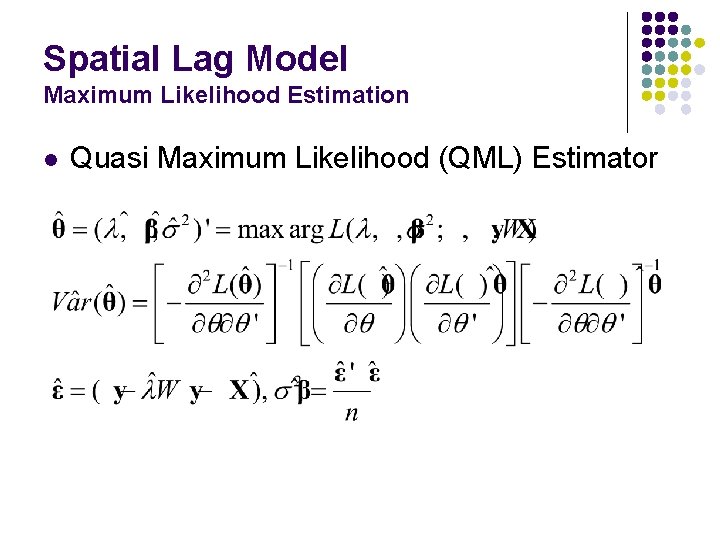
Spatial Lag Model Maximum Likelihood Estimation l Quasi Maximum Likelihood (QML) Estimator
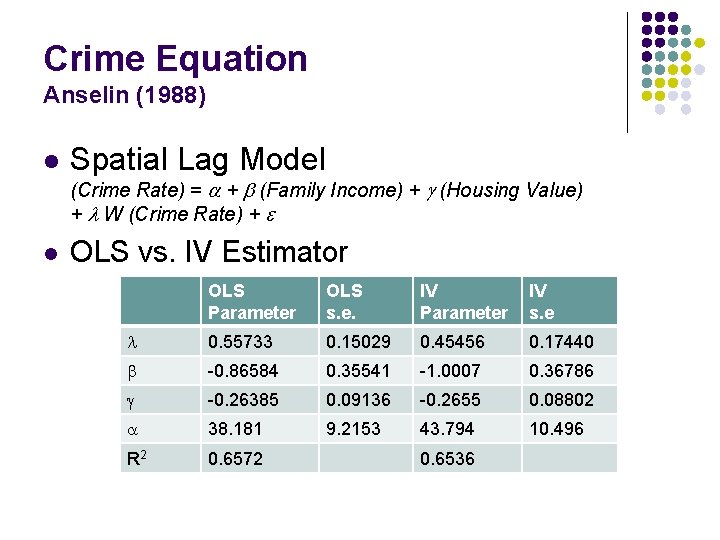
Crime Equation Anselin (1988) l Spatial Lag Model (Crime Rate) = a + b (Family Income) + g (Housing Value) + l W (Crime Rate) + e l OLS vs. IV Estimator OLS Parameter OLS s. e. IV Parameter IV s. e l 0. 55733 0. 15029 0. 45456 0. 17440 b -0. 86584 0. 35541 -1. 0007 0. 36786 g -0. 26385 0. 09136 -0. 2655 0. 08802 a 38. 181 9. 2153 43. 794 10. 496 R 2 0. 6572 0. 6536
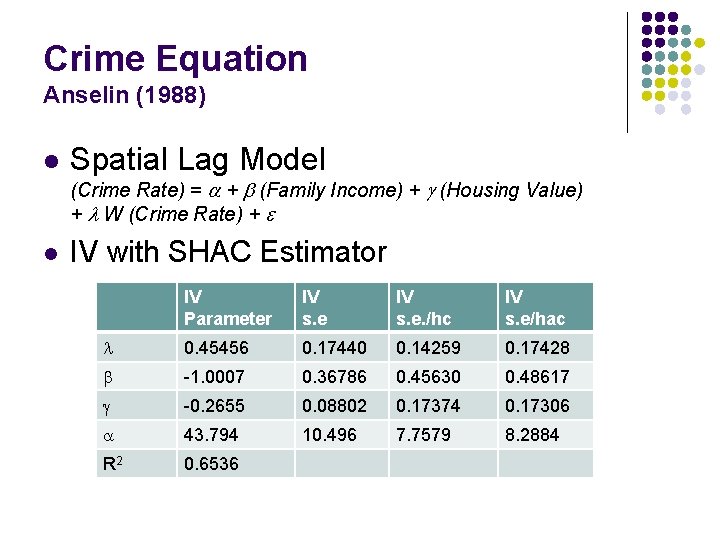
Crime Equation Anselin (1988) l Spatial Lag Model (Crime Rate) = a + b (Family Income) + g (Housing Value) + l W (Crime Rate) + e l IV with SHAC Estimator IV Parameter IV s. e. /hc IV s. e/hac l 0. 45456 0. 17440 0. 14259 0. 17428 b -1. 0007 0. 36786 0. 45630 0. 48617 g -0. 2655 0. 08802 0. 17374 0. 17306 a 43. 794 10. 496 7. 7579 8. 2884 R 2 0. 6536
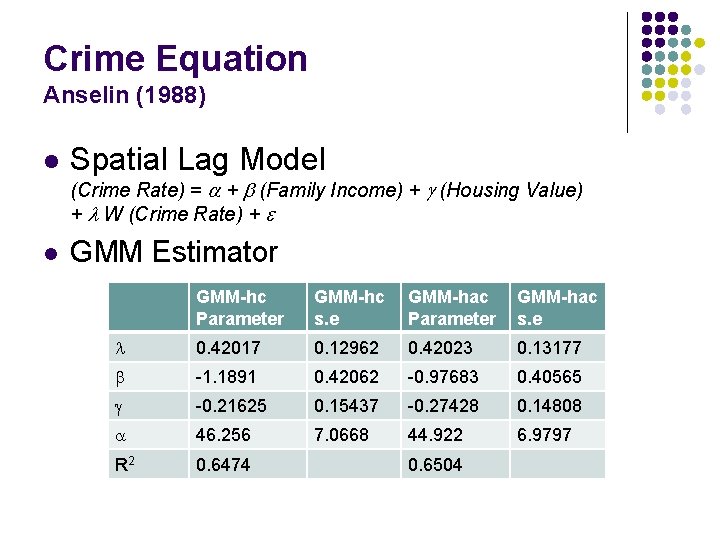
Crime Equation Anselin (1988) l Spatial Lag Model (Crime Rate) = a + b (Family Income) + g (Housing Value) + l W (Crime Rate) + e l GMM Estimator GMM-hc Parameter GMM-hc s. e GMM-hac Parameter GMM-hac s. e l 0. 42017 0. 12962 0. 42023 0. 13177 b -1. 1891 0. 42062 -0. 97683 0. 40565 g -0. 21625 0. 15437 -0. 27428 0. 14808 a 46. 256 7. 0668 44. 922 6. 9797 R 2 0. 6474 0. 6504
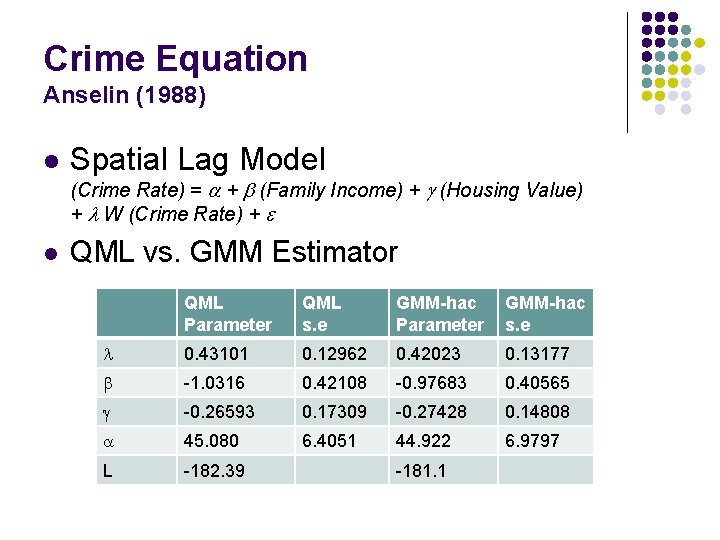
Crime Equation Anselin (1988) l Spatial Lag Model (Crime Rate) = a + b (Family Income) + g (Housing Value) + l W (Crime Rate) + e l QML vs. GMM Estimator QML Parameter QML s. e GMM-hac Parameter GMM-hac s. e l 0. 43101 0. 12962 0. 42023 0. 13177 b -1. 0316 0. 42108 -0. 97683 0. 40565 g -0. 26593 0. 17309 -0. 27428 0. 14808 a 45. 080 6. 4051 44. 922 6. 9797 L -182. 39 -181. 1
References l l l Kelejian,H. ,and I. R. Prucha,1999. A Generalized Moments Estimator for the Autoregressive Parameter in a Spatial Model. International Economic Review 40,509 -533. Kelejian, H. , and I. R. Prucha, 2009. Specification and Estimation of Spatial Autoregressive Models with Autoregressive and Heteroskedastic Disturbances. Journal of Econometrics, forthcoming. Lee,L. F. ,2004. Asymptotic Distributions of Maximum Likelihood Estimators for Spatial Autoregressive Models. Econometrica, 72, 1899 -1925.