
Social Inflation What Does It Mean to Cedents
- Slides: 14
Social Inflation: What Does It Mean to Cedents and Reinsurers? Paul Braithwaite, Senior Managing Director, FTI Consulting Elizabeth Geary, Chief Underwriting Officer, North America, Trans. Re Larry P. Schiffer, Schiffer Law & Consulting PLLC, Moderator
Agenda • • • What is Social Inflation? Is Social Inflation New? Why Does Social Inflation Matter to Insurers and Reinsurers? COVID-19 and Social Inflation Addressing the Effects of Social Inflation
What is Social Inflation? • Does anybody know? • Does everybody agree? • Common elements • Rising costs of insurance claims • Fueled by trends in society • • Nuclear verdicts/public desensitization to large jury verdicts More liberal treatment of claims Erosion of tort reforms Third-party litigation funding Erosion in trust of corporate America Changing views of social responsibility Populism
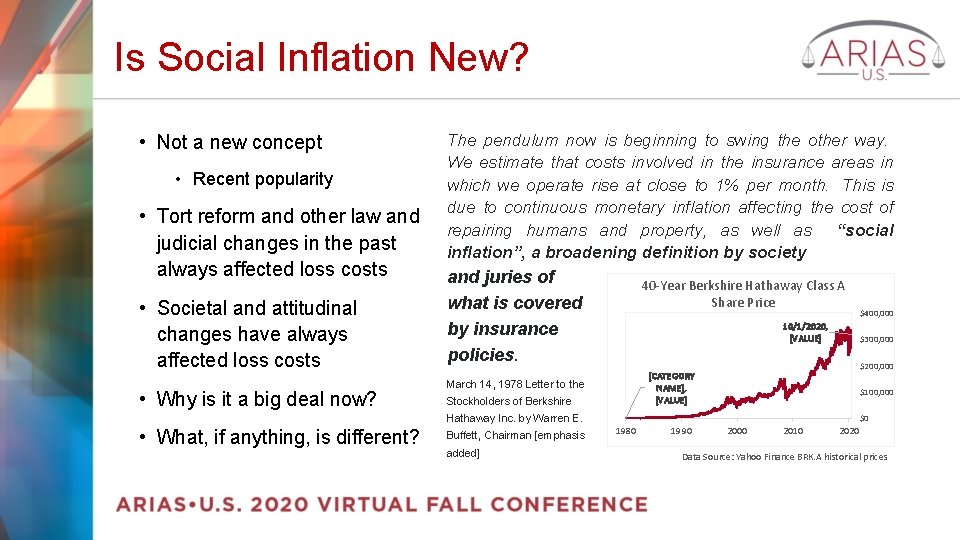
Is Social Inflation New? • Not a new concept • Recent popularity • Tort reform and other law and judicial changes in the past always affected loss costs • Societal and attitudinal changes have always affected loss costs • Why is it a big deal now? The pendulum now is beginning to swing the other way. We estimate that costs involved in the insurance areas in which we operate rise at close to 1% per month. This is due to continuous monetary inflation affecting the cost of repairing humans and property, as well as “social inflation”, a broadening definition by society and juries of what is covered by insurance policies. 40 -Year Berkshire Hathaway Class A Share Price 10/1/2020, [VALUE] $300, 000 $200, 000 [CATEGORY NAME], [VALUE] March 14, 1978 Letter to the Stockholders of Berkshire $100, 000 Hathaway Inc. by Warren E. • What, if anything, is different? Buffett, Chairman [emphasis added] $400, 000 $0 1980 1990 2000 2010 2020 Data Source: Yahoo Finance BRK. A historical prices
Why Does Social Inflation Matter to Insurers and Reinsurers? • Economic effect of Social Inflation • Social Inflation and profits • Effect on loss reserves • Effect on direct and reinsurance premiums • Does the line or class of business matter? • The leveraged effect of inflation on excess & umbrella insurance
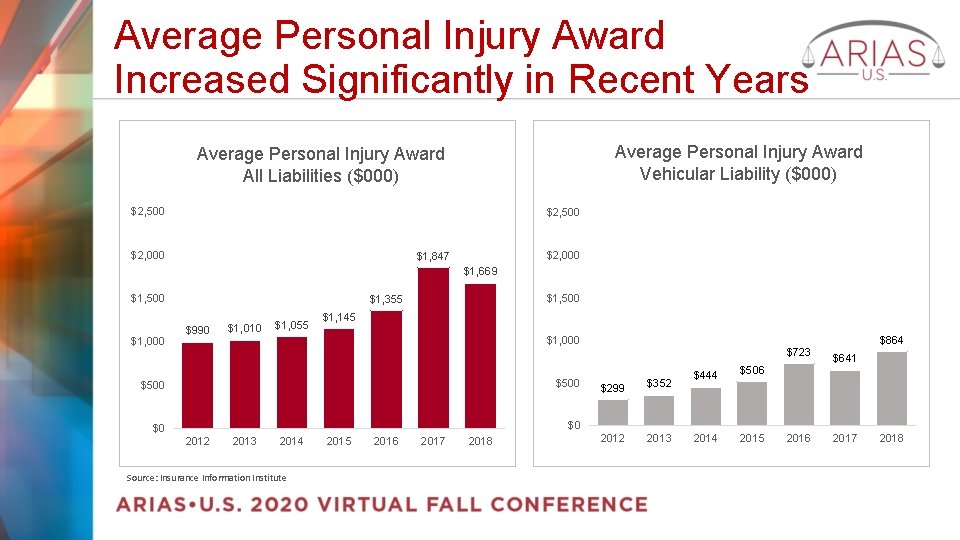
Average Personal Injury Award Increased Significantly in Recent Years Average Personal Injury Award Vehicular Liability ($000) Average Personal Injury Award All Liabilities ($000) $2, 500 $2, 000 $1, 847 $1, 669 $1, 500 $1, 000 $1, 500 $1, 355 $990 $1, 010 $1, 055 $1, 145 $1, 000 $500 $0 $0 2012 2013 2014 Source: Insurance Information Institute 2015 2016 2017 2018 $723 $299 $352 2013 $444 $506 2014 2015 2016 $864 $641 2017 2018
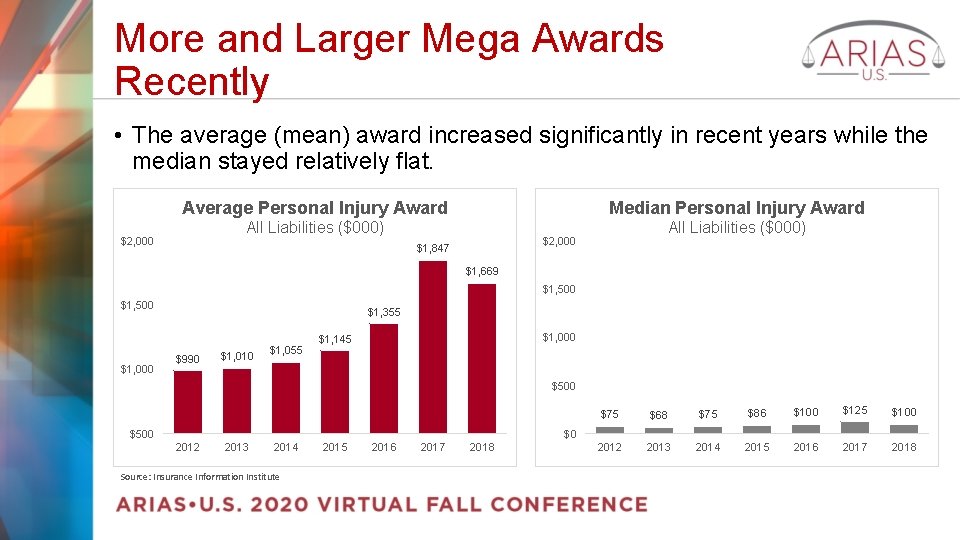
More and Larger Mega Awards Recently • The average (mean) award increased significantly in recent years while the median stayed relatively flat. Average Personal Injury Award Median Personal Injury Award All Liabilities ($000) $2, 000 $1, 847 $1, 669 $1, 500 $1, 000 $1, 355 $990 $1, 010 $1, 055 $1, 000 $1, 145 $500 $75 $68 $75 $86 $100 $125 $100 2012 2013 2014 2015 2016 2017 2018 $0 2012 2013 2014 Source: Insurance Information Institute 2015 2016 2017 2018
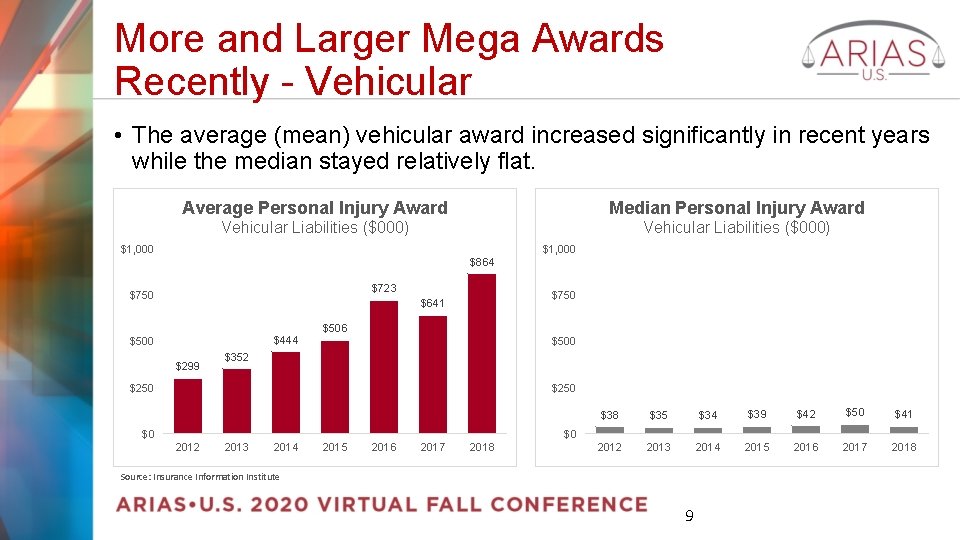
More and Larger Mega Awards Recently - Vehicular • The average (mean) vehicular award increased significantly in recent years while the median stayed relatively flat. Average Personal Injury Award Median Personal Injury Award Vehicular Liabilities ($000) $1, 000 $864 $723 $750 $641 $444 $500 $299 $506 $500 $352 $250 $0 $38 $35 $34 $39 $42 $50 $41 2012 2013 2014 2015 2016 2017 2018 $0 2012 2013 2014 2015 2016 2017 2018 Source: Insurance Information Institute 9
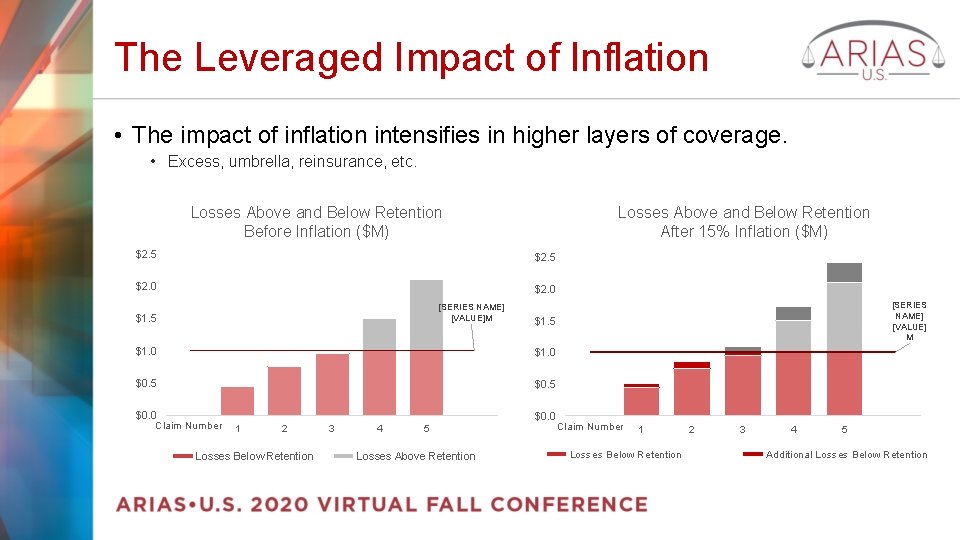
The Leveraged Impact of Inflation • The impact of inflation intensifies in higher layers of coverage. • Excess, umbrella, reinsurance, etc. Losses Above and Below Retention After 15% Inflation ($M) Losses Above and Below Retention Before Inflation ($M) $2. 5 2, 500, 000 $2. 0 2, 000 [SERIES NAME] [VALUE]M $1. 5 1, 500, 000 $1. 0 1, 000 $0. 5 500, 000 $0. 0 Claim Number 0 1 2 Losses Below Retention 3 4 5 Losses Above Retention $2. 5 2, 500, 000 $2. 0 2, 000 [SERIES NAME] [VALUE] M $1. 5 1, 500, 000 $1. 0 1, 000 $0. 5 500, 000 $0. 0 0 Claim Number 1 Losses Below Retention 2 3 4 5 Additional Losses Below Retention
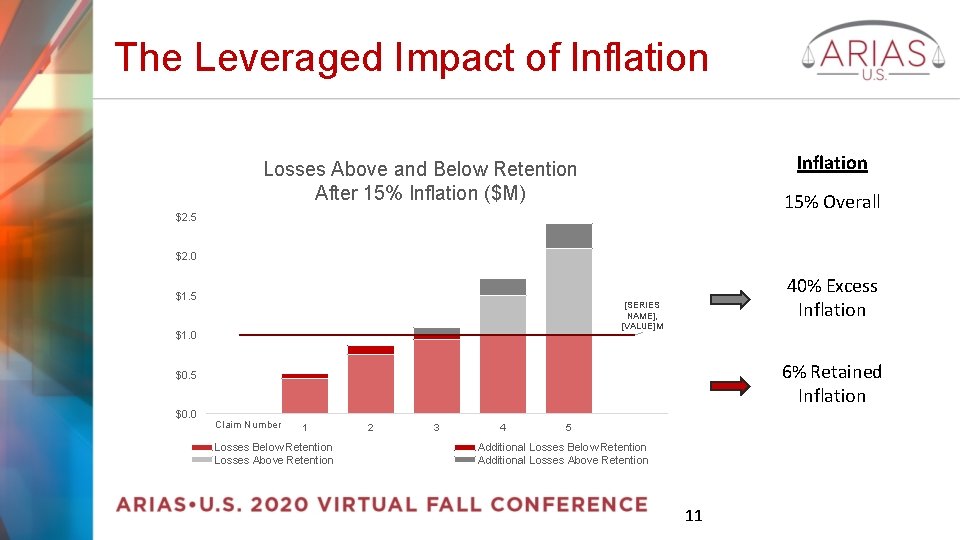
The Leveraged Impact of Inflation Losses Above and Below Retention After 15% Inflation ($M) 15% Overall $2. 5 2, 500, 000 $2. 0 2, 000 $1. 5 $1. 0 1, 000 $0. 5 $0. 0 40% Excess Inflation 1, 500, 000 [SERIES NAME], [VALUE]M 6% Retained Inflation 500, 000 0 Claim Number 1 Losses Below Retention Losses Above Retention 2 3 4 5 Additional Losses Below Retention Additional Losses Above Retention 11
COVID-19 and Social Inflation • Has COVID-19 stopped Social Inflation? • Some researchers point to the public’s dissatisfaction with “how things are going” as leading to higher awards • By causing a period of 15% unemployment, COVID-19 could make social inflation and rising litigation costs even worse
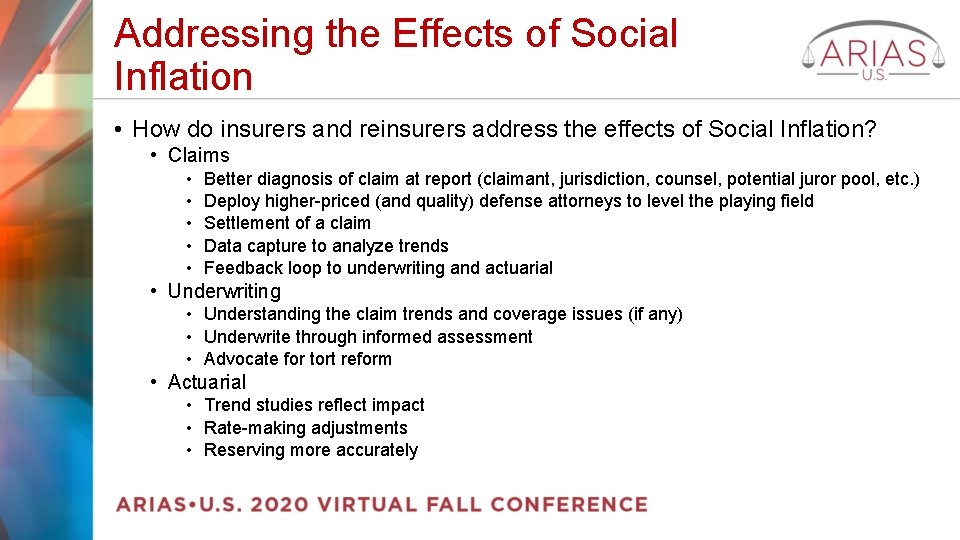
Addressing the Effects of Social Inflation • How do insurers and reinsurers address the effects of Social Inflation? • Claims • • • Better diagnosis of claim at report (claimant, jurisdiction, counsel, potential juror pool, etc. ) Deploy higher-priced (and quality) defense attorneys to level the playing field Settlement of a claim Data capture to analyze trends Feedback loop to underwriting and actuarial • Underwriting • Understanding the claim trends and coverage issues (if any) • Underwrite through informed assessment • Advocate for tort reform • Actuarial • Trend studies reflect impact • Rate-making adjustments • Reserving more accurately
Q&A THANK YOU! Paul Braithwaite - Paul. Braithwaite@fticonsulting. com Elizabeth Geary - egeary@transre. com Larry Schiffer – larry. schiffer@schifferlc. com