
SOB Acquisition Finance eskoslovensk obchodn banka a s
ČSOB Acquisition Finance Československá obchodní banka, a. s. Prague, Kampa, March 3, 2008
Acquisition Finance Models 1. Direct M&A 2. LBOs Financing of Transactions 2
AD 1. Direct M&A Model Elements and Characteristics: • Direct purchase of a Target and held directly by Investor in its books; • Investor directly bears 100% risk of potential failure and all liabilities resulting from an acquisition loan; • This model is typical for industry (strategic) Investors; • Bank provides the financing within the framework of the whole group; 3
AD 1. Direct M&A Model Elements and Characteristics: • Investor may not valuate the acquisition based on a direct capital gain, but rather prefer other positive impacts; • Positive impacts – synergy resulting in increase in sales, decrease in costs, or buying new markets; • Bank evaluates the risk of the whole corporation; • The financing model typically includes existing financing, acquisition financing and operational loans provided to the Target; 4
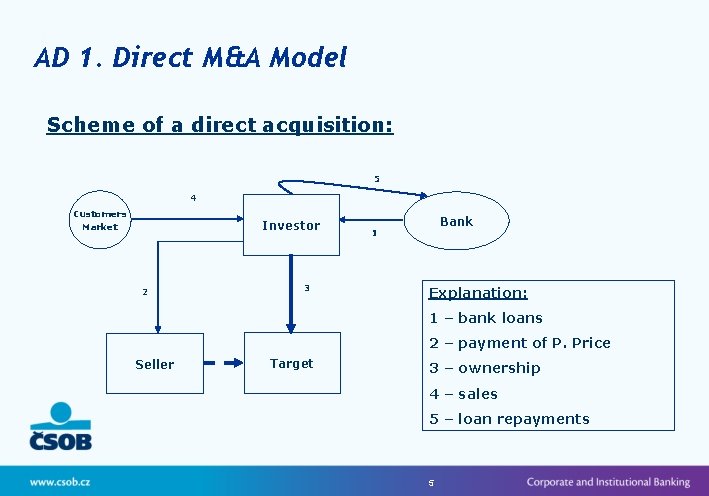
AD 1. Direct M&A Model Scheme of a direct acquisition: 5 4 Customers Market Investor 2 3 Bank 1 Explanation: 1 – bank loans 2 – payment of P. Price Seller Target 3 – ownership 4 – sales 5 – loan repayments 5
AD 2. Leveraged Buy-outs Elements and Characteristics: • Using an SPV; • Financing of the purchase price is based on future CF generated by the Target; • Investor is secluded from direct transaction and financing risks; • Bank evaluates the risk of the Target; • LBO is typically used by: • Financial Investors • Corporations already leveraged • Intra-shareholders settlements 6
AD 2. Leveraged Buy-outs Elements and Characteristics: • Low equity ratios = high leverage; • Positive impacts on the tax cost and on WACC; • Significantly reduced risk of Investor (limited to equity contribution); • Well-proven, and well-developed transaction structuring; • Tested according to the LMA standards; 7
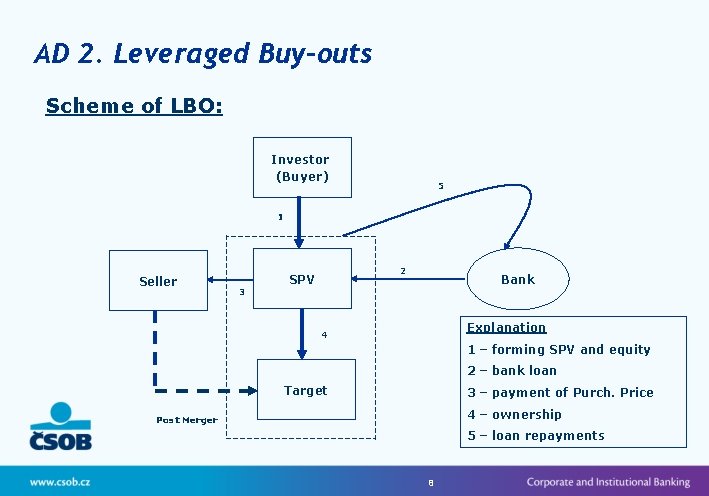
AD 2. Leveraged Buy-outs Scheme of LBO: Investor (Buyer) 5 1 Seller 2 SPV Bank 3 Explanation 4 1 – forming SPV and equity 2 – bank loan Target 3 – payment of Purch. Price 4 – ownership Post Merger 5 – loan repayments 8
Acquisition Finance Models Financing of Transactions 9
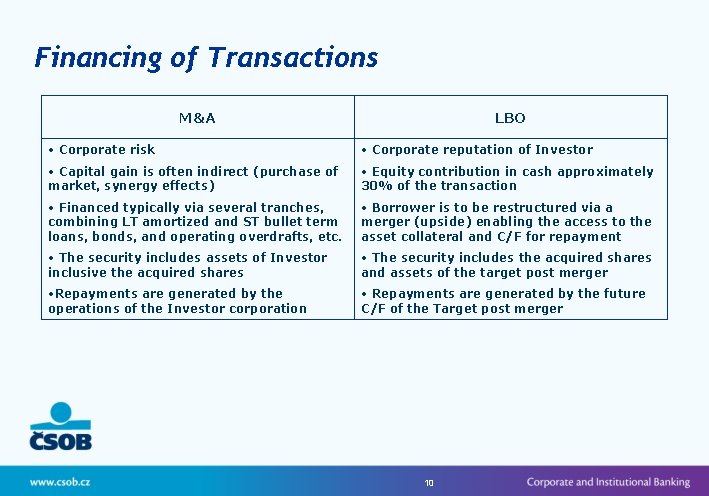
Financing of Transactions M&A LBO • Corporate risk • Corporate reputation of Investor • Capital gain is often indirect (purchase of market, synergy effects) • Equity contribution in cash approximately 30% of the transaction • Financed typically via several tranches, combining LT amortized and ST bullet term loans, bonds, and operating overdrafts, etc. • Borrower is to be restructured via a merger (upside) enabling the access to the asset collateral and C/F for repayment • The security includes assets of Investor inclusive the acquired shares • The security includes the acquired shares and assets of the target post merger • Repayments are generated by the operations of the Investor corporation • Repayments are generated by the future C/F of the Target post merger 10
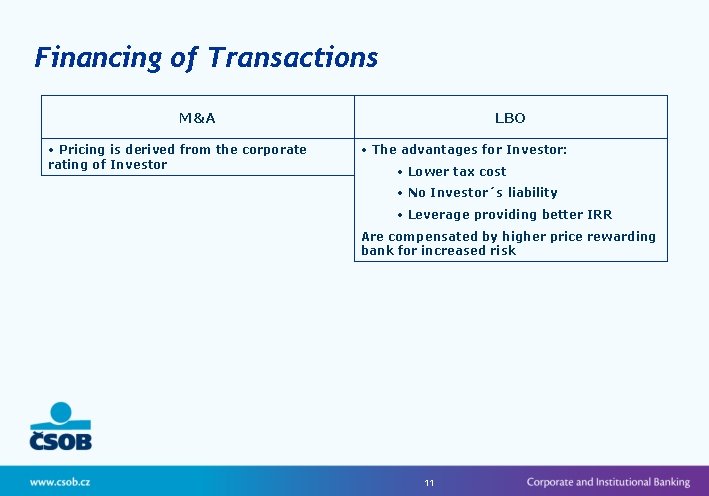
Financing of Transactions M&A • Pricing is derived from the corporate rating of Investor LBO • The advantages for Investor: • Lower tax cost • No Investor´s liability • Leverage providing better IRR Are compensated by higher price rewarding bank for increased risk 11
Contact Dalibor Jeřábek Acquisition Finance phone +420 224 114 391 mob. +420 603 151 561 e-mail djerabek@csob. cz 12
- Slides: 12