
Small Dimension PDE for Discrete Asian Options Eric
- Slides: 16
Small Dimension PDE for Discrete Asian Options Eric Ben. Hamou (LSE, UK) & Alexandre Duguet (LSE, UK) CEF 2000 Conference (Barcelona)
Plan • • • Introduction How to reduce the dimension Homogeneous case Extension to non Homogeneous case Numerical results Conclusion 6 -8 July 2000 CEF 2000 Conference Slide N° 2
Introduction to the Asian Option • Origin and motivation – spot manipulation – periodic cash flows • Definition: – type of averaging – fixed or floating strike • Pricing problem? 6 -8 July 2000 CEF 2000 Conference Slide N° 3
Different methods • Closed forms solutions – Geometric approximations (Vorst 92 96) – density distributions assumptions (Turnbull Wakeman 91, Levy 92 Jacques 95, Milevsky Posner 97) – Laplace Transform (Geman Yor 93) (Madan Yu 95) • Numerical methods – Monte Carlo (Kemma Vorst 90 96) – Fast Fourier Transform PDE (Caverhill Clewlow 92 Benhamou 2000) – PDE (Roger Shi 95 He and Takashi 96 Alziary et al. 97 Forsyth et al. 98) 6 -8 July 2000 CEF 2000 Conference Slide N° 4
Motivations • Find a numerical method consistent with: – Smile model: (Dupire 93 Derman Kani 94) – Discrete non proportional dividend • Use PDE method to solve this problem: – determination of the PDE – dimension reduction problem 6 -8 July 2000 CEF 2000 Conference Slide N° 5
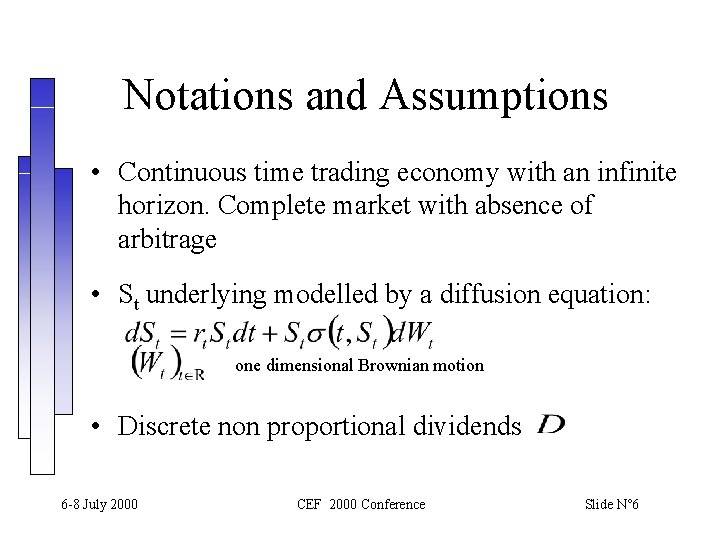
Notations and Assumptions • Continuous time trading economy with an infinite horizon. Complete market with absence of arbitrage • St underlying modelled by a diffusion equation: one dimensional Brownian motion • Discrete non proportional dividends 6 -8 July 2000 CEF 2000 Conference Slide N° 6
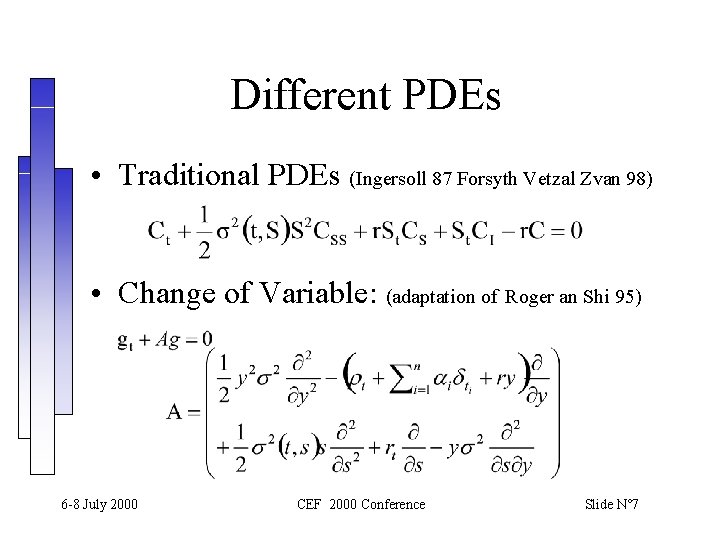
Different PDEs • Traditional PDEs (Ingersoll 87 Forsyth Vetzal Zvan 98) • Change of Variable: (adaptation of Roger an Shi 95) 6 -8 July 2000 CEF 2000 Conference Slide N° 7
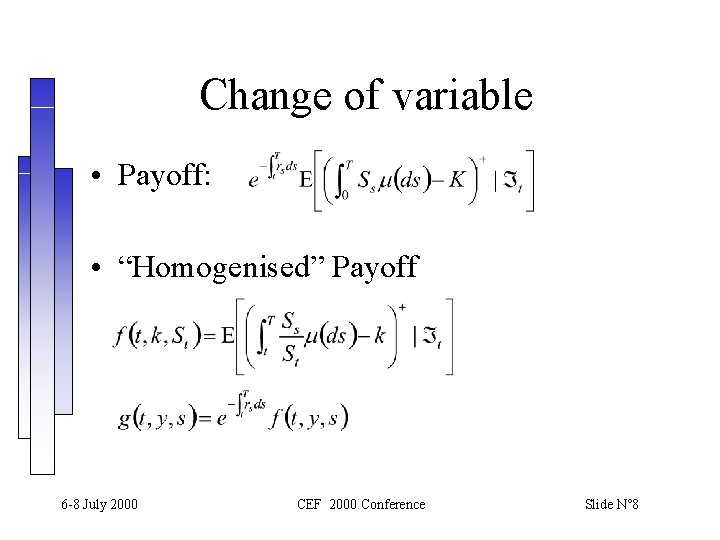
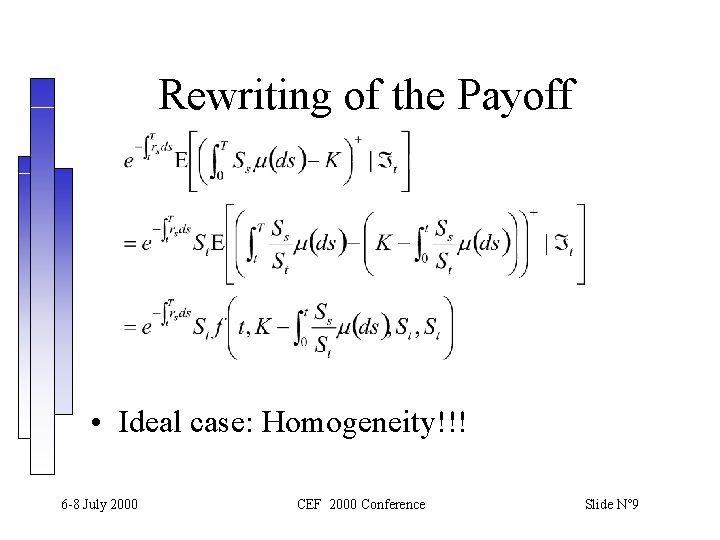
Change of variable • Payoff: • “Homogenised” Payoff 6 -8 July 2000 CEF 2000 Conference Slide N° 8
Rewriting of the Payoff • Ideal case: Homogeneity!!! 6 -8 July 2000 CEF 2000 Conference Slide N° 9
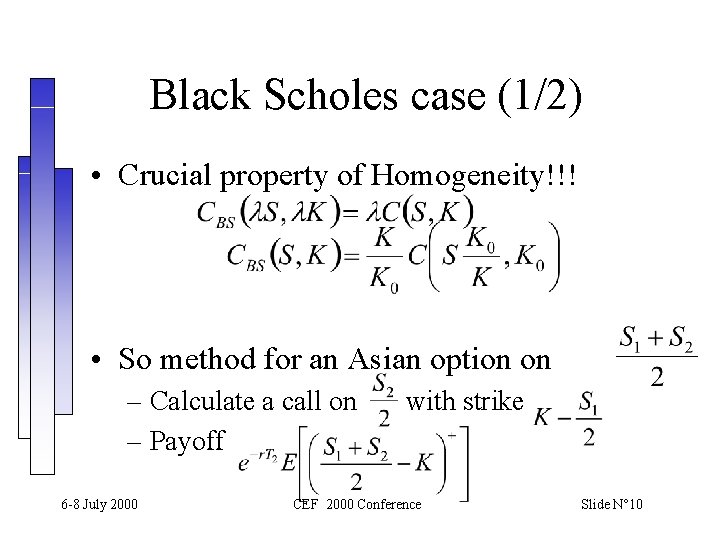
Black Scholes case (1/2) • Crucial property of Homogeneity!!! • So method for an Asian option on – Calculate a call on – Payoff 6 -8 July 2000 with strike CEF 2000 Conference Slide N° 10
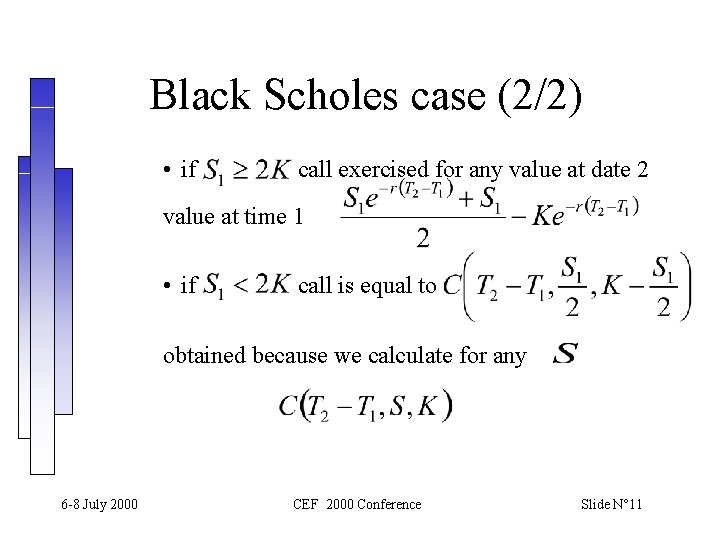
Black Scholes case (2/2) • if call exercised for any value at date 2 value at time 1 • if call is equal to obtained because we calculate for any 6 -8 July 2000 CEF 2000 Conference Slide N° 11
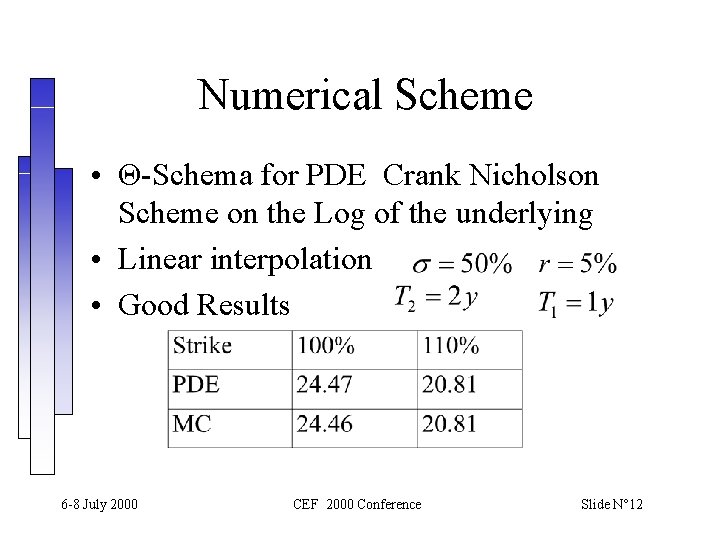
Numerical Scheme • Θ-Schema for PDE Crank Nicholson Scheme on the Log of the underlying • Linear interpolation • Good Results 6 -8 July 2000 CEF 2000 Conference Slide N° 12
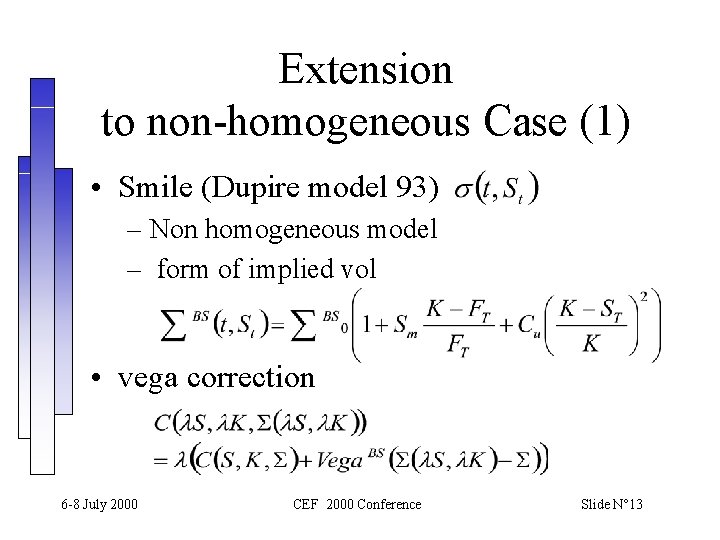
Extension to non-homogeneous Case (1) • Smile (Dupire model 93) – Non homogeneous model – form of implied vol • vega correction 6 -8 July 2000 CEF 2000 Conference Slide N° 13
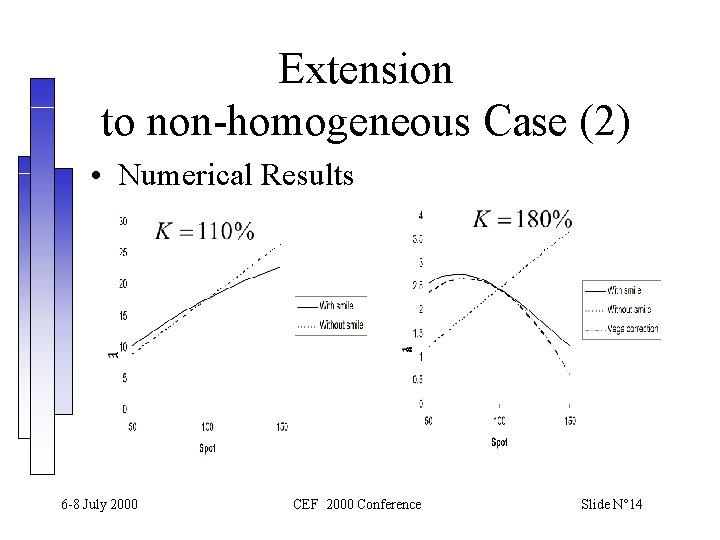
Extension to non-homogeneous Case (2) • Numerical Results 6 -8 July 2000 CEF 2000 Conference Slide N° 14
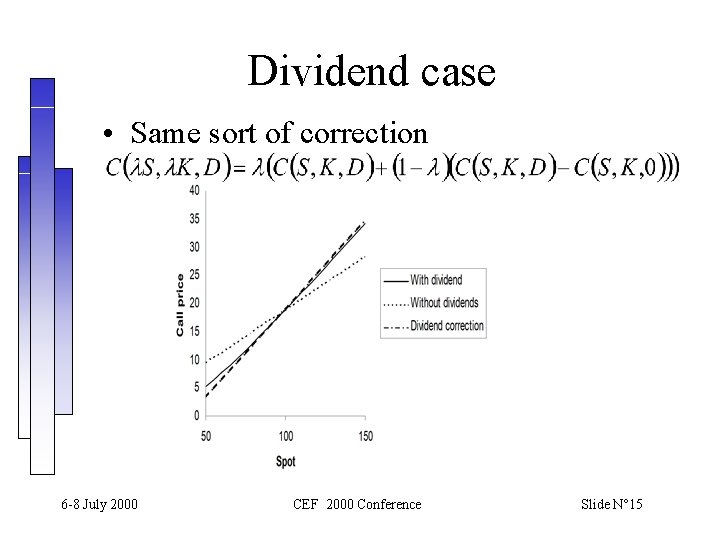
Dividend case • Same sort of correction 6 -8 July 2000 CEF 2000 Conference Slide N° 15
Conclusion • Method efficient for these more realistic cases – smile – non proportional discrete dividends • Extensions – to other options like Ratchet and path dependent options – control of the error 6 -8 July 2000 CEF 2000 Conference Slide N° 16