
SFT COMPLIANCE FORM 61 61 A ORGANISED BY
SFT COMPLIANCE FORM 61 & 61 A ORGANISED BY INCOME-TAX DEPARTMENT DEHRADUN ON MARCH 27, 2018 AT DEHRADUN Presented by: CA Verendra Kalra 1 Assisted by: CA. Ritika Pundir
Reporting in accordance with Rules 114 B to 114 E The Income Tax Rules, 1962 are hereinafter referred to as ‘Rules’ for brevity The Income Tax Act, 1961 is hereinafter referred to as ‘Act’ for brevity SFT – PROCEDURE & COMPLIANCE 2
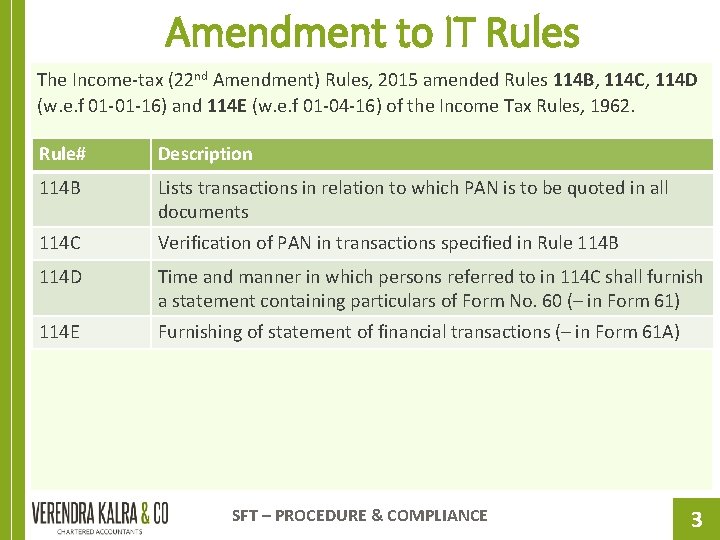
Amendment to IT Rules The Income-tax (22 nd Amendment) Rules, 2015 amended Rules 114 B, 114 C, 114 D (w. e. f 01 -01 -16) and 114 E (w. e. f 01 -04 -16) of the Income Tax Rules, 1962. Rule# Description 114 B Lists transactions in relation to which PAN is to be quoted in all documents 114 C Verification of PAN in transactions specified in Rule 114 B 114 D Time and manner in which persons referred to in 114 C shall furnish a statement containing particulars of Form No. 60 (– in Form 61) 114 E Furnishing of statement of financial transactions (– in Form 61 A) SFT – PROCEDURE & COMPLIANCE 3
Rule 114 B Obtaining Form 60 SFT – PROCEDURE & COMPLIANCE 4
Offline Form No. 60 As per second proviso to Rule 114 B of the Rules, any person who: • does not have a PAN and ; • enters into any transaction specified in Rule 114 B, will make a declaration in Form 60, giving complete particulars of such transaction. The form contains verification that the declarant does not have a PAN and his estimated total income (including income of spouse, minor child etc. as per section 64 of Income-tax Act, 1961) computed in accordance with the provisions of Income-tax Act, 1961 for the financial year in which the above transaction is held will be less than maximum amount not chargeable to tax. Pl. note that in case the total income of such declarant exceeds the maximum amount chargeable to tax, such declarant is required to obtain PAN as per provisions of section 139 A of the Act. SFT – PROCEDURE & COMPLIANCE 5
Consequences of false declaration Any person making a false statement in the declaration in Form 60 shall be liable to prosecution under section 277 of the Income-tax Act, 1961 and on conviction be punishable: • in a case where tax sought to be evaded exceeds 25 lacs, imprisonment of not less than 6 months, extendable to 7 years with fine • in other cases, imprisonment of not less than 3 months, extendable to 2 years with fine The instructions to the Form also state that the person receiving the declaration shall not accept the declaration where the non-agricultural income, as mentioned in the Form, exceeds the maximum amount which is not chargeable to tax, unless PAN is applied for and acknowledgment number of PAN applied for, is duly filled in the Form. SFT – PROCEDURE & COMPLIANCE 6
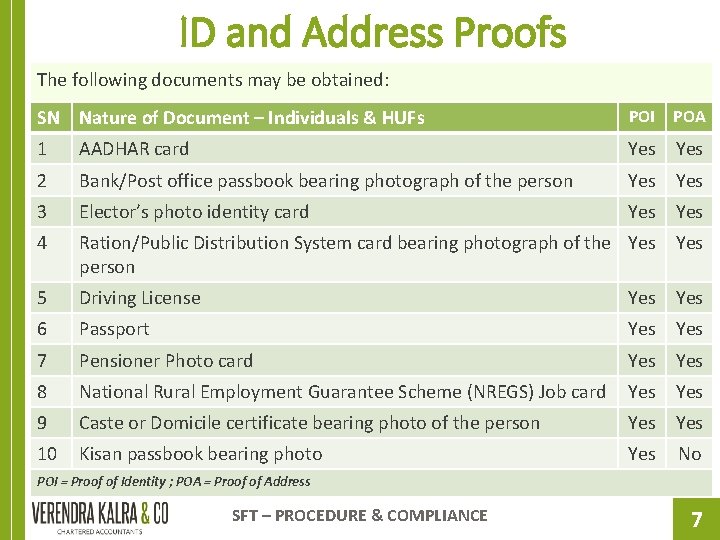
ID and Address Proofs The following documents may be obtained: SN Nature of Document – Individuals & HUFs POI POA 1 AADHAR card Yes 2 Bank/Post office passbook bearing photograph of the person Yes 3 Elector’s photo identity card Yes 4 Ration/Public Distribution System card bearing photograph of the Yes person Yes 5 Driving License Yes 6 Passport Yes 7 Pensioner Photo card Yes 8 National Rural Employment Guarantee Scheme (NREGS) Job card Yes 9 Caste or Domicile certificate bearing photo of the person Yes 10 Kisan passbook bearing photo Yes No POI = Proof of Identity ; POA = Proof of Address SFT – PROCEDURE & COMPLIANCE 7
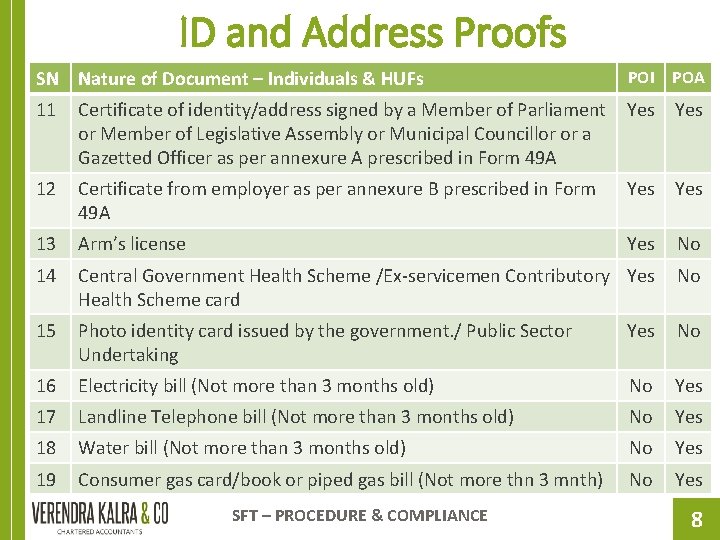
ID and Address Proofs SN Nature of Document – Individuals & HUFs POI POA 11 Certificate of identity/address signed by a Member of Parliament Yes or Member of Legislative Assembly or Municipal Councillor or a Gazetted Officer as per annexure A prescribed in Form 49 A Yes 12 Certificate from employer as per annexure B prescribed in Form 49 A Yes 13 Arm’s license Yes No 14 Central Government Health Scheme /Ex-servicemen Contributory Yes Health Scheme card No 15 Photo identity card issued by the government. / Public Sector Undertaking Yes No 16 Electricity bill (Not more than 3 months old) No Yes 17 Landline Telephone bill (Not more than 3 months old) No Yes 18 Water bill (Not more than 3 months old) No Yes 19 Consumer gas card/book or piped gas bill (Not more thn 3 mnth) No Yes SFT – PROCEDURE & COMPLIANCE 8
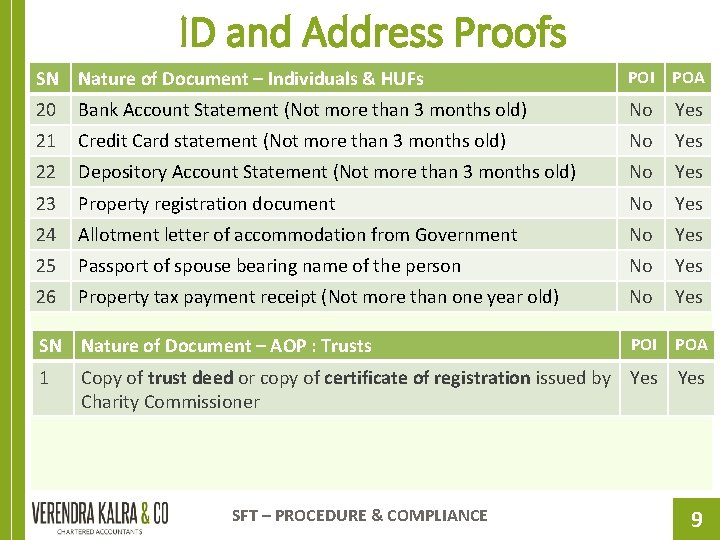
ID and Address Proofs SN Nature of Document – Individuals & HUFs POI POA 20 Bank Account Statement (Not more than 3 months old) No Yes 21 Credit Card statement (Not more than 3 months old) No Yes 22 Depository Account Statement (Not more than 3 months old) No Yes 23 Property registration document No Yes 24 Allotment letter of accommodation from Government No Yes 25 Passport of spouse bearing name of the person No Yes 26 Property tax payment receipt (Not more than one year old) No Yes SN Nature of Document – AOP : Trusts 1 POI POA Copy of trust deed or copy of certificate of registration issued by Yes Charity Commissioner SFT – PROCEDURE & COMPLIANCE Yes 9
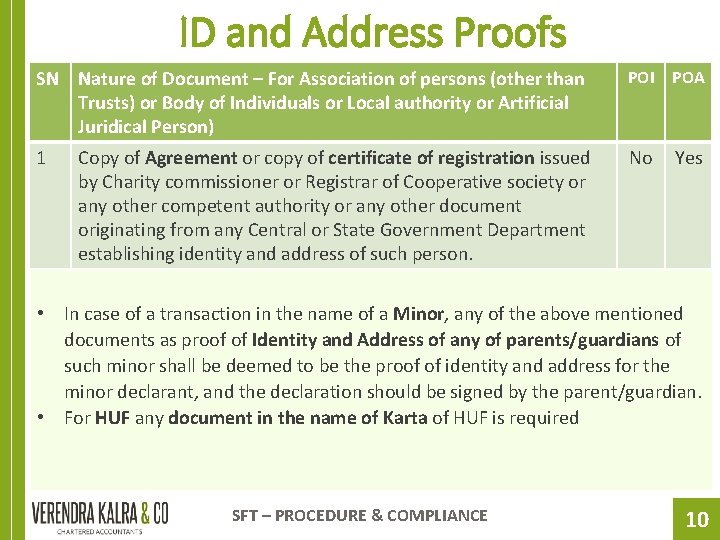
ID and Address Proofs SN Nature of Document – For Association of persons (other than Trusts) or Body of Individuals or Local authority or Artificial Juridical Person) POI POA 1 No Copy of Agreement or copy of certificate of registration issued by Charity commissioner or Registrar of Cooperative society or any other competent authority or any other document originating from any Central or State Government Department establishing identity and address of such person. Yes • In case of a transaction in the name of a Minor, any of the above mentioned documents as proof of Identity and Address of any of parents/guardians of such minor shall be deemed to be the proof of identity and address for the minor declarant, and the declaration should be signed by the parent/guardian. • For HUF any document in the name of Karta of HUF is required SFT – PROCEDURE & COMPLIANCE 10
REPORTING IN FORM 61 Rule 114 B, 114 C & 114 D Transactions in which PAN is not quoted, e-form 61 to be filed with particulars of Form 60 obtained SFT – PROCEDURE & COMPLIANCE 11
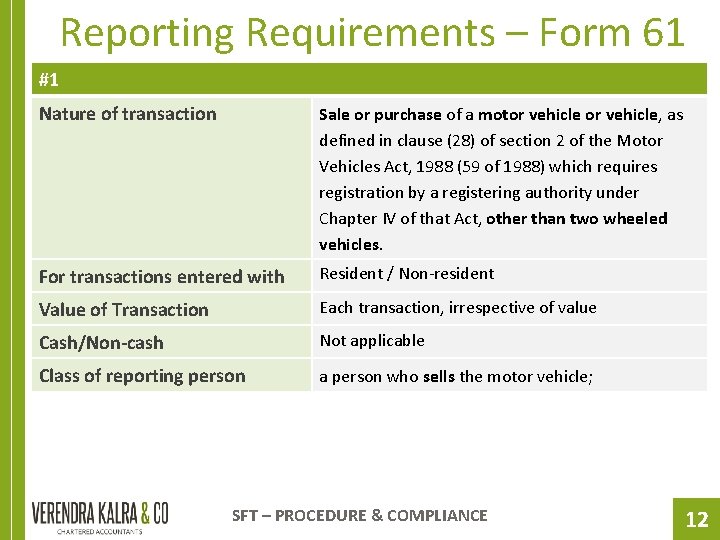
Reporting Requirements – Form 61 #1 Nature of transaction Sale or purchase of a motor vehicle, as defined in clause (28) of section 2 of the Motor Vehicles Act, 1988 (59 of 1988) which requires registration by a registering authority under Chapter IV of that Act, other than two wheeled vehicles. For transactions entered with Resident / Non-resident Value of Transaction Each transaction, irrespective of value Cash/Non-cash Not applicable Class of reporting person a person who sells the motor vehicle; SFT – PROCEDURE & COMPLIANCE 12
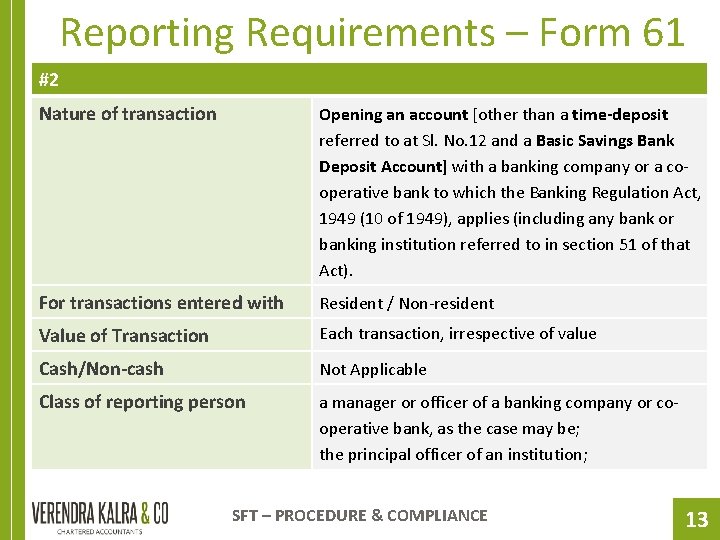
Reporting Requirements – Form 61 #2 Nature of transaction Opening an account [other than a time-deposit referred to at Sl. No. 12 and a Basic Savings Bank Deposit Account] with a banking company or a cooperative bank to which the Banking Regulation Act, 1949 (10 of 1949), applies (including any bank or banking institution referred to in section 51 of that Act). For transactions entered with Resident / Non-resident Value of Transaction Each transaction, irrespective of value Cash/Non-cash Not Applicable Class of reporting person a manager or officer of a banking company or cooperative bank, as the case may be; the principal officer of an institution; SFT – PROCEDURE & COMPLIANCE 13
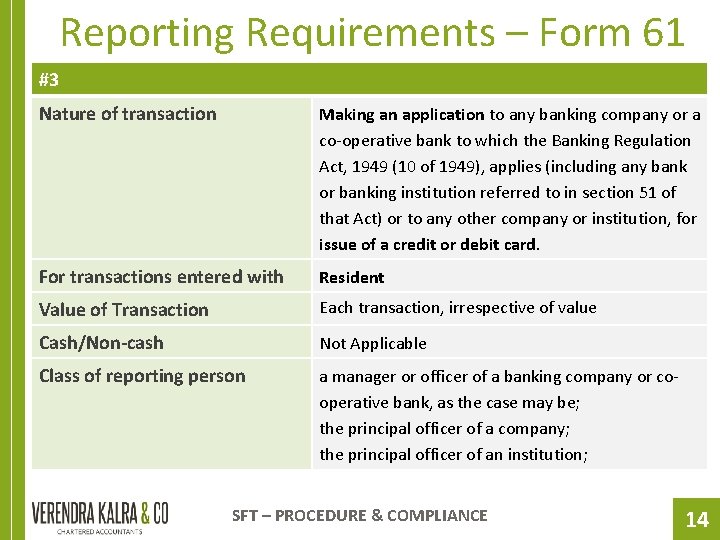
Reporting Requirements – Form 61 #3 Nature of transaction Making an application to any banking company or a co-operative bank to which the Banking Regulation Act, 1949 (10 of 1949), applies (including any bank or banking institution referred to in section 51 of that Act) or to any other company or institution, for issue of a credit or debit card. For transactions entered with Resident Value of Transaction Each transaction, irrespective of value Cash/Non-cash Not Applicable Class of reporting person a manager or officer of a banking company or cooperative bank, as the case may be; the principal officer of a company; the principal officer of an institution; SFT – PROCEDURE & COMPLIANCE 14
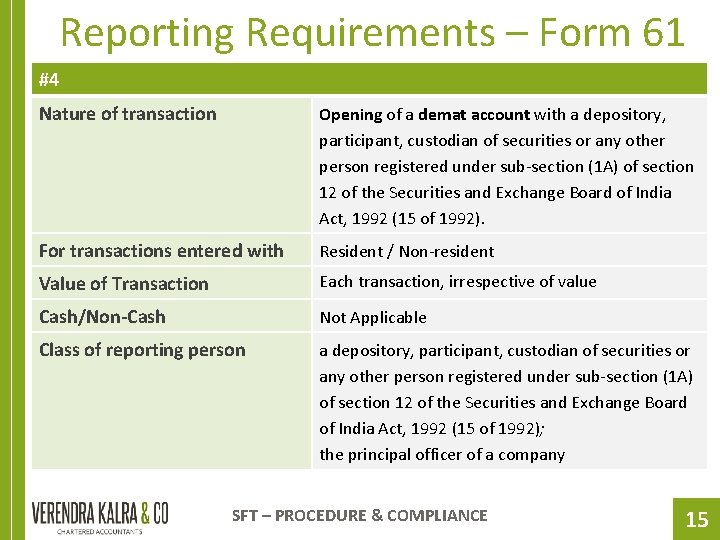
Reporting Requirements – Form 61 #4 Nature of transaction Opening of a demat account with a depository, participant, custodian of securities or any other person registered under sub-section (1 A) of section 12 of the Securities and Exchange Board of India Act, 1992 (15 of 1992). For transactions entered with Resident / Non-resident Value of Transaction Each transaction, irrespective of value Cash/Non-Cash Not Applicable Class of reporting person a depository, participant, custodian of securities or any other person registered under sub-section (1 A) of section 12 of the Securities and Exchange Board of India Act, 1992 (15 of 1992); the principal officer of a company SFT – PROCEDURE & COMPLIANCE 15
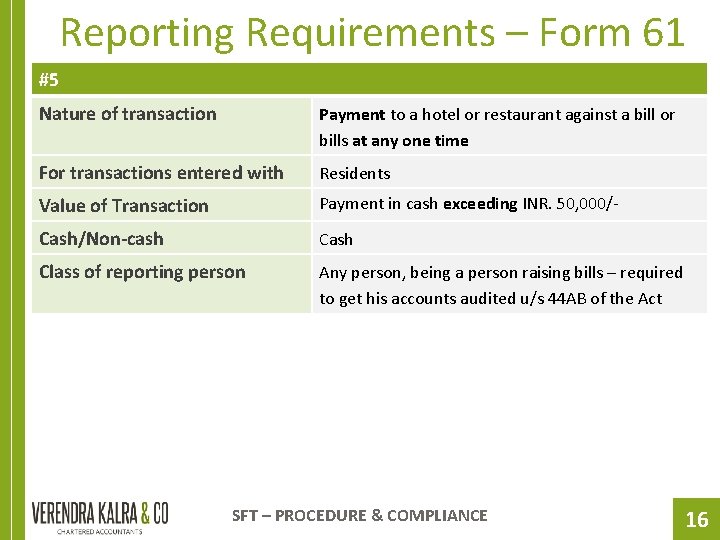
Reporting Requirements – Form 61 #5 Nature of transaction Payment to a hotel or restaurant against a bill or bills at any one time For transactions entered with Residents Value of Transaction Payment in cash exceeding INR. 50, 000/- Cash/Non-cash Class of reporting person Any person, being a person raising bills – required to get his accounts audited u/s 44 AB of the Act SFT – PROCEDURE & COMPLIANCE 16
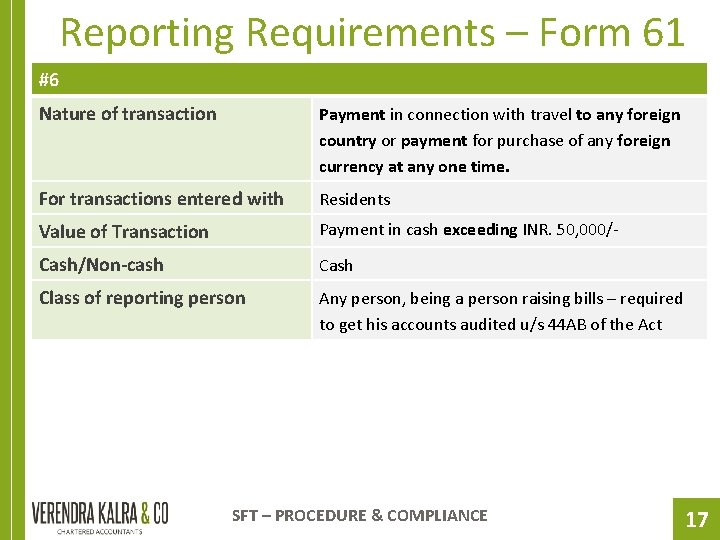
Reporting Requirements – Form 61 #6 Nature of transaction Payment in connection with travel to any foreign country or payment for purchase of any foreign currency at any one time. For transactions entered with Residents Value of Transaction Payment in cash exceeding INR. 50, 000/- Cash/Non-cash Class of reporting person Any person, being a person raising bills – required to get his accounts audited u/s 44 AB of the Act SFT – PROCEDURE & COMPLIANCE 17
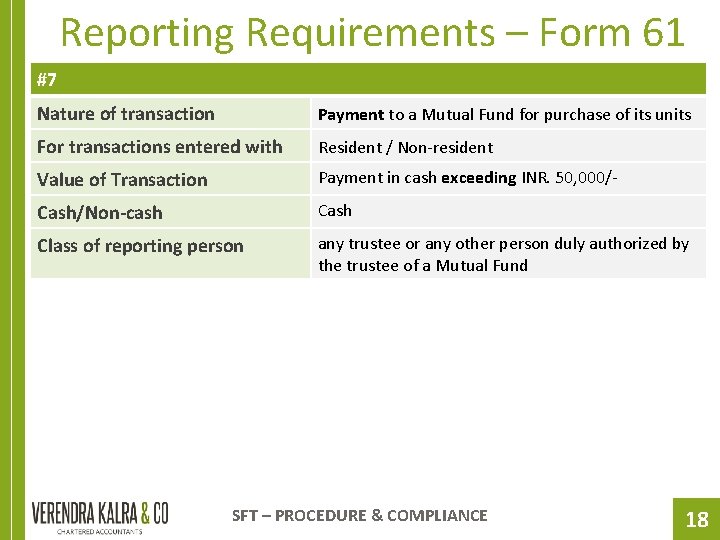
Reporting Requirements – Form 61 #7 Nature of transaction Payment to a Mutual Fund for purchase of its units For transactions entered with Resident / Non-resident Value of Transaction Payment in cash exceeding INR. 50, 000/- Cash/Non-cash Class of reporting person any trustee or any other person duly authorized by the trustee of a Mutual Fund SFT – PROCEDURE & COMPLIANCE 18
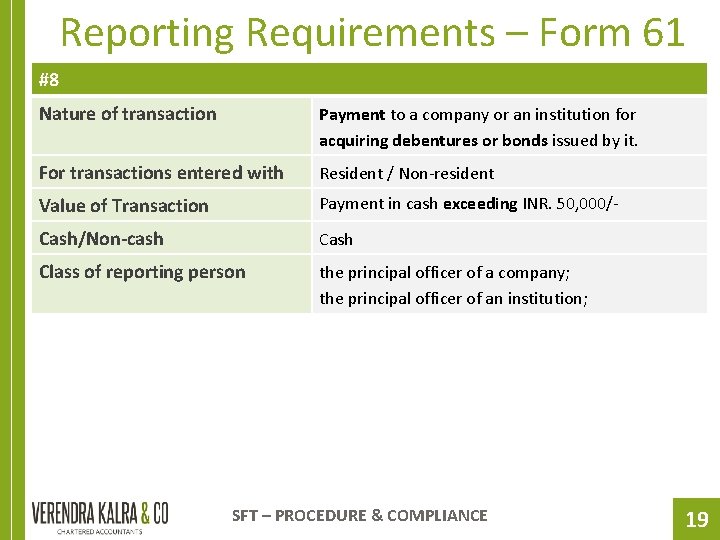
Reporting Requirements – Form 61 #8 Nature of transaction Payment to a company or an institution for acquiring debentures or bonds issued by it. For transactions entered with Resident / Non-resident Value of Transaction Payment in cash exceeding INR. 50, 000/- Cash/Non-cash Class of reporting person the principal officer of a company; the principal officer of an institution; SFT – PROCEDURE & COMPLIANCE 19
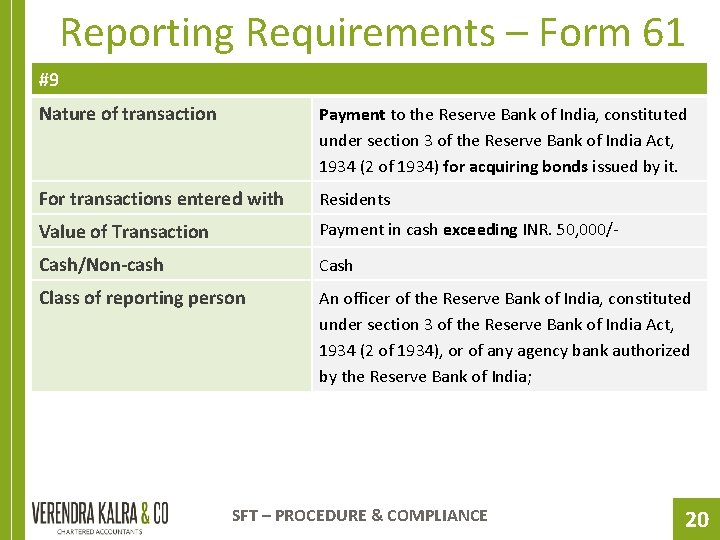
Reporting Requirements – Form 61 #9 Nature of transaction Payment to the Reserve Bank of India, constituted under section 3 of the Reserve Bank of India Act, 1934 (2 of 1934) for acquiring bonds issued by it. For transactions entered with Residents Value of Transaction Payment in cash exceeding INR. 50, 000/- Cash/Non-cash Class of reporting person An officer of the Reserve Bank of India, constituted under section 3 of the Reserve Bank of India Act, 1934 (2 of 1934), or of any agency bank authorized by the Reserve Bank of India; SFT – PROCEDURE & COMPLIANCE 20
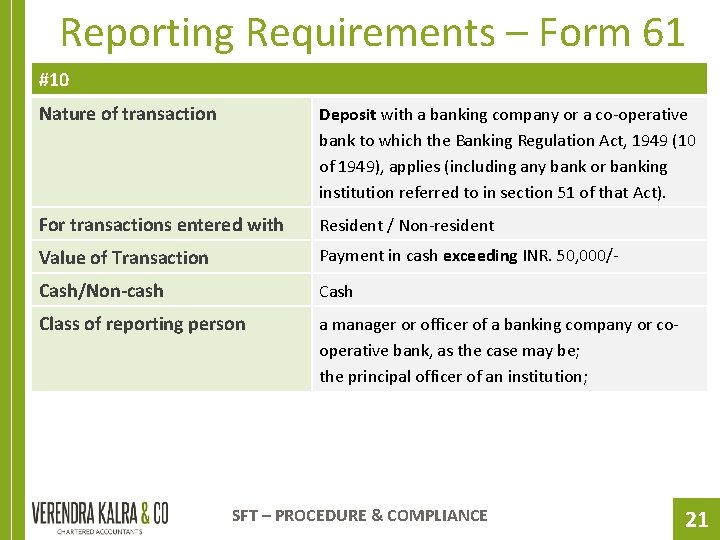
Reporting Requirements – Form 61 #10 Nature of transaction Deposit with a banking company or a co-operative bank to which the Banking Regulation Act, 1949 (10 of 1949), applies (including any bank or banking institution referred to in section 51 of that Act). For transactions entered with Resident / Non-resident Value of Transaction Payment in cash exceeding INR. 50, 000/- Cash/Non-cash Class of reporting person a manager or officer of a banking company or cooperative bank, as the case may be; the principal officer of an institution; SFT – PROCEDURE & COMPLIANCE 21
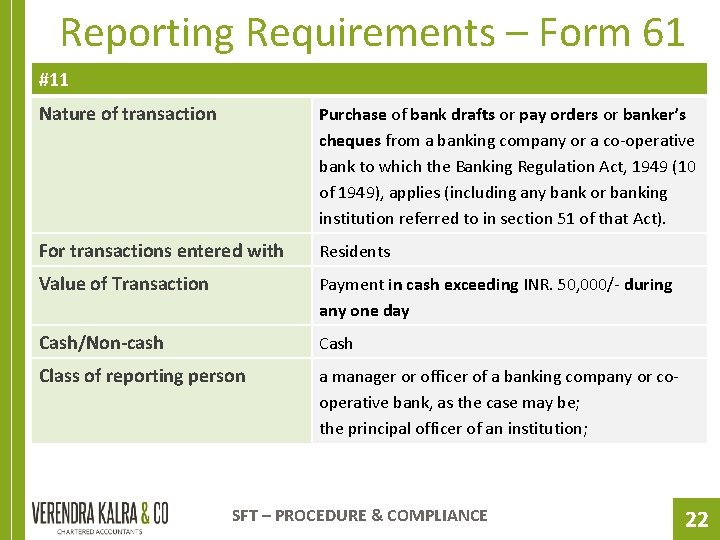
Reporting Requirements – Form 61 #11 Nature of transaction Purchase of bank drafts or pay orders or banker’s cheques from a banking company or a co-operative bank to which the Banking Regulation Act, 1949 (10 of 1949), applies (including any bank or banking institution referred to in section 51 of that Act). For transactions entered with Residents Value of Transaction Payment in cash exceeding INR. 50, 000/- during any one day Cash/Non-cash Class of reporting person a manager or officer of a banking company or cooperative bank, as the case may be; the principal officer of an institution; SFT – PROCEDURE & COMPLIANCE 22
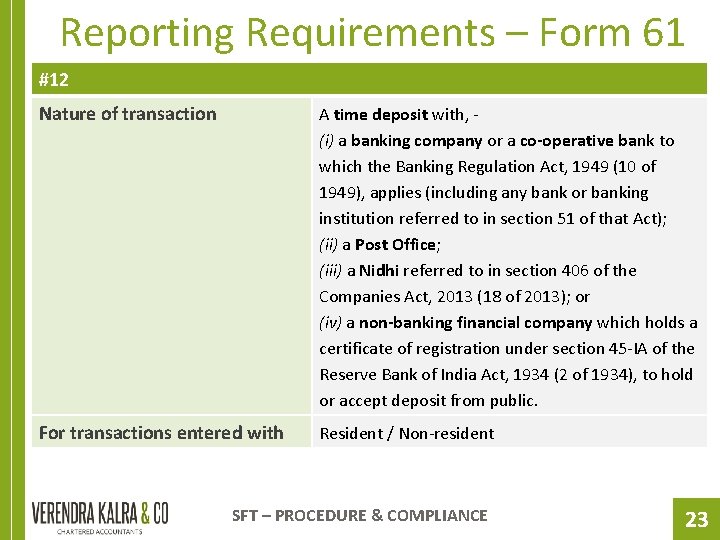
Reporting Requirements – Form 61 #12 Nature of transaction A time deposit with, - (i) a banking company or a co-operative bank to which the Banking Regulation Act, 1949 (10 of 1949), applies (including any bank or banking institution referred to in section 51 of that Act); (ii) a Post Office; (iii) a Nidhi referred to in section 406 of the Companies Act, 2013 (18 of 2013); or (iv) a non-banking financial company which holds a certificate of registration under section 45 -IA of the Reserve Bank of India Act, 1934 (2 of 1934), to hold or accept deposit from public. For transactions entered with Resident / Non-resident SFT – PROCEDURE & COMPLIANCE 23
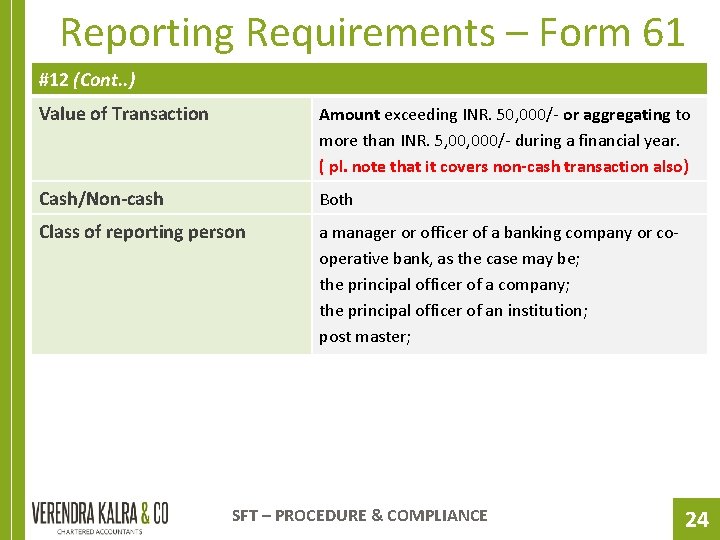
Reporting Requirements – Form 61 #12 (Cont. . ) Value of Transaction Amount exceeding INR. 50, 000/- or aggregating to more than INR. 5, 000/- during a financial year. ( pl. note that it covers non-cash transaction also) Cash/Non-cash Both Class of reporting person a manager or officer of a banking company or cooperative bank, as the case may be; the principal officer of a company; the principal officer of an institution; post master; SFT – PROCEDURE & COMPLIANCE 24
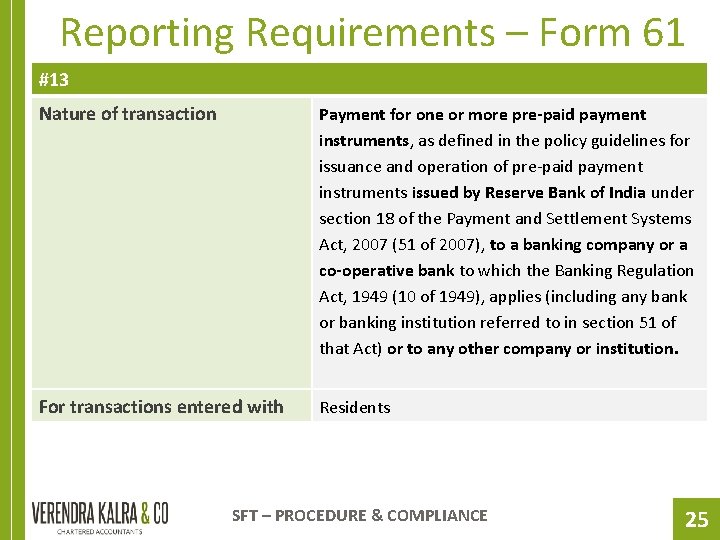
Reporting Requirements – Form 61 #13 Nature of transaction Payment for one or more pre-paid payment instruments, as defined in the policy guidelines for issuance and operation of pre-paid payment instruments issued by Reserve Bank of India under section 18 of the Payment and Settlement Systems Act, 2007 (51 of 2007), to a banking company or a co-operative bank to which the Banking Regulation Act, 1949 (10 of 1949), applies (including any bank or banking institution referred to in section 51 of that Act) or to any other company or institution. For transactions entered with Residents SFT – PROCEDURE & COMPLIANCE 25
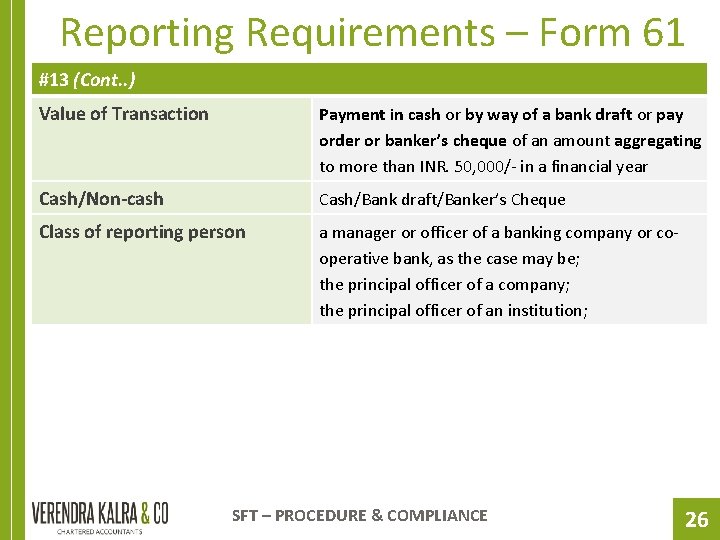
Reporting Requirements – Form 61 #13 (Cont. . ) Value of Transaction Payment in cash or by way of a bank draft or pay order or banker’s cheque of an amount aggregating to more than INR. 50, 000/- in a financial year Cash/Non-cash Cash/Bank draft/Banker’s Cheque Class of reporting person a manager or officer of a banking company or cooperative bank, as the case may be; the principal officer of a company; the principal officer of an institution; SFT – PROCEDURE & COMPLIANCE 26
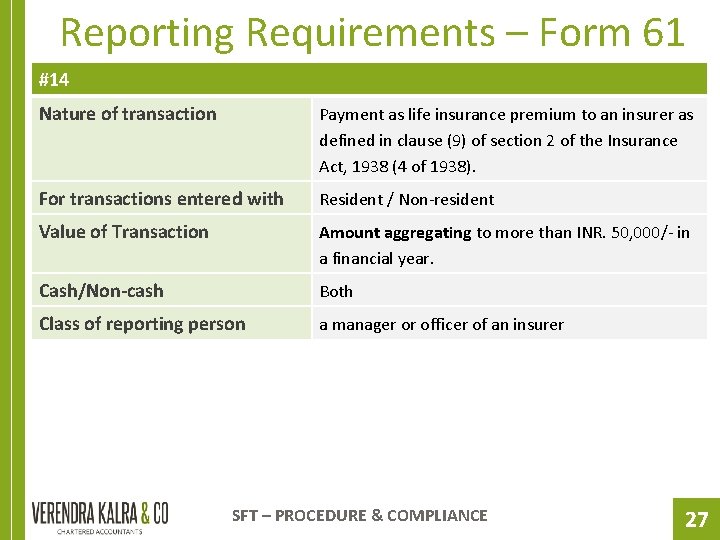
Reporting Requirements – Form 61 #14 Nature of transaction Payment as life insurance premium to an insurer as defined in clause (9) of section 2 of the Insurance Act, 1938 (4 of 1938). For transactions entered with Resident / Non-resident Value of Transaction Amount aggregating to more than INR. 50, 000/- in a financial year. Cash/Non-cash Both Class of reporting person a manager or officer of an insurer SFT – PROCEDURE & COMPLIANCE 27
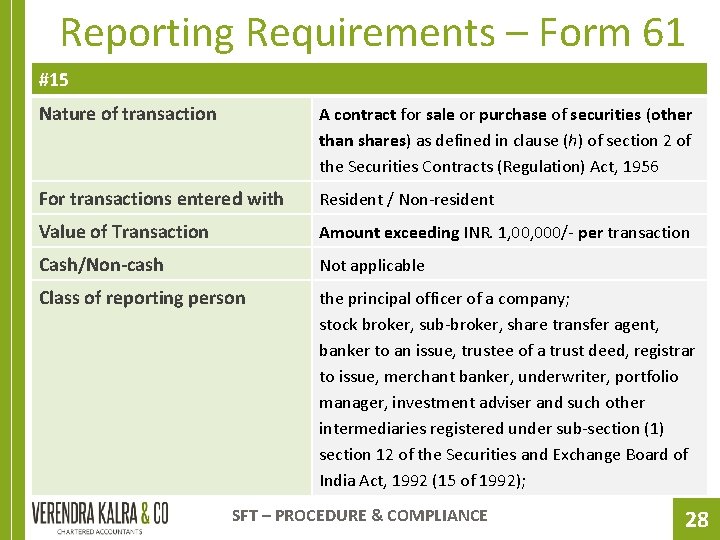
Reporting Requirements – Form 61 #15 Nature of transaction A contract for sale or purchase of securities (other than shares) as defined in clause (h) of section 2 of the Securities Contracts (Regulation) Act, 1956 For transactions entered with Resident / Non-resident Value of Transaction Amount exceeding INR. 1, 000/- per transaction Cash/Non-cash Not applicable Class of reporting person the principal officer of a company; stock broker, sub-broker, share transfer agent, banker to an issue, trustee of a trust deed, registrar to issue, merchant banker, underwriter, portfolio manager, investment adviser and such other intermediaries registered under sub-section (1) section 12 of the Securities and Exchange Board of India Act, 1992 (15 of 1992); SFT – PROCEDURE & COMPLIANCE 28
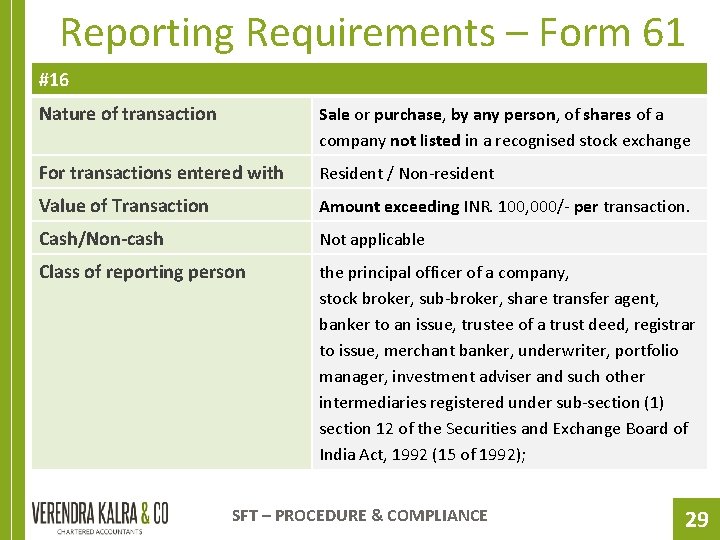
Reporting Requirements – Form 61 #16 Nature of transaction Sale or purchase, by any person, of shares of a company not listed in a recognised stock exchange For transactions entered with Resident / Non-resident Value of Transaction Amount exceeding INR. 100, 000/- per transaction. Cash/Non-cash Not applicable Class of reporting person the principal officer of a company, stock broker, sub-broker, share transfer agent, banker to an issue, trustee of a trust deed, registrar to issue, merchant banker, underwriter, portfolio manager, investment adviser and such other intermediaries registered under sub-section (1) section 12 of the Securities and Exchange Board of India Act, 1992 (15 of 1992); SFT – PROCEDURE & COMPLIANCE 29
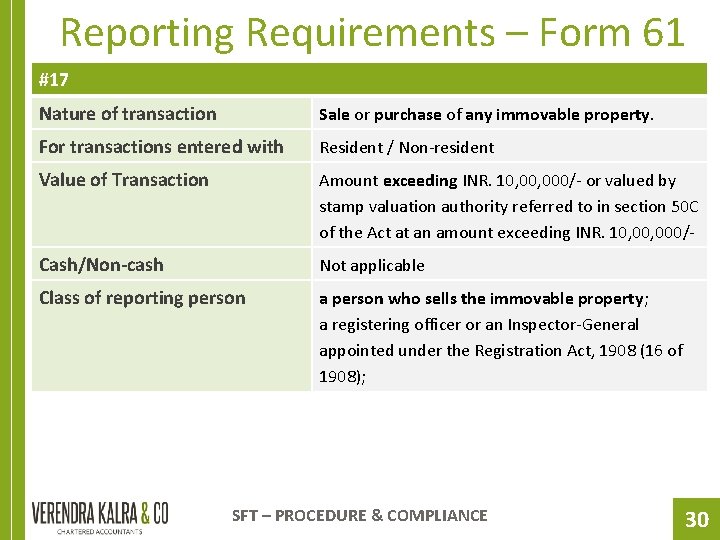
Reporting Requirements – Form 61 #17 Nature of transaction Sale or purchase of any immovable property. For transactions entered with Resident / Non-resident Value of Transaction Amount exceeding INR. 10, 000/- or valued by stamp valuation authority referred to in section 50 C of the Act at an amount exceeding INR. 10, 000/- Cash/Non-cash Not applicable Class of reporting person a person who sells the immovable property; a registering officer or an Inspector-General appointed under the Registration Act, 1908 (16 of 1908); SFT – PROCEDURE & COMPLIANCE 30
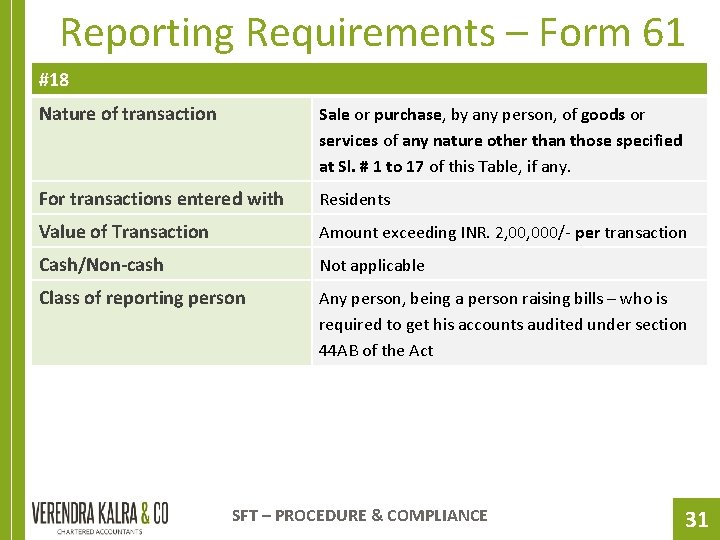
Reporting Requirements – Form 61 #18 Nature of transaction Sale or purchase, by any person, of goods or services of any nature other than those specified at Sl. # 1 to 17 of this Table, if any. For transactions entered with Residents Value of Transaction Amount exceeding INR. 2, 000/- per transaction Cash/Non-cash Not applicable Class of reporting person Any person, being a person raising bills – who is required to get his accounts audited under section 44 AB of the Act SFT – PROCEDURE & COMPLIANCE 31
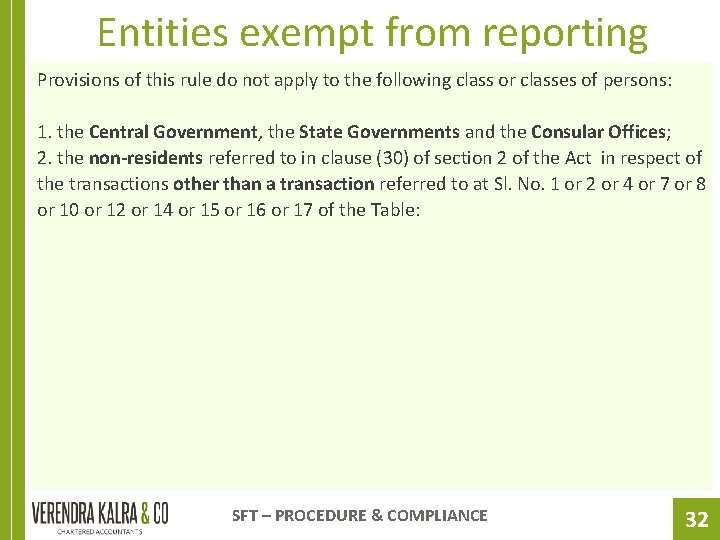
Entities exempt from reporting Provisions of this rule do not apply to the following class or classes of persons: 1. the Central Government, the State Governments and the Consular Offices; 2. the non-residents referred to in clause (30) of section 2 of the Act in respect of the transactions other than a transaction referred to at Sl. No. 1 or 2 or 4 or 7 or 8 or 10 or 12 or 14 or 15 or 16 or 17 of the Table: SFT – PROCEDURE & COMPLIANCE 32
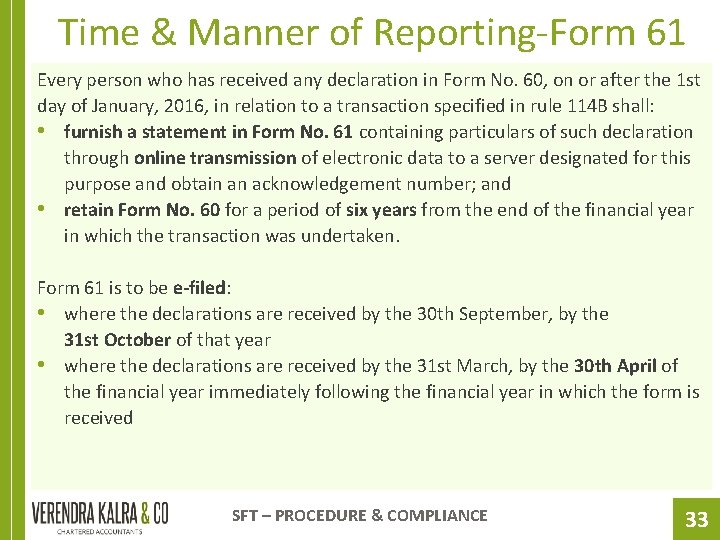
Time & Manner of Reporting-Form 61 Every person who has received any declaration in Form No. 60, on or after the 1 st day of January, 2016, in relation to a transaction specified in rule 114 B shall: • furnish a statement in Form No. 61 containing particulars of such declaration through online transmission of electronic data to a server designated for this purpose and obtain an acknowledgement number; and • retain Form No. 60 for a period of six years from the end of the financial year in which the transaction was undertaken. Form 61 is to be e-filed: • where the declarations are received by the 30 th September, by the 31 st October of that year • where the declarations are received by the 31 st March, by the 30 th April of the financial year immediately following the financial year in which the form is received SFT – PROCEDURE & COMPLIANCE 33
REPORTING IN FORM 61 A Rule 114 E Furnishing statement of financial transaction or reportable account by specified persons. SFT – PROCEDURE & COMPLIANCE 34
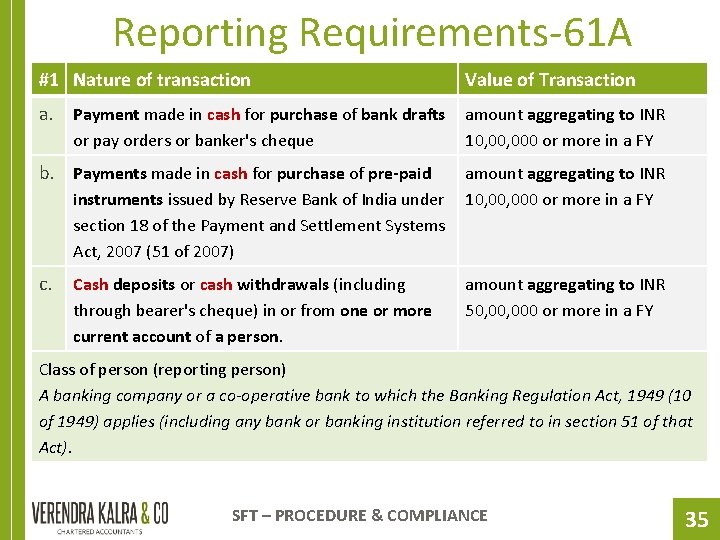
Reporting Requirements-61 A #1 Nature of transaction a. Value of Transaction Payment made in cash for purchase of bank drafts amount aggregating to INR or pay orders or banker's cheque 10, 000 or more in a FY b. Payments made in cash for purchase of pre-paid amount aggregating to INR instruments issued by Reserve Bank of India under 10, 000 or more in a FY section 18 of the Payment and Settlement Systems Act, 2007 (51 of 2007) c. Cash deposits or cash withdrawals (including through bearer's cheque) in or from one or more current account of a person. amount aggregating to INR 50, 000 or more in a FY Class of person (reporting person) A banking company or a co-operative bank to which the Banking Regulation Act, 1949 (10 of 1949) applies (including any bank or banking institution referred to in section 51 of that Act). SFT – PROCEDURE & COMPLIANCE 35
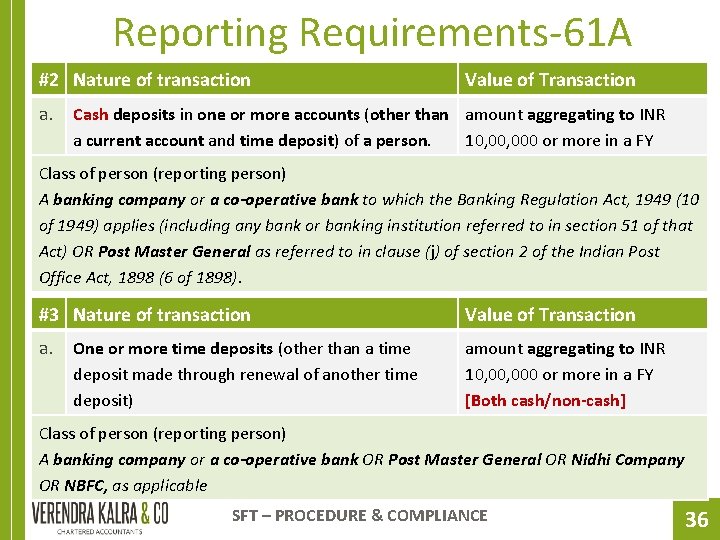
Reporting Requirements-61 A #2 Nature of transaction a. Value of Transaction Cash deposits in one or more accounts (other than amount aggregating to INR a current account and time deposit) of a person. 10, 000 or more in a FY Class of person (reporting person) A banking company or a co-operative bank to which the Banking Regulation Act, 1949 (10 of 1949) applies (including any bank or banking institution referred to in section 51 of that Act) OR Post Master General as referred to in clause (j) of section 2 of the Indian Post Office Act, 1898 (6 of 1898). #3 Nature of transaction Value of Transaction a. amount aggregating to INR 10, 000 or more in a FY [Both cash/non-cash] One or more time deposits (other than a time deposit made through renewal of another time deposit) Class of person (reporting person) A banking company or a co-operative bank OR Post Master General OR Nidhi Company OR NBFC, as applicable SFT – PROCEDURE & COMPLIANCE 36
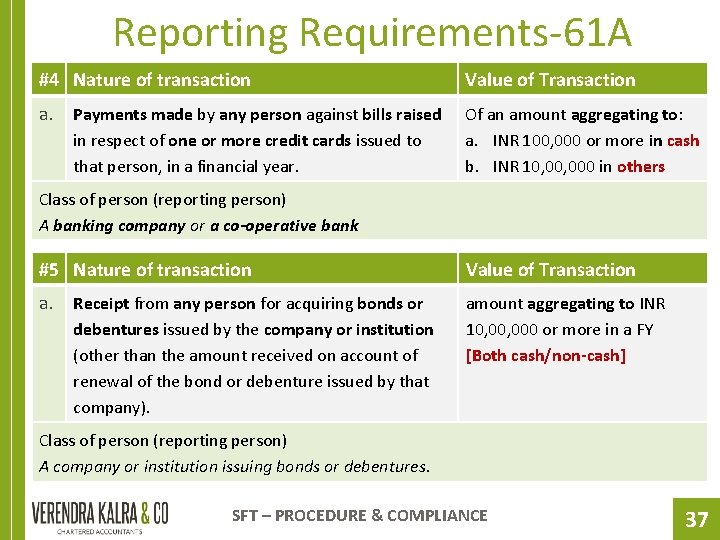
Reporting Requirements-61 A #4 Nature of transaction Value of Transaction a. Of an amount aggregating to: a. INR 100, 000 or more in cash b. INR 10, 000 in others Payments made by any person against bills raised in respect of one or more credit cards issued to that person, in a financial year. Class of person (reporting person) A banking company or a co-operative bank #5 Nature of transaction Value of Transaction a. amount aggregating to INR 10, 000 or more in a FY [Both cash/non-cash] Receipt from any person for acquiring bonds or debentures issued by the company or institution (other than the amount received on account of renewal of the bond or debenture issued by that company). Class of person (reporting person) A company or institution issuing bonds or debentures. SFT – PROCEDURE & COMPLIANCE 37
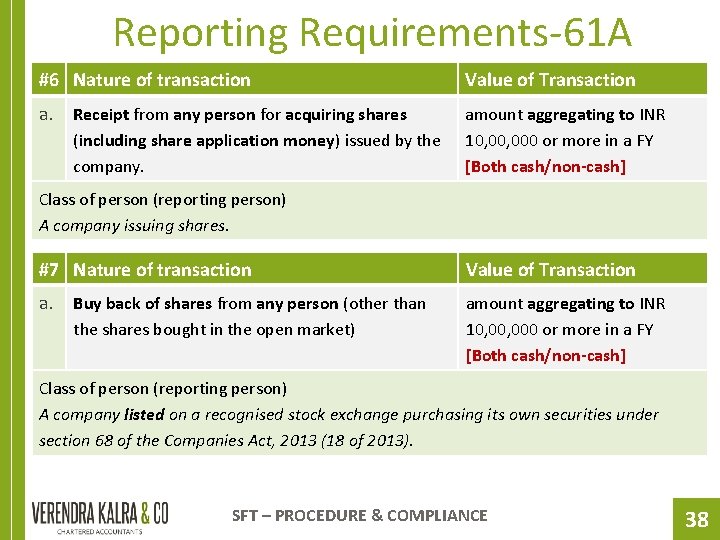
Reporting Requirements-61 A #6 Nature of transaction Value of Transaction a. amount aggregating to INR 10, 000 or more in a FY [Both cash/non-cash] Receipt from any person for acquiring shares (including share application money) issued by the company. Class of person (reporting person) A company issuing shares. #7 Nature of transaction Value of Transaction a. amount aggregating to INR 10, 000 or more in a FY [Both cash/non-cash] Buy back of shares from any person (other than the shares bought in the open market) Class of person (reporting person) A company listed on a recognised stock exchange purchasing its own securities under section 68 of the Companies Act, 2013 (18 of 2013). SFT – PROCEDURE & COMPLIANCE 38
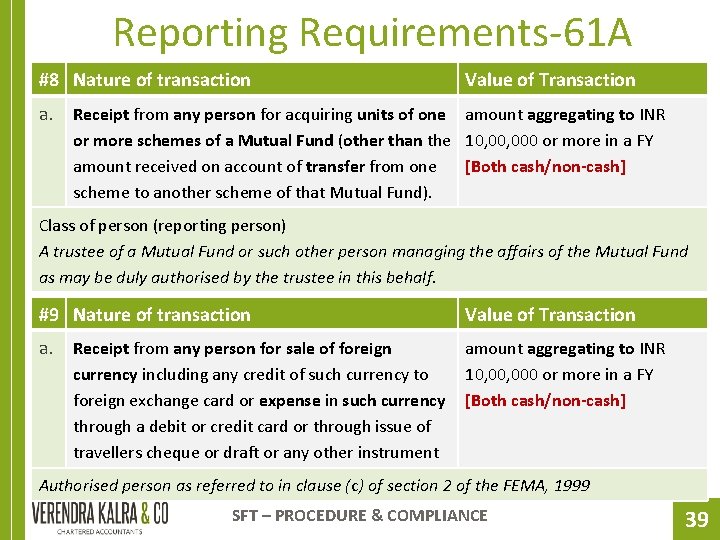
Reporting Requirements-61 A #8 Nature of transaction a. Value of Transaction Receipt from any person for acquiring units of one amount aggregating to INR or more schemes of a Mutual Fund (other than the 10, 000 or more in a FY amount received on account of transfer from one [Both cash/non-cash] scheme to another scheme of that Mutual Fund). Class of person (reporting person) A trustee of a Mutual Fund or such other person managing the affairs of the Mutual Fund as may be duly authorised by the trustee in this behalf. #9 Nature of transaction a. Value of Transaction Receipt from any person for sale of foreign amount aggregating to INR currency including any credit of such currency to 10, 000 or more in a FY foreign exchange card or expense in such currency [Both cash/non-cash] through a debit or credit card or through issue of travellers cheque or draft or any other instrument Authorised person as referred to in clause (c) of section 2 of the FEMA, 1999 SFT – PROCEDURE & COMPLIANCE 39
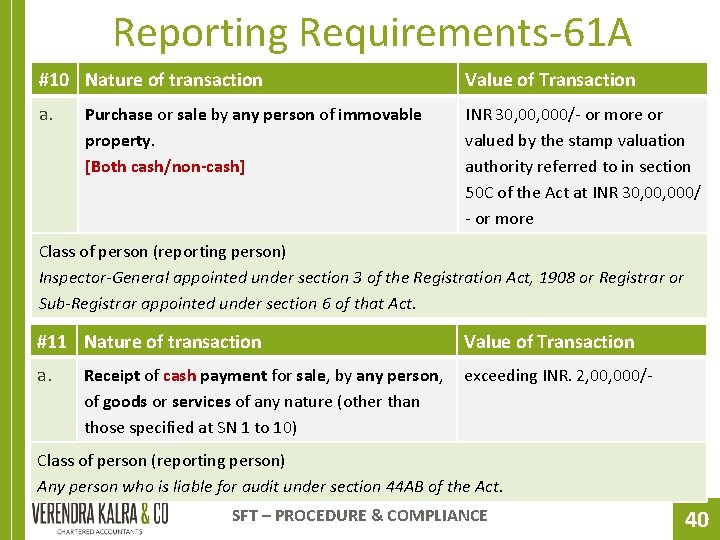
Reporting Requirements-61 A #10 Nature of transaction Value of Transaction a. INR 30, 000/- or more or valued by the stamp valuation authority referred to in section 50 C of the Act at INR 30, 000/ - or more Purchase or sale by any person of immovable property. [Both cash/non-cash] Class of person (reporting person) Inspector-General appointed under section 3 of the Registration Act, 1908 or Registrar or Sub-Registrar appointed under section 6 of that Act. #11 Nature of transaction a. Value of Transaction Receipt of cash payment for sale, by any person, exceeding INR. 2, 000/of goods or services of any nature (other than those specified at SN 1 to 10) Class of person (reporting person) Any person who is liable for audit under section 44 AB of the Act. SFT – PROCEDURE & COMPLIANCE 40
Aggregation Rule The reporting person shall, while aggregating the amounts for determining the threshold amount for reporting in respect of the person for whom reporting is being done: • take into account all the accounts of the same nature in respect of that person during the financial year • aggregate all the transactions of the same nature recorded in respect of that person during the financial year • attribute the entire value of the transaction or the aggregated value of all the transactions to all the persons, in a case where the account is maintained or transaction is recorded in the name of more than one person. • apply the threshold limit separately to deposits and withdrawals in respect of transaction in one or more current accounts of a person The above rule of aggregation is however, not applicable to: • Purchase or sale by any person of immovable property. • Receipt of cash payment for sale, of goods or services of any nature SFT – PROCEDURE & COMPLIANCE 41
Designated Director "Designated Director" means a person designated by the reporting person to ensure overall compliance with the obligations imposed under section 285 BA of the Act and the rules 114 B to 114 D and this rule and includes • the Managing Director or a whole-time Director, as defined in the Companies Act, 2013 (18 of 2013), duly authorised by the Board of Directors if the reporting person is a company; • the managing partner if the reporting person is a partnership firm; • the proprietor if the reporting person is a proprietorship concern; • the managing trustee if the reporting person is a trust; • a person or individual, as the case may be, who controls and manages the affairs of the reporting entity if the reporting person is, an unincorporated association or, a body of individuals or, any other person "Principal Officer" means an officer designated by the reporting person SFT – PROCEDURE & COMPLIANCE 42
Other Regulations for Form 61 A • The return in Form No. 61 A referred to in sub-rule (1) shall be furnished to the • • Director of Income-tax (Intelligence and Criminal Investigation) or the Joint Director of Income-tax (Intelligence and Criminal Investigation) through online Under the digital signature of Designated Director The statement of financial transactions referred to in sub-rule (1) shall be furnished on or before the 31 st May, immediately following the financial year in which the transaction is registered or recorded Provided that where the reporting person is a non-resident, the statement may be signed, verified and furnished by a person who holds a valid power of attorney from such Designated Director. The statement of financial transaction referred to in sub-rule (1) shall be signed, verified and furnished by the Designated Director specified in sub-rule (6) SFT – PROCEDURE & COMPLIANCE 43
Consequences of non-furnishing 61 A Penalty u/s 271 FA: Penalty of INR 100/- for every day during which such failure continues. (increased to INR 500/- for each day of continuing default w. e. f April 01, 2018) Issuance of Notice – inaccuracy & penalty Where the statement is not furnished the same within specified time, the prescribed income-tax authority may serve a notice requiring furnishing such statement within a period not exceeding 30 days from the date of service of such notice. Where the statement is not furnished within the period specified in the notice, penalty of INR 500/- for every day during which the failure continues would be levied, starting from expiry of time specified in notice for compliance. (increased to INR 1, 000/- for each day of continuing default w. e. f April 01, 2018) If any inaccuracy is discovered in information provided in the statement, the person shall within a period of 10 days inform the income-tax authority, the inaccuracy in such statement and furnish the correct information in such manner as may be prescribed. SFT – PROCEDURE & COMPLIANCE 44
Notice of defect Where the prescribed income-tax authority considers that the statement furnished is defective, he may intimate the defect to the person who has furnished such statement and give him an opportunity of rectifying the defect within a period of 30 days from the date of such intimation or within such further period which, on an application made in this behalf, the said income-tax authority may, in his discretion, allow. If the defect is not rectified within the said period of 30 days or, as the case may be, the further period so allowed, then, notwithstanding anything contained in any other provision of this Act, such statement shall be treated as an invalid statement and the provisions of this Act shall apply as if such person had failed to furnish the statement. SFT – PROCEDURE & COMPLIANCE 45
Form 61 & 61 A Registration and E-filing SFT – PROCEDURE & COMPLIANCE 46
Procedure Users who have already registered in e-Filing portal can use this functionality to generate ITDREIN (Income Tax Department Reporting Entity Identification Number) and upload certain forms in e-Filing portal using the generated ITDREIN is the Unique ID issued by ITD which will be communicated by ITD after the registration of the reporting entity with ITD. The ITDREIN is a 16 -character identification number. The procedure and steps for registration for Forms 61 & 61 A are detailed in the User Manual for ITDREIN Registration and Upload of Form 61 and Form 61 A of the Income-tax Department. For brevity, the steps are summarized as under: 1. Generation of ITDREIN on the Income-tax login of the reporting person 2. Adding authorized person (Pl. note Principal Officer can only view the compliance, the designated director can both view and submit the compliance on the portal) 3. Uploading the Forms 4. Processing of the Forms – ‘Accepted’ or ‘Rejected’ A separate guide for filing the SFT form has also been published by the department, in January 2017, ‘SFT Report Generation Utility User Guide Version 1. 0’ SFT – PROCEDURE & COMPLIANCE 47
SFT Preliminary Response Rule 114 E SFT – PROCEDURE & COMPLIANCE 48
No reportable transaction The registration of reporting person (ITDREIN registration) is mandatory only when at least one of the Transaction Type is reportable. A functionality "SFT Preliminary Response" has been provided on the e. Filing portal for the reporting persons to indicate that a specified transaction type is not reportable for the year. In case there are reportable transactions for the year, the reporting person/entity is required to register with the Income Tax Department and generate Income Tax Department Reporting Entity Identification Number (ITDREIN). Preliminary SFT is required to be filed only in cases where there are no reportable transactions. In case there are reportable transactions, and an option is selected in P-SFT, the requisite form 61 A will be required to be filed separately. Also, pl. note that Preliminary SFT is only in respect of transactions reportable in Form 61 A, and not Form 61. SFT – PROCEDURE & COMPLIANCE 49
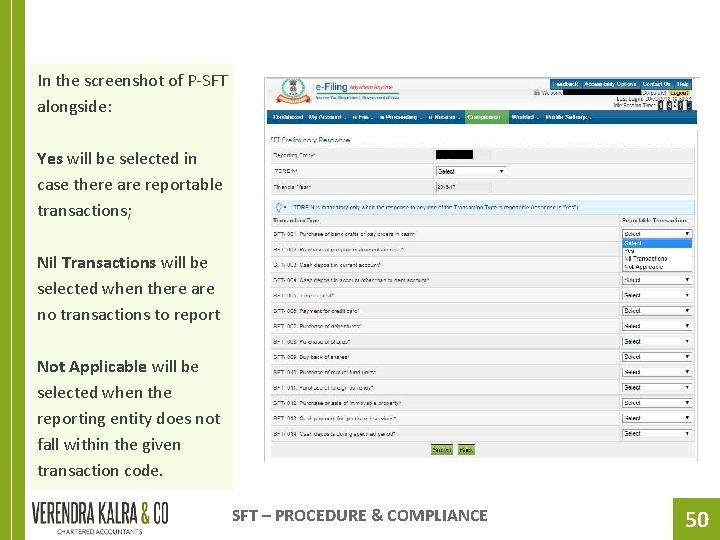
In the screenshot of P-SFT alongside: Yes will be selected in case there are reportable transactions; Nil Transactions will be selected when there are no transactions to report Not Applicable will be selected when the reporting entity does not fall within the given transaction code. SFT – PROCEDURE & COMPLIANCE 50
Thank you. SFT – PROCEDURE & COMPLIANCE 51
- Slides: 51