
Session 11 BreakEven Analysis Chapter Content BreakEven Analysis
Session 11 Break-Even Analysis
Chapter Content Break-Even Analysis Formulae Multiproduct Limitations
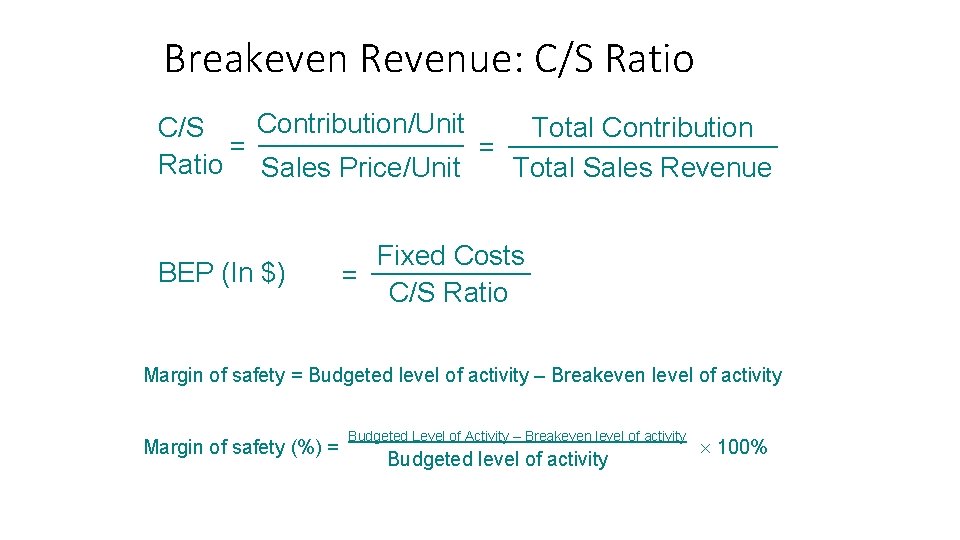
Breakeven Revenue: C/S Ratio Contribution/Unit Total Contribution C/S = = Ratio Sales Price/Unit Total Sales Revenue BEP (In $) Fixed Costs = C/S Ratio Margin of safety = Budgeted level of activity – Breakeven level of activity Margin of safety (%) = Budgeted Level of Activity – Breakeven level of activity Budgeted level of activity 100%
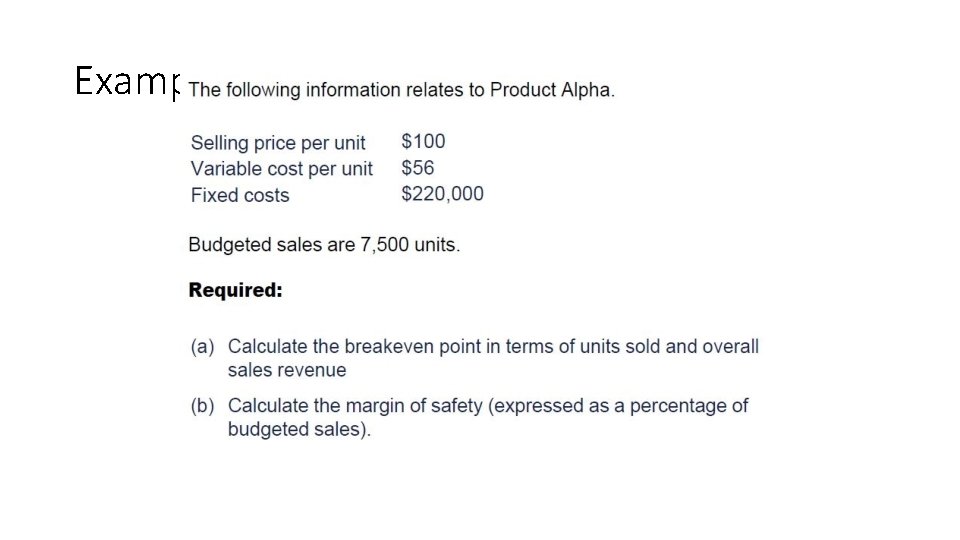
Example. .
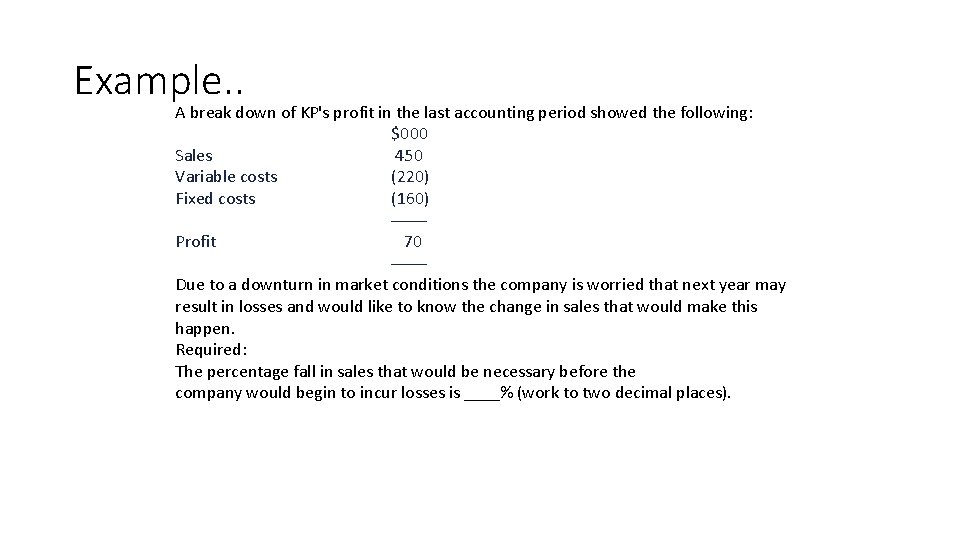
Example. . A break down of KP's profit in the last accounting period showed the following: $000 Sales 450 Variable costs (220) Fixed costs (160) –––– Profit 70 –––– Due to a downturn in market conditions the company is worried that next year may result in losses and would like to know the change in sales that would make this happen. Required: The percentage fall in sales that would be necessary before the company would begin to incur losses is ____% (work to two decimal places).
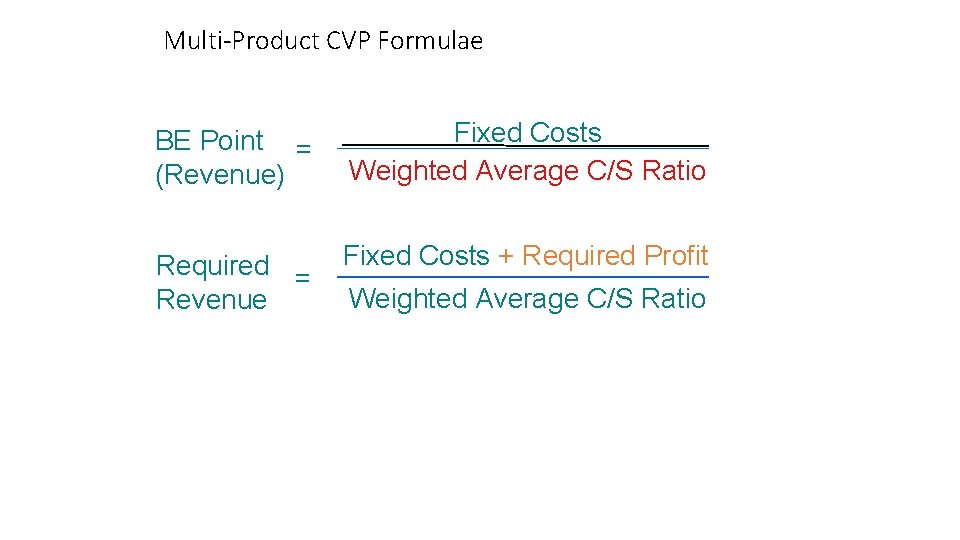
Multi-Product CVP Formulae BE Point = (Revenue) Fixed Costs Ratio C/S Ratio Weighted. C/S Average Required = Revenue Fixed Costs + Required Profit Weighted Average C/S Ratio
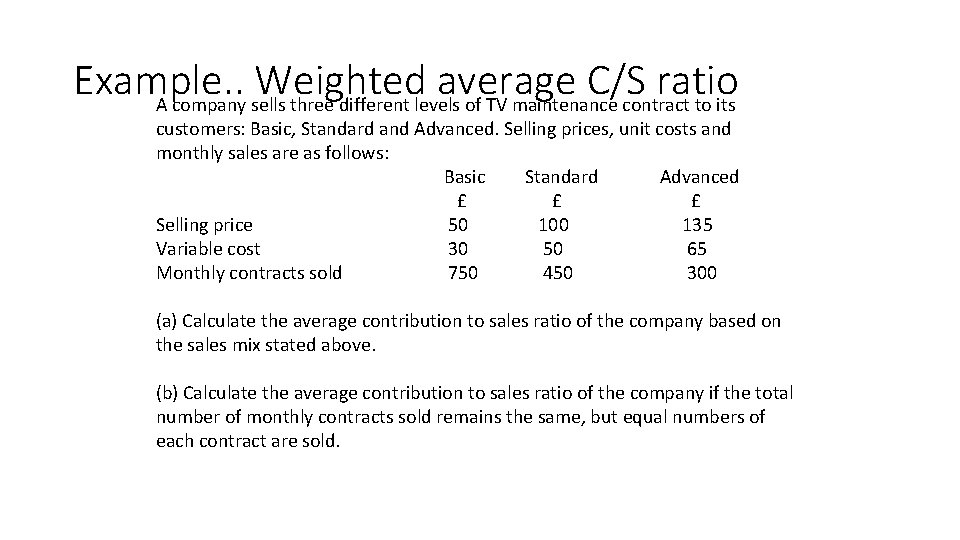
Example. . Weighted average C/S ratio A company sells three different levels of TV maintenance contract to its customers: Basic, Standard and Advanced. Selling prices, unit costs and monthly sales are as follows: Basic Standard Advanced £ £ £ Selling price 50 100 135 Variable cost 30 50 65 Monthly contracts sold 750 450 300 (a) Calculate the average contribution to sales ratio of the company based on the sales mix stated above. (b) Calculate the average contribution to sales ratio of the company if the total number of monthly contracts sold remains the same, but equal numbers of each contract are sold.

Break-even charts
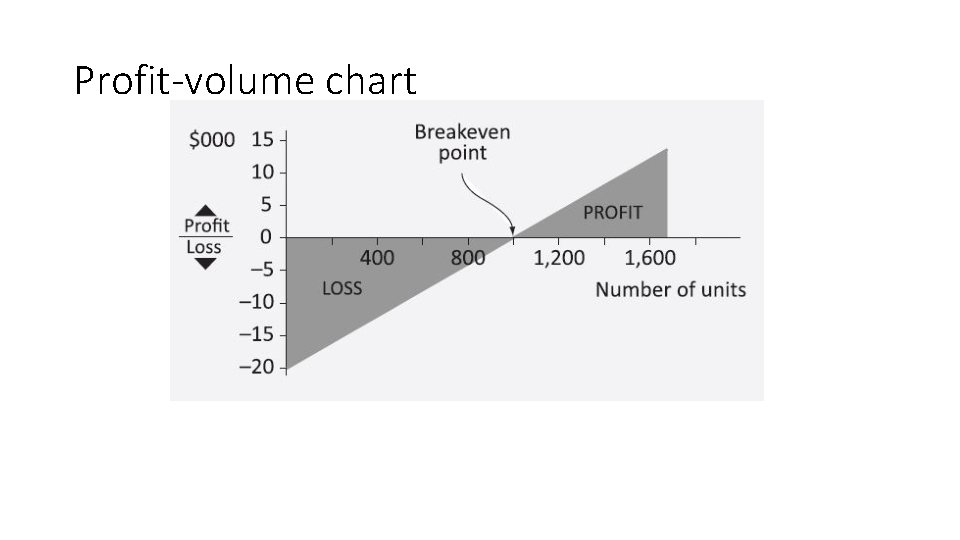
Profit-volume chart
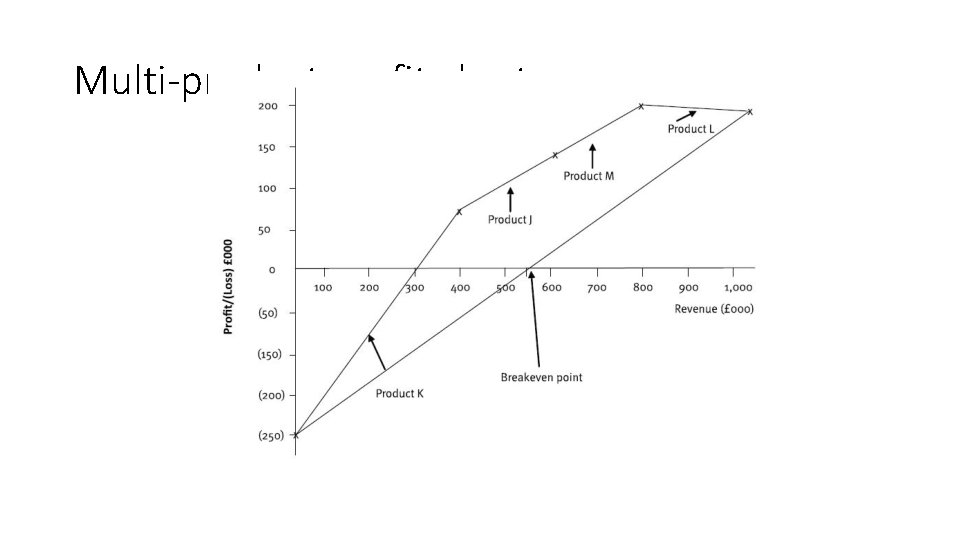
Multi-product profit chart
Limitations of CVP Analysis • Linearity of total cost and total revenue • All costs can be divided into fixed and variable elements • Efficiency and productivity are unchanged • The sales mix is maintained as total volume changes • Constant price • Constant variable cost per unit • Constant contribution • Constant fixed costs
- Slides: 11