
Section 44 AE 44 AE1 Notwithstanding anything to
- Slides: 35
Section 44 AE
44 AE(1) • Notwithstanding anything to the contrary contained in section 28 to 43 C • In the case of an assessee • Who owns not more than 10 goods carriage, at any time during the previous year and who is engaged in the business of plying, hiring or leasing of such goods carriage • The income of such business shall be deemed to be aggregate of profit and gains from all the goods carriage owned by him during the previous year as per subsection(2).
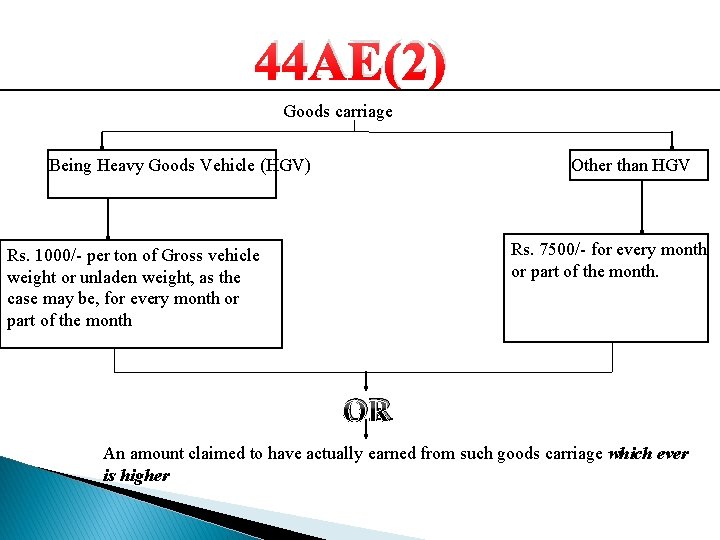
44 AE(2) Goods carriage Being Heavy Goods Vehicle (HGV) Other than HGV Rs. 7500/- for every month or part of the month. Rs. 1000/- per ton of Gross vehicle weight or unladen weight, as the case may be, for every month or part of the month OR An amount claimed to have actually earned from such goods carriage which ever is higher
44 AE(3) Any deduction allowable under the provision of section 30 to 38 shall be deemed to have been allowed and no further deduction under those sections shall be allowed provided that where the assessee is a firm the salary and interest paid to its partner shall be deducted subject to section 40(b)
44 AE(4) The WDV of any asset used for the purpose of such business shall be deemed to have been calculated as if the assessee had claimed and had actually been allowed depreciation.
44 AE(5) The provision of section 44 AA & 44 AB shall not apply in so far as they relates to business covered u/s 44 AE and in computing the monetary limits under those sections, the gross receipt from the said business shall be excluded
44 AE(6) Applicable up to A. Y. 1997 -98 only
44 AE(7) • Assessee may claim lower profit • If he keeps and maintain such books and accounts as per section 44 AA and get it audited u/s 44 AB
Explanation a) “Goods carriage”, “Gross vehicle weight ” and “unladen weight” shall have the same meaning as given u/s 2 of MVA 1988 b) “HGV” means any goods carriage the gross vehicle weight of which exceeds 12000 KG (12 MT) Definitions as per Motor Vehicle Act, 1988 Section 2 • “Goods carriage" means any motor vehicle constructed or adapted for use solely for the carriage of goods, or any motor vehicle not so constructed or adapted when used for the carriage of goods; • “Gross vehicle weight' means in respect of any vehicle the total weight of the vehicle and load certified and registered by the registering authority as permissible for that vehicle; • “Unladen weight" means the weight of a vehicle or trailer including all equipment ordinarily used with the vehicle or trailer when working, but excluding the weight of a driver or attendant; and where alternative parts or bodies are used the unladen weight of the vehicle means the weight of the vehicle with the heaviest such alternative part or body;
Section 44 ADA
44 ADA(1) • Notwithstanding anything contained in section 28 to 43 C in case of an assessee • Being resident in India, who is engaged in a profession referred u/s 44 AA(1) & • whose gross receipt do not exceed Rs. 50. 00 Lacs in a previous Year • A sum equal to 50% of the total gross receipt of the assessee in the Previous year or a sum higher than the said sum claimed to have been earned by the assessee, shall be deemed
44 ADA(2) Deduction allowable u/s 30 to 38 shall be deemed to have been allowed and no further deduction under those section shall be allowed
44 ADA(3) The WDV of any asset used for the purpose of profession hall be deemed to have been calculated as if the assessee had claimed and had actually been allowed depreciation.
44 ADA(4) Not withstanding anything contained in foregoing provision of this section, an assessee who claims that his profit and gains from the profession are lower and whose total income exceeds the basic exemption limit he shall be required to keep and maintain books and account as per section 44 AA and shall get them audited u/s 44 AB
FAQ ♦ Which profession are covered u/s 44 ADA ? As per section 44 AA(1) ○ Legal ○ Medical ○ Engineering ○ Architecture ○ Accountancy ○ Technical consultancy ○ Interior decorator ○ Other profession notified by CBDT* *Other professions as notified till date are: ○ Information Technology ○ Company secretary ○ Authorized representative ○ Film artist
FAQ ♦ Whether Gross receipt referred u/s 44 ADA is to be calculated on Accrual basis or cash basis? As per section 145 (1) which deals with method of accounting, income chargeable under the head profit and gains of business and profession shall be computed in accordance with either cash or mercantile system of accounting regularly employed by the assessee
Section 44 AD
44 AD(1) • “Notwithstanding anything to contrary contained in Section 28 to 43 C, in the case of eligible assessee engaged in eligible business, ” • A sum equal to 8 % of the total turnover or gross receipt of on account of such business or a sum higher than above as claimed to have been earned by the assessee shall be deemed to profit and gains of such business. • Provided that 6% shall be deemed to be the profits and gains of so much of the amount of total turnover/Gross receipt which is received by an account payee cheque or an account payee bank draft or use of ECS during the previous year or before the due date u/s 139(1) of that previous year.
44 AD(2) Deduction allowable u/s 30 to 38 shall be deemed to have been allowed and no further deduction under those section shall be allowed
44 AD(3) The WDV of any asset used for the purpose of profession hall be deemed to have been calculated as if the assessee had claimed and had actually been allowed depreciation.
44 AD(4) • When an eligible assessee declares profit for any P. Y in accordance with the provisions of this section(i. e. he has estimated his income @ 8% or 6% of the turnover/Gross receipt u/s 44 AD(1)). • He declares profit for any of the five previous years succeeding such previous year not in accordance with this section(i. e. he declare lower profit than estimated @ 8% or 6% u/s 44 AD(1)) • He shall not be eligible to claim benefit of this section (i. e. he can’t estimate his income u/s 44 AD(1)). • For five consecutive P. Y succeeding such P. Y.
44 AD(5) • In the case of an assessee to whom provisions of sec 44 AD(4) are applicable and whose total income exceeds basic exemption limit • He shall be required to keep and maintain books and account as per section 44 AA and shall get them audited u/s 44 AB
44 AD(6) 44 AD (6) “The provisions of this section shall not apply to ; • A person carrying on Profession • A person earning income from Commission & Brokerage • A person carrying on any Agency Business ” ♦ Issues • Often architects/interior designers also supply material, labour, etc. under their own name or carry on such contractor business in addition to the profession referred above. So, in such cases, these persons cannot avail the benefit of Section 44 AD for contractor business or for turnover from supply of material because they are also engaged in profession as referred above and such profession is outside the purview of this scheme as referred to in subsection (6) of section 44 AD. • Same will be the case of doctors/medical professionals who are providing medical, nursing home, medical consultation (OPD) services and in addition to that are also carrying on business activities like medical supplies, charging room rent from their patients, etc
Eligible assessee and Eligible business ♦ Eligible Assessee means - • A Resident Individual/HUF/Firm (other than LLP) • Who has not claimed profit linked deduction (10 AA, Chapter- VI sub heading C) ♦ Eligible business means • Other than the business u/s 44 AE & • Whose T. O. does not exceed Rs. 2. 00 crores 24
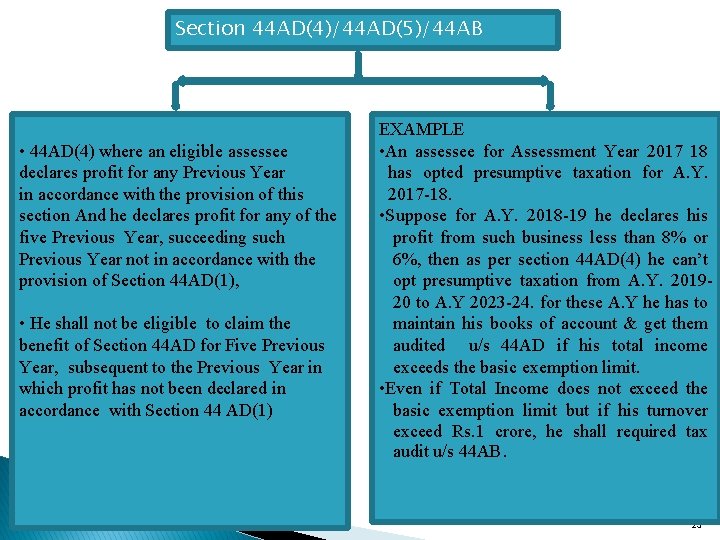
Section 44 AD(4)/44 AD(5)/44 AB • 44 AD(4) where an eligible assessee declares profit for any Previous Year in accordance with the provision of this section And he declares profit for any of the five Previous Year, succeeding such Previous Year not in accordance with the provision of Section 44 AD(1), • He shall not be eligible to claim the benefit of Section 44 AD for Five Previous Year, subsequent to the Previous Year in which profit has not been declared in accordance with Section 44 AD(1) EXAMPLE • An assessee for Assessment Year 2017 18 has opted presumptive taxation for A. Y. 2017 -18. • Suppose for A. Y. 2018 -19 he declares his profit from such business less than 8% or 6%, then as per section 44 AD(4) he can’t opt presumptive taxation from A. Y. 201920 to A. Y 2023 -24. for these A. Y he has to maintain his books of account & get them audited u/s 44 AD if his total income exceeds the basic exemption limit. • Even if Total Income does not exceed the basic exemption limit but if his turnover exceed Rs. 1 crore, he shall required tax audit u/s 44 AB. 25
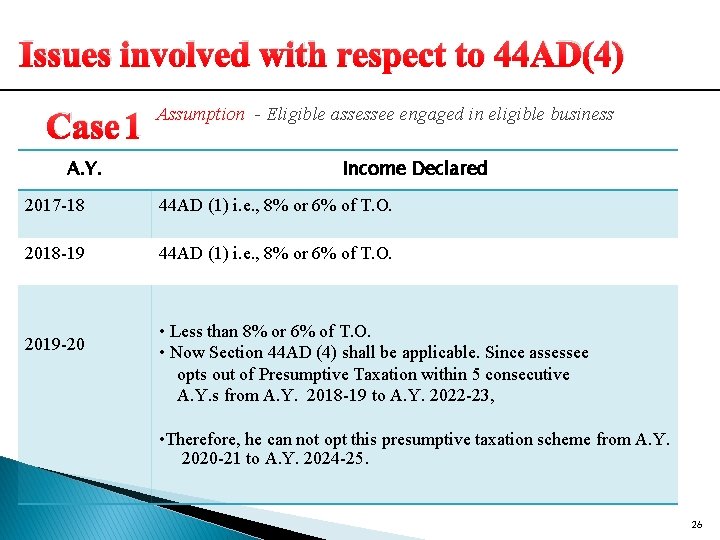
Issues involved with respect to 44 AD(4) Case 1 A. Y. Assumption - Eligible assessee engaged in eligible business Income Declared 2017 -18 44 AD (1) i. e. , 8% or 6% of T. O. 2018 -19 44 AD (1) i. e. , 8% or 6% of T. O. 2019 -20 • Less than 8% or 6% of T. O. • Now Section 44 AD (4) shall be applicable. Since assessee opts out of Presumptive Taxation within 5 consecutive A. Y. s from A. Y. 2018 -19 to A. Y. 2022 -23, • Therefore, he can not opt this presumptive taxation scheme from A. Y. 2020 -21 to A. Y. 2024 -25. 26
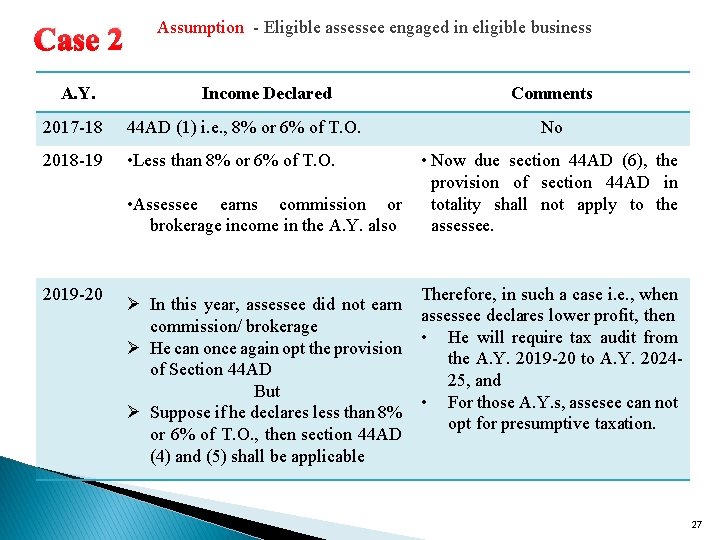
Case 2 A. Y. Assumption - Eligible assessee engaged in eligible business Income Declared Comments 2017 -18 44 AD (1) i. e. , 8% or 6% of T. O. No 2018 -19 • Less than 8% or 6% of T. O. 2019 -20 Therefore, in such a case i. e. , when Ø In this year, assessee did not earn assessee declares lower profit, then commission/ brokerage • He will require tax audit from Ø He can once again opt the provision the A. Y. 2019 -20 to A. Y. 2024 of Section 44 AD 25, and But • For those A. Y. s, assesee can not Ø Suppose if he declares less than 8% opt for presumptive taxation. or 6% of T. O. , then section 44 AD (4) and (5) shall be applicable • Now due section 44 AD (6), the provision of section 44 AD in • Assessee earns commission or totality shall not apply to the brokerage income in the A. Y. also assessee. 27
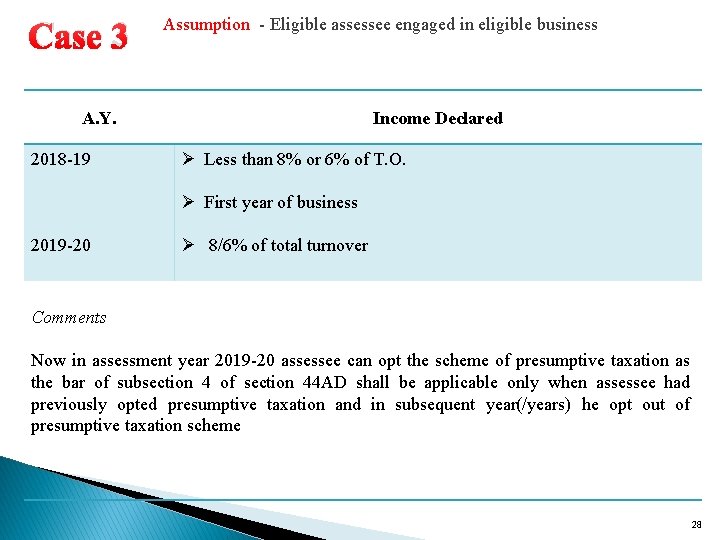
Case 3 Assumption - Eligible assessee engaged in eligible business A. Y. 2018 -19 Income Declared Ø Less than 8% or 6% of T. O. Ø First year of business 2019 -20 Ø 8/6% of total turnover Comments Now in assessment year 2019 -20 assessee can opt the scheme of presumptive taxation as the bar of subsection 4 of section 44 AD shall be applicable only when assessee had previously opted presumptive taxation and in subsequent year(/years) he opt out of presumptive taxation scheme 28
Important issues related to section 44 AD/ADA/AE ♦ Applicability of Section 44 ADA to a partner of firm receiving remuneration and/or interest from the firm Such receipts would normally be taxed as professional income by virtue of Section 28(v). In this connection, attention is invited to the decisions of Kolkata bench of the Income Tax Appellate Tribunal in the case of Amal Ganguli v. DCIT (ITA No. 2135/Kol/2008) and Sagar Dutta v. DCIT (ITA No. 692/Kol/2012) wherein it was held that a partner would be liable to tax audit under Section 44 AB if his salary/interest from the partnership firm exceeds the threshold limit prescribed under Section 44 AB.
Important issues related to section 44 AD/ADA/AE ♦ Share of profits of a partner - Gross receipts for the purpose of Section 44 ADA The Mumbai Bench of the Income Tax Appellate Tribunal in the case of ACIT v. India Magnum Fund (81 ITD 295) also held that in order to trigger the provisions of Section 44 AB, there should be first computation of profits and gains of business or profession i. e. computation of total income as per Section 4. As the income exempt under Section 10 does not form part of the total income, such exempt income cannot be subjected to the provisions of Section 44 AB. Consequently, one may argue that share of partners profit which is exempt under section 10(2 A) would not be considered for the purposes of the gross receipts.
Important issues related to section 44 AD/ADA/AE ♦ Do disallowances like 43 B attract in case of an assessee whose income is computed under 44 AD? -Good Luck Kinetic v. ITO (2015) 58 taxmann. com 267 (Panaji - Trib. ) 44 AD starts with “notwithstanding anything to the contrary contained in Sec. 28 to 43 C” whereas section 43 B starts with the words “notwithstanding anything contained in any other provisions of this Act” The non-obstante clause in Sec. 43 B has a far wider amplitude Hence, disallowance could be made by invoking the provisions of Sec. 43 B
Important issues related to section 44 AD/ADA/AE ♦ Do disallowances like 40 A(3), 40(a)(ia) attract in case of an assessee whose income is computed under 44 AD? Jawahar lal mukherjee Vs. ITO ITAT Kolkata (2015) Provision of section 44 AD has an overriding effect over other provision contained in section 28 to 43 C of the Act , when an income is presumptively taxed u/s 44 AD of the Act any furthur business income by applying provisions of section 28 to 43 C would get telescoped with the presumptive income determined , for this reason the legislation had provided section 44 AD of the Act with a non obstante clause Other case law: • ITO vs Rajesh kumar Gupta (2017)(Jaipur ITAT) • CIT vs M. V Construction Co. (HC) (Gujrat) • Shri Sanjiv Javerilal Jain vs DCIT (Ahd ITAT) • Shri Himanshu H Thakkar vs ITO (Ahd ITAT)
Important issues related to section 44 AD/ADA/AE SECTION 44 AD vis a vis SECTIONS 68/69 Similarly, whether a taxpayer declaring income under section 44 AD could be subjected to tax under sections 68 /69 for the amounts credited in his bank account became an issue in CIT v. Surinder Paul Anand [2010[ 48 DTR (P. & H. ) 135. In the assessment, the assessee was asked to explain the cash deposit in his bank account and finally an addition of Rs. 14, 95, 300 was made to the returned income. The Court held that the assessee having opted for presumptive provision is exempted from maintaining books of account. It held that the assessee is under an obligation to explain individual entry of cash deposit only when such entry had no nexus with the gross receipts of the business. The assessee claimed both before CIT (A) and tribunal that the said amount was part of business receipts and in the absence of any other contrary material / evidence, the cash deposits could not be taxed as unexplained or undisclosed income of the assessee. The court held that there was no substantial question of law in the appeal and hence upheld the order of the tribunal.
Important issues related to section 44 AD/ADA/AE ♦ Whether GST has to be included in Total turnover/Gross reciept reffered u/s 44 AD or 44 ADA Refer Section 145 A of the IT Act as inserted by Finance Act 2017, Guidance note issued by ICAI & CBDT circular No. 23/2017 TDS would NOT be deducted on service tax component if the amount of service tax is shown separately in the invoice. As per circular No 1/2014 (issued by CBDT) TDS had to be deducted on the amount paid/payable without including service tax component.