
Second Attempt at JumpDetection and Analysis Mike Schwert
- Slides: 14
Second Attempt at Jump-Detection and Analysis Mike Schwert ECON 201 FS 2/13/08
My Approach This Week • Last time, found too many jump days. Likely explanations include microstructure noise from using minute-by-minute prices and accidental inclusion of overnight returns in intraday calculations. • This time, rewrote code to sample prices at 5 minute frequency and exclude overnight returns. Recalculated summary statistics and number of jump days. • Examined effect of sampling frequency on jump detection by calculating zstatistics and counting jump days for 5, 10, 15, and 20 minute sampling frequencies. • Examined effect of sampling frequency on volatility calculations by creating volatility signature plots for realized variance and bipower variation.
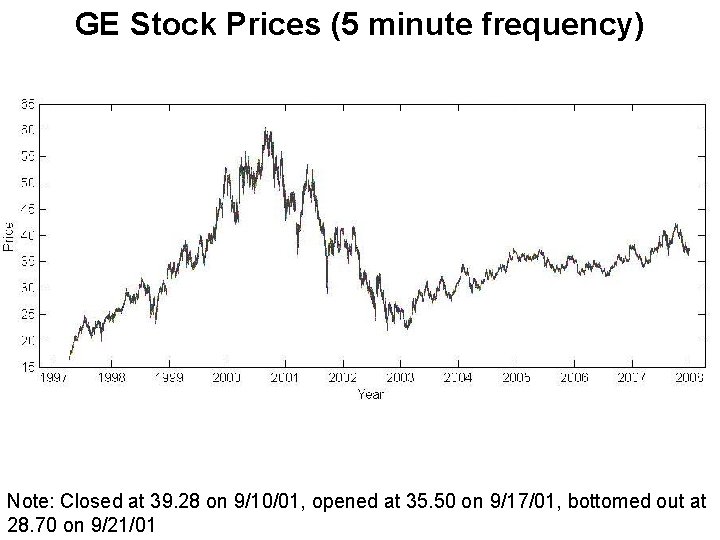
GE Stock Prices (5 minute frequency) Note: Closed at 39. 28 on 9/10/01, opened at 35. 50 on 9/17/01, bottomed out at 28. 70 on 9/21/01
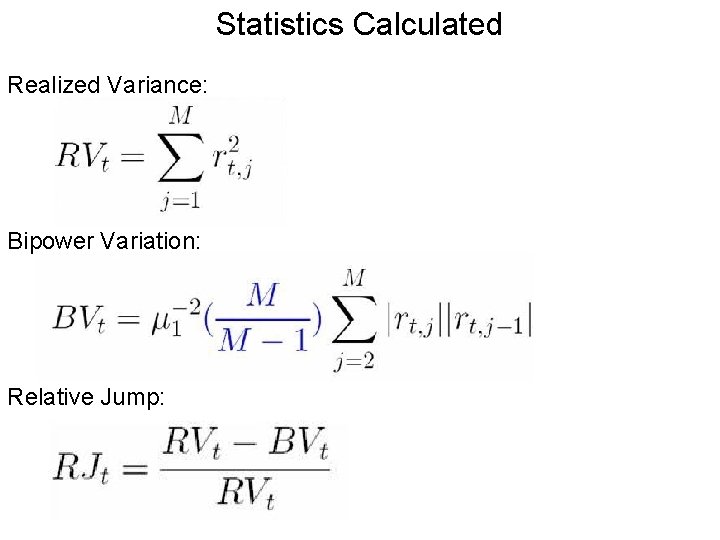
Statistics Calculated Realized Variance: Bipower Variation: Relative Jump:
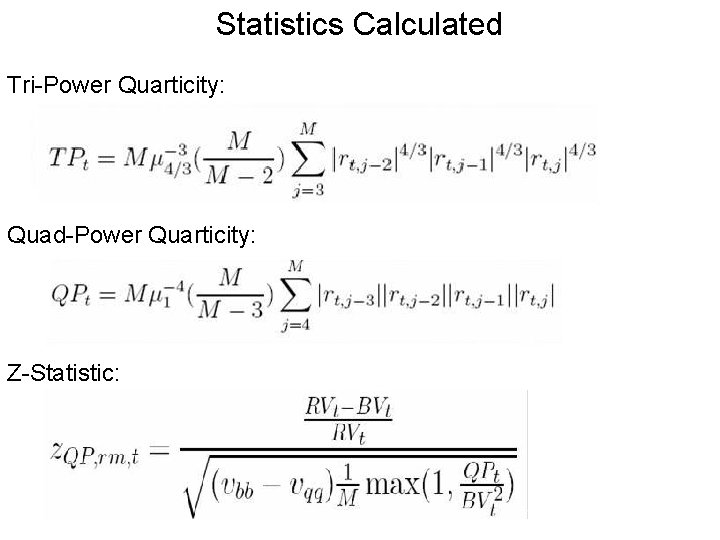
Statistics Calculated Tri-Power Quarticity: Quad-Power Quarticity: Z-Statistic:
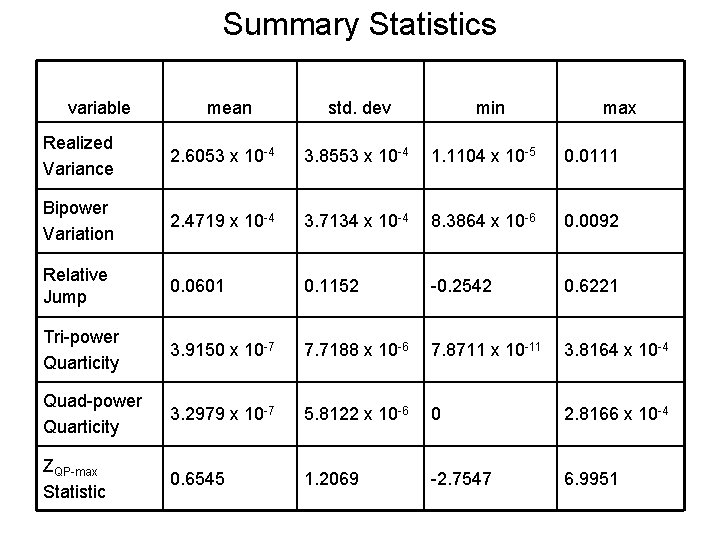
Summary Statistics variable mean std. dev min max Realized Variance 2. 6053 x 10 -4 3. 8553 x 10 -4 1. 1104 x 10 -5 0. 0111 Bipower Variation 2. 4719 x 10 -4 3. 7134 x 10 -4 8. 3864 x 10 -6 0. 0092 Relative Jump 0. 0601 0. 1152 -0. 2542 0. 6221 Tri-power Quarticity 3. 9150 x 10 -7 7. 7188 x 10 -6 7. 8711 x 10 -11 3. 8164 x 10 -4 Quad-power Quarticity 3. 2979 x 10 -7 5. 8122 x 10 -6 0 2. 8166 x 10 -4 ZQP-max Statistic 0. 6545 1. 2069 -2. 7547 6. 9951
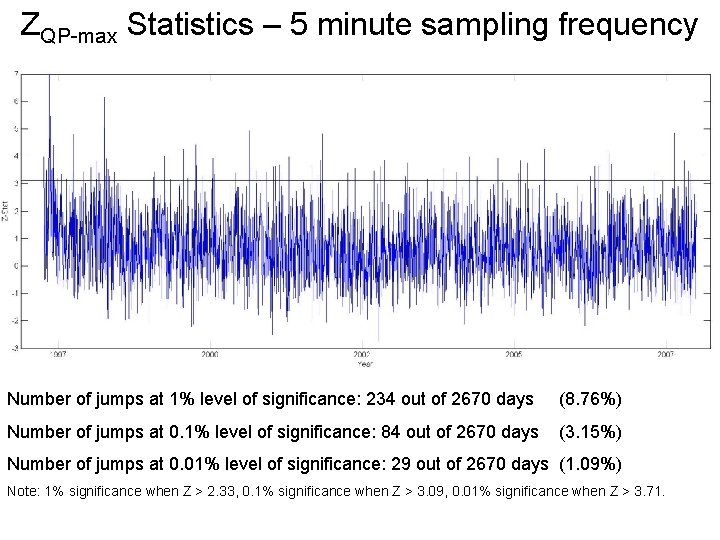
ZQP-max Statistics – 5 minute sampling frequency Number of jumps at 1% level of significance: 234 out of 2670 days (8. 76%) Number of jumps at 0. 1% level of significance: 84 out of 2670 days (3. 15%) Number of jumps at 0. 01% level of significance: 29 out of 2670 days (1. 09%) Note: 1% significance when Z > 2. 33, 0. 1% significance when Z > 3. 09, 0. 01% significance when Z > 3. 71.
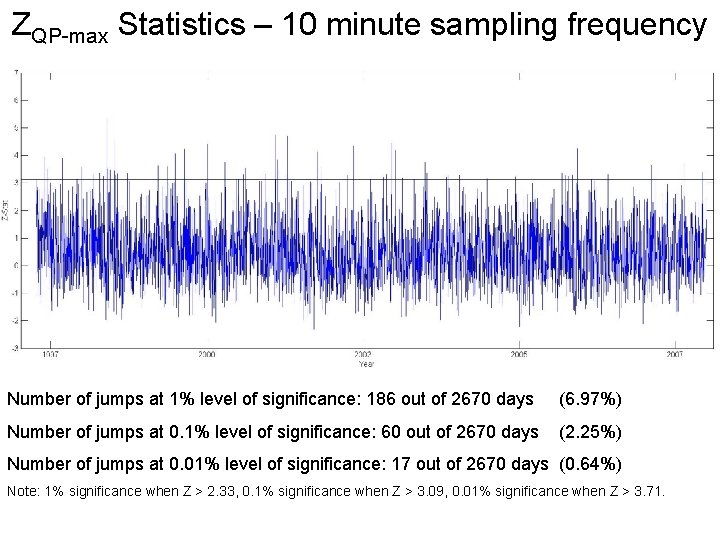
ZQP-max Statistics – 10 minute sampling frequency Number of jumps at 1% level of significance: 186 out of 2670 days (6. 97%) Number of jumps at 0. 1% level of significance: 60 out of 2670 days (2. 25%) Number of jumps at 0. 01% level of significance: 17 out of 2670 days (0. 64%) Note: 1% significance when Z > 2. 33, 0. 1% significance when Z > 3. 09, 0. 01% significance when Z > 3. 71.
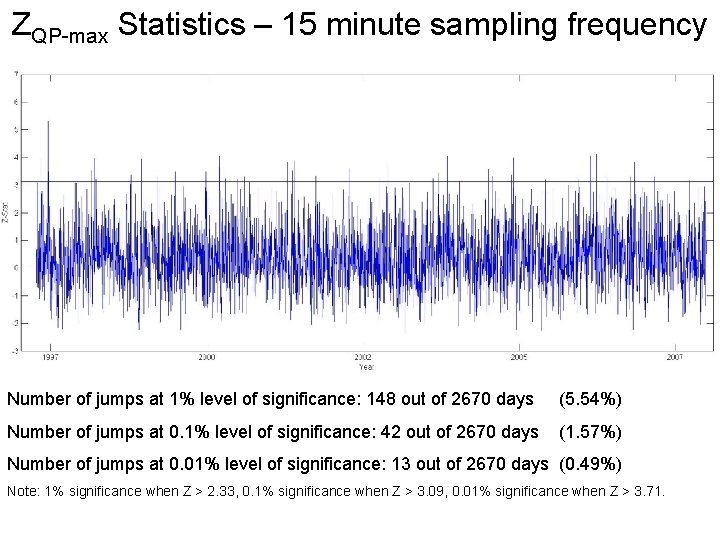
ZQP-max Statistics – 15 minute sampling frequency Number of jumps at 1% level of significance: 148 out of 2670 days (5. 54%) Number of jumps at 0. 1% level of significance: 42 out of 2670 days (1. 57%) Number of jumps at 0. 01% level of significance: 13 out of 2670 days (0. 49%) Note: 1% significance when Z > 2. 33, 0. 1% significance when Z > 3. 09, 0. 01% significance when Z > 3. 71.
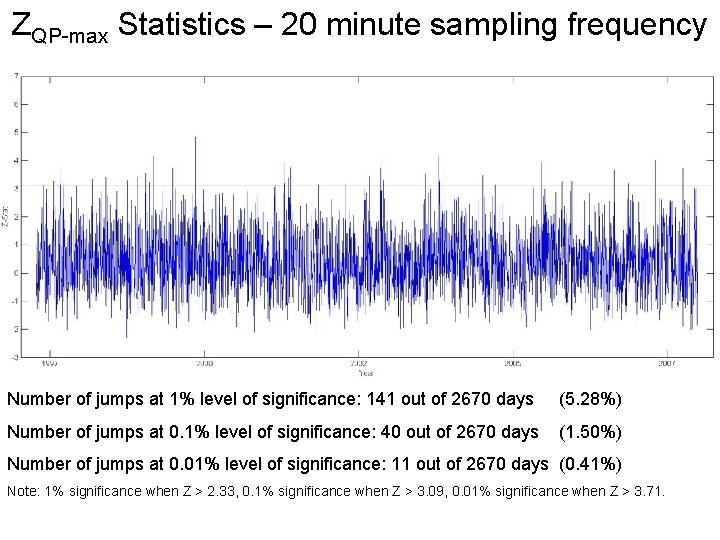
ZQP-max Statistics – 20 minute sampling frequency Number of jumps at 1% level of significance: 141 out of 2670 days (5. 28%) Number of jumps at 0. 1% level of significance: 40 out of 2670 days (1. 50%) Number of jumps at 0. 01% level of significance: 11 out of 2670 days (0. 41%) Note: 1% significance when Z > 2. 33, 0. 1% significance when Z > 3. 09, 0. 01% significance when Z > 3. 71.
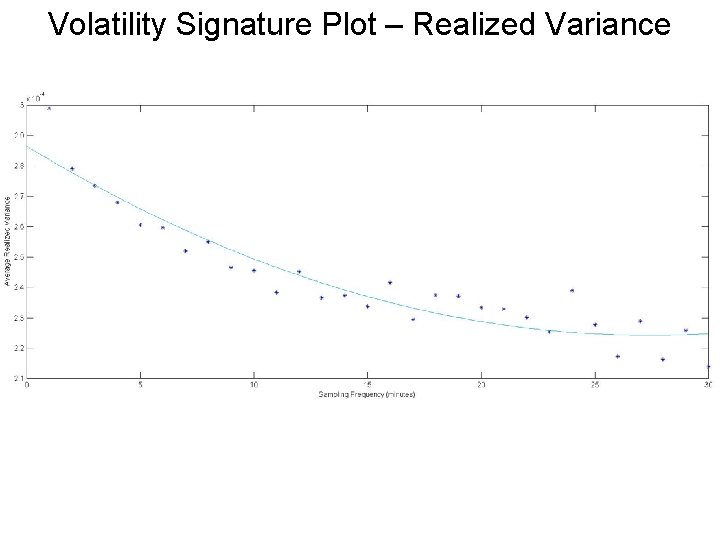
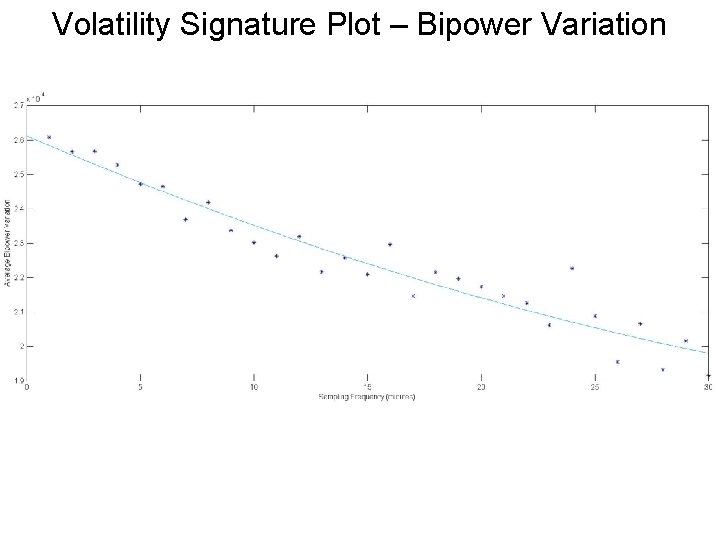
Volatility Signature Plots • Used idea introduced by Andersen, Bollerslev, Diebold, and Labys (1999). • Calculated mean daily realized variance and bipower variation over the sample period under sampling frequencies of 1 minute, 2 minutes, …, 30 minutes. • Plotted mean realized variance and bipower variation on the y-axis with sampling frequency on the x-axis. • RV and BV are higher for high-frequency samples because returns are distorted by microstructure noise such as bid-ask bounce. • RV and BV decrease as interval between samples increases because microstructure noise is cancelled out. • Must be wary of using too low of a sampling frequency, as sampling variation will affect volatility calculations. • Balance between sampling variation and microstructure noise appears to be reached around 15 minute sampling frequency.
Volatility Signature Plot – Realized Variance
Volatility Signature Plot – Bipower Variation
Possible Extensions • Perform same calculations on S&P 100 index and stocks highly correlated with GE, or those with similar beta, or from a similar industry, etc. • Check whether GE jumps on the same days as these other assets. • Determine how much jumps are systematic vs. idiosyncratic. • Use volatility signature plots from several stocks to determine ideal sampling frequency for jump detection, if possible. • Incorporate ARCH, GARCH, or stochastic volatility models somehow?