
SAY HELLO TO ROYAL LONDON SAY HELLO TO
- Slides: 99
SAY HELLO TO ROYAL LONDON
SAY HELLO TO ROYAL LONDON AGENDA • Overview to our proposition • Easy to do business with • Critical Illness Cover • Underwriting • Enhanced Children’s Critical Illness Cover • Lifestyle review • Family income benefit • Building a plan with Royal London • Income Protection • Mortgage protection • Helping Hand • Marketing studio
WHO WE ARE • A mutual - established over 150 years ago • We’re committed to the intermediary market – and that won’t change 3
WE HAVE GREAT EXPECTATIONS For you: • User-friendly technology • Personal service from a named contact • Fast, efficient, helpful new business processes • Direct access to underwriters • Valuable business support and marketing tools 4
WE HAVE GREAT EXPECTATIONS For your clients: • Quality products • Wide cover for the most common definitions • Help and support when your clients need it most • Claims paid quickly – no hidden barriers 5
OVERVIEW TO OUR PROPOSITION 6
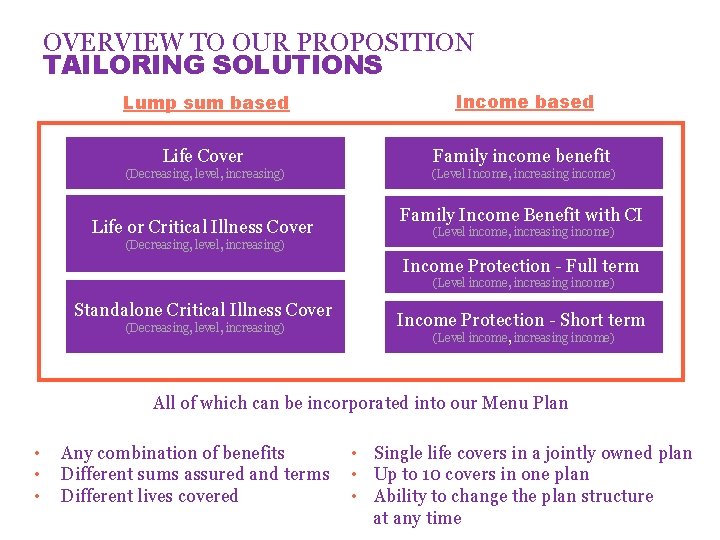
OVERVIEW TO OUR PROPOSITION TAILORING SOLUTIONS Lump sum based Income based Life Cover Family income benefit (Decreasing, level, increasing) (Level Income, increasing income) Life or Critical Illness Cover (Decreasing, level, increasing) Family Income Benefit with CI (Level income, increasing income) Income Protection - Full term (Level income, increasing income) Standalone Critical Illness Cover (Decreasing, level, increasing) Income Protection - Short term (Level income, increasing income) All of which can be incorporated into our Menu Plan • • • Any combination of benefits Different sums assured and terms Different lives covered • Single life covers in a jointly owned plan • Up to 10 covers in one plan • Ability to change the plan structure at any time
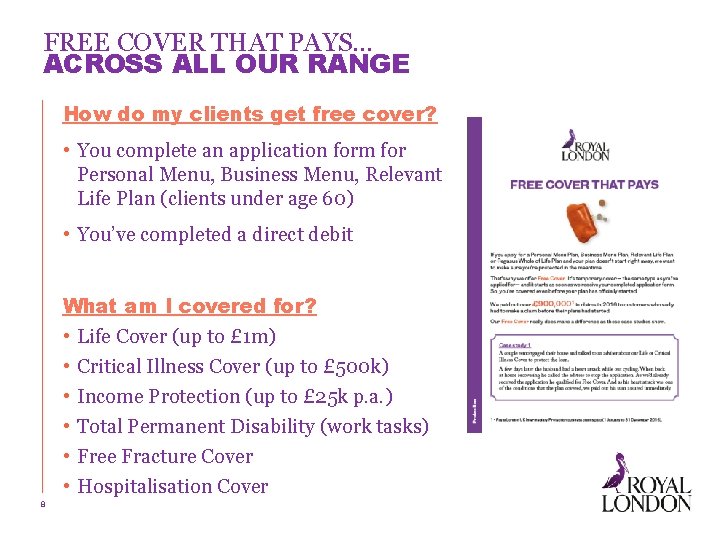
FREE COVER THAT PAYS… ACROSS ALL OUR RANGE How do my clients get free cover? • You complete an application form for Personal Menu, Business Menu, Relevant Life Plan (clients under age 60) • You’ve completed a direct debit What am I covered for? • • • 8 Life Cover (up to £ 1 m) Critical Illness Cover (up to £ 500 k) Income Protection (up to £ 25 k p. a. ) Total Permanent Disability (work tasks) Free Fracture Cover Hospitalisation Cover
FREE COVER THAT PAYS… ACROSS ALL OUR RANGE How long will it last? • Free Cover will last for no longer than 90 days • If we accept your application, your Free Cover will end 14 days after we make our decision or when your actual cover starts, if earlier • If your cover is in connection with a mortgage we’ll extend Free Cover beyond the 14 days to the date you complete your mortgage 9
CRITICAL ILLNESS WHAT WE OFFER
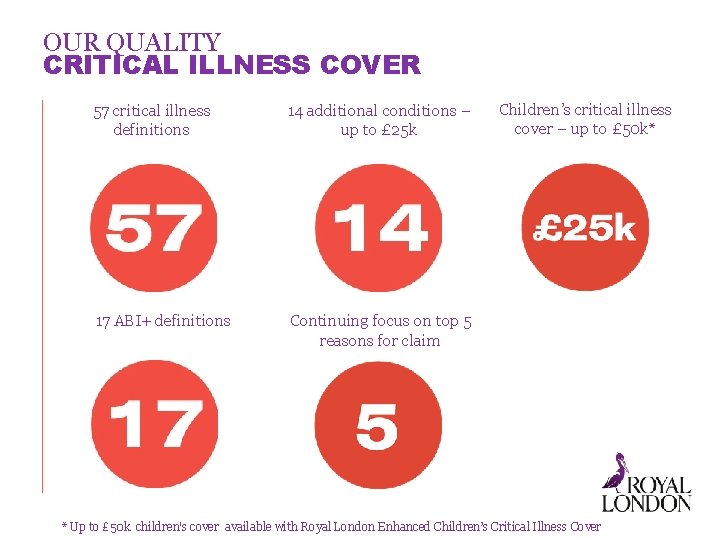
OUR QUALITY CRITICAL ILLNESS COVER 57 critical illness definitions 14 additional conditions – up to £ 25 k 17 ABI+ definitions Continuing focus on top 5 reasons for claim Children’s critical illness cover – up to £ 50 k* * Up to £ 50 k children's cover available with Royal London Enhanced Children’s Critical Illness Cover
ENHANCED CHILDREN’S CRITICAL ILLNESS COVER
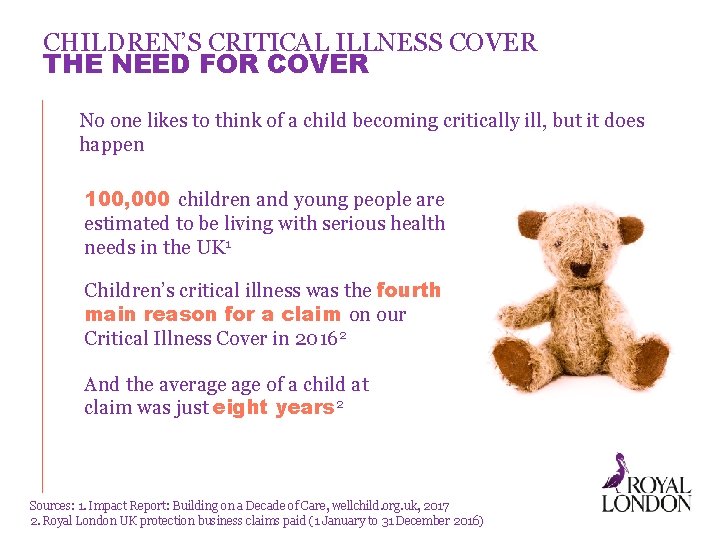
CHILDREN’S CRITICAL ILLNESS COVER THE NEED FOR COVER No one likes to think of a child becoming critically ill, but it does happen 100, 000 children and young people are estimated to be living with serious health needs in the UK 1 Children’s critical illness was the fourth main reason for a claim on our Critical Illness Cover in 20162 And the average of a child at claim was just eight years 2 Sources: 1. Impact Report: Building on a Decade of Care, wellchild. org. uk, 2017 2. Royal London UK protection business claims paid (1 January to 31 December 2016)
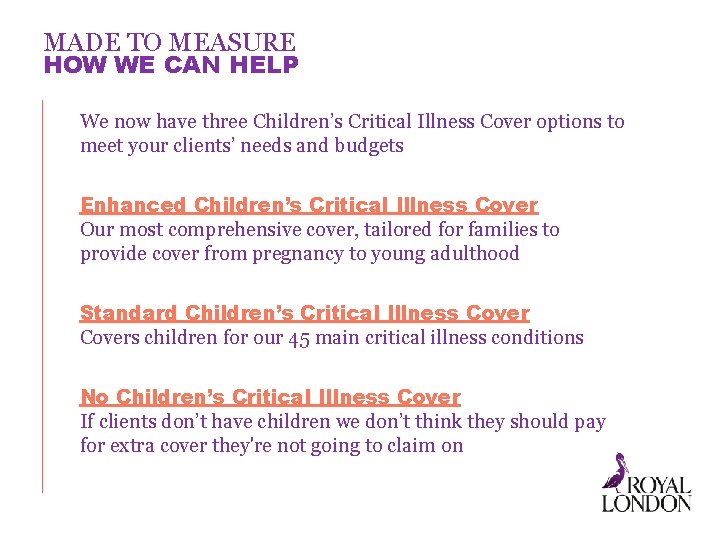
MADE TO MEASURE HOW WE CAN HELP We now have three Children’s Critical Illness Cover options to meet your clients’ needs and budgets Enhanced Children’s Critical Illness Cover Our most comprehensive cover, tailored for families to provide cover from pregnancy to young adulthood Standard Children’s Critical Illness Covers children for our 45 main critical illness conditions No Children’s Critical Illness Cover If clients don’t have children we don’t think they should pay for extra cover they're not going to claim on
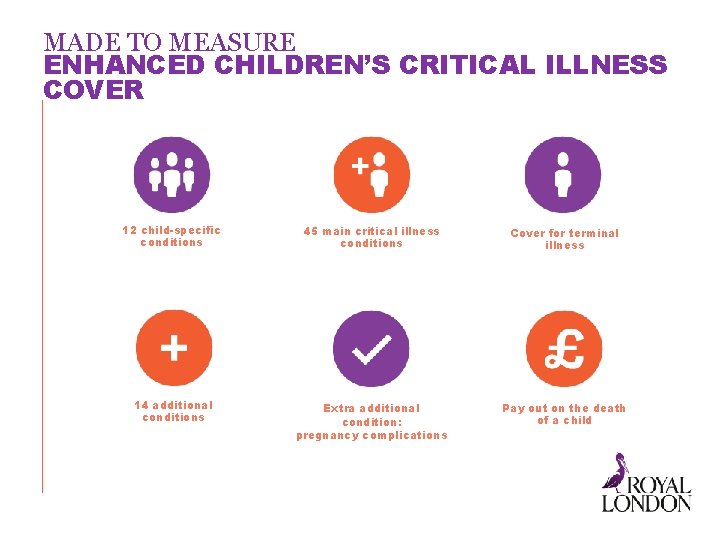
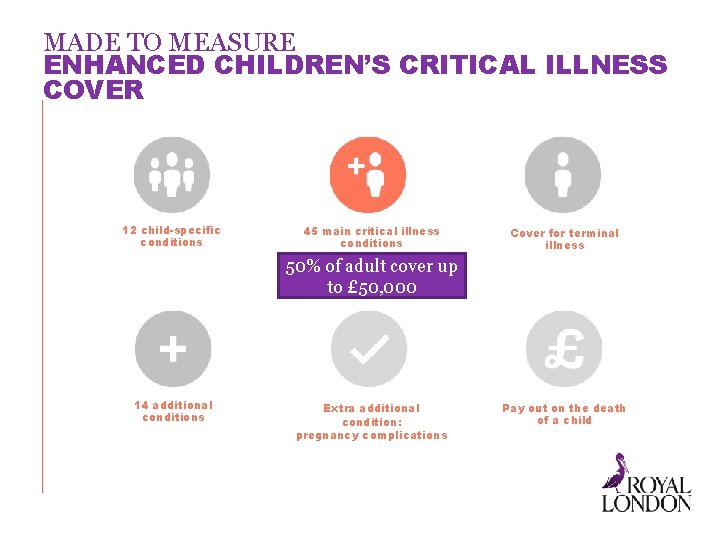
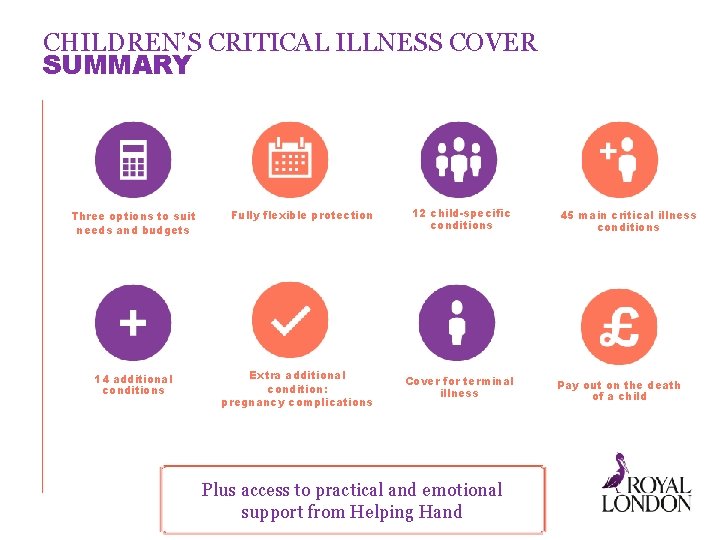
MADE TO MEASURE ENHANCED CHILDREN’S CRITICAL ILLNESS COVER 12 child-specific conditions 45 main critical illness conditions Cover for terminal illness 14 additional conditions Extra additional condition: pregnancy complications Pay out on the death of a child
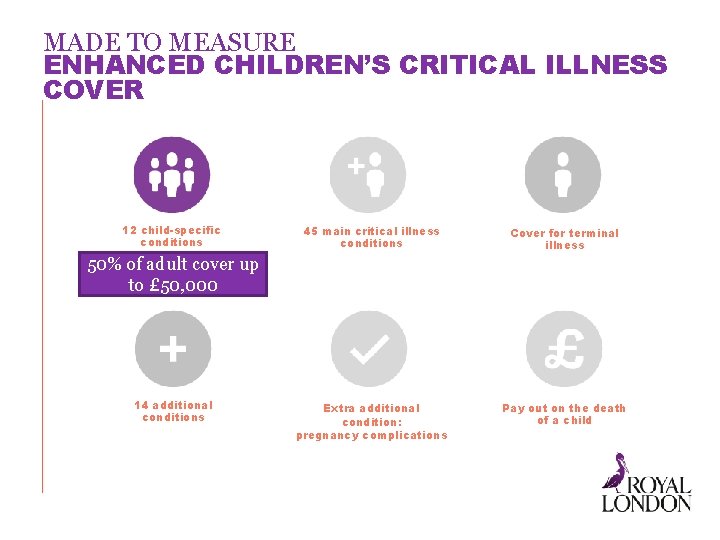
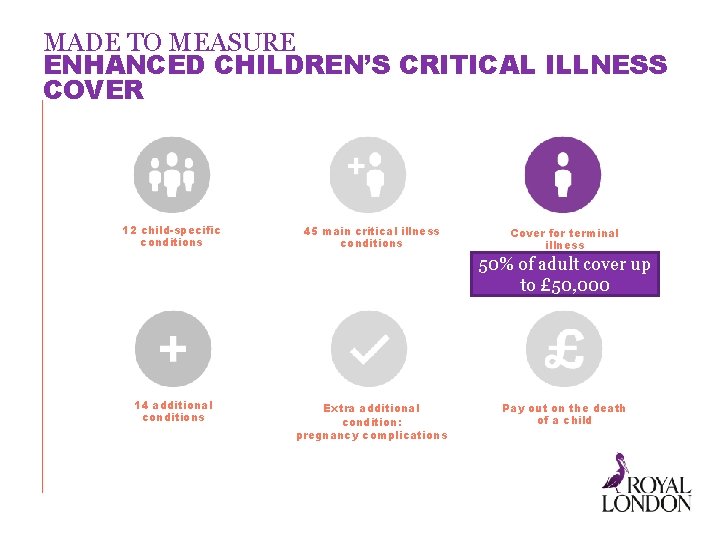
MADE TO MEASURE ENHANCED CHILDREN’S CRITICAL ILLNESS COVER 12 child-specific conditions 45 main critical illness conditions Cover for terminal illness Extra additional condition: pregnancy complications Pay out on the death of a child 50% of adult cover up to £ 50, 000 14 additional conditions
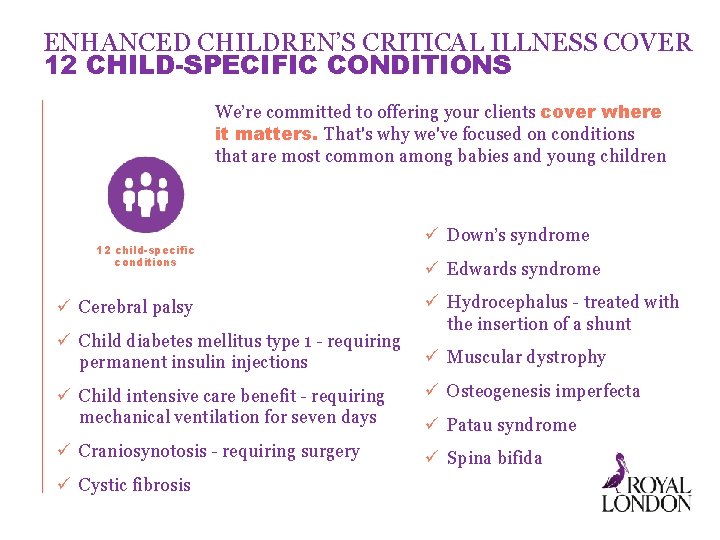
ENHANCED CHILDREN’S CRITICAL ILLNESS COVER 12 CHILD-SPECIFIC CONDITIONS We’re committed to offering your clients cover where it matters. That's why we've focused on conditions that are most common among babies and young children 12 child-specific conditions ü Cerebral palsy ü Child diabetes mellitus type 1 - requiring permanent insulin injections ü Down’s syndrome ü Edwards syndrome ü Hydrocephalus - treated with the insertion of a shunt ü Muscular dystrophy ü Child intensive care benefit - requiring mechanical ventilation for seven days ü Osteogenesis imperfecta ü Craniosynotosis - requiring surgery ü Spina bifida ü Cystic fibrosis ü Patau syndrome
MADE TO MEASURE ENHANCED CHILDREN’S CRITICAL ILLNESS COVER 12 child-specific conditions 45 main critical illness conditions Cover for terminal illness 50% of adult cover up to £ 50, 000 14 additional conditions Extra additional condition: pregnancy complications Pay out on the death of a child
MADE TO MEASURE ENHANCED CHILDREN’S CRITICAL ILLNESS COVER 12 child-specific conditions 45 main critical illness conditions Cover for terminal illness 50% of adult cover up to £ 50, 000 14 additional conditions Extra additional condition: pregnancy complications Pay out on the death of a child
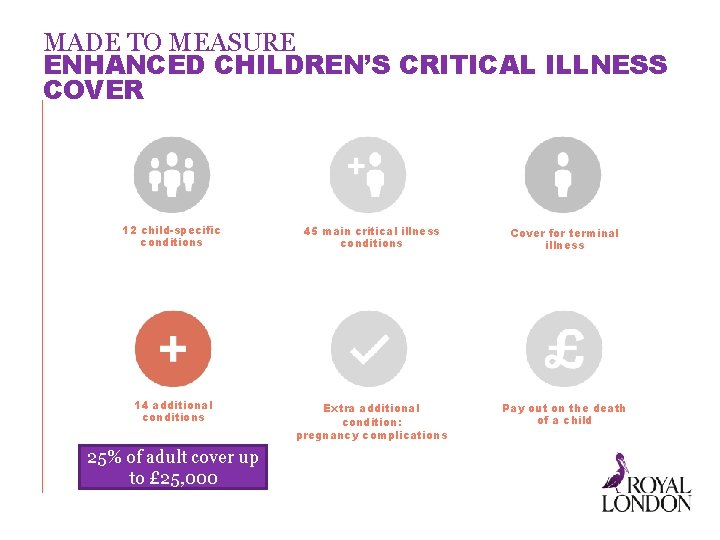
MADE TO MEASURE ENHANCED CHILDREN’S CRITICAL ILLNESS COVER 12 child-specific conditions 45 main critical illness conditions Cover for terminal illness 14 additional conditions Extra additional condition: pregnancy complications Pay out on the death of a child 25% of adult cover up to £ 25, 000
MADE TO MEASURE ENHANCED CHILDREN’S CRITICAL ILLNESS COVER 12 child-specific conditions 45 main critical illness conditions Cover for terminal illness 14 additional conditions Extra additional condition: pregnancy complications Pay out on the death of a child £ 5, 000 for each affected pregnancy
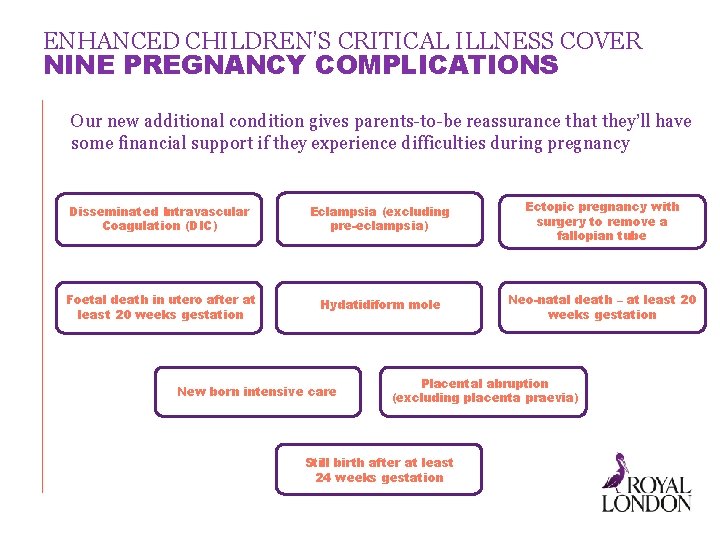
ENHANCED CHILDREN’S CRITICAL ILLNESS COVER NINE PREGNANCY COMPLICATIONS Our new additional condition gives parents-to-be reassurance that they’ll have some financial support if they experience difficulties during pregnancy Disseminated Intravascular Coagulation (DIC) Eclampsia (excluding pre-eclampsia) Ectopic pregnancy with surgery to remove a fallopian tube Foetal death in utero after at least 20 weeks gestation Hydatidiform mole Neo-natal death – at least 20 weeks gestation New born intensive care Placental abruption (excluding placenta praevia) Still birth after at least 24 weeks gestation
MADE TO MEASURE ENHANCED CHILDREN’S CRITICAL ILLNESS COVER 12 child-specific conditions 45 main critical illness conditions Cover for terminal illness 14 additional conditions Extra additional condition: pregnancy complications Pay out on the death of a child £ 5, 000 on the death of a child
MADE TO MEASURE FULLY FLEXIBLE PROTECTION When it comes to children’s cover, there's no one-size-fits-all. Families all have different needs – which change over the years • Clients can change their Children’s Critical Illness Cover option at any time during the term of their plan • They can upgrade their cover with no underwriting
CHILDREN’S CRITICAL ILLNESS COVER SUMMARY Three options to suit needs and budgets 14 additional conditions Fully flexible protection 12 child-specific conditions Extra additional condition: pregnancy complications Cover for terminal illness Plus access to practical and emotional support from Helping Hand 45 main critical illness conditions Pay out on the death of a child
HELP FROM US USE OUR SALES AID
FAMILY INCOME BENEFIT
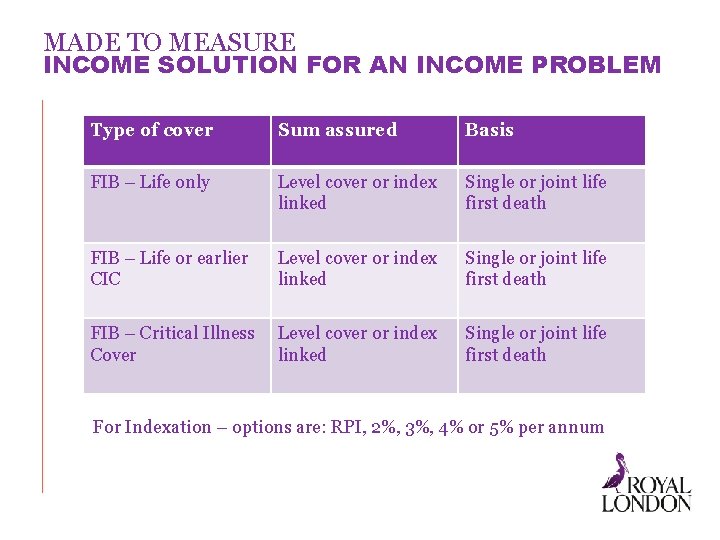
MADE TO MEASURE INCOME SOLUTION FOR AN INCOME PROBLEM Type of cover Sum assured Basis FIB – Life only Level cover or index linked Single or joint life first death FIB – Life or earlier CIC Level cover or index linked Single or joint life first death FIB – Critical Illness Cover Level cover or index linked Single or joint life first death For Indexation – options are: RPI, 2%, 3%, 4% or 5% per annum
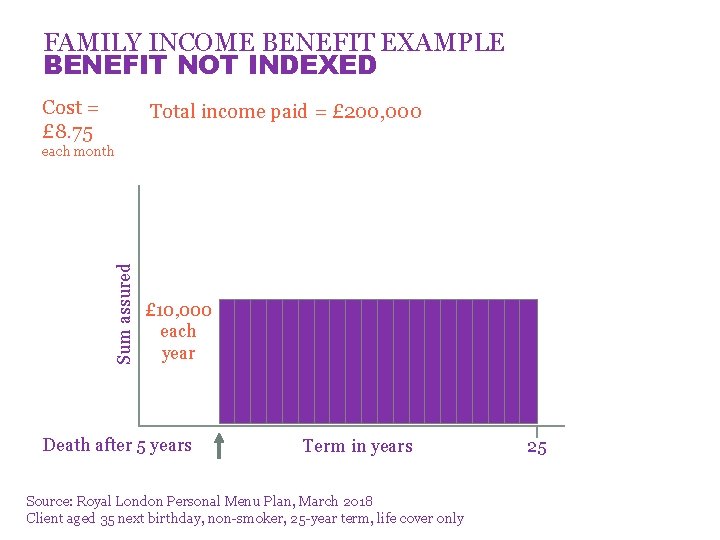
FAMILY INCOME BENEFIT EXAMPLE BENEFIT NOT INDEXED Cost = £ 8. 75 Total income paid = £ 200, 000 Sum assured each month £ 10, 000 each year Death after 5 years Term in years Source: Royal London Personal Menu Plan, March 2018 Client aged 35 next birthday, non-smoker, 25 -year term, life cover only 25
INDEXATION OF FAMILY INCOME BENEFIT HOW DOES IT WORK? • Clients will be offered the option to increase cover, either RPI or fixed rate • Indexed family income benefit costs slightly more than non-indexed • We’ll stop offering the option if a client refuses the increase two years in a row • Let’s look at the situation again. . . 30
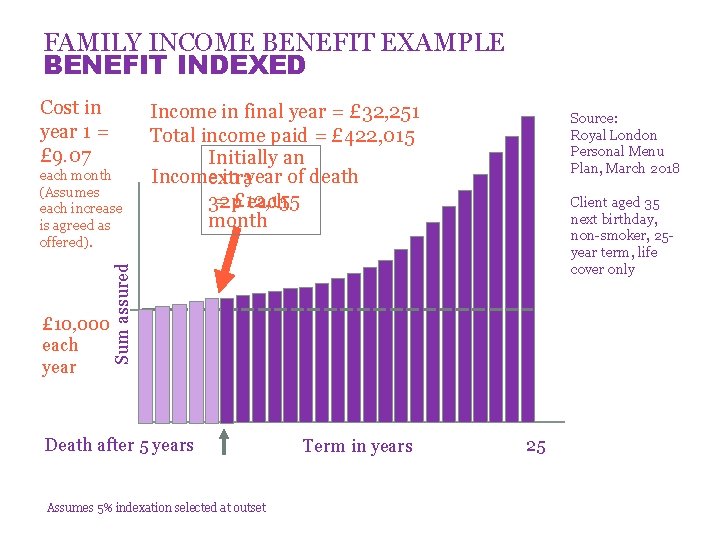
FAMILY INCOME BENEFIT EXAMPLE BENEFIT INDEXED Cost in year 1 = £ 9. 07 £ 10, 000 each year Source: Royal London Personal Menu Plan, March 2018 Client aged 35 next birthday, non-smoker, 25 year term, life cover only Sum assured each month (Assumes each increase is agreed as offered). Income in final year = £ 32, 251 Total income paid = £ 422, 015 Initially an Incomeextra in year of death = £ 12, 155 32 p each month Death after 5 years Assumes 5% indexation selected at outset Term in years 25
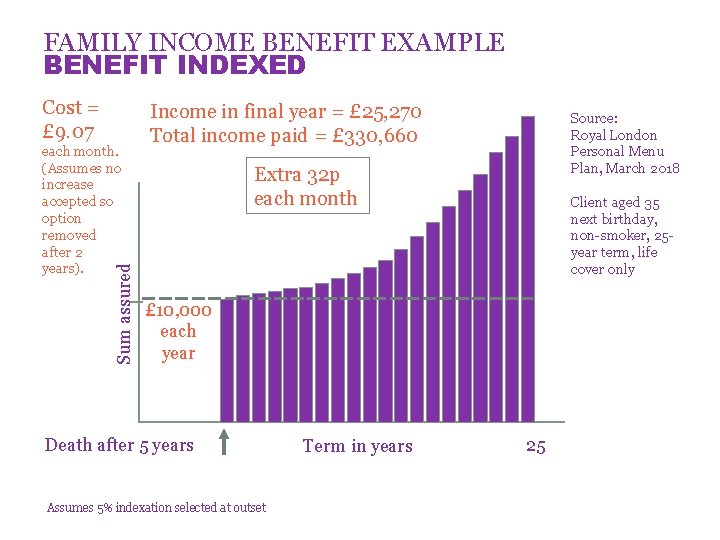
FAMILY INCOME BENEFIT EXAMPLE BENEFIT INDEXED Cost = £ 9. 07 Sum assured each month. (Assumes no increase accepted so option removed after 2 years). Income in final year = £ 25, 270 Total income paid = £ 330, 660 Source: Royal London Personal Menu Plan, March 2018 Extra 32 p each month Client aged 35 next birthday, non-smoker, 25 year term, life cover only £ 10, 000 each year Death after 5 years Assumes 5% indexation selected at outset Term in years 25
INCOME PROTECTION
INCOME PROTECTION COVER THAT MEETS CLIENTS’ NEEDS Reassuring • Your clients can claim if they can't do their own occupation due to illness or injury • They can protect up to 65% of the first £ 15, 000 of their pre-tax earnings, plus 55% of the remainder, up to a maximum of £ 250, 000 a year o. Self-employed clients can include certain regular fixed overheads when calculating their maximum sum assured o. Employed clients can include dividends, a nominal spouse salary and P 11 D benefits as income • Cover up to age 70 for all occupations 34
INCOME PROTECTION COVER THAT MEETS CLIENTS’ NEEDS Flexible and affordable • Choice of level or increasing cover • Range of deferred periods • Choice of one year, two year or full term payment periods 35
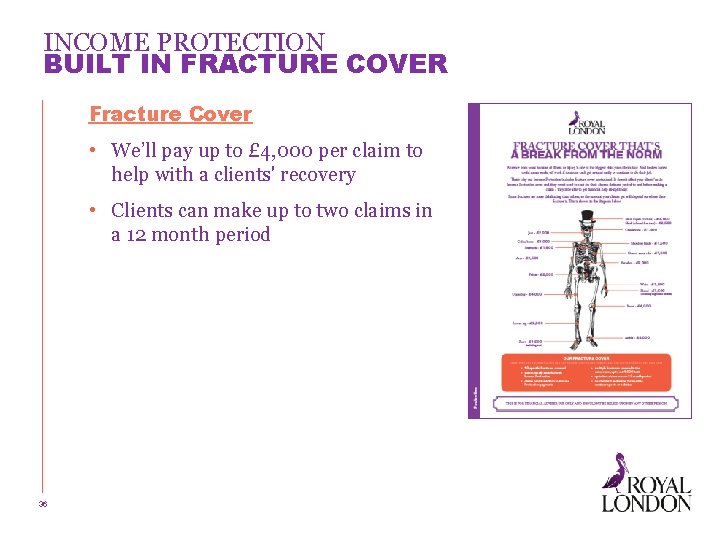
INCOME PROTECTION BUILT IN FRACTURE COVER Fracture Cover • We’ll pay up to £ 4, 000 per claim to help with a clients' recovery • Clients can make up to two claims in a 12 month period 36
INCOME PROTECTION ADDITIONAL BENEFITS OF INCOME PROTECTION Fracture cover and hospitalisation payment are included as standard These benefits don't affect the main Income Protection cover so your client won't need to wait for the chosen deferred period to end before making a claim Hospitalisation payment If a client is hospitalised for more than six consecutive nights during their deferred period, we’ll pay £ 100 per night, for up to 90 nights during the term of their cover 37
INCOME PROTECTION ADDITIONAL BENEFITS OF INCOME PROTECTION A fair claims process • In some circumstances, we may be able to arrange for a client’s monthly payments to start before we’ve received all the financial evidence we need Accelerated claims for terminal illness • Terminally ill clients won’t need to wait for their deferred period to end before their monthly payments start Additional payment on death • We pay a lump sum equal to 12 times the monthly premium for their Income Protection 38
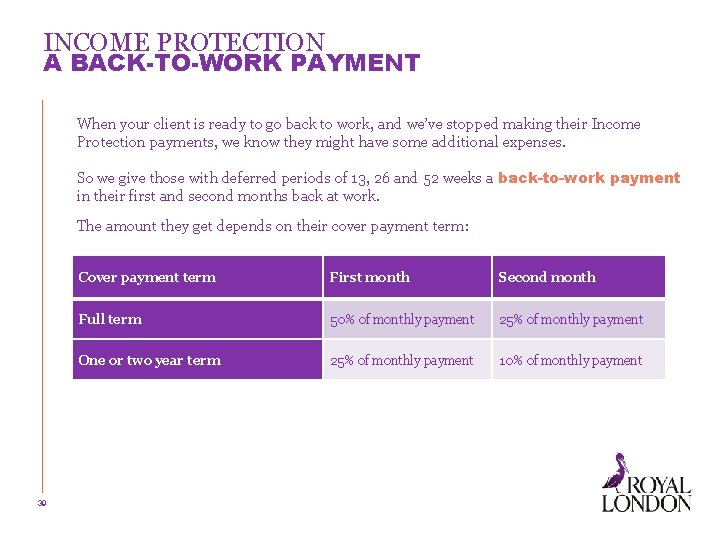
INCOME PROTECTION A BACK-TO-WORK PAYMENT When your client is ready to go back to work, and we’ve stopped making their Income Protection payments, we know they might have some additional expenses. So we give those with deferred periods of 13, 26 and 52 weeks a back-to-work payment in their first and second months back at work. The amount they get depends on their cover payment term: 39 Cover payment term First month Second month Full term 50% of monthly payment 25% of monthly payment One or two year term 25% of monthly payment 10% of monthly payment
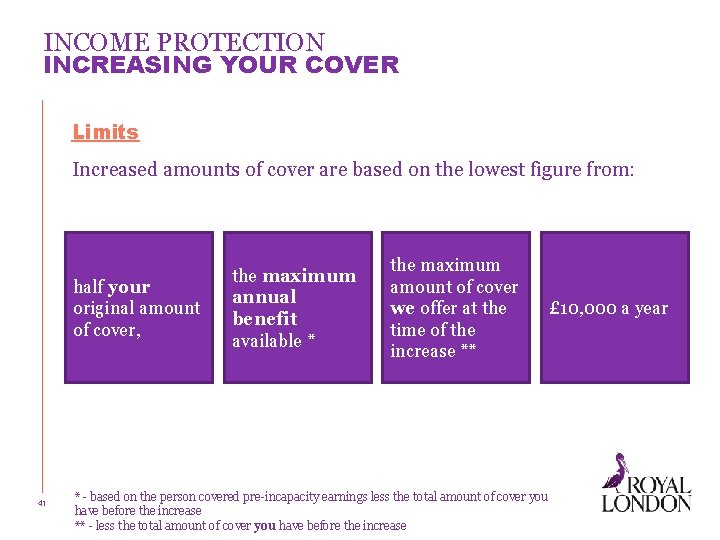
INCOME PROTECTION INCREASING YOUR COVER How it works Clients can increase their Income Protection cover, without giving us any medical information, if • gets married or divorced, or enters into or dissolves a civil partnership • increases their mortgage • has or adopts a child • gets an increase in salary Eligible Clients must be under 55 years of age 40
INCOME PROTECTION INCREASING YOUR COVER Limits Increased amounts of cover are based on the lowest figure from: half your original amount of cover, 41 the maximum annual benefit available * the maximum amount of cover we offer at the time of the increase ** * - based on the person covered pre-incapacity earnings less the total amount of cover you have before the increase ** - less the total amount of cover you have before the increase £ 10, 000 a year
INCOME PROTECTION LEVEL OR INDEXED COVER? • When you apply for Income Protection with Royal London, you can choose Level cover or Indexed cover • When you choose Indexed Cover, you can choose a rate to increase your cover each year by - 2%, 3%, 4%, 5% or Retail Prices Index • Premiums for indexed cover are slightly higher than for level cover 42
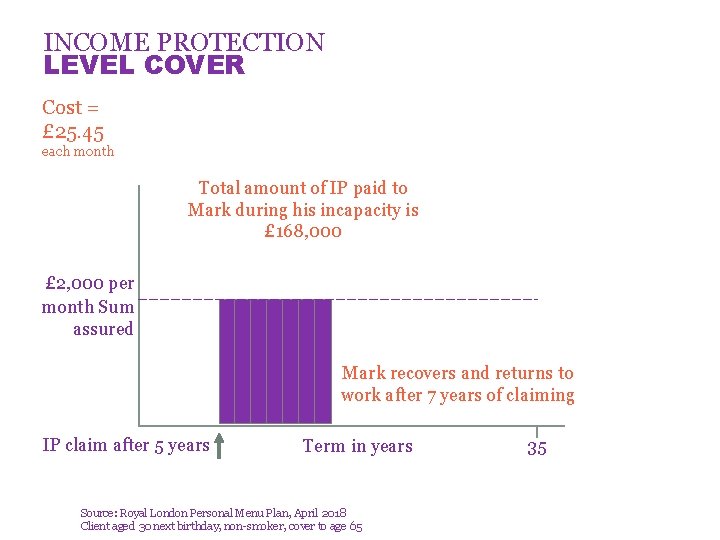
INCOME PROTECTION AN EXAMPLE • Mark 30 nb, Class 1, non smoker • Takes out level Income Protection to cover 50% of his annual income to age 65, D 26 weeks • Salary £ 48, 000 pa • Royal London Income Protection £ 24, 000 pa or £ 2, 000 pm • Mark registers his first Income Protection claim after year 5 • Mark is off work sick for 7 years 43
INCOME PROTECTION LEVEL COVER Cost = £ 25. 45 each month Total amount of IP paid to Mark during his incapacity is £ 168, 000 £ 2, 000 per month Sum assured Mark recovers and returns to work after 7 years of claiming IP claim after 5 years Term in years Source: Royal London Personal Menu Plan, April 2018 Client aged 30 next birthday, non-smoker, cover to age 65 35
INCOME PROTECTION AN EXAMPLE • Lets take a look at the same client scenario again, but this time where Mark has Income Protection from Royal London – indexed @ 5% per annum 45
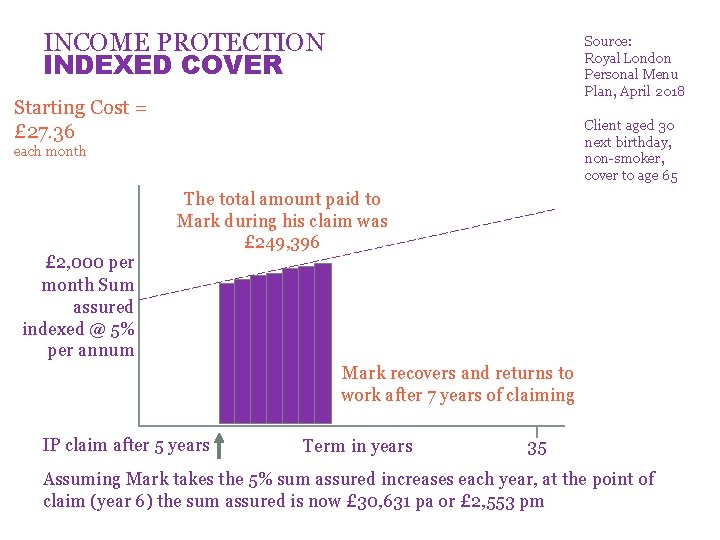
INCOME PROTECTION INDEXED COVER Source: Royal London Personal Menu Plan, April 2018 Starting Cost = £ 27. 36 Client aged 30 next birthday, non-smoker, cover to age 65 each month £ 2, 000 per month Sum assured indexed @ 5% per annum The total amount paid to Mark during his claim was £ 249, 396 Mark recovers and returns to work after 7 years of claiming IP claim after 5 years Term in years 35 Assuming Mark takes the 5% sum assured increases each year, at the point of claim (year 6) the sum assured is now £ 30, 631 pa or £ 2, 553 pm
INCOME PROTECTION AN EXAMPLE • Lets take a look at the same client scenario again, but this time where Mark has Income Protection from Royal London – indexed @ 5% per annum – but chooses not to increase his plan sum assured when we write to him 47
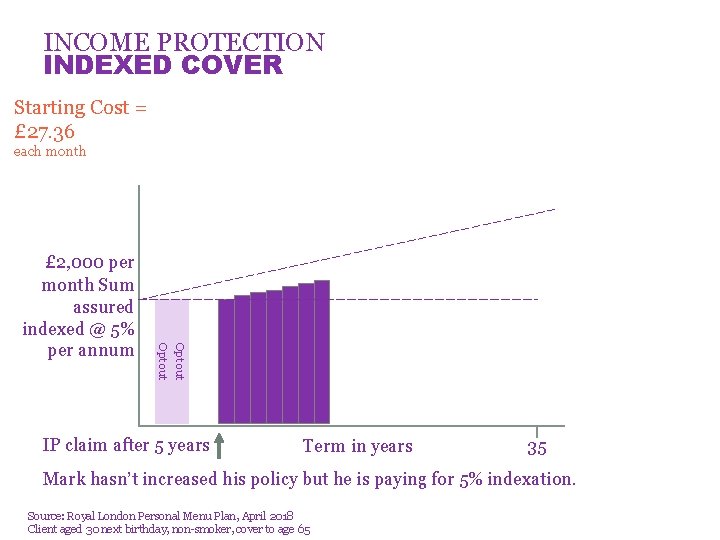
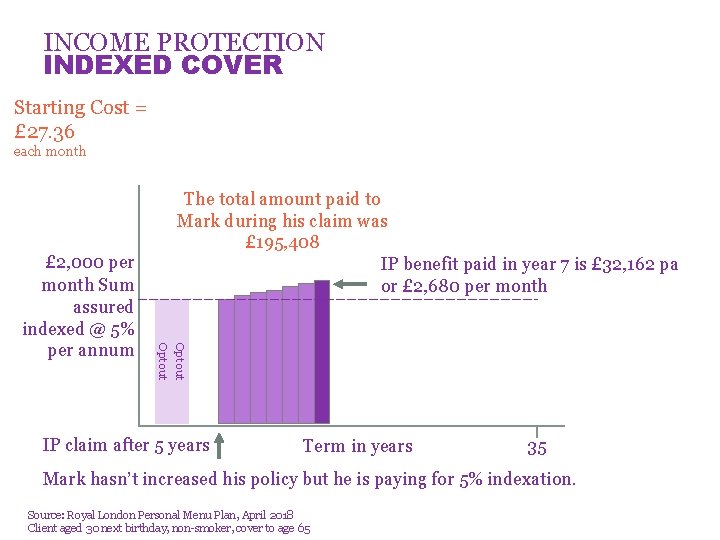
INCOME PROTECTION INDEXED COVER Starting Cost = £ 27. 36 each month Opt out £ 2, 000 per month Sum assured indexed @ 5% per annum IP claim after 5 years Term in years 35 Mark hasn’t increased his policy but he is paying for 5% indexation. Source: Royal London Personal Menu Plan, April 2018 Client aged 30 next birthday, non-smoker, cover to age 65
INCOME PROTECTION INDEXED COVER Starting Cost = £ 27. 36 each month Opt out £ 2, 000 per month Sum assured indexed @ 5% per annum The total amount paid to Mark during his claim was £ 195, 408 IP benefit paid in year 7 is £ 32, 162 pa or £ 2, 680 per month IP claim after 5 years Term in years 35 Mark hasn’t increased his policy but he is paying for 5% indexation. Source: Royal London Personal Menu Plan, April 2018 Client aged 30 next birthday, non-smoker, cover to age 65
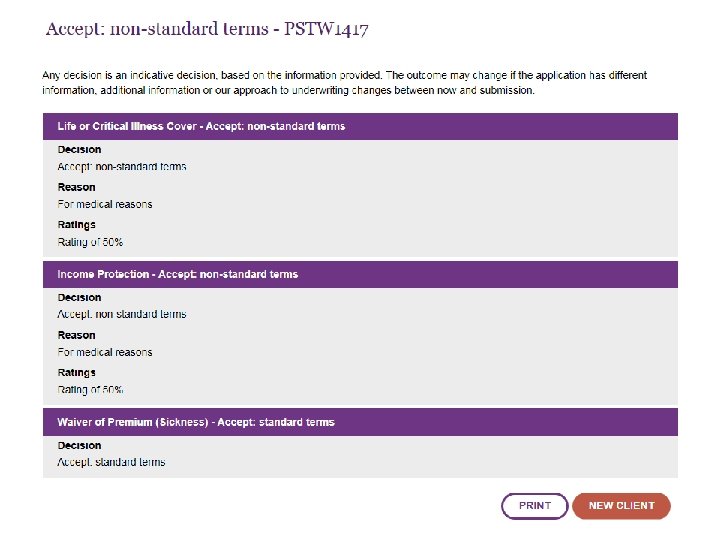
INCOME PROTECTION TOOLS AND REPORTS Marketing studio Create tailored reports to show your clients the risks they face Maximum benefit calculator A quick and easy way to calculate their maximum sum assured Pre-sale underwriting tool Get an accurate indicative underwriting decision online 50 All our tools are available at: adviser. royallondon. com/protection
MORTGAGE PROTECTION
MORTGAGE PROTECTION PEACE OF MIND & FLEXIBILITY Decreasing cover • Sliding scale for interest rates between 0% and 15% Mortgage guarantee • Or you can opt for our mortgage guarantee • Subject to conditions, we guarantee to pay off your outstanding mortgage 52
MORTGAGE PROTECTION INCREASING YOUR COVER How it works Clients can increase their Life or earlier Critical Illness protection cover, without giving us any medical information, if • gets married or divorced, or enters into or dissolves a civil partnership • increases their mortgage • has or adopts a child • gets an increase in salary Eligible clients must be under 55 years of age 53
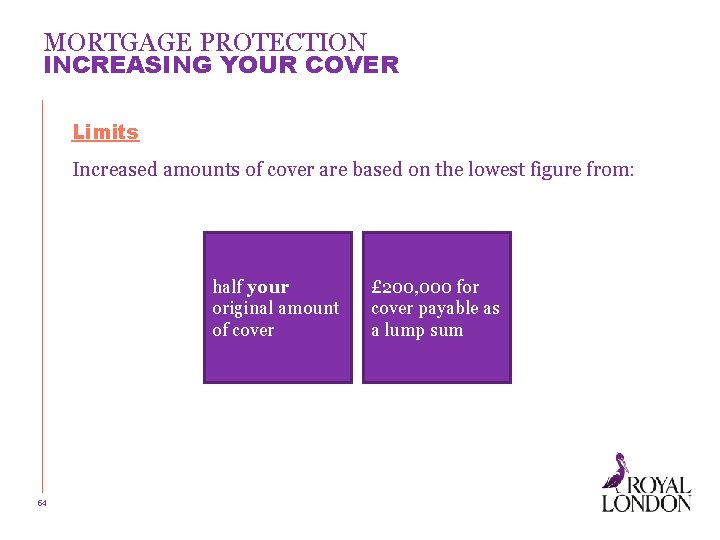
MORTGAGE PROTECTION INCREASING YOUR COVER Limits Increased amounts of cover are based on the lowest figure from: half your original amount of cover 54 £ 200, 000 for cover payable as a lump sum
HELPING HAND TAILORED SUPPORT
SUPPORTING YOU HELPING HAND • Every menu and relevant life plan comes with Helping Hand* • It offers help to your clients whenever they need it • The support is tailored and specific • There's no extra cost • Available from the day their plan starts even if there's no claim *Helping Hand is a package of support services, provided by third parties that aren’t regulated by the Financial Conduct Authority. These services aren’t part of our terms and conditions, so can be amended or withdrawn at any time.
SUPPORT SERVICE HELPING HAND • Access to a dedicated nurse • Extra practical and emotional support such as: • • • 57 A second medical opinion Specialist nursing support Bereavement counselling Complementary therapies Physiotherapy Arrange specialist support to help someone cope with cancer • Cardiac rehabilitation support after heart attack • Specialist speech and language therapy • • • Counselling for a wide range of issues including coping with the loss of someone Practical help at home Help for carers Extra information such as medical factsheets Home visit from a healthcare specialist Living aids and mobility equipment
SUPPORT SERVICE REAL STORIES HELPING HAND 58
EASY TO DO BUSINESS WITH 59
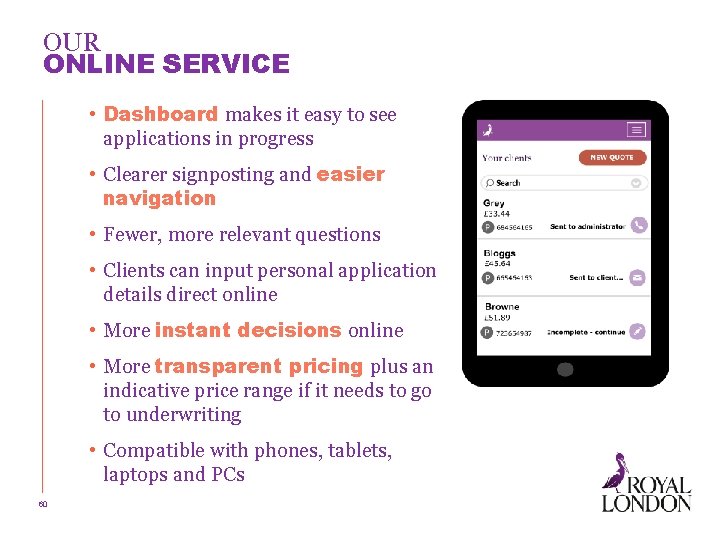
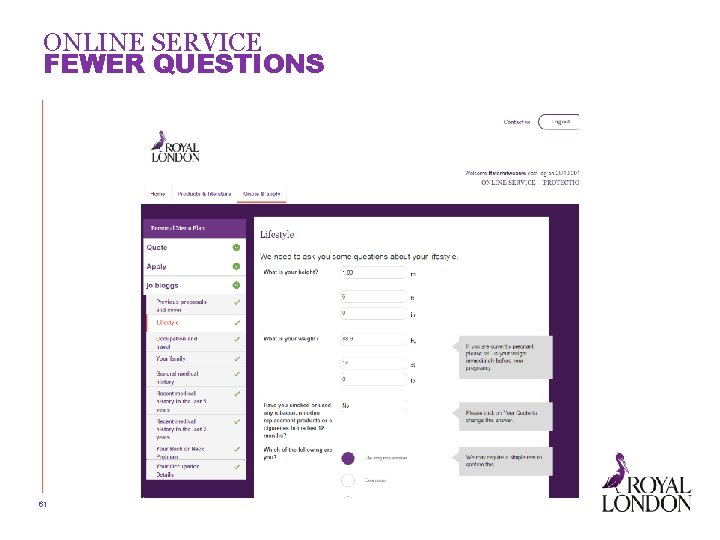
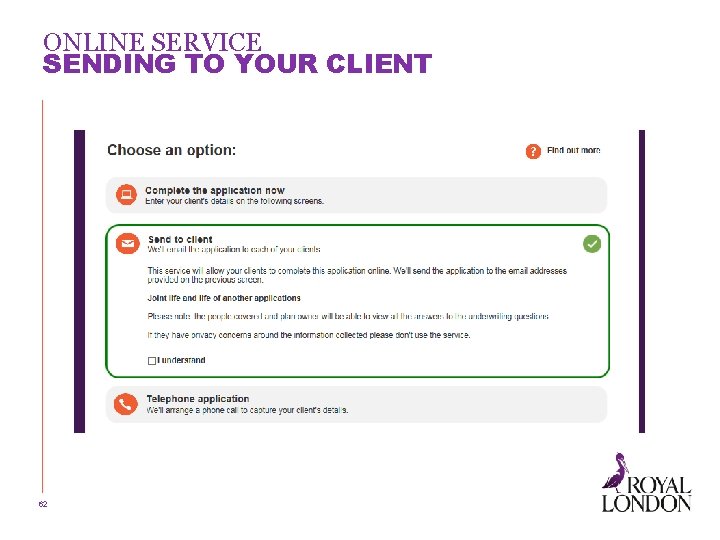
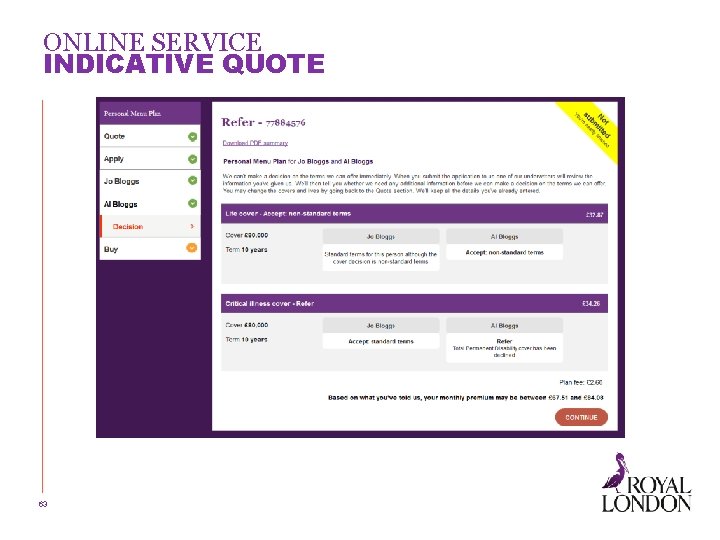
OUR ONLINE SERVICE • Dashboard makes it easy to see applications in progress • Clearer signposting and easier navigation • Fewer, more relevant questions • Clients can input personal application details direct online • More instant decisions online • More transparent pricing plus an indicative price range if it needs to go to underwriting • Compatible with phones, tablets, laptops and PCs 60
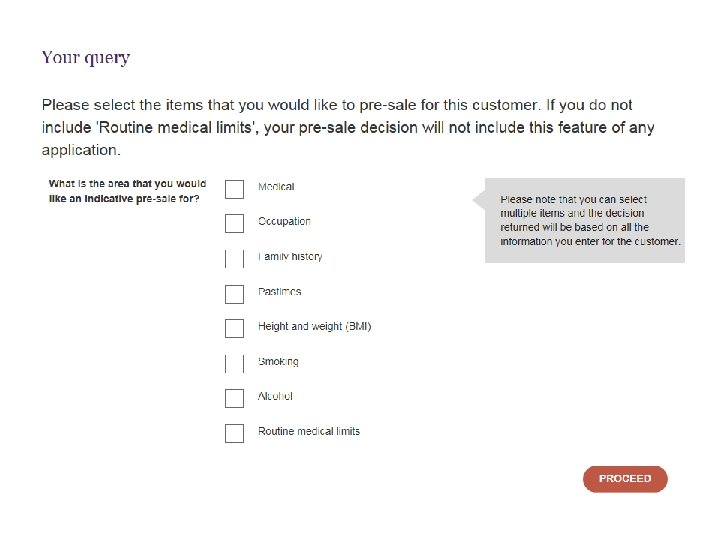
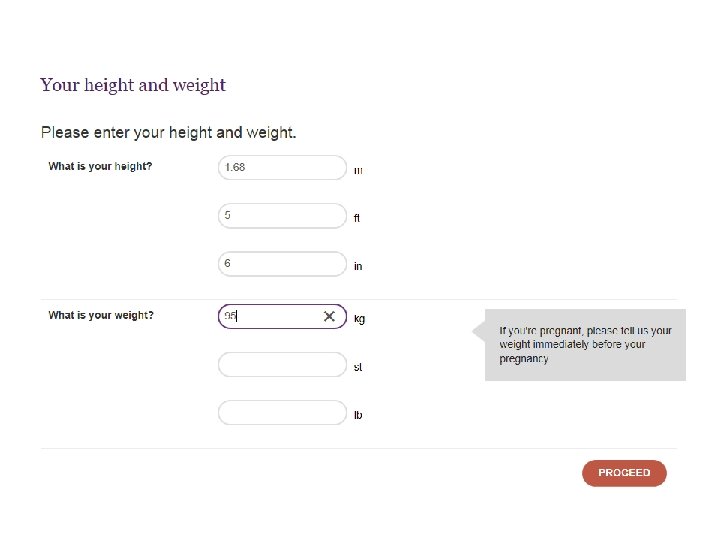
ONLINE SERVICE FEWER QUESTIONS 61
ONLINE SERVICE SENDING TO YOUR CLIENT 62
ONLINE SERVICE INDICATIVE QUOTE 63
ADDED VALUE MARKETING STUDIO 64
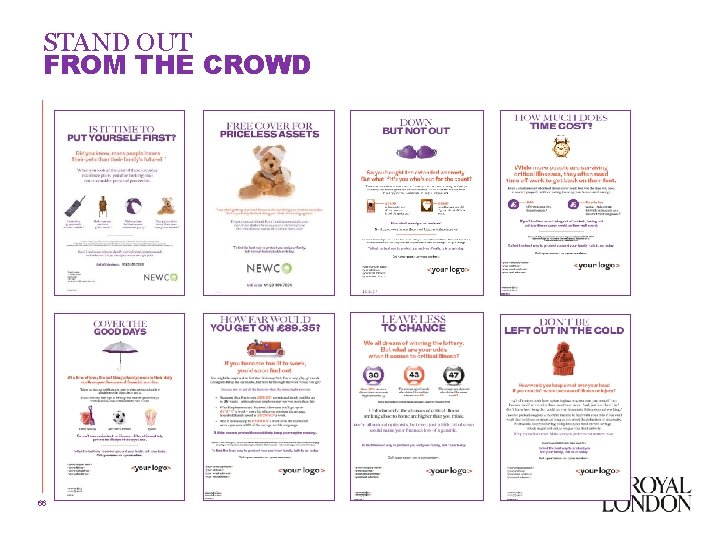
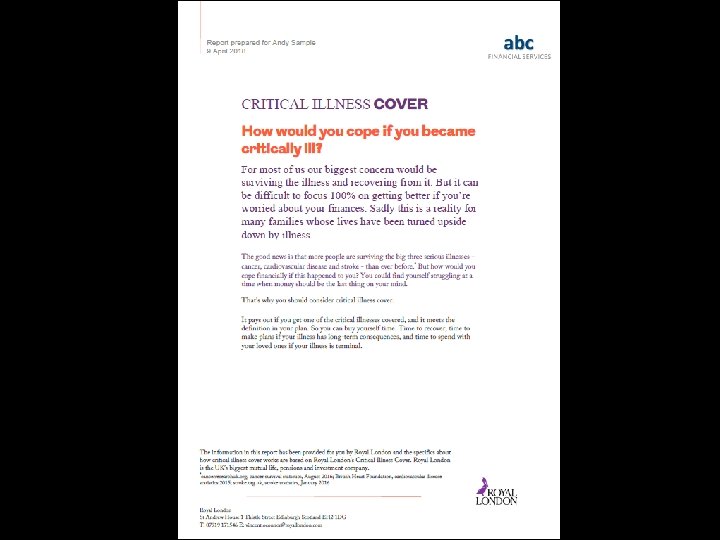
MARKETING STUDIO A useful tool to help you grow your business • Extensive sales and marketing material – choose from a range of posters and sales aids • Use the Royal London version or add your own branding • Run individual critical illness reports, access forms and fact finds 65
STAND OUT FROM THE CROWD 66
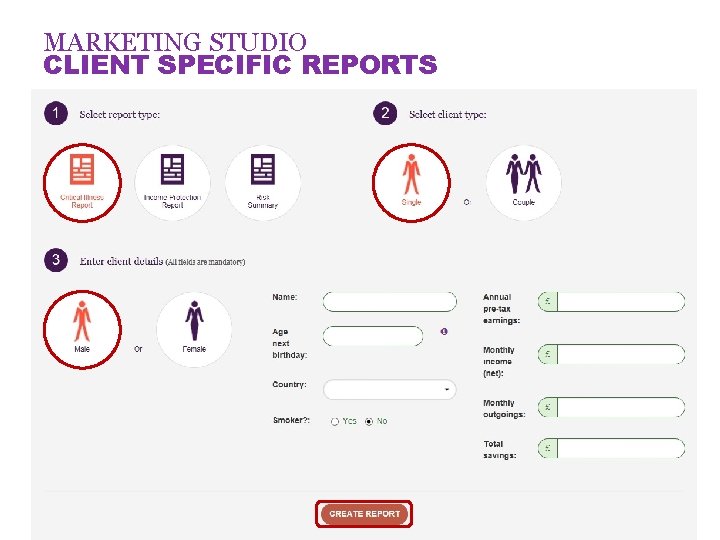
MARKETING STUDIO CLIENT SPECIFIC REPORTS
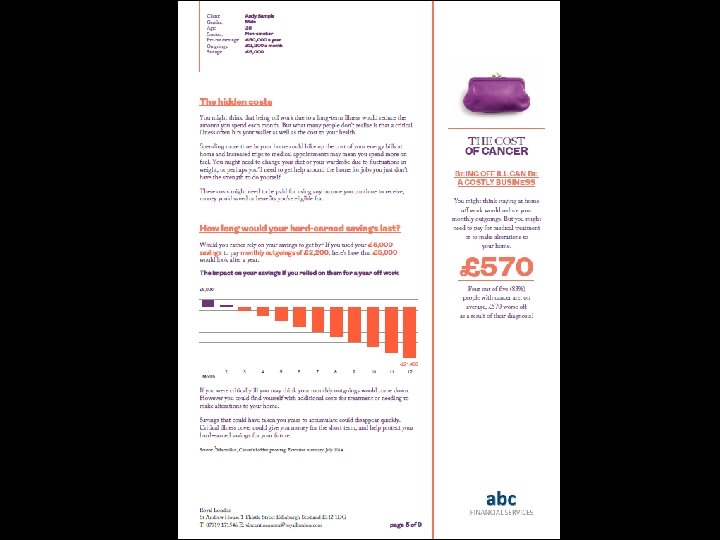
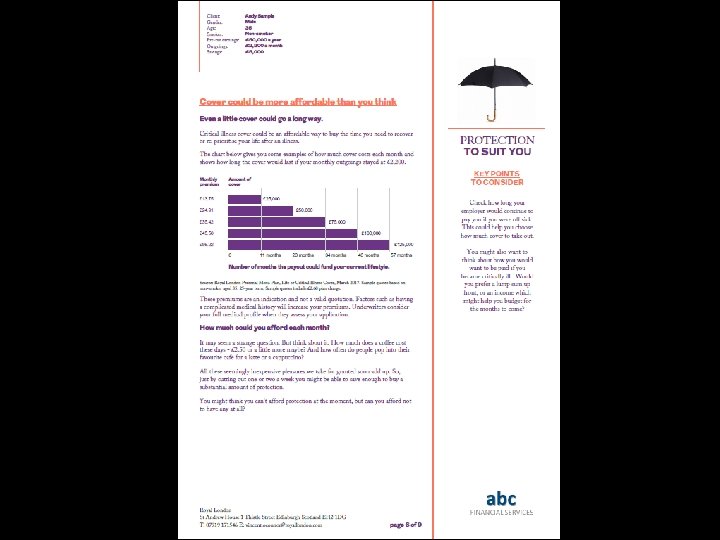
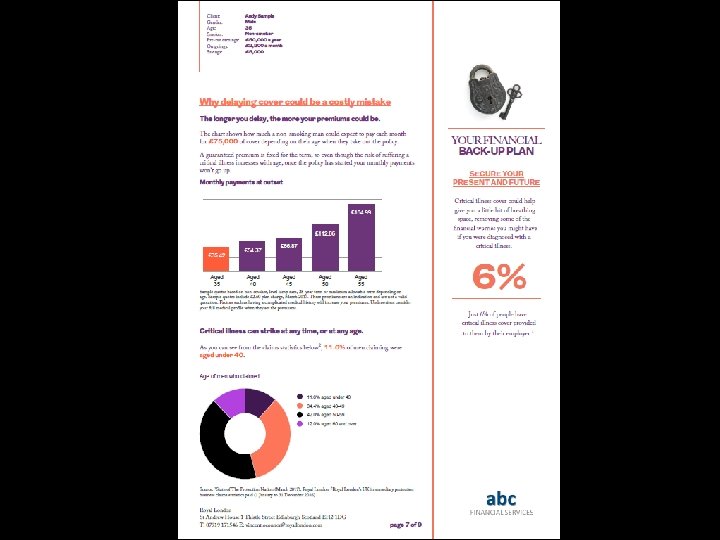
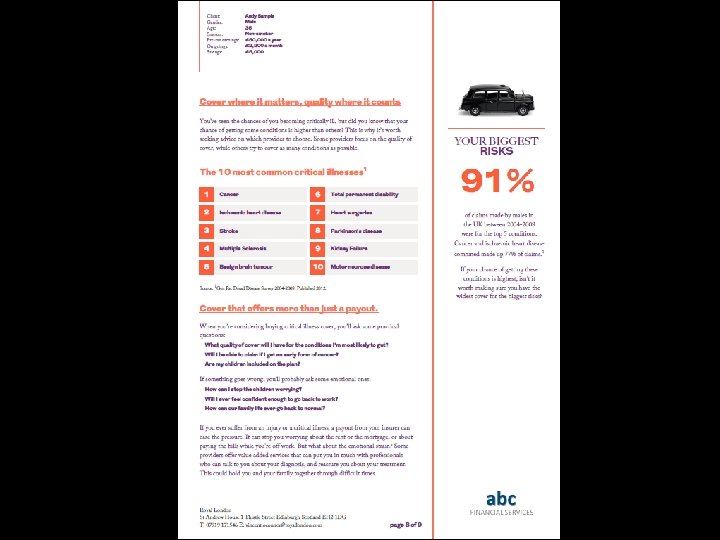
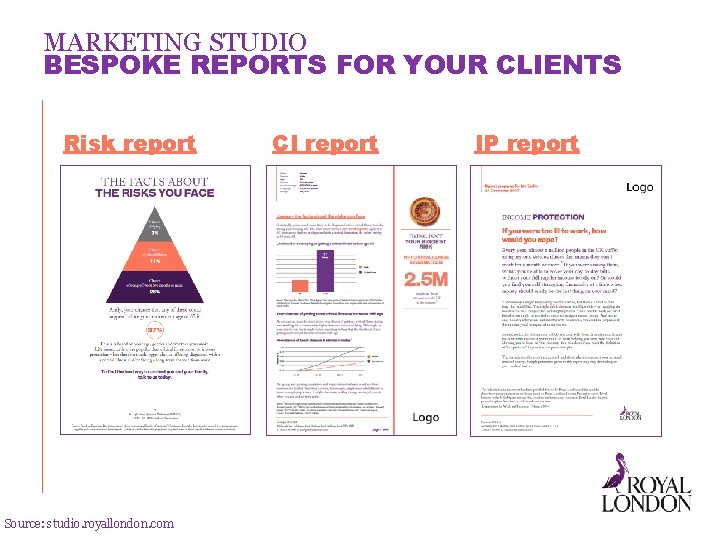
MARKETING STUDIO BESPOKE REPORTS FOR YOUR CLIENTS Risk report Source: studio. royallondon. com CI report IP report
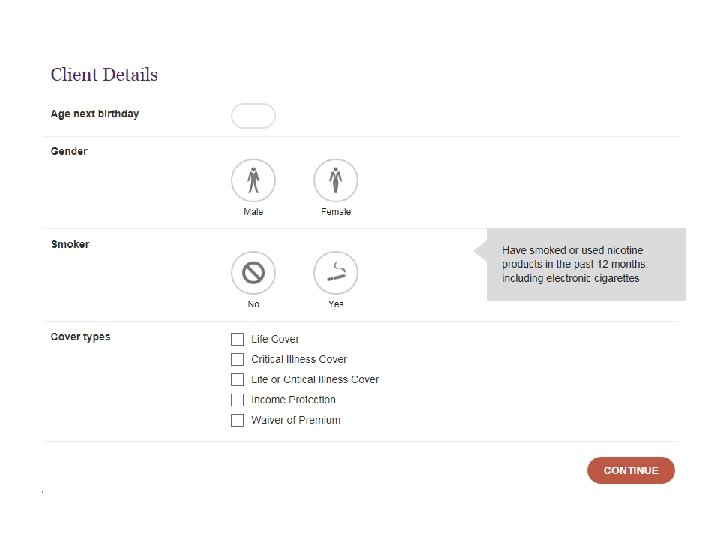
HELP WITH UNDERWRITING OUR ONLINE TOOL
DIRECT ACCESS TO AN UNDERWRITER Speak to the right people when you need to: • You’ll have a dedicated underwriter for each plan • Call or email your underwriter with any questions from pre-sale onwards • If you have specific concerns, our experienced underwriters can assess the case and confirm our best terms 84
LIFESTYLE REVIEW
LIFESTYLE REVIEW BECAUSE THINGS CHANGE… What is it? • If cover is accepted on non standard terms or smoker rates, and your lifestyle changes, we may be able to reduce your premium • Just give us a call Examples • Giving up Smoking • No longer participating in hazardous sports • Reduced BMI • Improved Health – i. e. blood pressure / cholesterol 86
SPREADING THE RISK BUILDING A PLAN
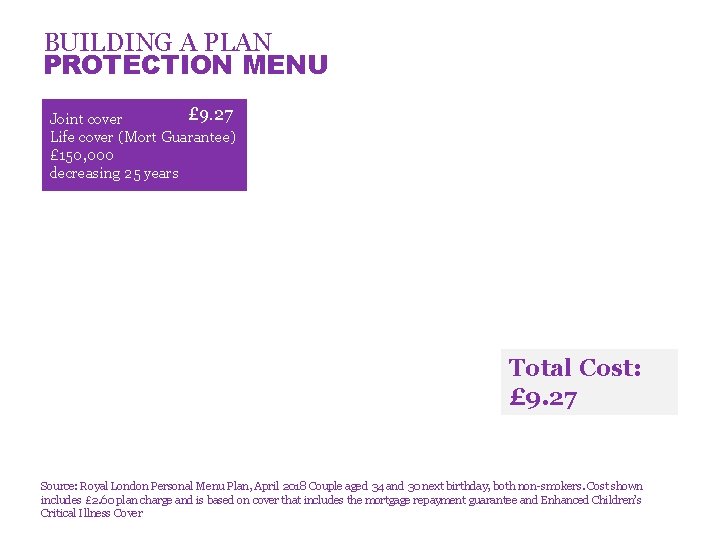
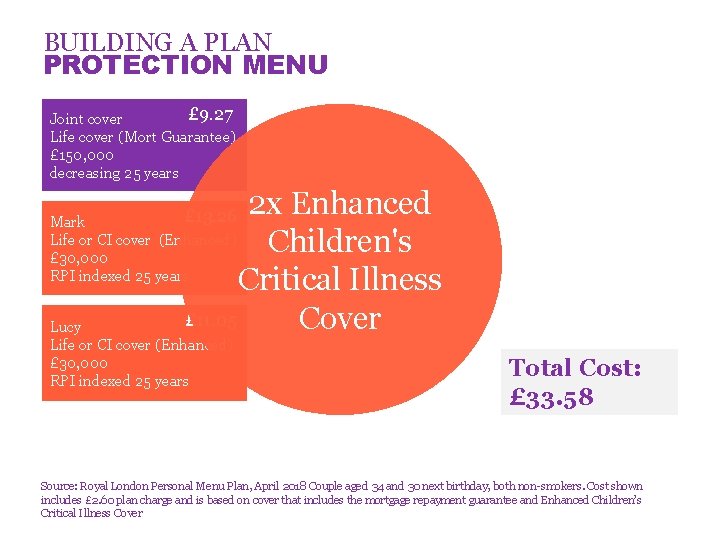
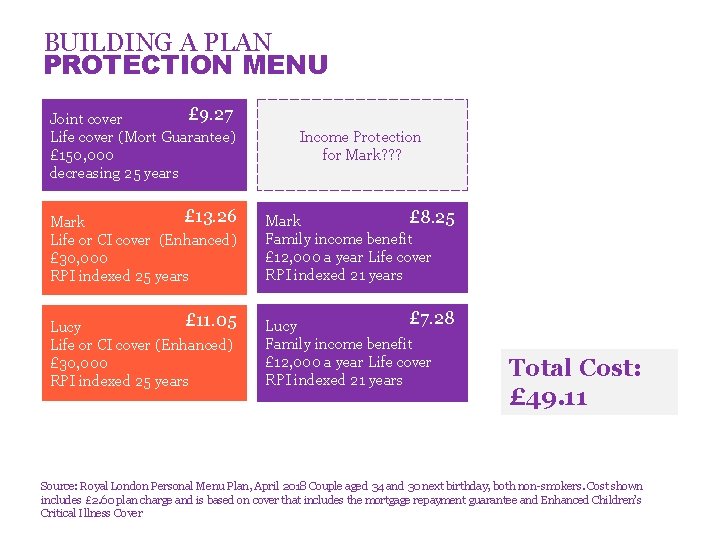
BUILDING A PLAN AN EXAMPLE • Mark 34 nb, Lucy 30 nb • Both non-smokers • Are expecting their first child • Just taken out a mortgage of £ 150, 000 over 25 years • Mark is main breadwinner on £ 40, 000 a year • No protection in place • Budget for protection is around £ 50 a month
BUILDING A PLAN PROTECTION MENU £ 9. 27 Joint cover Life cover (Mort Guarantee) £ 150, 000 decreasing 25 years Total Cost: £ 9. 27 Source: Royal London Personal Menu Plan, April 2018 Couple aged 34 and 30 next birthday, both non-smokers. Cost shown includes £ 2. 60 plan charge and is based on cover that includes the mortgage repayment guarantee and Enhanced Children’s Critical Illness Cover
BUILDING A PLAN PROTECTION MENU £ 9. 27 Joint cover Life cover (Mort Guarantee) £ 150, 000 decreasing 25 years 2 x Enhanced Children's Critical Illness £ 11. 05 Cover £ 13. 26 Mark Life or CI cover (Enhanced) £ 30, 000 RPI indexed 25 years Lucy Life or CI cover (Enhanced) £ 30, 000 RPI indexed 25 years Total Cost: £ 33. 58 £ 22. 53 £ 9. 27 Source: Royal London Personal Menu Plan, April 2018 Couple aged 34 and 30 next birthday, both non-smokers. Cost shown includes £ 2. 60 plan charge and is based on cover that includes the mortgage repayment guarantee and Enhanced Children’s Critical Illness Cover
BUILDING A PLAN PROTECTION MENU £ 9. 27 Joint cover Life cover (Mort Guarantee) £ 150, 000 decreasing 25 years Income Protection for Mark? ? ? £ 13. 26 Mark Life or CI cover (Enhanced) £ 30, 000 RPI indexed 25 years £ 8. 25 Mark Family income benefit £ 12, 000 a year Life cover RPI indexed 21 years £ 11. 05 Lucy Life or CI cover (Enhanced) £ 30, 000 RPI indexed 25 years £ 7. 28 Lucy Family income benefit £ 12, 000 a year Life cover RPI indexed 21 years Total Cost: £ 49. 11 £ 41. 83 £ 33. 58 £ 20. 45 £ 8. 57 Source: Royal London Personal Menu Plan, April 2018 Couple aged 34 and 30 next birthday, both non-smokers. Cost shown includes £ 2. 60 plan charge and is based on cover that includes the mortgage repayment guarantee and Enhanced Children’s Critical Illness Cover
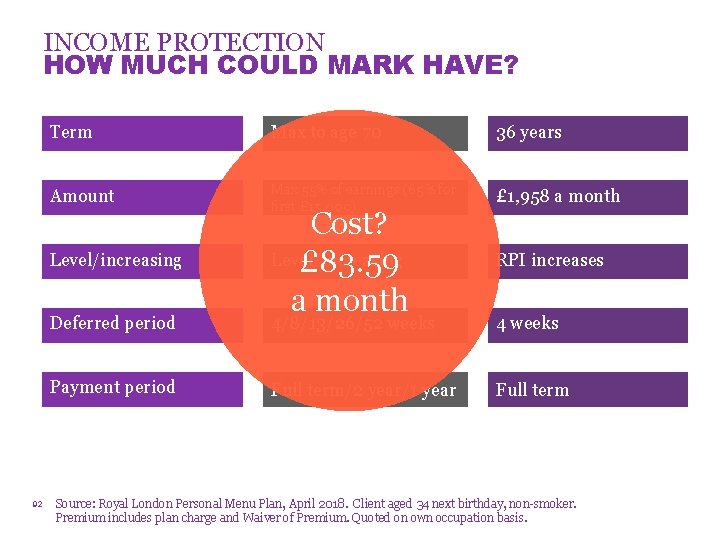
INCOME PROTECTION HOW MUCH COULD MARK HAVE? Term Max to age 70 36 years Amount Max 55% of earnings (65% for first £ 15, 000) £ 1, 958 a month Level/increasing Deferred period Payment period 92 Cost? Level/increasing £ 83. 59 a month RPI increases 4/8/13/26/52 weeks 4 weeks Full term/2 year/1 year Full term Source: Royal London Personal Menu Plan, April 2018. Client aged 34 next birthday, non-smoker. Premium includes plan charge and Waiver of Premium. Quoted on own occupation basis.
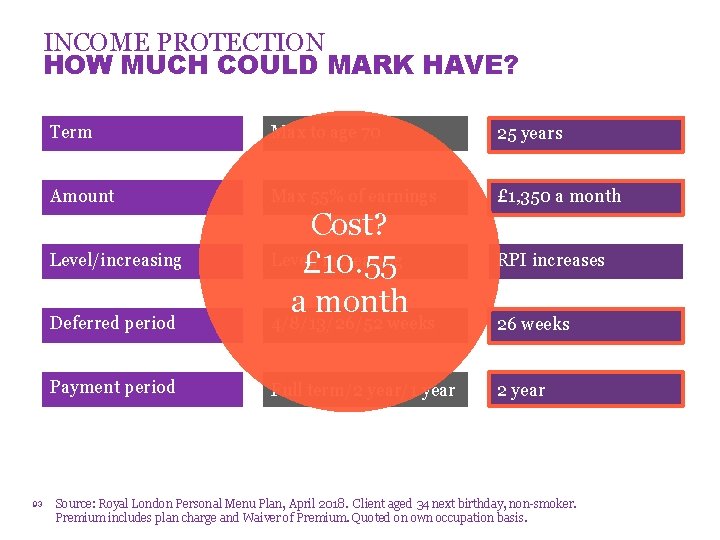
INCOME PROTECTION HOW MUCH COULD MARK HAVE? Term Max to age 70 36 years 25 Amount Max 55% of earnings £ 1, 350 £ 1, 958 a month Level/increasing Deferred period Payment period 93 Cost? Level/increasing £ 10. 55 a month RPI increases 4/8/13/26/52 weeks 26 weeks 4 weeks Full term/2 year/1 year 2 Full year term Source: Royal London Personal Menu Plan, April 2018. Client aged 34 next birthday, non-smoker. Premium includes plan charge and Waiver of Premium. Quoted on own occupation basis.
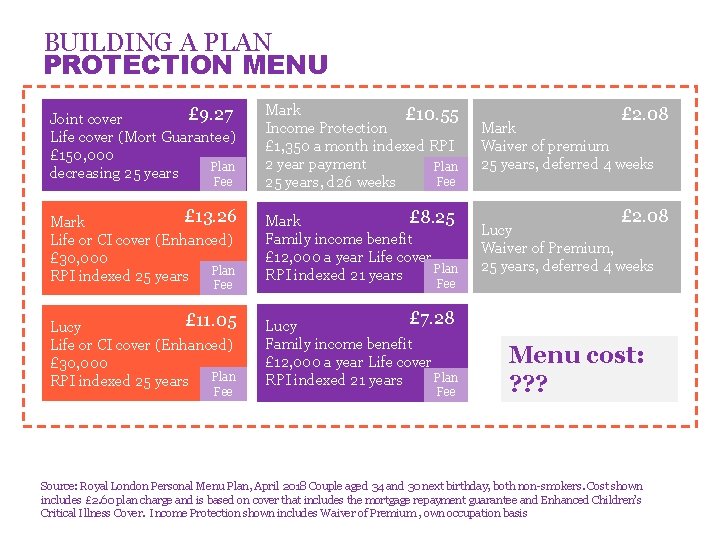
BUILDING A PLAN PROTECTION MENU £ 9. 27 Joint cover Life cover (Mort Guarantee) £ 150, 000 Plan decreasing 25 years Mark £ 10. 55 Income Protection £ 1, 350 a month indexed RPI 2 year payment Plan Fee 25 years, d 26 weeks Mark Waiver of premium 25 years, deferred 4 weeks £ 13. 26 Mark Life or CI cover (Enhanced) £ 30, 000 RPI indexed 25 years Plan £ 8. 25 Mark Family income benefit £ 12, 000 a year Life cover Plan RPI indexed 21 years Lucy Waiver of Premium, 25 years, deferred 4 weeks £ 11. 05 Lucy Life or CI cover (Enhanced) £ 30, 000 RPI indexed 25 years Plan £ 7. 28 Lucy Family income benefit £ 12, 000 a year Life cover Plan RPI indexed 21 years Fee Fee £ 2. 08 Fee Total Menu. Cost: cost: £ 8. 57 £ 38. 28 £ 30. 03 £ 20. 45 £ 59. 66 £ 49. 11 ? ? ? Source: Royal London Personal Menu Plan, April 2018 Couple aged 34 and 30 next birthday, both non-smokers. Cost shown includes £ 2. 60 plan charge and is based on cover that includes the mortgage repayment guarantee and Enhanced Children’s Critical Illness Cover. Income Protection shown includes Waiver of Premium , own occupation basis
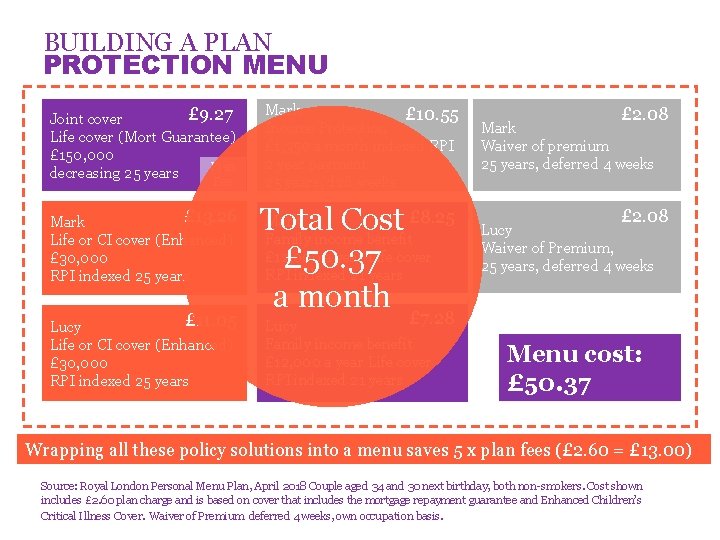
BUILDING A PLAN PROTECTION MENU £ 9. 27 Joint cover Life cover (Mort Guarantee) £ 150, 000 Plan decreasing 25 years Mark £ 10. 55 Income Protection £ 1, 350 a month indexed RPI 2 year payment 25 years, d 26 weeks £ 13. 26 Mark Life or CI cover (Enhanced) £ 30, 000 RPI indexed 25 years £ 8. 25 Mark Total Cost Family income benefit £ 12, 000 a year Life cover £ 50. 37 RPI indexed 21 years a month Fee £ 11. 05 Lucy Life or CI cover (Enhanced) £ 30, 000 RPI indexed 25 years £ 7. 28 Lucy Family income benefit £ 12, 000 a year Life cover RPI indexed 21 years £ 2. 08 Mark Waiver of premium 25 years, deferred 4 weeks £ 2. 08 Lucy Waiver of Premium, 25 years, deferred 4 weeks Menu cost: Cost: £ 50. 37 ? ? ? Wrapping all these policy solutions into a menu saves 5 x plan fees (£ 2. 60 = £ 13. 00) Source: Royal London Personal Menu Plan, April 2018 Couple aged 34 and 30 next birthday, both non-smokers. Cost shown includes £ 2. 60 plan charge and is based on cover that includes the mortgage repayment guarantee and Enhanced Children’s Critical Illness Cover. Waiver of Premium deferred 4 weeks, own occupation basis.
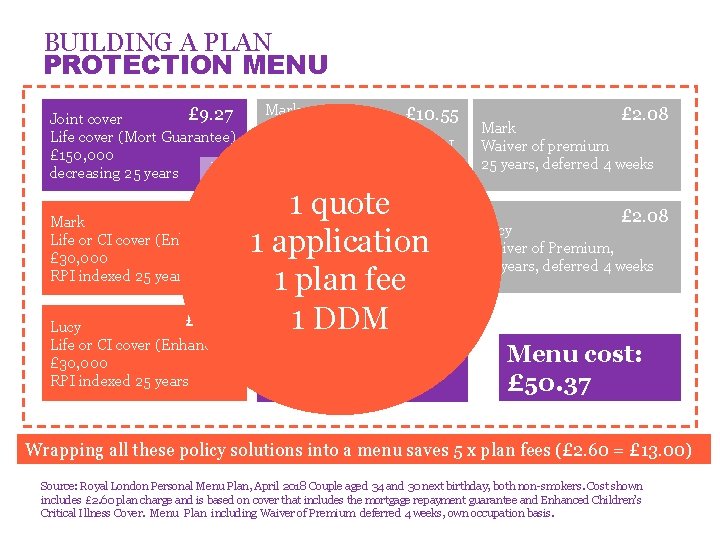
BUILDING A PLAN PROTECTION MENU £ 9. 27 Joint cover Life cover (Mort Guarantee) £ 150, 000 Plan decreasing 25 years Fee £ 13. 26 Mark Life or CI cover (Enhanced) £ 30, 000 RPI indexed 25 years £ 11. 05 Lucy Life or CI cover (Enhanced) £ 30, 000 RPI indexed 25 years Mark £ 10. 55 Income Protection £ 1, 350 a month indexed RPI 2 year payment 25 years, d 26 weeks Mark Waiver of premium 25 years, deferred 4 weeks £ 8. 25 Mark Family income benefit £ 12, 000 a year Life cover RPI indexed 21 years Lucy Waiver of Premium, 25 years, deferred 4 weeks 1 quote 1 application 1 plan fee Lucy 1 DDM £ 7. 28 Family income benefit £ 12, 000 a year Life cover RPI indexed 21 years £ 2. 08 Menu cost: £ 50. 37 Wrapping all these policy solutions into a menu saves 5 x plan fees (£ 2. 60 = £ 13. 00) Source: Royal London Personal Menu Plan, April 2018 Couple aged 34 and 30 next birthday, both non-smokers. Cost shown includes £ 2. 60 plan charge and is based on cover that includes the mortgage repayment guarantee and Enhanced Children’s Critical Illness Cover. Menu Plan including Waiver of Premium deferred 4 weeks, own occupation basis.
SUMMARY
OUR PROPOSITION IN SUMMARY • Overview to our proposition • Easy to do business with • Critical Illness Cover • Enhanced Children’s Critical • Underwriting • Lifestyle review Illness • Marketing Studio • Family income benefit • Building a plan with • Income Protection Royal London • Mortgage protection • Helping Hand 98
adviser. royallondon. com THANK YOU The Royal London Mutual Insurance Society Limited is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority. The firm is on the Financial Services Register, registration number 117672. It provides life assurance and pensions and is a member of the Association of British Insurers and the Association of Financial Mutuals. Registered in England Wales number 99064. Registered office: 55 Gracechurch Street, London EC 3 V 0 RL. Royal London Marketing Limited is authorised and regulated by the Financial Conduct Authority and introduces Royal London’s customers to other insurance companies. The firm is on the Financial Services Register, registration number 302391. Registered in England Wales number 4414137. Registered office: 55 Gracechurch Street, London, EC 3 V 0 RL. May 2018 PR P 8 PN 0093