
RON EZRA TUVAL Founder Managing Director IPesa International
- Slides: 26
RON EZRA TUVAL Founder & Managing Director I-Pesa International Inc. (incorporated in Delaware) ron@l-pesa. com Phone: +97 254 4682519 L-Pesa Microfinance www. l-pesa. com
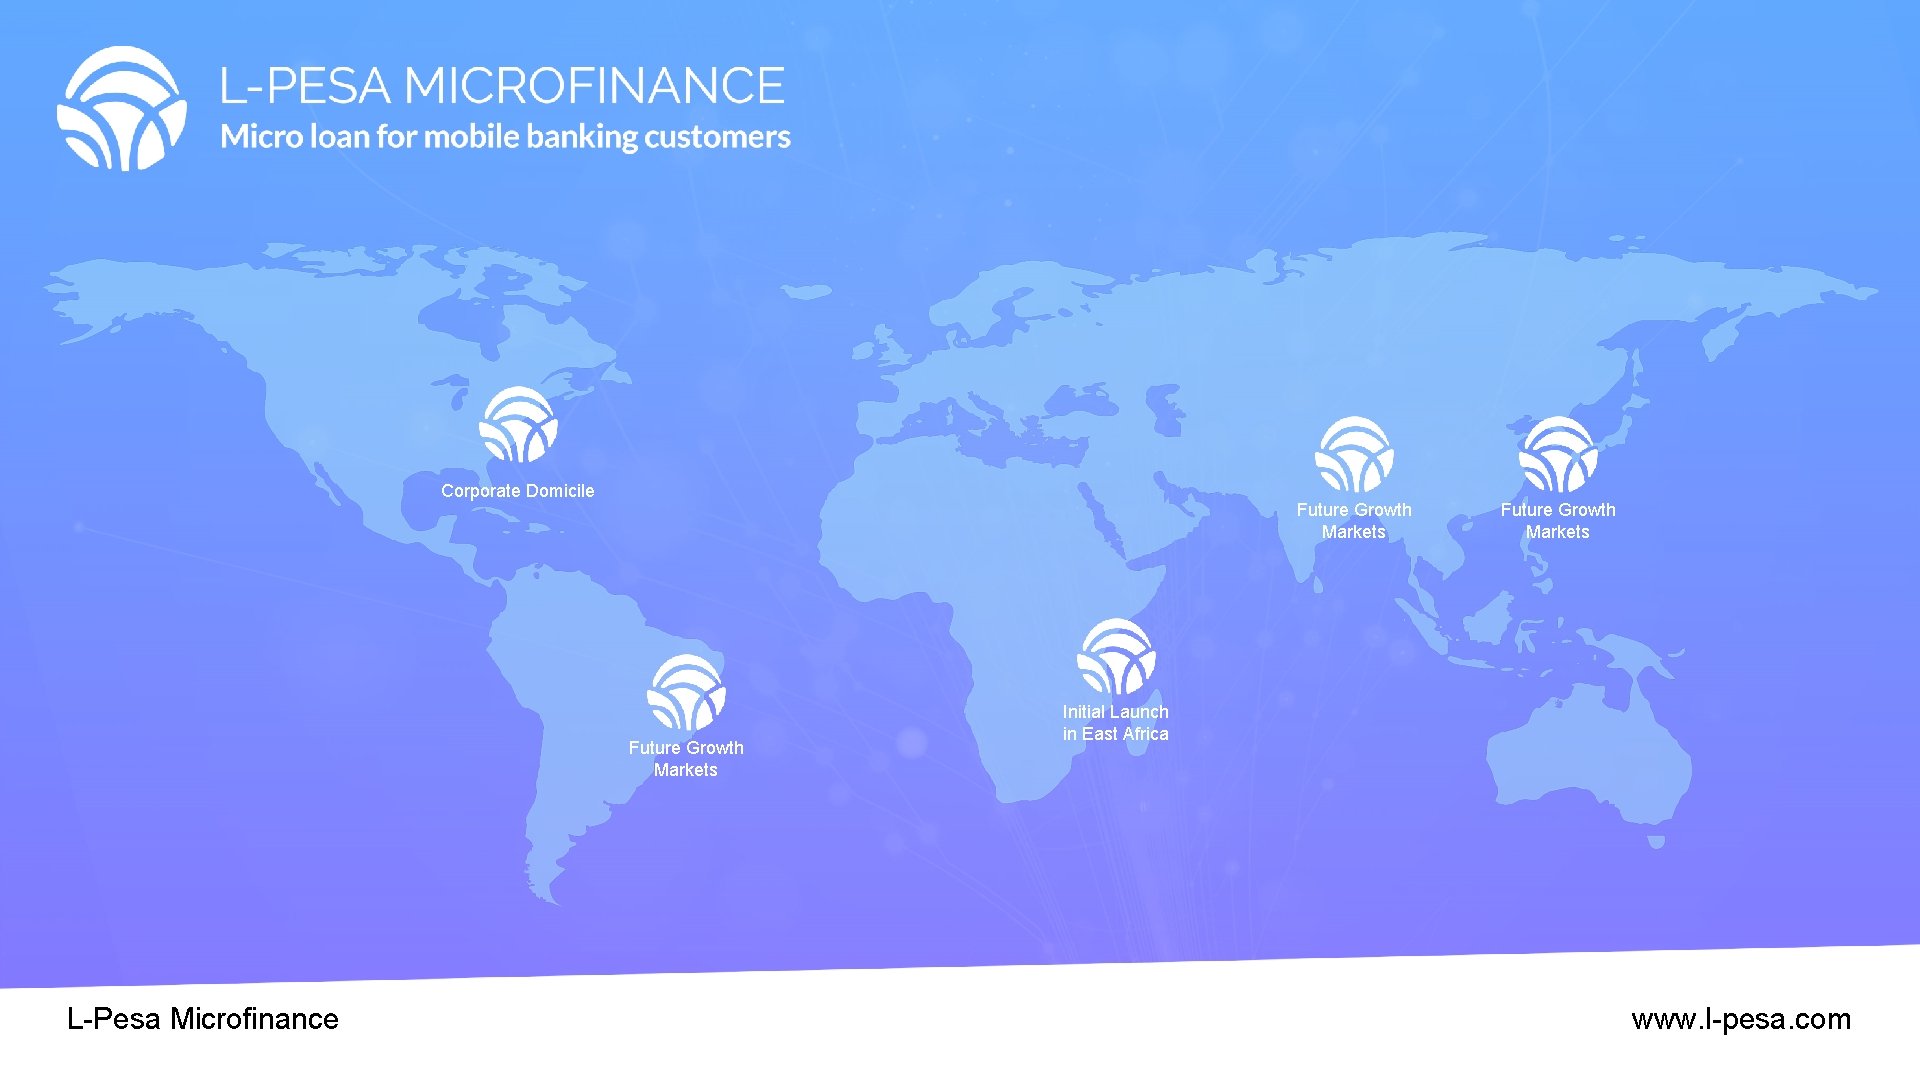
Corporate Domicile Future Growth Markets L-Pesa Microfinance Future Growth Markets Initial Launch in East Africa www. l-pesa. com
Launched to take advantage of market forces revolutionizing finance First loan issued in Tanzania 20 months ago Over 150, 000 registered users, over 25, 000 loans issued Effective user acquisition engine developed Loss ratio below 10% L-Pesa Microfinance www. l-pesa. com
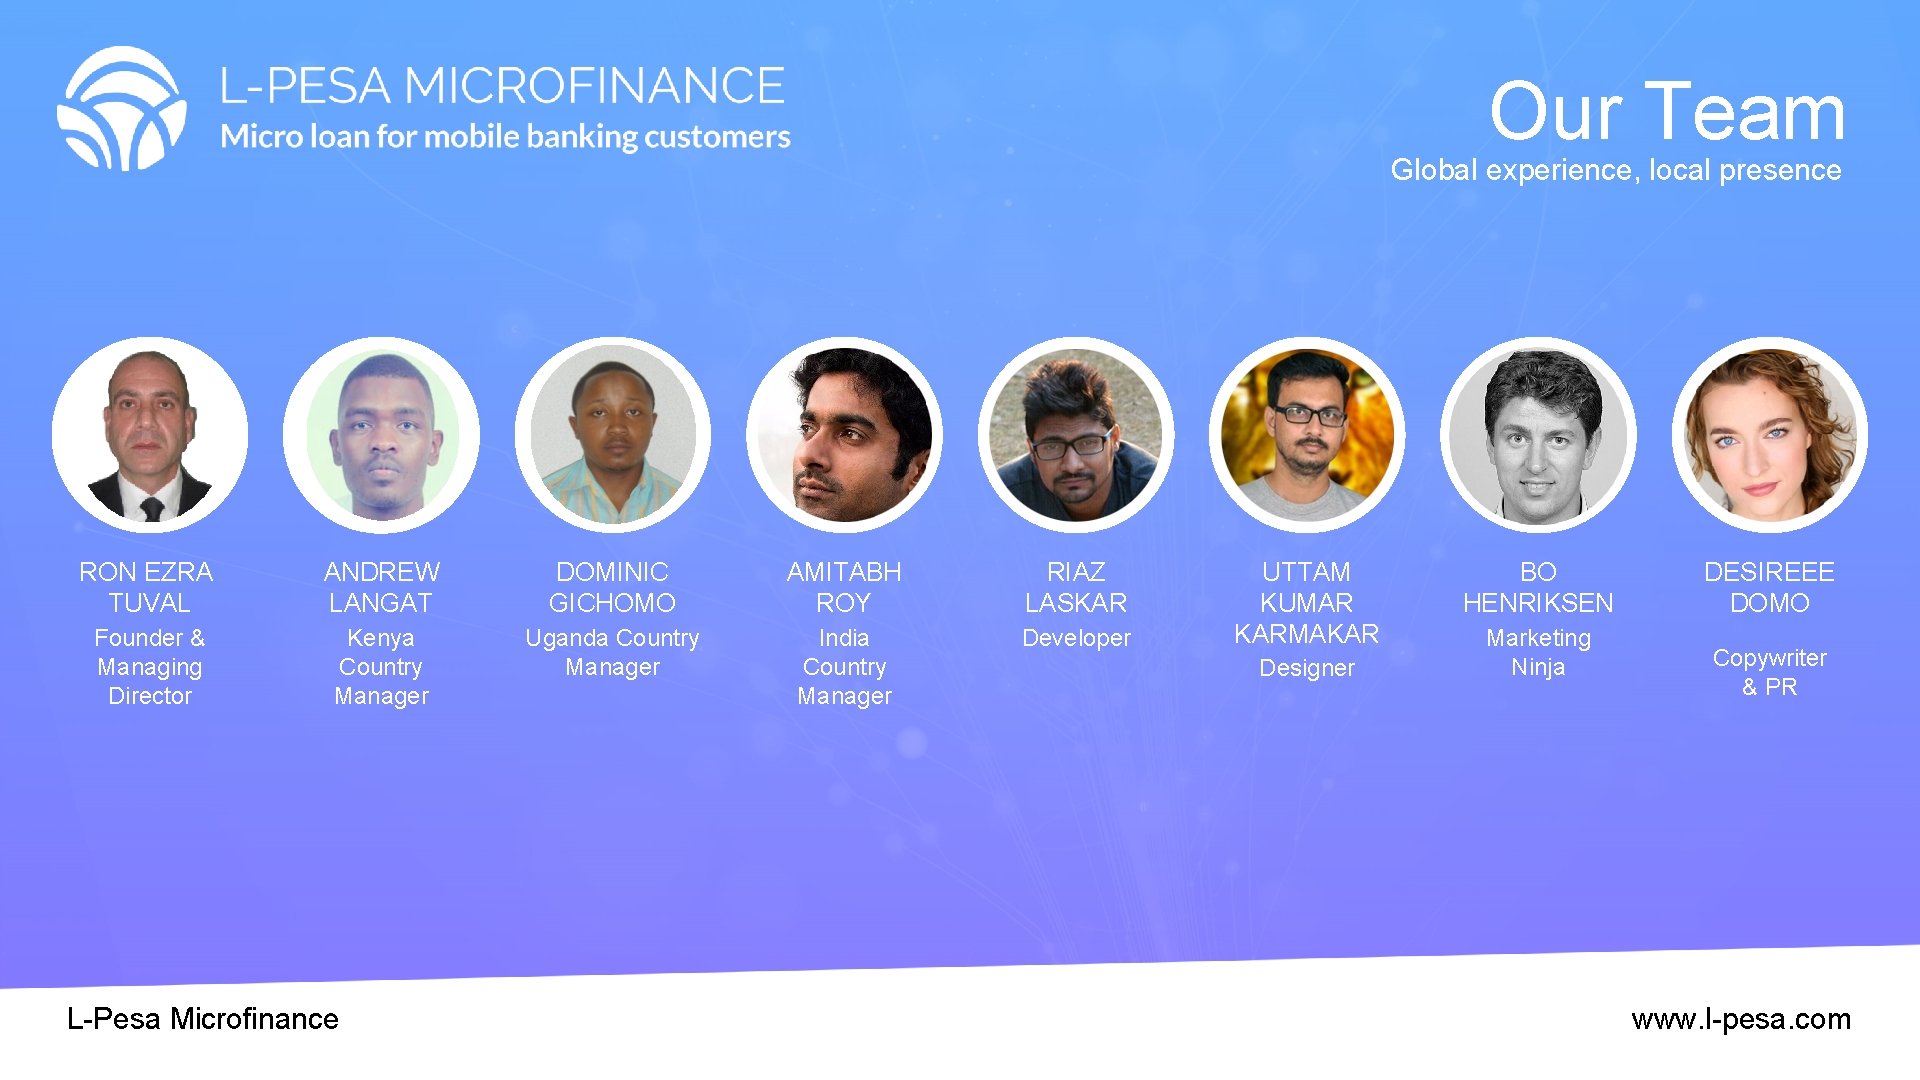
Our Team Global experience, local presence RON EZRA TUVAL ANDREW LANGAT DOMINIC GICHOMO AMITABH ROY RIAZ LASKAR Founder & Managing Director Kenya Country Manager Uganda Country Manager India Country Manager Developer L-Pesa Microfinance UTTAM KUMAR KARMAKAR Designer BO HENRIKSEN Marketing Ninja DESIREEE DOMO Copywriter & PR www. l-pesa. com
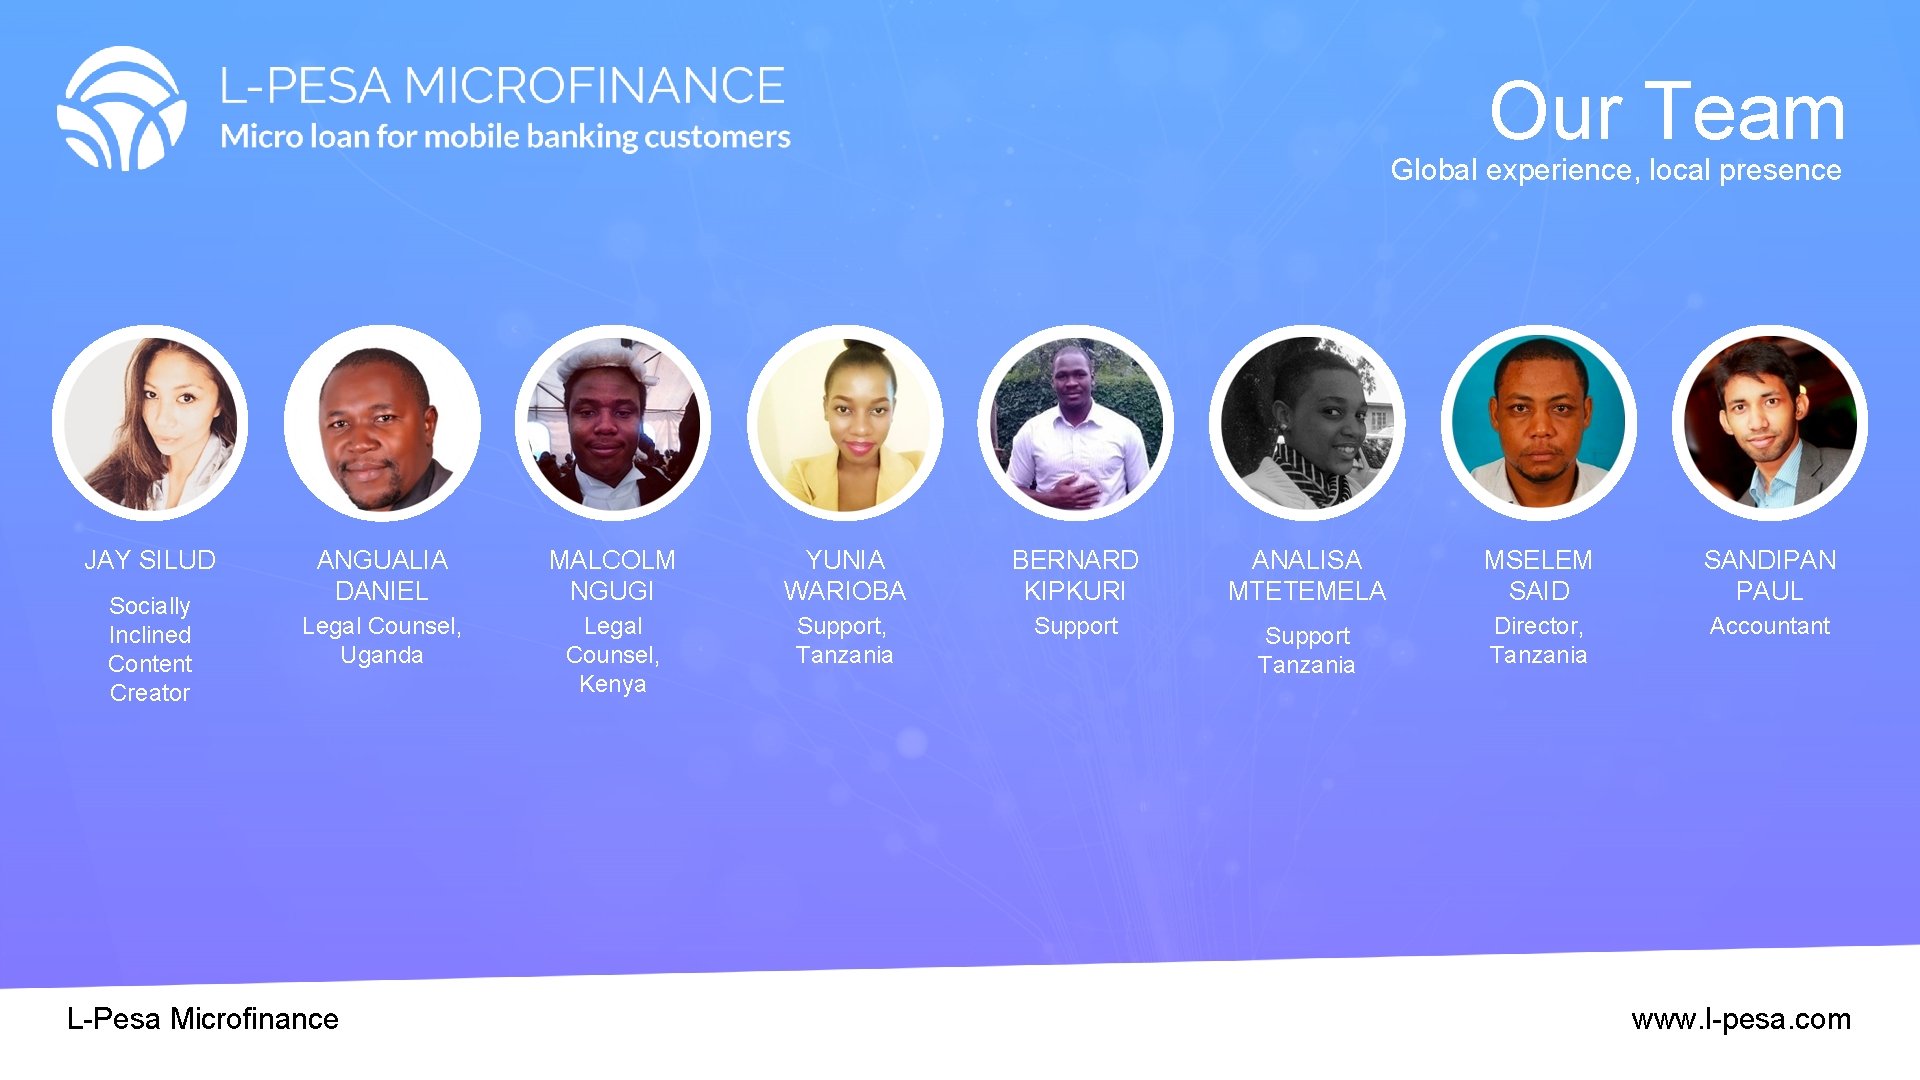
Our Team Global experience, local presence JAY SILUD Socially Inclined Content Creator ANGUALIA DANIEL MALCOLM NGUGI YUNIA WARIOBA BERNARD KIPKURI ANALISA MTETEMELA MSELEM SAID SANDIPAN PAUL Legal Counsel, Uganda Legal Counsel, Kenya Support, Tanzania Support Tanzania Director, Tanzania Accountant L-Pesa Microfinance www. l-pesa. com
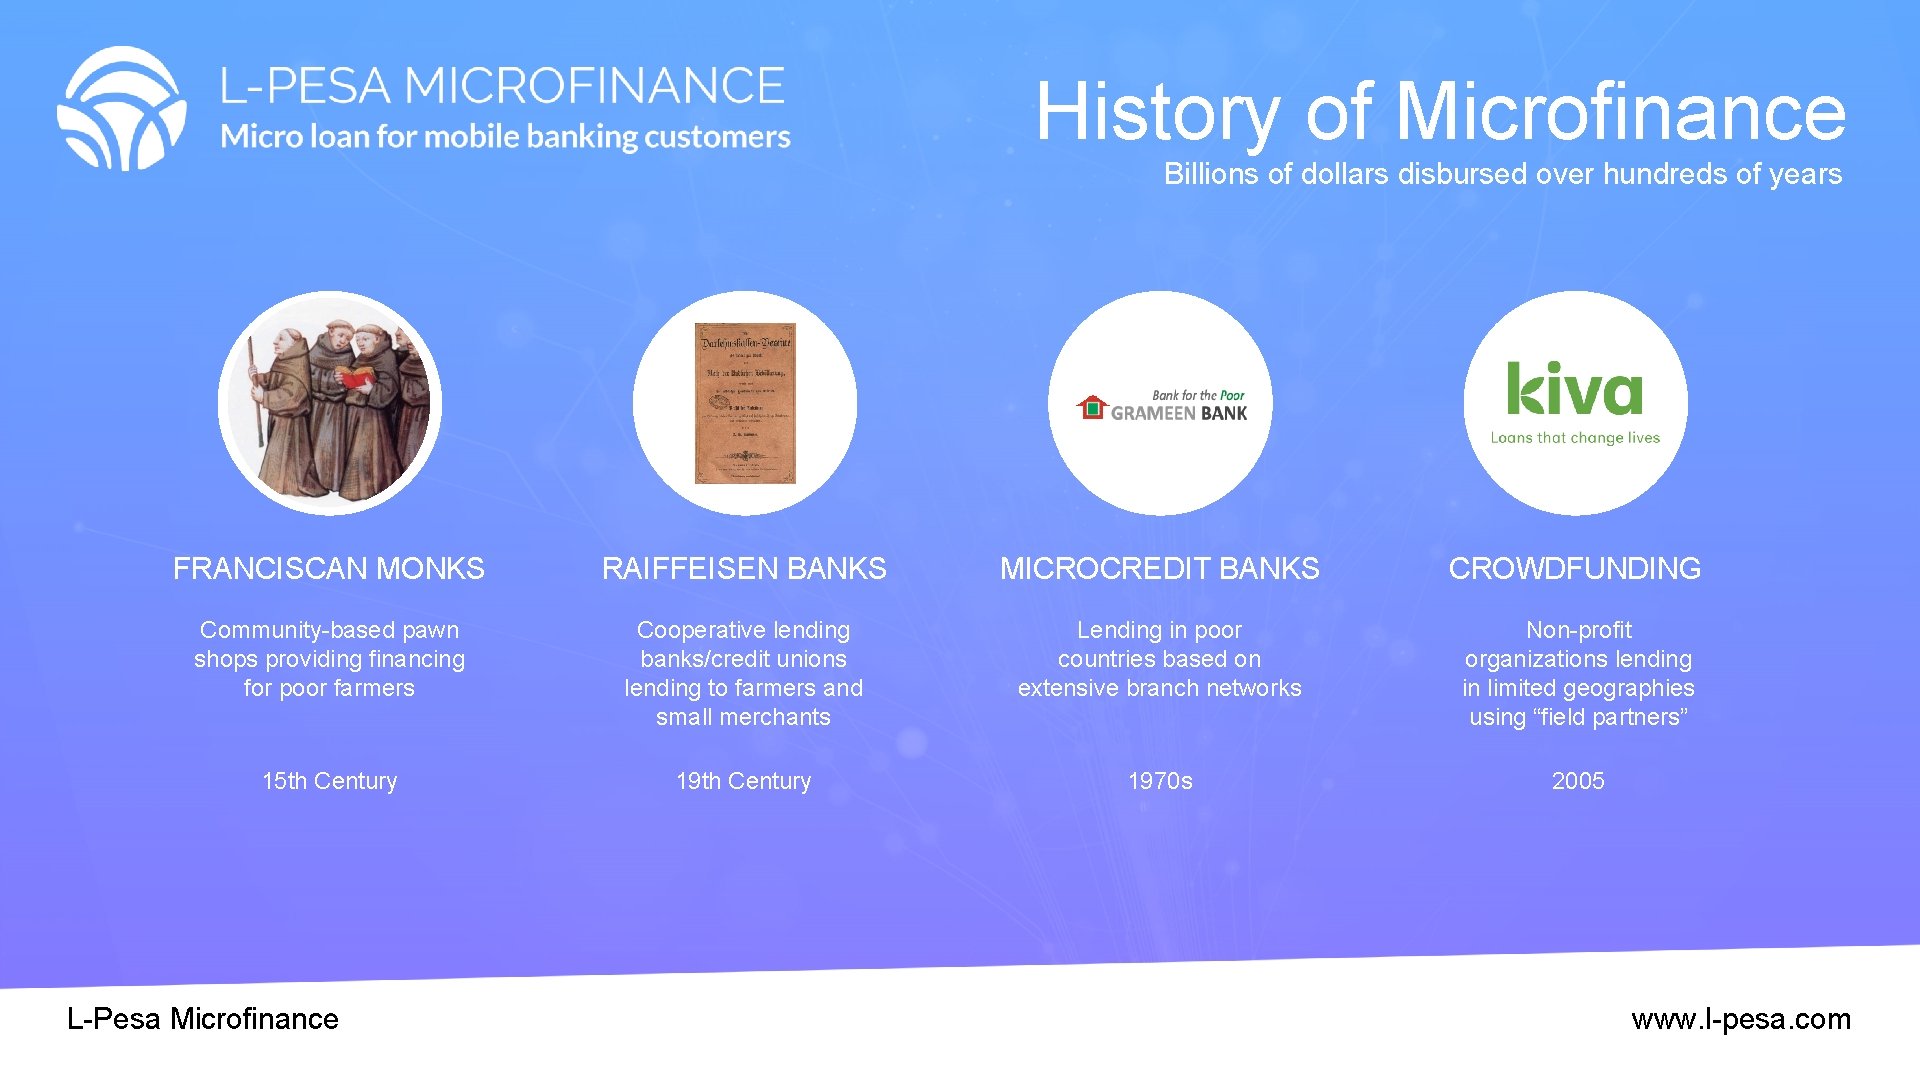
History of Microfinance Billions of dollars disbursed over hundreds of years FRANCISCAN MONKS RAIFFEISEN BANKS MICROCREDIT BANKS CROWDFUNDING Community-based pawn shops providing financing for poor farmers Cooperative lending banks/credit unions lending to farmers and small merchants Lending in poor countries based on extensive branch networks Non-profit organizations lending in limited geographies using “field partners” 15 th Century 1970 s 2005 L-Pesa Microfinance www. l-pesa. com
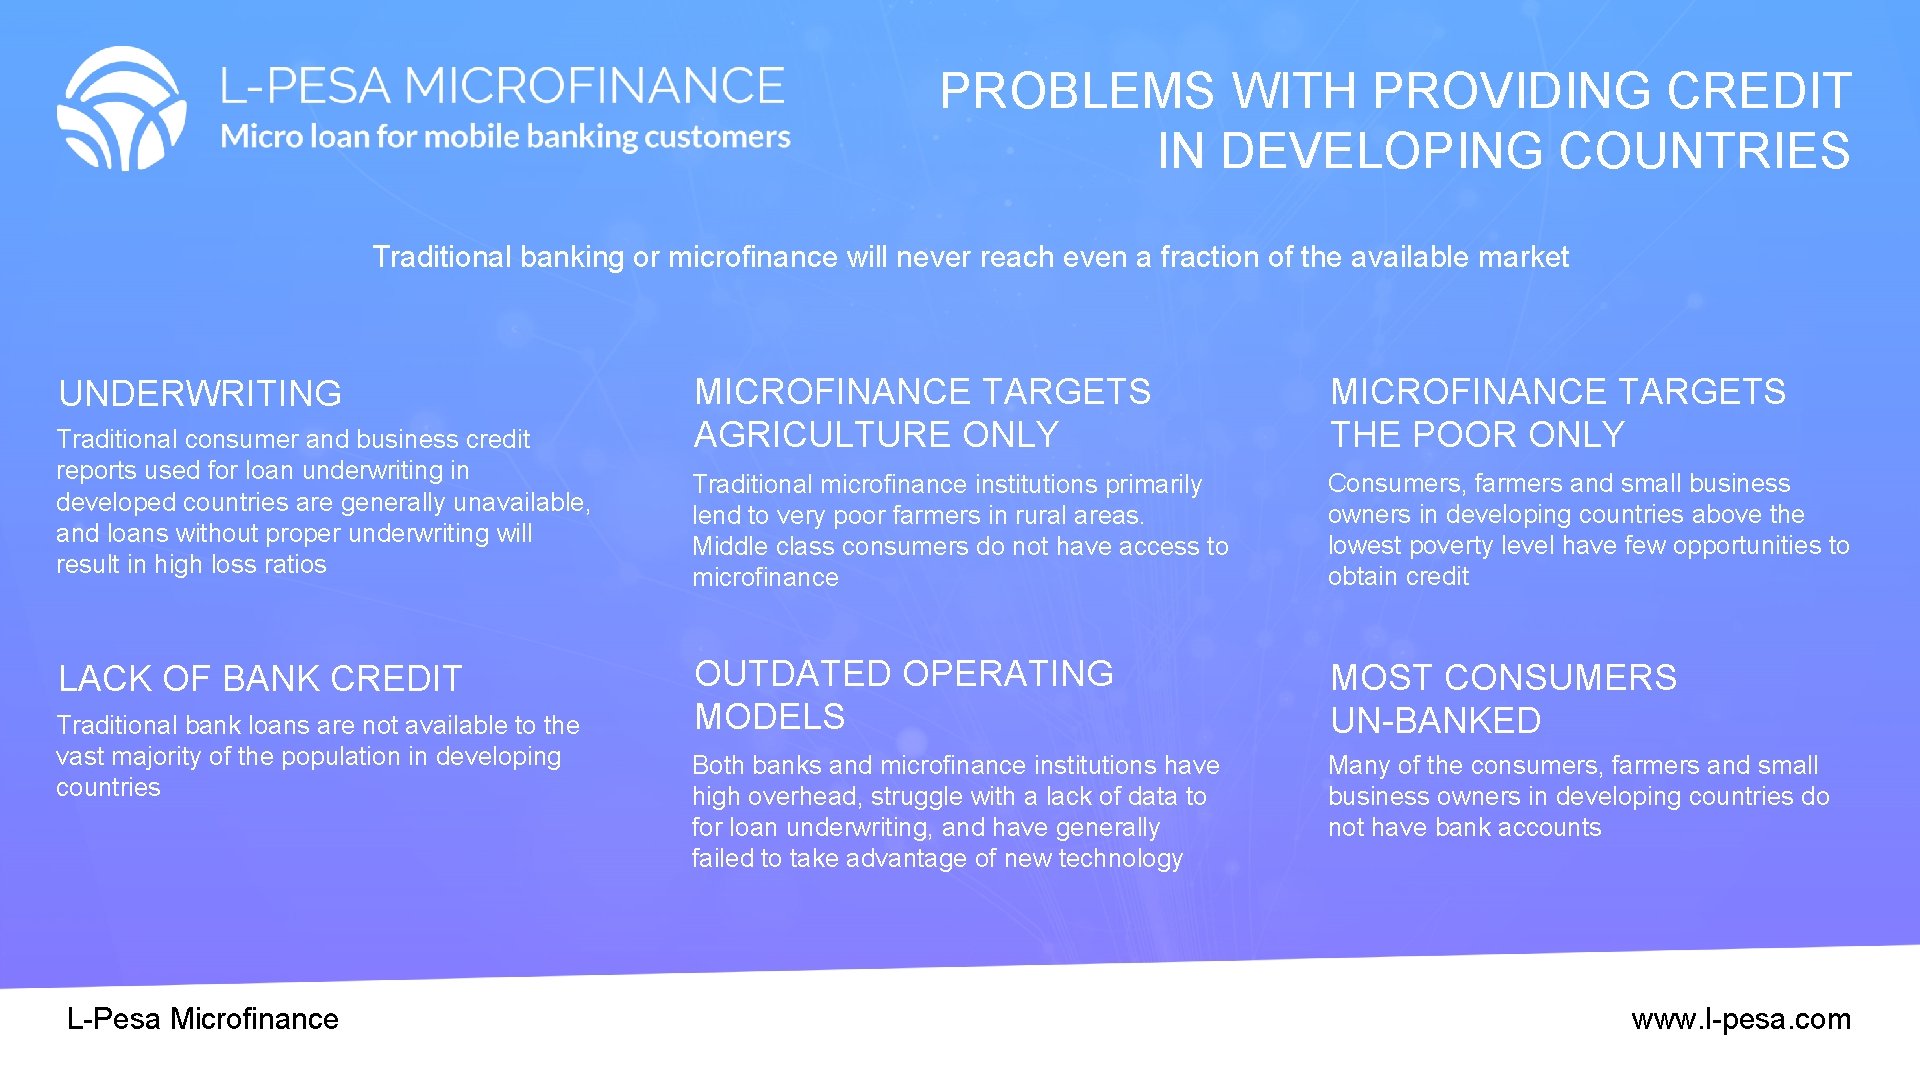
PROBLEMS WITH PROVIDING CREDIT IN DEVELOPING COUNTRIES Traditional banking or microfinance will never reach even a fraction of the available market UNDERWRITING Traditional consumer and business credit reports used for loan underwriting in developed countries are generally unavailable, and loans without proper underwriting will result in high loss ratios LACK OF BANK CREDIT Traditional bank loans are not available to the vast majority of the population in developing countries L-Pesa Microfinance MICROFINANCE TARGETS AGRICULTURE ONLY MICROFINANCE TARGETS THE POOR ONLY Traditional microfinance institutions primarily lend to very poor farmers in rural areas. Middle class consumers do not have access to microfinance Consumers, farmers and small business owners in developing countries above the lowest poverty level have few opportunities to obtain credit OUTDATED OPERATING MODELS MOST CONSUMERS UN-BANKED Both banks and microfinance institutions have high overhead, struggle with a lack of data to for loan underwriting, and have generally failed to take advantage of new technology Many of the consumers, farmers and small business owners in developing countries do not have bank accounts www. l-pesa. com
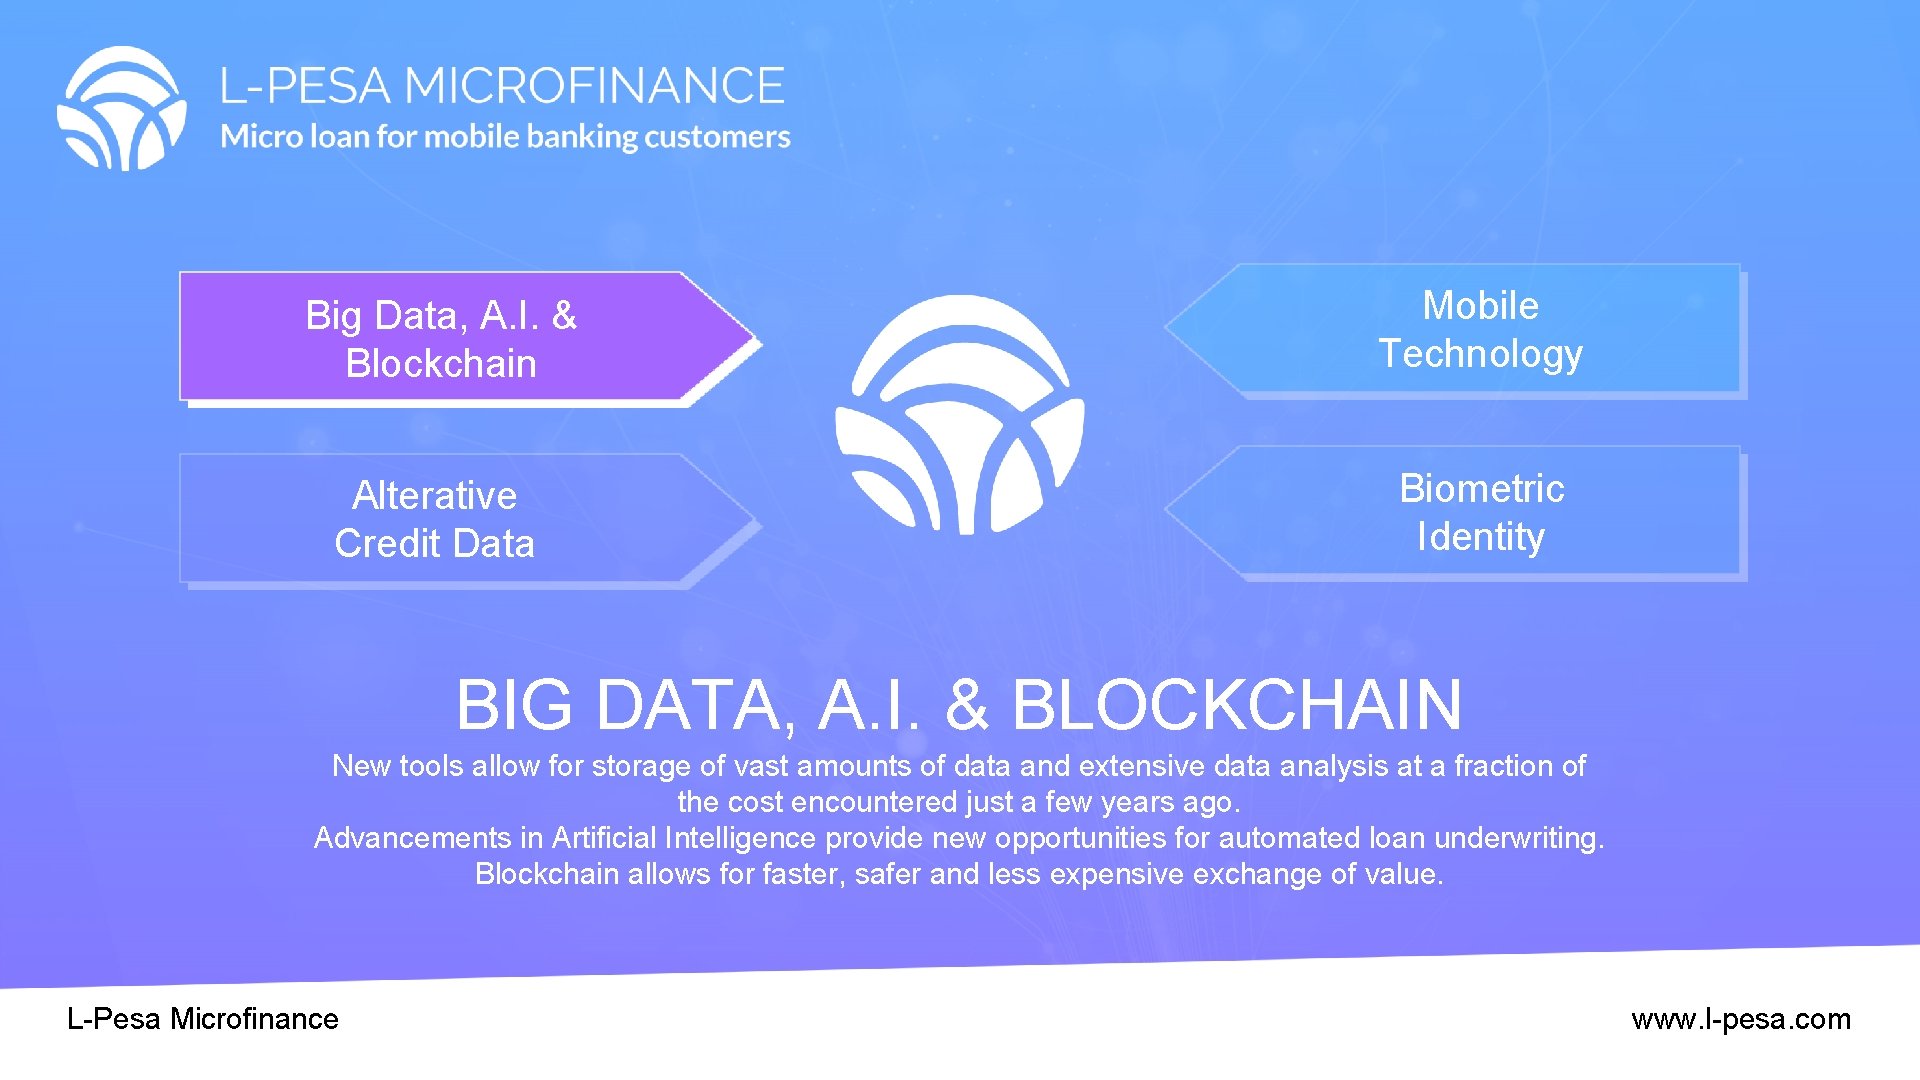
Big Data, A. I. & Blockchain Mobile Technology Alterative Credit Data Biometric Identity BIG DATA, A. I. & BLOCKCHAIN New tools allow for storage of vast amounts of data and extensive data analysis at a fraction of the cost encountered just a few years ago. Advancements in Artificial Intelligence provide new opportunities for automated loan underwriting. Blockchain allows for faster, safer and less expensive exchange of value. L-Pesa Microfinance www. l-pesa. com
Big Data, A. I. & Blockchain Mobile Technology Alterative Credit Data Biometric Identity ALTERATIVE CREDIT DATA Just a decade ago, there was very little data available on most of the people in the world. This has changed with the advent of social media and related trends. New tools have been developed to make this data useful for loan underwriting decision making. L-Pesa has developed a unique, proprietary credit scoring model based on user behavior combined with traditional and alternative credit data. L-Pesa Microfinance www. l-pesa. com
Big Data, A. I. & Blockchain Mobile Technology Alterative Credit Data Biometric Identity MOBILE TECHNOLOGY The rise of the mobile phone over the past two decades has been one of the most profound technological and market shifts in human history. A large majority of humankind now owns a mobile phone, and many own smartphones. Mobile financial services such as M-Pesa have become available in many countries and support both the banked as well as the unbanked population. L-Pesa Microfinance www. l-pesa. com
Big Data, A. I. & Blockchain Mobile Technology Alterative Credit Data Biometric Identity BIOMETRIC IDENTITY Traditional microfinance has relied on a large network of branches since identity verification has been impossible online and difficult in person. India’s Aadhaar biometric ID system is leading the world and has enrolled >99% of India’s 1. 2 billion citizens. Other countries are expected to follow India’s successful implementation. L-Pesa Microfinance www. l-pesa. com
Big Data, A. I. & Blockchain Mobile Technology Alterative Credit Data Biometric Identity L-PESA SOLUTION Broadly available, targeting middle class and small business Overhead is extremely low; operations are largely automated Taking advantage of latest technology Loss ratio well below 10% due to sophisticated underwriting Using mobile money transfer services like M-Pesa Integration with biometric ID systems L-Pesa Microfinance www. l-pesa. com
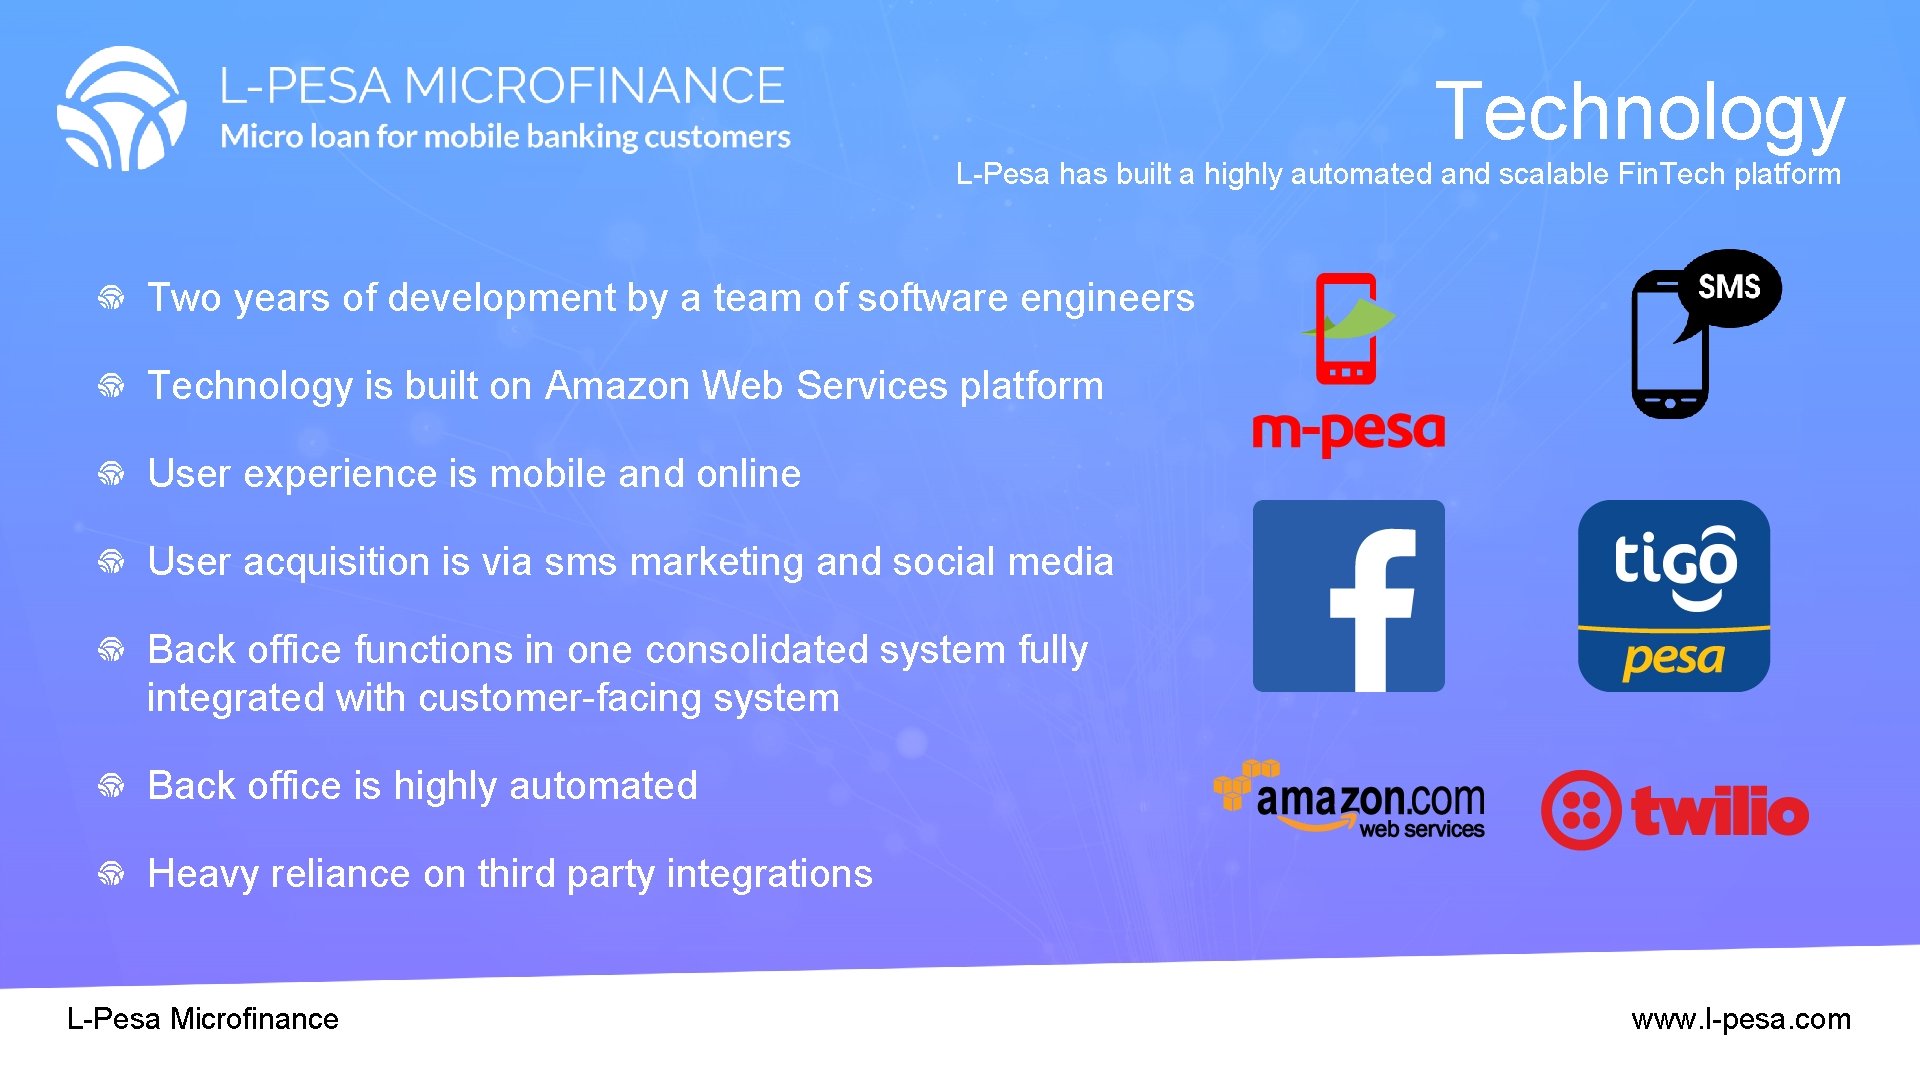
Technology L-Pesa has built a highly automated and scalable Fin. Tech platform Two years of development by a team of software engineers Technology is built on Amazon Web Services platform User experience is mobile and online User acquisition is via sms marketing and social media Back office functions in one consolidated system fully integrated with customer-facing system Back office is highly automated Heavy reliance on third party integrations L-Pesa Microfinance www. l-pesa. com
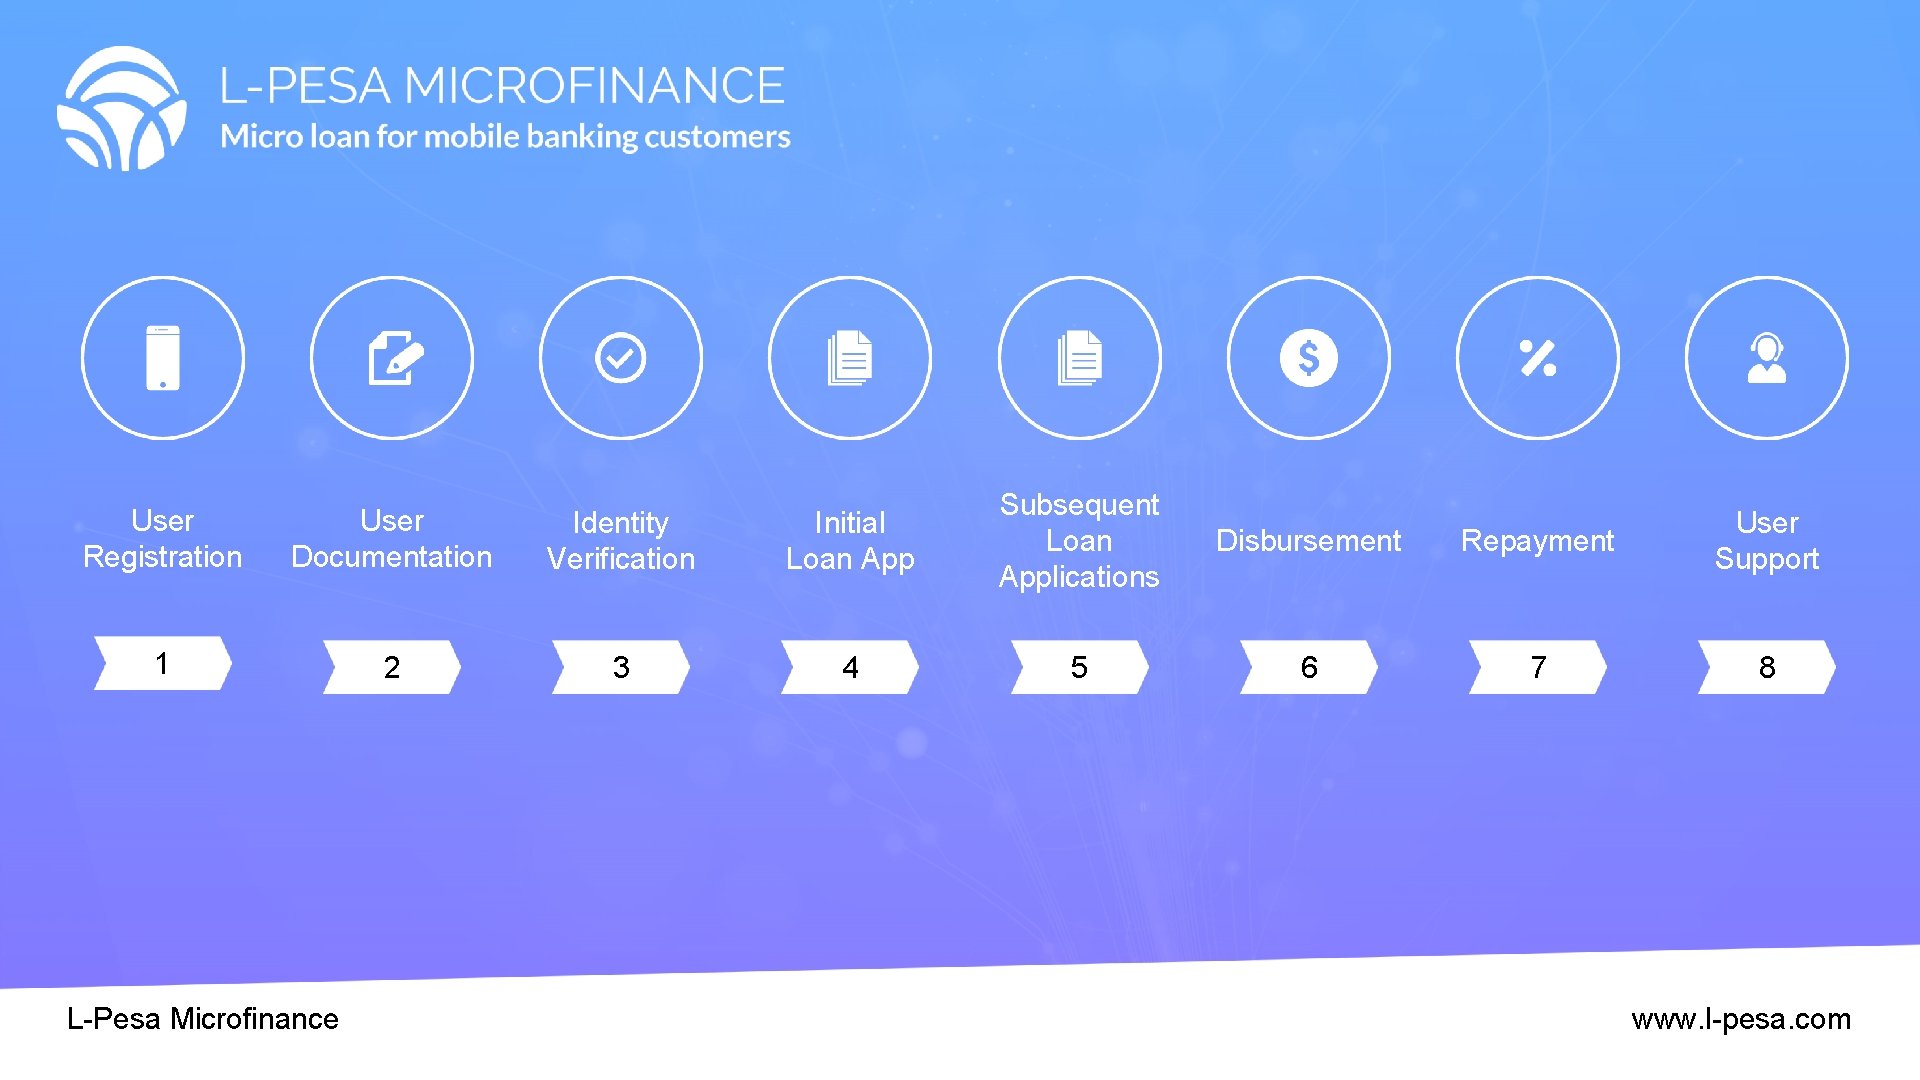
User Registration User Documentation Identity Verification Initial Loan App Subsequent Loan Applications 1 2 3 4 5 L-Pesa Microfinance Disbursement Repayment User Support 6 7 8 www. l-pesa. com
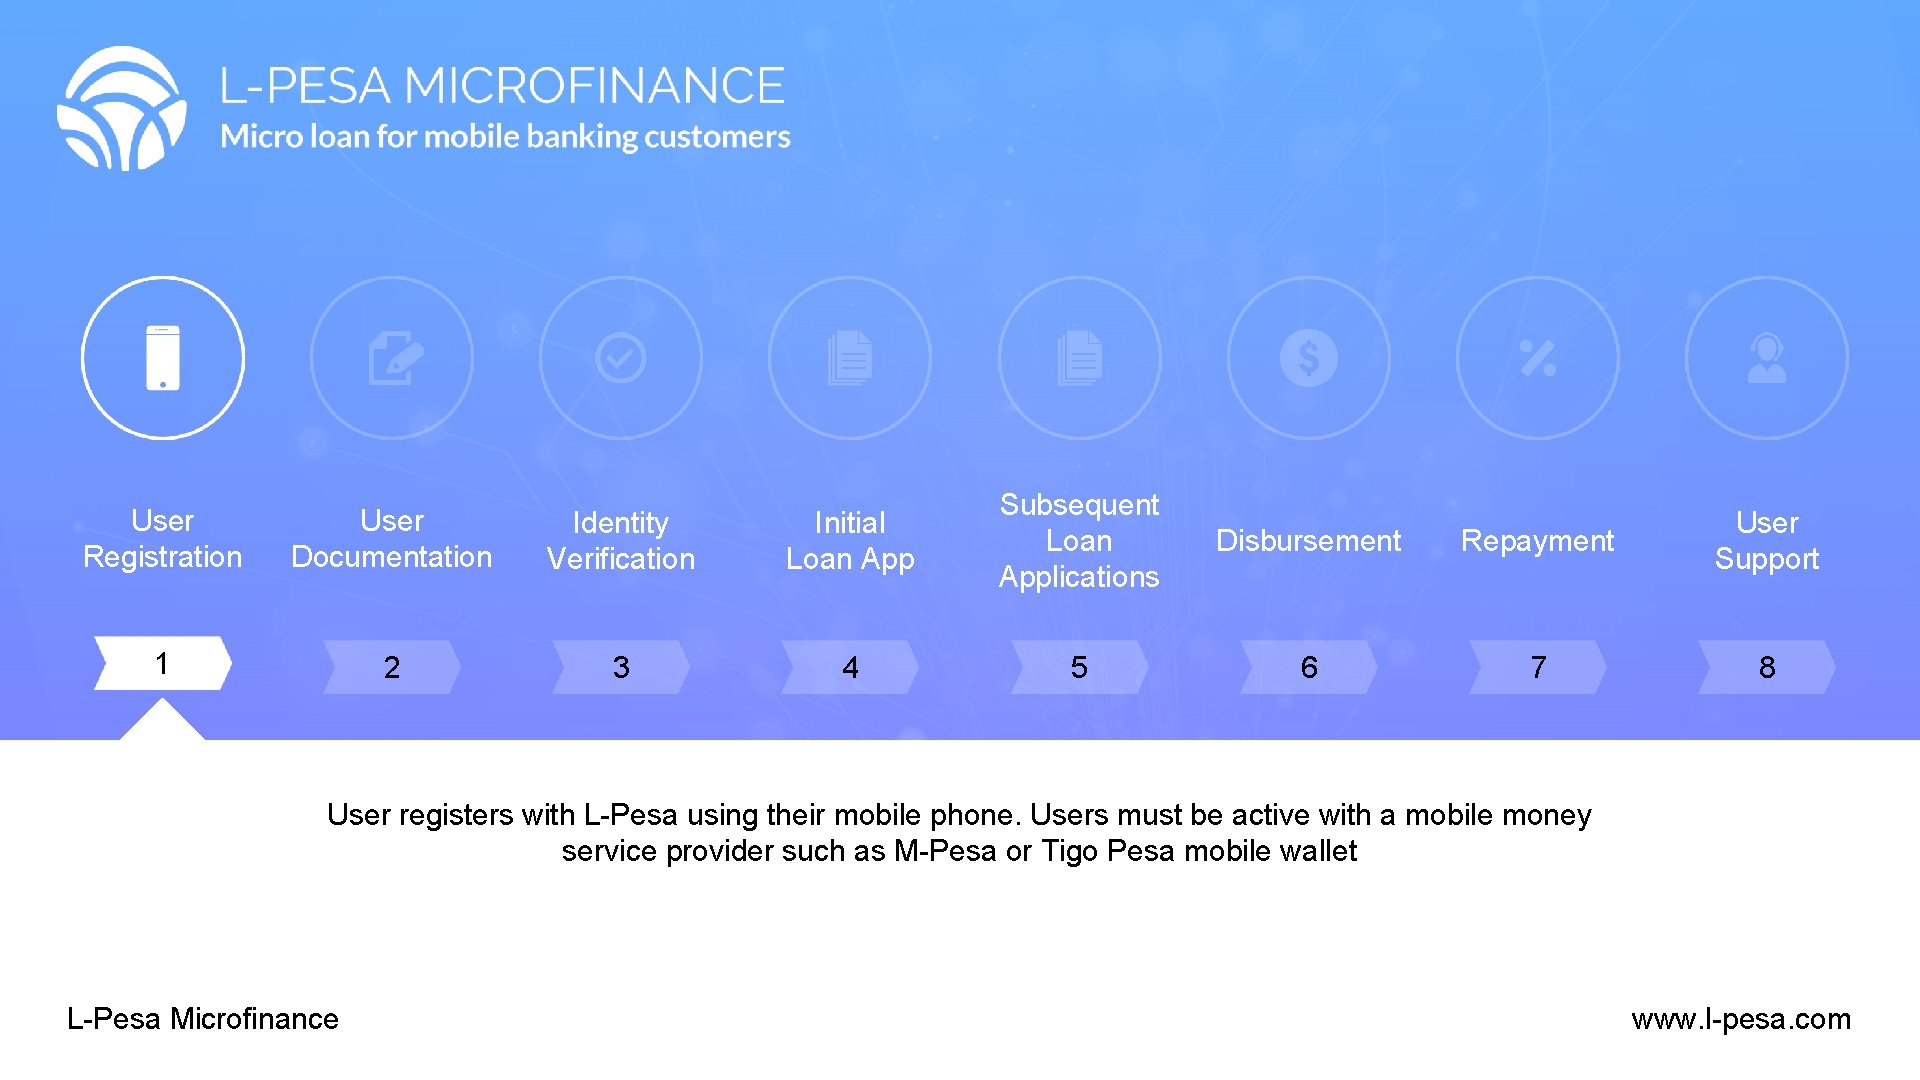
User Registration User Documentation Identity Verification Initial Loan App Subsequent Loan Applications 1 2 3 4 5 Disbursement Repayment User Support 6 7 8 User registers with L-Pesa using their mobile phone. Users must be active with a mobile money service provider such as M-Pesa or Tigo Pesa mobile wallet L-Pesa Microfinance www. l-pesa. com
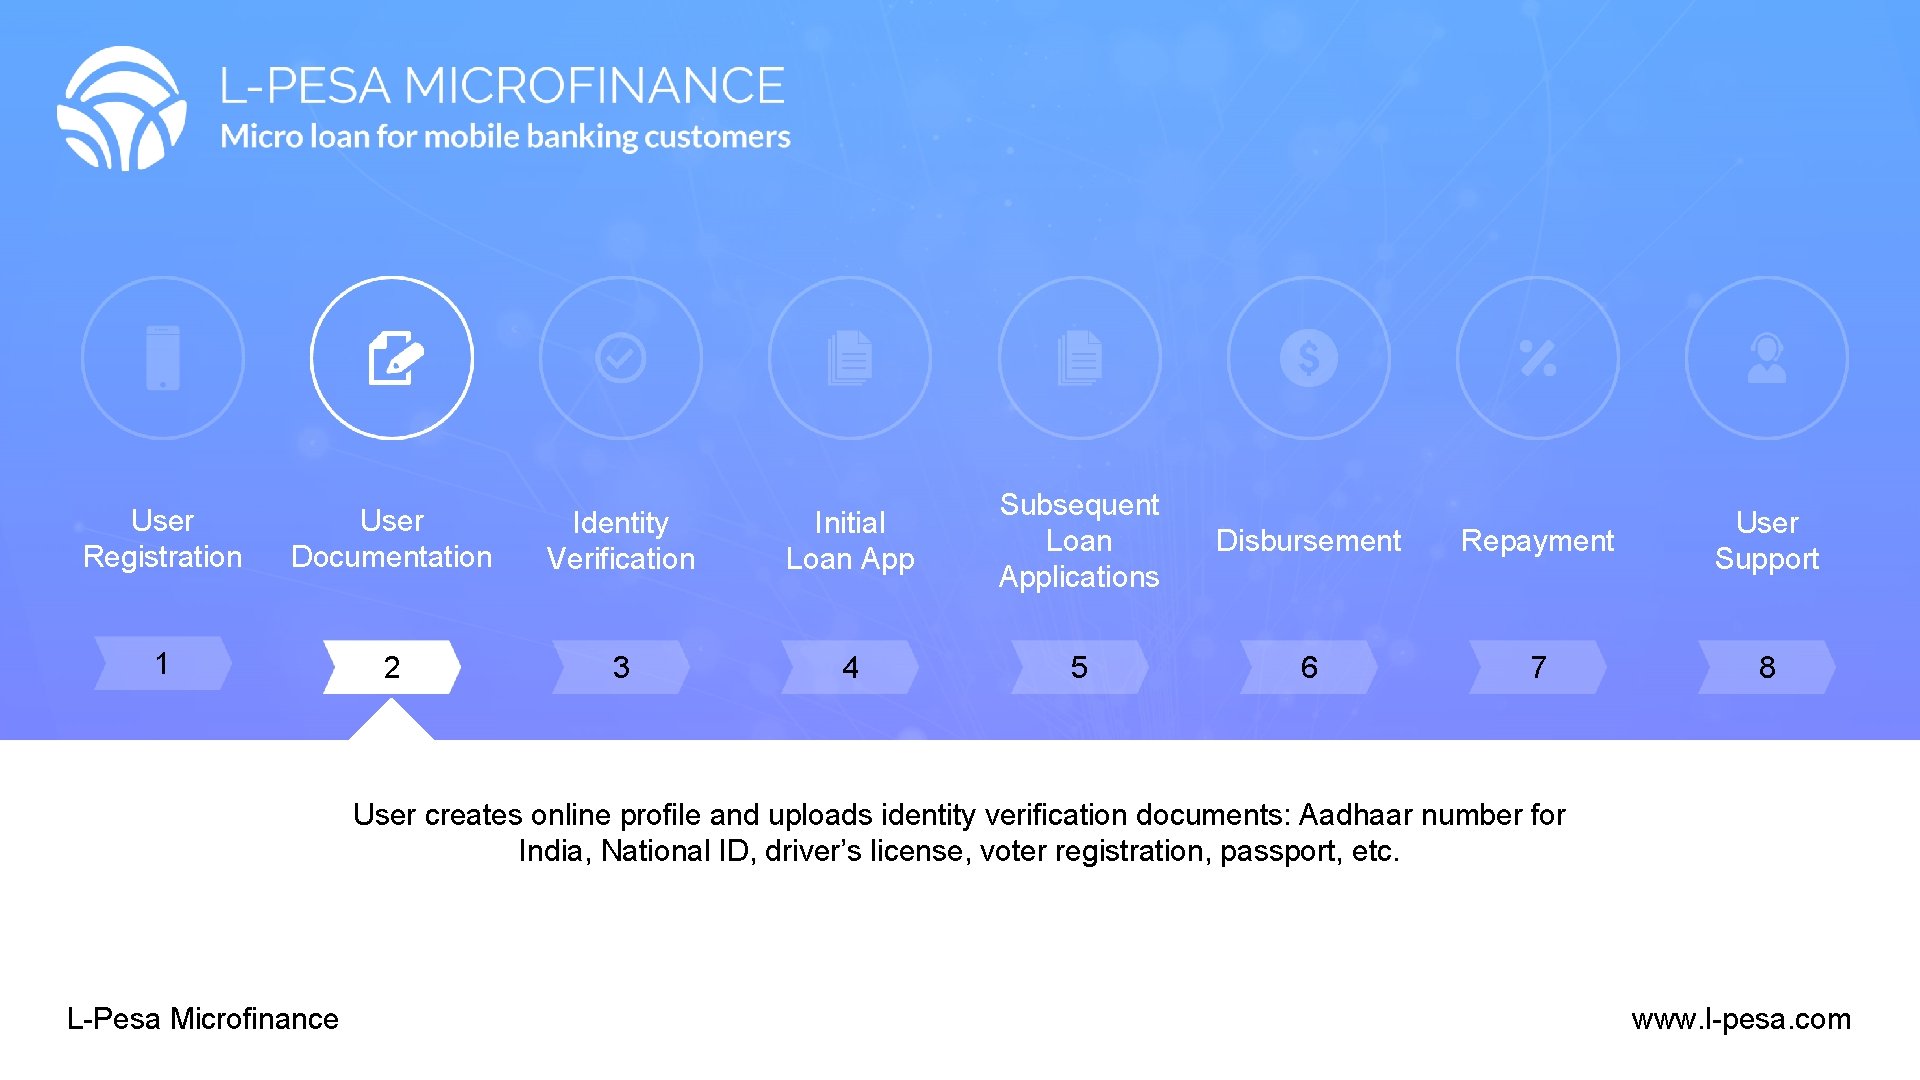
User Registration User Documentation Identity Verification Initial Loan App Subsequent Loan Applications 1 2 3 4 5 Disbursement Repayment User Support 6 7 8 User creates online profile and uploads identity verification documents: Aadhaar number for India, National ID, driver’s license, voter registration, passport, etc. L-Pesa Microfinance www. l-pesa. com
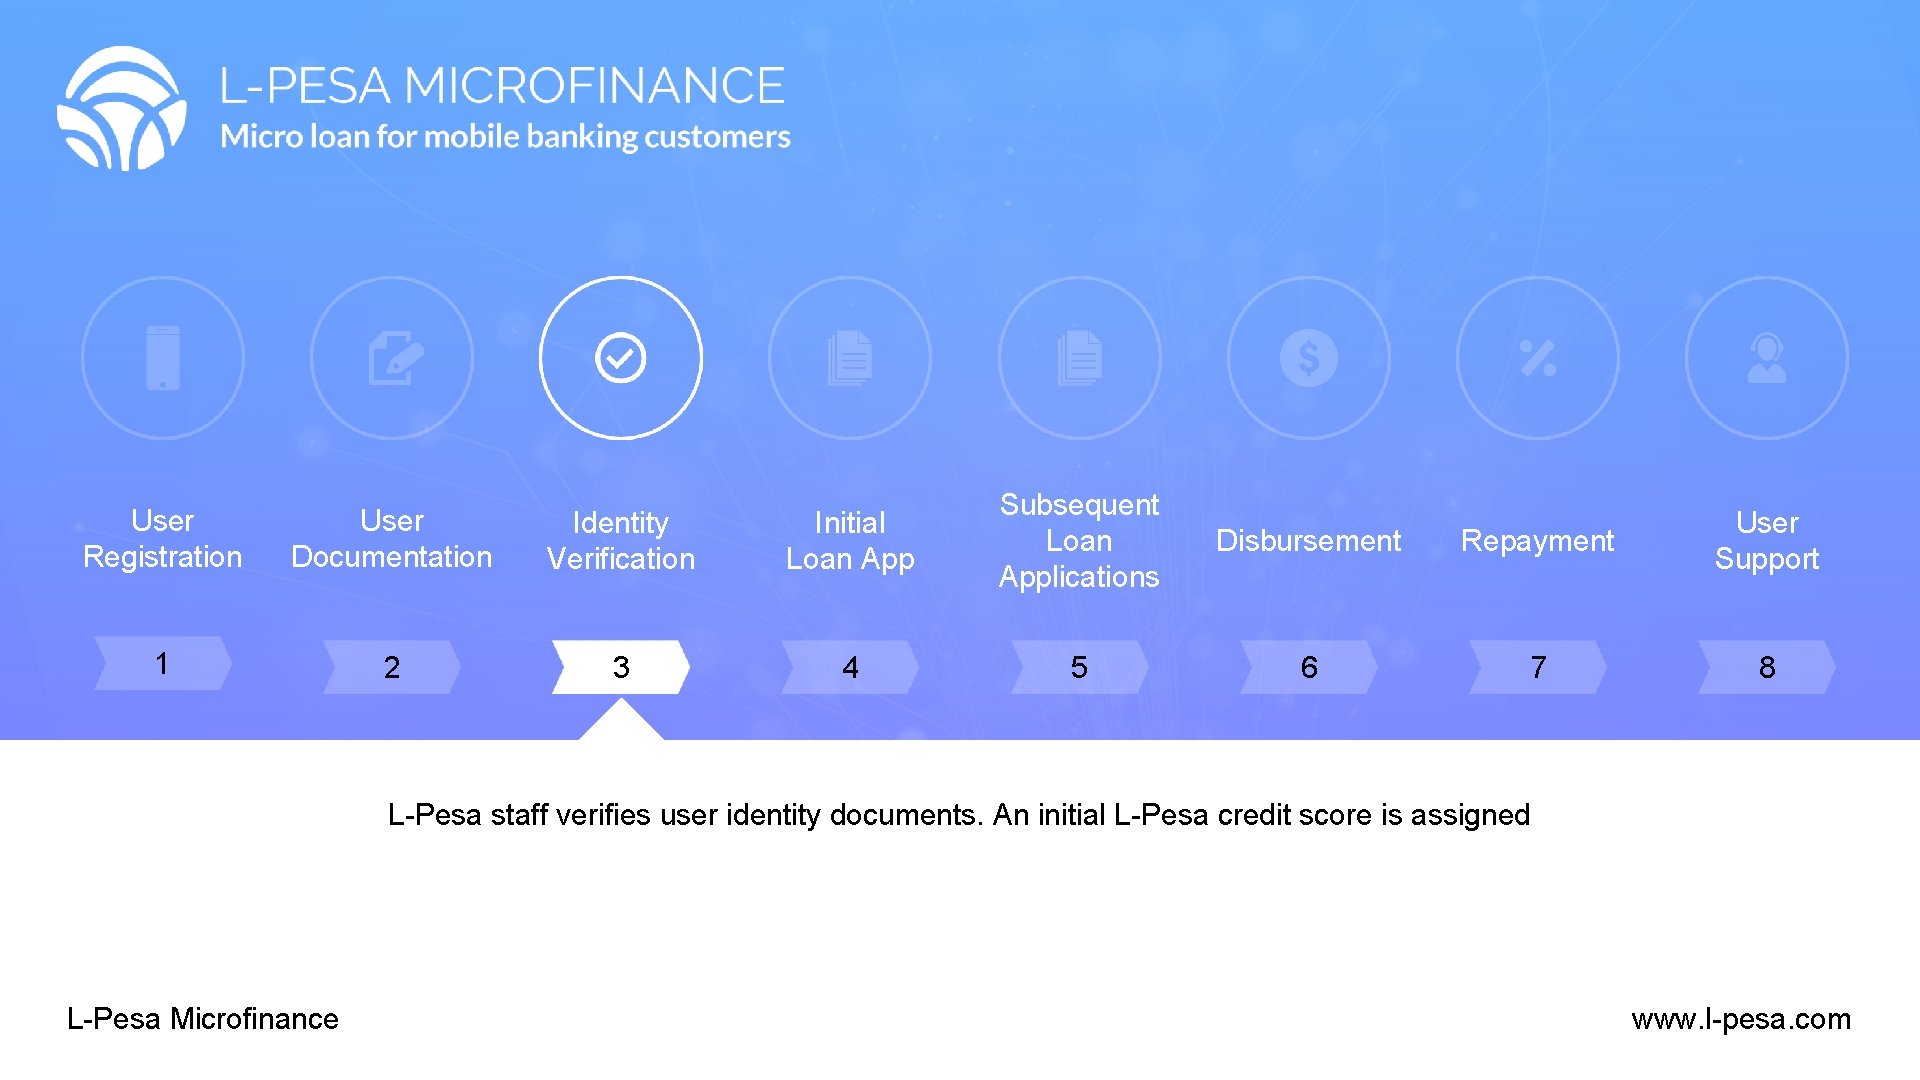
User Registration User Documentation Identity Verification Initial Loan App Subsequent Loan Applications 1 2 3 4 5 Disbursement Repayment User Support 6 7 8 L-Pesa staff verifies user identity documents. An initial L-Pesa credit score is assigned L-Pesa Microfinance www. l-pesa. com
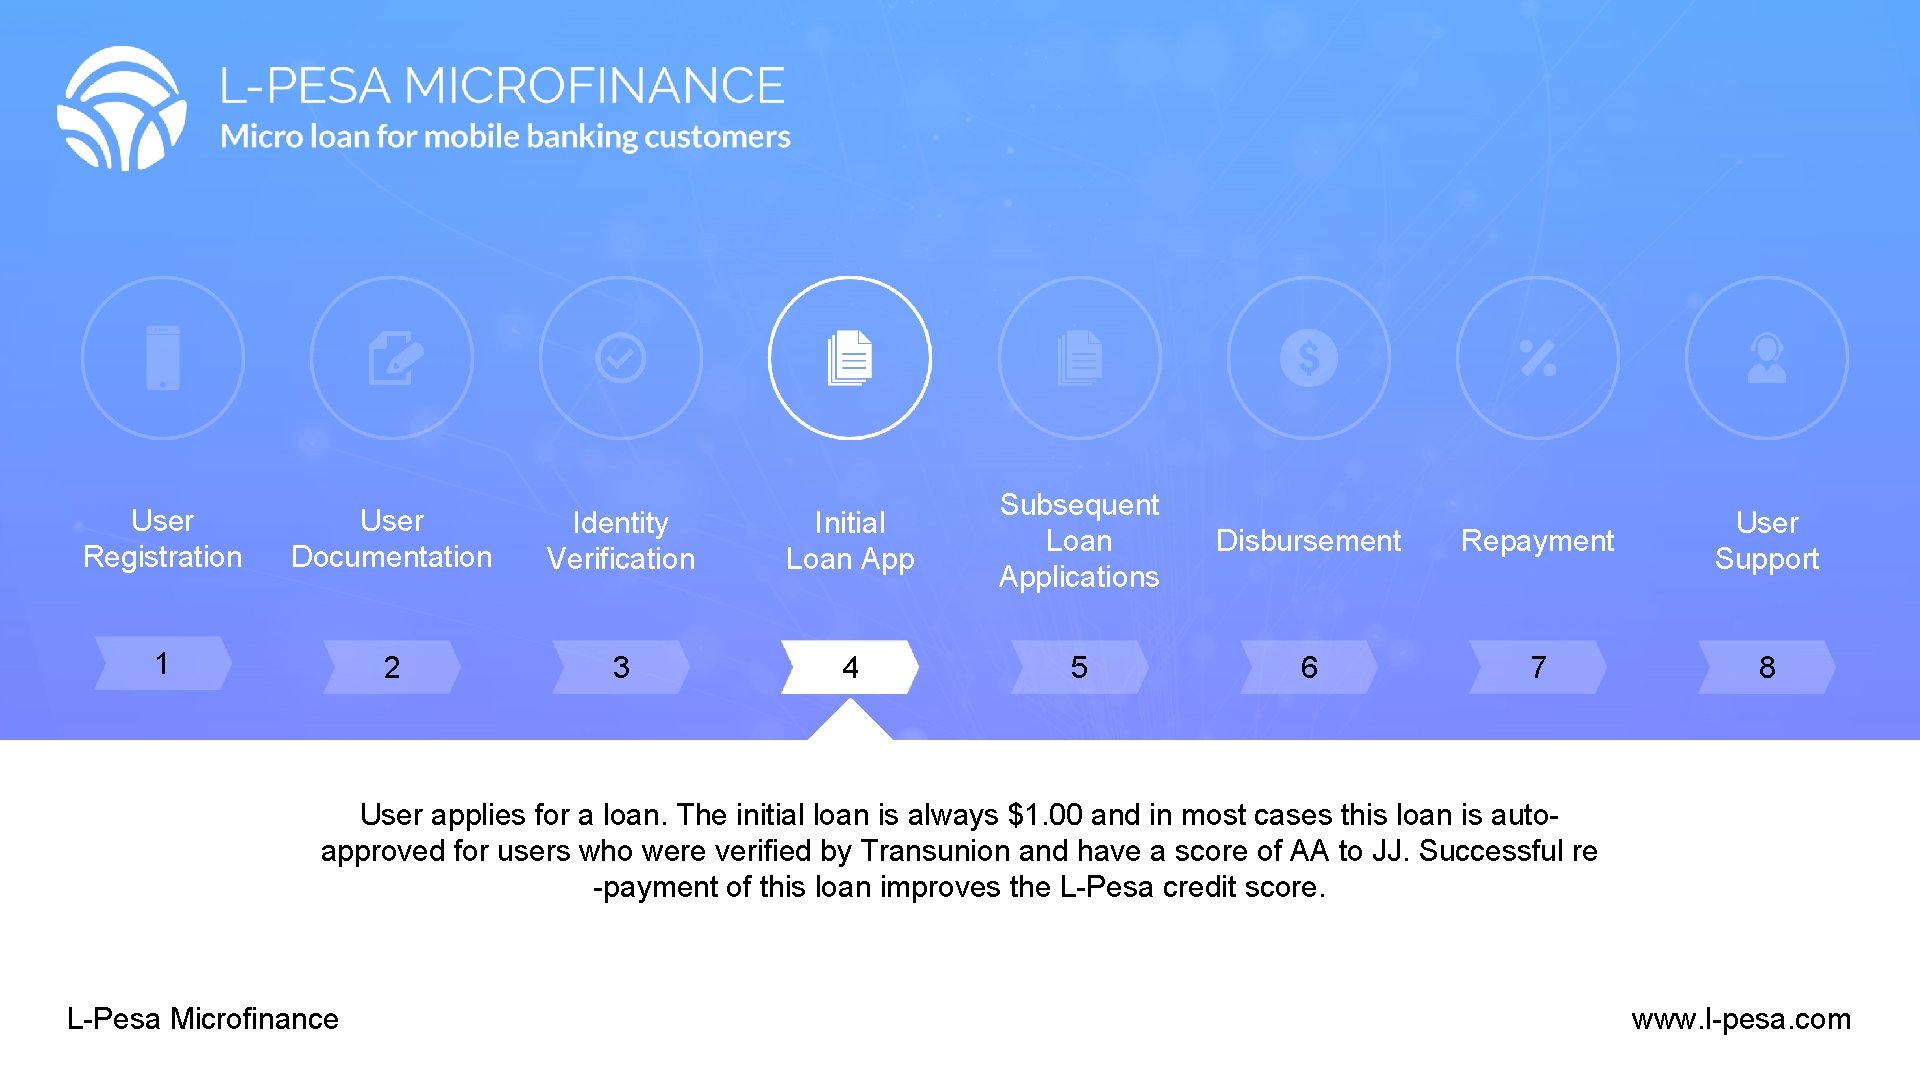
User Registration User Documentation Identity Verification Initial Loan App Subsequent Loan Applications 1 2 3 4 5 Disbursement Repayment User Support 6 7 8 User applies for a loan. The initial loan is always $1. 00 and in most cases this loan is autoapproved for users who were verified by Transunion and have a score of AA to JJ. Successful re -payment of this loan improves the L-Pesa credit score. L-Pesa Microfinance www. l-pesa. com
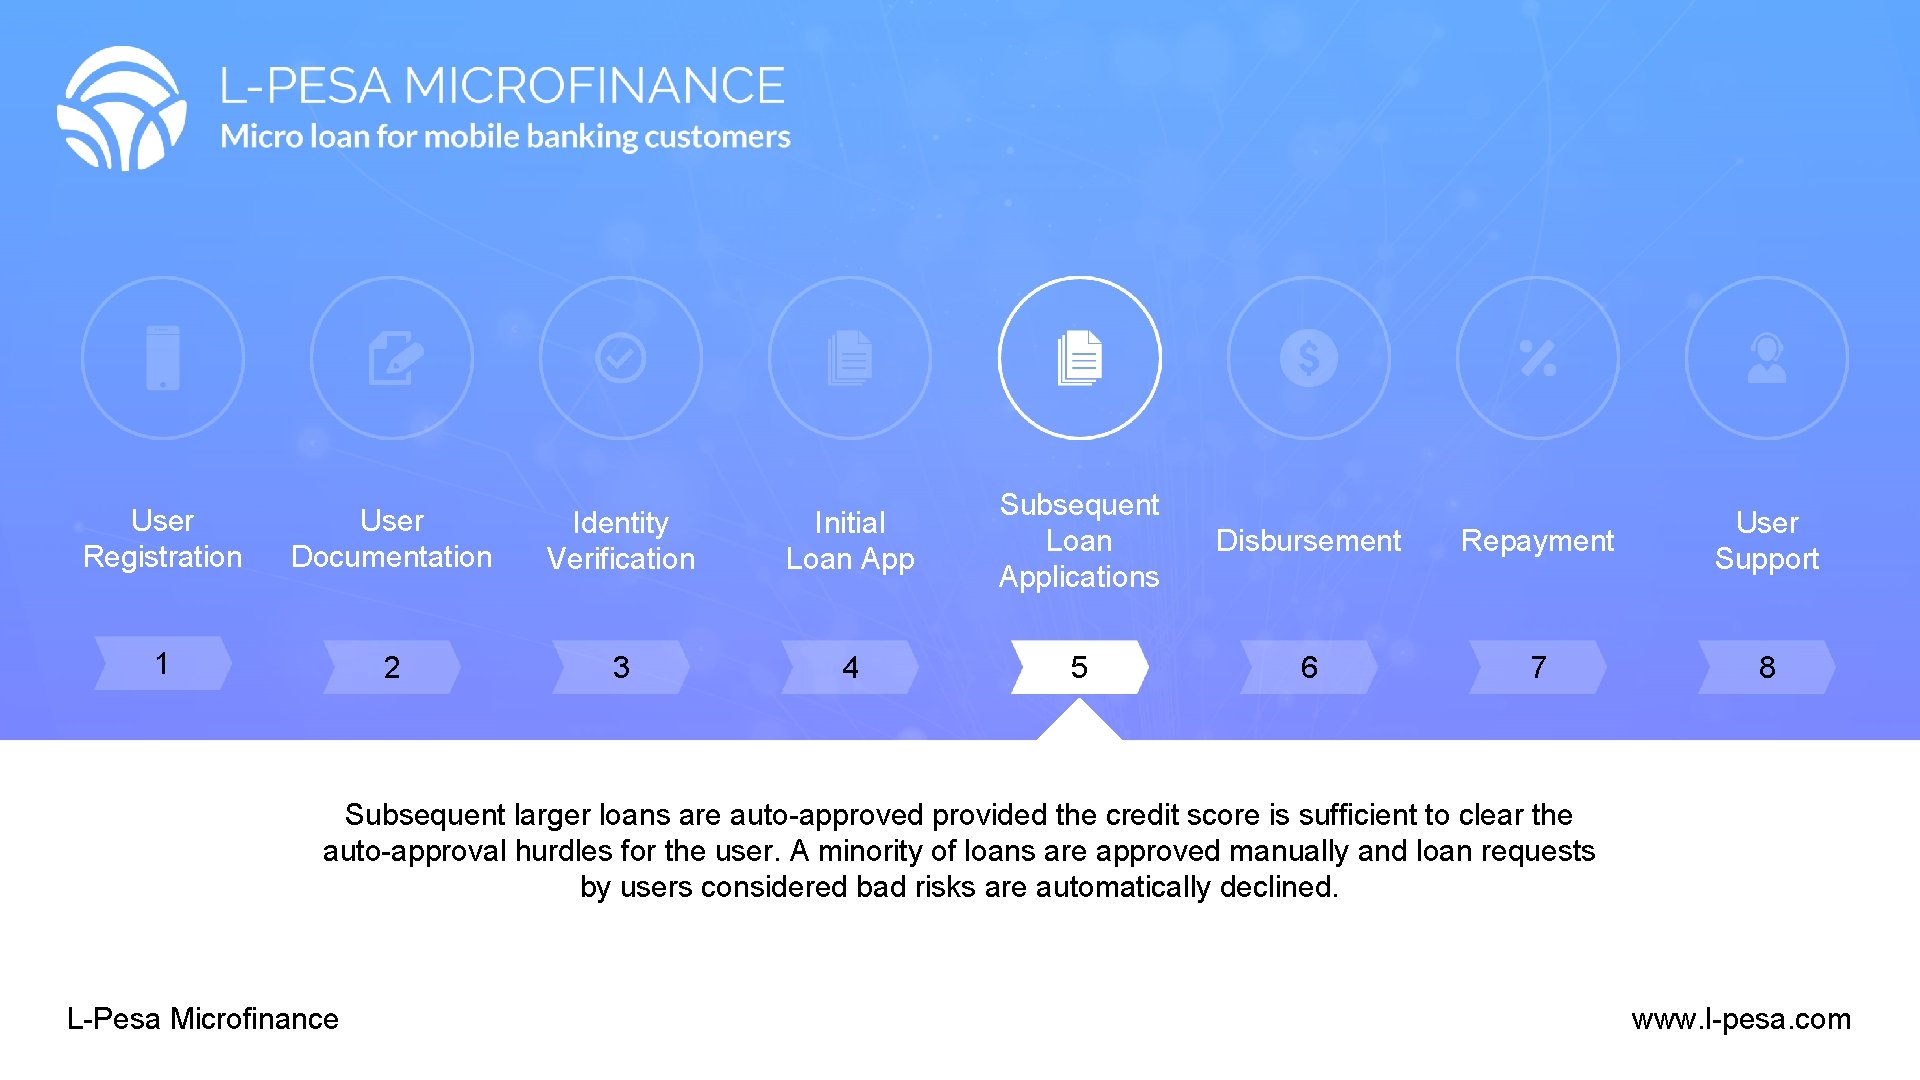
User Registration User Documentation Identity Verification Initial Loan App Subsequent Loan Applications 1 2 3 4 5 Disbursement Repayment User Support 6 7 8 Subsequent larger loans are auto-approved provided the credit score is sufficient to clear the auto-approval hurdles for the user. A minority of loans are approved manually and loan requests by users considered bad risks are automatically declined. L-Pesa Microfinance www. l-pesa. com
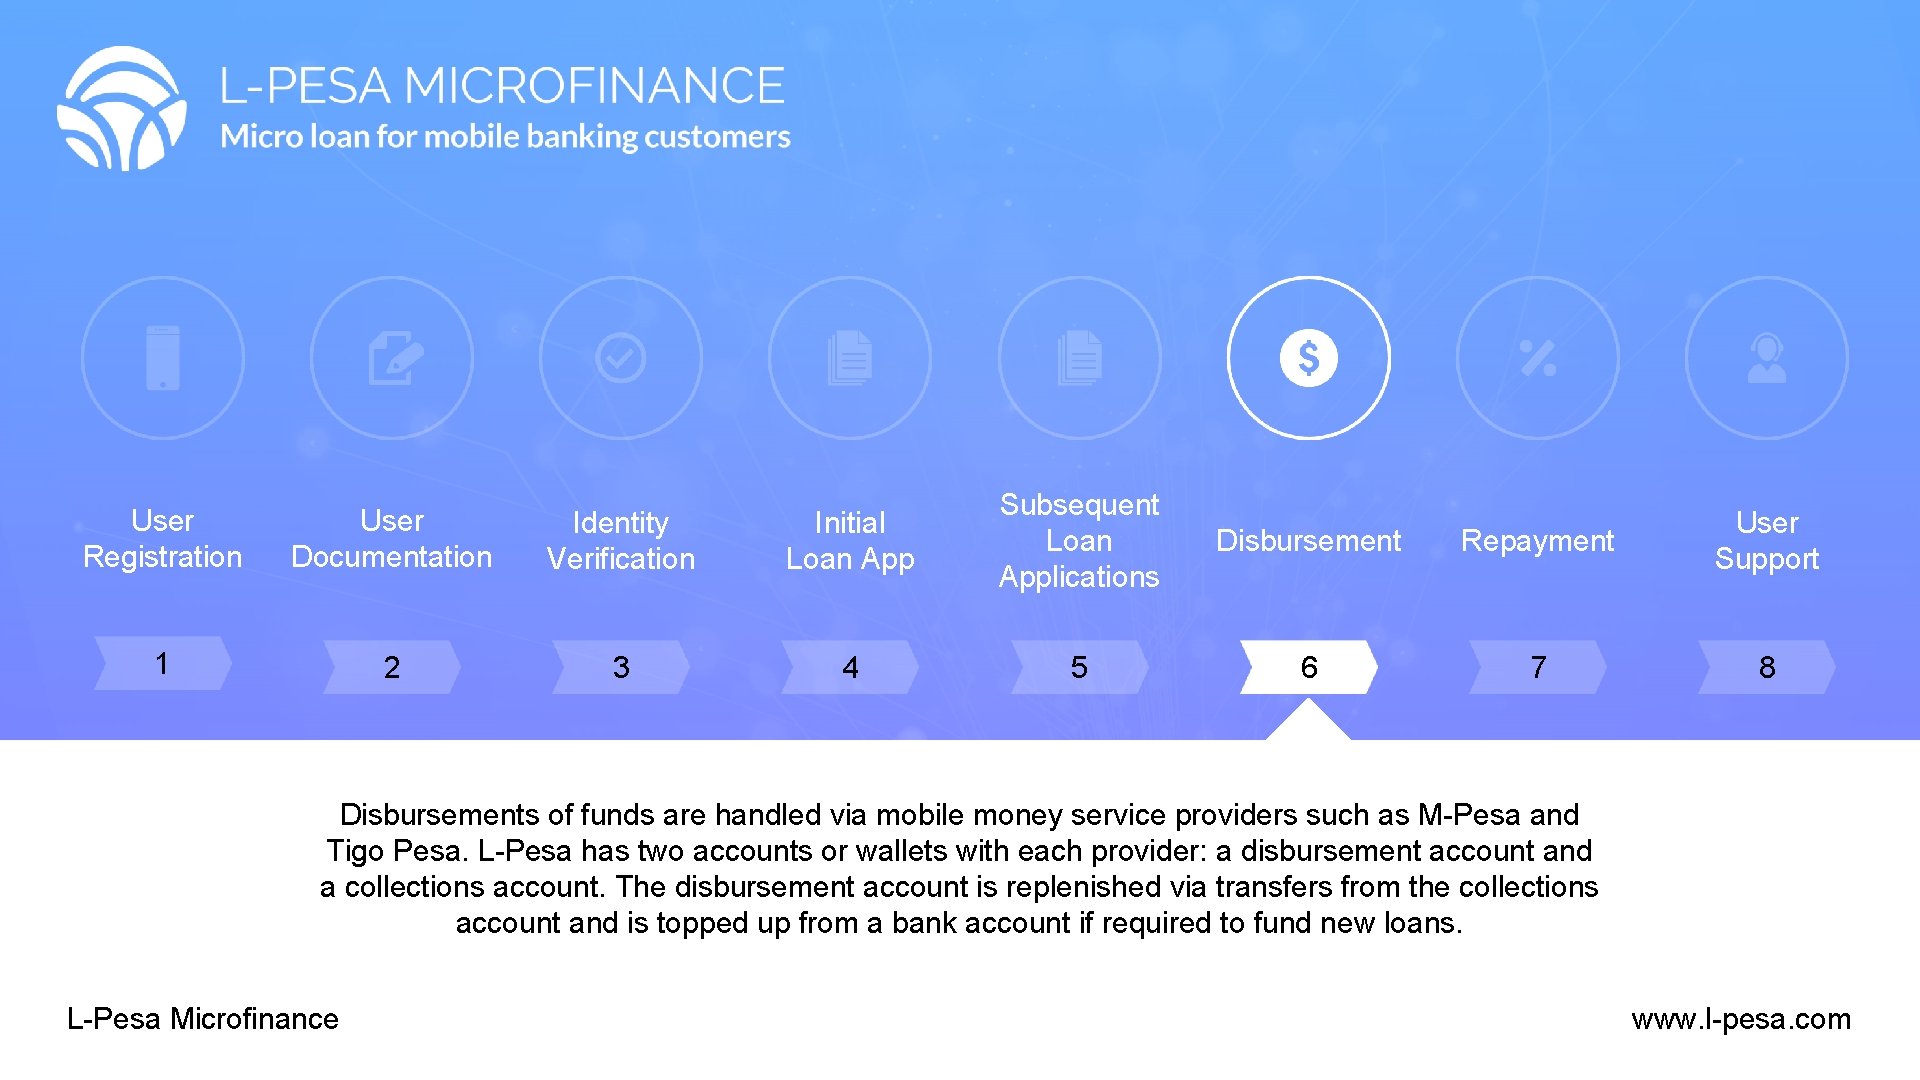
User Registration User Documentation Identity Verification Initial Loan App Subsequent Loan Applications 1 2 3 4 5 Disbursement Repayment User Support 6 7 8 Disbursements of funds are handled via mobile money service providers such as M-Pesa and Tigo Pesa. L-Pesa has two accounts or wallets with each provider: a disbursement account and a collections account. The disbursement account is replenished via transfers from the collections account and is topped up from a bank account if required to fund new loans. L-Pesa Microfinance www. l-pesa. com
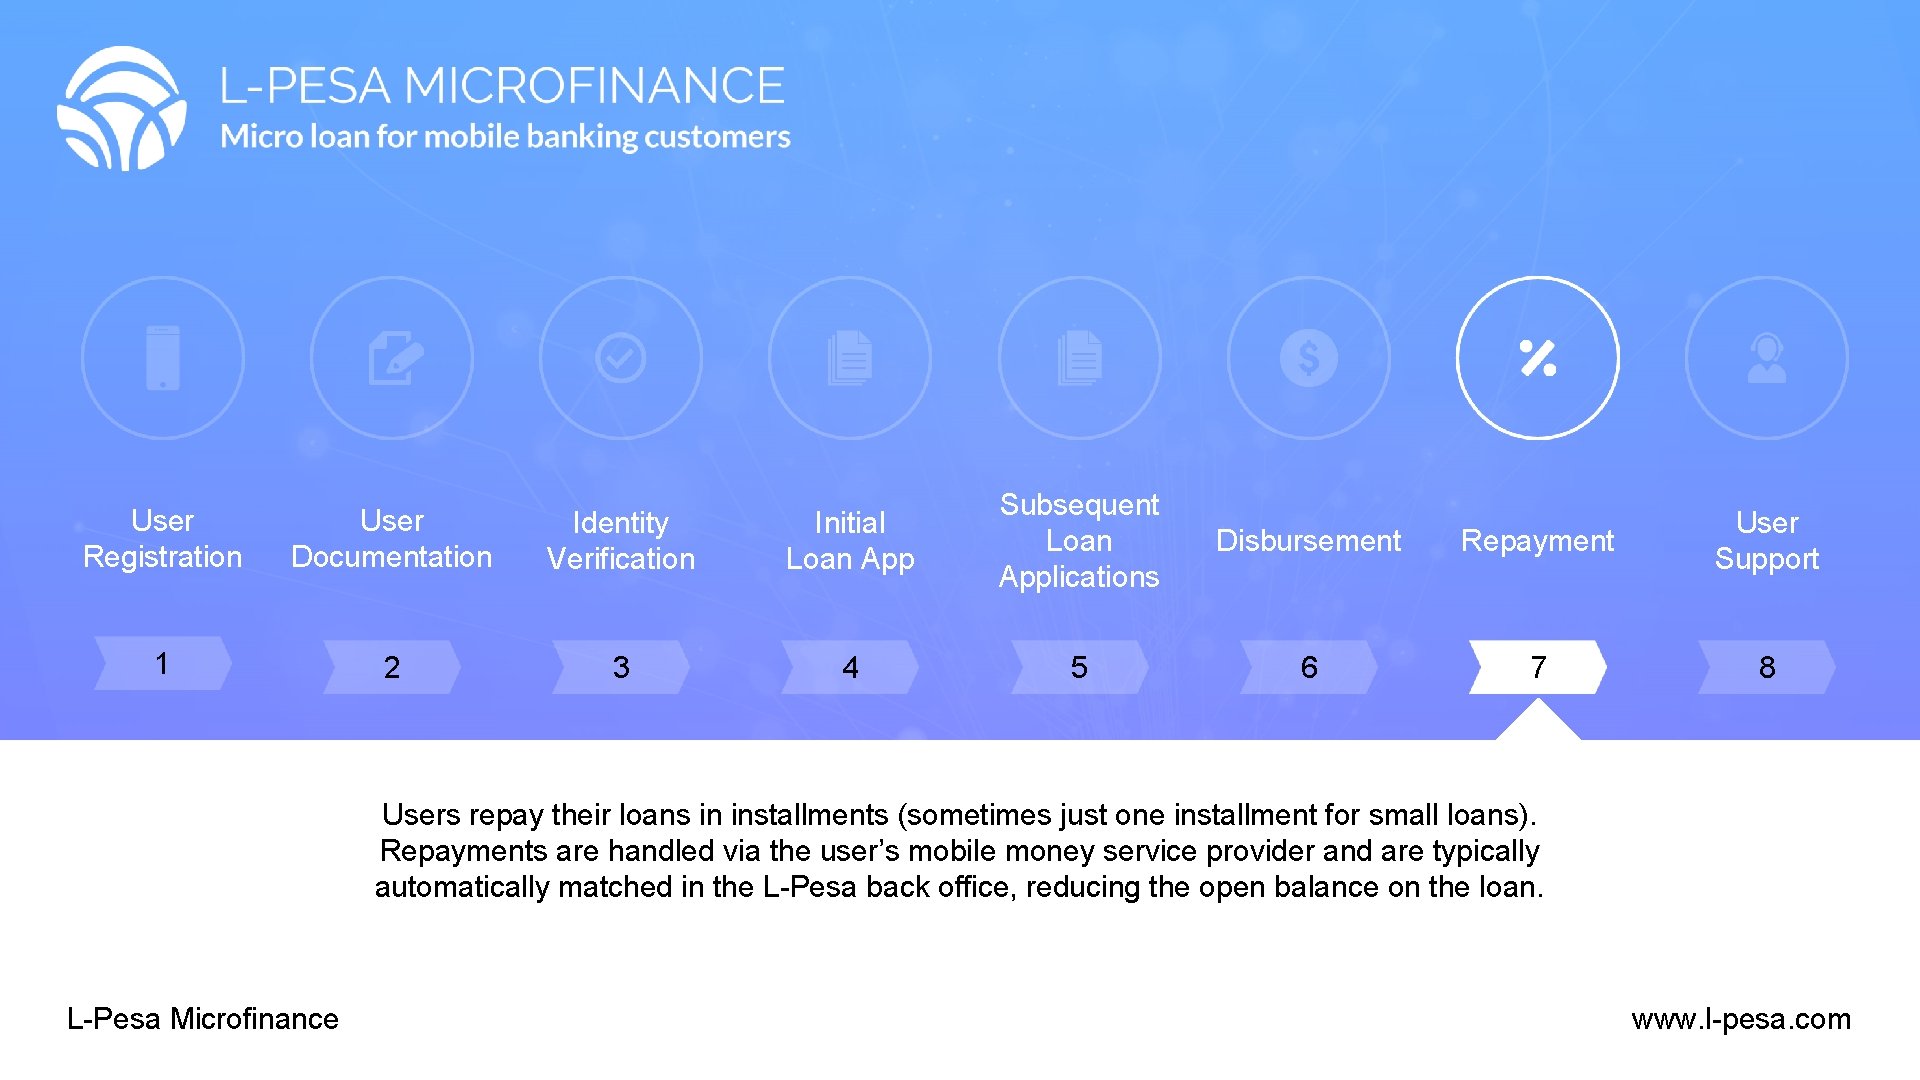
User Registration User Documentation Identity Verification Initial Loan App Subsequent Loan Applications 1 2 3 4 5 Disbursement Repayment User Support 6 7 8 Users repay their loans in installments (sometimes just one installment for small loans). Repayments are handled via the user’s mobile money service provider and are typically automatically matched in the L-Pesa back office, reducing the open balance on the loan. L-Pesa Microfinance www. l-pesa. com
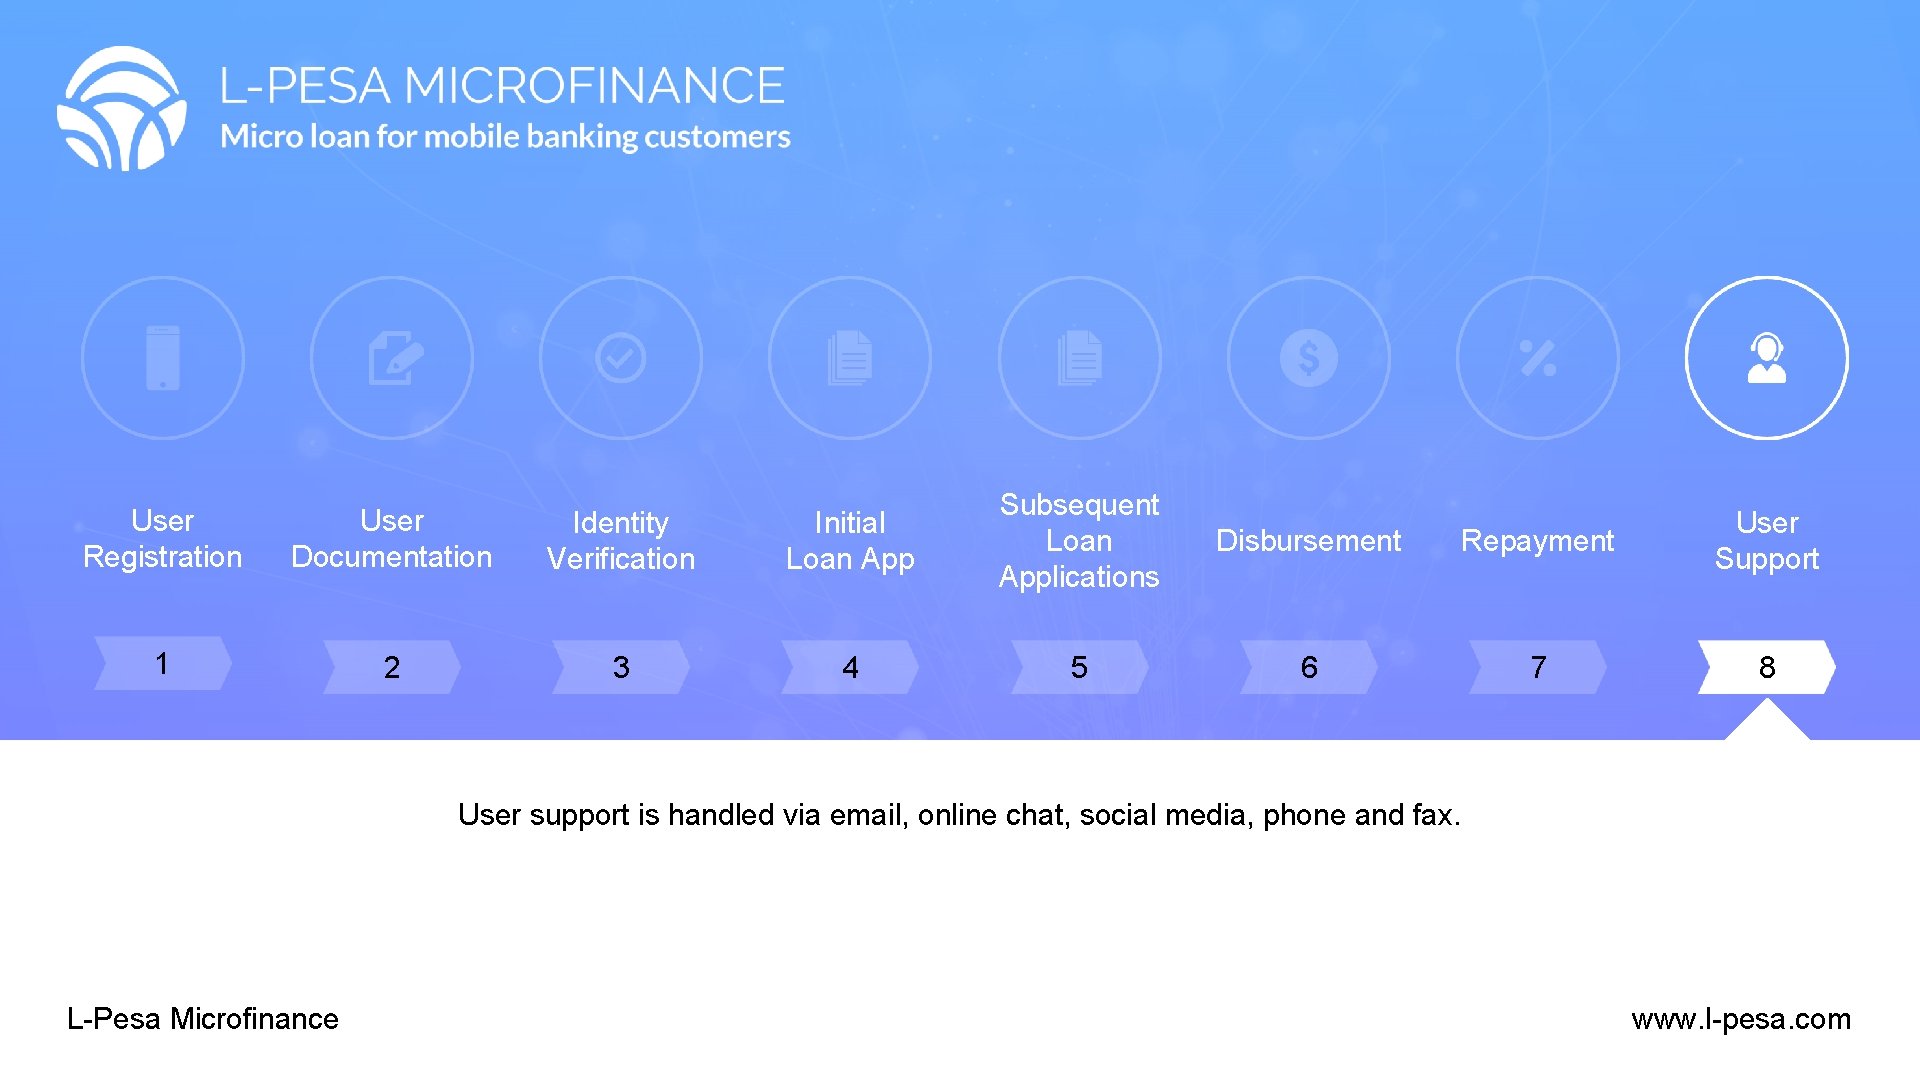
User Registration User Documentation Identity Verification Initial Loan App Subsequent Loan Applications 1 2 3 4 5 Disbursement Repayment User Support 6 7 8 User support is handled via email, online chat, social media, phone and fax. L-Pesa Microfinance www. l-pesa. com
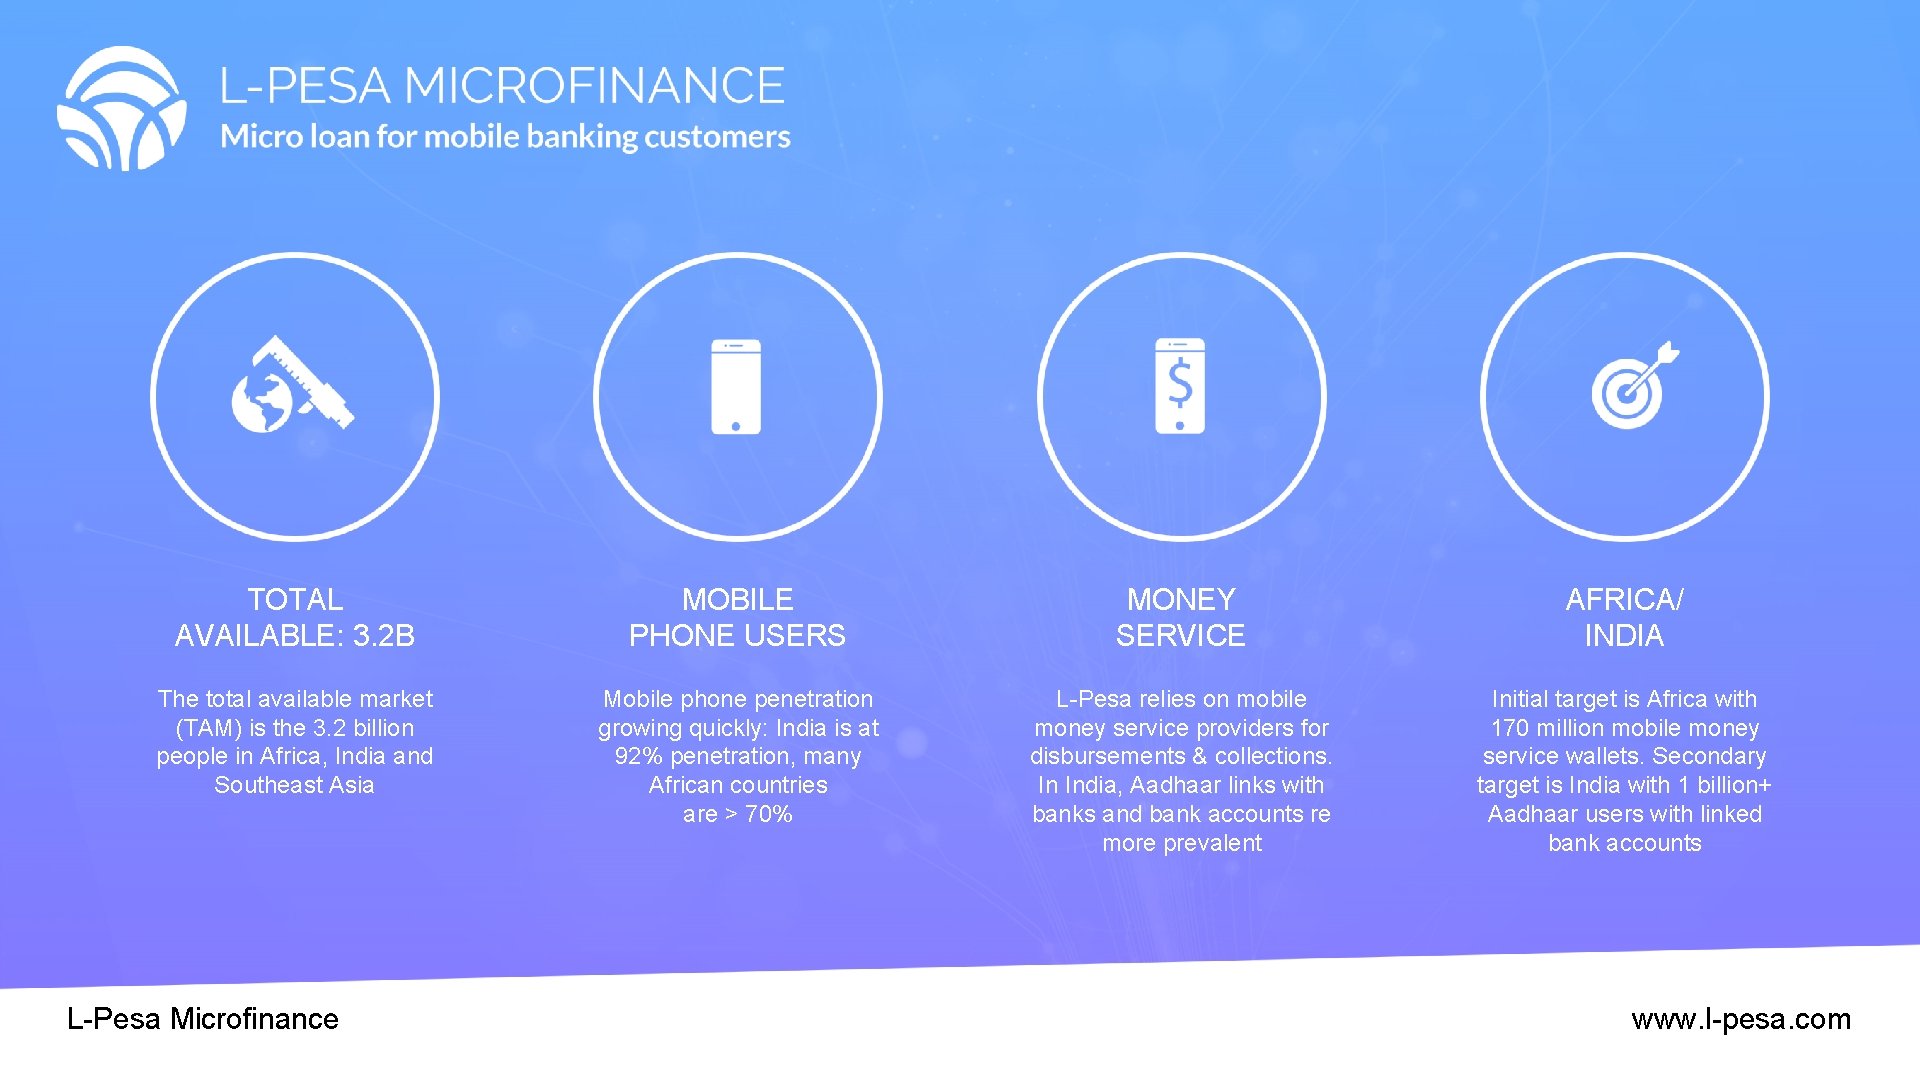
TOTAL AVAILABLE: 3. 2 B MOBILE PHONE USERS MONEY SERVICE AFRICA/ INDIA The total available market (TAM) is the 3. 2 billion people in Africa, India and Southeast Asia Mobile phone penetration growing quickly: India is at 92% penetration, many African countries are > 70% L-Pesa relies on mobile money service providers for disbursements & collections. In India, Aadhaar links with banks and bank accounts re more prevalent Initial target is Africa with 170 million mobile money service wallets. Secondary target is India with 1 billion+ Aadhaar users with linked bank accounts L-Pesa Microfinance www. l-pesa. com
Sales & Marketing L-Pesa has built a predictable and efficient user acquisition engine The demand is enormous and won’t be satisfied for many years L-Pesa has spent 20 months refining its user acquisition engine and it’s now highly efficient 150, 000 registered users have been acquired, primarily via social media marketing campaigns Small scale tests have shown that SMS marketing is the most cost effective campaign type Social media and user referral campaigns will be used to support SMS marketing Target lists for SMS marketing campaigns are already in hand The primary purpose for raising outside capital is to fund marketing campaigns Response rate is expected to exceed 10% L-Pesa Microfinance www. l-pesa. com
Technology L-Pesa has built a highly automated and scalable Fin. Tech platform The market is so large and untapped that competitors actually help each other with user awareness Traditional microfinance institutions compete for a small portion of the market Kiva and similar institutions compete for an even smaller portion of the market Branch is well funded by top VCs and has a strong team. They target Kenya, Tanzania and Nigeria Mobile money service businesses may enter the microfinance market in the future L-Pesa Microfinance www. l-pesa. com
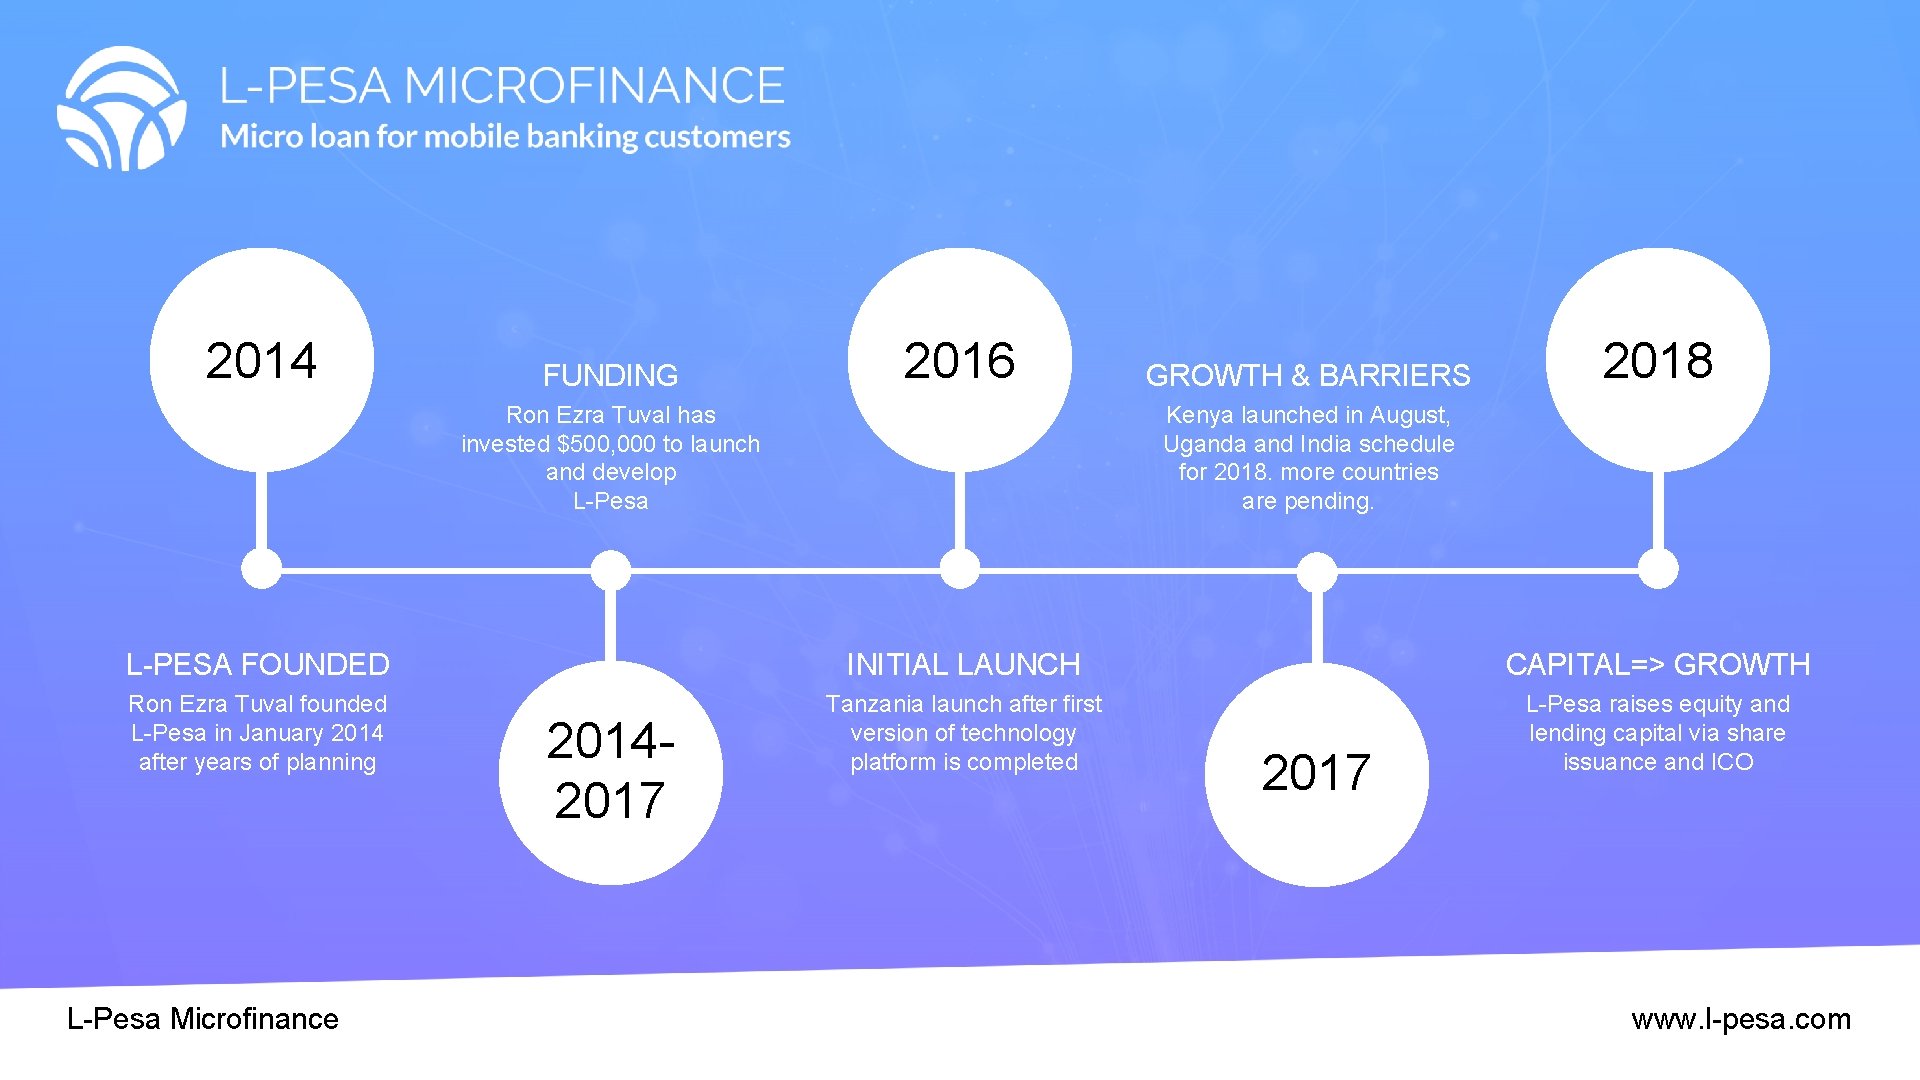
2014 FUNDING 2016 Ron Ezra Tuval has invested $500, 000 to launch and develop L-Pesa GROWTH & BARRIERS 2018 Kenya launched in August, Uganda and India schedule for 2018. more countries are pending. L-PESA FOUNDED INITIAL LAUNCH CAPITAL=> GROWTH Ron Ezra Tuval founded L-Pesa in January 2014 after years of planning Tanzania launch after first version of technology platform is completed L-Pesa raises equity and lending capital via share issuance and ICO L-Pesa Microfinance 20142017 www. l-pesa. com