
Redundancy where to from here Presentation date Presenter
- Slides: 32
Redundancy – where to from here? << Presentation date >> << Presenter name >> << Presenter job title >> << Business details >> << Insert licensee logo >>
Important notice << Insert company disclaimer >>
[Company name] – our credentials • Experienced – Over xx years experience – Over xxxx clients – Over $xx funds under advice • Professional personal advice • Advice underpinned by quality research and technical teams • Over xx offices nationwide • Backed by a global company
Making the right decisions • It’s important to seek professional financial advice during times of change • Sound financial advice may help you Ø Minimise tax paid on termination payments Ø Choose the right superannuation fund Ø Maximise retirement savings Ø Maximise social security entitlements Ø Qualify for cheap pharmaceuticals Ø Maintain essential insurance coverage Ø Effectively manage existing debts
Tailored advice is important • You have your own set of needs and objectives • Each redundancy package is unique and requires a tailored approach • Types of redundancy payments and amounts received depend on Ø Time served with your employer Ø Your income Ø Terms and conditions in your award (if applicable), workplace agreement (if applicable) and other relevant laws
Tax concessions on genuine redundancies • Not all redundancies are classed as genuine redundancies • Genuine redundancies qualify for special taxation treatment on unused annual leave and long service leave payments • Genuine redundancies also qualify for some of your payment, called genuine redundancy payment, to be tax free
What is a genuine redundancy? Generally, a genuine redundancy occurs where: Ø Job role is no longer required or is relocated to a distant location Ø Employee is under age 65 Ø No arrangement with employer to re-employ Ø Payments are made on a arm’s length basis
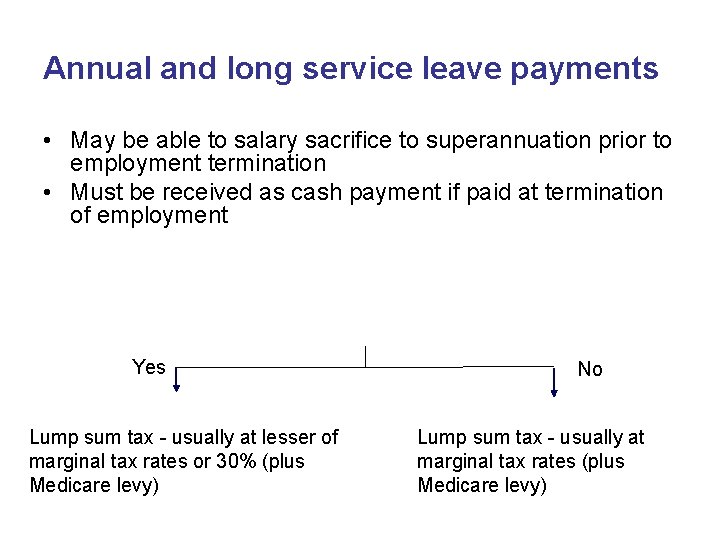
Annual and long service leave payments • May be able to salary sacrifice to superannuation prior to employment termination • Must be received as cash payment if paid at termination of employment Yes Lump sum tax - usually at lesser of marginal tax rates or 30% (plus Medicare levy) No Lump sum tax - usually at marginal tax rates (plus Medicare levy)
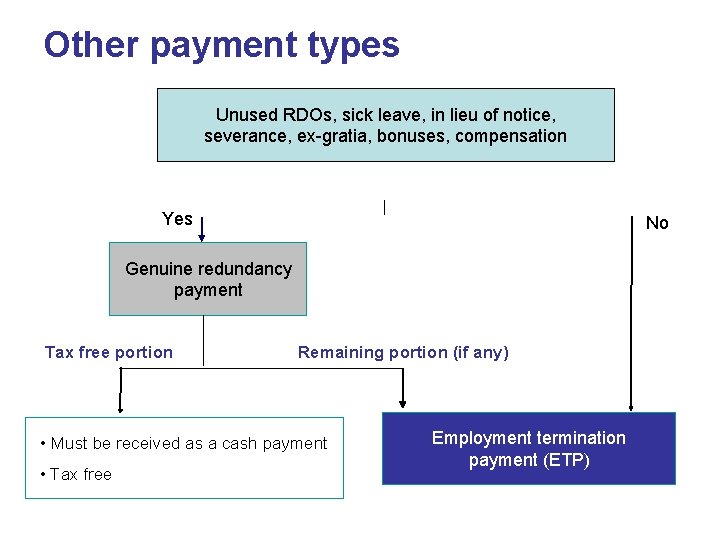
Other payment types Unused RDOs, sick leave, in lieu of notice, severance, ex-gratia, bonuses, compensation Yes No Genuine redundancy payment Tax free portion Remaining portion (if any) • Must be received as a cash payment • Tax free Employment termination payment (ETP)
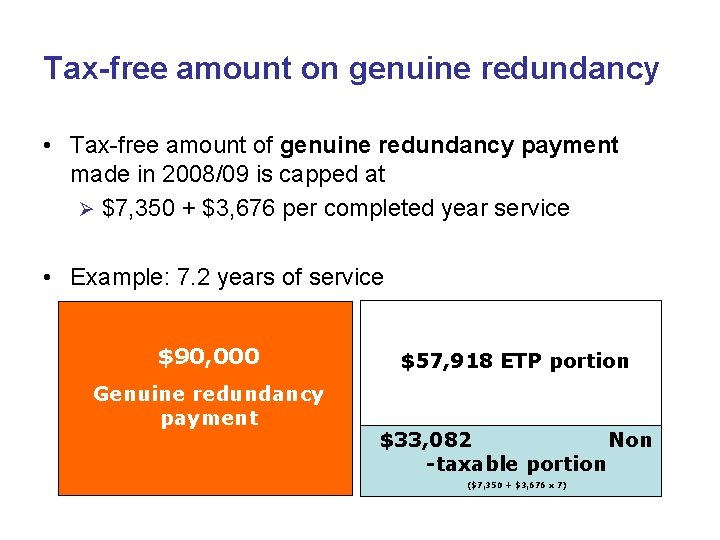
Tax-free amount on genuine redundancy • Tax-free amount of genuine redundancy payment made in 2008/09 is capped at Ø $7, 350 + $3, 676 per completed year service • Example: 7. 2 years of service $90, 000 Genuine redundancy payment $57, 918 ETP portion $33, 082 Non -taxable portion ($7, 350 + $3, 676 x 7)
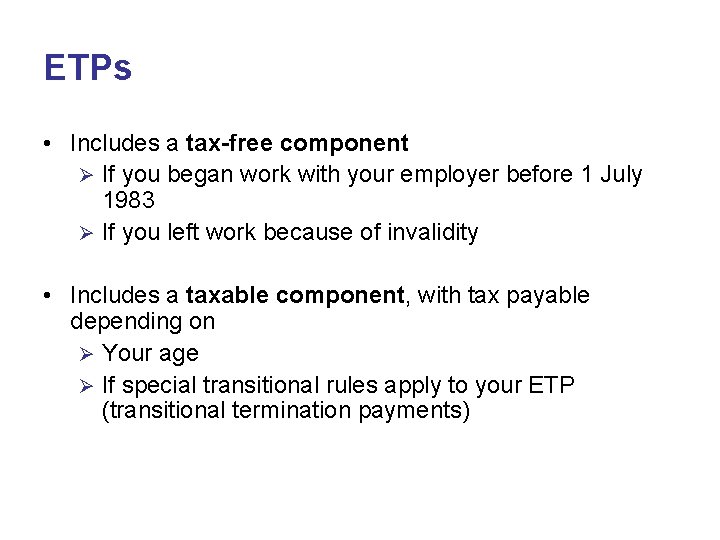
ETPs • Includes a tax-free component Ø If you began work with your employer before 1 July 1983 Ø If you left work because of invalidity • Includes a taxable component, with tax payable depending on Ø Your age Ø If special transitional rules apply to your ETP (transitional termination payments)
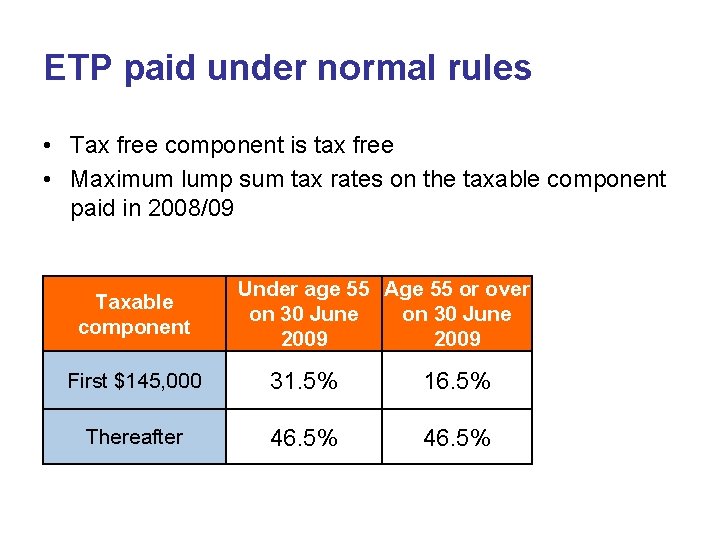
ETP paid under normal rules • Tax free component is tax free • Maximum lump sum tax rates on the taxable component paid in 2008/09 Taxable component Under age 55 Age 55 or over on 30 June 2009 First $145, 000 31. 5% 16. 5% Thereafter 46. 5%
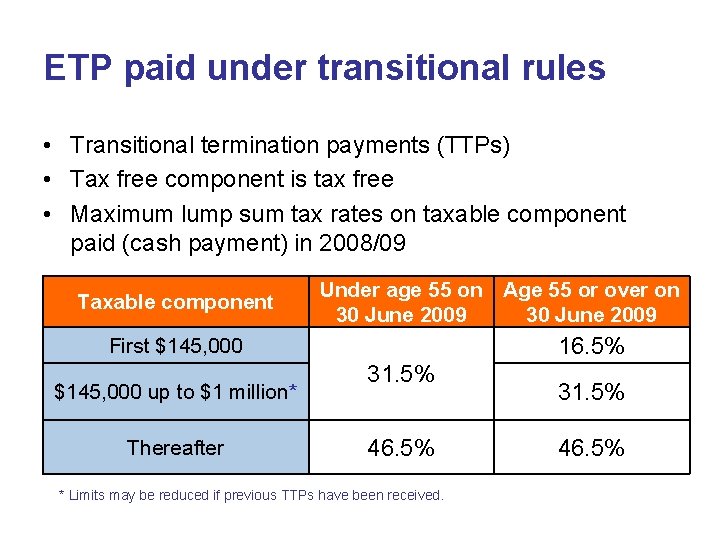
ETP paid under transitional rules • Transitional termination payments (TTPs) • Tax free component is tax free • Maximum lump sum tax rates on taxable component paid (cash payment) in 2008/09 Taxable component Under age 55 on Age 55 or over on 30 June 2009 16. 5% First $145, 000 up to $1 million* Thereafter 31. 5% 46. 5% * Limits may be reduced if previous TTPs have been received. 31. 5% 46. 5%
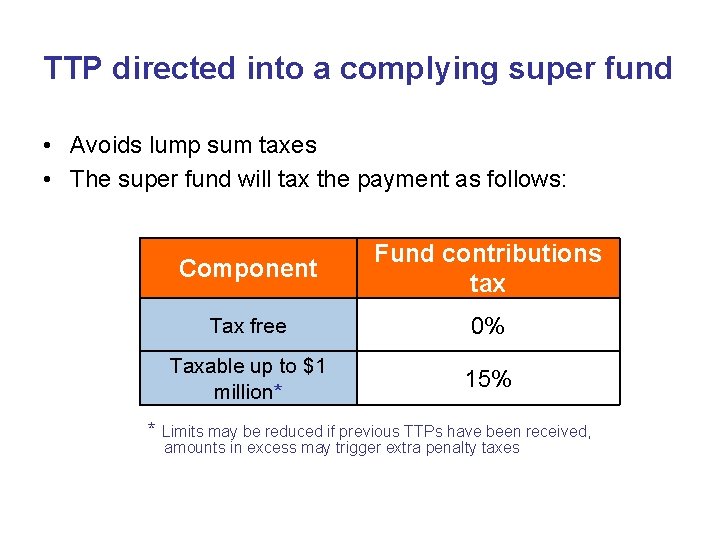
TTP directed into a complying super fund • Avoids lump sum taxes • The super fund will tax the payment as follows: Component Fund contributions tax Tax free 0% Taxable up to $1 million* 15% * Limits may be reduced if previous TTPs have been received, amounts in excess may trigger extra penalty taxes
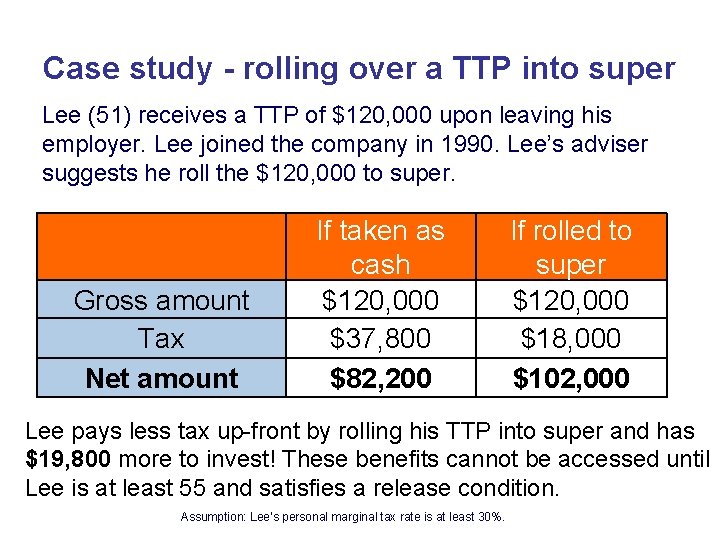
Case study - rolling over a TTP into super Lee (51) receives a TTP of $120, 000 upon leaving his employer. Lee joined the company in 1990. Lee’s adviser suggests he roll the $120, 000 to super. Gross amount Tax Net amount If taken as cash $120, 000 $37, 800 $82, 200 If rolled to super $120, 000 $18, 000 $102, 000 Lee pays less tax up-front by rolling his TTP into super and has $19, 800 more to invest! These benefits cannot be accessed until Lee is at least 55 and satisfies a release condition. Assumption: Lee’s personal marginal tax rate is at least 30%.
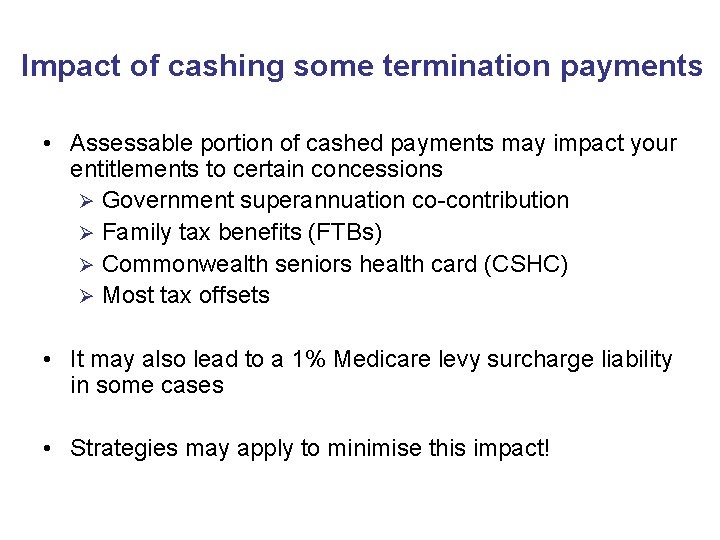
Impact of cashing some termination payments • Assessable portion of cashed payments may impact your entitlements to certain concessions Ø Government superannuation co-contribution Ø Family tax benefits (FTBs) Ø Commonwealth seniors health card (CSHC) Ø Most tax offsets • It may also lead to a 1% Medicare levy surcharge liability in some cases • Strategies may apply to minimise this impact!
Making the hard decisions • Available choices depend on your personal circumstances Ø Age Ø Payment types and amounts Ø Providing for dependants Ø Future work prospects Ø Family’s financial position • I can help you make the right decision
Your choices • Your payments can be used for a variety of purposes Ø Ongoing living expenses Ø Home improvements and other one-off purchases Ø Family holiday Ø Repay personal loans and credit cards Ø Repay non-deductible debts Ø Repay deductible debts Ø Save for your family’s future
Saving via a superannuation vehicle • Superannuation is not an investment but an investment holding vehicle – Cash / fixed interest – Property – Shares – Other • Amounts you contribute are subject to caps and may not be immediately accessible.
Saving via a superannuation vehicle • Tax concessions – 15% maximum tax rate on earnings • No fund tax if in pension mode – No tax on withdrawals from age 60 (most funds) • Social security concessions – Exempt from income and assets testing if under pension age and not in pension mode – Income test concessions if in pension mode
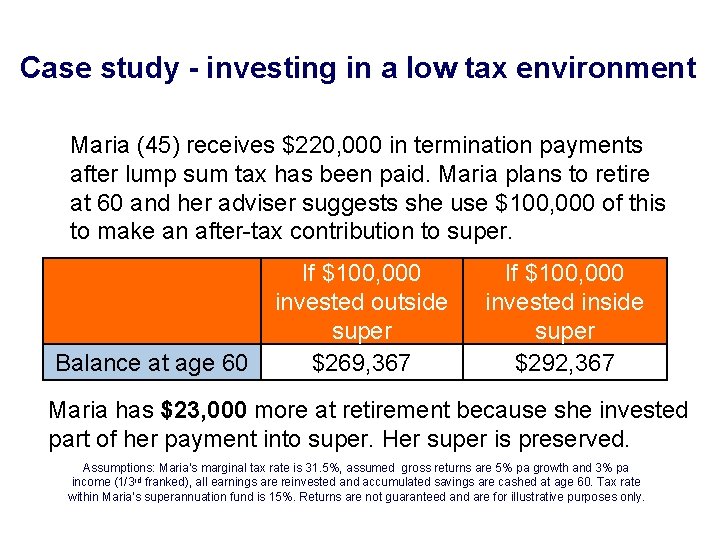
Case study - investing in a low tax environment Maria (45) receives $220, 000 in termination payments after lump sum tax has been paid. Maria plans to retire at 60 and her adviser suggests she use $100, 000 of this to make an after-tax contribution to super. Balance at age 60 If $100, 000 invested outside super $269, 367 If $100, 000 invested inside super $292, 367 Maria has $23, 000 more at retirement because she invested part of her payment into super. Her super is preserved. Assumptions: Maria’s marginal tax rate is 31. 5%, assumed gross returns are 5% pa growth and 3% pa income (1/3 rd franked), all earnings are reinvested and accumulated savings are cashed at age 60. Tax rate within Maria’s superannuation fund is 15%. Returns are not guaranteed and are for illustrative purposes only.
Your existing superannuation benefits • You generally only have access to existing unrestricted non-preserved amounts only • Access to other amounts is denied until you – Are retired and have reached your preservation age (age 55 if born before 1 July 1960) – Reach age 65 – Meet a qualifying release condition
Your existing superannuation benefits • Depending on your superannuation fund’s rules, you may need to transfer your superannuation savings to a new fund • Before transferring your superannuation savings, make sure – Your employer has paid all outstanding superannuation contributions – You exercise continuation options or arrange replacement cover on insurance policies!
Meeting your personal insurance needs • Will your personal insurance policies pay benefits while you’re not employed? • Make sure your family is protected if something was to happen to you Ø Cash flow friendly superannuation ownership option may apply to you Ø Remember, if you hold cover in an existing superannuation fund, exercise continuation options or arrange replacement cover before transferring your benefits out.
Centrelink www. centrelink. gov. au Appointments Ph: 13 10 21 Disability & Carers Ph: 13 27 17 Employment services Ph: 13 28 50 Family Assistance Office Ph: 13 61 50 DVA Ph: 13 32 54
Centrelink support • Income support entitlements are generally based on your income and assets • Your termination payments may lead to a waiting period before you can claim Ø You may qualify for certain strategies to reduce or avoid these waiting periods • There are many types of income support payments and concession cards (cheap pharmaceuticals) available through Centrelink
Common Centrelink income support benefits • Newstart Allowance • Age Pension • Disability Support Pension • Parenting Payment • Carer Payment
Case study - Centrelink payments sooner Rachel (51) receives $35, 000 in termination payments (35 weeks worth of pay), of which $20, 000 can be directed to super. Rachel wishes to claim Newstart Allowance. Rachel’s adviser recommends she directs the $20, 000 to her super fund. Waiting period If TTP taken as cash If TTP rolled to super 35 weeks 15 weeks By directing the $20, 000 into her super fund, Rachel qualifies for Newstart Allowance 20 weeks sooner. These benefits cannot be accessed until age 55 and a release condition has been satisfied.
GEERS • Applies where employer becomes bankrupt or liquidator appointed • General Employee Entitlements & Redundancy Scheme (GEERS) can pay your lost entitlements up to Ø 3 months unpaid wages (includes sacrificed salary) Ø Unpaid annual leave and long service leave Ø 5 weeks unpaid payment in lieu of notice Ø 16 weeks unpaid redundancy entitlement www. workplace. gov. au/geers
Other useful contacts • If your employer is late paying your superannuation guarantee payments Ø Australian Taxation Office (ATO) Ø Ph: 13 10 20 • To find out more about your employment rights Ø Workplace Infoline Ø Ph: 1300 363 264 Ø Workplace Ombudsman Help Line Ø Ph: 1300 724 200
How can I help? • Preparation of a tailored financial plan to help you through your redundancy Ø Effective strategies to limit lump sum taxes payable and maximise social security entitlements Ø Superannuation advice Ø Risk management advice Ø Investment advice Ø Budget planning advice Ø Debt management advice Ø Estate planning
Like some financial advice? Please call me if you’d like to find out more about how I can help you take advantage of your financial options. << insert adviser name >> << insert adviser job title >> Ø Ph: ( ) Ø Mob: ( ) Ø Email: Ø << insert adviser work address >> << Insert business logo and licensee details here>>