
Recent Tax Developments June 2020 Direct tax landscape
- Slides: 6
Recent Tax Developments June 2020
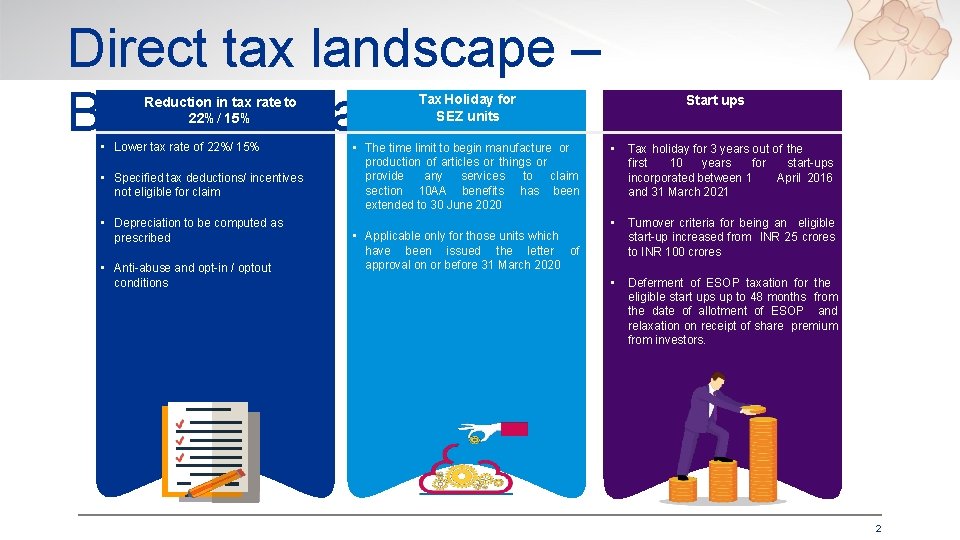
Direct tax landscape – Beneficial tax regime Reduction in tax rate to 22%/ 15% • Lower tax rate of 22%/ 15% • Specified tax deductions/ incentives not eligible for claim • Depreciation to be computed as prescribed • Anti-abuse and opt-in / optout conditions Tax Holiday for SEZ units • The time limit to begin manufacture or production of articles or things or provide any services to claim section 10 AA benefits has been extended to 30 June 2020 • Applicable only for those units which have been issued the letter of approval on or before 31 March 2020 Start ups • Tax holiday for 3 years out of the first 10 years for start-ups April 2016 incorporated between 1 and 31 March 2021 • Turnover criteria for being an eligible start-up increased from INR 25 crores to INR 100 crores • Deferment of ESOP taxation for the eligible start ups up to 48 months from the date of allotment of ESOP and relaxation on receipt of share premium from investors. 2
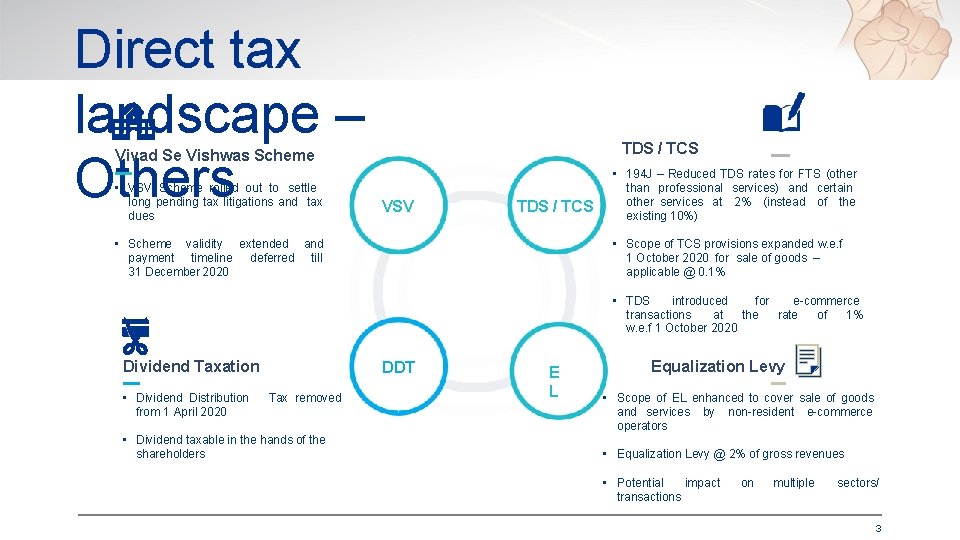
Direct tax landscape – Others TDS / TCS Vivad Se Vishwas Scheme • VSV Scheme rolled out to settle long pending tax litigations and tax dues VSV TDS / TCS • Scheme validity extended and payment timeline deferred till 31 December 2020 • 194 J – Reduced TDS rates for FTS (other than professional services) and certain other services at 2% (instead of the existing 10%) • Scope of TCS provisions expanded w. e. f 1 October 2020 for sale of goods – applicable @ 0. 1% • TDS introduced for e-commerce transactions at the rate of 1% w. e. f 1 October 2020 Dividend Taxation • Dividend Distribution from 1 April 2020 DDT Tax removed • Dividend taxable in the hands of the shareholders E L Equalization Levy • Scope of EL enhanced to cover sale of goods and services by non-resident e-commerce operators • Equalization Levy @ 2% of gross revenues • Potential impact transactions on multiple sectors/ 3
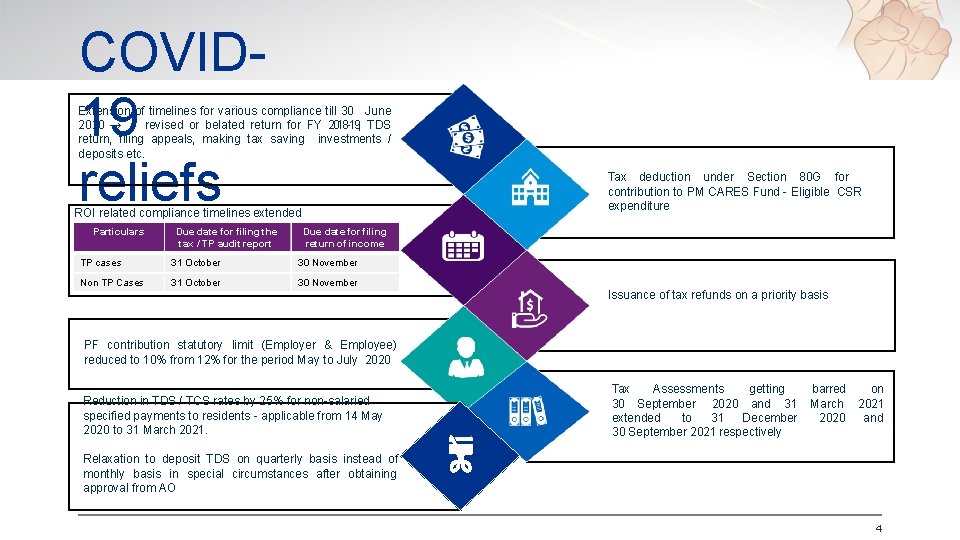
COVID 19 reliefs Extension of timelines for various compliance till 30 June 2020 → revised or belated return for FY 2018 -19, TDS return, filing appeals, making tax saving investments / deposits etc. Tax deduction under Section 80 G for contribution to PM CARES Fund - Eligible CSR expenditure ROI related compliance timelines extended Particulars Due date for filing the tax / TP audit report Due date for filing return of income TP cases 31 October 30 November Non TP Cases 31 October 30 November Issuance of tax refunds on a priority basis PF contribution statutory limit (Employer & Employee) reduced to 10% from 12% for the period May to July 2020 Reduction in TDS / TCS rates by 25% for non-salaried specified payments to residents - applicable from 14 May 2020 to 31 March 2021. Tax Assessments getting 30 September 2020 and 31 extended to 31 December 30 September 2021 respectively barred March 2020 on 2021 and Relaxation to deposit TDS on quarterly basis instead of monthly basis in special circumstances after obtaining approval from AO 4
Key indirect tax measures Due date for SEIS application for FY 2018 -19 extended up to 31 December 2020. No clarity on extension of SEIS benefits for FY 2020 -21. Notification being expected. Immediate Grant of Refund - Direction given to issue all pending eligible refunds under GST and Customs law in specified cases Extension of certain time limits for GST compliances, completion of proceedings, issuance of notices, filing of appeals etc. under GST and Customs laws till 30 Jun 2020 5
• • Key tax consideratio ns Consolidation perspective. of multiple entities Expediting tax refunds and incentives optimization standpoint. from an efficiency from a cash flow • Streamlining of profitable and loss making units IBC protection standpoint to be considered. • Strengthening of balance sheet can be considered to enable ease of fund raise. • Impact of tax holiday claim under section 10 AA in case of employees working from home. • Deductibility of expenses during would need to be evaluated. from a the period of lockdown 6