
Real Estate Funds and Tax Caspar Noble Director
Real Estate Funds and Tax. Caspar Noble Director, Private Client Services 27 October 2006

Real Estate Funds Current commercial situation • Shift in real estate ownership patterns from direct to indirect ownership via professionallymanaged, diversified funds, evidenced by rapid growth of funds under management: – Globally, there was € 695 bn of real estate held in RE funds at end 2005 (€ 485 bn in 2004) of which € 405 bn in Europe (€ 310 bn in 2004) • Increase in cross-border capital flows within EU and, particularly, the eurozone: – € 54 bn in cross-border acquisitions in 2004 compared with € 18 bn in 1999 • Recent push into emerging markets – $3 bn of cross-border acquisitions in Asia-Pac (excl Japan) in 2004 • Impact of REIT regimes globally • Trends: – Increased complexity – Growing internationalisation 2 © 2006 Deloitte PCS Limited. Private and confidential
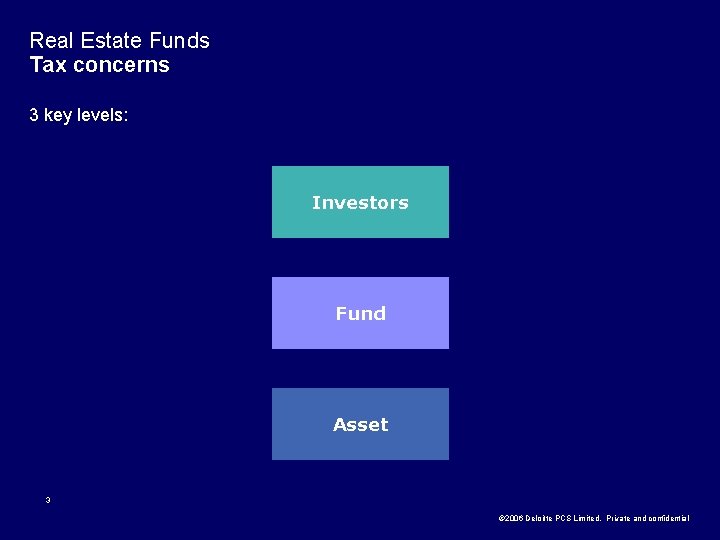
Real Estate Funds Tax concerns 3 key levels: Investors Fund Asset 3 © 2006 Deloitte PCS Limited. Private and confidential
The asset
Real Estate Funds Asset - acquisition • Transfer taxes / registration duties payable by purchaser? – Spain - 6%/7% depending on the location of the property – UK: stamp duty at 4% – France: 4. 8% transfer tax on the sale of shares in French real estate companies or 4. 89% registration duty on the purchase of buildings older than 5 years – Germany: 3. 5% transfer tax • Capital duty? • 6 th directive tax? • In many jurisdictions the above can be limited by acquisitions through local property holding Companies. May also be an administrative/legal requirement 5 © 2006 Deloitte PCS Limited. Private and confidential
Real Estate Funds Asset – exit • Some jurisdictions do not tax capital gains realised by non resident investors in domestic real estate (eg UK). • Owning property through a local holding company may allow a tax free gain to be achieved by a share sale. • Commonly a separate company will be used to hold each company as this gives more options on exit. • ‘Participation Exemption’ – partial or complete exemption from tax on gains on the sale of shares (eg Netherlands, Luxembourg, Belgium). 6 © 2006 Deloitte PCS Limited. Private and confidential
Real Estate Funds Asset – income and expenses Income recognition: Level of tax deductibility of expenses pushed down to asset level likely to be regulated: • Thin capitalisation rules: − UK – arm’s length − Germany – 60: 40 debt to equity on internal financing − Luxembourg – 85: 15 debt to equity, however 99: 1 may be permitted under a tax ruling • Transfer pricing rules: − UK – arm’s length − Germany – arm’s length − Luxembourg – arm’s length, however interest margin can be agreed in a tax ruling • Other deductions – ‘tax depreciation’ – Eg in Spain, tax depreciation is available on all tangible fixed assets (except land) at particular rates, depreciation methods and terms established by the tax regulations for various economic and industrial sectors 7 © 2006 Deloitte PCS Limited. Private and confidential
The fund

Real Estate Funds Key structuring considerations • Transparency: Investor receives share of income flow and capital value of real estate in line with percentage share of investment • Tax neutrality: Investment vehicle should be tax transparent, or at least not add material tax cost • Liquidity: Investor may be able to dispose of shares in the vehicle separately from asset itself 9 © 2006 Deloitte PCS Limited. Private and confidential
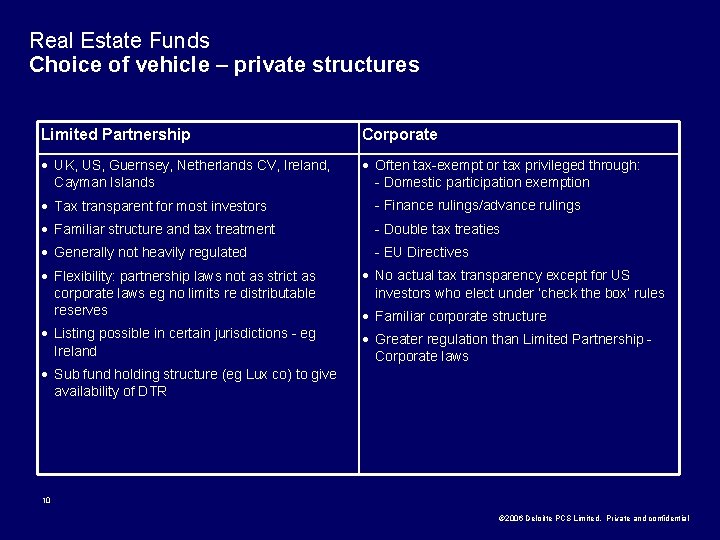
Real Estate Funds Choice of vehicle – private structures Limited Partnership Corporate • UK, US, Guernsey, Netherlands CV, Ireland, Cayman Islands • Often tax-exempt or tax privileged through: - Domestic participation exemption • Tax transparent for most investors - Finance rulings/advance rulings • Familiar structure and tax treatment - Double tax treaties • Generally not heavily regulated - EU Directives • Flexibility: partnership laws not as strict as corporate laws eg no limits re distributable reserves • No actual tax transparency except for US investors who elect under ‘check the box’ rules • Listing possible in certain jurisdictions - eg Ireland • Greater regulation than Limited Partnership Corporate laws • Sub fund holding structure (eg Lux co) to give availability of DTR • Familiar corporate structure 10 © 2006 Deloitte PCS Limited. Private and confidential

Real Estate Funds Choice of vehicle – public structures Real Estate Investment Trust – an alternative to listed property companies • Key = no tax at vehicle level for a REIT but investment and distribution requirements, etc • Now more than 20 jurisdictions eg: – 1960 - US REIT (Real Estate Investment Trust) – 1969 - Dutch FBI or FII (Fiscale Beleggingsinstelling) – 2003 - French SIIC (Sociétés d’Investissements Immobiliers Cotées); – 2004 - Italian FII (Fondi di Investimento Immobiliare); – 2004 - Luxembourg SICAR (Société d’Investissement à Capital Risque) – 2007 - UK REIT – 2007/2008 - German REIT (? ) • Displacing listed property companies? 11 © 2006 Deloitte PCS Limited. Private and confidential

Real Estate Funds Real Estate Investment Trust - conditions • Should be no tax at level of Fund Advantage • Investment requirements Potential disadvantage • Distribution requirements • Recently in UK, proposed in March 2005 and to be introduced on 1 January 2007 • Closed Ended UK resident listed company − Conversion charge − 22% withholding tax on dividends − Taxable as UK property income in the hands of the investor 12 © 2006 Deloitte PCS Limited. Private and confidential
Real Estate Funds Fund Type of Fund and refinements to the Fund maybe driven by investors: 13 © 2006 Deloitte PCS Limited. Private and confidential
The investors
Real Estate Funds Real estate fund investors Investor key concerns, some common to all (even non taxables), others specific eg: • Asset and Fund structured to minimise tax at those levels (as above) • No tax withholdings on distributions from Fund • Form of distribution from Fund – Capital/Income • No investor exposure to individual “CFC” rules eg US PFIC, UK s 739 issues • Ability to pick up credits for underlying taxes, if relevant - eg US • Limit or eliminate investor filings/disclosure caused by structure eg French 3% annual tax on real estate and US tax filings 15 © 2006 Deloitte PCS Limited. Private and confidential
Real Estate Funds Real Estate fund investors Addressing investor key concerns: Need to be addressed on a case by case basis: • Common issues to address in structure eg tax leakage and withholdings • Solution to specifics depends on weighting of investor concerns • Can be addressed in structure or add ons eg structure which can give capital and income returns, or feeder to give capital? • Structural solution to French 3% tax by listing or listed feeder? • Check the box on Fund structure for US taxables and for US tax exempts? 16 © 2006 Deloitte PCS Limited. Private and confidential
Contact details Caspar Noble’s contact details: Direct tel : +44 (0)20 7007 3393 Direct fax : +44 (0)20 7007 0178 Email : casparanoble@deloitte. co. uk Address : Hill House, 1 Little New Street, London, EC 4 A 3 TR 17 © 2006 Deloitte PCS Limited. Private and confidential
19 Member of Deloitte Touche Tohmatsu
- Slides: 18