
Ratings for Local Government Investment Pools Roger Merritt
- Slides: 12
Ratings for Local Government Investment Pools Roger Merritt, Managing Director Government Investment Officers Association Las Vegas, March 2012
Agenda / overview • Fitch’s rating criteria for local government pools • Credit Rating • Volatility Rating • Additional Risk Factors • Assessment of the pool management • Surveillance • New Market Developments • Downgrade/Outlook Negative on U. S. • Appendix A: Examples of research • Appendix B: Rating definitions www. fitchratings. com 9/16/2020 2
Rating Local Government Pools • Apply Global Bond Fund Rating Criteria • Rating for local pools comprises fund credit and volatility ratings • Includes assessment of capability of the pool management • Frequent reviews of pool holdings and other key risk metrics • Ongoing communication with the pool management, including onsite reviews www. fitchratings. com 9/16/2020 3
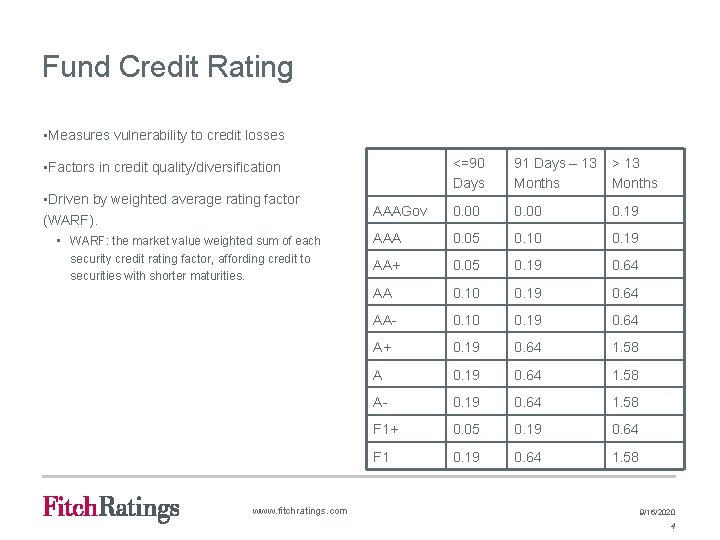
Fund Credit Rating • Measures vulnerability to credit losses <=90 Days 91 Days – 13 > 13 Months AAAGov 0. 00 0. 19 AAA 0. 05 0. 10 0. 19 AA+ 0. 05 0. 19 0. 64 AA 0. 10 0. 19 0. 64 AA- 0. 10 0. 19 0. 64 A+ 0. 19 0. 64 1. 58 A- 0. 19 0. 64 1. 58 F 1+ 0. 05 0. 19 0. 64 F 1 0. 19 0. 64 1. 58 • Factors in credit quality/diversification • Driven by weighted average rating factor (WARF). • WARF: the market value weighted sum of each security credit rating factor, affording credit to securities with shorter maturities. www. fitchratings. com 9/16/2020 4
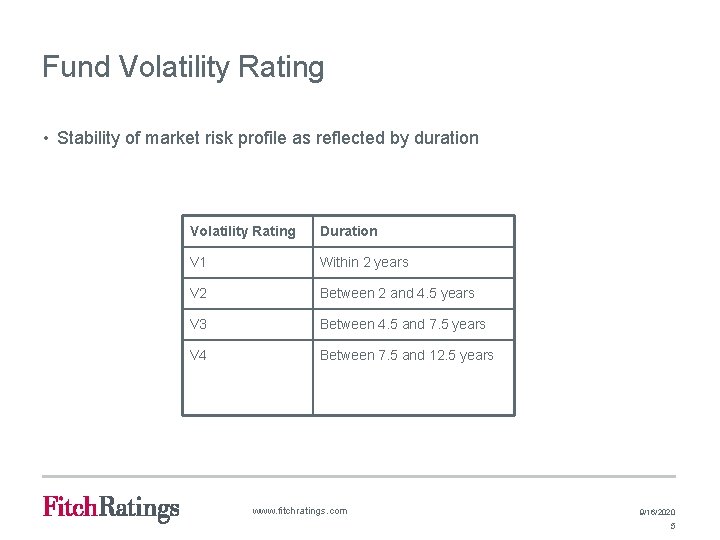
Fund Volatility Rating • Stability of market risk profile as reflected by duration Volatility Rating Duration V 1 Within 2 years V 2 Between 2 and 4. 5 years V 3 Between 4. 5 and 7. 5 years V 4 Between 7. 5 and 12. 5 years www. fitchratings. com 9/16/2020 5
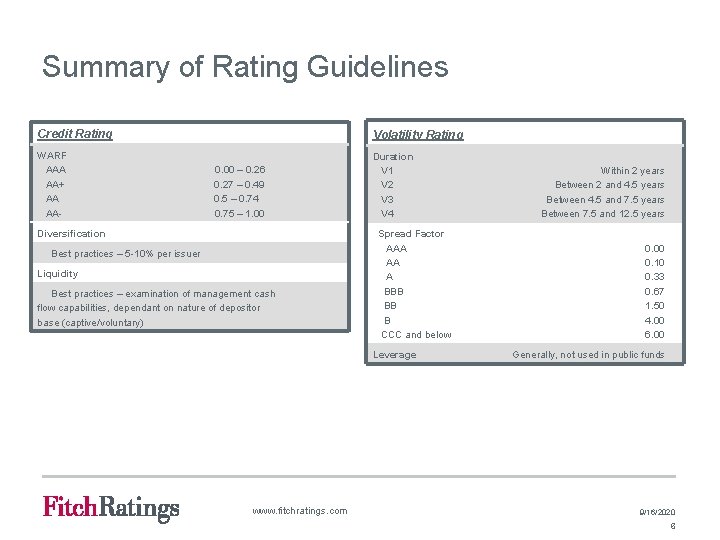
Summary of Rating Guidelines Credit Rating Volatility Rating WARF AAA 0. 00 – 0. 26 AA+ 0. 27 – 0. 49 AA 0. 5 – 0. 74 AA- 0. 75 – 1. 00 Duration V 1 V 2 V 3 V 4 Diversification Spread Factor AAA AA A BBB BB B CCC and below Best practices – 5 -10% per issuer Liquidity Best practices – examination of management cash flow capabilities, dependant on nature of depositor base (captive/voluntary) Leverage www. fitchratings. com Within 2 years Between 2 and 4. 5 years Between 4. 5 and 7. 5 years Between 7. 5 and 12. 5 years 0. 00 0. 10 0. 33 0. 67 1. 50 4. 00 6. 00 Generally, not used in public funds 9/16/2020 6
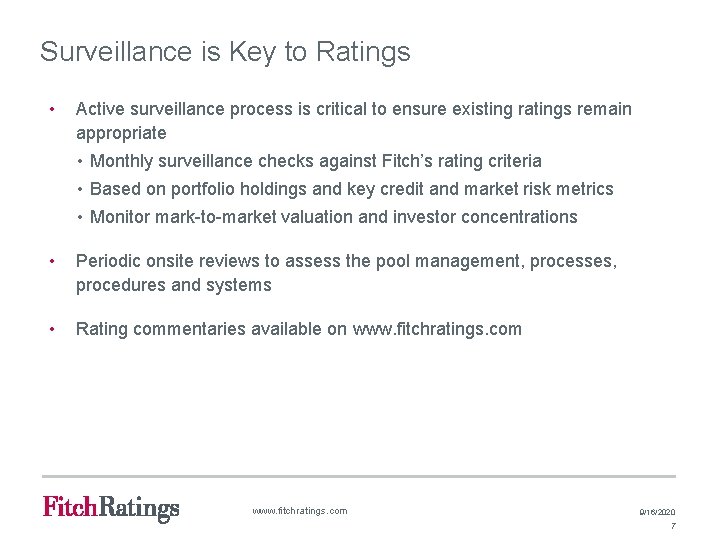
Surveillance is Key to Ratings • Active surveillance process is critical to ensure existing ratings remain appropriate • Monthly surveillance checks against Fitch’s rating criteria • Based on portfolio holdings and key credit and market risk metrics • Monitor mark-to-market valuation and investor concentrations • Periodic onsite reviews to assess the pool management, processes, procedures and systems • Rating commentaries available on www. fitchratings. com 9/16/2020 7
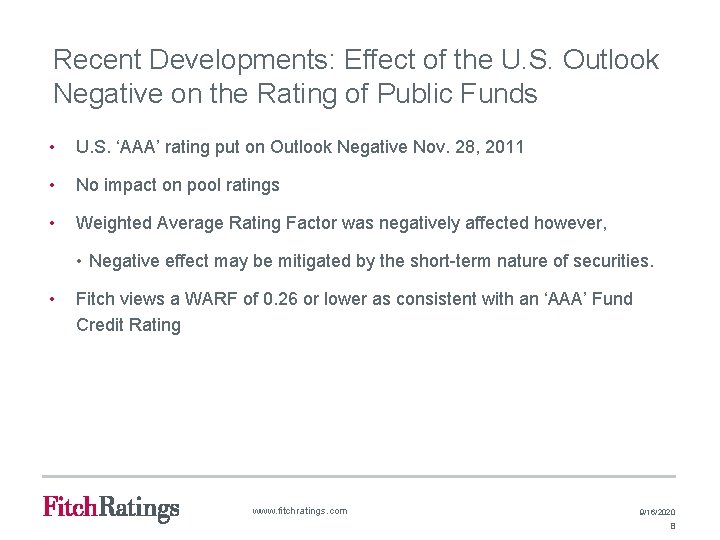
Recent Developments: Effect of the U. S. Outlook Negative on the Rating of Public Funds • U. S. ‘AAA’ rating put on Outlook Negative Nov. 28, 2011 • No impact on pool ratings • Weighted Average Rating Factor was negatively affected however, • Negative effect may be mitigated by the short-term nature of securities. • Fitch views a WARF of 0. 26 or lower as consistent with an ‘AAA’ Fund Credit Rating www. fitchratings. com 9/16/2020 8
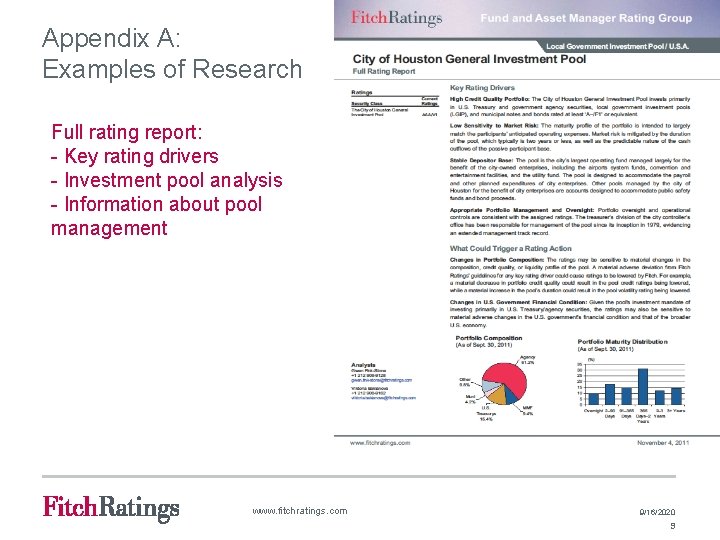
Appendix A: Examples of Research Full rating report: - Key rating drivers - Investment pool analysis - Information about pool management www. fitchratings. com 9/16/2020 9
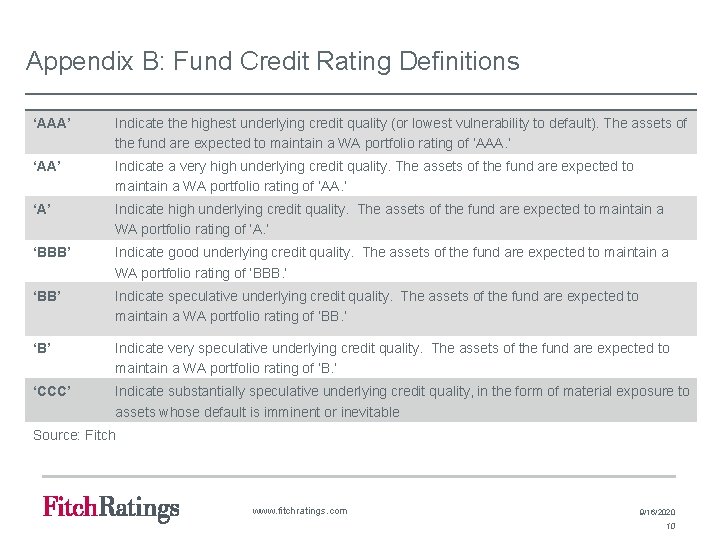
Appendix B: Fund Credit Rating Definitions ‘AAA’ Indicate the highest underlying credit quality (or lowest vulnerability to default). The assets of the fund are expected to maintain a WA portfolio rating of ‘AAA. ’ ‘AA’ Indicate a very high underlying credit quality. The assets of the fund are expected to maintain a WA portfolio rating of ‘AA. ’ ‘A’ Indicate high underlying credit quality. The assets of the fund are expected to maintain a WA portfolio rating of ‘A. ’ ‘BBB’ Indicate good underlying credit quality. The assets of the fund are expected to maintain a WA portfolio rating of ‘BBB. ’ ‘BB’ Indicate speculative underlying credit quality. The assets of the fund are expected to maintain a WA portfolio rating of ‘BB. ’ ‘B’ Indicate very speculative underlying credit quality. The assets of the fund are expected to maintain a WA portfolio rating of ‘B. ’ ‘CCC’ Indicate substantially speculative underlying credit quality, in the form of material exposure to assets whose default is imminent or inevitable Source: Fitch www. fitchratings. com 9/16/2020 10
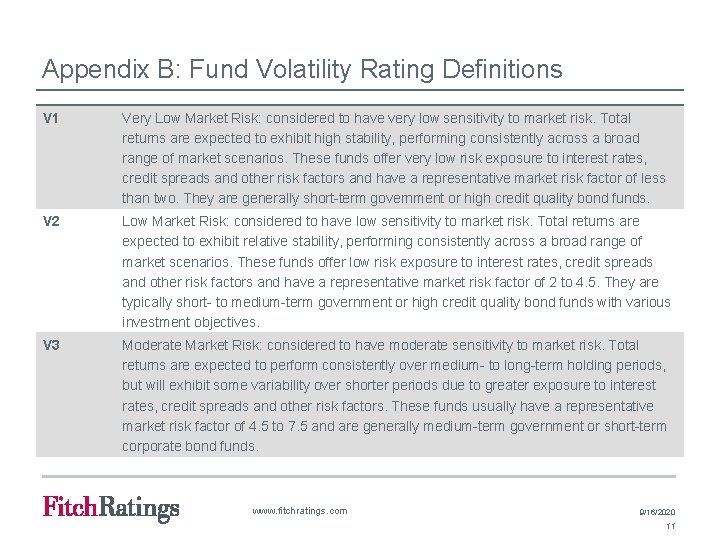
Appendix B: Fund Volatility Rating Definitions V 1 Very Low Market Risk: considered to have very low sensitivity to market risk. Total returns are expected to exhibit high stability, performing consistently across a broad range of market scenarios. These funds offer very low risk exposure to interest rates, credit spreads and other risk factors and have a representative market risk factor of less than two. They are generally short-term government or high credit quality bond funds. V 2 Low Market Risk: considered to have low sensitivity to market risk. Total returns are expected to exhibit relative stability, performing consistently across a broad range of market scenarios. These funds offer low risk exposure to interest rates, credit spreads and other risk factors and have a representative market risk factor of 2 to 4. 5. They are typically short- to medium-term government or high credit quality bond funds with various investment objectives. V 3 Moderate Market Risk: considered to have moderate sensitivity to market risk. Total returns are expected to perform consistently over medium- to long-term holding periods, but will exhibit some variability over shorter periods due to greater exposure to interest rates, credit spreads and other risk factors. These funds usually have a representative market risk factor of 4. 5 to 7. 5 and are generally medium-term government or short-term corporate bond funds. www. fitchratings. com 9/16/2020 11
New York One State Street Plaza New York, NY 10004 London 30 North Colonnade Canary Wharf London E 14 5 GN