
QAD WEBINAR 2012 Presented by Stacey Hillyard QAD
QAD WEBINAR 2012 Presented by: Stacey Hillyard, QAD reviewer Henrietta Thompson, QAD reviewer BUSINESS WITH CONFIDENCE icaew. com
Contents • Audit Monitoring Report 2011 • Clarified ISAs – common problem areas • Professional scepticism • Q&A BUSINESS WITH CONFIDENCE © ICAEW 2012 icaew. com
Ask a question • Participate in today’s webinar – send us a question BUSINESS WITH CONFIDENCE © ICAEW 2012 icaew. com
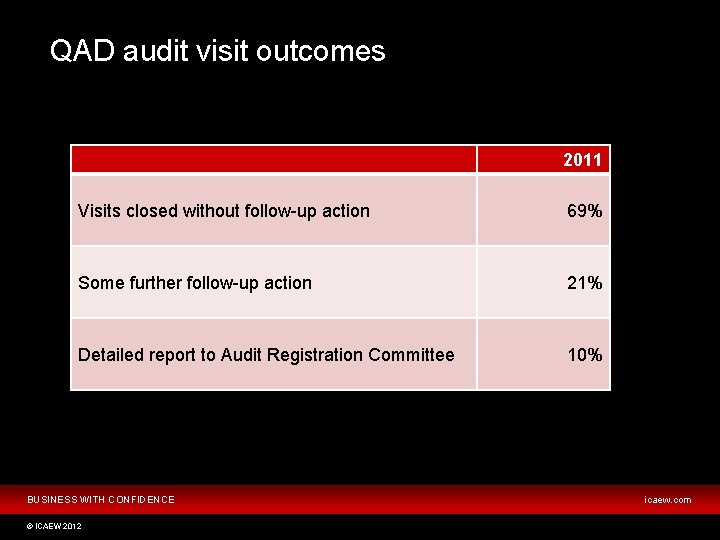
QAD audit visit outcomes 2011 Visits closed without follow-up action 69% Some further follow-up action 21% Detailed report to Audit Registration Committee 10% BUSINESS WITH CONFIDENCE © ICAEW 2012 icaew. com
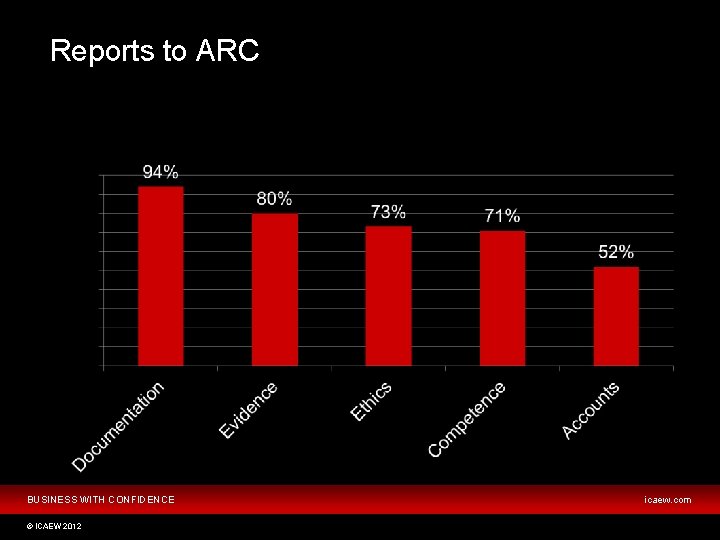
Reports to ARC BUSINESS WITH CONFIDENCE © ICAEW 2012 icaew. com
QAD initiatives in 2011 • Roadshows • Webinars • Mid visit cycle BUSINESS WITH CONFIDENCE © ICAEW 2012 icaew. com
Clarified ISAs – common problem areas • Accounting estimates • Related parties • Risk of fraud – – revenue recognition – management override of controls • Performance materiality • Group audits BUSINESS WITH CONFIDENCE © ICAEW 2012 icaew. com
ISA 540 - Accounting estimates • Planning stage: – Estimates either not identified or recording vague/incomplete – Lack of evidence of discussion with management – review of outcome of PY estimate – either not performed or poorly recorded – High level of estimation uncertainty – not assessed as a significant risk BUSINESS WITH CONFIDENCE © ICAEW 2012 icaew. com
ISA 550 - Related parties • Inquiries with management • Discussion of RP fraud risk at team meeting • Weak documentation of RPs BUSINESS WITH CONFIDENCE © ICAEW 2012 icaew. com
ISA 240 - Fraud considerations • Revenue recognition: – no justification of low risk assessment “N/A covered by audit work” !! “No risk as no cash income” – If significant risk assessed – unclear if sufficient work performed • Management override controls: – Para 32 procedures – work missing or poorly documented BUSINESS WITH CONFIDENCE © ICAEW 2012 icaew. com
ISA 320 - Materiality • F/S level materiality: – No consideration for using separate levels – Questionable benchmark used • Performance materiality: – Not calculated – Some cases too low! BUSINESS WITH CONFIDENCE © ICAEW 2012 icaew. com
ISA 600 - Group audits • Lack of communication with component auditors and weak documentation: – Understanding of CA, recording of the assessment and scope of work – Significant components – involvement in risk assessment/communication – Review and conclusion on adequacy of CA audit work BUSINESS WITH CONFIDENCE © ICAEW 2012 icaew. com
Professional scepticism BUSINESS WITH CONFIDENCE © ICAEW 2012 icaew. com
Characteristics • A questioning mind • Self confidence • Not jumping to conclusions • Understanding management behaviour and motivations BUSINESS WITH CONFIDENCE © ICAEW 2012 icaew. com
Professional scepticism • Fraud risk – Team meeting “fraud is low risk as no previous history of fraud” “fraud is low risk as the client is long standing” BUSINESS WITH CONFIDENCE © ICAEW 2012 icaew. com
Professional scepticism • Substantive analytical review – Management explanations • Provisions – Review of prior year outcome – Lack of provision • Going concern – Recording of discussions BUSINESS WITH CONFIDENCE © ICAEW 2012 icaew. com
Professional scepticism BUSINESS WITH CONFIDENCE © ICAEW 2012 icaew. com
Cold file reviews – the first line of defence! • Identify where audit work can be improved • Evidence of follow up • CFR process – small firms – Annual CFR (either internal or external) – External CFR every 3 rd year • External reviews BUSINESS WITH CONFIDENCE © ICAEW 2012 icaew. com
Resources and support • Audit & Beyond • CPD aide memoire • Audit News • ICAEW Practice Support Services • Technical Advisory Services • ICAEW website BUSINESS WITH CONFIDENCE © ICAEW 2012 icaew. com
QUESTIONS & ANSWERS BUSINESS WITH CONFIDENCE © ICAEW 2012 icaew. com
A world leader of the accountancy and finance profession BUSINESS WITH CONFIDENCE icaew. com
- Slides: 21