
Protective Life Power Session Core Protection Actionable Sales
Protective Life Power Session Core Protection & Actionable Sales Ideas for TODAY WEBINAR Presented by Nicholas Lines Regional Vice President, Protective Life PLAG. 793793 (02. 19) For Financial Professional Use Only. Not For Use With Consumers. For Financial Professional Use Only.
Agenda 1 Protective Story 2 Don’t Sell Your Term Business Short 3 …. No-Lapse IUL, the GUL Alternative For Financial Professional Use Only. Not For Use With Consumers. 2 For Financial Professional Use Only.
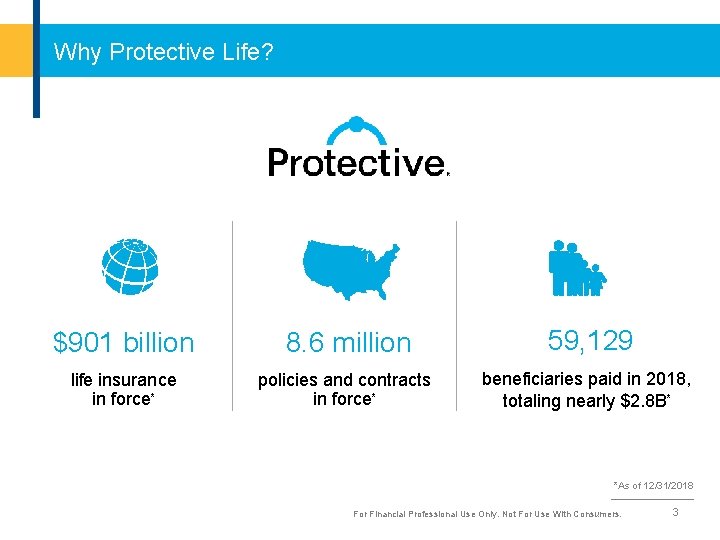
Why Protective Life? $901 billion 8. 6 million 59, 129 life insurance in force* policies and contracts in force* beneficiaries paid in 2018, totaling nearly $2. 8 B* *As of 12/31/2018 For Financial Professional Use Only. Not For Use With Consumers. 3 For Financial Professional Use Only.
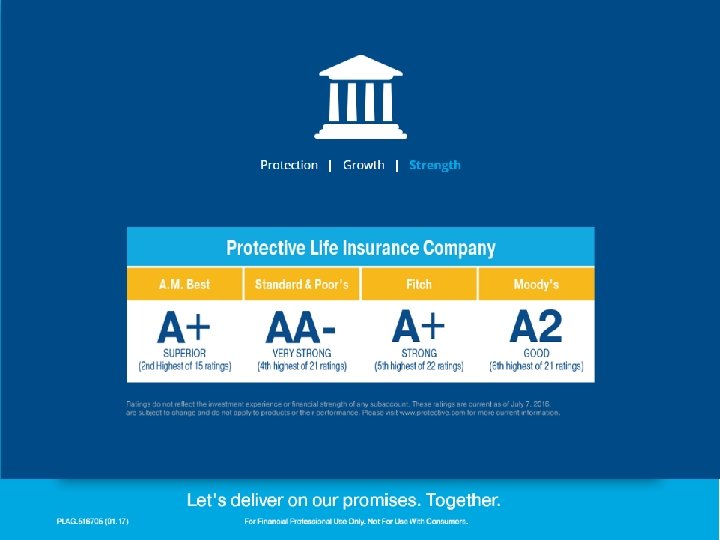
For Financial Professional Use Only. Not For Use With Consumers. 4 For Financial Professional Use Only.
Protective Custom Choice. SM UL Product highlights Coverage that can be extended at no additional cost For Financial Professional Use Only. Not For Use With Consumers. 5 For Financial Professional Use Only.
Protective Custom Choice. SM UL Product highlights Coverage that can All single life permanent be extended with no products available at additional cost the time of conversion For Financial Professional Use Only. Not For Use With Consumers. 6 For Financial Professional Use Only.
Protective Custom Choice. SM UL Product highlights Coverage that can All single life permanent Customized death be extended at no products available at benefit periods additional cost the time of conversion For Financial Professional Use Only. Not For Use With Consumers. 7 For Financial Professional Use Only.
Protective Custom Choice. SM UL Product highlights Coverage that can All single life permanent Customized death be extended at no products available at benefit periods additional cost the time of conversion The acceptance of lump sum payments and 1035 exchanges into the policy For Financial Professional Use Only. Not For Use With Consumers. 8 For Financial Professional Use Only.
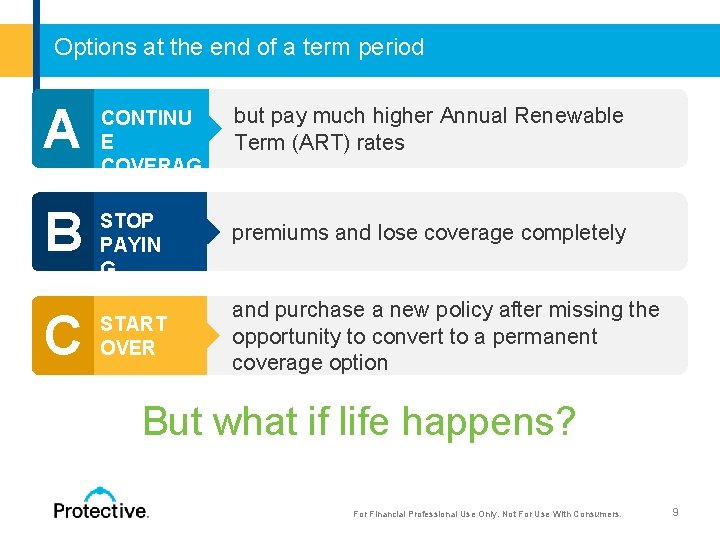
Options at the end of a term period A CONTINU E COVERAG E B STOP PAYIN G C START OVER but pay much higher Annual Renewable Term (ART) rates premiums and lose coverage completely and purchase a new policy after missing the opportunity to convert to a permanent coverage option But what if life happens? 9 For Financial Professional Use Only. Not For Use With Consumers. 9 For Financial Professional Use Only.
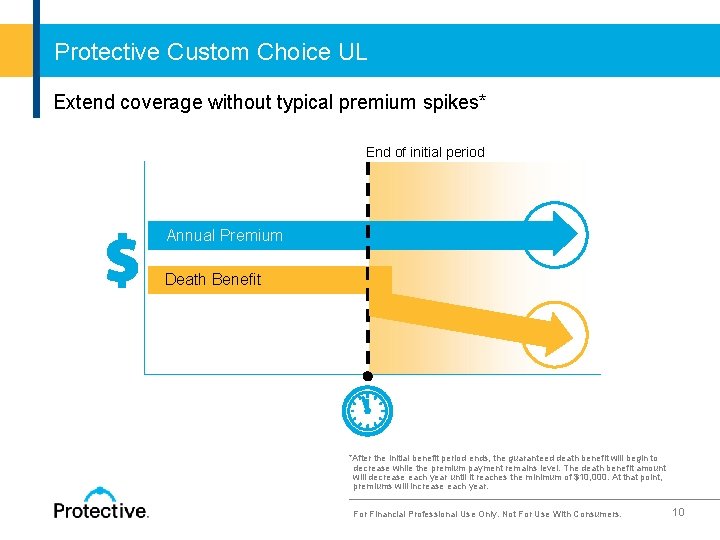
Protective Custom Choice UL Extend coverage without typical premium spikes* End of initial period Annual Premium Death Benefit *After the initial benefit period ends, the guaranteed death benefit will begin to decrease while the premium payment remains level. The death benefit amount will decrease each year until it reaches the minimum of $10, 000. At that point, premiums will increase each year. For Financial Professional Use Only. Not For Use With Consumers. 10 For Financial Professional Use Only.
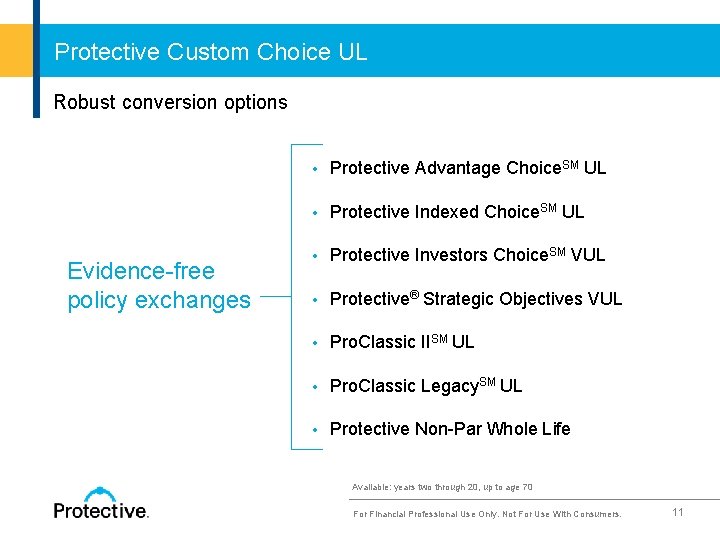
Protective Custom Choice UL Robust conversion options Evidence-free policy exchanges • Protective Advantage Choice. SM UL • Protective Indexed Choice. SM UL • Protective Investors Choice. SM VUL • Protective® Strategic Objectives VUL • Pro. Classic IISM UL • Pro. Classic Legacy. SM UL • Protective Non-Par Whole Life Available: years two through 20, up to age 70 For Financial Professional Use Only. Not For Use With Consumers. 11 For Financial Professional Use Only.
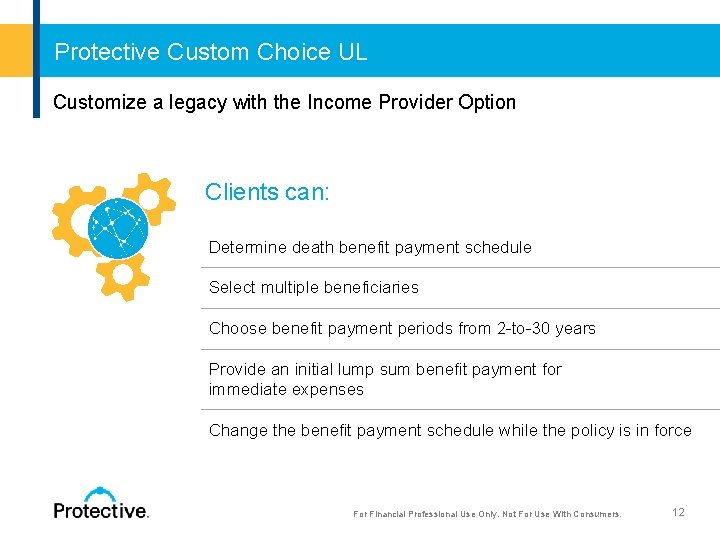
Protective Custom Choice UL Customize a legacy with the Income Provider Option Clients can: Determine death benefit payment schedule Select multiple beneficiaries Choose benefit payment periods from 2 -to-30 years Provide an initial lump sum benefit payment for immediate expenses Change the benefit payment schedule while the policy is in force For Financial Professional Use Only. Not For Use With Consumers. 12 For Financial Professional Use Only.
Process Enhancements Tele. Life® EZ-Worksheet Tele. Life Text Message Reminders Direct Transfer to a Tele. Life Representative For Financial Professional Use Only. Not For Use With Consumers. 13 For Financial Professional Use Only.
Process Enhancements For Financial Professional Use Only. Not For Use With Consumers. 14 For Financial Professional Use Only.
Process Enhancements For Financial Professional Use Only. Not For Use With Consumers. 15 For Financial Professional Use Only.
Process Enhancements For Financial Professional Use Only. Not For Use With Consumers. 16 For Financial Professional Use Only.
Process Enhancements For Financial Professional Use Only. Not For Use With Consumers. 17 For Financial Professional Use Only.
Voice Signature! For Financial Professional Use Only. Not For Use With Consumers. 18 For Financial Professional Use Only.
Voice Signature! For Financial Professional Use Only. Not For Use With Consumers. 19 For Financial Professional Use Only.
The Opportunity Give them what they ask for, then present another option! 20 For Financial Professional Use Only. Not For Use With Consumers. 20 For Financial Professional Use Only.
Protective Indexed Choice UL The Highlights Affordable lifetime protection and flexible premiums Simple design with low cost of insurance and practical illustration rates More cash value and the guaranteed protection of GUL For Financial Professional Use Only. Not For Use With Consumers. 21 For Financial Professional Use Only.
Your Target Client ● Conservative, play-it-safe ● Worried about loss ● Interested in higher yields, but wants downside protection For Financial Professional Use Only. Not For Use With Consumers. 22 For Financial Professional Use Only.
Product Design For Financial Professional Use Only. Not For Use With Consumers. 24 For Financial Professional Use Only.
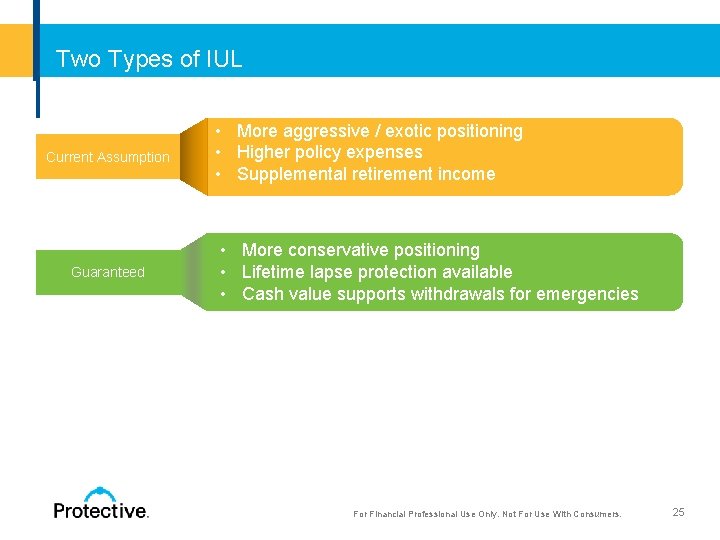
Two Types of IUL Current Assumption Guaranteed • More aggressive / exotic positioning • Higher policy expenses • Supplemental retirement income • More conservative positioning • Lifetime lapse protection available • Cash value supports withdrawals for emergencies Access to the policy value for future expenses or unexpected costs 2 For Financial Professional Use Only. Not For Use With Consumers. 25 For Financial Professional Use Only.
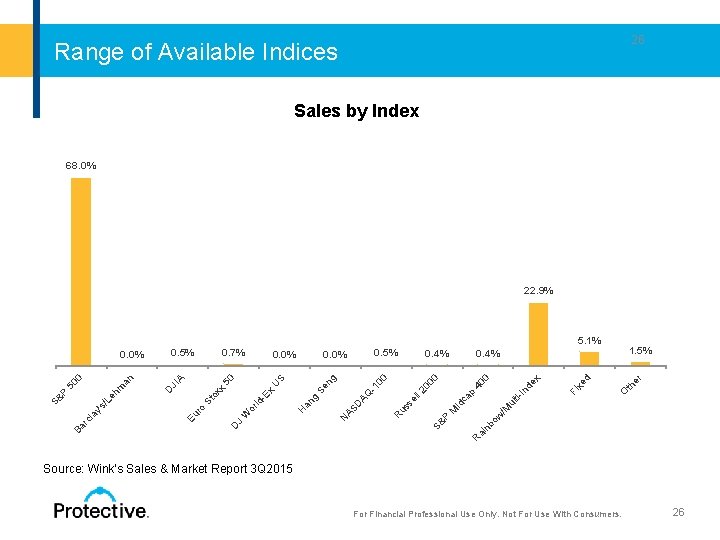
26 Range of Available Indices Sales by Index 68. 0% 22. 9% 5. 1% er O th d xe Fi de x /M ul R ai nb o w M id P S& ti- p ca se ll us R In 00 20 00 1. 5% 0. 4% 40 0 0. 4% -1 N AS D AQ g S an H ld or W J Eu ro S t -E ox x x U S A JI D 0. 5% 0. 0% en g 0. 0% 50 0. 5% D Ba rc la y's /L S& eh P 50 0 m an 0. 0% 0. 7% Source: Wink’s Sales & Market Report 3 Q 2015 For Financial Professional Use Only. Not For Use With Consumers. 26 For Financial Professional Use Only.
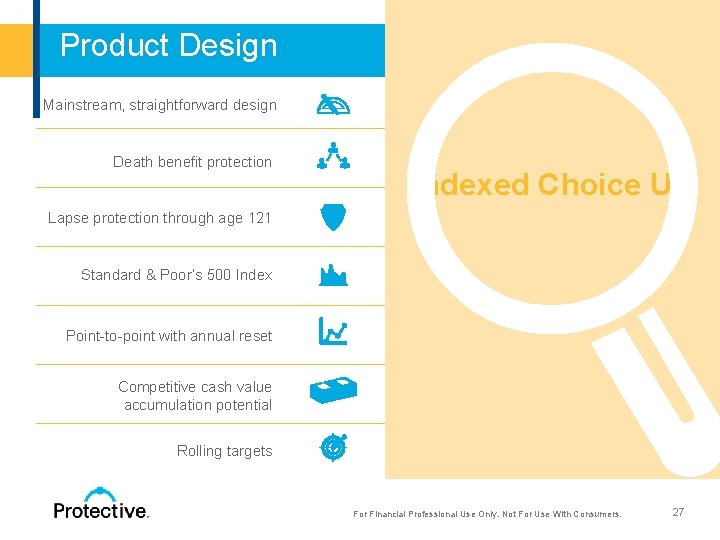
Product Design Mainstream, straightforward design Death benefit protection Indexed Choice UL Lapse protection through age 121 Standard & Poor’s 500 Index Point-to-point with annual reset Competitive cash value accumulation potential Rolling targets For Financial Professional Use Only. Not For Use With Consumers. 27 For Financial Professional Use Only.
28 For Financial Professional Use Only. Not For Use With Consumers. 28 For Financial Professional Use Only.
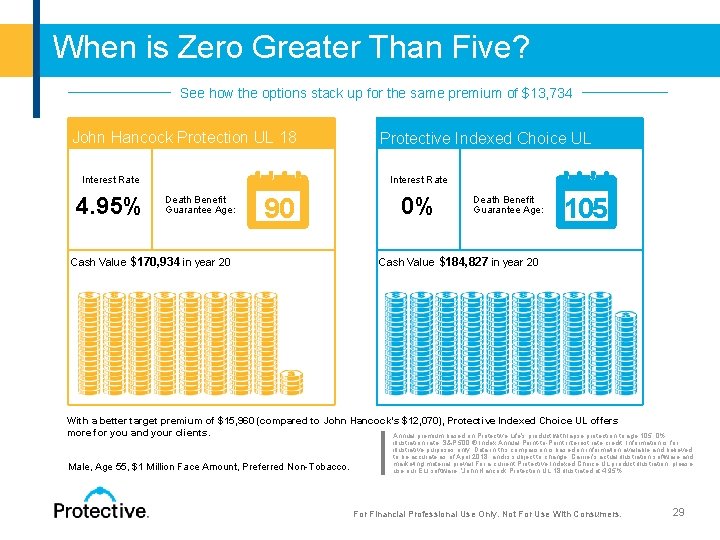
When is Zero Greater Than Five? See how the options stack up for the same premium of $13, 734 John Hancock Protection UL 18 Protective Indexed Choice UL Interest Rate 4. 95% Death Benefit Guarantee Age: 90 Cash Value $170, 934 in year 20 Interest Rate 0% Death Benefit Guarantee Age: 105 Cash Value $184, 827 in year 20 With a better target premium of $15, 960 (compared to John Hancock’s $12, 070), Protective Indexed Choice UL offers more for you and your clients. Annual premium based on Protective Life's product with lapse protection to age 105. 0% Male, Age 55, $1 Million Face Amount, Preferred Non-Tobacco. illustration rate. S&P 500 ® Index Annual Point-to-Point interest rate credit. Information is for illustrative purposes only. Data in this comparison is based on information available and believed to be accurate as of April 2018. and is subject to change. Carrier's actual illustration software and marketing material prevail For a current Protective Indexed Choice UL product illustration. please use our ELI software. 'John Hancock Protection UL 18 illustrated at 4. 95%. For Financial Professional Use Only. Not For Use With Consumers. 29 For Financial Professional Use Only.
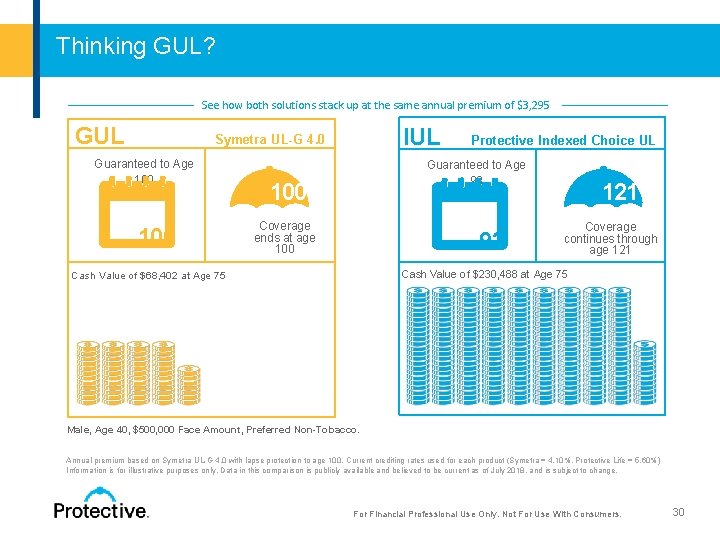
Thinking GUL? See how both solutions stack up at the same annual premium of $3, 295 GUL Symetra UL-G 4. 0 Guaranteed to Age 100 IUL Protective Indexed Choice UL Guaranteed to Age 93 Coverage ends at age 100 93 Cash Value of $68, 402 at Age 75 121 Coverage continues through age 121 Cash Value of $230, 488 at Age 75 Male, Age 40, $500, 000 Face Amount, Preferred Non-Tobacco. Annual premium based on Symetra UL-G 4. 0 with lapse protection to age 100. Current crediting rates used for each product (Symetra = 4. 10%, Protective Life = 5. 60%) Information is for illustrative purposes only. Data in this comparison is publicly available and believed to be current as of July 2018, and is subject to change. For Financial Professional Use Only. Not For Use With Consumers. 30 For Financial Professional Use Only.
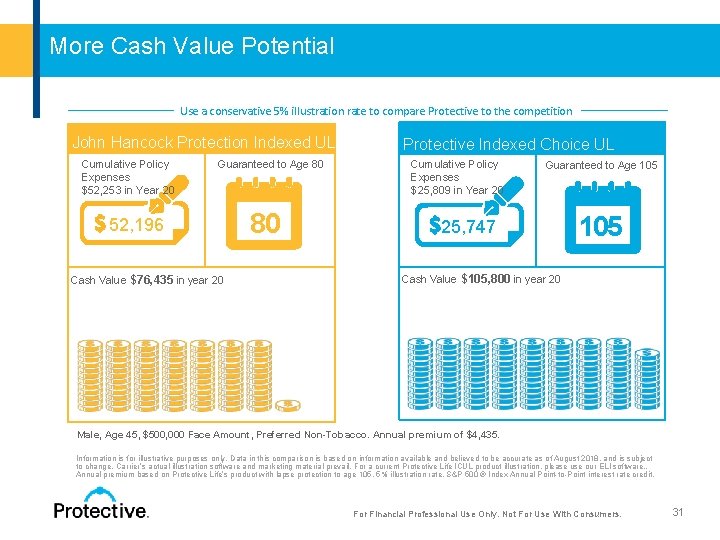
More Cash Value Potential Use a conservative 5% illustration rate to compare Protective to the competition John Hancock Protection Indexed UL Cumulative Policy Expenses $52, 253 in Year 20 52, 196 Guaranteed to Age 80 100 Cash Value $76, 435 in year 20 80 Protective Indexed Choice UL Cumulative Policy Expenses Guaranteed to Age 105 $25, 809 in Year 20 25, 747 121 105 Cash Value $105, 800 in year 20 Male, Age 45, $500, 000 Face Amount, Preferred Non-Tobacco. Annual premium of $4, 435. Information is for illustrative purposes only. Data in this comparison is based on information available and believed to be accurate as of August 2018, and is subject to change. Carrier’s actual illustration software and marketing material prevail. For a current Protective Life ICUL product illustration, please use our ELI software. . Annual premium based on Protective Life’s product with lapse protection to age 105, 5% illustration rate, S&P 500 ® Index Annual Point-to-Point interest rate credit. . For Financial Professional Use Only. Not For Use With Consumers. 31 For Financial Professional Use Only.
Extend. Care Rider The Highlights Monthly benefit helps ease the financial burden of a chronic illness Benefit payments can be used toward both medical and non-medical costs Unused death benefit will remain available for clients’ loved ones For Financial Professional Use Only. Not For Use With Consumers. 32 For Financial Professional Use Only.
What’s New Benefit Trigger § § One year expectation of disability ‒ Inability to perform 2 of 6 Activities of Daily Living ‒ Severe cognitive impairment Condition does not need to be permanent For Financial Professional Use Only. Not For Use With Consumers. 33 For Financial Professional Use Only.
What’s New Waiver of Charges § No policy expenses while on claim § No premiums while on claim § Charges resume if recovery occurs prior to 25 consecutive months of chronic illness For Financial Professional Use Only. Not For Use With Consumers. 34 For Financial Professional Use Only.
What’s New Permanent Waiver § With 25 consecutive months of chronic illness § Premiums and policy expenses permanently waived § Remaining death benefit will stay in force for the rest of the client’s life* § Must be recertified every 12 months to continue benefit payments * Subject to lapse caused by withdrawals or loans For Financial Professional Use Only. Not For Use With Consumers. 35 For Financial Professional Use Only.
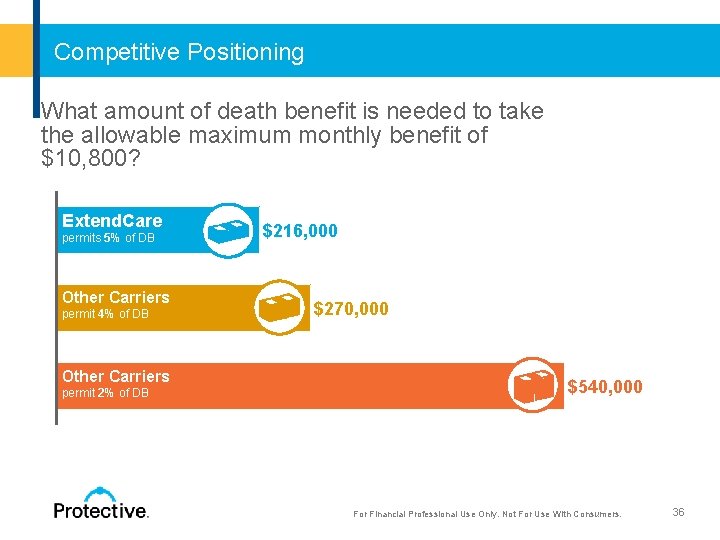
Competitive Positioning What amount of death benefit is needed to take the allowable maximum monthly benefit of $10, 800? Category 3 Category 2 Category 1 Extend. Care permits 5% of DB Other Carriers permit 4% of DB Other Carriers permit 2% of DB $216, 000 $270, 000 $540, 000 For Financial Professional Use Only. Not For Use With Consumers. 36 For Financial Professional Use Only.
www. Sell. What. Matters. com For Financial Professional Use Only. Not For Use With Consumers. 37 37 For Financial Professional Use Only.
Thank you For Financial Professional Use Only. Not For Use With Consumers. 38 For Financial Professional Use Only.
Important information Protective Custom Choice UL (UL-22), a universal life insurance policy, and Protective Classic Choice Term (ICC 16 -TL 21/TL-21), a level death benefit term insurance policy, to age 90 are both issued by Protective Life Insurance Company, Birmingham, AL. Policy form numbers, product features and availability may vary by state. Consult policies for benefits, riders, limitations and exclusions. Subject to underwriting. Up to a two-year contestable and suicide period. Benefits adjusted for misstatements of age of sex. In Montana, unisex rates apply. Premiums increase annually after the initial guaranteed premium period. All payments and guarantees are subject to the claims-paying ability of Protective Life Insurance Company. Income Provider Option (UL-E 35) is an endorsement available only at issue on certain UL products issued by Protective Life Insurance Company. Actual terms and conditions contained in the product policy and the endorsement govern benefits provided. A portion of periodic payments may be reported as taxable income to the beneficiary. Purchasers should consult their attorney or tax advisor regarding their individual situations. Please see the endorsement for more detailed information. May not be available in all states or on all currently-marketed UL products. State variations may apply. Protective is a registered trademark of Protective Life Insurance Company; all product names are trademarks of Protective Life Insurance Company. For Financial Professional Use Only. Not For Use With Consumers. 39 For Financial Professional Use Only.
- Slides: 38