
Profitability Analysis An Extended Look Dr Nancy Mangold
Profitability Analysis An Extended Look Dr. Nancy Mangold California State University, East Bay 1
Interpreting ROAs • What factors explain the consistly high or consistently low ROAs of some industries compared to the average of all industries • What factors explain the fact that – certain industries have high profit margins and low assets turnovers while – other industries experience low profit margins and high assets turnovers 2
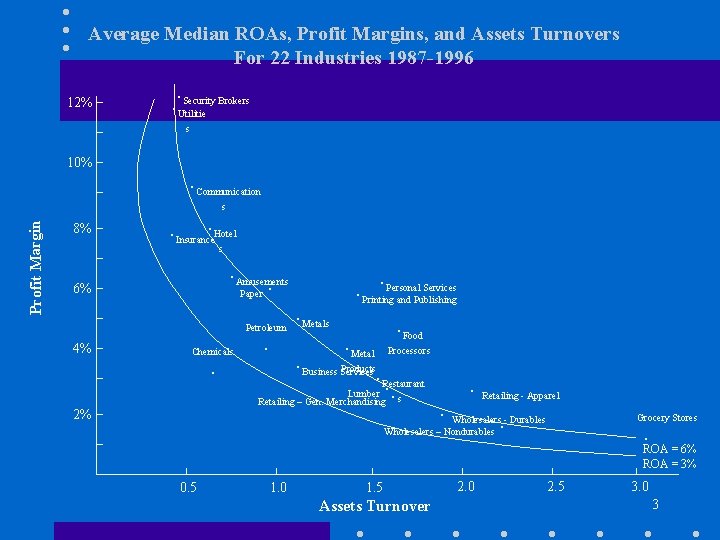
Average Median ROAs, Profit Margins, and Assets Turnovers For 22 Industries 1987 -1996 12% ·Security Brokers ·Utilitie s 10% ·Communication Profit Margin s 8% ·Insurance·Hotel s ·Amusements Paper · 6% Petroleum 4% Chemicals · 2% ·Metals ·Personal Services ·Printing and Publishing ·Food ·Metal Processors Products ·Business Services ·Restaurant Lumber · Retailing – Gen. Merchandising · s · · Retailing - Apparel · Wholesalers - Durables Wholesalers – Nondurables · Grocery Stores ·ROA = 6% ROA = 3% 0. 5 1. 0 1. 5 Assets Turnover 2. 0 2. 5 3. 0 3
Operating Leverage • Firms operate with different mixtures of fixed and variable costs in their cost structures 4
Operating Leverage • Firms with high proportions of fixed costs • High operating leverage firms • Capital intensive industries – Utilities – Communications – Hotels – Petroleum – Chemical 5
Operating Leverage • Firms with high proportions of variable costs • Low operating leverage firms] • Less capital intensive industries – Retailers – Wholesalers 6
Operating Leverage • Firms with high proportions of fixed costs • Significant increase in NI as sales increase – Fixed costs spread over a larger number of units sold – average unit cost decreased • Sharp decreases in NI when sales decrease 7
Operating Leverage • High level of operating leverage • Greater risk in their operations • Should earn higher rates of return 8
Operating Leverage • Unfortunately firms do not publicly disclose information about their fixed and variable cost structures • One approach is to study the various cost items of a firm and attempt to identify the items that are likely to behave as fixed costs 9
Committed Fixed Costs • Fixed costs committed regardless of actual level of activity during a period – Depreciation – Amortization – Rent – Lease payments 10
Discretionary Fixed Costs • Firms can alter the amount of some other costs in the short run in response to operating conditions – R & D expenses – Maintenance – Advertising – Central corporate staff expenses • Classify as FC or VC depending on behavior in a particular firm 11
Cost Structure • • • Exhibit 8. 3 Kelley Services (. 8%, 99. 2%) Coke (3. 2%, 96. 8%) USX (US Steel) (4. 6%, 95. 4%) Consolidated Edison (18. 3%, 81. 7%) 12
Cyclicality of Sales • The sales of certain goods and services are sensitive to conditions in the economy – Construction services – Industrial equipment – Computers – Automobiles – Other durable goods 13
Cyclicality of Sales • When the economy is in an upswing – Healthy GNP growth – low unemployment – Low interest rate • Customers purchase high-priced items • Sales of these firms grow 14
Cyclicality of Sales • When the economy enters a recession • Customers curtail their purchases • The sales of these firms drop significantly 15
Noncyclical Sales • Industries sell products that most consumers consider necessities – Grocery stores – Food processors – non-fashion clothing producers – electric utilities • Products have lower per unit costs 16
Cyclicality of Sales • Firms with cyclical sales patterns incur more risk • Firms with non-cyclical sales patterns incur less risk 17
Cyclicality of Sales • A firm can reduce its risk by • Incorporate high proportion of variable cost in its cost structure – Pay employee hourly wage vs fixed salary – Rent building and equipment under short-term cancelable leases instead of purchasing facilities • Airlines, railroads 18
Cyclicality of Sales • A noncyclical sales pattern can compensate for high operating leverage and neutralize risk • Electric utilities • Telecommunication firms 19
Product Life Cycle • Product life cycle – Introduction – Growth – Maturity – Decline 20
Introduction & Growth • Product development – High R & D spending • Capacity enlargement – Capacity spending • high uncertainty regarding the market viability of a firm’s products 21
Maturity Phase • Firms have gained market acceptance – Reduce capital expenditures on operating capacity • More intense competition-reducing costs through – improved capacity utilization (economies of scale) – more efficient production 22
Decline Phase • Firms exit the industry as sales decline and profit diminish 23
Product Life Cycle & ROA • Introduction & early growth phase • Negative ROAs – high expenditures on product development, marketing, capital expenditure – Low sales – operating losses • Higher risk 24
Product Life Cycle & ROA • High growth phase • Positive ROAs – Positive operating income • ROA does not grow as rapidly as sales – Product development – marketing – depreciation – heavy capital expenditures to build capacity for 25 expected higher future sales
Product Life Cycle & ROA • Maturity phase • ROA increases significantly – Economies of scale – learning curve benefits – curtailment of capital expenditures • Lower risk 26
Product Life Cycle & ROA • Declining phase • ROA deteriorates – operating income decreases – may remain positive 27
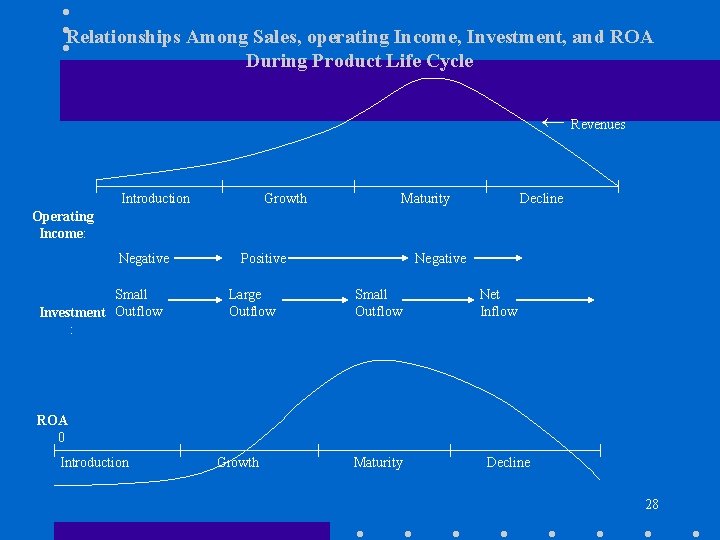
Relationships Among Sales, operating Income, Investment, and ROA During Product Life Cycle ← Revenues Introduction Growth Maturity Decline Operating Income: Negative Small Investment Outflow : Positive Large Outflow Negative Small Outflow Net Inflow ROA 0 Introduction Growth Maturity Decline 28
Product Life Cycle Industry Level • Computer industry in all phases – Overall in high growth phase • Soft drinks and food processing industries – maturity phase – constantly introduces new products • Steel industry – declining phase – modernize production to stave off decline 29
Consistent ROAs in Exhibit 8. 1 • Amusements industry- high ROA – High operating leverage, growth, dominant market positions • Apparel Retailers - low ROA – risk of fashion obsolescence • Insurance companies - low ROA – low operating leverage, low sales cyclicality – less risk of life cycle 30
Inconsistent ROAs in Exhibit 8. 1 • Petroleum, Chemical and Hotel industries • Lower ROA – high operating leverage – risk of sales cyclicality • Due to excess capacity and obsolete plant assets 31
ROA and GAAP • Food processors • Major assets - Brand names • GAAP – expensed advertising and development costs – Assets understated – ROA overstated 32
ROA and GAAP • Publishing industry – Value of copyrights not recognized • Service firms – Value of employees not an asset • Reverse the immediate expensing of advertising, R & D, recognize it as assets 33
Differences in Profit Margin and Assets Turnover • Microeconomic theory • Firms and industries characterized by capacity constraint (heavy fixed capacity costs, lengthy periods to add new capacity) – Upper limit on the size of assets turnover – Must generate high profit margin to attract sufficient capital (Area A in Exhibit 8. 5) 34
Differences in Profit Margin and Assets Turnover • Firms achieve high profit margin by • entry barrier – large required capital outlays – high risks – regulations • Explain communications, utilities, hotels, and amusements industries in Exhibit 8. 1 35
Differences in Profit Margin and Assets Turnover • Lack of entry barrier • Excess capacity • Explains low ROA for chemical and petroleum industries 36
Differences in Profit Margin and Assets Turnover • Firms – Products are commodity-like in nature – Few entry barriers – Intense competition – Operate under competitive constraint • Upper limit on achievable profit margin • Strive for high asset turnovers to attract sufficient capital (Area C in Exhibit 8. 5) 37
Differences in Profit Margin and Assets Turnover • Firms achieve higher asset turnovers by – minimize fixed overhead costs – purchase in sufficient quantities to realize discounts – integrate vertically or horizontally to obtain cost savings • Explains retailers and wholesalers 38
Differences in Profit Margin and Assets Turnover • A area in Exhibit 8. 5 – Give up large profit margin to obtain asset turnover – Emphasize actions to increase profit margin • C area in Exhibit 8. 5 – Give up large assets turnover to achieve a higher profit margin – Emphasize actions to increase assets turnover 39
Differences in Profit Margin and Assets Turnover • Business Strategy • Product differentiation – Product capabilities, quality, service, channels of distribution • Low cost leadership – economies of scale, production efficiencies, outsourcing 40
Differences in Profit Margin and Assets Turnover • Specialty retailers • Differentiation strategy • Higher profit margin than general merchandise stores and grocery stores 41
Differences in Profit Margin and Assets Turnover • External factors – Degree of competition – extent of regulation – entry barriers • Internal strategic choices – Product differentiation – Low-cost leadership 42
43
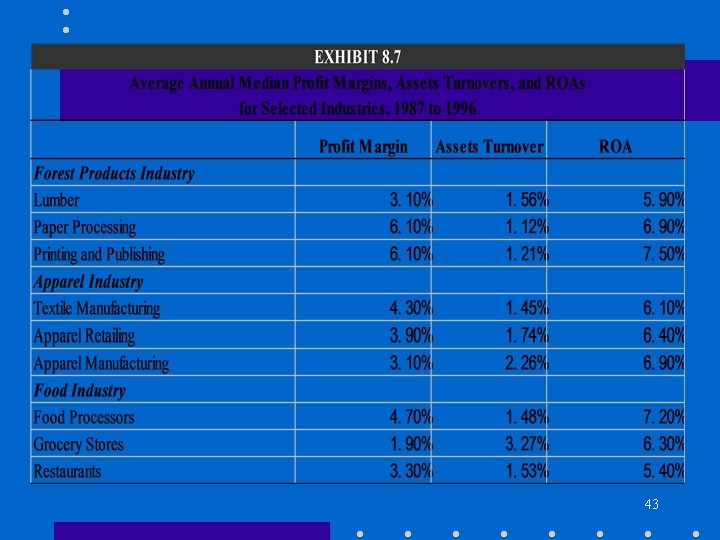
ROA and Value Chain Analysis • Forest Products Industry • Lumber – low profit margin (commodity product) – higher asset turnover • Forest assets reported at acquisition costs • Undervaluation of fixed assets • overstates assets turnover 44
ROA and Value Chain Analysis • Forest Products Industry • Paper processing – higher profit margin than lumber – Capital intensive paper processing facilities – lower assets turnover 45
ROA and Value Chain Analysis • Forest Products Industry • Printing and Publishing – Higher profit margin • Non-differentiated and differentiated products – Capital intensive printing facilities – lower assets turnover – Highest ROA in industry 46
ROA and Value Chain Analysis • Apparel industry • Textile manufacturing – higher profit margin • undifferentiated products - fabrics – Lower asset turnover • capital intensive • Risk of diseconomies of scale in capitalintensive manufacturing facilities 47
ROA and Value Chain Analysis • Apparel industry • Apparel manufacturing • Higher profit margin – outsource manufacturing to lower wage rate countries and – outsource to the brand names of apparel products • Risk of exchange rate changes, political risk 48 and fashion changes
ROA and Value Chain Analysis • Apparel Industry • Apparel Retailing • Lower profit margin – small value-added activity – mixture of branded apparel and discount apparel firms • Risk of fashion changes and swings in consumer spending 49
ROA and Value Chain Analysis • Food Industry • Food processors – Highest profit margins - brand-name products – Lower asset turnovers - capital intensive in food manufacturing 50
ROA and Value Chain Analysis • Food Industry • Grocery stores – Low profit margins - undifferentiated products – Higher asset turnover - less investment in buildings and space 51
ROA and Value Chain Analysis • Food Industry • Restaurants • Higher profit margin – brand name recognition – intense competition • Lower asset turnover – investment in land restaurant buildings 52
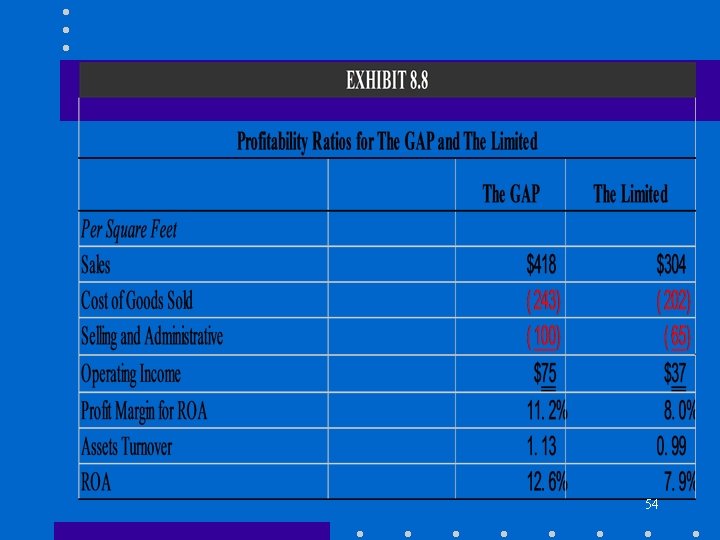
Supplementing ROA • Analyzing Retailers • Some own and some lease their stores • Express sales, operating expenses, and operating income on a per square foot basis • Exhibit 8. 8 53
54
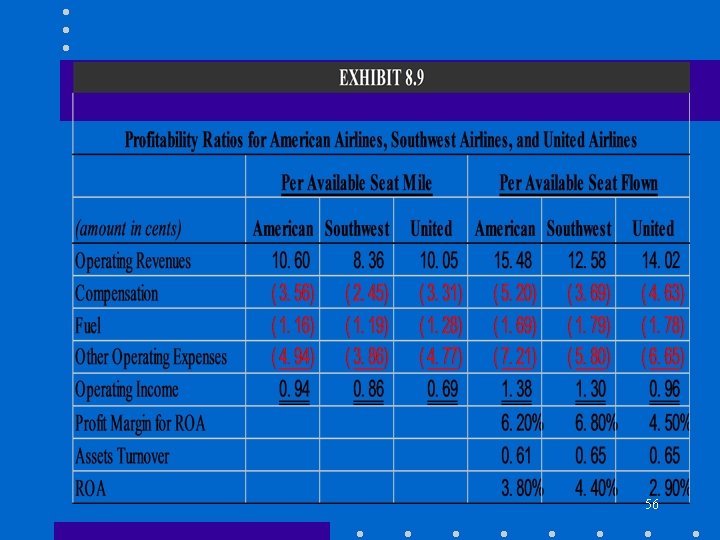
Supplementing ROA • Analyzing airlines • Compute revenues and expenses – per available seat mile and – per seat miles flown 55
56
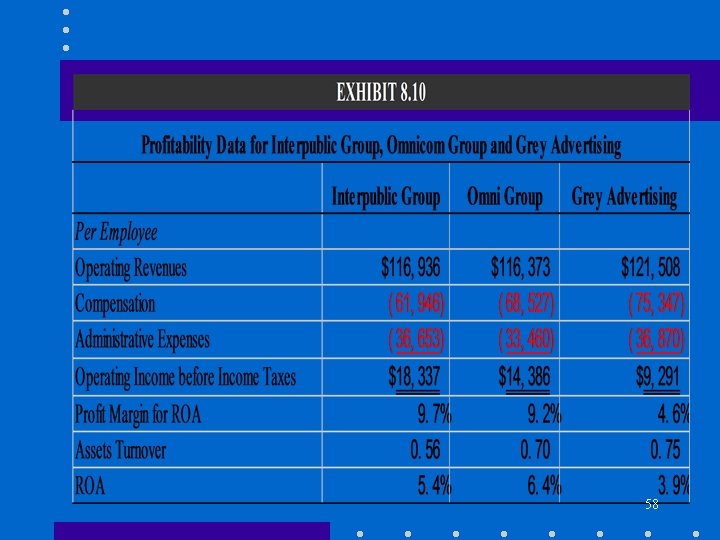
Supplementing ROA • Analyzing Advertising Firm • Analyze income data on per employee basis 57
58
Supplementing ROA • Analyzing Technology-Based Firms • Two important resources not reported as assets – People – Technology (R & D expensed) • Assets and net income understated 59
- Slides: 59