
Prof Morteza Anvari Cost Analysis Requirement MS I
- Slides: 69
Prof. Morteza Anvari
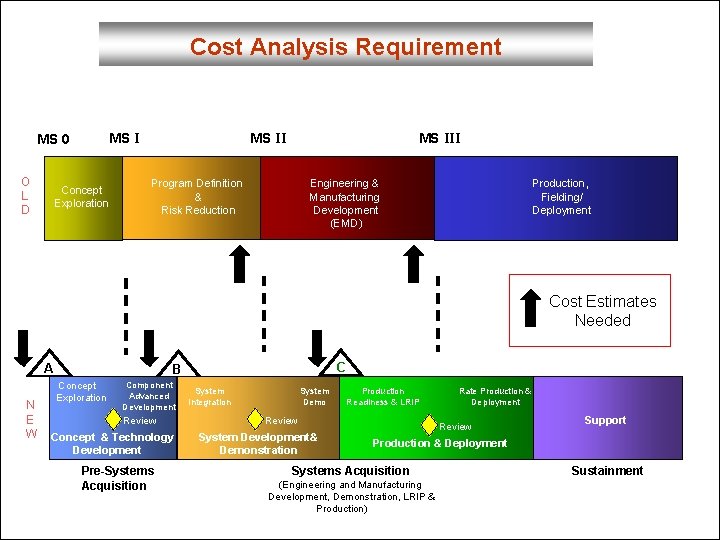
Cost Analysis Requirement MS I MS 0 O L D Concept Exploration MS III Program Definition & Risk Reduction Engineering & Manufacturing Development (EMD) Production, Fielding/ Deployment Cost Estimates Needed A N E W C B Concept Exploration Component Advanced Development Review Concept & Technology Development Pre-Systems Acquisition System Integration System Demo Production Readiness & LRIP Review System Development& Demonstration Rate Production & Deployment Review Support Production & Deployment Systems Acquisition (Engineering and Manufacturing Development, Demonstration, LRIP & Production) Sustainment
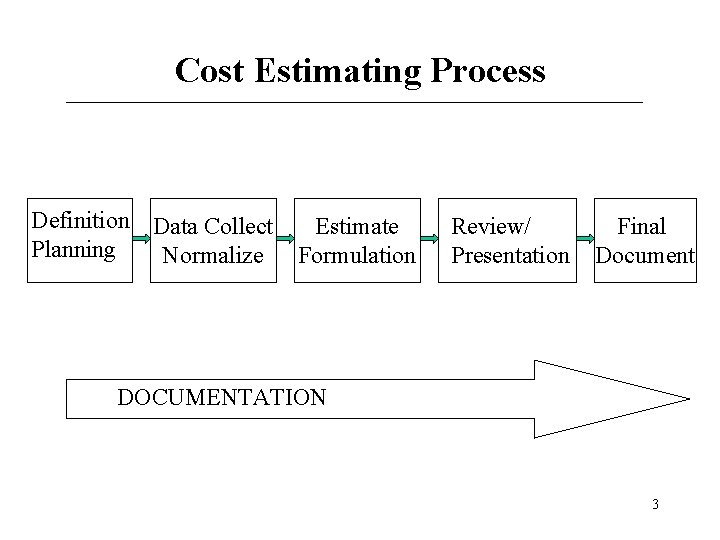
Cost Estimating Process Definition Data Collect Planning Normalize Estimate Formulation Review/ Presentation Final Document DOCUMENTATION 3
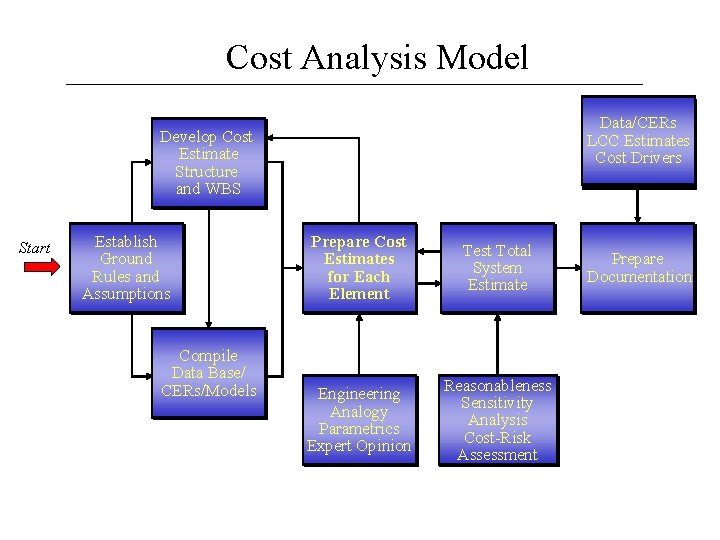
Cost Analysis Model Data/CERs LCC Estimates Cost Drivers Develop Cost Estimate Structure and WBS Start Establish Ground Rules and Assumptions Compile Data Base/ CERs/Models Prepare Cost Estimates for Each Element Test Total System Estimate Engineering Analogy Parametrics Expert Opinion Reasonableness Sensitivity Analysis Cost-Risk Assessment Prepare Documentation
Situation • You have just been tasked to develop a cost estimate, that is, a professional opinion about the cost of an item, a service or a thing. • Let’s discuss a process for organizing and developing this estimate. 5
Definition and Planning • Influences the success of the estimate • Understanding the requirements and how you approach the process will establish the guidelines and procedures for the estimate. • Ask lots of questions…They help you understand the requirement. 6
Questions • Why is this cost estimate needed? • What decisions are pending on the results of this estimate? • Will the estimate be briefed and to whom? • Will the results be incorporated into some document? • What does the recipient expect to have included or excluded? • What excursions or variations from the baseline are anticipated? 7
Questions Continued • What are the program and funding constraints especially if the program is a Joint Program? • What are the time constraints for this estimate? • What is the acquisition phase of the program? • Is the program definition mature? • Does technology exist today to design, develop, test and manufacture the system? • What is the interrelationship with other systems? • Are there previous contracts? How many? What type? • How have the contractors performed to date? 8
Definition and Planning Know Purpose of the Estimate • Main purposes of estimates: – Budget Formulation – Comparative Studies – Source Selection 9
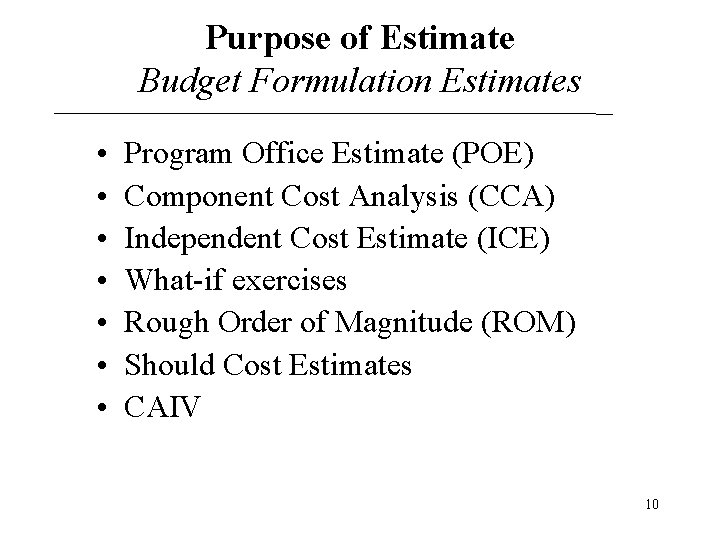
Purpose of Estimate Budget Formulation Estimates • • Program Office Estimate (POE) Component Cost Analysis (CCA) Independent Cost Estimate (ICE) What-if exercises Rough Order of Magnitude (ROM) Should Cost Estimates CAIV 10
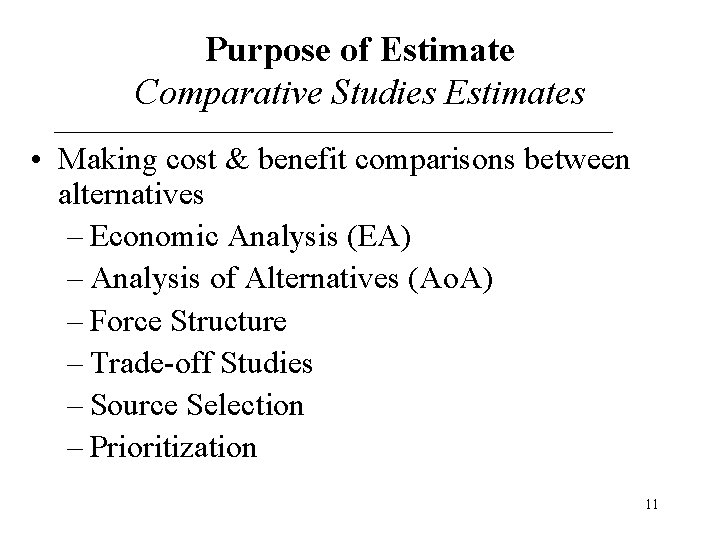
Purpose of Estimate Comparative Studies Estimates • Making cost & benefit comparisons between alternatives – Economic Analysis (EA) – Analysis of Alternatives (Ao. A) – Force Structure – Trade-off Studies – Source Selection – Prioritization 11
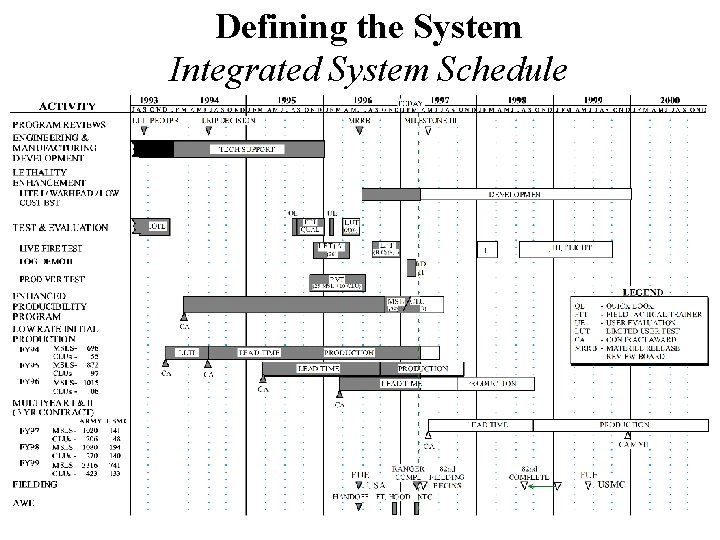
Definition and Planning Defining the System • Adequate description of the technical and program characteristics of the system • What are the physical and performance characteristics? • What are the development, production, and deployment schedules? • How many systems are to be produced? • How will the systems be supported: contract, inhouse, two or three levels of maintenance? 12
Defining the System Integrated System Schedule
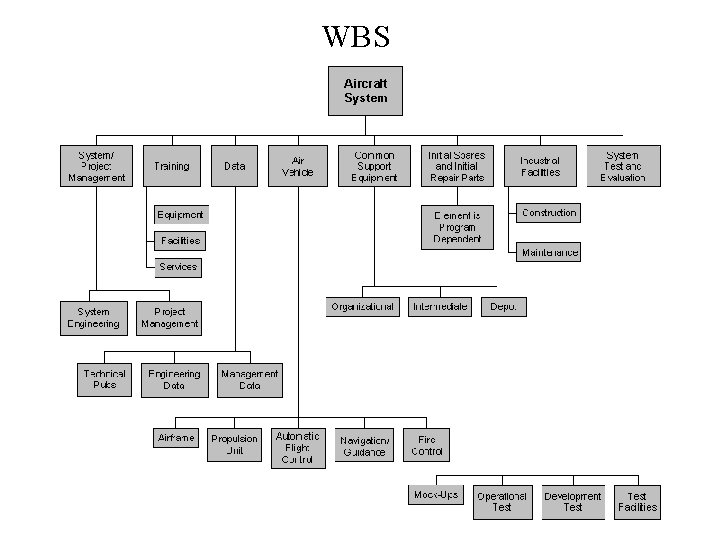
Defining the System Work Breakdown Structure (WBS) • WBS definition – product-oriented breakdown of hardware, software, services, data and facilities that define the system. • WBS breaks a total job down into manageable pieces & portrays the way work is to be done. • WBS displays a company’s reporting structure. • Program managers may cite MIL-HDBK-881 “for guidance only” in contract solicitations. 14
WBS
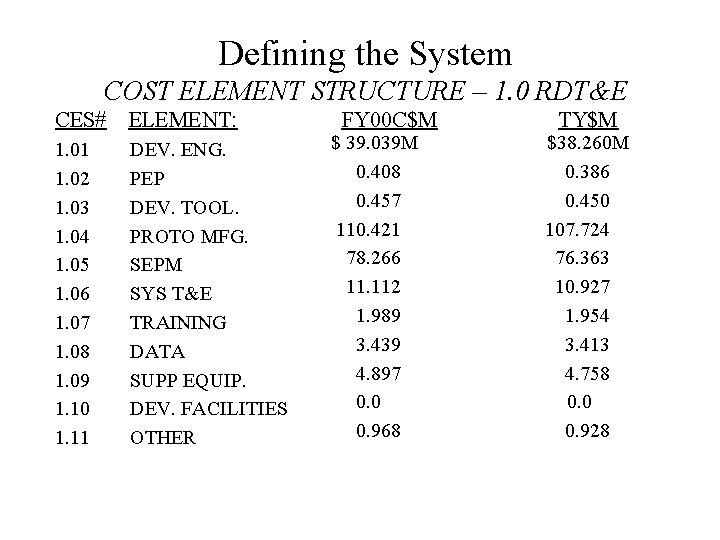
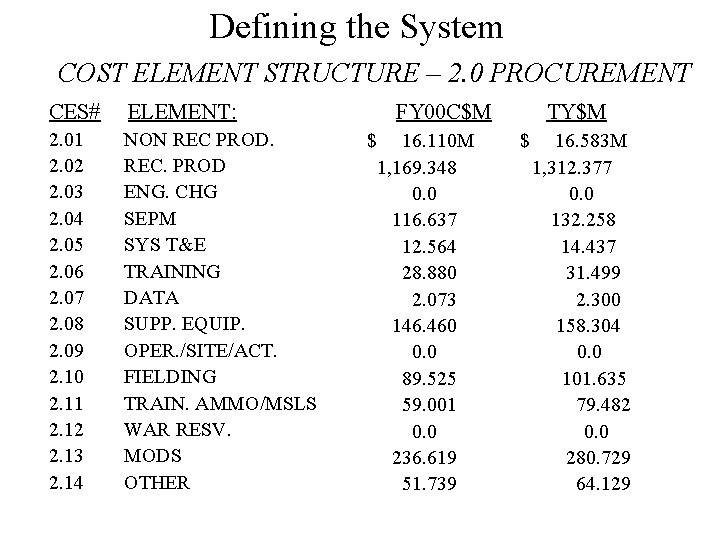
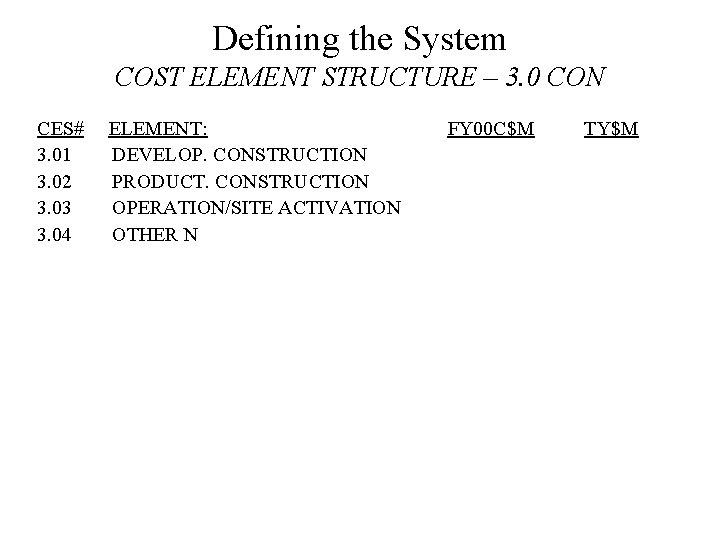
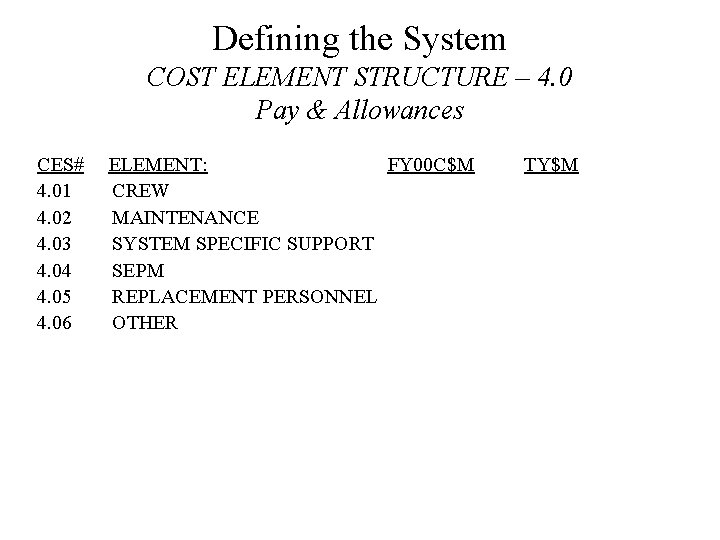
Defining the System Cost Element Structure (CES) 1. 0 Research Development Test & Evaluation (RDT&E) 2. 0 Production 3. 0 Construction (CON) 4. 0 Pay and Allowances 5. 0 Operating and Maintenance Army (O&M) 16
Defining the System COST ELEMENT STRUCTURE – 1. 0 RDT&E CES# ELEMENT: FY 00 C$M TY$M $ 39. 039 M 1. 01 DEV. ENG. 0. 408 1. 02 PEP 0. 457 1. 03 DEV. TOOL. 110. 421 1. 04 PROTO MFG. 78. 266 1. 05 SEPM 11. 112 1. 06 SYS T&E 1. 989 1. 07 TRAINING 3. 439 1. 08 DATA 4. 897 1. 09 SUPP EQUIP. 0. 0 1. 10 DEV. FACILITIES 0. 968 1. 11 OTHER $38. 260 M 0. 386 0. 450 107. 724 76. 363 10. 927 1. 954 3. 413 4. 758 0. 0 0. 928
Defining the System COST ELEMENT STRUCTURE – 2. 0 PROCUREMENT CES# ELEMENT: FY 00 C$M TY$M 2. 01 NON REC PROD. $ 16. 110 M $ 16. 583 M 2. 02 REC. PROD 1, 169. 348 1, 312. 377 2. 03 ENG. CHG 0. 0 2. 04 SEPM 116. 637 132. 258 2. 05 SYS T&E 12. 564 14. 437 2. 06 TRAINING 28. 880 31. 499 2. 07 DATA 2. 073 2. 300 2. 08 SUPP. EQUIP. 146. 460 158. 304 2. 09 OPER. /SITE/ACT. 0. 0 2. 10 FIELDING 89. 525 101. 635 2. 11 TRAIN. AMMO/MSLS 59. 001 79. 482 2. 12 WAR RESV. 0. 0 0. 0 2. 13 MODS 236. 619 280. 729 2. 14 OTHER 51. 739 64. 129
Defining the System COST ELEMENT STRUCTURE – 3. 0 CON CES# ELEMENT: FY 00 C$M TY$M 3. 01 DEVELOP. CONSTRUCTION 3. 02 PRODUCT. CONSTRUCTION 3. 03 OPERATION/SITE ACTIVATION 3. 04 OTHER N
Defining the System COST ELEMENT STRUCTURE – 4. 0 Pay & Allowances CES# ELEMENT: FY 00 C$M TY$M 4. 01 CREW 4. 02 MAINTENANCE 4. 03 SYSTEM SPECIFIC SUPPORT 4. 04 SEPM 4. 05 REPLACEMENT PERSONNEL 4. 06 OTHER
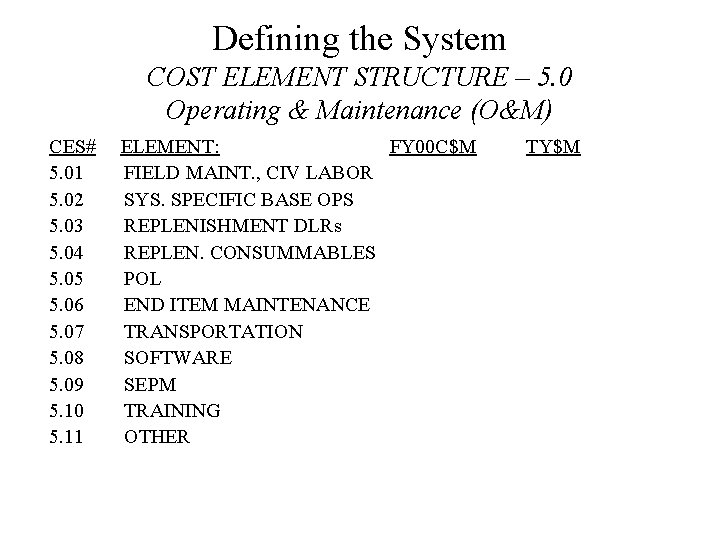
Defining the System COST ELEMENT STRUCTURE – 5. 0 Operating & Maintenance (O&M) CES# ELEMENT: FY 00 C$M TY$M 5. 01 FIELD MAINT. , CIV LABOR 5. 02 SYS. SPECIFIC BASE OPS 5. 03 REPLENISHMENT DLRs 5. 04 REPLEN. CONSUMMABLES 5. 05 POL 5. 06 END ITEM MAINTENANCE 5. 07 TRANSPORTATION 5. 08 SOFTWARE 5. 09 SEPM 5. 10 TRAINING 5. 11 OTHER
Defining the System Cost Analysis Requirements Description (CARD) • Source of a system’s description • Describes important features • Is provided to other groups preparing cost estimates • Helps ensure all groups are costing out the same “program. ” • Prepared by program office; approved by Do. D Component Program Executive Officer 22
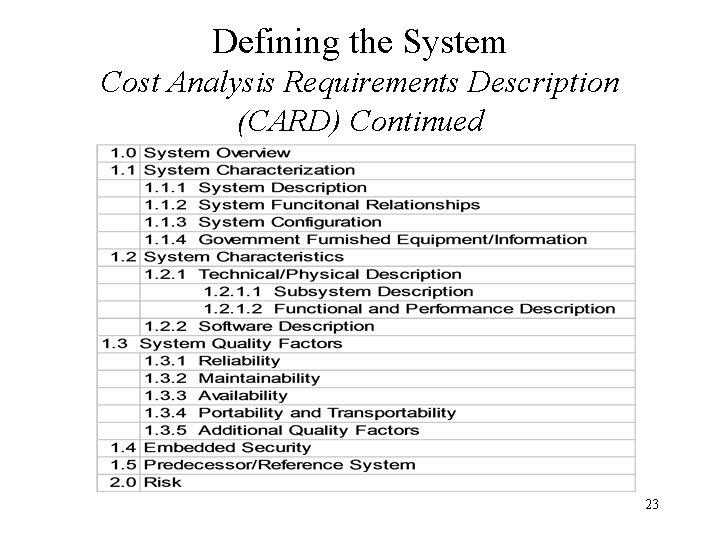
Defining the System Cost Analysis Requirements Description (CARD) Continued 23
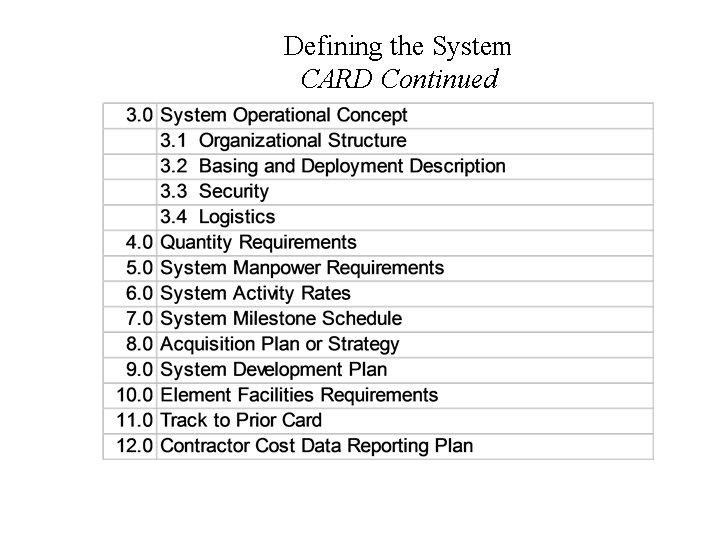
Defining the System CARD Continued
Definition and Planning Ground Rules & Assumptions • State the conditions which must take place in order for the estimate to be valid • Ground rules and assumptions must be documented since changes in these areas provide an audit trail for changes in the cost estimate. 25
Data Collection and Analysis • Collection and analysis represent a significant amount of the overall estimating task in terms of time. The analysis will include decisions on what programs to include in the data set to whether to truncate lot data on a program for which you are calculating a learning curve. • Document data in your analysis, and any assumptions you make 26
Data Collection and Analysis • The direction we take in collecting historical data will be determined by our choice of estimating methodologies. • This step may also dictate a change in estimating approach due to the availability or non-availability of certain data. • Data collection is not limited to cost data. We must also collect technical and program data if we want the total picture of the historical systems. This will help us ensure the comparability of the systems that we are collecting data on with the system we are estimating. 27
Data Collection and Analysis Most Difficult Task in Cost Estimating • Data Sources – Data Types: Cost/Resource, Technical, Program – Categories: Primary, Secondary • Data Problems – Wrong Format – Matching up – Definition – Temporal Factors - comparability • Normalization • Data Location 28
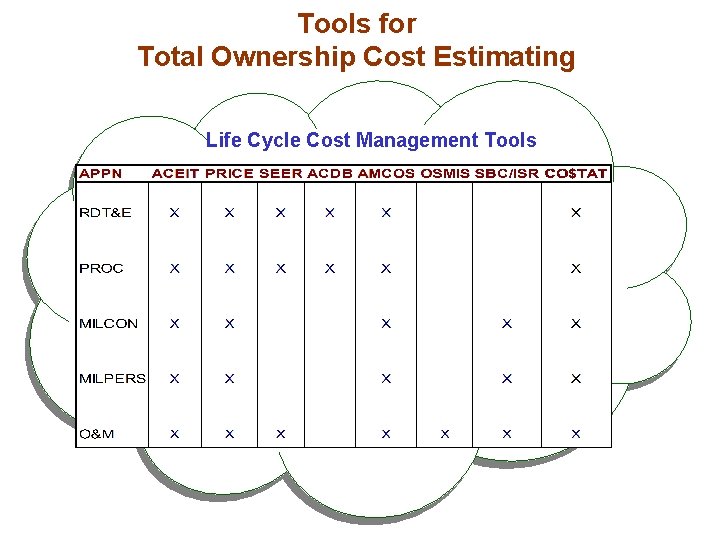
Tools for Total Ownership Cost Estimating Life Cycle Cost Management Tools
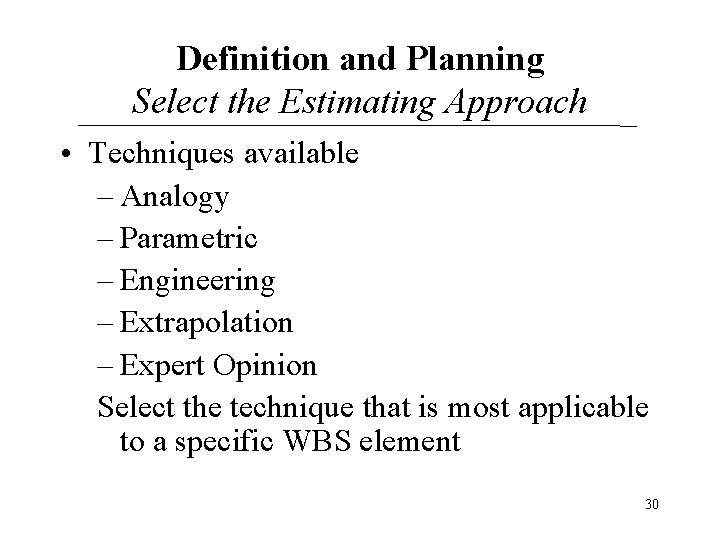
Definition and Planning Select the Estimating Approach • Techniques available – Analogy – Parametric – Engineering – Extrapolation – Expert Opinion Select the technique that is most applicable to a specific WBS element 30
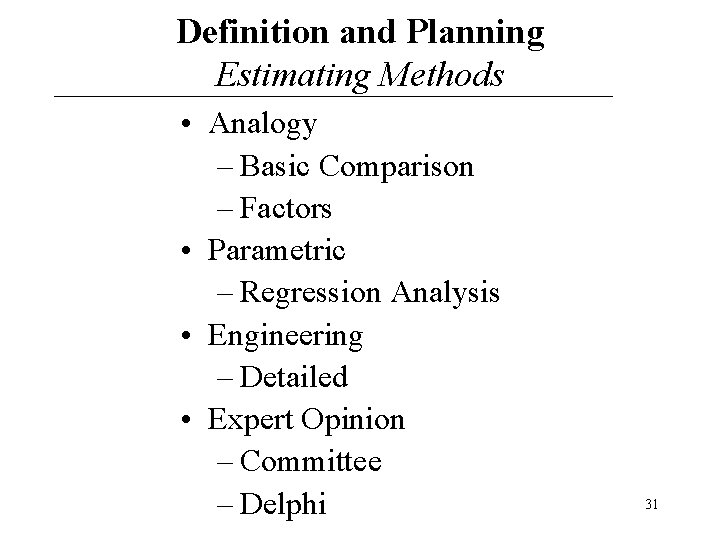
Definition and Planning Estimating Methods • Analogy – Basic Comparison – Factors • Parametric – Regression Analysis • Engineering – Detailed • Expert Opinion – Committee – Delphi 31
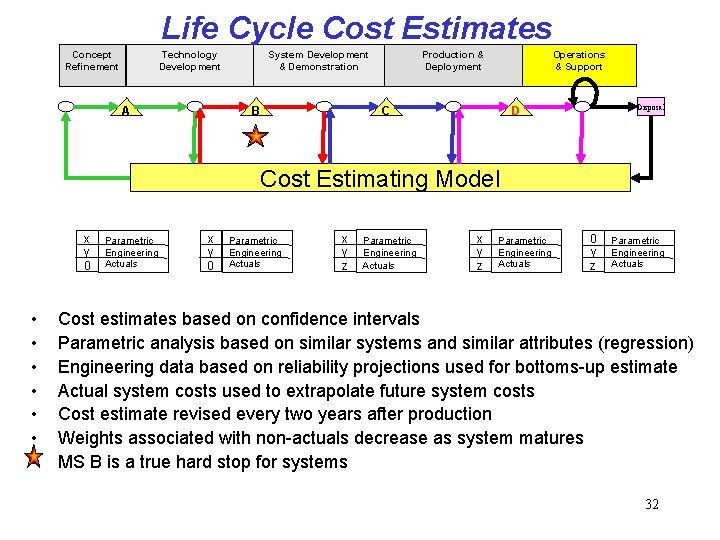
Life Cycle Cost Estimates Concept Refinement Technology Development A System Development & Demonstration B Production & Deployment Operations & Support C Disposal D Cost Estimating Model x y 0 • • Parametric Engineering Actuals x y 0 Parametric Engineering Actuals x y z Parametric Engineering Actuals 0 y z Parametric Engineering Actuals Cost estimates based on confidence intervals Parametric analysis based on similar systems and similar attributes (regression) Engineering data based on reliability projections used for bottoms-up estimate Actual system costs used to extrapolate future system costs Cost estimate revised every two years after production Weights associated with non-actuals decrease as system matures MS B is a true hard stop for systems 32
Cost Estimating Methods Analogy Method • Based on direct comparison with historical information of similar existing activities, systems, or components. • Compares new system with one or more existing similar systems where there is accurate cost and technical data. • Analyst must show validity of comparison. 33
Cost Estimating Methods Analogy Method • Based on known costs of a similar program • Adjustments for complexity, technical, physical • Strengths – Based on representative experience – Less time consuming than others – Can be used as a check on other techniques • Weaknesses – Small sample size – Heavy reliance on judgment – Sometimes difficult to identify analogy and associated costs 34
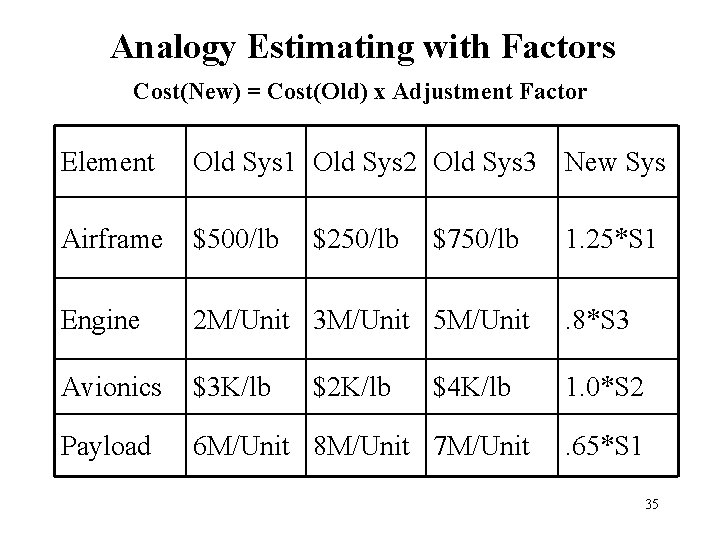
Analogy Estimating with Factors Cost(New) = Cost(Old) x Adjustment Factor Element Old Sys 1 Old Sys 2 Old Sys 3 New Sys Airframe $500/lb 1. 25*S 1 Engine 2 M/Unit 3 M/Unit 5 M/Unit . 8*S 3 Avionics $3 K/lb 1. 0*S 2 Payload 6 M/Unit 8 M/Unit 7 M/Unit $250/lb $2 K/lb $750/lb $4 K/lb . 65*S 1 35
Cost Estimating Methods Parametric Method • Known as Statistical Method or Top Down Method • Relates cost to physical attributes or performance characteristics • Uses database of elements from similar systems • Uses multiple systems • Most beneficial in earlier stages of the system or project life cycle 36
Cost Estimating Methods Parametric Method • Statistical relationships between cost and physical or performance parameters of past systems. • Strengths – Captures major portion of cost – Quick what if type estimates • Weaknesses – Less detailed – Getting accurate data 37
Cost Estimating Methods Parametric Method (Extrapolation) • Use historical values to establish a trend for the future. • Example problem: Given the actual productivity and labor rates in the given table. How much will it take to complete a 3 -year software development project of 10 K lines of code, if 50% is completed in the second year and 25% is completed in first and third years? 38
Cost Estimating Methods Engineering Method • Known as bottom up method • Requires extensive knowledge of system characteristics • Divide into segments; estimate costs for each segment • Combine segments plus integration cost • Uses a combination of cost estimating methods • Detailed knowledge of new technologies may not be available. 39
Cost Estimating Methods Engineering Method • Strengths – Detailed • Best when long stable production process • Weaknesses – Requires a lot of time – Cost – Cannot be used until system well defined 40
Cost Estimating Methods Expert Opinion Method • Subjective judgment of an experienced individual or group • Use if time does not permit a more thorough analysis • Document source(s) of opinion of experts • List attributes of the source(s) Example: Delphi Technique 41
Cost Estimating Methods Expert Opinion Method • Consulting with one or more experts who use their knowledge and experience to arrive at an estimate • Group techniques include – Consensus (Committee) – Delphi • Strengths and weaknesses 42
Expert Opinion Method Delphi Technique • • • Query expert opinion from group Seek information from each expert Summarize the results Send report to each expert Gather second opinion after each individual reviews report • Summarize results • Iterative process continues until the experts reach a consensus, or near‑consensus. 43
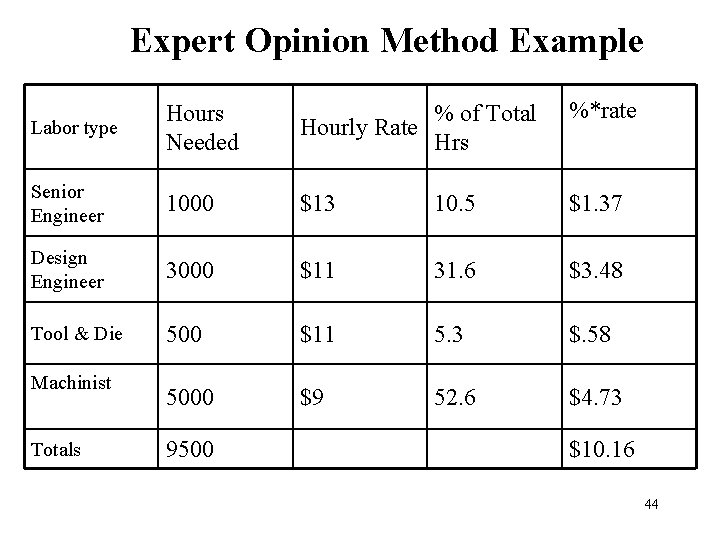
Expert Opinion Method Example Labor type Hours Needed % of Total Hourly Rate Hrs %*rate Senior Engineer 1000 $13 10. 5 $1. 37 Design Engineer 3000 $11 31. 6 $3. 48 Tool & Die 500 $11 5. 3 $. 58 5000 $9 52. 6 $4. 73 Machinist Totals 9500 $10. 16 44
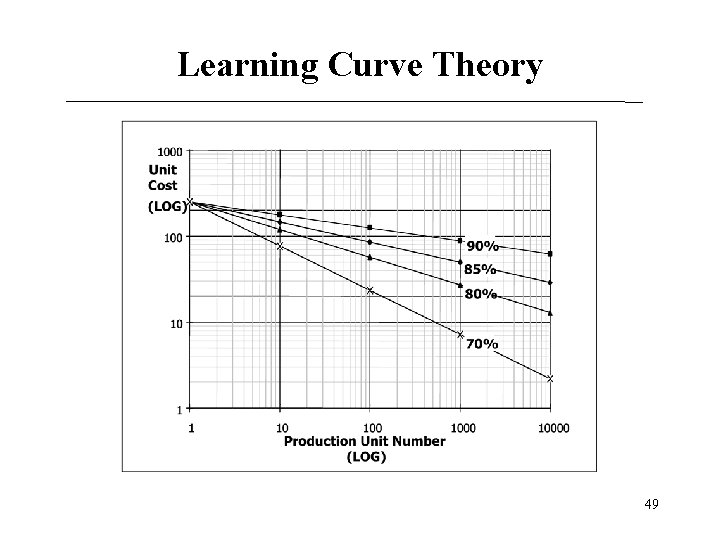
Learning Curve Theory As the quantity of a product produced doubles, the man-hours- per-unit expended to produce the product decreases at a fixed rate or constant percentage (usually 10% to 15%).
Learning Curve Theory Factors Contributing to Efficiency • Job familiarization by both production workers and supervisory personnel. • Changes in product design which do not materially affect the product, but result in increased ease and speed of production. • Changes in tooling, machinery, and equipment which simplify or speed up the production process. • Improved production planning and scheduling, and improvements in production techniques and operational methods. • Improvements in shop organization, engineering coordination and liaison. • Improvements in the handling and flow of materials, and in the materials and parts supply systems
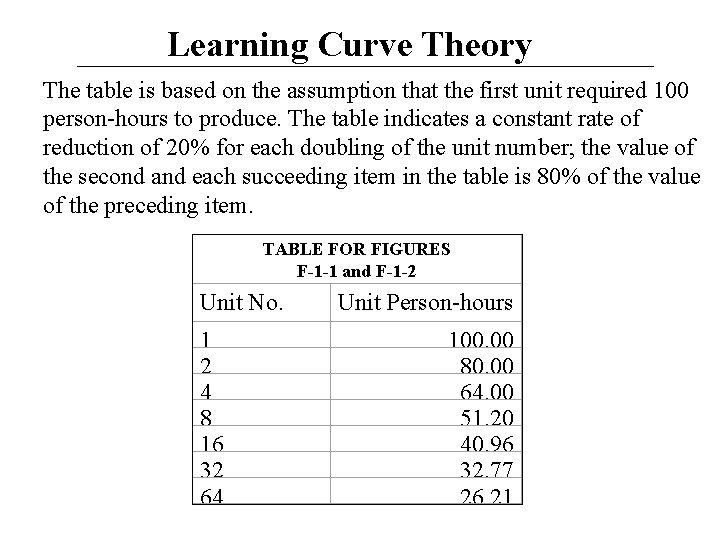
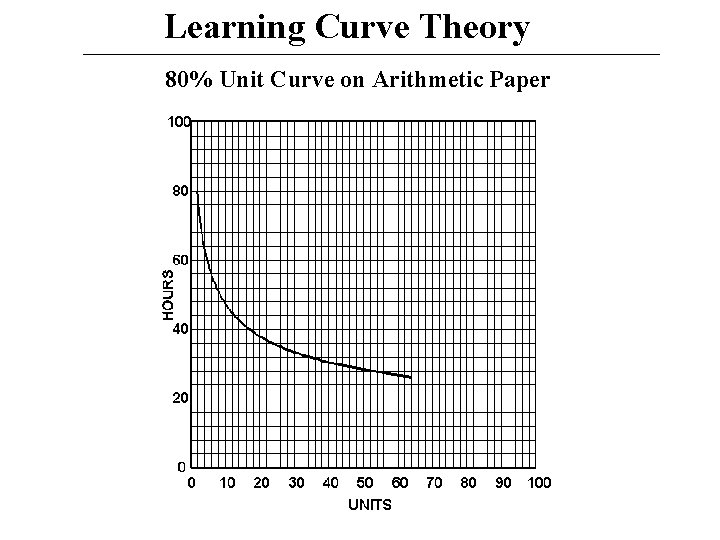
Learning Curve Theory The table is based on the assumption that the first unit required 100 person-hours to produce. The table indicates a constant rate of reduction of 20% for each doubling of the unit number; the value of the second and each succeeding item in the table is 80% of the value of the preceding item. TABLE FOR FIGURES F-1 -1 and F-1 -2 Unit No. 1 2 4 8 16 32 64 Unit Person-hours 100. 00 80. 00 64. 00 51. 20 40. 96 32. 77 26. 21
Learning Curve Theory 80% Unit Curve on Arithmetic Paper
Learning Curve Theory 49
Learning Curve Theory Uses – Evaluating contract production costs. – Assessing impact of production interruptions, product changes and production rate change. – Rate of improvement experienced by a particular contractor on a prior product may be indicative of rate of improvement expected on new product of similar size, complexity, and construction. – Improvement curve pattern experienced in the production of past item can be extended to calculate costs of future items. 50
Estimate Formulation • We have defined our tasks, planned the estimate, assigned cost responsibilities, and performed data collection and analysis. • Here we apply our estimating methodologies and tools: develop the factors, analogies, CERs, and learning curves. • We will aggregate the various cost elements into development, production, and O&S estimates, fiscally spread the costs, and apply inflation. 51
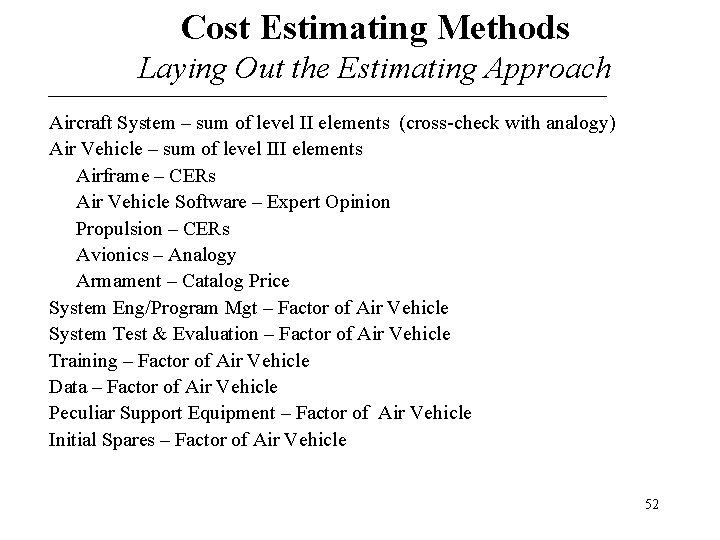
Cost Estimating Methods Laying Out the Estimating Approach Aircraft System – sum of level II elements (cross-check with analogy) Air Vehicle – sum of level III elements Airframe – CERs Air Vehicle Software – Expert Opinion Propulsion – CERs Avionics – Analogy Armament – Catalog Price System Eng/Program Mgt – Factor of Air Vehicle System Test & Evaluation – Factor of Air Vehicle Training – Factor of Air Vehicle Data – Factor of Air Vehicle Peculiar Support Equipment – Factor of Air Vehicle Initial Spares – Factor of Air Vehicle 52
Review and Presentation • We want to ensure that the estimate is reasonable, realistic, and complete. • Reasonableness addresses areas such as: using appropriate and acceptable methodologies; presenting methodologies systematically; the use of relevant data; and ensuring that assumptions are valid and clearly stated. 53
Review and Presentation (Continued) • The realism test checks to see if the assumptions and ground rules are consistent with the statement of work and if the costs are in line with historical data. • We evaluate completeness by determining whether the estimate includes all the work stated in the request for proposal and whether the costs are traceable and reconcilable. 54
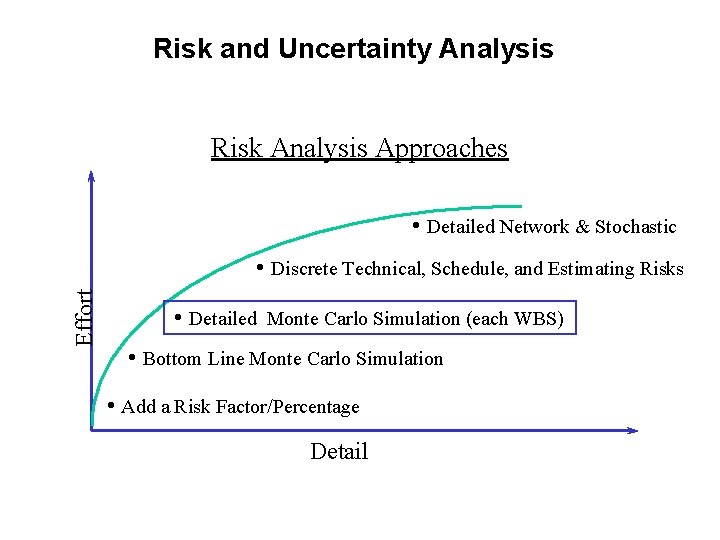
Risk and Uncertainty Analysis Risk Analysis Approaches • Detailed Network & Stochastic Effort • Discrete Technical, Schedule, and Estimating Risks • Detailed Monte Carlo Simulation (each WBS) • Bottom Line Monte Carlo Simulation • Add a Risk Factor/Percentage Detail
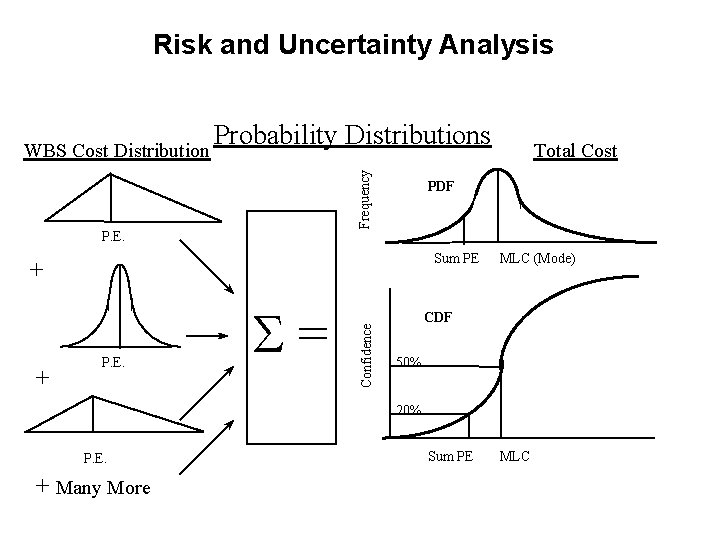
Risk and Uncertainty Analysis Frequency Probability Distributions WBS Cost Distribution P. E. PDF Sum PE + P. E. Confidence + S = Total Cost MLC (Mode) CDF 50% 20% P. E. + Many More Sum PE MLC
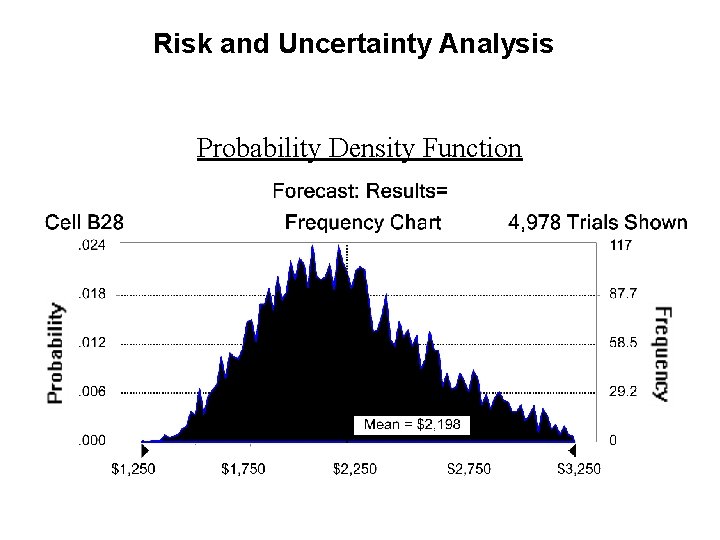
Risk and Uncertainty Analysis Probability Density Function
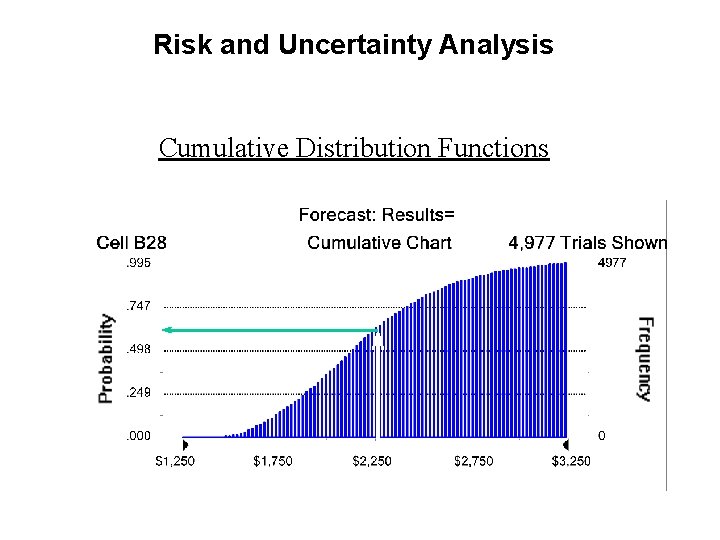
Risk and Uncertainty Analysis Cumulative Distribution Functions
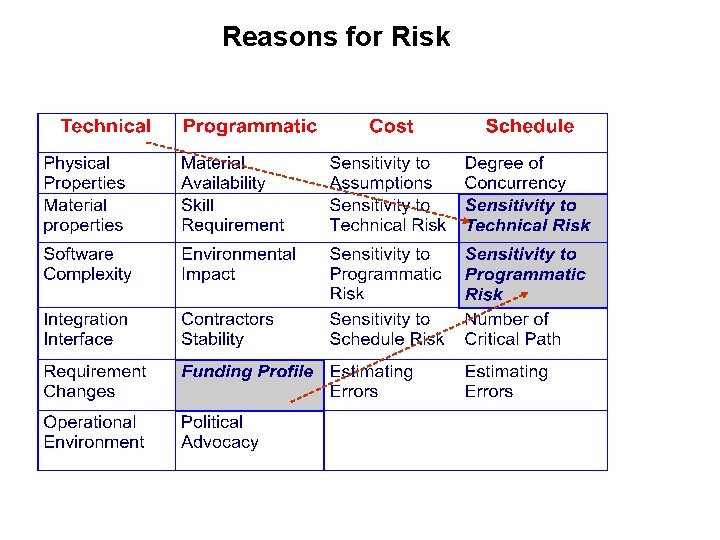
Reasons for Risk
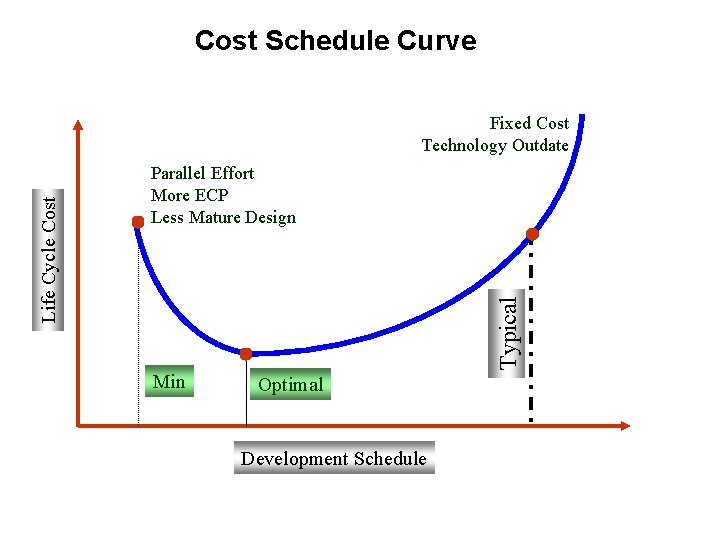
Cost Schedule Curve Parallel Effort More ECP Less Mature Design Typical Life Cycle Cost Fixed Cost Technology Outdate Min Optimal Development Schedule
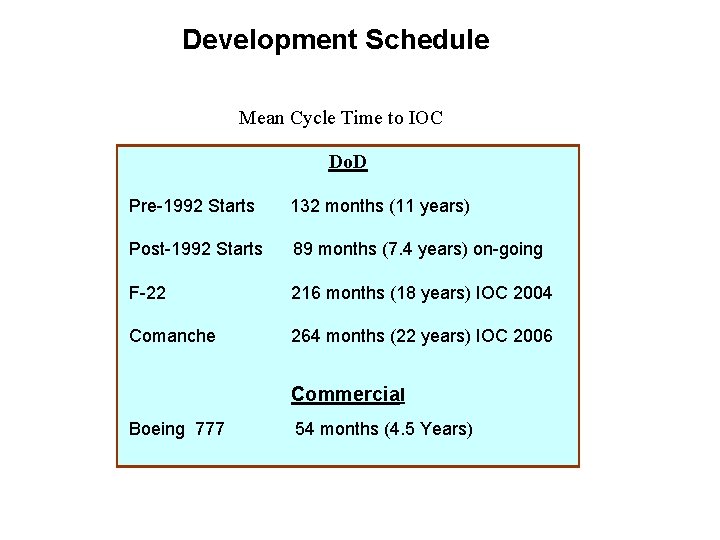
Development Schedule Mean Cycle Time to IOC Do. D Pre-1992 Starts 132 months (11 years) Post-1992 Starts 89 months (7. 4 years) on-going F-22 216 months (18 years) IOC 2004 Comanche 264 months (22 years) IOC 2006 Commercial Boeing 777 54 months (4. 5 Years)
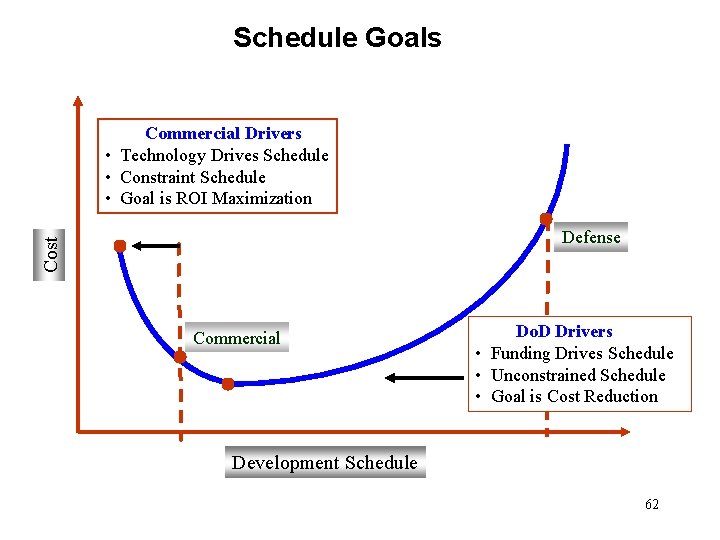
Schedule Goals Commercial Drivers • Technology Drives Schedule • Constraint Schedule • Goal is ROI Maximization Cost Defense Commercial Do. D Drivers • Funding Drives Schedule • Unconstrained Schedule • Goal is Cost Reduction Development Schedule 62
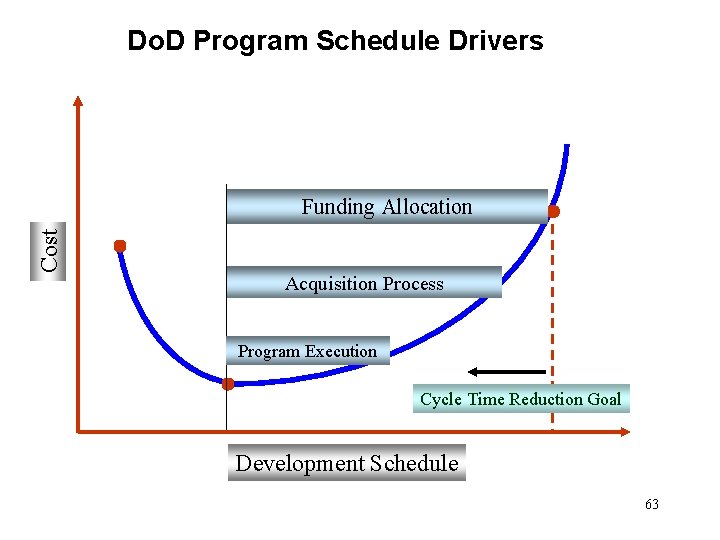
Do. D Program Schedule Drivers Cost Funding Allocation Acquisition Process Program Execution Cycle Time Reduction Goal Development Schedule 63
Final Documentation • Provide the means for other analysts to get the same results that we have in our cost estimate. • Providing good directions and a clear trail to follow are essential in having an estimate that can be replicated. • Provide step-by-step documentation of the methodologies, supporting data, ground rules, and assumptions, equations, examples, etc. , • Ability to interpret or evaluate someone else’s cost documentation is as important as ability to prepare good cost documentation. 64
CAIV Process • Set realistic but aggressive cost objectives early in acquisition program • Manage risks • Track progress using appropriate metrics • Motivate Government and industry managers to achieve program objectives • Incorporate incentives to reduce O&S costs for fielded systems
Cost As An Independent Variable (CAIV) • Best time to reduce cost is early in the process. • Involves the stakeholders in the process. • Cost tradeoffs must be addressed early in the acquisition process and embedded in program requirement documents, Request For Proposals (RFPs), contract provisions, and source selection process. 66
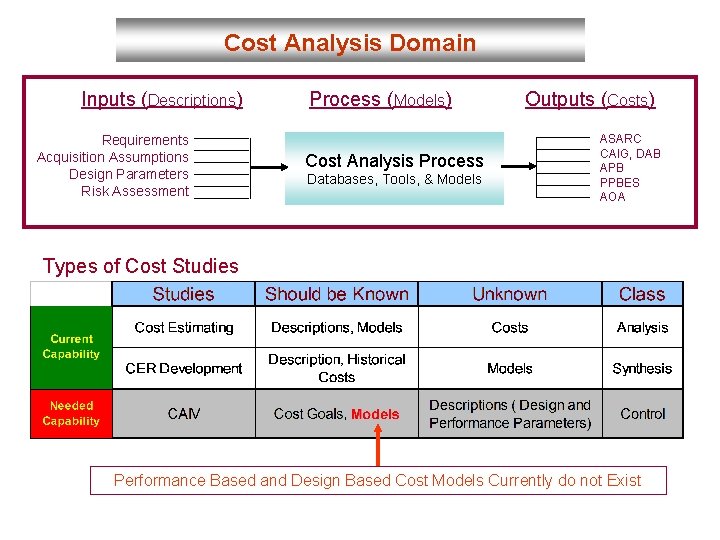
Cost Analysis Domain Inputs (Descriptions) Requirements Acquisition Assumptions Design Parameters Risk Assessment Process (Models) Cost Analysis Process Databases, Tools, & Models Outputs (Costs) ASARC CAIG, DAB APB PPBES AOA Types of Cost Studies Performance Based and Design Based Cost Models Currently do not Exist
Analysis of Alternatives • Set realistic, aggressive cost objectives early in development • Manage risks • Track progress with appropriate metrics • Motivate government/industry managers to achieve program objectives • Incorporate incentives to reduce O&S costs for fielded systems.
Cost Analysis Art or Science?