
Presented by Kimberly A Rayer Esq and Katherine
Presented by: Kimberly A. Rayer, Esq. and Katherine D. Tohanczyn, Esq. Fundamental s of SBA Lending
What is the SBA? The SBA is the United States Small Business Administration. The mission of the SBA is to foster the growth of small business. 2
SBA SOP 50 10(5)(I) p What is the SOP? p Regulation that governs the processing, documenting and closing of SBA loans p Last revision effective January 1, 2017 n 50 10 5(I) n Franchise eligibility p Notice 5000 -1941 amendments 3
SBA Loan Programs p 7(a) divided by size: n $350, 000 and under n Over $350, 000 to $5, 000 p 504 Loan Program p SBAExpress Loan Program p Export Working Capital Program p CAP Lines p Export Working Capital Program p International Trade 4
The SBA 7(a) Program Deferred Loan Participation Program (Guaranteed Loan) p (Aggregate) Maximum loan limit – $5 million p Maximum maturity – shortest term based on UOP and repayment ability (1 – 25 years) p Fixed or Variable Interest Rate p SBA guarantees 50% to 85% of Lender’s loan BUT the Guaranty is conditional p Active secondary market 5
7(a) Lender Participation p GP - least experienced; Lender submits complete application to SBA; SBA prepares Loan Authorization p CLP - more experienced with greater authority (streamlined application) p PLP - most experienced lenders; most authority (most streamlined) 6 SOP 5010(5)(B) pgs 18 -31
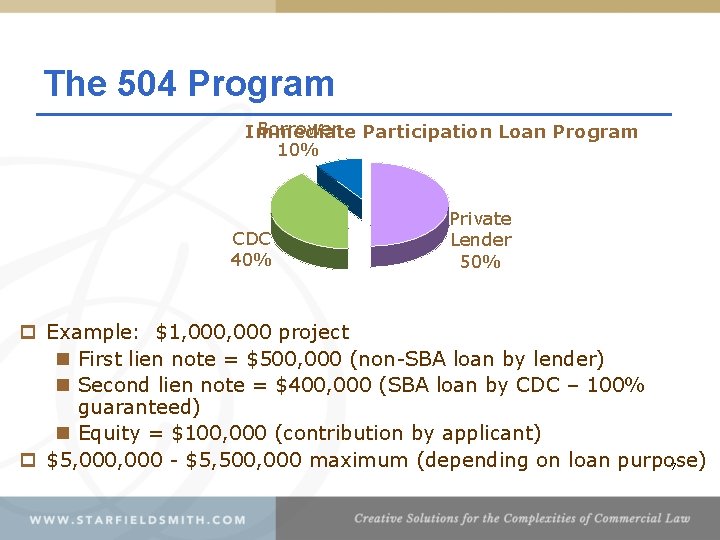
The 504 Program Borrower Participation Loan Program Immediate 10% CDC 40% Private Lender 50% p Example: $1, 000 project n First lien note = $500, 000 (non-SBA loan by lender) n Second lien note = $400, 000 (SBA loan by CDC – 100% guaranteed) n Equity = $100, 000 (contribution by applicant) p $5, 000 - $5, 500, 000 maximum (depending on loan purpose) 7
Differences Between the 7(a) and 504 Loan Programs p p p p 7(a) SBA guarantees a percentage Lender prepares and funds loan Proceeds can be used for any business use Note interest can be fixed or variable Any term up to maximum maturity of 25 years Injection must be Borrower’s money Conditional Guaranty p p p p 504 SBA has junior lien CDC prepares loan documents and assigns to the SBA Proceeds must be used for fixed assets (real estate or long term equipment) Note interest rate is fixed Fixed maturity – either 10 or 20 years Borrower’s contribution may be borrowed or as a matter of credit, CDC may want borrower to inject its own funds Limited ability to refinance existing debt 8
General Eligibility Requirements 7(a) and 504 p Applicant must be: n Located in the US n Organized for profit n Small under SBA size requirements n Demonstrate a need for guaranty p Credit Elsewhere Test p 504 Loan must create jobs or meet community or public policy objective 9
Ineligible Businesses: p Business foreign owned p Business engaged in lending p Passive business p Life insurance companies p Businesses located in foreign countries p Gambling p Illegal activities 10
Uses of SBA Loan Proceeds Permanent working capital; Revolving working capital; Furniture and fixtures; Machinery and equipment; Purchase of land building including construction and renovations; p Business acquisition; and p Refinancing of existing debt p p p 11
Credit Criteria – Loan < $350, 000 p Loans $350, 000 and under must be processed under 7(a) Small Loan (previously SLA) Credit Score prescreening prior to submission of ETran application p If loan application does not receive an acceptable credit score, Lender may submit Standard processing or (if SBA Express Lender) an SBA Express Application via ETran for 50% guaranty. 12
Credit Criteria – Loan < $350, 000 p Eligibility for Small Business Loans will continue to be based on pre-screening credit score and specified mandatory credit evaluation: n Applicant’s DSCR must be equal to or greater than 1: 1 on a historical or projected basis 13
Credit Criteria – Loans > $350, 000. 00 p Repayment ability from business cash flow: n DSCR equal to or greater than 1. 15: 1 based on a historical and/or projected basis p Should also analyze: n n Collateral Personal Financial Strength Management Experience Strengths and Weaknesses 14
Collateral Requirements p For loans of $25, 000 and less – no collateral required p For loans over $25, 000 – Lien on all assets financed by loan proceeds still mandatory 15
Collateral Requirements Loans Between $25, 000 - $350, 000 p Follow collateral policies and procedures that Lender has established and implemented for its similarly-sized non. SBA-guaranteed commercial loans. p At a minimum obtain a lien on the applicant’s fixed assets. p Lender may secure applicant’s trading assets (using a 10% current book value for the calculation) if it does so for similarly sized non-SBA-guaranteed commercial loans. 16
Collateral Requirements Loans Between $350, 000 $5, 000 p SBA requires that the lender collateralize the loan to the maximum extent possible up to the loan amount. p Fully Secured means all available assets with a combined net book value up to the loan amount. p Fixed Assets, then Trading Assets (10% of current book value) and then personal real estate and investment property (up to shortfall) 17
Residential Collateral Requirements p Lien on personal residence still NOT required if equity less than 25% p Lien on jointly held R/E still required even if one spouse has NO ownership interest in business p No lien required if R/E wholly owned by non-owner spouse Liens on residence may be limited to 150% of equity - if tax implications from filing at higher amount 18
SBA 7(a) Loan Authorization p “Roadmap for a compliant loan” p Not a contract or Loan Agreement p Borrower is not a third party beneficiary of the Authorization p Modifications allowed during life of the loan 19
SBA Forms – 7(a) Lender must use the following SBA forms for the loan: n. SBA Form 1050, Settlement Sheet n. SBA Form 159, Compensation Agreement, for each required agent n. SBA Form 722, Equal Opportunity Poster n. SBA Form 4506 -T, Tax Return Verification n. SBA Form 601, Agreement of Compliance, when applicable Lender may use SBA form or own form: n SBA Form 147, Note n SBA Forms 148 and 148 L, Guarantees 20
SBA 504 – Documentation p 504 Loan Authorization (produced by CDC/SBA) n Changes must be approved by SBA p Third Party Lender Loan Documents n Permanent Loan Documents n Bridge Loan Documents n Third Party Lender Agreement n Interim Lender Certification 21
Due Diligence - Company Information p Borrower and Guarantor Entity Documentation: n Corporation, LLC, LLP, Partnership and Trusts n Tax ID Numbers n Resolutions n Good Standing Certifications 22
Due Diligence - Searches p Searches: n UCC (to perfect collateral position) n Name Searches of Borrower, Guarantor and Seller n CAIVRS n Tax lien, judgment & bankruptcy n Corporate Tax Clearance/Bulk Sales Compliance n 4506 -T Transcript n Flood Zone 23
Due Diligence – Real Property p Commercial Real Estate: n Purchase Agreement n Appraisal n Environmental Report n Title Insurance Policy p. Deeds p. Exceptions p. Survey p. Taxes p. Endorsements p. Look for Covenants Running with the Land 24
Due Diligence – Real Property p Personal Residence and Investment Property n O&E search n Deed n Recording Costs and Taxes p Leases n Landlord Waivers n Collateral Assignments n Tenant Estoppel 25
Due Diligence – Personal Property p Asset Purchase Agreement or Equipment Invoices p Equipment list with itemization for items valued in excess of $5, 000 p Patents, Trademarks & Security Agreements p Vehicles p CD, Money Markets and Marketable Securities 26
Due Diligence – Refinance p Copy of Notes p May refinance same intuition debt and/or current SBA Loan p Business purpose p Pay-Off Statements and Loan Numbers with lien release language p UCC-3 - Release of Existing Liens 27
Construction Documentation n Fixed Sum Contract (AIA vs. Attorney Prepared) n Plans and Specifications n Payment and Performance Bond > $350, 000 p. Or construction management n Statement of Qualification n Contractors License n Copies of Architect Agreement n SBA Form 601, Compliance Agreement 28
Insurance Information p Insurance n Hazard n Flood n Personal Property n Worker’s Comp n General Liability n Industry-specific Liability p Life Insurance n Collateral Assignment 29
Business Acquisitions p Change of Ownership n Must be 100% change n Seller cannot remain for more than one year n Seller Financing preferred p Agreements of Sale n Business Valuation n Stock Certificates n Bill of Sale n Resolutions n New operating documents 30
7(a) Equity Injection p Sufficient monies, assets injected into the business p Not borrowed funds n HELOC (Maybe if outside source of repayment) p Verify source of funds p Review the proof or evidence of funds p Insure proper purpose 31
504 Borrower’s Contribution p 10% - existing business p 15% - new business or special purpose property p 20% - new business and special purpose property p May be borrowed funds p Eligible Project Costs incurred within 9 months of application 32
Franchises p Review of Franchise/License/Dealer/Jobber or Similar Agreement provisions n FTC Definition n Two Options for Determining Affiliation p SBA Addendum- Form 2462 p Alternative Documentation: § SBA Negotiated Addendum for 2015 & 2016 Agreement § SB Form 2463 p Identify Franchise in E-Tran or SBAONE When in doubt Collect an Addendum 33 © 2014, Starfield & Smith, P. C.
Allocation of Loan Proceeds p Verify no change in use of proceeds p Compare Settlement Statement with Loan Authorization p If reallocation, ascertain whether the change affects the term of the loan n If Non-PLP: 327 n If PLP: Notice and paper trail p No working capital proceeds to EPC p Verify correct use of proceeds, especially with vendors 34
Agents p Who are “Agents”? n Doing business with SBA n Brokers (“Referral Agents”) n Packagers (prepare and submit the SBA application package for a fee) p SBA Form 159 (7 a), Compensation Agreement n Who executes? p. Lender paid fees – comply with “two master rule” p. Borrower paid fees – only initial 159 must be executed n Itemization of expenses p$2, 500 threshold p “Other Services” - can be charged as a percentage of loan, up to $30, 000 (must be consistent with non-SBA loans) 35
Common Mistakes – Repairs or Denials p Refinancing debt not originally eligible for SBA financing p Refinancing same institution’s debt PLP p Failure to verify tax transcripts p Affiliation - exceeds program maximums p Not clearing 912 issue p Not completing Phase I recommendations p Not properly documenting change of Use of Proceeds p Not in correct lien position on collateral 36
Servicing and Liquidation p Document changes to Loan Terms through out term p Early defaulting loans – 18 months from disbursement p Servicing and Liquidation Regulations are in the SOP 50 57 p Servicing and Liquidation Actions 7(a) Lender Matrix 37
Liquidation Lenders must: p Take timely action to secure the collateral p Notify the SBA – loan in liquidation on 1502 Report p Site Visit p Devise a liquidation plan p When submitting guaranty purchase request – must be in special 10 Tab Submission that is required by SBA’s NGPC. 38
Thanks! Kimberly A. Rayer, Esq. krayer@starfieldsmith. com 1300 Virginia Drive Suite 325 Ft. Washington, PA 19034 P: 267 -470 -1208 F: 215 -534 -9023 1101 North Lake Destiny Road, Suite 105 Maitland, FL 32751 P: (407) 667 -8811 F: (407) 667 -0020 www. starfieldsmith. com 39
- Slides: 39