
Presented by DAN MCNEILL Filling Gaps with Supplemental
Presented by DAN MCNEILL Filling Gaps with Supplemental Health Solutions Presented to CKAHU May 7, 2019 Course approval: C 19265
Presented by Dan Mc. Neill to CKAHU AGENDA • Introduction • About Beazley • The Changing Marketplace • About Supplemental Medical • About Group Limited Indemnity • Q&A
About Beazley
About Beazley At A Glance Worldwide operation Established in 1986 Headquartered in London More than 33 years Founded by Andrew Beazley A specialist insurer and reinsurer with operations in Europe, Asia, and the U. S. Rated A by A. M. Best $2. 6 billion in gross premium Manages five Lloyd’s of London syndicates (making it the 3 rd largest) Recognized market leader in Specialty Lines, Re-insurance, Property, Marine, Political Risks & Contingency and Life, Accident & Health
About Beazley Where is the product approved/available?
About Beazley Where is the product approved/available?
About Beazley Full-service capabilities for producers PRODUCER APPOINTMENT NEW BUSINESS ONBOARDING PRODUCER PORTAL • Timely appointment and registration • Dedicated new case implementation support • Online access to quotes, active cases, commissions and marketing materials
About Beazley Full-service capabilities for employer customers CUSTOMER SUPPORT AND SERVICE ONLINE SELFSERVICE PORTAL EFFICIENT CLAIMS PROCESS • Dedicated implementation specialist and ongoing customer service • Online fulfillment, billing and eligibility management • Efficient claims processing
About Beazley Education for employees Employee education materials, built around theme: Ready for Whatever’s Down the Line • What is the product? • Why do I need it? • What are the plan benefits (includes benefit amounts and definitions)? • How much does it cost? • What’s covered/what’s not? • How are claims processed? • Who is Beazley?
About Beazley Our team • Regional Sales Managers: Dan Mc. Neill based in Ohio (330) 703 -3822 Daniel. Mc. Neill@beazley. com Jeffrey Morgan based in Georgia (904) 631 -5142 Jeffrey. Morgan@beazley. com Barry Johnson based in Nebraska (402) 486 -1525 Barry. Johnson@beazley. com Scott Long based in Texas (832) 457 -1472 Scott. Long@beazley. com (949) 310 -5032 Ryan. Whittaker@beazley. com Ryan Whittaker based in California • Assistant Sales Representative: Marie Samovoski based in Ohio (330)242 -0148 Marie. Samovoski@beazley. com
About Beazley Your points of contact Dan Mc. Neill Dan. Mc. Neill@beazley. com (330) 703 -3822 Marie Samovoski Marie. Samovoski@beazley. com (330) 242 -0148
Presented by DAN MCNEILL Filling Gaps with Supplemental Health Solutions Presented to CKAHU May 7, 2019 Course approval: C 19265
The Changing Marketplace
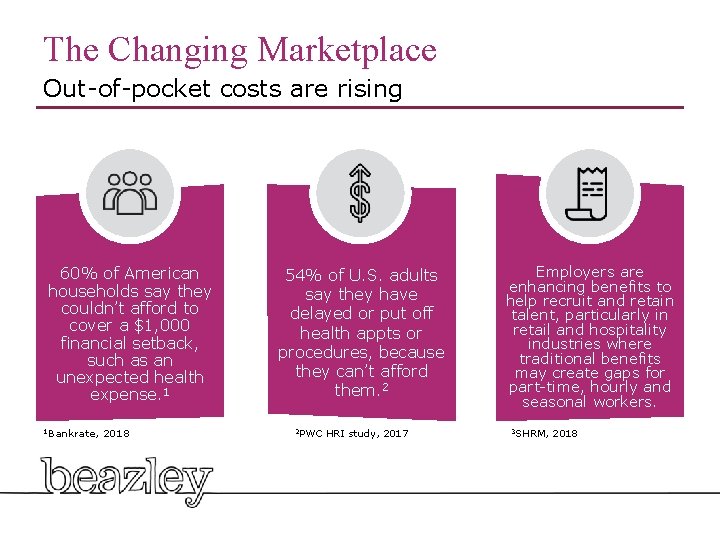
The Changing Marketplace Out-of-pocket costs are rising 60% of American households say they couldn’t afford to cover a $1, 000 financial setback, such as an unexpected health expense. 1 1 Bankrate, 2018 54% of U. S. adults say they have delayed or put off health appts or procedures, because they can’t afford them. 2 2 PWC HRI study, 2017 Employers are enhancing benefits to help recruit and retain talent, particularly in retail and hospitality industries where traditional benefits may create gaps for part-time, hourly and seasonal workers. 3 SHRM, 2018
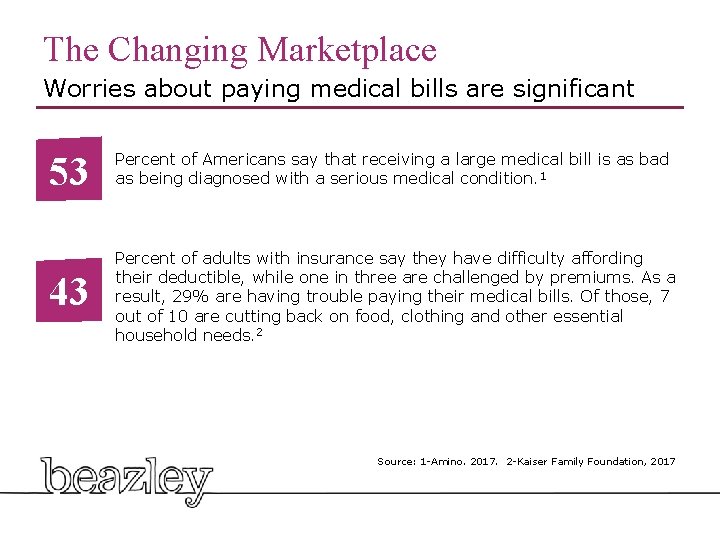
The Changing Marketplace Worries about paying medical bills are significant 53 Percent of Americans say that receiving a large medical bill is as bad as being diagnosed with a serious medical condition. 1 43 Percent of adults with insurance say they have difficulty affording their deductible, while one in three are challenged by premiums. As a result, 29% are having trouble paying their medical bills. Of those, 7 out of 10 are cutting back on food, clothing and other essential household needs. 2 53 Source: 1 -Amino. 2017. 2 -Kaiser Family Foundation, 2017
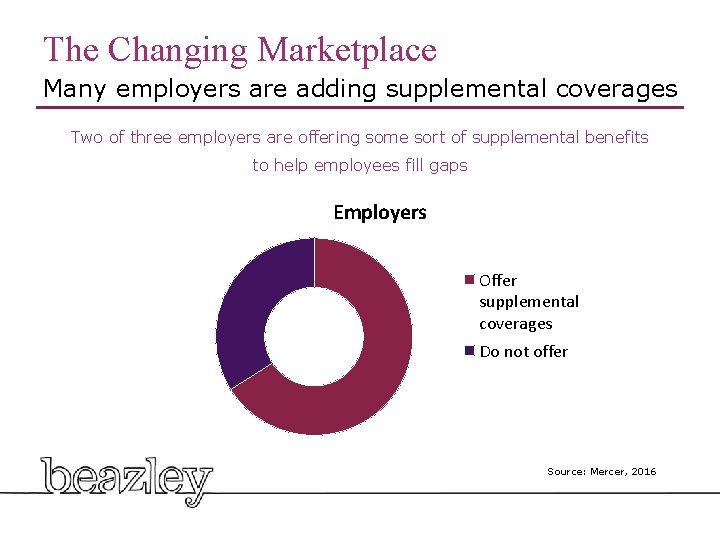
The Changing Marketplace Many employers are adding supplemental coverages Two of three employers are offering some sort of supplemental benefits to help employees fill gaps Employers Offer supplemental coverages Do not offer Source: Mercer, 2016
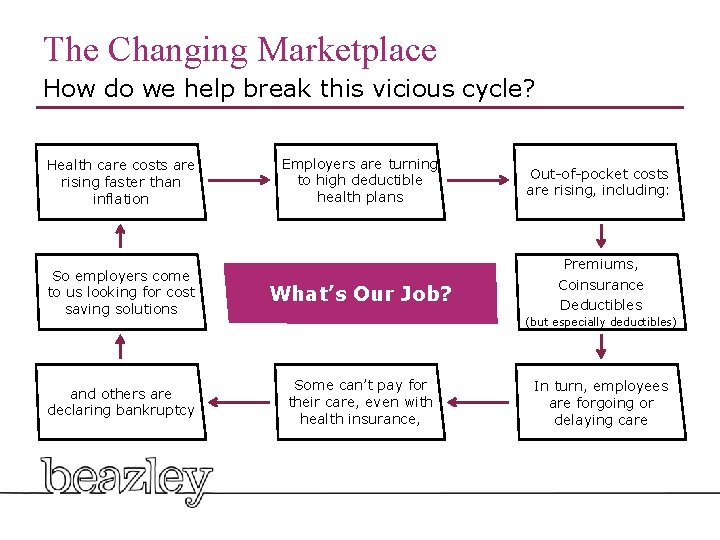
The Changing Marketplace How do we help break this vicious cycle? Health care costs are rising faster than inflation Employers are turning to high deductible health plans So employers come to us looking for cost saving solutions What’s Our Job? and others are declaring bankruptcy Some can’t pay for their care, even with health insurance, Out-of-pocket costs are rising, including: Premiums, Coinsurance Deductibles (but especially deductibles) In turn, employees are forgoing or delaying care
Cost Saving Solutions
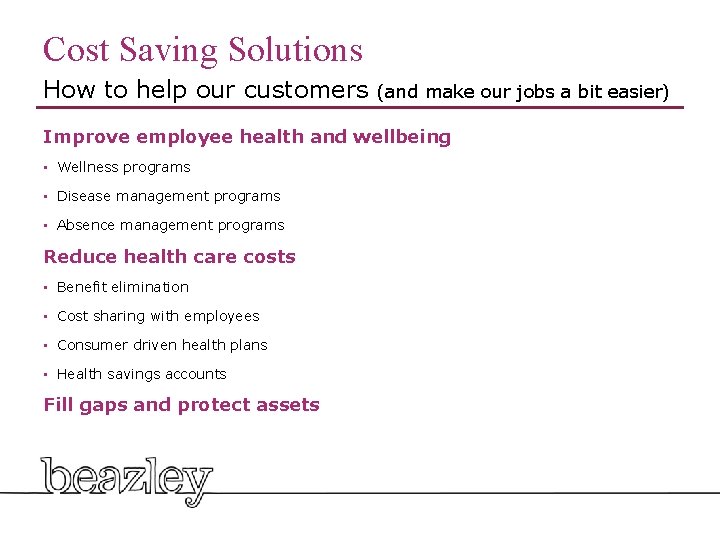
Cost Saving Solutions How to help our customers (and make our jobs a bit easier) Improve employee health and wellbeing • Wellness programs • Disease management programs • Absence management programs Reduce health care costs • Benefit elimination • Cost sharing with employees • Consumer driven health plans • Health savings accounts Fill gaps and protect assets
Cost Saving Solutions Examples of supplemental insurance products SUPPLEMENTAL MEDICAL HOSPITAL INDEMNITY CRITICAL ILLNESS ACCIDENT
Cost Saving Solutions Examples of supplemental insurance products • What are your ideas for cost saving solutions? • What products do you recommend? • What products are your customers asking for?
Cost Saving Solutions What can you do with cost savings? • Lower premiums? • Add wellness? • Add telemedicine? • Add non-insurance? • Add financial counseling?
Supplemental Medical
Supplemental Medical (Gap) What is it? • Pays for eligible out-of-pocket expenses, incurred in inpatient and select outpatient settings Examples of benefits • Inpatient hospitalization • Often requires an underlying medical plan • Outpatient surgery and diagnostic testing • Does not replace health insurance • Ambulance transport • Is your product an Indemnity or Expense Incurred Plan • Other indemnity benefits
Supplemental Medical (Gap) What is typically covered? INPATIENT OUTPATIENT AMBULANCE • Pays for expenses that are eligible under the major medical plan: – Inpatient expenses, such as hospitalization – Outpatient expenses, such as ER visits, outpatient surgery and radiological diagnostic testing
Supplemental Medical (Gap) What is typically not covered? • What is not covered? • How do you fill holes in the gap?
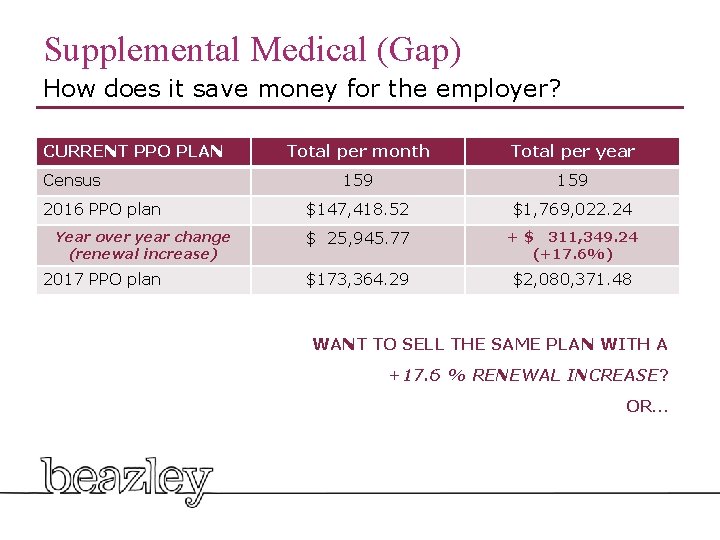
Supplemental Medical (Gap) How does it save money for the employer? CURRENT PPO PLAN Census 2016 PPO plan Year over year change (renewal increase) 2017 PPO plan Total per month Total per year 159 $147, 418. 52 $1, 769, 022. 24 $ 25, 945. 77 + $ 311, 349. 24 (+17. 6%) $173, 364. 29 $2, 080, 371. 48 WANT TO SELL THE SAME PLAN WITH A +17. 6 % RENEWAL INCREASE? OR…
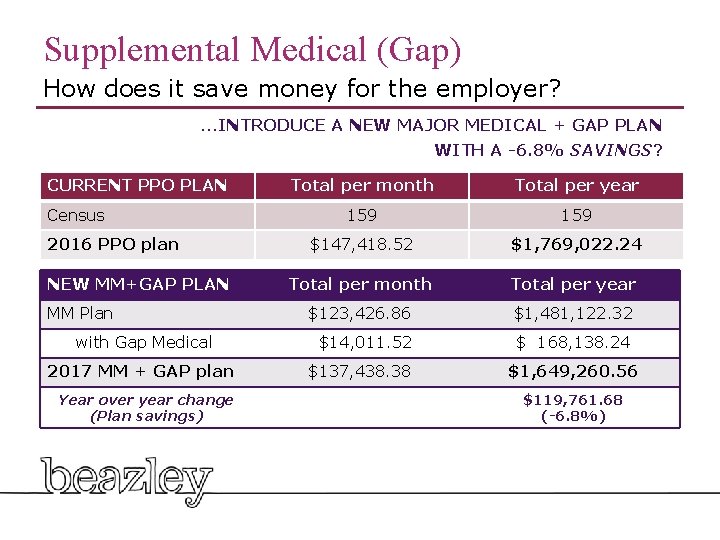
Supplemental Medical (Gap) How does it save money for the employer? …INTRODUCE A NEW MAJOR MEDICAL + GAP PLAN WITH A -6. 8% SAVINGS? CURRENT PPO PLAN Total per month Total per year 159 $147, 418. 52 $1, 769, 022. 24 Total per month Total per year MM Plan $123, 426. 86 $1, 481, 122. 32 with Gap Medical $14, 011. 52 $ 168, 138. 24 2017 MM + GAP plan $137, 438. 38 $1, 649, 260. 56 Census 2016 PPO plan NEW MM+GAP PLAN Year over year change (Plan savings) $119, 761. 68 (-6. 8%)
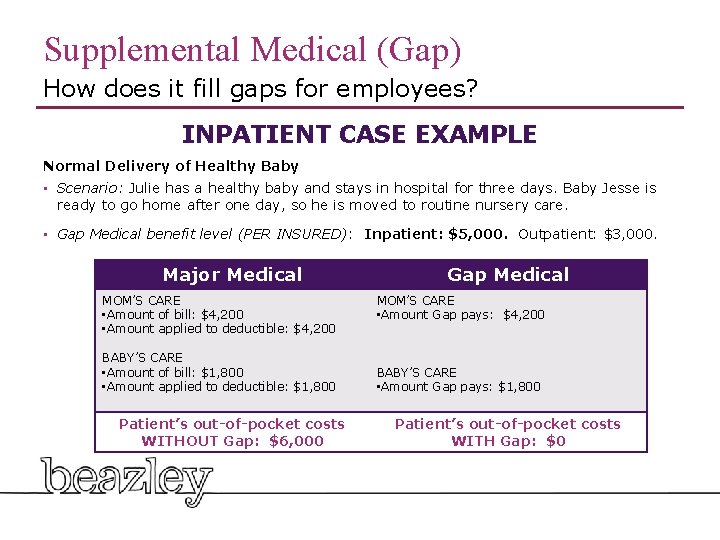
Supplemental Medical (Gap) How does it fill gaps for employees? INPATIENT CASE EXAMPLE Normal Delivery of Healthy Baby • Scenario: Julie has a healthy baby and stays in hospital for three days. Baby Jesse is ready to go home after one day, so he is moved to routine nursery care. • Gap Medical benefit level (PER INSURED): Inpatient: $5, 000. Outpatient: $3, 000. Major Medical MOM’S CARE • Amount of bill: $4, 200 • Amount applied to deductible: $4, 200 BABY’S CARE • Amount of bill: $1, 800 • Amount applied to deductible: $1, 800 Patient’s out-of-pocket costs WITHOUT Gap: $6, 000 Gap Medical MOM’S CARE • Amount Gap pays: $4, 200 BABY’S CARE • Amount Gap pays: $1, 800 Patient’s out-of-pocket costs WITH Gap: $0
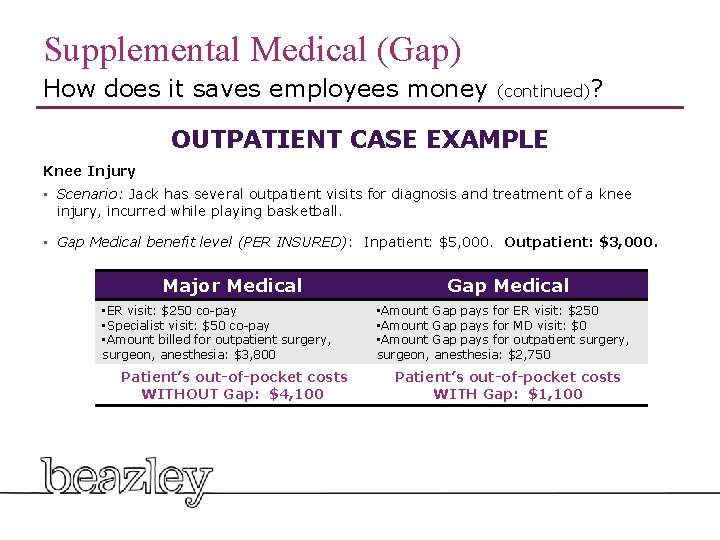
Supplemental Medical (Gap) How does it saves employees money (continued)? OUTPATIENT CASE EXAMPLE Knee Injury • Scenario: Jack has several outpatient visits for diagnosis and treatment of a knee injury, incurred while playing basketball. • Gap Medical benefit level (PER INSURED): Inpatient: $5, 000. Outpatient: $3, 000. Major Medical • ER visit: $250 co-pay • Specialist visit: $50 co-pay • Amount billed for outpatient surgery, surgeon, anesthesia: $3, 800 Patient’s out-of-pocket costs WITHOUT Gap: $4, 100 Gap Medical • Amount Gap pays for ER visit: $250 • Amount Gap pays for MD visit: $0 • Amount Gap pays for outpatient surgery, surgeon, anesthesia: $2, 750 Patient’s out-of-pocket costs WITH Gap: $1, 100
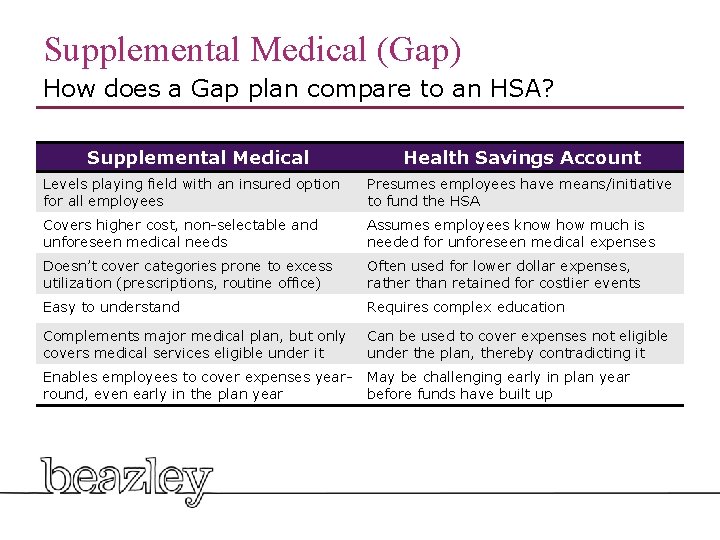
Supplemental Medical (Gap) How does a Gap plan compare to an HSA? Supplemental Medical Health Savings Account Levels playing field with an insured option for all employees Presumes employees have means/initiative to fund the HSA Covers higher cost, non-selectable and unforeseen medical needs Assumes employees know how much is needed for unforeseen medical expenses Doesn’t cover categories prone to excess utilization (prescriptions, routine office) Often used for lower dollar expenses, rather than retained for costlier events Easy to understand Requires complex education Complements major medical plan, but only covers medical services eligible under it Can be used to cover expenses not eligible under the plan, thereby contradicting it Enables employees to cover expenses yearround, even early in the plan year May be challenging early in plan year before funds have built up
Supplemental Medical (Gap) Benefits to you and your customers • For you – Drives revenue – Helps diversify your product portfolio • For your employer customers – Saves money for the company – Frees up money to offer Gap on employer-funded basis, or for adding other voluntary benefits – Easy to implement – ACA “excepted” benefit • Is the plan you are offering ACA compliant? • For their employees – Fills gaps – Affordable and easy to understand
Group Limited Indemnity
Group Limited Indemnity What is it? • Coverage for basic expenses • Set schedule of benefit amounts and maximums Examples of benefits • Compatible with Health Savings Accounts (HSAs) • Hospital confinement • Guarantee issue HOSPITAL BENEFITS • Hospital admission • Hospital ICU • Inpatient surgery
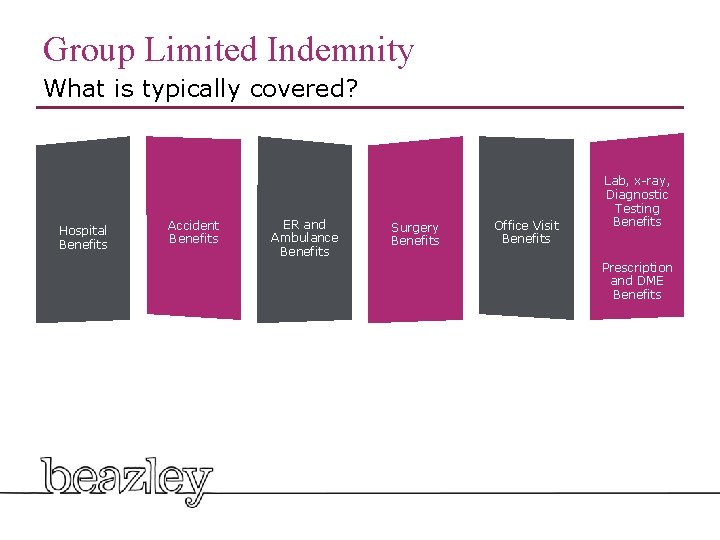
Group Limited Indemnity What is typically covered? Hospital Benefits Accident Benefits ER and Ambulance Benefits Surgery Benefits Office Visit Benefits Lab, x-ray, Diagnostic Testing Benefits Prescription and DME Benefits
Group Limited Indemnity What is the purpose of the plan? • Standalone Limited Medical? • Limited Medical with MEC? • Hospital Indemnity, compatible with HSAs?
Group Limited Indemnity Benefits to you and your customers • For you – Drives revenue – Helps diversify your product portfolio • For employers – Saves money for the company – Easy to implement • For their employees – Covers basic medical expenses – Affordable and easy to understand
Supplemental Insurance Products Top 10 objections • 10. It looks too good to be true; where’s the catch? • 9. My group will never understand it • 8. My group’s medical carrier won’t like it • 7. My group’s employees will never carry two ID cards • 6. There are too many holes in the gap • 5. My group won’t want to deal with two insurance companies • 4. My group will be concerned Gap could drive utilization. • 3. My group can’t afford it. • 2. If it is not my idea, then it must be bad idea. • 1. What about next year?
1 Solid Reason Who Wins? The Employer with the Best Benefits Package Wins
Q&A
About Beazley Your points of contact Dan Mc. Neill Dan. Mc. Neill@beazley. com (330) 703 -3822 Marie Samovoski Marie. Samovoski@beazley. com (330) 242 -0148
Thank you
Insurance is underwritten by Beazley Insurance Company, Inc. , 30 Batterson Park Road, Farmington, Connecticut, 06032. Beazley is rated A by A. M. Best. Beazley is licensed in all 50 states and the District of Columbia. (CA License #2868 -8) The Supplemental Medical Expense (Gap) policy is offered under Policy Form Series AHGMM 0001. It is not a major medical plan. The product is designed to reimburse certain covered expenses, and is only available if an employer has a major medical plan in place. Out-of-pocket expenses submitted for reimbursement must be eligible under the major medical plan, and must meet the coverage definitions under our policy (may not include full reimbursement, if annual plan limits have been met). Riders for outpatient services performed in a physician’s office/urgent care, or for outpatient chemotherapy/radiation performed in a licensed facility, may not be available in all states. The Group Limited Indemnity policy is offered under Policy Form Series AHGLIMM 001. Pre-existing condition limitations may apply. (Pre-exiting condition means any sickness, disease, or physical condition for which the insured 1) had treatment, or 2) received a diagnosis or advice from a physician, during the pre-existing condition period. ) Coverage is not available in all states. Benefits may vary by state. Premium will vary based on the plan chosen. A waiting period for late entrants may apply. This policy is renewable at the option of Beazley. Refer to the Master Policy and Certificate for all terms, conditions, exclusions and limitations. Beazley uses the services of a third party administrator. CB_AH_117_US_7/16 (CE, refreshed 4/19)
- Slides: 43