
Post Award Grants and Contracts Accounting Linda Heide
- Slides: 42
Post Award Grants and Contracts Accounting Linda Heide, Manager August 11, 2017
Agen da • Research Administration = Shared Responsibility • Effort Certification • Grants Monthly Review • Cost Transfers • Grant Close-out
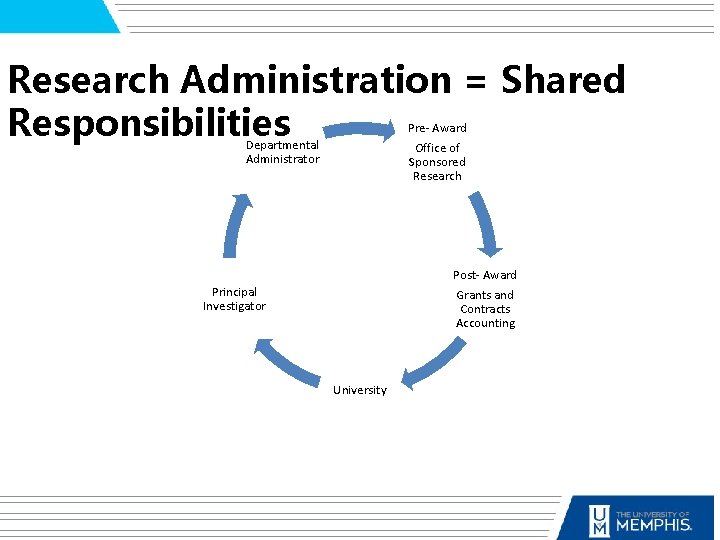
Research Administration = Shared Responsibilities Pre- Award Office of Sponsored Research Departmental Administrator Post- Award Grants and Contracts Accounting Principal Investigator University
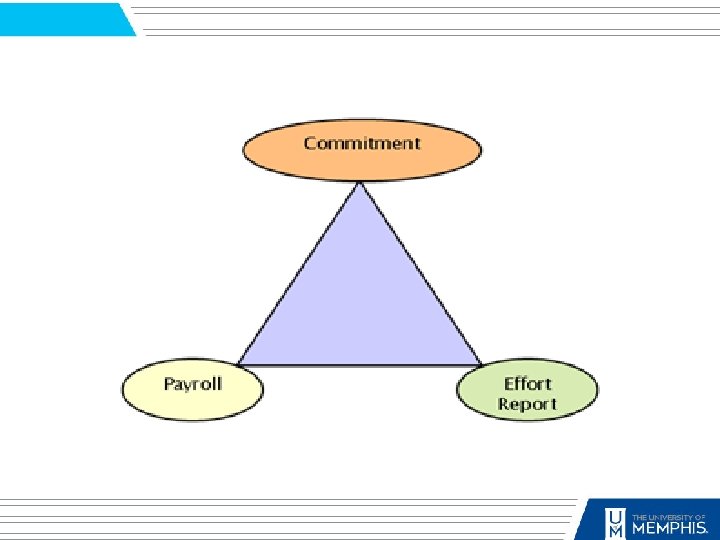
Effort Reporting UM 1676 Certification of Effort
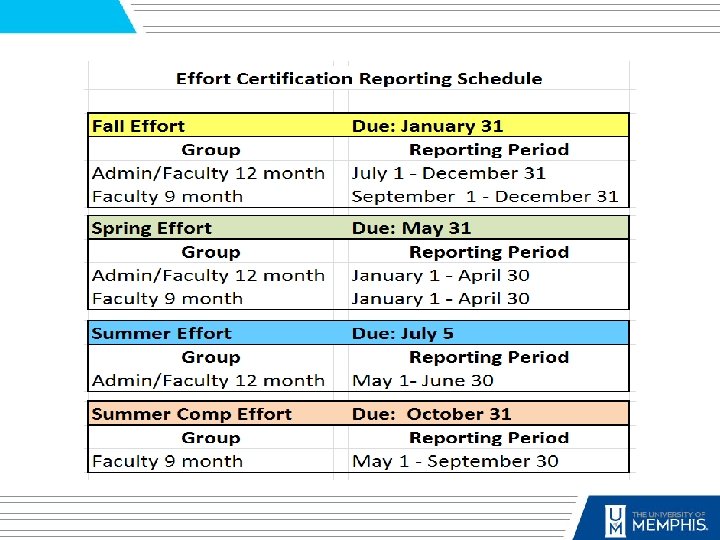
Definitions Effort § Time spent on any activity by an individual, expressed as a percentage of the individual’s total University Effort Certification § The affirmation by the individuals completing each Effort Certification form that the percentages of effort charged to sponsored projects as direct charges or cost sharing reported on the form is accurate based on the work performed during the reporting period. Knowingly signing an inaccurate effort certification is a serious violation of University policy, as well as potentially a violation of civil and criminal fraud statutes. Effort Reporting § The process by which the University documents the percent of Institutional Base Salary and Summer Salary charged to sponsored projects and other accounts during each effort reporting period, and individuals certify that the work was performed. The effort report form documents the proportion of time devoted to sponsored projects, teaching and other activities expressed as a percentage of total University effort. Certification Period § The 30 day time period for individuals to certify and/or approve effort for work performed on grant projects.
Who Must Comply All individuals involved with the administration and conduct of federally sponsored award activities, including central and departmental administrators. Principle Investigators(PIs)/Faculty Department Administrator/Business Officer Departmental Chair/Directors Dean Financial Reporting Grants and Contracts Accounting Provost Office Vice President of Research
Roles and Responsibility Principal Investigator (PI) § Responsible for understanding the principals of accurate effort reporting § Must be aware of the level of effort committed to a sponsor in relation to all other professional activities included in total effort. § When appropriate, request sponsor approval in advance for planned reductions in effort greater than 25% (or other applicable threshold) § Identify situations where the salary representing the effort devoted to a award is more than the actual percent of effort devoted to the award. § Change the effort report when inaccuracies exist. § Must certify his/her own form and should approve effort forms of others working on his/her awards. § In accordance with Effort Certification Procedures, complete and/or approve all Effort Certifications for grants under his/her responsibility. § 9 -month faculty receiving summer compensation during the summer months must ensure that the effort was expended during the summer effort reporting period for which they were funded. Administrator/Business Officer § Assist individuals required to certify effort with understanding the certification of effort process. § Assist PI in initiating requests for adjustments in labor distribution in accordance with the UM 1720 Cost Transfers. § Ensure that effort reports are completed and certified and in accordance with UM 1676 Certification of Effort.
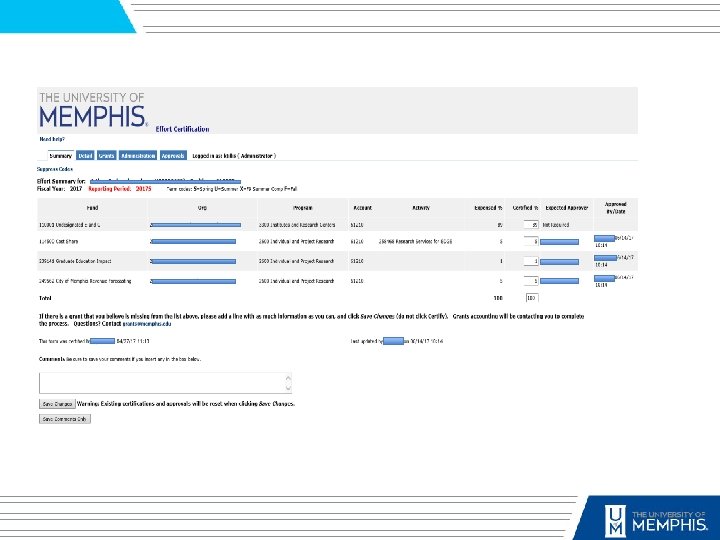
Tabs: Summary, Detail, Grants, Approvals v Summary- provides Fund, Program, Expensed%, Certified%, Expected Approver v Detail- provides the month, account code, fund, org, and activity percent v Grants- list of individuals on grant(s) by fund v Approval-Forms awaiting approval
Effort Review ü Review salary charges for effort certification period with PI and staff. ü Is all of the effort accounted for in the system? ü Does salary splits agree with budget and PI’s expectation? ü If changes are needed, submit salary redistribution form. If after the fact, submit effort re-certification form.
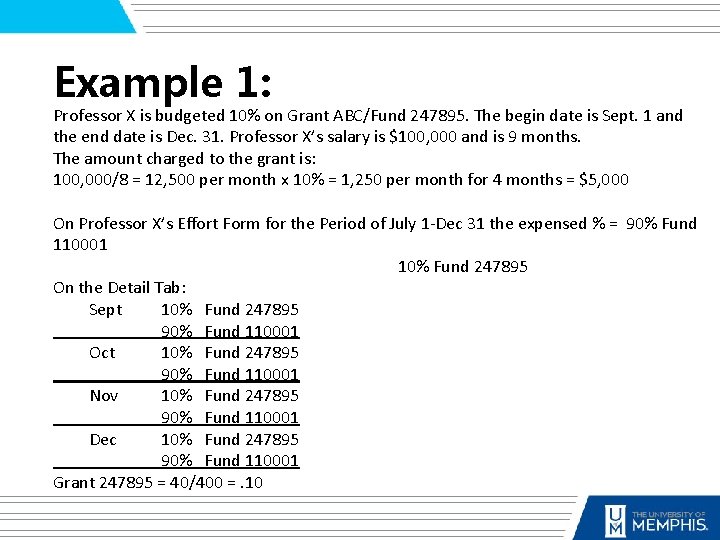
Example 1: Professor X is budgeted 10% on Grant ABC/Fund 247895. The begin date is Sept. 1 and the end date is Dec. 31. Professor X’s salary is $100, 000 and is 9 months. The amount charged to the grant is: 100, 000/8 = 12, 500 per month x 10% = 1, 250 per month for 4 months = $5, 000 On Professor X’s Effort Form for the Period of July 1 -Dec 31 the expensed % = 90% Fund 110001 10% Fund 247895 On the Detail Tab: Sept 10% Fund 247895 90% Fund 110001 Oct 10% Fund 247895 90% Fund 110001 Nov 10% Fund 247895 90% Fund 110001 Dec 10% Fund 247895 90% Fund 110001 Grant 247895 = 40/400 =. 10
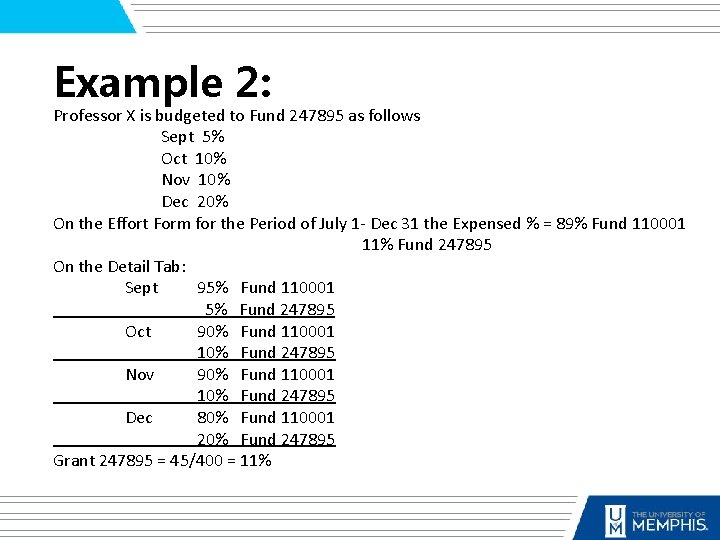
Example 2: Professor X is budgeted to Fund 247895 as follows Sept 5% Oct 10% Nov 10% Dec 20% On the Effort Form for the Period of July 1 - Dec 31 the Expensed % = 89% Fund 110001 11% Fund 247895 On the Detail Tab: Sept 95% Fund 110001 5% Fund 247895 Oct 90% Fund 110001 10% Fund 247895 Nov 90% Fund 110001 10% Fund 247895 Dec 80% Fund 110001 20% Fund 247895 Grant 247895 = 45/400 = 11%
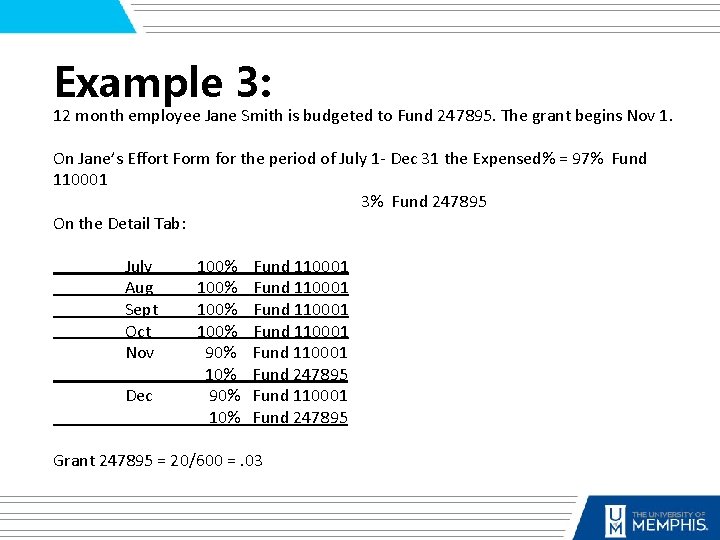
Example 3: 12 month employee Jane Smith is budgeted to Fund 247895. The grant begins Nov 1. On Jane’s Effort Form for the period of July 1 - Dec 31 the Expensed% = 97% Fund 110001 3% Fund 247895 On the Detail Tab: July Aug Sept Oct Nov Dec 100% 90% 10% Fund 110001 Fund 110001 Fund 247895 Grant 247895 = 20/600 =. 03
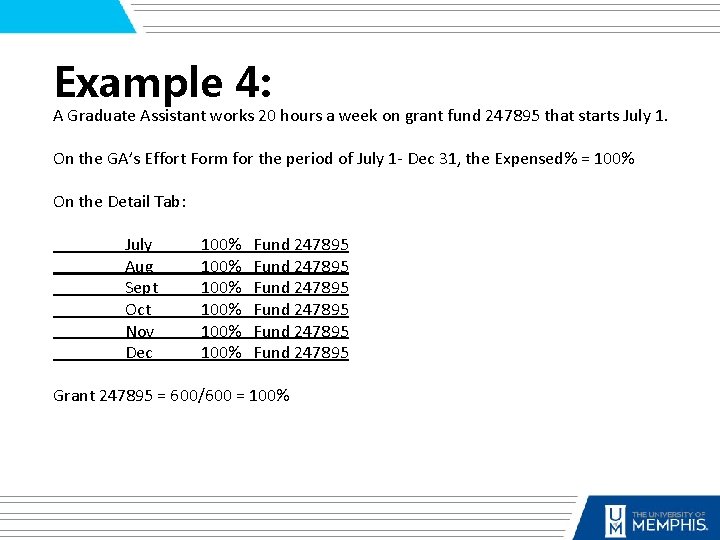
Example 4: A Graduate Assistant works 20 hours a week on grant fund 247895 that starts July 1. On the GA’s Effort Form for the period of July 1 - Dec 31, the Expensed% = 100% On the Detail Tab: July Aug Sept Oct Nov Dec 100% 100% Fund 247895 Fund 247895 Grant 247895 = 600/600 = 100%
Grants Monthly Review UM 1719 Charges to Sponsored Agreements
Roles of Administrator/ Business Office • • Provide guidance/assistance to Principal Investigators/Program Directors regarding the development of costs budgeted and actual costs charged; Review costs on a monthly basis for reasonableness, allocability, consistency and allowability to ensure compliance with sponsor regulations.
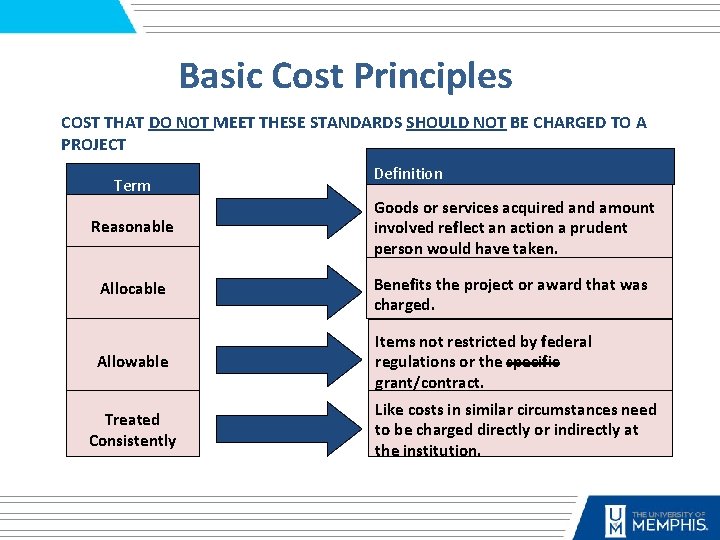
Basic Cost Principles COST THAT DO NOT MEET THESE STANDARDS SHOULD NOT BE CHARGED TO A PROJECT Term Definition Reasonable Goods or services acquired and amount involved reflect an action a prudent person would have taken. Allocable Benefits the project or award that was charged. Allowable Items not restricted by federal regulations or the specific grant/contract. Treated Consistently Like costs in similar circumstances need to be charged directly or indirectly at the institution.
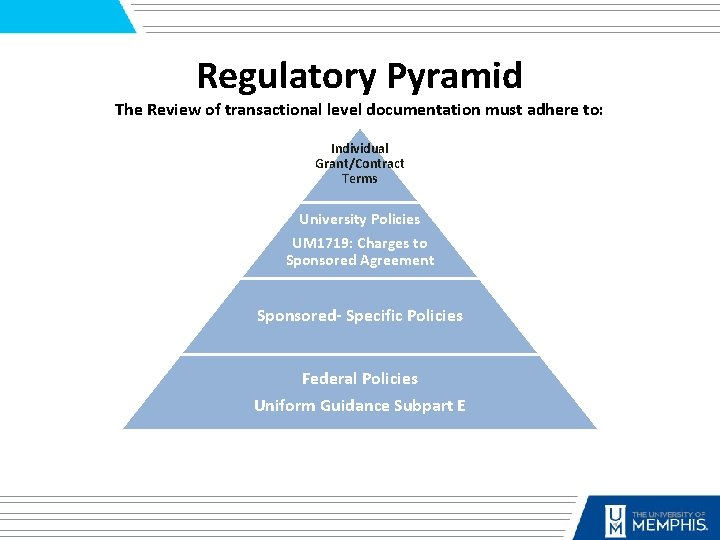
Regulatory Pyramid The Review of transactional level documentation must adhere to: Individual Grant/Contract Terms University Policies UM 1719: Charges to Sponsored Agreement Sponsored- Specific Policies Federal Policies Uniform Guidance Subpart E
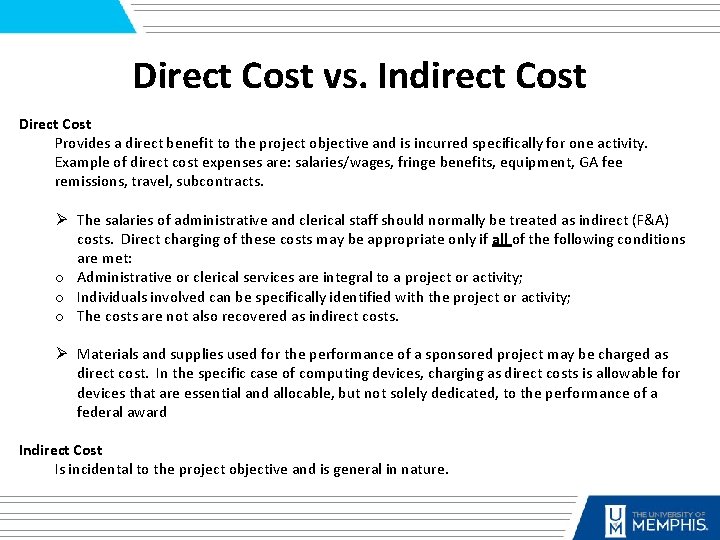
Direct Cost vs. Indirect Cost Direct Cost Provides a direct benefit to the project objective and is incurred specifically for one activity. Example of direct cost expenses are: salaries/wages, fringe benefits, equipment, GA fee remissions, travel, subcontracts. Ø The salaries of administrative and clerical staff should normally be treated as indirect (F&A) costs. Direct charging of these costs may be appropriate only if all of the following conditions are met: o Administrative or clerical services are integral to a project or activity; o Individuals involved can be specifically identified with the project or activity; o The costs are not also recovered as indirect costs. Ø Materials and supplies used for the performance of a sponsored project may be charged as direct cost. In the specific case of computing devices, charging as direct costs is allowable for devices that are essential and allocable, but not solely dedicated, to the performance of a federal award Indirect Cost Is incidental to the project objective and is general in nature.
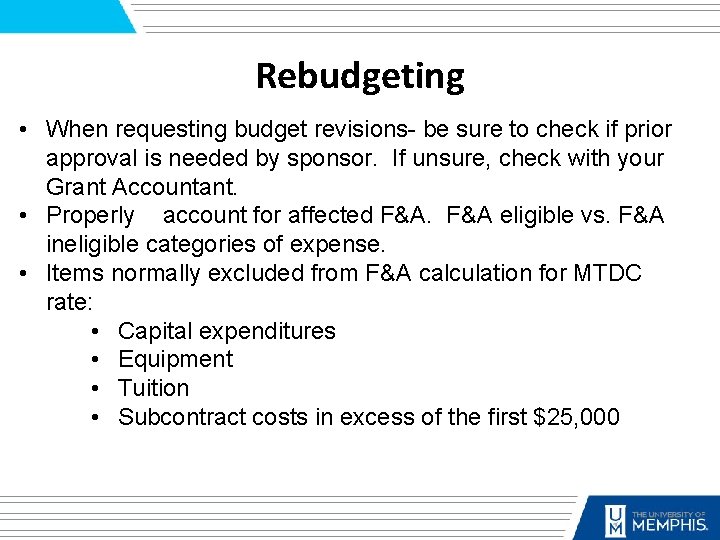
Rebudgeting • When requesting budget revisions- be sure to check if prior approval is needed by sponsor. If unsure, check with your Grant Accountant. • Properly account for affected F&A eligible vs. F&A ineligible categories of expense. • Items normally excluded from F&A calculation for MTDC rate: • Capital expenditures • Equipment • Tuition • Subcontract costs in excess of the first $25, 000
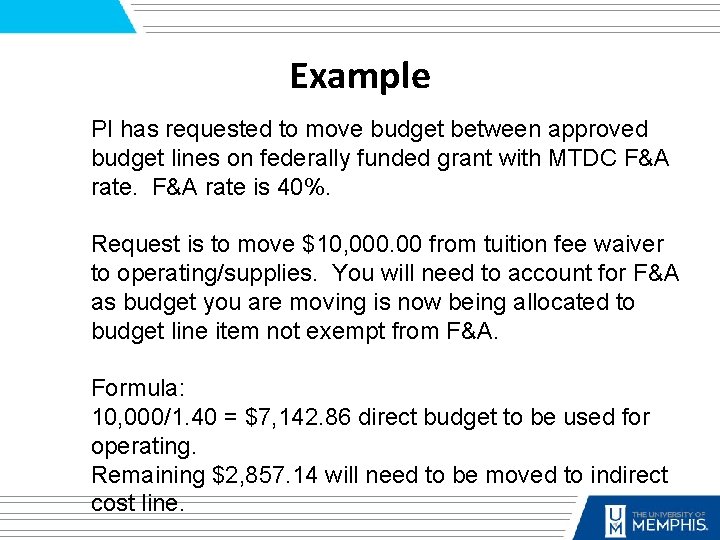
Example PI has requested to move budget between approved budget lines on federally funded grant with MTDC F&A rate is 40%. Request is to move $10, 000. 00 from tuition fee waiver to operating/supplies. You will need to account for F&A as budget you are moving is now being allocated to budget line item not exempt from F&A. Formula: 10, 000/1. 40 = $7, 142. 86 direct budget to be used for operating. Remaining $2, 857. 14 will need to be moved to indirect cost line.
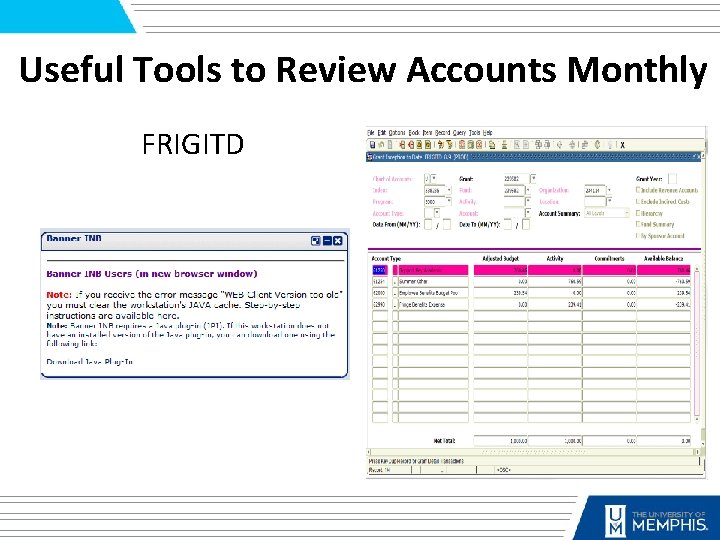
Useful Tools to Review Accounts Monthly FRIGITD
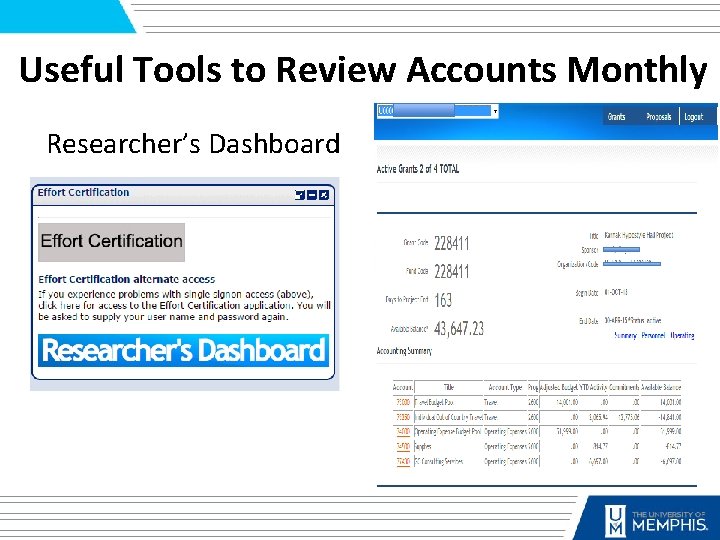
Useful Tools to Review Accounts Monthly Researcher’s Dashboard
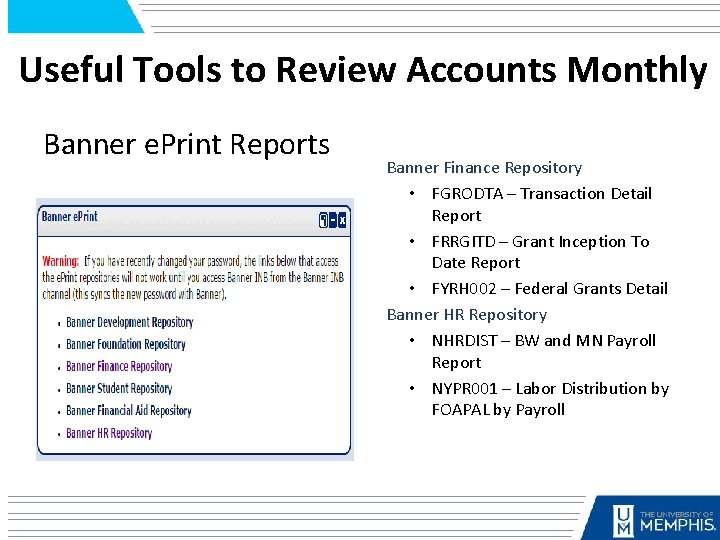
Useful Tools to Review Accounts Monthly Banner e. Print Reports Banner Finance Repository • FGRODTA – Transaction Detail Report • FRRGITD – Grant Inception To Date Report • FYRH 002 – Federal Grants Detail Banner HR Repository • NHRDIST – BW and MN Payroll Report • NYPR 001 – Labor Distribution by FOAPAL by Payroll
Allowability Test True or False Scenario #1 A federally funded research grant specializing in Sickle Cell research requires an extraordinary amount of plastic dividers and manila folders in order to keep track of the hundreds of volunteer subjects and their medical records. Answer: True Because the volume is so great and the data being collected needs to be kept confidential and separated, an unlike circumstance for the purchase of these office supplies exists
Allowability Test What is your response and why? Scenario #3 You are administering three federal research grants. The PI is the same on all awards and regularly orders lab supplies for the projects. The PI tells you that the supplies should just be charged equally to the three grants stating that during the next budget review (9 months in the future), this distribution can be reviewed and changed if funding is not available in one of the awards.
Allowability Test What is your response and why? Scenario #4 You are administering a federal research grant. A graduate student has went on a business trip which was directly related to the project and allowable. It is understood that she needed to rent a car to complete the tasks required of her on this trip. She rented a Full-size SUV.
Allocation Test What is your response and why? Scenario #5 An investigator’s federal research project will end the last day of the month and he has $10, 000 remaining. The investigator has instructed his departmental administrator to transfer expenditures from another research project, which is currently in deficit, to deplete the balance of funds. Should the administrator prepare such transfers?
Allocation Test What is your response and why? Scenario #6 Dr. Capri would like to use funds from two sponsored projects to split the cost of his equipment purchase – Project A and Project B. Project A will receive a 75% benefit from this purchase. Project B will receive a 25% benefit. Can Dr. Capri split the purchase, charging 50% to each grant since both will be utilizing the equipment and funds were budgeted in this manner?
Cost Transfers UM 1719 Charges to Sponsored Agreements
Roles of Administrator/ Business Office • • Provide guidance/assistance to Principal Investigators/Program Directors regarding the development of costs budgeted and actual costs charged; Review costs on a monthly basis for allowability, allocability, reasonableness and consistency to ensure compliance with sponsor regulations; Assist Principal Investigators with completion and submission of forms, and ensure forms have all required documentation and complete justification; and Retain all documentation and justification
It is expected that costs will be posted to the correct grant or contract at the time of purchase. However, in the event the transfer of a charge is required, the transfer should be made as soon as the need for correction is identified. Following forms are needed to transfer cost: q Salary Redistribution Form q Transfer Voucher Form
Cost transfers must: ü Be completed and submitted to the Accounting Office within 90 calendar days of the initial charge, or within a shorter time frame if mandated by the sponsor. ü Be fully documented. Documentation includes the FOAPAs affected by the change, dollar amounts, and written explanations providing reasons for change. ü Have authorized approvals. Principal Investigators and Business Officers are responsible for cost transfers to sponsored projects. The Principal Investigator must sign the Transfer Voucher form and the Salary Redistribution Request form. The Principal Investigator certifies the cost transferred is an appropriate expenditure for the sponsored agreement charged, and the expenditure complies with the terms and restrictions governing the sponsored agreement. The signature of the Chair is required on salary redistributions when the departmental recovery is reduced. The signatures of the Chair and Dean are required when a cost transfer or salary redistribution exceeds 90 calendar days of the initial charge. Grants and Contracts Accounting will review and approve cost transfers that affect a sponsored program.
Cost transfers more than 90 days old: v Will be granted only under extenuating circumstances; v Requires written explanation of why the transfer was not completed within 90 days on the Transfer Voucher and Salary Redistribution Request form(s); v Requires sponsor approval when applicable; v Requires review and approval of Department Chair and Dean; and v Requires review and approval of Grants and Contracts Accounting.
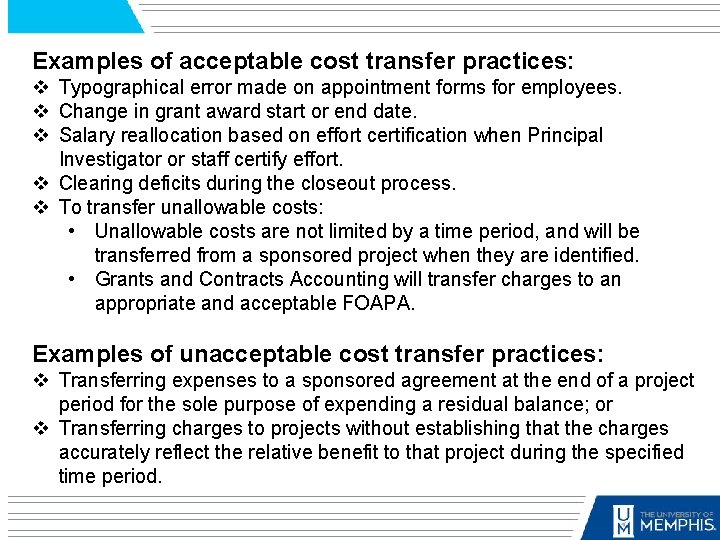
Examples of acceptable cost transfer practices: v Typographical error made on appointment forms for employees. v Change in grant award start or end date. v Salary reallocation based on effort certification when Principal Investigator or staff certify effort. v Clearing deficits during the closeout process. v To transfer unallowable costs: • Unallowable costs are not limited by a time period, and will be transferred from a sponsored project when they are identified. • Grants and Contracts Accounting will transfer charges to an appropriate and acceptable FOAPA. Examples of unacceptable cost transfer practices: v Transferring expenses to a sponsored agreement at the end of a project period for the sole purpose of expending a residual balance; or v Transferring charges to projects without establishing that the charges accurately reflect the relative benefit to that project during the specified time period.
Grants Closeout
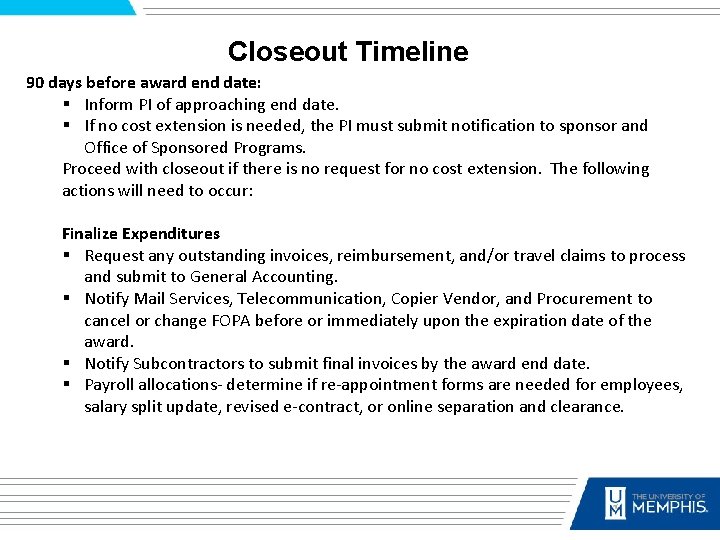
Closeout Timeline 90 days before award end date: § Inform PI of approaching end date. § If no cost extension is needed, the PI must submit notification to sponsor and Office of Sponsored Programs. Proceed with closeout if there is no request for no cost extension. The following actions will need to occur: Finalize Expenditures § Request any outstanding invoices, reimbursement, and/or travel claims to process and submit to General Accounting. § Notify Mail Services, Telecommunication, Copier Vendor, and Procurement to cancel or change FOPA before or immediately upon the expiration date of the award. § Notify Subcontractors to submit final invoices by the award end date. § Payroll allocations- determine if re-appointment forms are needed for employees, salary split update, revised e-contract, or online separation and clearance.
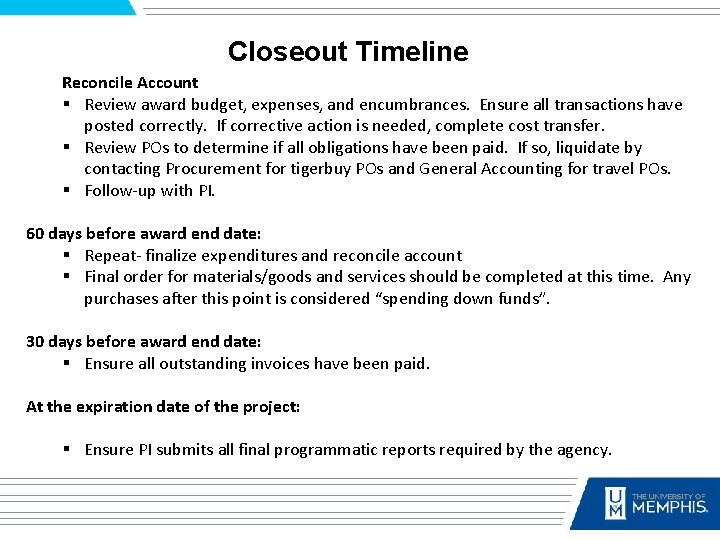
Closeout Timeline Reconcile Account § Review award budget, expenses, and encumbrances. Ensure all transactions have posted correctly. If corrective action is needed, complete cost transfer. § Review POs to determine if all obligations have been paid. If so, liquidate by contacting Procurement for tigerbuy POs and General Accounting for travel POs. § Follow-up with PI. 60 days before award end date: § Repeat- finalize expenditures and reconcile account § Final order for materials/goods and services should be completed at this time. Any purchases after this point is considered “spending down funds”. 30 days before award end date: § Ensure all outstanding invoices have been paid. At the expiration date of the project: § Ensure PI submits all final programmatic reports required by the agency.
Questions and Answers Question 1 Why doesn’t the department get to keep the balance that was not spent in a grant? Answer. Once the project ends funds are no longer available if contract is cost reimbursable, unless no cost extension is received. If contract is fixed fee depending on terms of the contract, department will receive residual balance. Question 2 A PI wants to reward students who participate in his research with tablets. How do we buy them? Can we give them cash? Answer. Purchase of a tablet is not allowable. Research participants are to receive minimal payment for time and/or gas. Reasonable payment amount is normally $25. 00. Question 3 Why does the participant supportion of an award have to be assigned a separate index? Answer. Per federal guidelines- Since participant support cost is not a normal account classification the awardee organization must be able to separately identify participant support costs. It is highly recommended that separate accounts, sub-task, or sub-ledgers be established to accumulate theses cost. Question 4 How can I find out the end date for a grant?
Questions and Answers Answer. Award notification provides the project period of the award. Also, FRAGRNT screen provides award dates. Question 5 How do I find out which accountant is assigned to my grant? Answer. Award assignments are subject to change for Grant Accountants. Please contact Grants and Contracts for current Grant Accountant assigned to your department. Question 6 Why do I need a new position number for a new grant? Answer. Each grant has its own unique FOP which requires position numbers assigned to specific FOP. Question 7 A cost share account has a negative balance. Where are the funds to cover this? Answer. Grants and Contract Accounting moves budget to cover salary for following lines: 61210, 61310, 61610. University covers benefits. All remaining budget lines are to be covered by department for pooled positions, operating, tuition.