
POLYESTER FIBER OVERVIEW AND DYNAMICS MAY 2011 Bill
POLYESTER FIBER OVERVIEW AND DYNAMICS MAY 2011 Bill Jasper, Chairman and CEO, Unifi
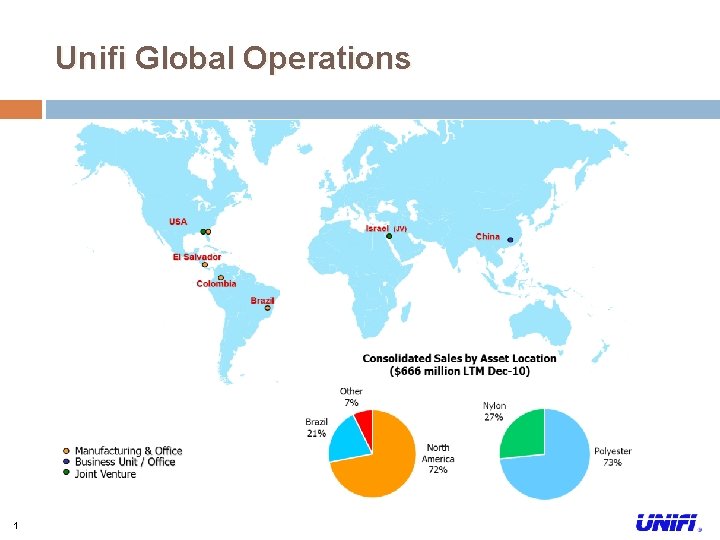
Unifi Global Operations 1
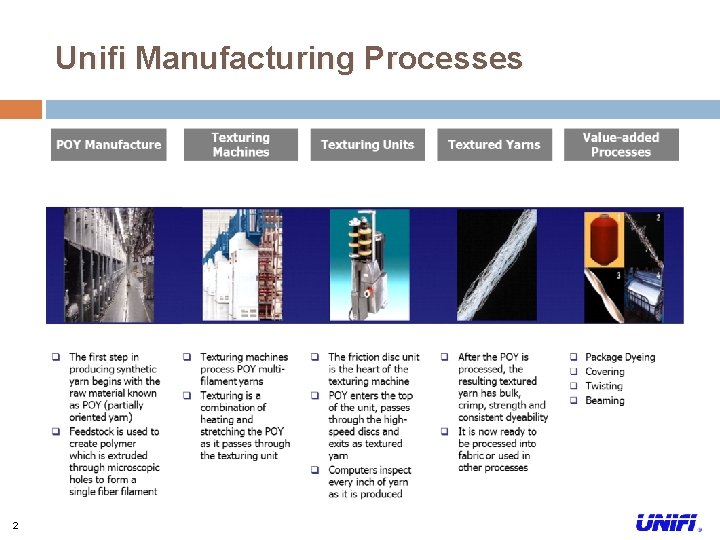
Unifi Manufacturing Processes 2
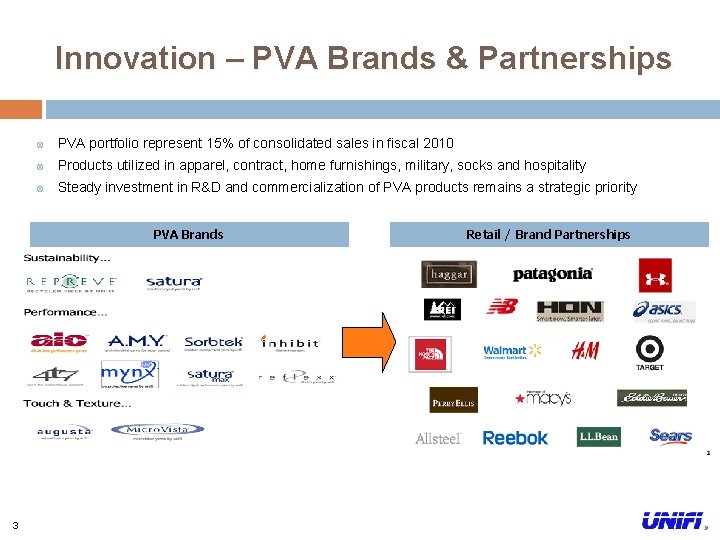
Innovation – PVA Brands & Partnerships PVA portfolio represent 15% of consolidated sales in fiscal 2010 Products utilized in apparel, contract, home furnishings, military, socks and hospitality Steady investment in R&D and commercialization of PVA products remains a strategic priority PVA Brands 3 Retail / Brand Partnerships
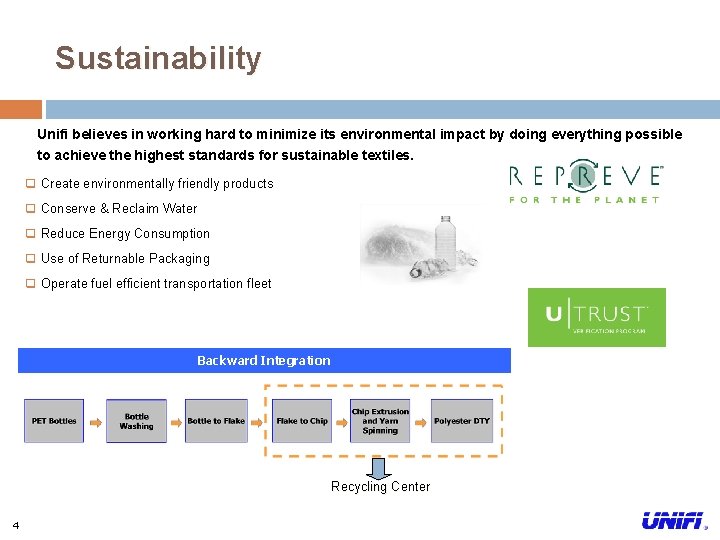
Sustainability Unifi believes in working hard to minimize its environmental impact by doing everything possible to achieve the highest standards for sustainable textiles. q Create environmentally friendly products q Conserve & Reclaim Water q Reduce Energy Consumption q Use of Returnable Packaging q Operate fuel efficient transportation fleet Backward Integration Recycling Center 4
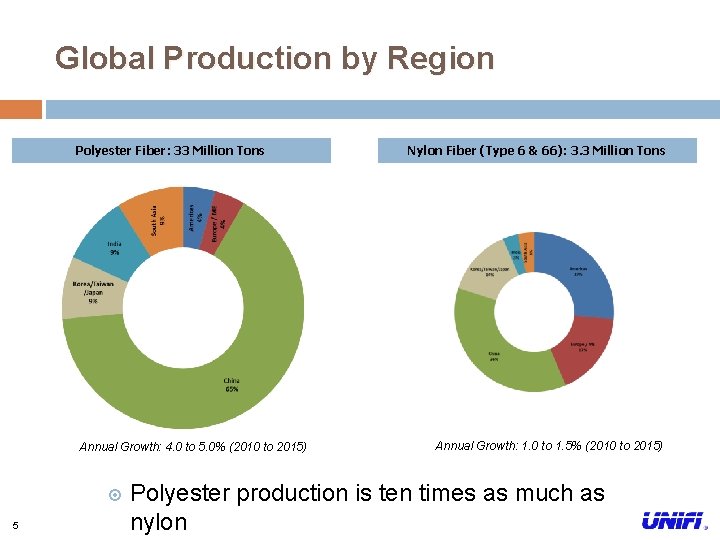
Global Production by Region Polyester Fiber: 33 Million Tons Annual Growth: 4. 0 to 5. 0% (2010 to 2015) 5 Nylon Fiber (Type 6 & 66): 3. 3 Million Tons Annual Growth: 1. 0 to 1. 5% (2010 to 2015) Polyester production is ten times as much as nylon
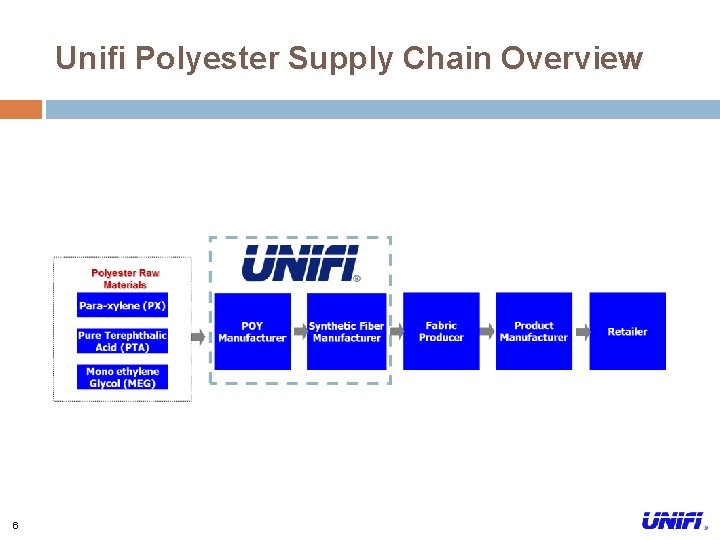
Unifi Polyester Supply Chain Overview 6
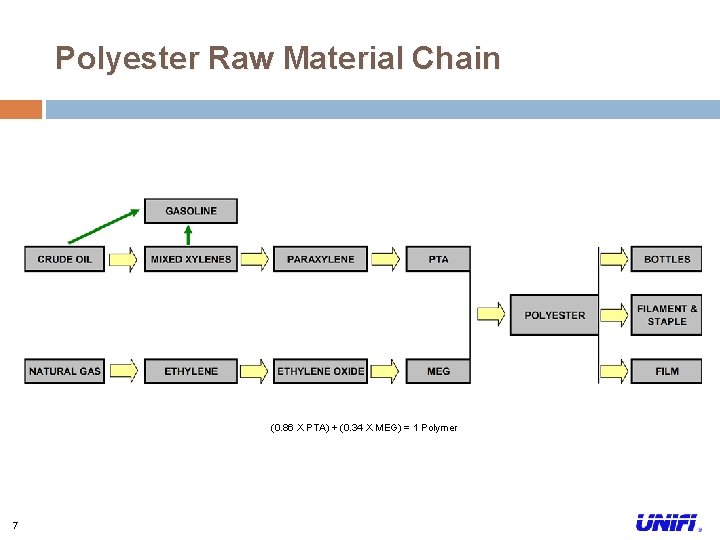
Polyester Raw Material Chain (0. 86 X PTA) + (0. 34 X MEG) = 1 Polymer 7
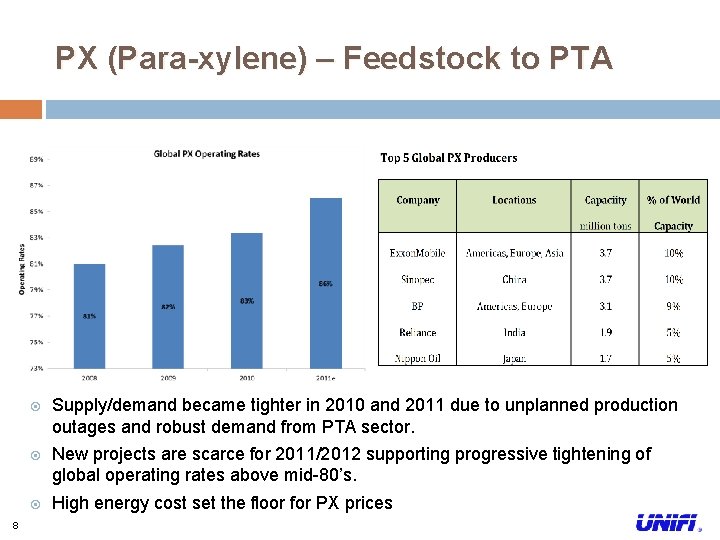
PX (Para-xylene) – Feedstock to PTA 8 Supply/demand became tighter in 2010 and 2011 due to unplanned production outages and robust demand from PTA sector. New projects are scarce for 2011/2012 supporting progressive tightening of global operating rates above mid-80’s. High energy cost set the floor for PX prices
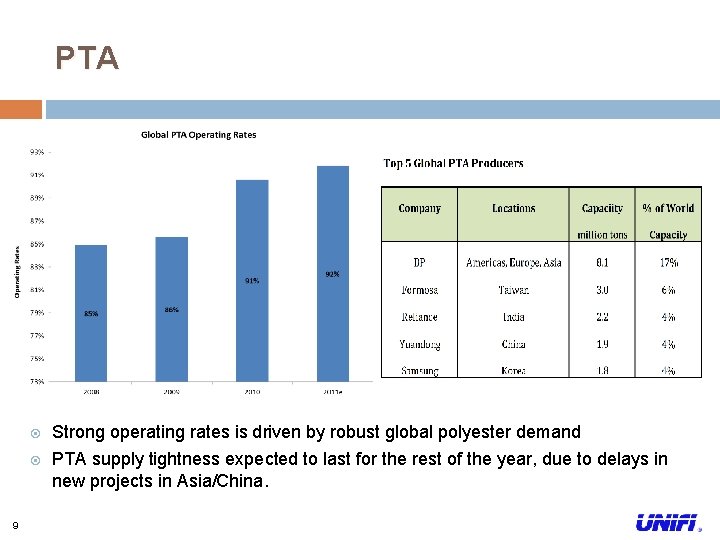
PTA 9 Strong operating rates is driven by robust global polyester demand PTA supply tightness expected to last for the rest of the year, due to delays in new projects in Asia/China.
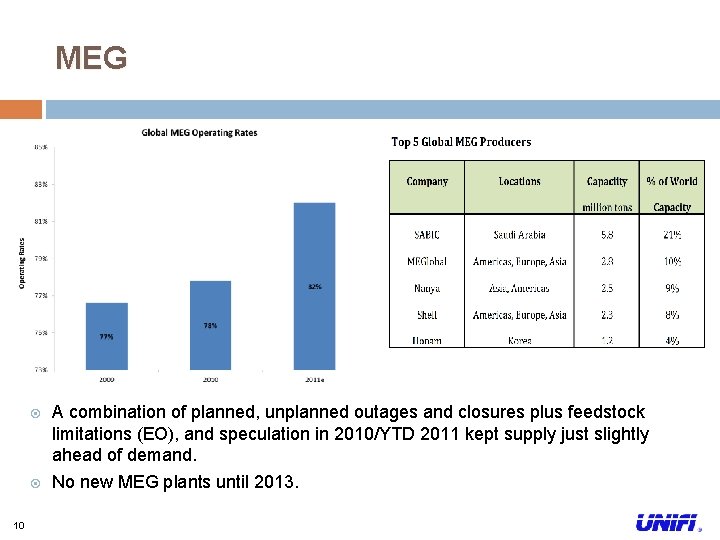
MEG 10 A combination of planned, unplanned outages and closures plus feedstock limitations (EO), and speculation in 2010/YTD 2011 kept supply just slightly ahead of demand. No new MEG plants until 2013.
Polyester Raw Material Drivers Global supply/demand of key ingredients Energy cost Crude oil Natural gas Multiple product effect 11 New plant start-ups or expansions, plant shut-downs (planned and unplanned), Inventory levels, trade flows, regional demand patterns Variety of products compete for the same molecules used by the textile polyester industry – PET bottle, anti-freeze, fertilizers, gasoline, and chemicals
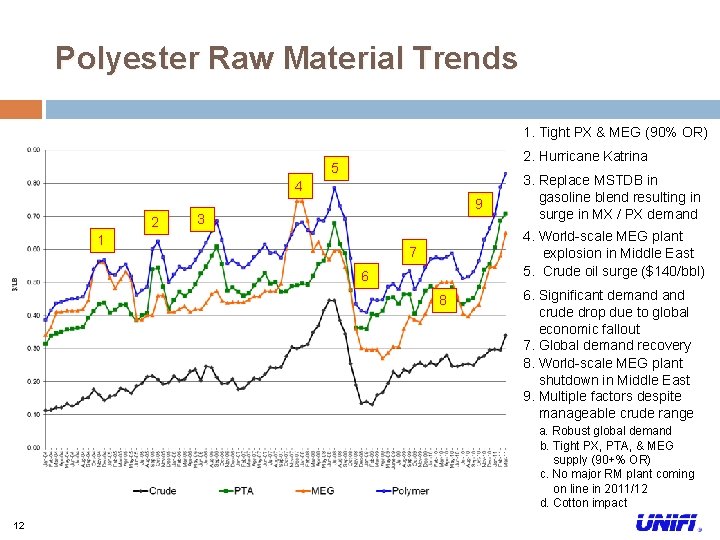
Polyester Raw Material Trends 1. Tight PX & MEG (90% OR) 2. Hurricane Katrina 5 4 2 9 3 1 3. Replace MSTDB in gasoline blend resulting in surge in MX / PX demand 4. World-scale MEG plant explosion in Middle East 5. Crude oil surge ($140/bbl) 7 6 8 6. Significant demand crude drop due to global economic fallout 7. Global demand recovery 8. World-scale MEG plant shutdown in Middle East 9. Multiple factors despite manageable crude range a. Robust global demand b. Tight PX, PTA, & MEG supply (90+% OR) c. No major RM plant coming on line in 2011/12 d. Cotton impact 12
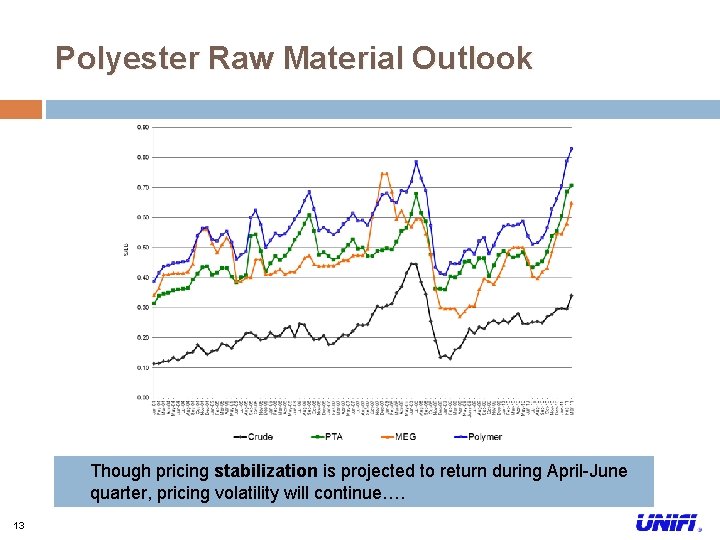
Polyester Raw Material Outlook Though pricing stabilization is projected to return during April-June quarter, pricing volatility will continue…. 13
THANK YOU!
- Slides: 15