
Philip R Merry Jr CIC AAI Hutson Etherredge
- Slides: 51
Philip R. Merry, Jr. , CIC, AAI Hutson Etherredge Companies Vice-President PO Box 419 Aiken, SC 29801 Toll Free: 888 -539 -8013 Phone: 803 -649 -5141
Insurance? What is all the fuss about?
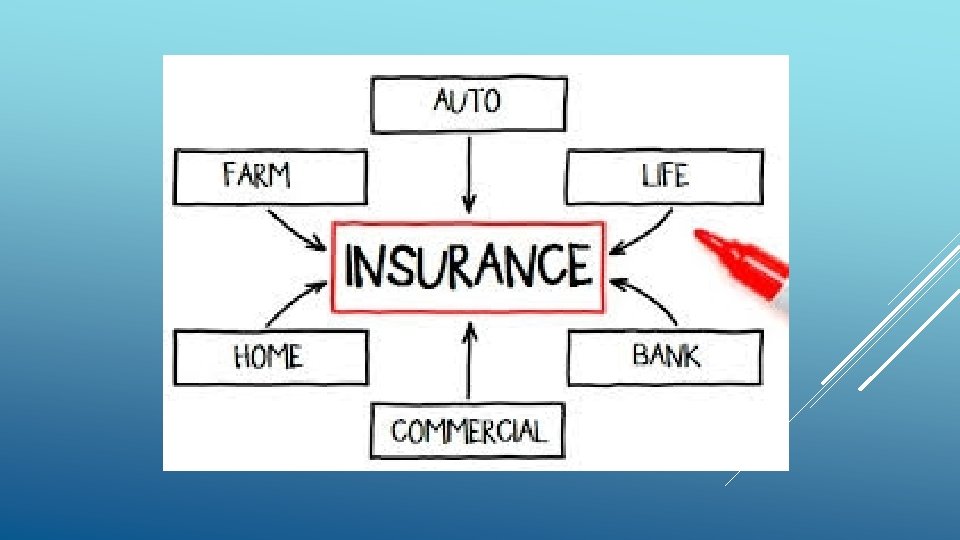
What is an Insurance Policy? Insurance is a contract in which a business entity or an individual pays an insurance company in return for the company bearing the risk of loss against certain specified conditions. The entity is “INDEMNIFIED” against losses from an insurance company as a result of a covered loss. The company pools the clients’ risks to make payments more affordable for the insured
INDEMNIFICATION? The promise to protect an individual or entity by compensating them for the precise cost of damage, loss, or injury in order to restore them to the same physical or financial condition they enjoyed prior to the indemnifiable event.
Some Types of Potential Business Losses • Property • Liability • Automobile • Professional (E&O) • Work related accidents & illnesses • Time Element • Mobile Equipment • Executive Risk • Fiduciary • Personal Injury • PII / Data / Cyber / Information Security
Property • Perils: Fire, lightning, windstorm, hail, etc. • Coverage Forms: (These dictate the covered perils) • Basic • Broad • Special • Always choose the “Special Form” -- it covers ‘all risks of direct physical loss except those perils or items specifically excluded’.
Insurable Property • Building: Structures including all permanently installed equipment • Business Personal Property: All other property owned by the business on or in the designated premises. This can be anything that is not “building coverage”. • Mobile Equipment: (Inland Marine) Any business property that is stored, used, or taken away from the insured premises. Excellent coverage! Very item and price specific…but very flexible!
Insurable Property (Cont. ) • Property of Others: Care, Custody, & Control (Bailee) • Signs: • Money & Securities: • Accounts Receivable: • Outdoor Property: • And much more:
Liability Insurance • “Loose” Definition of Liability: The state of being responsible to someone else, especially by law, as a result of an action, deed, accident, inaction, error, failure, etc. • Frequently AKA: “GENERAL LIABILITY” • One of the “best deals” in the world. You are covered for your ‘legal liability’ for almost anything…. except those things specifically excluded.
Liability Insurance • While subject to underwriting, a single General Liability policy can provide coverage for ALL of an ‘insured’s’ activities…no matter how small or how large, no matter how diverse or unrelated, and no matter how complex or how simple…. or even known or unknown • How? One policy is written and all activities of the insured business are listed (called business classes or classifications). This is the key!
Liability Insurance (Cont. ) • Classifications: Virtually any business activity imaginable has been classified and had actuarially determined rates applied. Examples: Process pipe welding in nuclear power plants. Cricket breeding. Fishing pole manufacturing. Technical Staff Augmentation. • Rating: Each class has rates assigned that are measured by a class specific “rating basis” (i. e. payroll, receipts, area, number, etc. ). • Auditable: What? ? ?
Liability Insurance (Cont. ) • Example #1: Which business is more likely to experience a liability related loss? • Plumbing Company - A: Eight years in business, 12 employees, Gross revenues of $1, 300, 000. Eight trucks. Annual payroll of $660, 000. • Plumbing – B: Twenty one years in business. Annual payroll of $405, 000 for 9 employees. Six trucks and gross revenues of $800, 000. • Which Company should pay the higher premium?
Liability Insurance (Cont. ) • Example #2: Which business is more likely to experience a liability related loss? • Cookie Company - A: 99 years in business, 90 employees, Gross revenues of $11, 000. Annual payroll of $3, 400, 000 over three locations. • Cookie Company – B: Fifteen years in business. Annual payroll of $2, 750, 000 for 55 employees. One location and revenues of $12, 000. • Which Company should pay the higher premium?
Property & Liability = PACKAGE POLICY Other Underwriting Considerations: • Owner’s prior Experience in business. • Owner’s prior Experience in the same field. • General housekeeping, risk management, business practices, etc. • Prior Claims experience: (Usually 3 -5 years) • Desirability of business class, location, age & updates of property, and MUCH more!
Inland Marine / Mobile Equipment • Miscellaneous Tools & Equipment. • Scheduled Contractors Equipment. • Builder’s Risk. • EDP – Electronic Data Processing Equipment. • Rented or Leased Equipment. • Cargo • Anything that may be transported.
Commercial Automobile • Similar, but different from personal auto policy. • For vehicles owned by or used in business for: Delivery/Transport – Veh. in constant use. Inherent to business. Service – Vehicles may sit as much as they travel. Used in the business operations at point of service (at customer’s site). Sales – Typically high mileage. Not used in delivery of product. • Liability Coverage - Symbol #1)? • Physical Damage – Comprehensive & Collision • Hired & Non-Owned Automobile • Cargo & Special Equipment
Professional – Errors & Ommissions • Many businesses at risk. Most common for those who do design work, write specifications, use ‘judgement’ or ‘advise’, write contracts or custom documents, anyone with special education or training. • Examples: Doctors, Lawyers, Architects, Engineers, Plumbers, HVAC Contractors, Real Estate Agents, Insurance Agents, etc.
Workers’ Compensation • Statutory • Required by state law when business has 4 or more employees – INCLUDING the owner. • Purchase of a W/C policy removes business from the “Tort” system but sets statutory system of compensation. • Accident – Injury – Illness • What does it pay? Medical Expenses Lost wages/income Death or Disability
Workers’ Compensation (Cont. ) • Similar Underwriting Analysis. • Similar (but different) class codes. • Based on payroll – “per hundred” • Multiple Classes can be on one policy. • The higher the risk, the higher the rate. • Clerical = Low Rate. Roofing = High Rate • Experience Rated = “Experience Mod” • Auditable
Time Element Coverage – Business Income • Pays for loss of “income” as a result of a COVERED cause of loss. (Ex. Fire damage). • Many expenses go on even if business is effected. • May be purchased with specific limit for a specific length of time. • Best = 12 months - Actual Loss Sustained • Not expensive.
Umbrella • All of the Above!! (Liability/Casualty coverages) • Limits available in increments of $1 M per step. • Usually much lower cost relative to primary Liability. • Requires certain limits from underlying policies.
Other Coverages: • Executive Risk – Directors & Officers Management Liability Employment Practices Liability – Important & Growing • Fiduciary Liability – Employee Benefits Liability - Important Crime Bonds See Data/Cyber/Information Security
Other Coverages: • Personal & Advertising Injury – Usually Included in GL Libel Slander False arrest Damage to reputation or brand (‘advertising injury’) Some defense for discrimination • Certain businesses (media, printers, writers, etc. ) may need to address this more specifically.
Cyber / Data / Information Security • Fastest growing area of loss. • Fastest growing amplification of claims = Big $$ • Identity theft • Credit Card Information • Personally Identifiable Information • Federal laws for notification & indemnification. • Can be unexpectedly VERY expensive. • Examples: doctors, hotels, retailers, accountants, etc.
Miscellaneous: • What is ALMOST as important as insurance and should be done first? ___________ • Insurance Distribution Channels: Online Direct Writer Independent Agent – Yay!! • Accidents happen (by definition) when you don’t expect or intend them. • You can be sued for anything, anytime. It’s getting worse!!
Questions: