
PayforPerformance Incentive Rewards The Challenges of Human Resources
- Slides: 52
Pay-for-Performance: Incentive Rewards The Challenges of Human Resources Management © 2012 Cengage Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in part, except for use as permitted in a license distributed with a certain product or service or otherwise on a password-protected website for classroom use. 1– 1
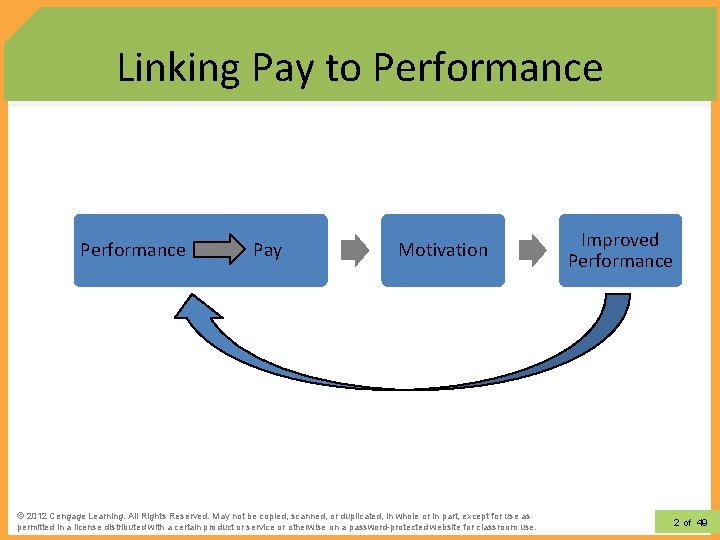
Linking Pay to Performance Pay Motivation © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for Improved Performance 2 of 49 36
Pay for Performance 12– 3 © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 3 of 49 36
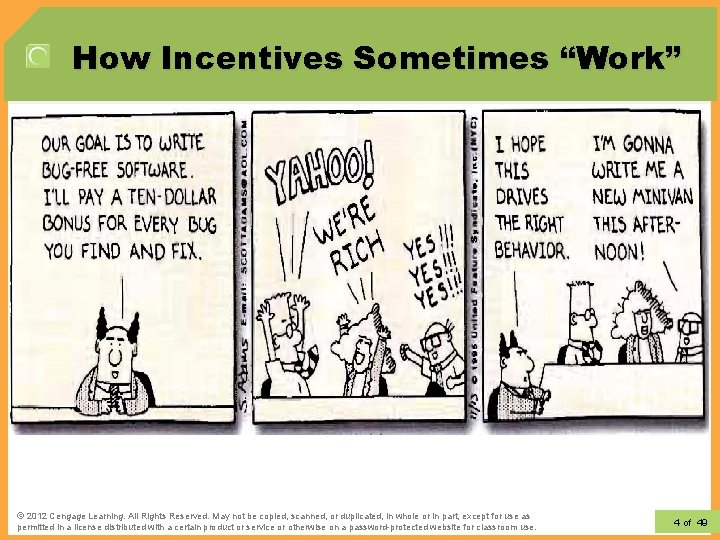
How Incentives Sometimes “Work” © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 4 of 49 36
Employee Opposition to Incentive Plans • Production standards are set unfairly. • Incentive plans are really “work speedup. ” • Incentive plans create competition among workers. • Increased earnings result in tougher standards. • Payout formulas are complex and difficult to understand. • Incentive plans cause friction between employees and management. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 5 of 49 36
Incentive Plans as Links to Organizational Objectives • Incentive Plan Purposes § Encourage employees to assume “ownership” of their jobs, thereby improving effort and job performance. § Motivate employees to expend more effort than under hourly and/or seniority-based compensation systems. § Support a compensation strategy to attract and retain top-performing employees. • Incentive Plan Effectiveness § There is evidence of a relationship between incentive plans and improved organizational performance. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 6 of 49 36
Requirements for a Successful Plan § § Identify important organizational metrics that encourage employee behavior. Involve employees. Incentive programs should seem fair to employees. Find the right incentive payout. Payout formulas should be simple and understandable. Establish a clear link between performance and payout. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 7 of 49 36
Why Incentive Plans Fail § They fail to meet employee expectations for pay gains. § There is confusion about incentive payment calculations due to poor design and implementation of the plan. § Employees do not have the capability to change their performance levels. § The organization environment does not support plan. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 8 of 49 36
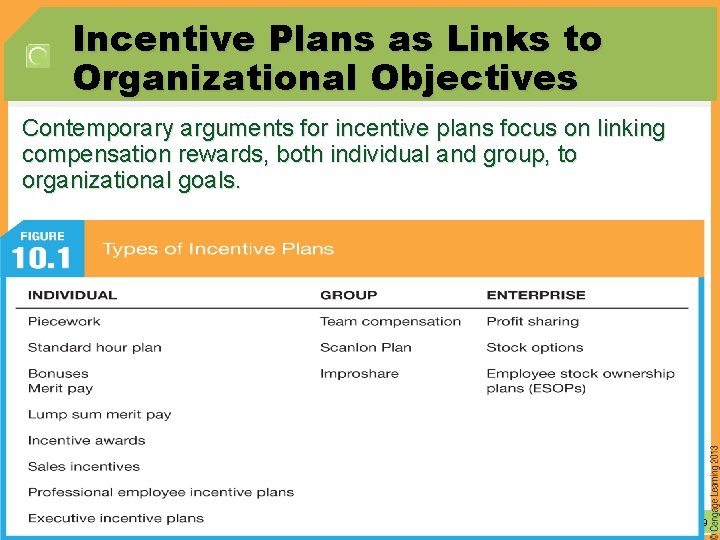
Incentive Plans as Links to Organizational Objectives Contemporary arguments for incentive plans focus on linking compensation rewards, both individual and group, to organizational goals. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 9 of 49 36
Individual Incentive Plans • Straight Piecework § An incentive plan under which employees receive a certain rate for each unit produced. • Differential Piece Rate § A compensation rate under which employees whose production exceeds the standard amount of output receive a higher rate for all of their work than the rate paid to those who do not exceed the standard amount. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 10 of 49 36
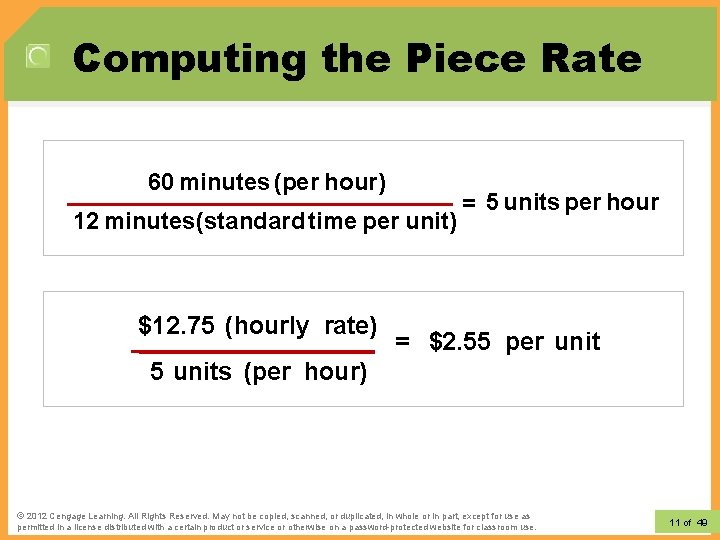
Computing the Piece Rate 60 minutes (per hour) 12 minutes(standard time per unit) $12. 75 (hourly rate) = 5 units per hour = $2. 55 per unit 5 units (per hour) © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 11 of 49 36
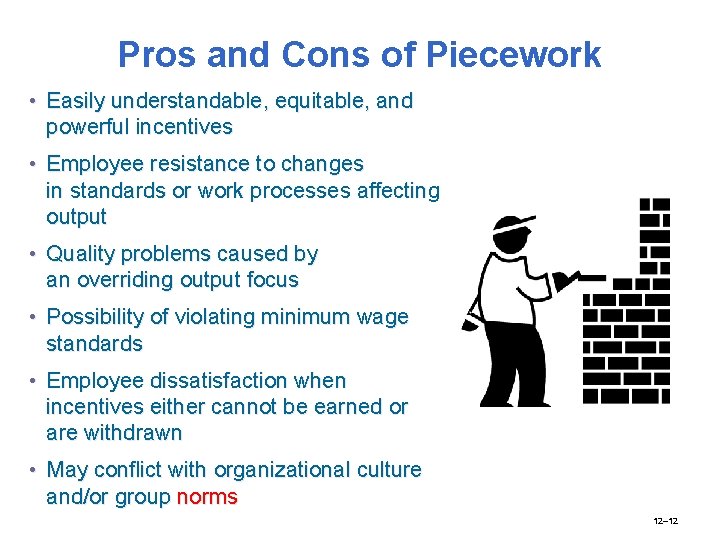
Pros and Cons of Piecework • Easily understandable, equitable, and powerful incentives • Employee resistance to changes in standards or work processes affecting output • Quality problems caused by an overriding output focus • Possibility of violating minimum wage standards • Employee dissatisfaction when incentives either cannot be earned or are withdrawn • May conflict with organizational culture and/or group norms 12– 12
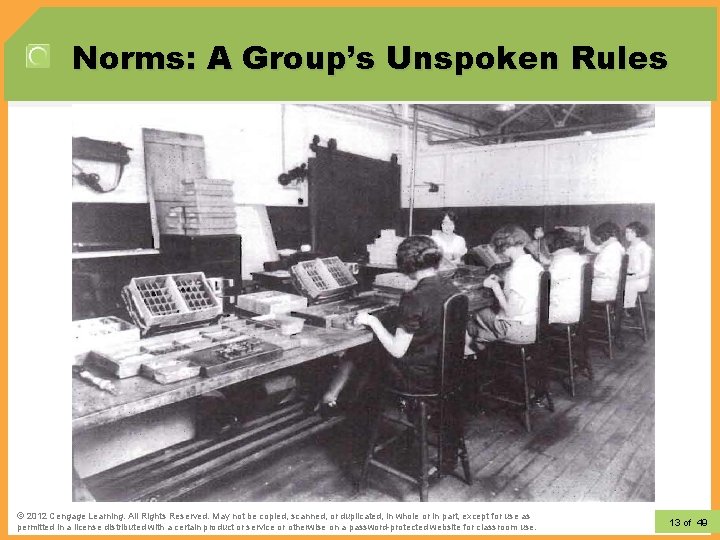
Norms: A Group’s Unspoken Rules © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 13 of 49 36
Individual Incentive Plans (cont’d. ) • Standard Hour Plan § § An incentive plan that sets pay rates based on the completion of a job in a predetermined “standard time. ” If employees finish the work in less than the expected time, their pay is still based on the standard time for the job multiplied by their hourly rate. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 14 of 49 36
Individual Incentive Plans (cont. ) • Bonus § Incentive payment that is supplemental to the base wage for cost reduction, quality improvement, or other performance criteria. • Spot bonus § Unplanned bonus given for employee effort unrelated to an established performance measure. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 15 of 49 36
Merit Pay • Merit Pay Program (Merit Raise) § Links an increase in base pay to how successfully an employee achieved some objective performance standard. • Merit Guidelines § Guidelines for awarding merit raises that are tied to performance objectives. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 16 of 49 36
Merit Pay and Motivation • Evidence suggests that merit raises of 10 -15% motivate changes in behavior. • Typical merit raises range from 2 -6% • Rewards are motivating if: – They are timely – They are public rather than secret – They are scarce rather than common © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 17 of 49 36
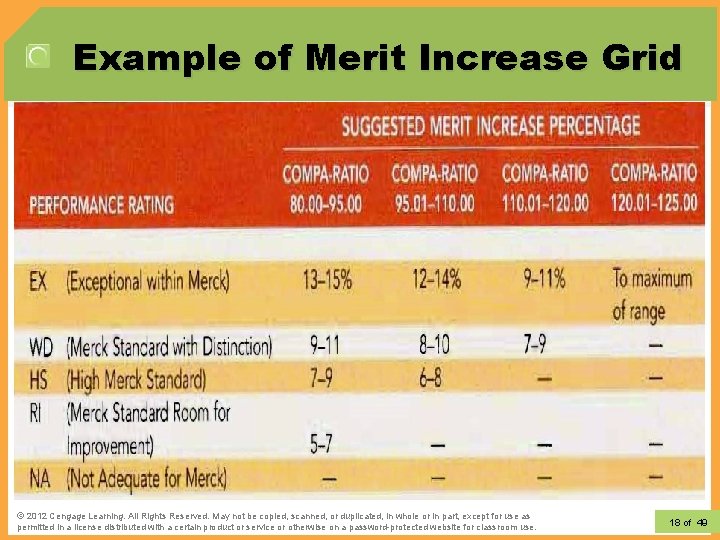
Example of Merit Increase Grid © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 18 of 49 36
Lump-Sum Merit Pay • Lump-Sum Merit Program – Program under which employees receive a year-end merit payment, which is not added to base pay. – Advantages: • Provides financial control by maintaining annual salary expenses and not escalating base salary levels. • Contains employee benefit costs for levels of benefits normally calculated from current salary levels. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 19 of 49 36
Problems with Merit Raises 1. Money for merit increases may be inadequate to satisfactorily raise all employees’ base pay. 2. Managers may have no guidance in how to define and measure performance; there may be vagueness regarding merit award criteria. 3. Employees may not believe that their compensation is tied to effort and performance; they may be unable to differentiate between merit pay and other types of pay increases. 4. Employees and their managers may hold different views of the factors that contribute to job success. 5. Merit pay plans may create feelings of pay inequity. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 20 of 49 36
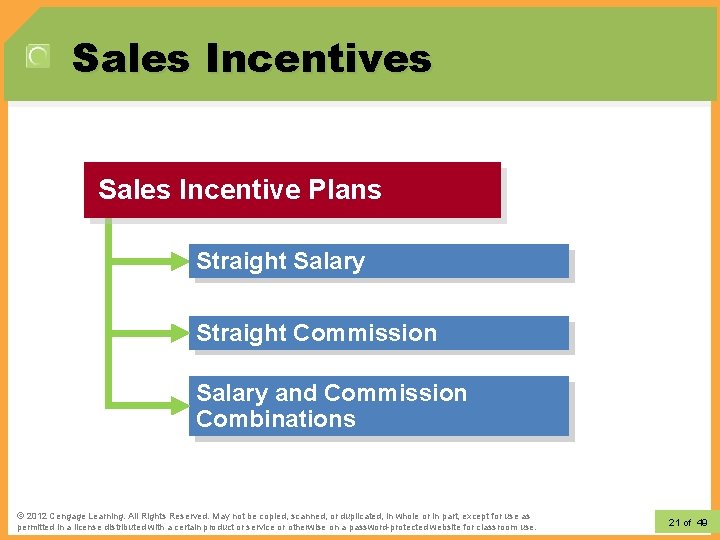
Sales Incentives Sales Incentive Plans Straight Salary Straight Commission Salary and Commission Combinations © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 21 of 49 36
Incentive Plans for Salespersons • Straight Salary Plan § Compensation plan that permits salespeople to be paid for performing various duties that are not reflected immediately in their sales volume. § Advantages: – Encourages building customer relationships. – Provides compensation during periods of poor sales. § Disadvantage: – May not provide sufficient motivation for maximizing sales volume. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 22 of 49 36
Incentive Plans for Salespersons (cont. ) • Straight Commission Plan § Compensation plan based upon a percentage of sales. – Draw is a cash advance that must be paid back as commissions are earned. § Disadvantages: – Salespeople will stress high-priced products. – Customer service after the sale is likely to be neglected. – Earnings tend to fluctuate widely between good and poor periods of business, an turnover of trained sales employees tends to increase in poor periods. – Salespeople are tempted to grant price concessions. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 23 of 49 36
Incentive Plans for Salespersons (cont. ) • Combined Salary and Commission Plan § A compensation plan that includes a straight salary and a commission component (“leverage”). § Advantages: – Combines the advantages of straight salary and straight commission forms of compensation. – Offers greater design flexibility – Can be used to develop the most favorable ratio of selling expense to sales. – Motivates sales force to achieve specific company marketing objectives in addition to sales volume. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 24 of 49 36
Group/Team Incentive Plans • Team Incentive Plans § Compensation plans where all team members receive an incentive bonus payment when production or service standards are met or exceeded. • Establishing Team Incentive Payments § § § Set performance measures upon which incentive payments are based Determine the size of the incentive bonus. Create a payout formula and fully explain to employees how payouts will be distributed. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 25 of 49 36
Team Incentive Plans • Advantages § Team incentives support group planning and problem solving, thereby building a team culture. § The contributions of individual employees depend on group cooperation. § Team incentives can broaden the scope of the contribution that employees are motivated to make. § Team bonuses tend to reduce employee jealousies and complaints over “tight” or “loose” individual standards. § Team incentives encourage cross-training and the acquiring of new interpersonal competencies. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 26 of 49 36
Team Incentive Plans (cont. ) • Disadvantages § Individual team members may perceive that “their” efforts contribute little to team success or to the attainment of the incentive bonus. § Intergroup social problems—pressure to limit performance and the “free-ride” effect may arise. § Complex payout formulas can be difficult for team members to understand. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 27 of 49 36
Team Incentive Plans (cont. ) • Gainsharing Plans § Programs under which both employees and the organization share the financial gains according to a predetermined formula that reflects improved productivity and profitability. • Increase in productivity is gained when: § § Greater output is obtained with less or equal input. Equal production output is obtained with less input. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 28 of 49 36
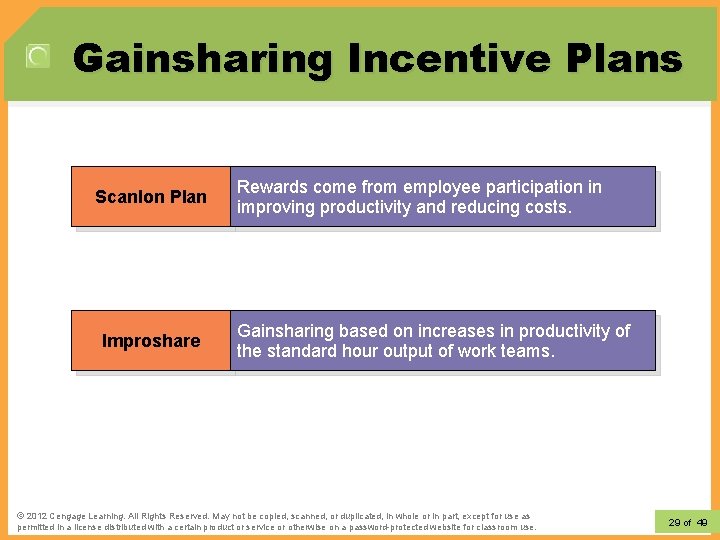
Gainsharing Incentive Plans Scanlon Plan Improshare Rewards come from employee participation in improving productivity and reducing costs. Gainsharing based on increases in productivity of the standard hour output of work teams. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 29 of 49 36
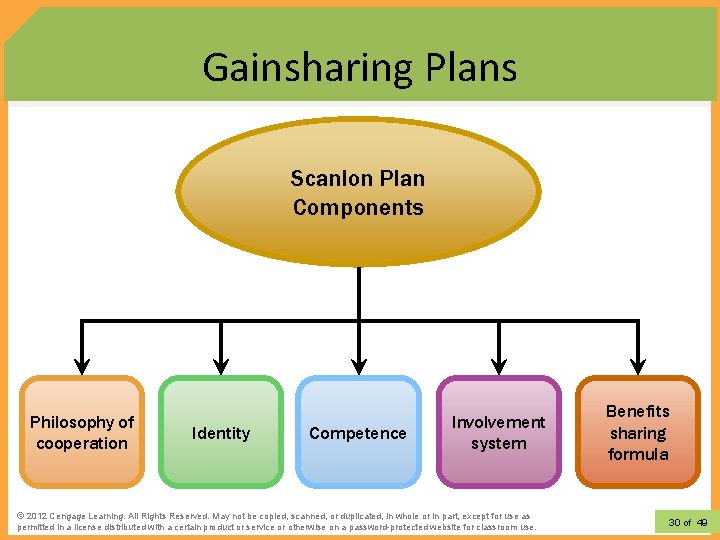
Gainsharing Plans Scanlon Plan Components Philosophy of cooperation Identity Competence Involvement system © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for Benefits sharing formula 30 of 49 36
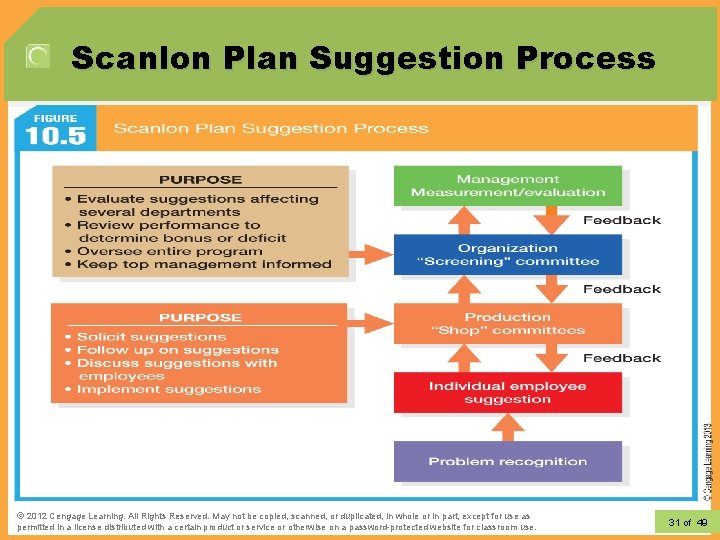
Scanlon Plan Suggestion Process © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 31 of 49 36
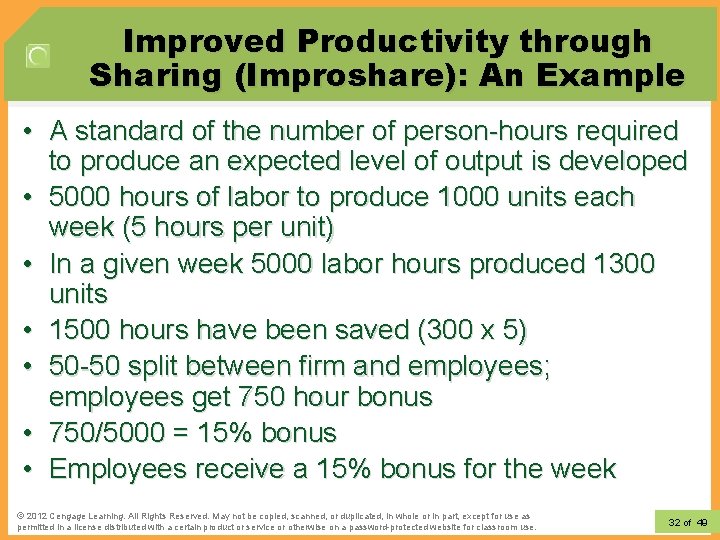
Improved Productivity through Sharing (Improshare): An Example • A standard of the number of person-hours required to produce an expected level of output is developed • 5000 hours of labor to produce 1000 units each week (5 hours per unit) • In a given week 5000 labor hours produced 1300 units • 1500 hours have been saved (300 x 5) • 50 -50 split between firm and employees; employees get 750 hour bonus • 750/5000 = 15% bonus • Employees receive a 15% bonus for the week © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 32 of 49 36
Enterprise Incentive Plans • Profit Sharing § Any procedure by which an employer pays, or makes available to all regular employees, in addition to their base pay, current or deferred sums based upon the profits of the enterprise. § Deferred profit-sharing plans – A predetermined portion of profits based on the employee’s contribution to the firm’s profits is placed in each employee’s retirement account under a trustee’s supervision. – Employees’ income taxes on the distributions are deferred, often until the employee retires. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 33 of 49 36
Enterprise Incentive Plans Profit Sharing Challenges • Agreement over the percentages of shared of profits and the forms of distribution (cash or deferred) of profits between company and employees • Annual variations and possibility of no payout due to financial condition of company • Maintaining motivational connection of profitsharing to performance of employees © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 34 of 49 36
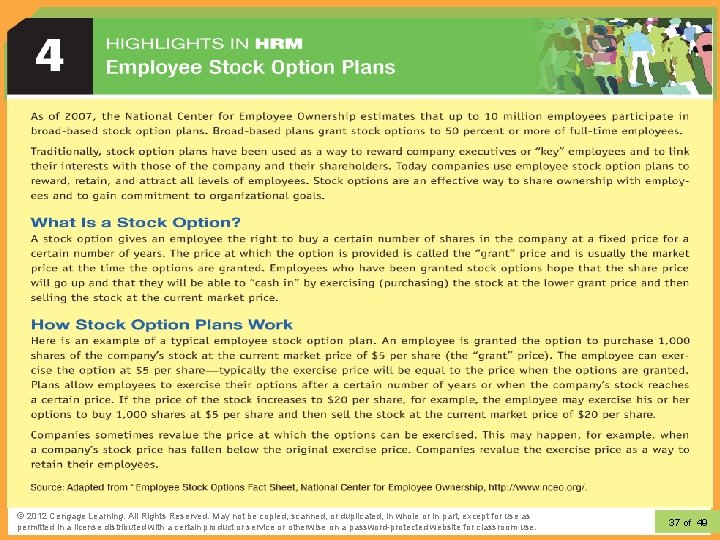
Enterprise Incentive Plans (cont. ) • Stock Options § § Granting employees the right to purchase a specific number of shares of the company’s stock at a guaranteed price (the option price) during a designated time period. The value of an option is subject to stock market conditions at the time that option is exercised. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 35 of 49 36
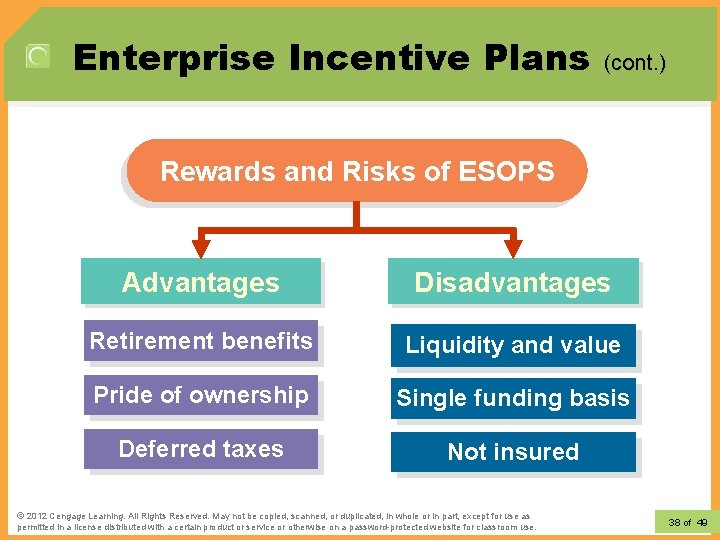
Enterprise Incentive Plans (cont. ) • Employee Stock Ownership Plans (ESOPs) § Stock plans in which an organization contributes shares of its stock to an established trust for the purpose of stock purchases by its employees. – The employer establishes an ESOP trust that qualifies as a tax-exempt employee trust under Section 401(a) of the Internal Revenue Code – Stock bonus plans are funded by direct employer contributions of its stock or cash to purchase its stock. – Leveraged plans are funded by employer borrowing to purchase its stock for the ESOP. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 36 of 49 36
© 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 37 of 49 36
Enterprise Incentive Plans (cont. ) Rewards and Risks of ESOPS Advantages Disadvantages Retirement benefits Liquidity and value Pride of ownership Single funding basis Deferred taxes Not insured © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 38 of 49 36
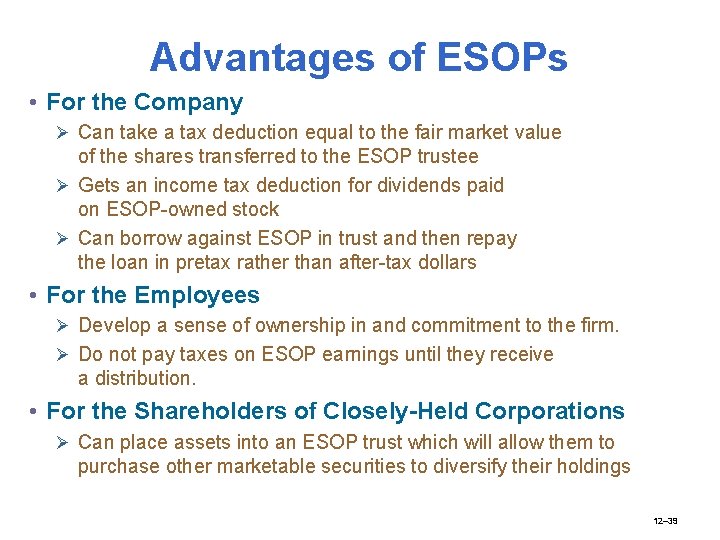
Advantages of ESOPs • For the Company Ø Can take a tax deduction equal to the fair market value of the shares transferred to the ESOP trustee Ø Gets an income tax deduction for dividends paid on ESOP-owned stock Ø Can borrow against ESOP in trust and then repay the loan in pretax rather than after-tax dollars • For the Employees Ø Develop a sense of ownership in and commitment to the firm. Ø Do not pay taxes on ESOP earnings until they receive a distribution. • For the Shareholders of Closely-Held Corporations Ø Can place assets into an ESOP trust which will allow them to purchase other marketable securities to diversify their holdings 12– 39
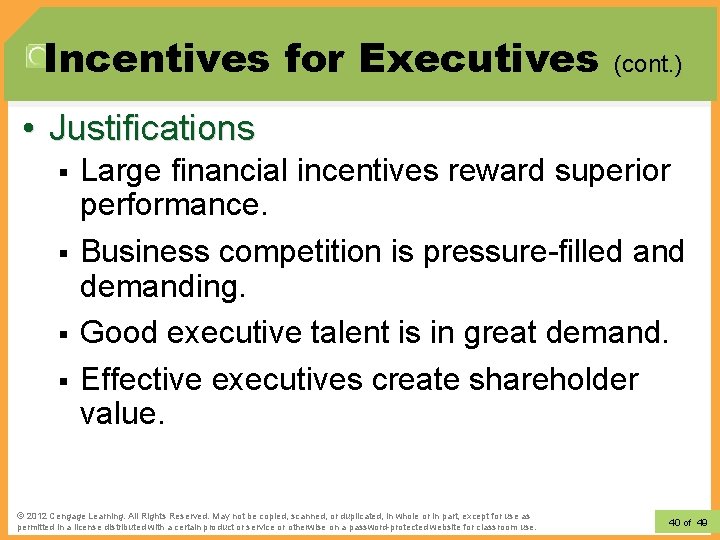
Incentives for Executives (cont. ) • Justifications § § Large financial incentives reward superior performance. Business competition is pressure-filled and demanding. Good executive talent is in great demand. Effective executives create shareholder value. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 40 of 49 36
Incentives for Executives • The Executive Pay Package § § § Base salary Short-term incentives or bonuses Long-term incentives or stock plans Benefits Perquisites (perks) © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 41 of 49 36
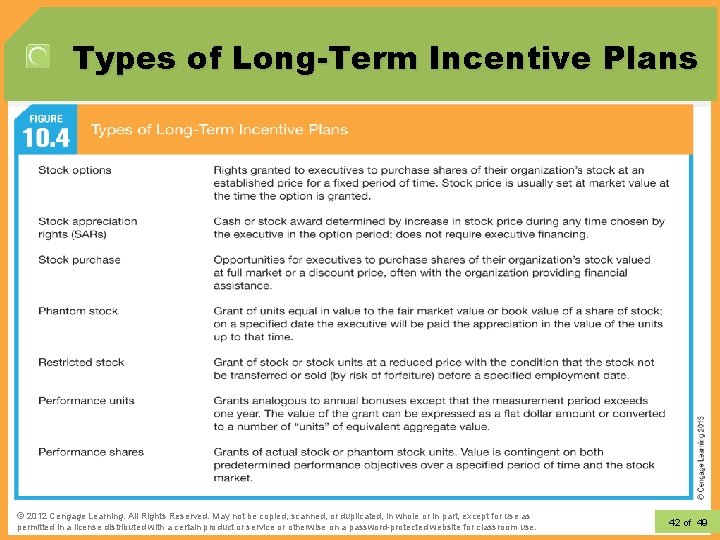
Types of Long-Term Incentive Plans © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 42 of 49 36
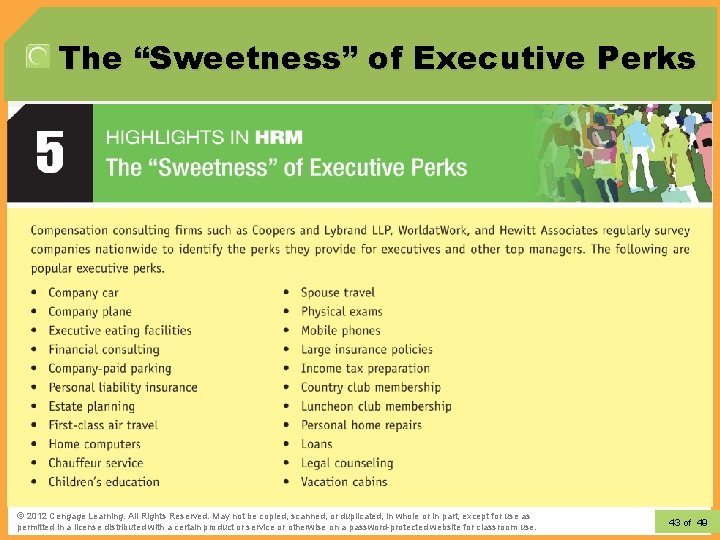
The “Sweetness” of Executive Perks © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 43 of 49 36
Executive Compensation Reform • Current Reform Measures § The Internal Revenue Service (IRS) is looking for taxcode violations in executive pay packages and will make executive pay a part of corporate audits. § The Securities and Exchange Commission issued pay disclosure rules which require companies listed on the New York Stock Exchange and NASDAQ to disclose the true size of their top executive pay packages. § The Financial Accounting Standards Board (FASB) now requires that stock options be recognized as an expense on income statements. © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 44 of 49 36
Executive Compensation Reform (cont. ) • Other Reform Measures: § The adoption of performance formulas that peg executive compensation to organizational benchmarks other than stock price § Shareholder resolutions that allow shareholders the right to vote on executive pay packages § Greater accountability by compensation committees to justify large executive pay awards or severance or retirement packages © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 45 of 49 36
Pay for Performance? ? ? • Give Me a Break: Big Bucks for Execs as Companies Flounder • Nardelli out at Home Depot © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 46 of 49 36
Nonfinancial and Recognition Awards • Effects of Recognition-Based Awards – Recognition has a positive impact on performance, either alone or in conjunction with financial rewards. – Day-to-day recognition from supervisors, peers, and team members is important. • Ways to Use Recognition – Social recognition – Performance-based recognition – Performance feedback © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 47 of 49 36
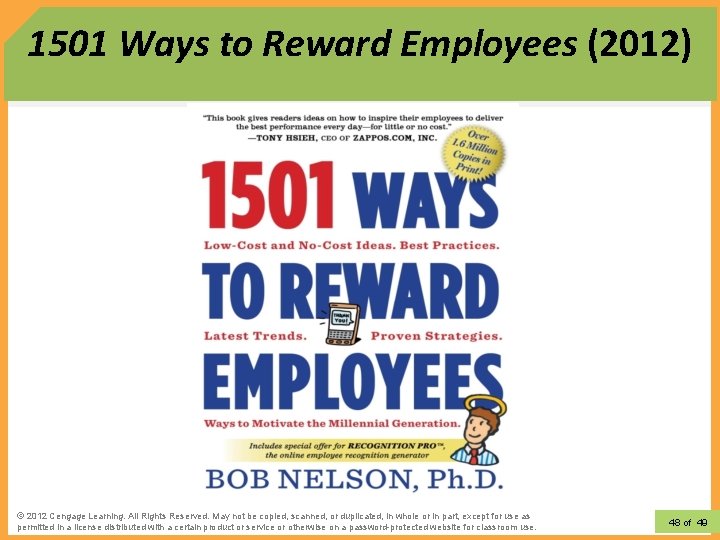
1501 Ways to Reward Employees (2012) © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 48 of 49 36
Social Recognition and Related Positive Reinforcement Managers Can Use • Challenging work assignments • Freedom to choose own work activity • Being provided with ample encouragement • Being allowed to set own goals • Having fun built into work • Compliments • More of preferred task • Expression of appreciation in front of others • Role as boss’s stand-in when he or she is away • Note of thanks • Role in presentations to top management • Employee-of-the-month award • Job rotation • Bigger desk • Encouragement of learning and continuous improvement • Bigger office or cubicle • Special commendation © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 49 of 49 36
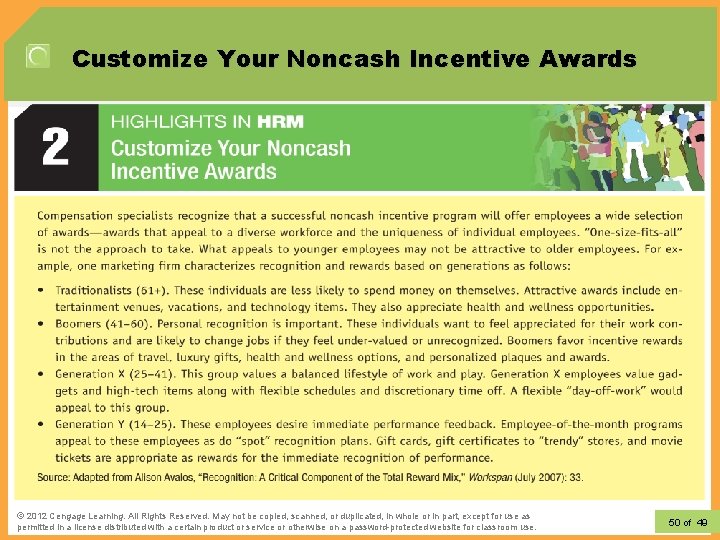
Customize Your Noncash Incentive Awards © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 50 of 49 36
Punished by Rewards (1999) • Punished by Rewards • Intrinsic v. extrinsic motivation © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 51 of 49 36
Intrinsic Motivation and Creativity • The issue of whether reward decreases or increases intrinsic interest and creativity is relevant to organizations because creative contributions help organizations become more efficient, adapt to change, and develop new products and services • http: //www. psychology. uh. edu/faculty/Eise nberger/IMC. html 12– 52 © 2012 Learning. All Rights Reserved. May not be copied, scanned, or duplicated, in whole or in except useexcept as © 2012 Cengage Learning. All Rights Reserved. May not be copied, or duplicated, in part, whole or infor part, for use as permitted distributed with a certain product or service or otherwise on a password-protected website for classroom use. permittedinina alicense distributed a certain product or service or otherwise on a password-protected website for 52 of 49 36