
Page 245 National Collection Standards Form 433 is
- Slides: 58
Page 245 National Collection Standards Form 433 is a part of the collection process that is slowly disappearing: 2012 Fresh Start Changes installment agreement process reducing or eliminating financial disclosure for accounts as large as $50, 000 ü 2017 IRS is testing higher and more relaxed disclosure and installment agreement streamlining for as much as $100, 000 ü Reality – OIC, CNC, and cases larger than $100, 000 are normally cases requiring Form 433 ü 1 10: Collection Information Statements
Page 245 National Collection Standards A minimum, maximum, or suggested amount as established by the Bureau of Labor Statistics Consumer Expenditure Survey Difficult to administer with IRS staff that has limited training. 2 10: Collection Information Statements
Page 245 National Collection Standards Working a Collection Information Statement (Form Series 433) can be almost as contentious as an exam The taxpayer will be asked to prove their necessary living expenses AND To the extent those expenses exceed the national standards substantiate that those expenses are reasonable 3 10: Collection Information Statements
Page 245 National Collection Standards The statutory, streamlined, and now the current test agreements that can be for debts up to $100, 000 mean that IRS is trying to limit its financial disclosure cases. 10: Collection Information Statements 4
Page 245 -248 The Allowable Expenses IRM 5. 8. 5. 20 The Internal Revenue Manual will be the playbook for determination of most cases IRM 5. 8. 5. 22. 1 – Necessary Expenses – Food, Clothing, Supplies, Etc. and Production of Income IRM 5. 8. 5. 22. 2 – Housing & Utilities IRM 5. 8. 5. 22. 3 – Transportation IRM 5. 8. 5. 22. 4 – Other – A collection of items of various character and nature 5 10: Collection Information Statements Change
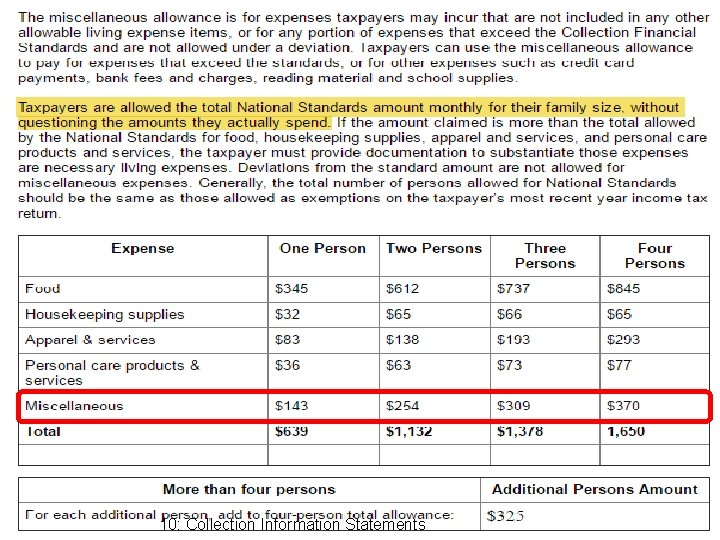
Page 245 The Allowable Expenses IRM 5. 8. 5. 20 IRM 5. 8. 5. 22. 1 – Necessary Expenses – Food, Clothing, Supplies, Etc. 2) Table amounts for necessary expenses are allowed without verification 3) Table amounts are guidelines § Allow taxpayers deviations if they are reasonable and § The taxpayer provides substantiation and § The reason can be documented in the file 6 10: Collection Information Statements
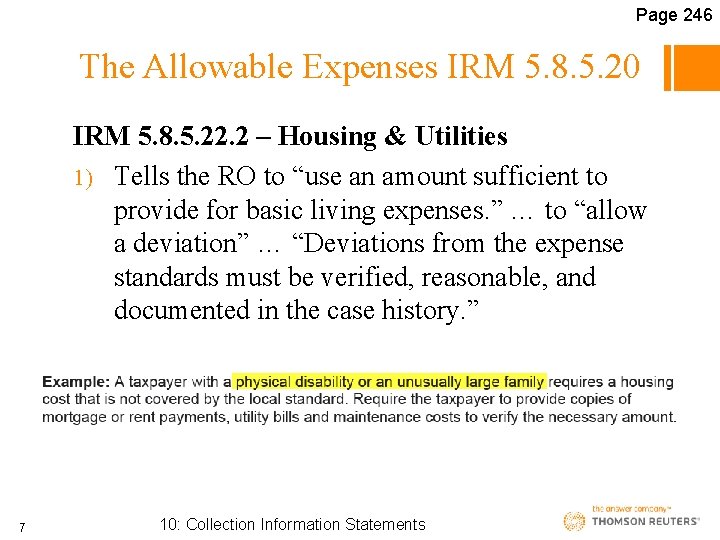
Page 246 The Allowable Expenses IRM 5. 8. 5. 20 IRM 5. 8. 5. 22. 2 – Housing & Utilities 1) Tells the RO to “use an amount sufficient to provide for basic living expenses. ” … to “allow a deviation” … “Deviations from the expense standards must be verified, reasonable, and documented in the case history. ” 7 10: Collection Information Statements
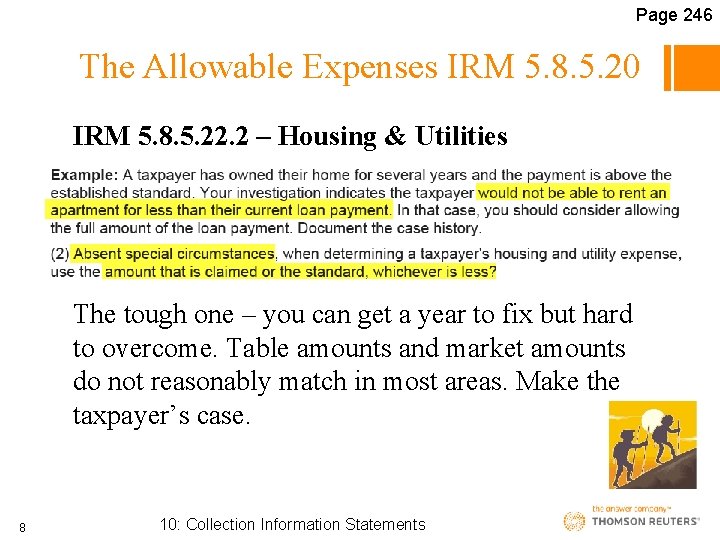
Page 246 The Allowable Expenses IRM 5. 8. 5. 20 IRM 5. 8. 5. 22. 2 – Housing & Utilities The tough one – you can get a year to fix but hard to overcome. Table amounts and market amounts do not reasonably match in most areas. Make the taxpayer’s case. 8 10: Collection Information Statements
Page 246 -247 The Allowable Expenses IRM 5. 8. 5. 20 IRM 5. 8. 5. 22. 3 – Transportation 1. Transportation - IRS charged with high degree of skepticism 2. Look to transportation standards, standard amounts, prove the additional 3. Ownership - “Limit” on ownership cost, meant to limit taxpayer from luxury auto 4. Operating – Std. is the cap, extenuating circumstances, i. e. work usage, etc. 5. Consideration of long commutes, etc. 9 10: Collection Information Statements
Page 247 The Allowable Expenses IRM 5. 8. 5. 20 IRM 5. 8. 5. 22. 3 – Transportation 6. Older Vehicles – 6 years old or 75, 000 miles or more. IRM says an additional $200, case can be made for more. 7. ALL deviations must be verified – Get the T/P to keep records. 10 10: Collection Information Statements
Page 247 The Allowable Expenses IRM 5. 8. 5. 20 IRM 5. 8. 5. 11 IRS is instructed to EXCLUDE up to $3, 450 per auto (up to two for the taxpayer’s family) in value from assets. 11 10: Collection Information Statements
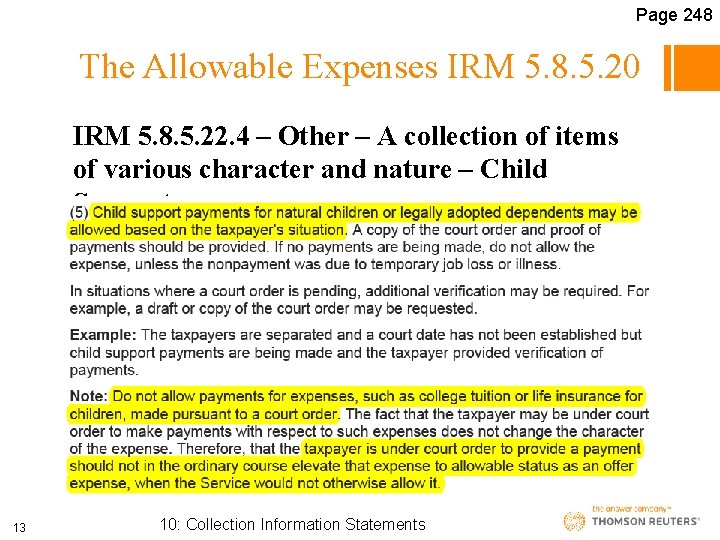
Page 248 The Allowable Expenses IRM 5. 8. 5. 20 IRM 5. 8. 5. 22. 4 – Other – A collection of items of various character and nature – Some notable issues 3) Repayment of student loans that can be verified and are being paid. Will be allowed ten days to get repayment agreement in place. 4) Education expenses are allowed for taxpayer only, not dependents. 12 10: Collection Information Statements
Page 248 The Allowable Expenses IRM 5. 8. 5. 20 IRM 5. 8. 5. 22. 4 – Other – A collection of items of various character and nature – Child Support 13 10: Collection Information Statements
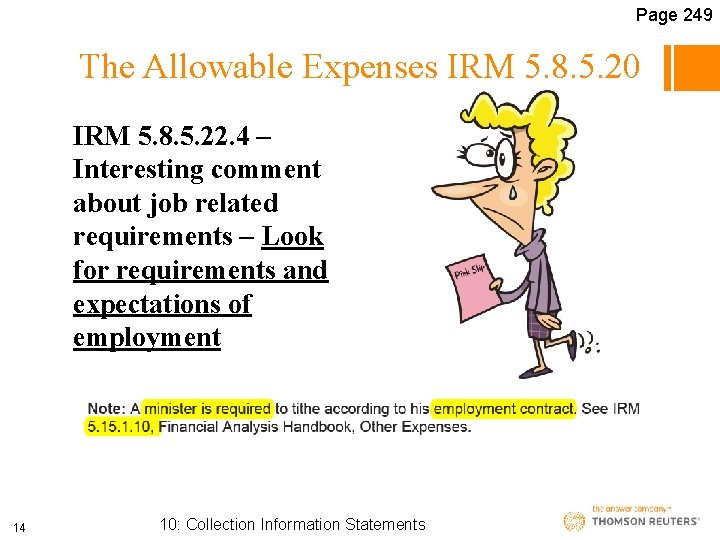
Page 249 The Allowable Expenses IRM 5. 8. 5. 20 IRM 5. 8. 5. 22. 4 – Interesting comment about job related requirements – Look for requirements and expectations of employment 14 10: Collection Information Statements
Page 249 The Allowable Expenses IRM 5. 8. 5. 20 IRM 5. 8. 5. 21 Conditional Expenses - Five Year Rule – Taxpayers who can pay their balance due within five years may be allowed additional expenses if: 1. Establishes ability to stay current with ALL paying and filing requirements 2. Tax liability PLUS accruals can be paid in five years 3. Expense amounts are reasonable 15 10: Collection Information Statements
Page 249 The Allowable Expenses IRM 5. 8. 5. 20 IRM 5. 8. 5. 21 – Conditional Expenses - One Year Rule – Taxpayers who can not pay their balance due within five years can be given up to one year to adjust their expenses 16 10: Collection Information Statements
Page 250 The Allowable Expenses IRM 5. 8. 5. 20 IRM 5. 8. 5. 24 Shared Expenses– Taxpayers that co-habitat while only one taxpayer is obligated for tax debt. – Allowance amounts will be based on relative income of each party 17 10: Collection Information Statements
Page 250 The Allowable Expenses IRM 5. 8. 5. 20 Shared Expenses A person that is a member of the household but is not on the return can be included as well, but be prepared to demonstrate relationships and that individuals contribution to their expenses 18 10: Collection Information Statements
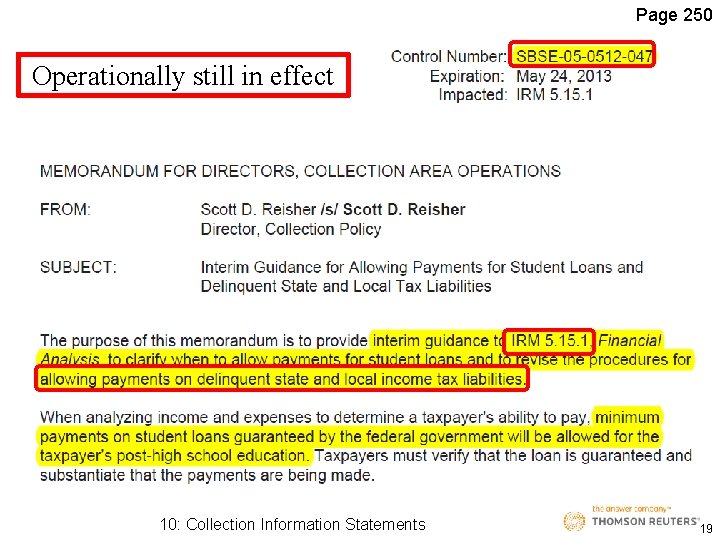
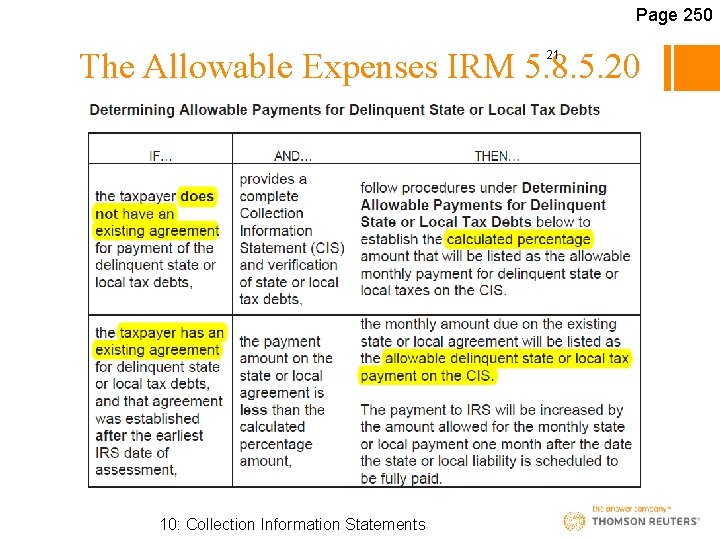
Page 250 The Allowable Expenses Operationally still in effect IRM 5. 8. 5. 20 19 A change in posture due to the “Fresh Start” Initiative for State Tax Payments 10: Collection Information Statements 19
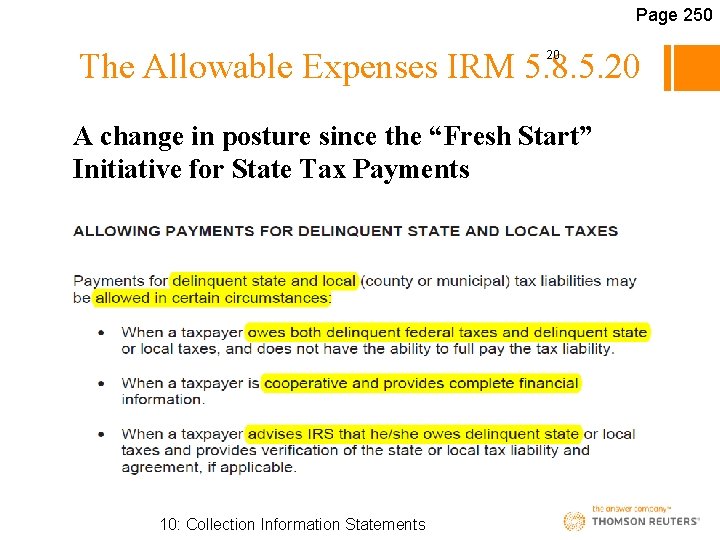
Page 250 The Allowable Expenses IRM 5. 8. 5. 20 20 A change in posture since the “Fresh Start” Initiative for State Tax Payments 10: Collection Information Statements
Page 250 The Allowable Expenses IRM 5. 8. 5. 20 21 A change in posture due to the “Fresh Start” Initiative for State Tax Payments 10: Collection Information Statements
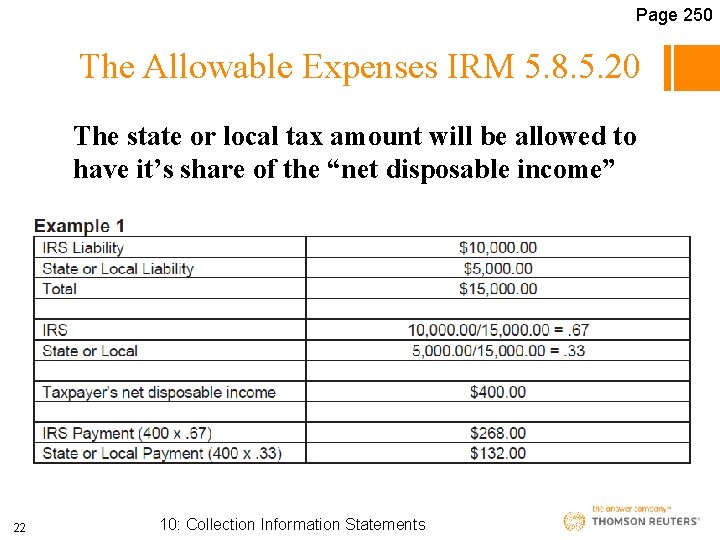
Page 250 The Allowable Expenses IRM 5. 8. 5. 20 The state or local tax amount will be allowed to have it’s share of the “net disposable income” 22 10: Collection Information Statements
Page 251 The Allowable Expenses IRM 5. 8. 5. 20 23 10: Collection Information Statements
Page 251 National Collection Standards 24 10: Collection Information Statements
Page 229 10: Collection Information Statements 25
Page 251 National Collection Standards IRS $ 26 Point to remember § NATIONAL Collection financial standards are meant to meet what is termed “minimal expenses to provide for the individual’s health, welfare, and production of income”. 10: Collection Information Statements
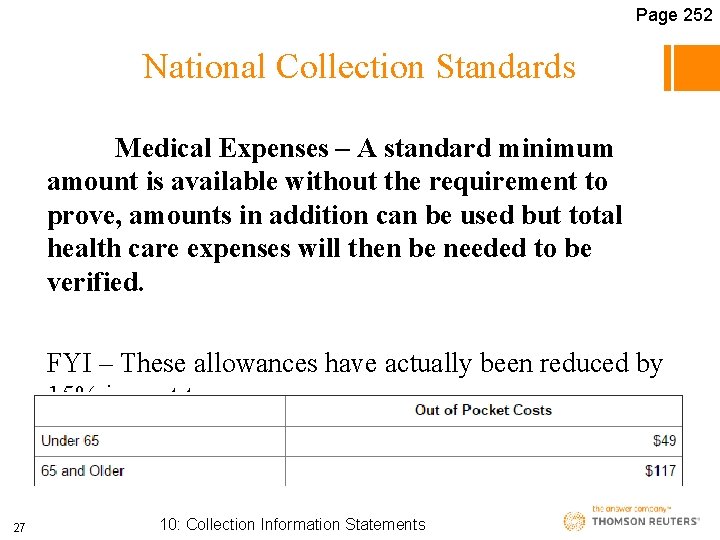
Page 252 National Collection Standards Medical Expenses – A standard minimum amount is available without the requirement to prove, amounts in addition can be used but total health care expenses will then be needed to be verified. FYI – These allowances have actually been reduced by 15% in past two years 27 10: Collection Information Statements
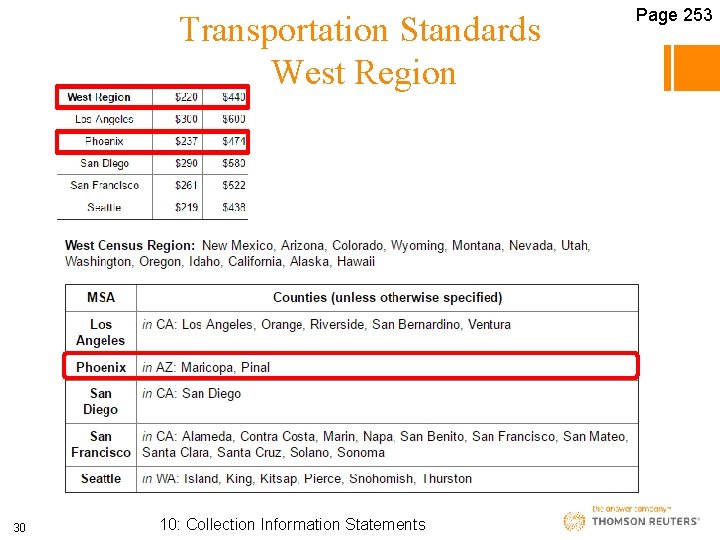
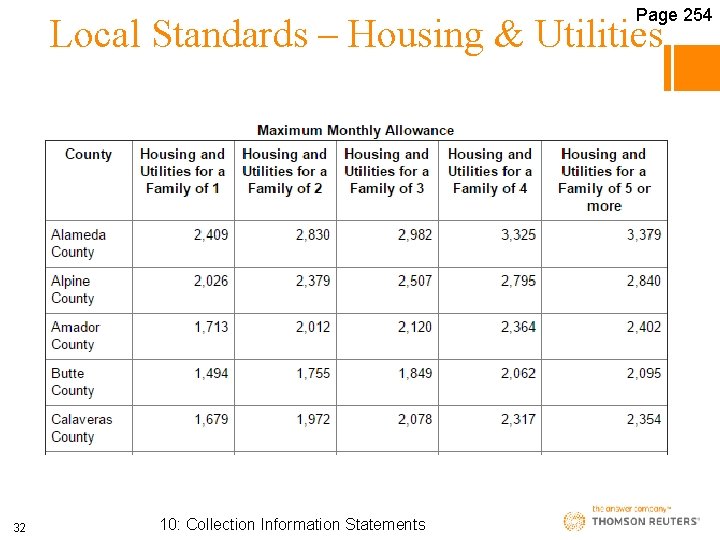
Page 253 National Collection Standards Local Standards – based on costs as determined on a local basis by the Bureau of Labor Statistics § Transportation § Housing and Utilities These are MAXIMUMS, the taxpayer will be required to provide documentation they are spending these amounts and deemed reasonable if in excess – i. e. long commutes 28 10: Collection Information Statements
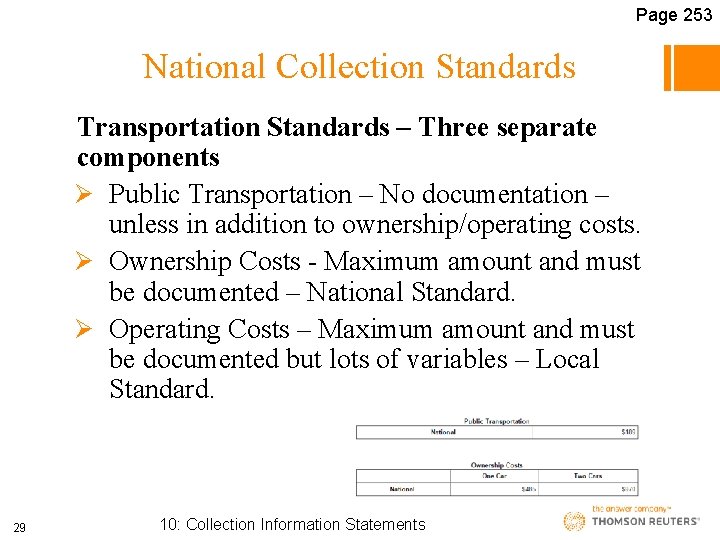
Page 253 National Collection Standards Transportation Standards – Three separate components Ø Public Transportation – No documentation – unless in addition to ownership/operating costs. Ø Ownership Costs - Maximum amount and must be documented – National Standard. Ø Operating Costs – Maximum amount and must be documented but lots of variables – Local Standard. 29 10: Collection Information Statements
Transportation Standards West Region 30 10: Collection Information Statements Page 253
Page 253 National Collection Standards Housing Allowances will be based on the locale of the taxpayer’s primary residence drilled down to a county level 31 10: Collection Information Statements
Page 254 Local Standards – Housing & Utilities 32 10: Collection Information Statements
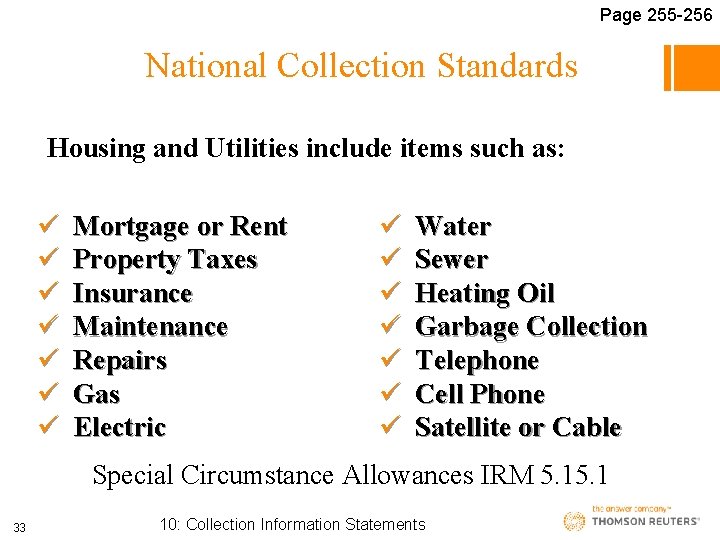
Page 255 -256 National Collection Standards Housing and Utilities include items such as: ü ü ü ü Mortgage or Rent Property Taxes Insurance Maintenance Repairs Gas Electric ü ü ü ü Water Sewer Heating Oil Garbage Collection Telephone Cell Phone Satellite or Cable Special Circumstance Allowances IRM 5. 1 33 10: Collection Information Statements
Page 256 Form 433 -A – Used most frequently has extensive disclosures and attachments – Rev. 2012 Form 433 -B – For business other than the self employed – Rev. 2012 Form 433 -F – A simpler two page form that has less information but may not be complete enough for many cases – Rev. 2017 34 10: Collection Information Statements
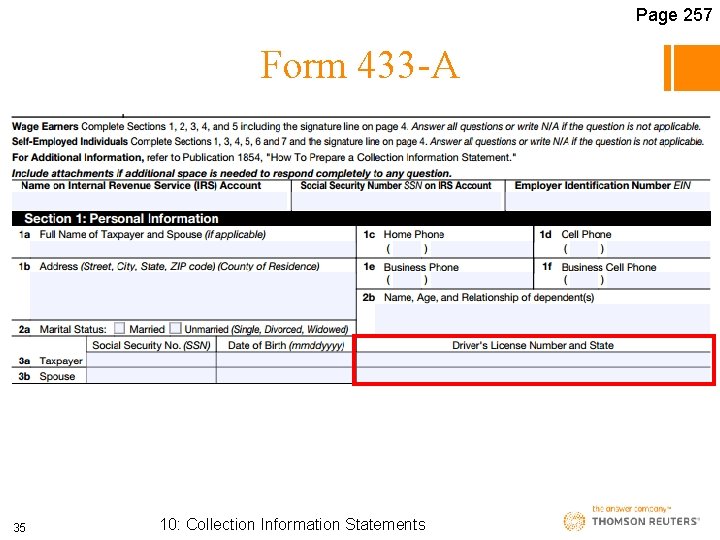
Page 257 Form 433 -A 35 10: Collection Information Statements
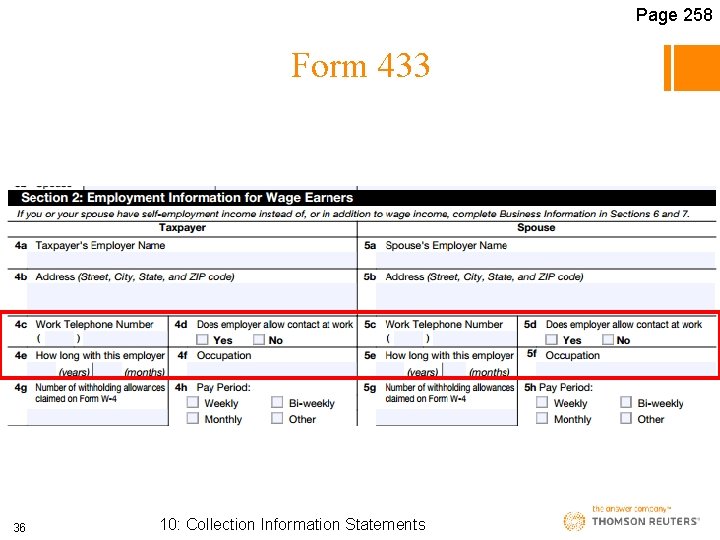
Page 258 Form 433 36 10: Collection Information Statements
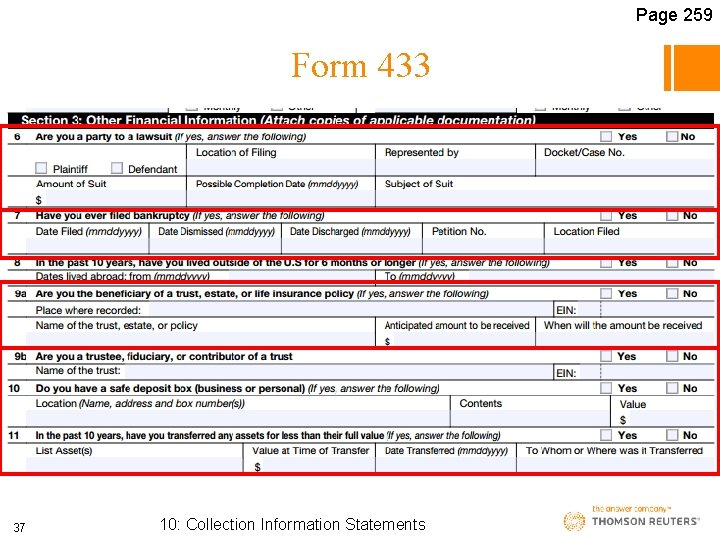
Page 259 Form 433 37 10: Collection Information Statements
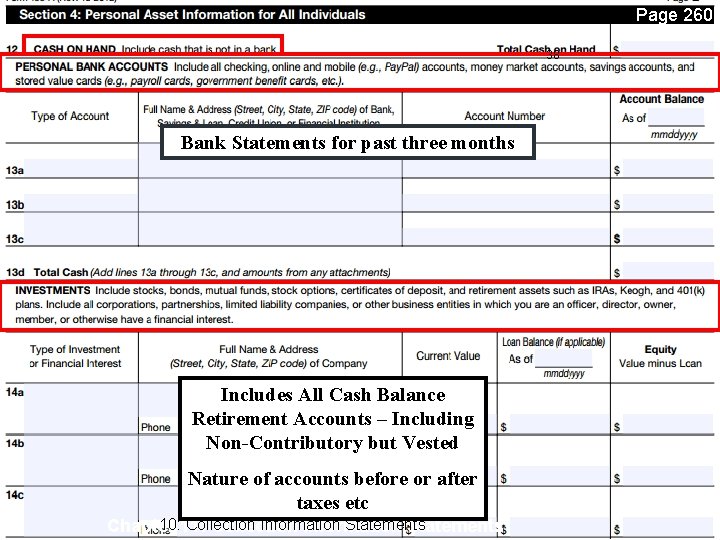
Page 260 38 Bank Statements for past three months Includes All Cash Balance Retirement Accounts – Including Non-Contributory but Vested Nature of accounts before or after taxes etc 10: 11: Collection Information Statements Chapter Collection Information Statements
Page 260 Form 433 -A IRM 5. 8. 5. 6 In the event the taxpayer reports cash on Form 433 -A the RO is now instructed to subtract up $1000 in value if the RO reasonably believes that it is likely that the taxpayer will use those funds for payment of monthly living expenses. 39 10: Collection Information Statements
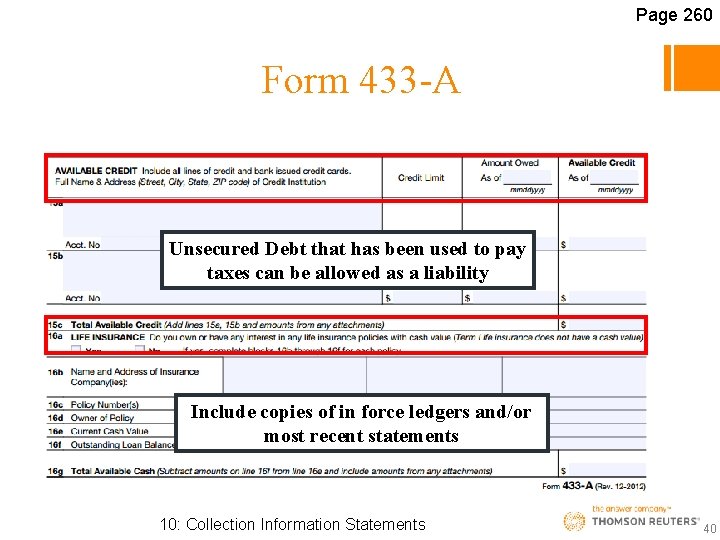
Page 260 Form 433 -A Unsecured Debt that has been used to pay taxes can be allowed as a liability Include copies of in force ledgers and/or most recent statements 10: Collection Information Statements 40
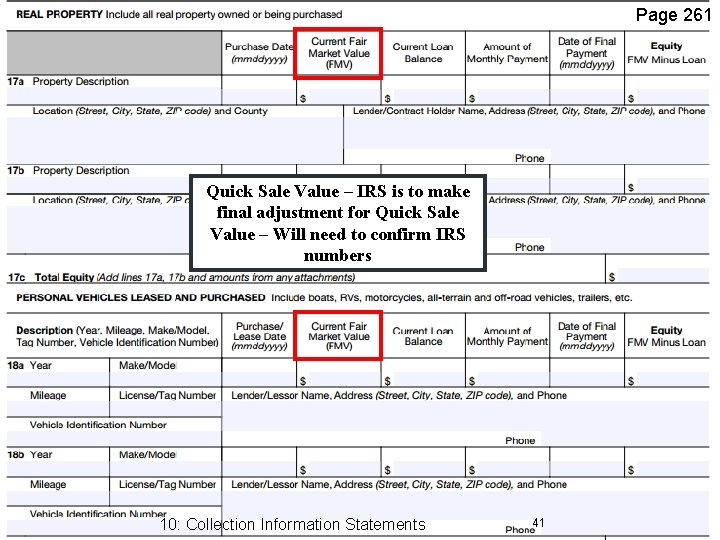
Page 261 Quick Sale Value – IRS is to make final adjustment for Quick Sale Value – Will need to confirm IRS numbers 10: Collection Information Statements 41
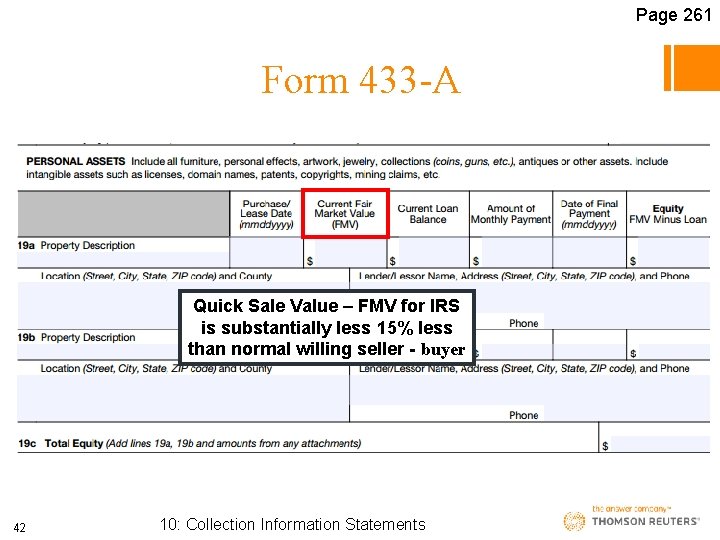
Page 261 Form 433 -A Quick Sale Value – FMV for IRS is substantially less 15% less than normal willing seller - buyer 42 10: Collection Information Statements
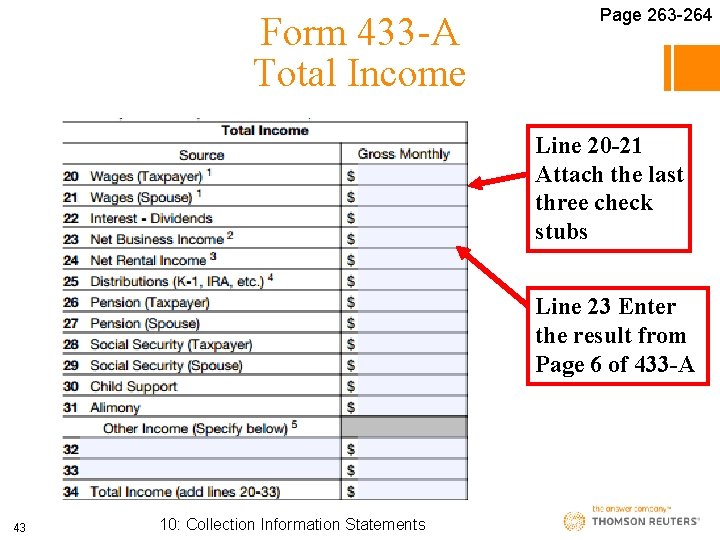
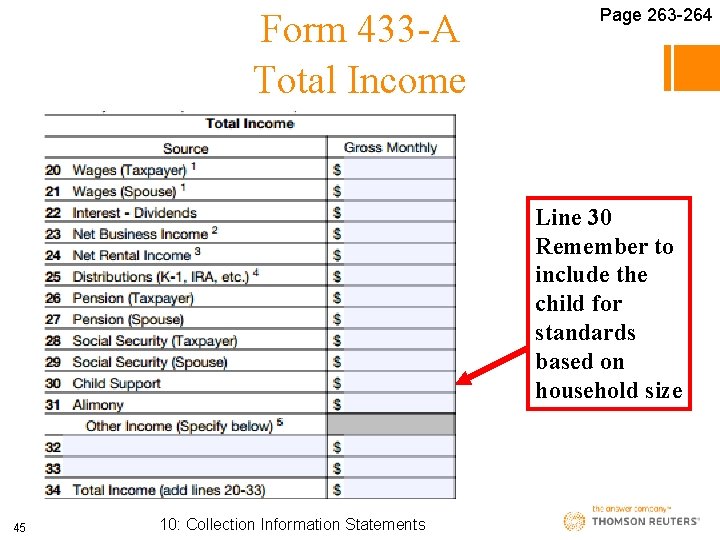
Form 433 -A Total Income Page 263 -264 Line 20 -21 Attach the last three check stubs Line 23 Enter the result from Page 6 of 433 -A 43 10: Collection Information Statements
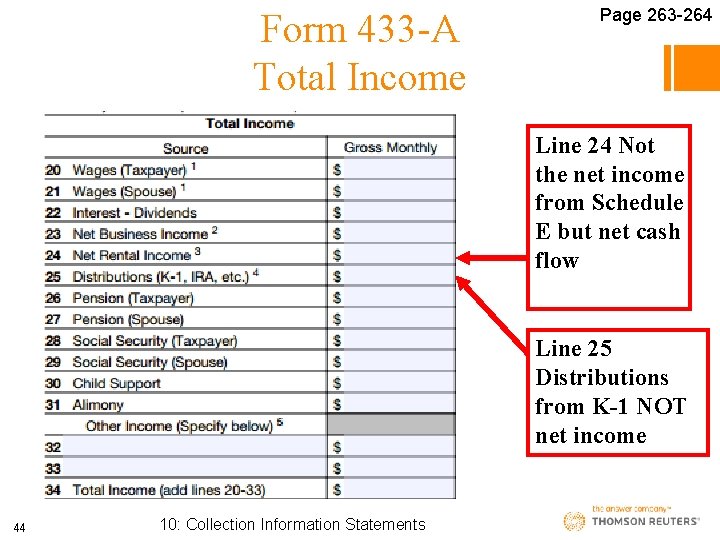
Form 433 -A Total Income Page 263 -264 Line 24 Not the net income from Schedule E but net cash flow Line 25 Distributions from K-1 NOT net income 44 10: Collection Information Statements
Form 433 -A Total Income Page 263 -264 Line 30 Remember to include the child for standards based on household size 45 10: Collection Information Statements
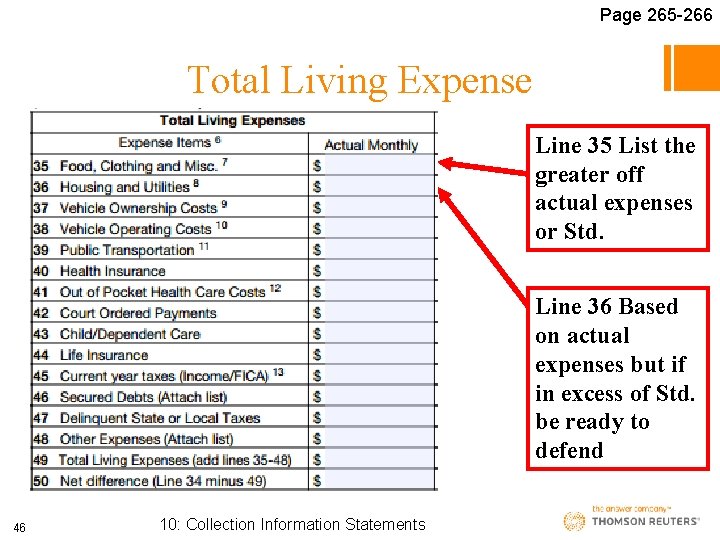
Page 265 -266 Total Living Expense Line 35 List the greater off actual expenses or Std. Line 36 Based on actual expenses but if in excess of Std. be ready to defend 46 10: Collection Information Statements
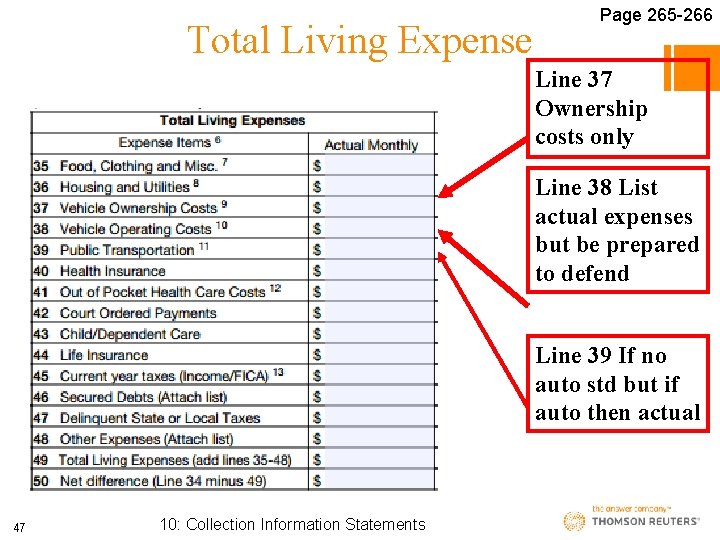
Total Living Expense Page 265 -266 Line 37 Ownership costs only Line 38 List actual expenses but be prepared to defend Line 39 If no auto std but if auto then actual 47 10: Collection Information Statements
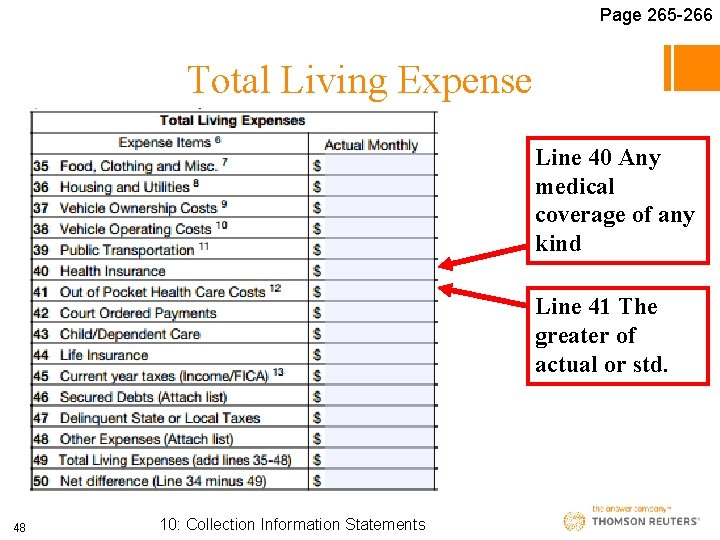
Page 265 -266 Total Living Expense Line 40 Any medical coverage of any kind Line 41 The greater of actual or std. 48 10: Collection Information Statements
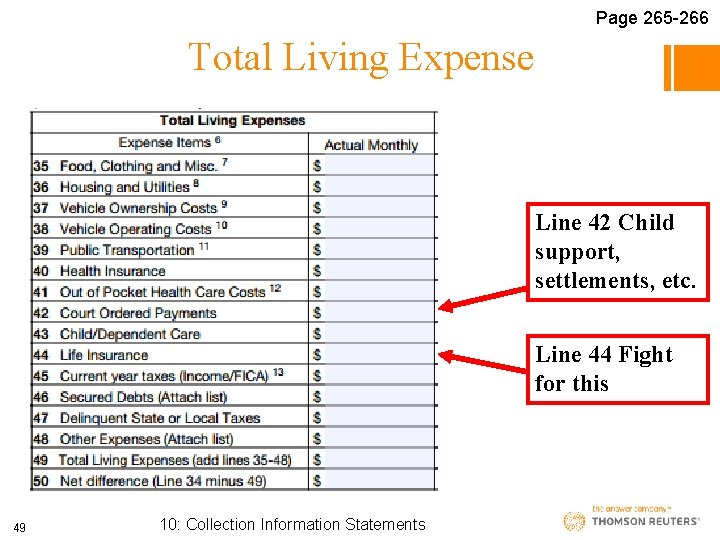
Page 265 -266 Total Living Expense Line 42 Child support, settlements, etc. Line 44 Fight for this 49 10: Collection Information Statements
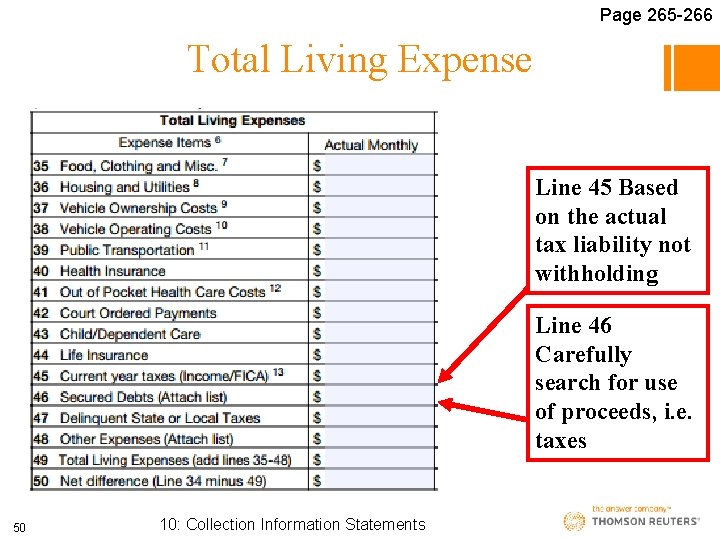
Page 265 -266 Total Living Expense Line 45 Based on the actual tax liability not withholding Line 46 Carefully search for use of proceeds, i. e. taxes 50 10: Collection Information Statements
Page 266 Form 433 -A Line 34 less Line 49 will be the monthly ability to pay. Dependent upon the period left in the statute or perhaps an OIC (offer in compromise) the result of the monthly ability to pay x the number of months applicable will be referred to as the RCP Reasonable Collection Potential 51 10: Collection Information Statements
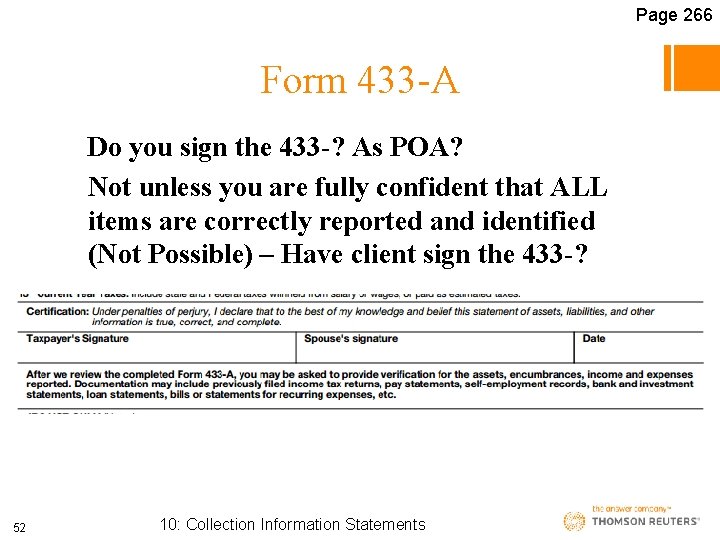
Page 266 Form 433 -A Do you sign the 433 -? As POA? Not unless you are fully confident that ALL items are correctly reported and identified (Not Possible) – Have client sign the 433 -? 52 10: Collection Information Statements
Page 266 Form 433 -A Practice Pointer While the 433 -A does not list contributions to retirement plans as an allowable expense special note should be given to: Ø Mandatory Retirement Plan Contributions Ø Plans that require employee contributions to receive employer pension contributions but IRS normally only allows in full pay agreements and not in an OIC 53 10: Collection Information Statements
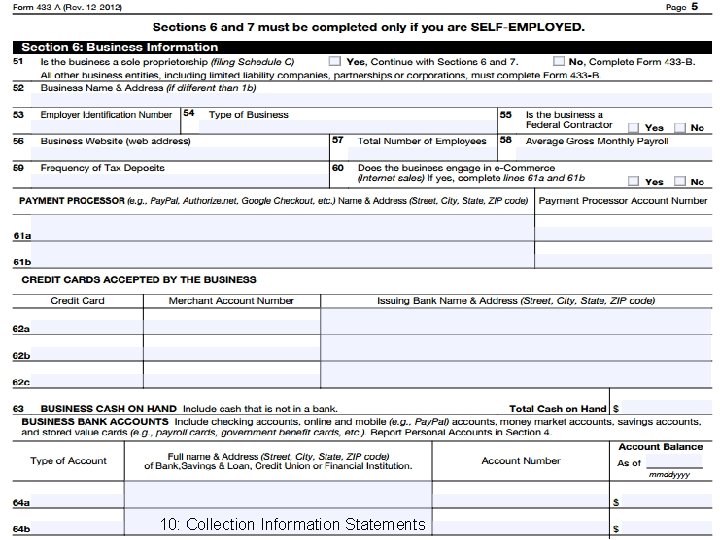
Page 267 -269 Form 433 -A Schedule C & F filers will complete pages 5 & 6 of Form 433 -A to report their net business income 54 10: Collection Information Statements
55 10: 11: Collection Information Statements Chapter Collection Information Statements
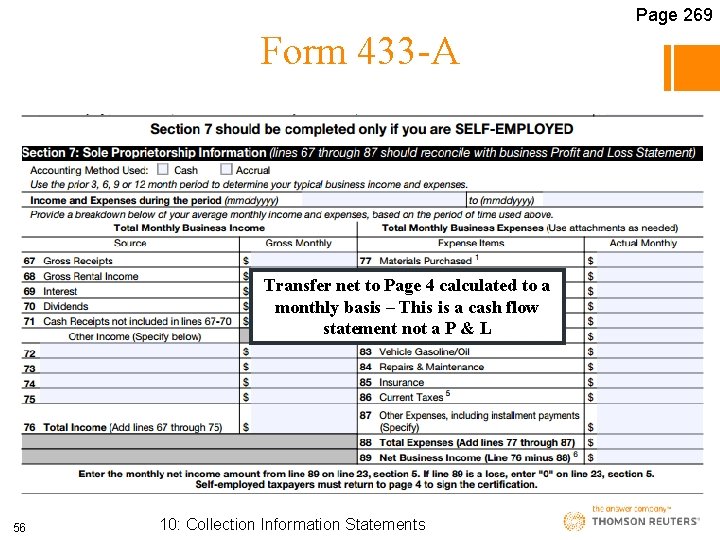
Page 269 Form 433 -A Transfer net to Page 4 calculated to a monthly basis – This is a cash flow statement not a P & L 56 10: Collection Information Statements
Page 270 -272 Form 433 -A Form 433 -B to be completed by business entities other than sole proprietors, including single member LLCs due to certain limitations of liability - Page 248 Form 433 -F the two page collection information statement abbreviated meant to simplify the process for taxpayers Page 249 57 10: Collection Information Statements
The Collection Information Statement is Difficult The Form 433 series that the IRS uses is a difficult form which is complicated to substantiate to the IRS. Respond by a show of hands: 1. Our firm has not really completed a Form 433 recently. 2. When we submit a Form 433 to the IRS it is difficult to resolve as the IRS is never satisfied with the documentation. 3. The IRS test program of raising the limit to potentially $100, 000 without requiring a Form 433 is very helpful to taxpayers in financial difficulty. 4. Raising the threshold of filing Form 433 to $100, 000 is a terrible idea and should be scrapped. 58 10: Collection Information Statements