
Open Banking and Payments update Ruth Milligan Head
Open Banking and Payments update Ruth Milligan, Head of Financial Services & Payments, tech. UK techuk. org |@tech. UK | #tech. UK
13 Jan 2018 • PSD 2 came into effect: PSD 2 is the legal basis and changes the law. It mandates PIS and AIS access. • ‘Open Banking platform ‘goes live’. OB is the technical infrastructure which allow communication between TPPs and the CMA 9. All other UK banks can sign join OB if they want – aim for everyone to join. In fact, only 3 out of the 9 banks have fully put systems in place. Nationwide asked for more time at last minute). CMA gave them deadlines of end Feb to complete – different for each bank. 5 TPPS registered thru OB and now functioning. A few more in pipeline. Will be 6 week testing period to see if the systems work. Many TPPs finding problems with the APIs – ie they don’t look the same vis-à-vis the different banks. Likely that other non-CMA 9 banks will join OB over this year. techuk. org |@tech. UK |#tech. UK
Other issues on the day • A report on fraud from Nat West which made negative comments on Open Banking – see news report • The ‘Opt-out’: Some banks and consumer groups lobbying for an ‘opt-out’ or ‘kill-switch’. Has been consumer demand following very negative press. OB had agreed to look at this possibility as part of Roadmap and try to reach consensus but some banks intend to just do it anyway. One tried to intro this on 13 Jan but was pressed not to do so. techuk. org |@tech. UK |#tech. UK
Opt-out issue The ‘arguments’ for ‘opt-out ‘ • Consumers do not read or understand what they are signing up to and some (it is claimed) have requested an opt-out. • Opt-out necessary to stop these people sharing data without meaning to – especially vulnerable customers. • A customer opt-out option would coerce market into behaving properly. Facts • OB is an opt-in procedure in any event. Customer consent is required to initiate process. • You could not opt-out of screen-scraping in any event. • Opt-out is anti-competitive and very likely contrary to PSD 2 (though FCA has not released a definitive view) • Stakeholders escalated issue – reaction Treasury/FCA. techuk. org |@tech. UK |#tech. UK
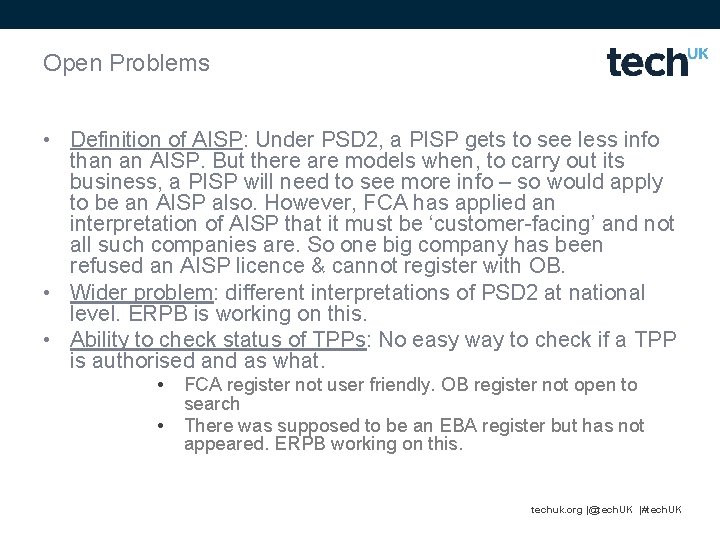
Open Problems • Definition of AISP: Under PSD 2, a PISP gets to see less info than an AISP. But there are models when, to carry out its business, a PISP will need to see more info – so would apply to be an AISP also. However, FCA has applied an interpretation of AISP that it must be ‘customer-facing’ and not all such companies are. So one big company has been refused an AISP licence & cannot register with OB. • Wider problem: different interpretations of PSD 2 at national level. ERPB is working on this. • Ability to check status of TPPs: No easy way to check if a TPP is authorised and as what. • • FCA register not user friendly. OB register not open to search There was supposed to be an EBA register but has not appeared. ERPB working on this. techuk. org |@tech. UK |#tech. UK
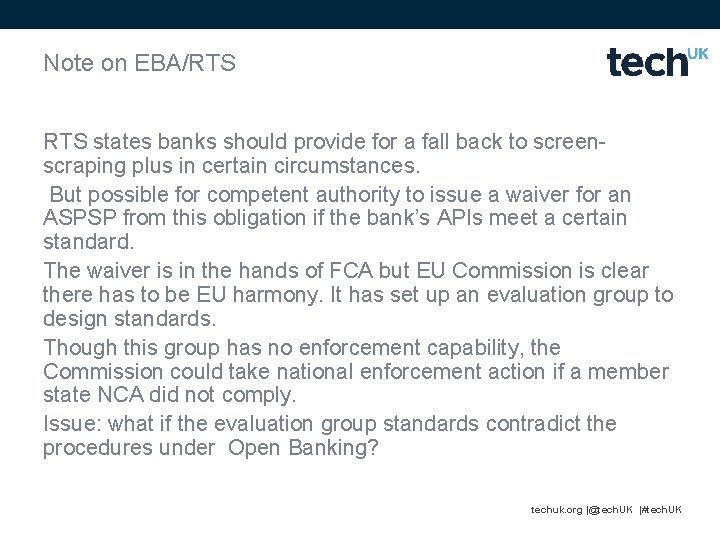
Note on EBA/RTS states banks should provide for a fall back to screenscraping plus in certain circumstances. But possible for competent authority to issue a waiver for an ASPSP from this obligation if the bank’s APIs meet a certain standard. The waiver is in the hands of FCA but EU Commission is clear there has to be EU harmony. It has set up an evaluation group to design standards. Though this group has no enforcement capability, the Commission could take national enforcement action if a member state NCA did not comply. Issue: what if the evaluation group standards contradict the procedures under Open Banking? techuk. org |@tech. UK |#tech. UK
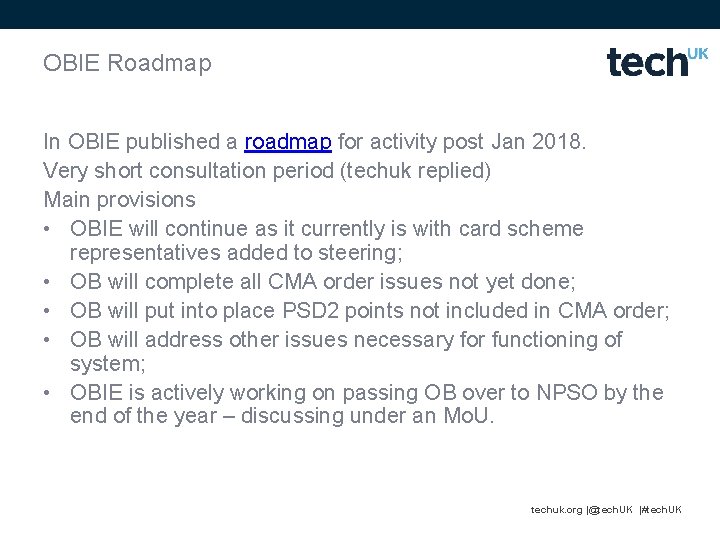
OBIE Roadmap In OBIE published a roadmap for activity post Jan 2018. Very short consultation period (techuk replied) Main provisions • OBIE will continue as it currently is with card scheme representatives added to steering; • OB will complete all CMA order issues not yet done; • OB will put into place PSD 2 points not included in CMA order; • OB will address other issues necessary for functioning of system; • OBIE is actively working on passing OB over to NPSO by the end of the year – discussing under an Mo. U. techuk. org |@tech. UK |#tech. UK
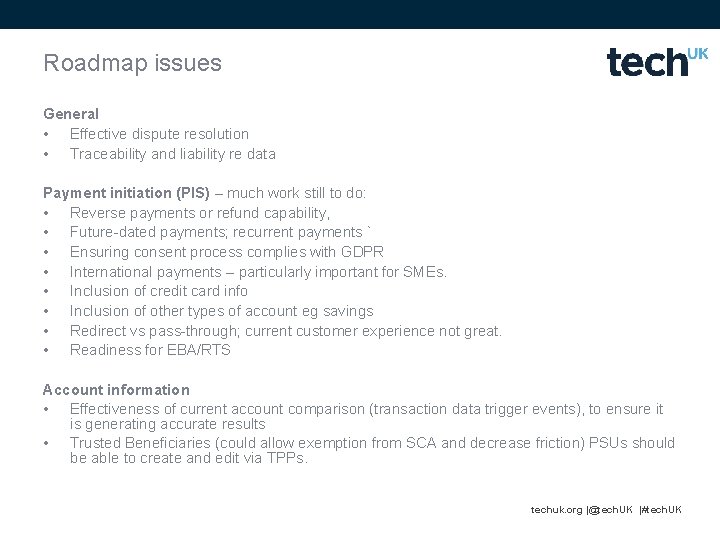
Roadmap issues General • Effective dispute resolution • Traceability and liability re data Payment initiation (PIS) – much work still to do: • Reverse payments or refund capability, • Future-dated payments; recurrent payments ` • Ensuring consent process complies with GDPR • International payments – particularly important for SMEs. • Inclusion of credit card info • Inclusion of other types of account eg savings • Redirect vs pass-through; current customer experience not great. • Readiness for EBA/RTS Account information • Effectiveness of current account comparison (transaction data trigger events), to ensure it is generating accurate results • Trusted Beneficiaries (could allow exemption from SCA and decrease friction) PSUs should be able to create and edit via TPPs. techuk. org |@tech. UK |#tech. UK
Policy problem areas Communication • Have been anti-OB press from some banks, picked up very heavily by parts of the press - raising consumer fears on security; inaccurate and misleading. • Tech community must step up and communicate the benefits of OB. • Must be coordinated plan to communicate PSD 2 and OB to public. Governance: • Current OBIE and Steering group is not functioning. We intend, with other stakeholders to propose a new structure which: • Has an independent board with full access to budget • Transparent – publishes all documents on a public website • Has a coherent structure of WG with identifiable responsibilities and coherent outreach to include all stakeholders. • Resolves issues of funding Long-term • tech. UK lobbying for a long-term strategy at government level to lead a coherent shift to a digital collaborative FS ecosystem. techuk. org |@tech. UK |#tech. UK
Techuk policy priorities • Ensure tech. UK and members are full participants in OB as it progresses. • Work with others on communications campaigns. • Ensure PSD 2 is implemented to allow full competition and TPP activity. • Work to obtain a governance structure which allows this. • Ensure members’ activities and services for OB are understood and welcomed by consumers and SMEs through a positive communication campaign. • Provide access to tech. UK members to policy discussions on future of open banking and all that follows from it. techuk. org |@tech. UK |#tech. UK
Current activity • FCA meeting Dec 2017 re governance, communication, longterm strategy. FCA has no mandate but being very helpful as convenor. Attendees: OBIE, FDATA, E-Money Assoc, UK Finance, Treasury. (Note Treasury said they are not decision-maker re long-term governance of OB) • FCA will continue to use its convening power to get main players together. • Communications: techuk joining with FDATA, UK Finance, OBIE re coordinated communication campaign • Governance: meeting 30 Jan with all stakeholder bodies techuk. org |@tech. UK |#tech. UK
RTGS Renewal and ISO 20022 Bank of England is updating the real-time gross settlement system (RTGS) • Migrate to ISO 20022 • Increase resilience and widen interoperability • Improve user functionality • Strengthen end-to-end risk management • Increase access for small banks and non-banks. The Bank has working groups of industry experts and is keen to hear from any tech. UK members who wish to assist in the work. Further info on Bank of England website techuk. org |@tech. UK |#tech. UK
- Slides: 12