
ONGC Pension Medical Scheme 19 11 2012 Hyderabad
ONGC Pension & Medical Scheme 19. 11. 2012 Hyderabad
Terminal Benefits available on Superannuation 1. Gratuity. - The maximum limit of Gratuity post 2007 pay revision is Rs 10 lac, from 01. 2007 till 25. 04. 2010, the amount in excess of Rs 3. 50 lac was taxable 2. Compulsory Employees Pension Scheme (EPS-95)- A contribution of Rs 541/- p. m. per employee from Employer contribution of CPF. From 2007 to 2012, the benefits ranged between Rs 1282 to Rs 1912 p. m. 3. Contributory Provident Fund(CPF)-12% of salary p. m. as employee contribution & 12% of salary less Rs 541 p. m. as employer contribution, plus accumulation of interest on YOY basis. . 4. Post Superannuation Medical Benefits- Funded from 30% superannuation benefits. Employee contributes 1. 61% of Basic + DA p. m. 2
DPE Guidelines ØCPSE are allowed 30% of Basic Pay plus DA as Superannuation Benefit. ØAny superannuation benefit will be under defined contribution Scheme and not under a Defined Benefit Scheme. ØThe Scheme will operate as Defined Contribution Scheme and the return will depend on performance of the fund/market conditions. ØMinimum 15 years of service before superannuation is required in a CPSE for availing benefits. ØThe Scheme to operate through IRDA approved
ONGC Existing Post Retirement Benefit Scheme Introduced w. e. f 01/04/1990 for Executives on optional basis Scheme covers regular employees having a continuous minimum service of Ten years except in case of death & PTD A Self Contributory Scheme Defined Benefit (DB) and is a recognized Pension Fund under Income Tax Act A Defined Contribution Scheme as per DPE guidelines from 01. 2007 onwards is under formulation.
PRBS Existing Scheme In Existing Scheme the benefits are based on: - (a) Reckonable Service- Past Service & Future Reckonable Service (b) Salary as on 16. 11. 1995 - for calculation of Past service pension (c) Notional Salary- Salary as on 16. 11. 1995 escalated @ 8% p. a. compounded annually for calculation of Future Service Pension. (d) The benefits are not directly linked with the amount contributed by the employee (defined benefit). (e) The current benefits are in the range of 18% to 20% of last Basic Pay of the superannuating employee i. e. an employee with a Basic Pay of Rs 40000/- p. m gets approximately Rs 7000/- p. m as Gross Pension (under
PRBS Existing Scheme In Existing Scheme the contributions are as follows: - (a) PRBS Normal Contribution- It is a % of Notional Salary. The % depends upon age at which an employee joined PRBS and ranges from 1% to 11%. (b) PRBS Additional ContributionØ The existing Scheme is a defined benefit Scheme and benefits are below sustenance level due to meagre pension amount presently. Ø The Benefits under the existing Scheme are dependent on Salary of 16. 11. 1995 which notionally escalated @ 8% p. a. and does not take into account provisions under pay revision guidelines.
Need for Conversion Ø In terms of extant DPE guidelines w. e. f 01. 2007, the PRBS Scheme is to be converted into Defined Contribution (DC) scheme. However, DC Scheme will not guarantee any pension and benefits would vary with interest rate. Ø Converted Scheme to be effective from 01. 2007, in tune with Pay Revision -2007. Ø Distinction may be drawn with Central Government Scheme where maximum pension is 50% of Basic + DA, as against ONGC PRBS Scheme. Further, there is no DA neutralization in ONGC case.
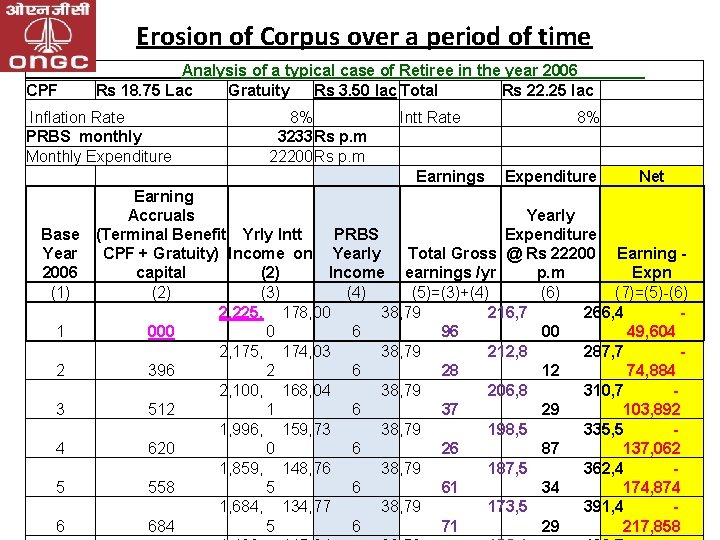
Erosion of Corpus over a period of time Analysis of a typical case of Retiree in the year 2006 CPF Rs 18. 75 Lac Gratuity Rs 3. 50 lac Total Rs 22. 25 lac Inflation Rate 8% Intt Rate 8% PRBS monthly 3233 Rs p. m Monthly Expenditure 22200 Rs p. m Earnings Expenditure Net Earning Accruals Yearly Expenditure Base (Terminal Benefit Yrly Intt PRBS Year CPF + Gratuity) Income on Yearly Total Gross @ Rs 22200 Earning - 2006 capital (2) Income earnings /yr p. m Expn (1) (2) (3) (4) (5)=(3)+(4) (6) (7)=(5)-(6) 2, 225, 178, 00 38, 79 216, 7 266, 4 1 000 0 6 96 00 49, 604 2, 175, 174, 03 38, 79 212, 8 287, 7 2 396 2 6 28 12 74, 884 2, 100, 168, 04 38, 79 206, 8 310, 7 3 512 1 6 37 29 103, 892 1, 996, 159, 73 38, 79 198, 5 335, 5 4 620 0 6 26 87 137, 062 1, 859, 148, 76 38, 79 187, 5 362, 4 5 558 5 6 61 34 174, 874 1, 684, 134, 77 38, 79 173, 5 391, 4 6 684 5 6 71 29 217, 858
Proposed Defined Contribution Pension Scheme 9
Conversion of Existing Scheme • In the light of DPE guidelines dated 26. 11. 2008 & 02. 04. 2009, the Scheme is to be converted into a Defined Contribution Scheme. • The accumulation of the existing PRBS Scheme will be apportioned into individual accounts on the day of conversion i. e. 01. 2007 and thereafter the Superannuation benefits under Defined Contribution Scheme will be remitted into individual Accounts. • The existing PRBS Scheme is managed through a Welfare Trust comprising Trustees representing collectives and management, the conversion of the Scheme from DB to DC
Pensionary Benefits • Since the Scheme shall be purely Defined Contribution Scheme, the superannuation benefits shall depend upon the amount accumulated in the individual Accounts and the performance of the pension fund as per the market condition from time to time. • On superannuation the accumulation in the individual account will be transferred to the IRDA approved Insurance Companies for disbursement of the pension with one third commutation option.
ONGC POST RETIREMENT MEDICAL BENEFIT SCHEME
Post Retirement Medical Benefits Ø ONGC is already having its medical benefit Scheme for superannuated employees which was on payment of lumpsum contribution up to 16. 06. 2011. Ø Medical facility is provided through ONGC hospitals/Dispensaries, and at remaining locations through empanelled hospitals. Ø Wherever such facility is not available, the medical claims are restricted to KEM rates (nearly 40% of private hospital rates). 13
Post Retirement Medical Benefit Scheme …. contd. • After 01. 2007, the beneficiary would be contributing 1. 61% of BP+ DA towards Post Retirement Medical Benefit Scheme during his entire service period out of the 30% superannuation benefits as provided in DPE guidelines. The medical facility would be available to the employee after superannuation. • 3% of Basic pay out of the 50% Cafeteria is recovered from Employee’s Salary towards interalia medical benefits.
Eligibility under the PRMBS Ø Regular employees who have retired from ONGC. Ø Employees who have put in 20 years of service and attained 50 years of age and have taken Voluntary Retirement are also eligible under this scheme. Ø Employees who joined ONGC from other Central Govt. Offices/PSUs /State Govt. and have taken Voluntary Retirement are also eligible under this scheme provided the total service put by them together without any break exceeds 20 years including 10 years in ONGC. Ø The employees who take up full time regular employment outside ONGC after retirement/separation shall not be
Points for deliberation 1. Whether the Pensionary and medical benefits under these Schemes are admissible to : (a) Death in harness before completing 15 years of service. (b) Death in harness after completing 15 years of service. (c) Case where the employee has taken VR after completing 15 years of Service. (d) Treatment of employer contribution in case of resignation in case of less than and more than 15 years of service? (e) Disbursement of benefits under lien cases and deposit of employer contribution? 2. Employees moving from one CPSE to another without break but superannuating after completing 15 years of service in CPSEs?
THANK YOU
- Slides: 17