
NY STATE OF HEALTH ASSISTOR CERTIFICATION TRAINING MODULE
- Slides: 46
NY STATE OF HEALTH ASSISTOR CERTIFICATION TRAINING MODULE SIX: PICK A PLAN nystateofhealth. ny. gov
LEARNING OBJECTIVES By the end of this module, you will be able to… • Help consumers understand how to compare health plans. • For Qualified Health Plan (QHP) eligible consumers, explain how out of pocket costs vary between each metal level and catastrophic plans. • Understand how to use the plan search tools available through the NY State of Health.
COMPARING MEDICAID MANAGED CARE PLANS MMCs have no premiums. There are low co-pays for some prescriptions. All MMCs provide Essential Health Benefits and some additional benefits When selecting a MMC plan, consumers should consider the following: o Provider network o Prescription formulary o Special programs o Referrals The Marketplace will tell each eligible individual which MMC plans are available to them. On the plan selection page, consumers can use filters to show plans that include their providers and can sort by quality rating.
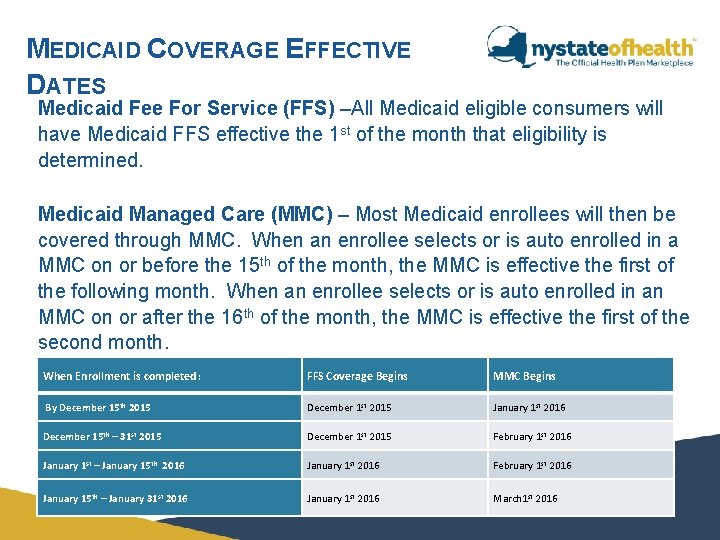
MEDICAID COVERAGE EFFECTIVE DATES Medicaid Fee For Service (FFS) –All Medicaid eligible consumers will have Medicaid FFS effective the 1 st of the month that eligibility is determined. Medicaid Managed Care (MMC) – Most Medicaid enrollees will then be covered through MMC. When an enrollee selects or is auto enrolled in a MMC on or before the 15 th of the month, the MMC is effective the first of the following month. When an enrollee selects or is auto enrolled in an MMC on or after the 16 th of the month, the MMC is effective the first of the second month. When Enrollment is completed : FFS Coverage Begins MMC Begins By December 15 th 2015 December 1 st 2015 January 1 st 2016 December 15 th – 31 st 2015 December 1 st 2015 February 1 st 2016 January 1 st – January 15 th 2016 January 1 st 2016 February 1 st 2016 January 15 th – January 31 st 2016 January 1 st 2016 March 1 st 2016
COMPARING CHILD HEALTH PLUS PLANS The family premium contribution for a child receiving subsidized CHPlus coverage is the same regardless of which plan they choose. NY State of Health will determine which CHPlus plans are available to the consumer and what the premium will be for each plan, if there is one. There is no cost sharing in any of the CHPlus plans (deductible/copay/coinsurance). The CHPlus plans offered by each carrier will vary by: o Provider network o Prescription formulary o Quality Rating NY State of Health will determine which CHPlus plans are available to the consumer and what the premium for each plan, if there is one. On the plan selection page, consumers can use filters to show provider networks and quality rating.
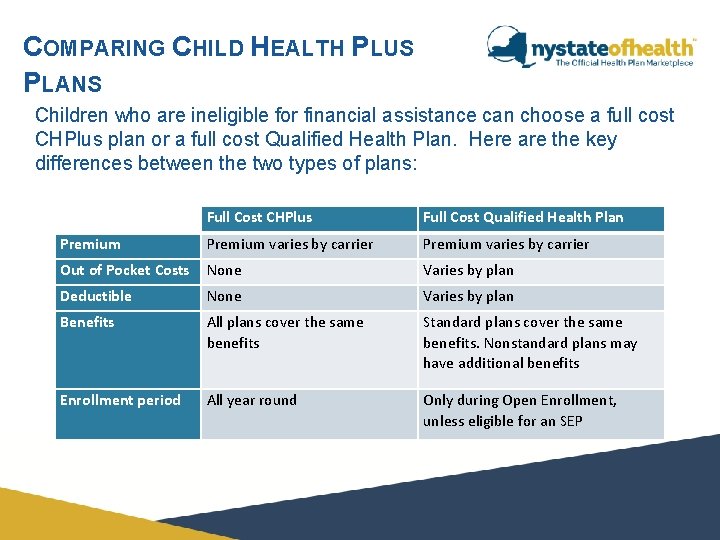
COMPARING CHILD HEALTH PLUS PLANS Children who are ineligible for financial assistance can choose a full cost CHPlus plan or a full cost Qualified Health Plan. Here are the key differences between the two types of plans: Full Cost CHPlus Full Cost Qualified Health Plan Premium varies by carrier Out of Pocket Costs None Varies by plan Deductible None Varies by plan Benefits All plans cover the same benefits Standard plans cover the same benefits. Nonstandard plans may have additional benefits Enrollment period All year round Only during Open Enrollment, unless eligible for an SEP
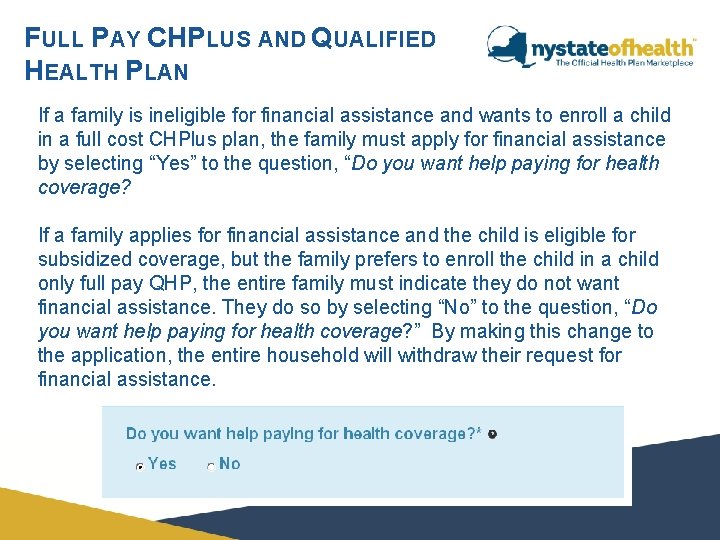
FULL PAY CHPLUS AND QUALIFIED HEALTH PLAN If a family is ineligible for financial assistance and wants to enroll a child in a full cost CHPlus plan, the family must apply for financial assistance by selecting “Yes” to the question, “Do you want help paying for health coverage? If a family applies for financial assistance and the child is eligible for subsidized coverage, but the family prefers to enroll the child in a child only full pay QHP, the entire family must indicate they do not want financial assistance. They do so by selecting “No” to the question, “Do you want help paying for health coverage? ” By making this change to the application, the entire household will withdraw their request for financial assistance.
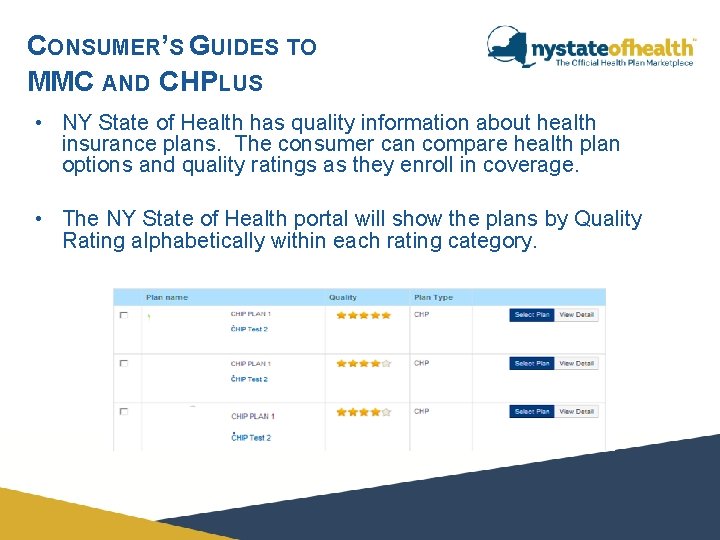
CONSUMER’S GUIDES TO MMC AND CHPLUS • NY State of Health has quality information about health insurance plans. The consumer can compare health plan options and quality ratings as they enroll in coverage. • The NY State of Health portal will show the plans by Quality Rating alphabetically within each rating category.
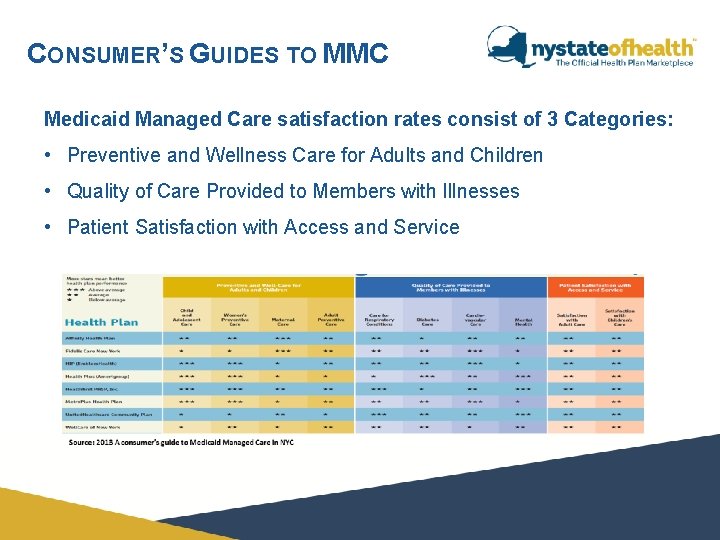
CONSUMER’S GUIDES TO MMC Medicaid Managed Care satisfaction rates consist of 3 Categories: • Preventive and Wellness Care for Adults and Children • Quality of Care Provided to Members with Illnesses • Patient Satisfaction with Access and Service
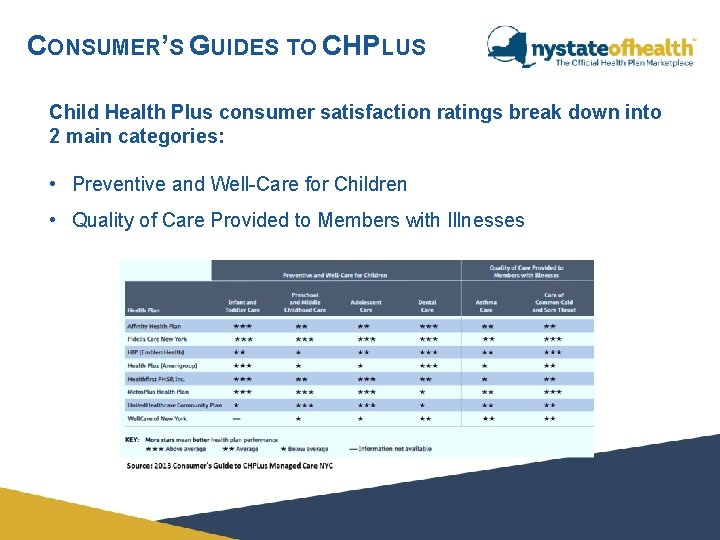
CONSUMER’S GUIDES TO CHPLUS Child Health Plus consumer satisfaction ratings break down into 2 main categories: • Preventive and Well-Care for Children • Quality of Care Provided to Members with Illnesses
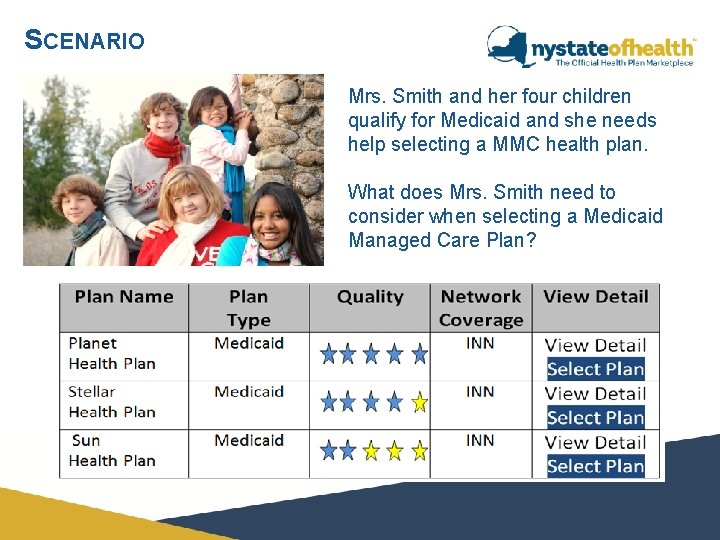
SCENARIO Mrs. Smith and her four children qualify for Medicaid and she needs help selecting a MMC health plan. What does Mrs. Smith need to consider when selecting a Medicaid Managed Care Plan?
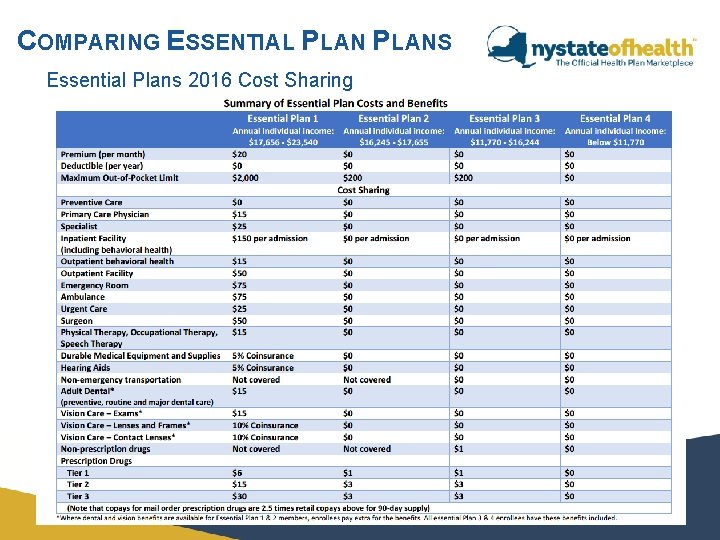
COMPARING ESSENTIAL PLANS Benefits o All plans cover the Essential Health Benefits. o Consumers who are eligible for Essential Plan 3 and 4 will receive additional benefits. o Consumers who are eligible for Essential Plan 1 and 2 will have the choice of selecting an Essential Plan with just the EHBs or an Essential Plan plus adult vision and dental services for an additional cost, or an Essential Plan and a separate Stand Alone Dental Plan. Cost o There is no deductible for any of the Essential Plan plans. o Consumers who are eligible for Essential Plan 2 will have no premium unless they select a plan with dental and vision. o Consumers who are eligible for Essential Plan 1 will have a premium of $20 per individual per month and a higher premium if they select a plan with dental and vision. o Co-pays and maximum out of pocket limits will be the same across carriers. o Premiums for optional vision and dental coverage will vary between Essential Plan 1 and Essential Plan 2 by carriers and region.
COMPARING ESSENTIAL PLANS Essential Plans 2016 Cost Sharing
ESSENTIAL PLAN – EFFECTIVE DATE OF COVERAGE For individuals who have income at or below 138% FPL and do not qualify for Medicaid due to immigration status, the effective date of coverage will be on the first of the month in which an Essential Plan is selected. • For example, an individual who enrolls in an Essential Plan on February 15, 2016, will have coverage starting February 1, 2016. For individuals who have income above 138% FPL, the effective date of coverage will follow the “ 15 th of the month” rule. For example: • An individual who enrolls in an Essential Plan on February 10, 2016, will have coverage starting March 1, 2016. • An individual who enrolls in an Essential Plan on February 20, 2016, will have coverage starting April 1, 2016.
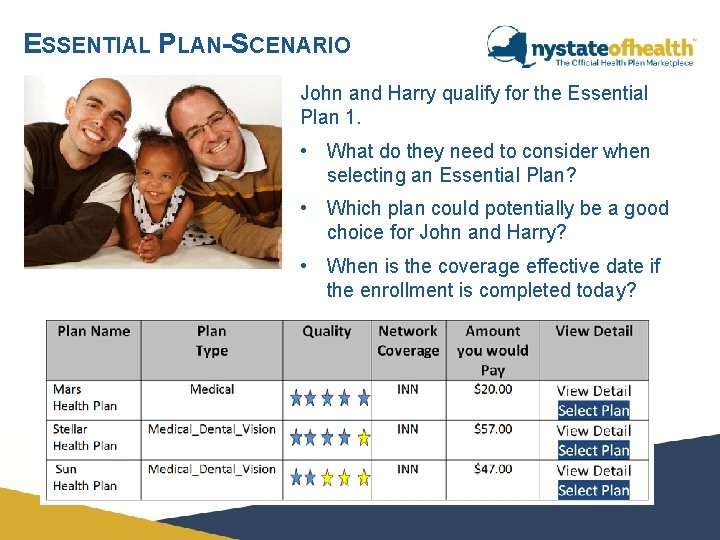
ESSENTIAL PLAN-SCENARIO John and Harry qualify for the Essential Plan 1. • What do they need to consider when selecting an Essential Plan? • Which plan could potentially be a good choice for John and Harry? • When is the coverage effective date if the enrollment is completed today?
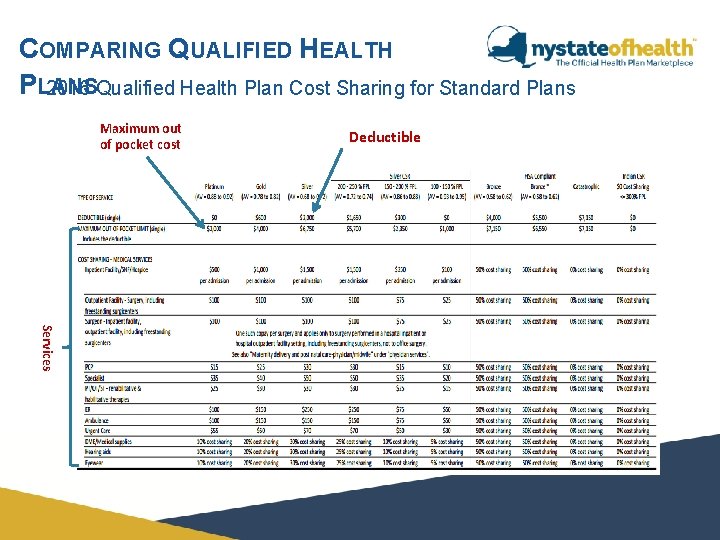
COMPARING QUALIFIED HEALTH PLANS All Qualified Health Plans cover the Essential Health Benefits. Nonstandard plans may cover additional benefits. Qualified Health Plans will vary by premium, provider network, prescription formulary and quality rating. All Standard Qualified Health Plans have the same out of pocket costs, maximum out of pocket limits and deductibles. Nonstandard Qualified Health Plans can have different out of pocket costs, maximum out of pocket limits and deductibles. Each distinct Qualified Health Plan will have the same benefits, network, formulary and quality rating across metal levels. Premium and cost-sharing will vary for each distinct Qualified Health Plan across metal levels. Each Qualified Health Plan will cover dependents up to 26 or through age 29.
COMPARING QUALIFIED HEALTH PLANS 2016 Qualified Health Plan Cost Sharing for Standard Plans Maximum out of pocket cost Deductible Services
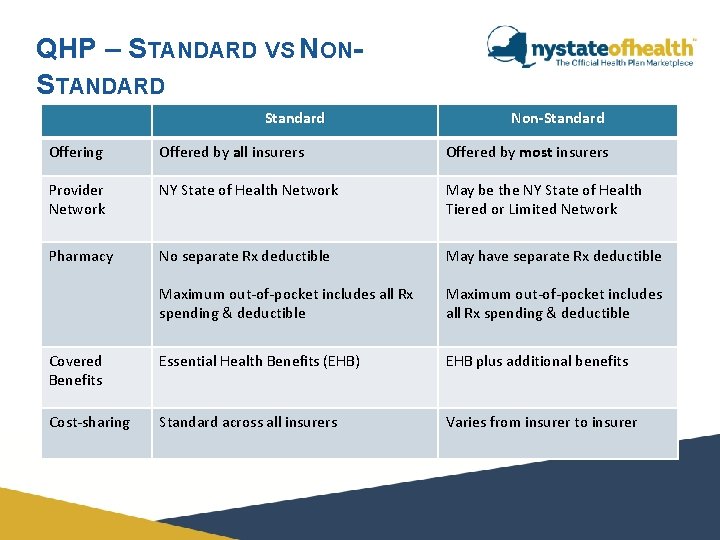
QHP – STANDARD VS NONSTANDARD Standard Non-Standard Offering Offered by all insurers Offered by most insurers Provider Network NY State of Health Network May be the NY State of Health Tiered or Limited Network Pharmacy No separate Rx deductible May have separate Rx deductible Maximum out-of-pocket includes all Rx spending & deductible Covered Benefits Essential Health Benefits (EHB) EHB plus additional benefits Cost-sharing Standard across all insurers Varies from insurer to insurer
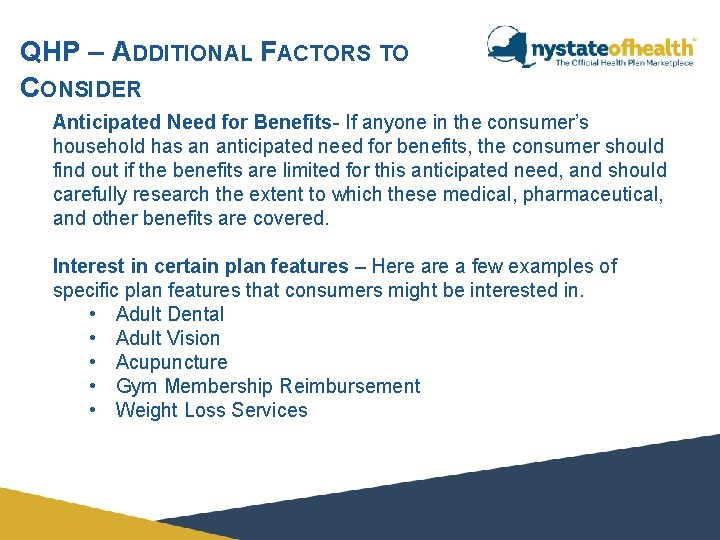
QHP – ADDITIONAL FACTORS TO CONSIDER Anticipated Need for Benefits- If anyone in the consumer’s household has an anticipated need for benefits, the consumer should find out if the benefits are limited for this anticipated need, and should carefully research the extent to which these medical, pharmaceutical, and other benefits are covered. Interest in certain plan features – Here a few examples of specific plan features that consumers might be interested in. • Adult Dental • Adult Vision • Acupuncture • Gym Membership Reimbursement • Weight Loss Services
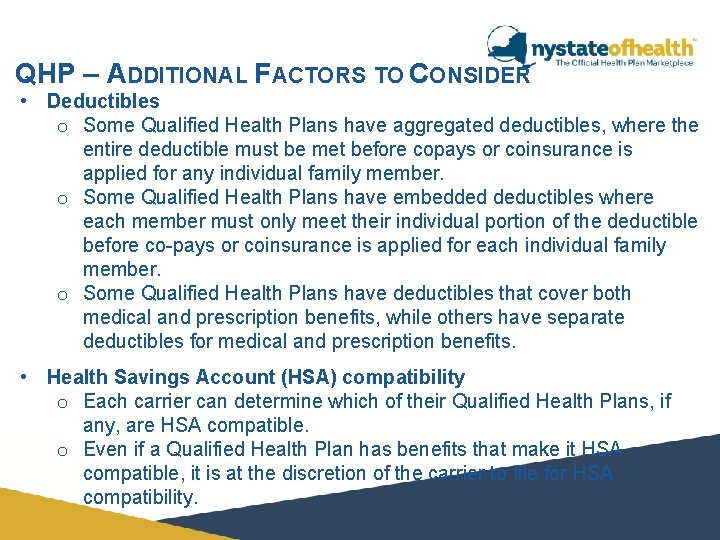
QHP – ADDITIONAL FACTORS TO CONSIDER • Deductibles o Some Qualified Health Plans have aggregated deductibles, where the entire deductible must be met before copays or coinsurance is applied for any individual family member. o Some Qualified Health Plans have embedded deductibles where each member must only meet their individual portion of the deductible before co-pays or coinsurance is applied for each individual family member. o Some Qualified Health Plans have deductibles that cover both medical and prescription benefits, while others have separate deductibles for medical and prescription benefits. • Health Savings Account (HSA) compatibility o Each carrier can determine which of their Qualified Health Plans, if any, are HSA compatible. o Even if a Qualified Health Plan has benefits that make it HSA compatible, it is at the discretion of the carrier to file for HSA compatibility.
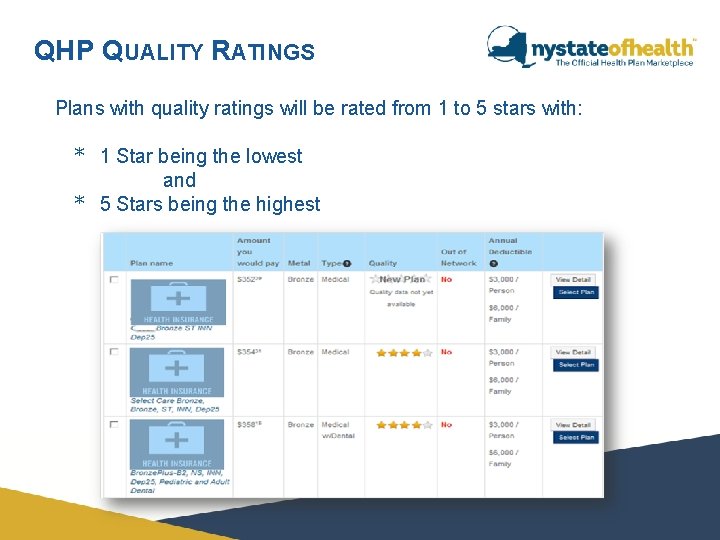
QHP QUALITY RATINGS Plans with quality ratings will be rated from 1 to 5 stars with: * 1 Star being the lowest and * 5 Stars being the highest
STAND ALONE DENTAL PLAN (SADP) Consumers who enroll in a Qualified Health Plan will have the option of also enrolling a Stand Alone Dental Plan (SADP). Consumers cannot enroll in a SADP without enrolling in a Qualified Health Plan. A stand‐alone dental plan will have its own premium, deductible and cost sharing. When consumers buy a SADP, they will receive separate bills from their QHP and SADP carrier. Stand Alone Dental Plans vary by: • Premium, deductible, out of pocket costs and maximum out of pocket limit • Network • Benefits • Quality Rating
COVERAGE EFFECTIVE DATE FOR QHP AND SADP During Open Enrollment, coverage effective dates following the 15 th of the month rule; • Consumers who select a plan on or before the 15 th of the month will have coverage the first of the following month. • Consumers who select a plan on or after the 16 th of the month will have coverage the first of the second month. • For SEPs, coverage effective dates follow the SEP rules.
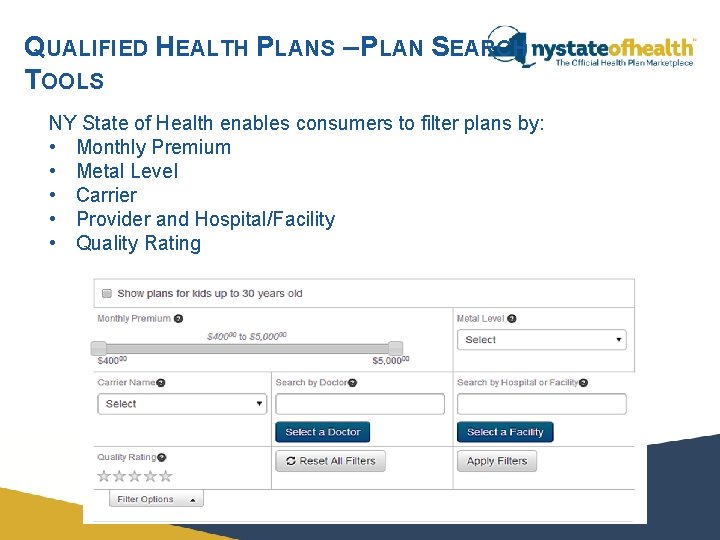
QUALIFIED HEALTH PLANS – PLAN SEARCH TOOLS NY State of Health enables consumers to filter plans by: • Monthly Premium • Metal Level • Carrier • Provider and Hospital/Facility • Quality Rating
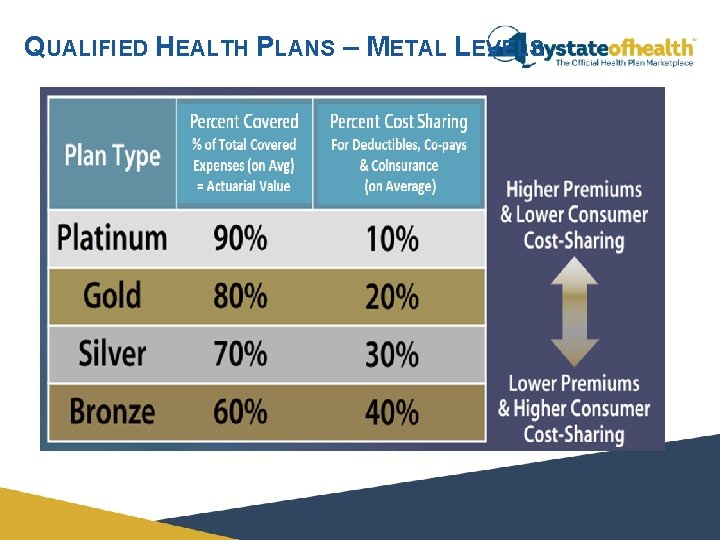
QUALIFIED HEALTH PLANS – METAL LEVELS
QHP – EXAMPLE ONE John - 27 years old - Income is 418% FPL: $49, 680 • 2 PCP Visits • 1 Emergency Room Visit (Broken Wrist) • 2 Tier Two Prescriptions Note: Because of John’s income, he does not qualify for APTC or CSR.
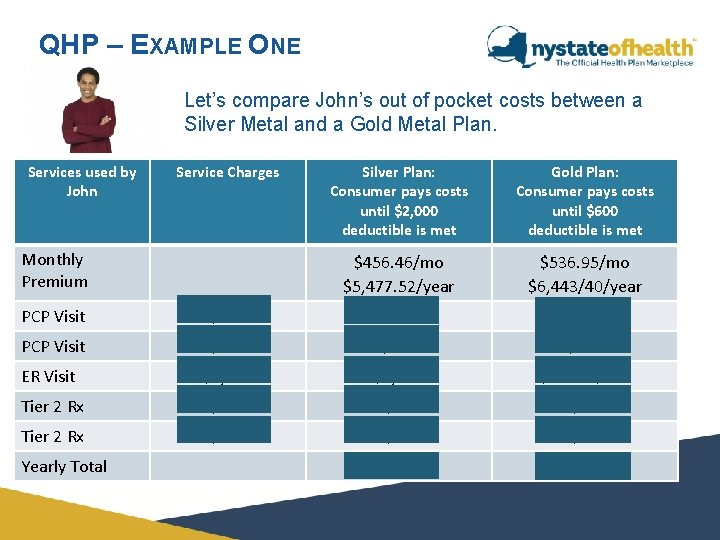
QHP – EXAMPLE ONE Let’s compare John’s out of pocket costs between a Silver Metal and a Gold Metal Plan. Services used by John Service Charges Monthly Premium Silver Plan: Consumer pays costs until $2, 000 deductible is met Gold Plan: Consumer pays costs until $600 deductible is met $456. 46/mo $5, 477. 52/year $536. 95/mo $6, 443/40/year PCP Visit $150 $0 $0 PCP Visit $150 ER Visit $1, 200 $450 + $150 Tier 2 Rx $200 $35 $35 $6, 897. 52 $7, 113. 40 Yearly Total
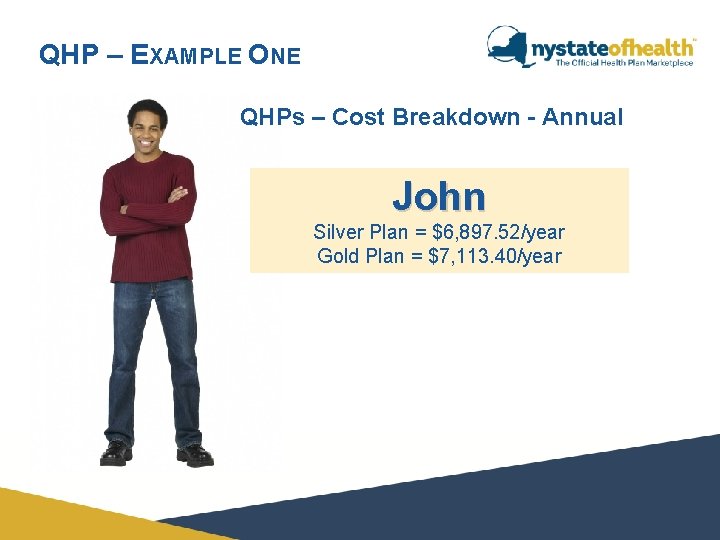
QHP – EXAMPLE ONE QHPs – Cost Breakdown - Annual John Silver Plan = $6, 897. 52/year Gold Plan = $7, 113. 40/year
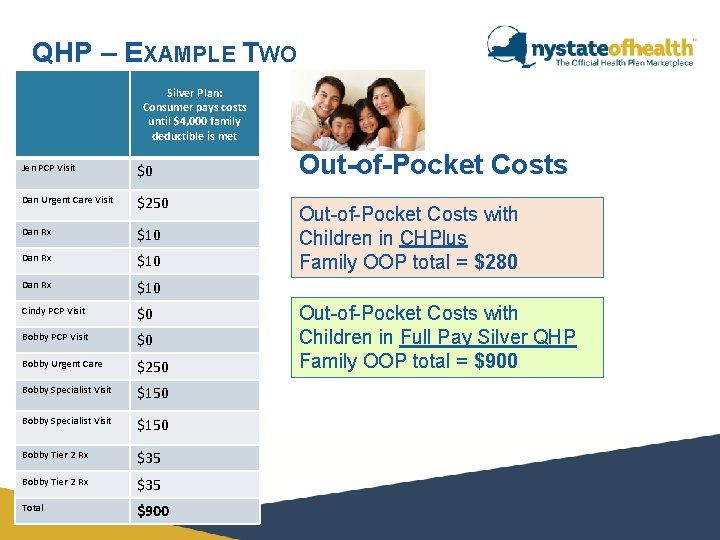
QHP – EXAMPLE TWO Meet the Chang Family Income is 402% FPL = $97, 800 Jen Chang – 1 PCP visit Dan Chang – 1 Trip to Urgent Care & 3 Generic Rx Cindy Chang – 1 PCP visit Bobby Chang – 1 PCP Visit, 1 Trip to Urgent Care, 2 Specialist Visits & 2 tier 2 Prescriptions.
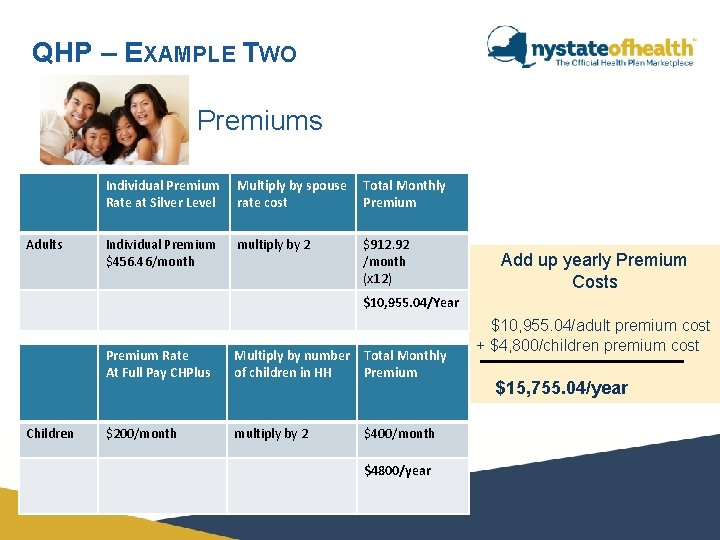
QHP – EXAMPLE TWO Premiums Adults Individual Premium Rate at Silver Level Multiply by spouse Total Monthly rate cost Premium Individual Premium $456. 46/month multiply by 2 $912. 92 /month (x 12) Add up yearly Premium Costs $10, 955. 04/Year $10, 955. 04/adult premium cost Children Premium Rate At Full Pay CHPlus Multiply by number Total Monthly of children in HH Premium $200/month multiply by 2 $400/month $4800/year + $4, 800/children premium cost $15, 755. 04/year
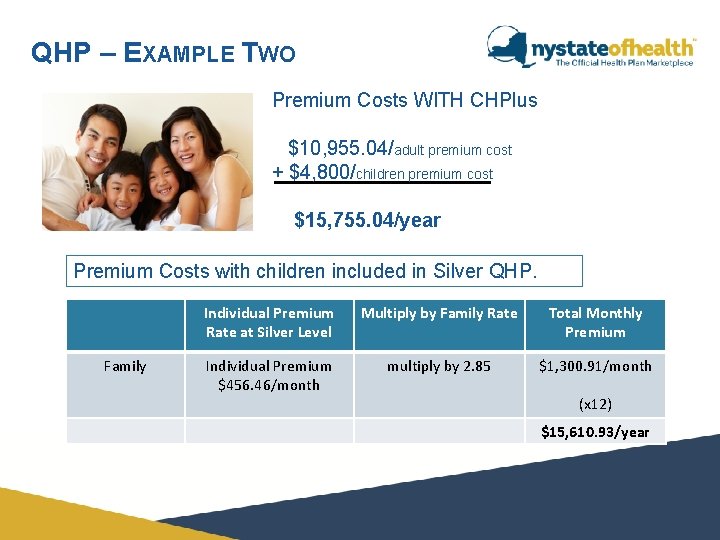
QHP – EXAMPLE TWO Premium Costs WITH CHPlus $10, 955. 04/adult premium cost + $4, 800/children premium cost $15, 755. 04/year Premium Costs with children included in Silver QHP. Family Individual Premium Rate at Silver Level Multiply by Family Rate Total Monthly Premium Individual Premium $456. 46/month multiply by 2. 85 $1, 300. 91/month (x 12) $15, 610. 93/year
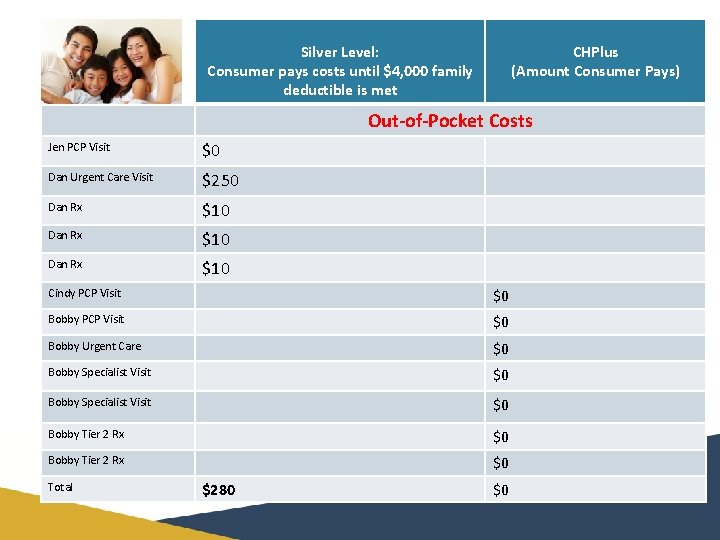
Silver Level: Consumer pays costs until $4, 000 family deductible is met CHPlus (Amount Consumer Pays) Out-of-Pocket Costs Jen PCP Visit $0 Dan Urgent Care Visit $250 Dan Rx $10 Cindy PCP Visit $0 Bobby Urgent Care $0 Bobby Specialist Visit $0 Bobby Tier 2 Rx $0 Total $280 $0
QHP – EXAMPLE TWO Silver Plan: Consumer pays costs until $4, 000 family deductible is met Jen PCP Visit $0 Dan Urgent Care Visit $250 Dan Rx $10 Cindy PCP Visit $0 Bobby Urgent Care $250 Bobby Specialist Visit $150 Bobby Tier 2 Rx $35 Total $900 Out-of-Pocket Costs with Children in CHPlus Family OOP total = $280 Out-of-Pocket Costs with Children in Full Pay Silver QHP Family OOP total = $900
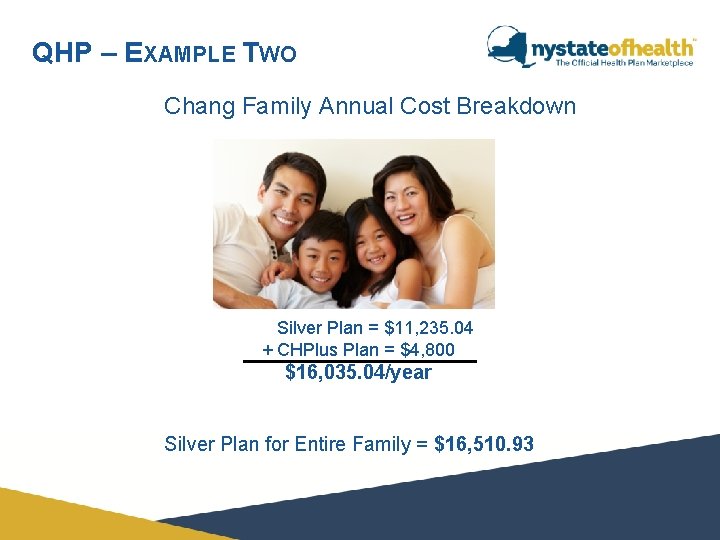
QHP – EXAMPLE TWO Chang Family Annual Cost Breakdown Silver Plan = $11, 235. 04 + CHPlus Plan = $4, 800 $16, 035. 04/year Silver Plan for Entire Family = $16, 510. 93
PLAN SELECTION PAGE
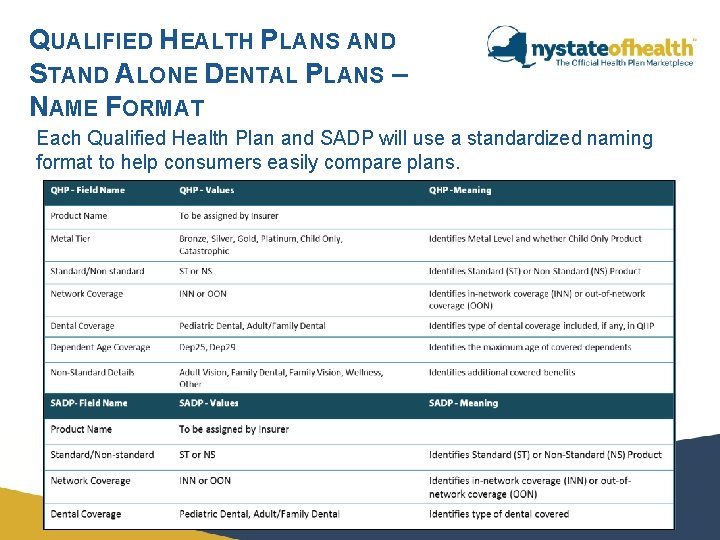
QUALIFIED HEALTH PLANS AND STAND ALONE DENTAL PLANS – NAME FORMAT Each Qualified Health Plan and SADP will use a standardized naming format to help consumers easily compare plans.
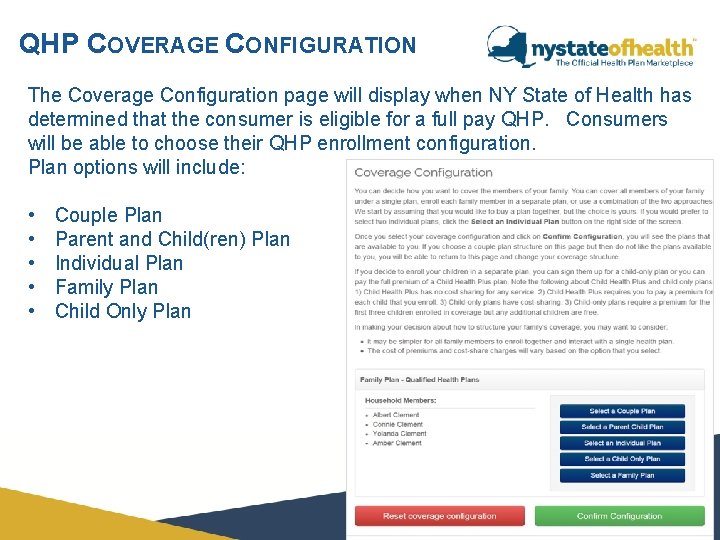
QHP COVERAGE CONFIGURATION The Coverage Configuration page will display when NY State of Health has determined that the consumer is eligible for a full pay QHP. Consumers will be able to choose their QHP enrollment configuration. Plan options will include: • • • Couple Plan Parent and Child(ren) Plan Individual Plan Family Plan Child Only Plan
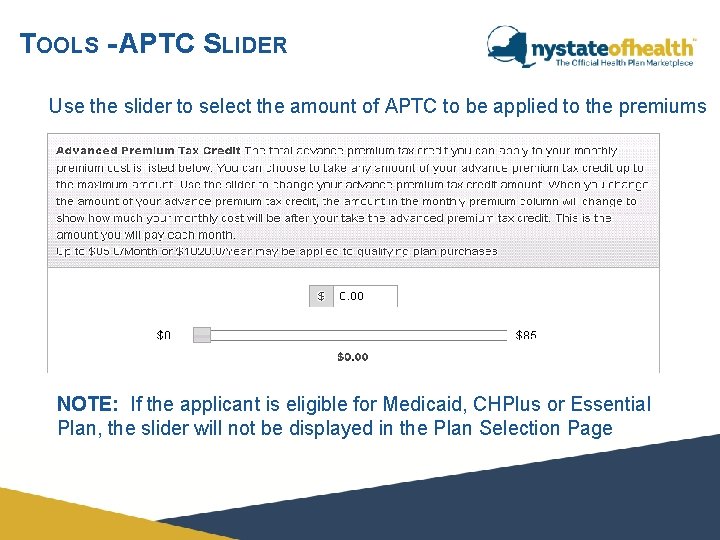
TOOLS - APTC SLIDER Use the slider to select the amount of APTC to be applied to the premiums NOTE: If the applicant is eligible for Medicaid, CHPlus or Essential Plan, the slider will not be displayed in the Plan Selection Page
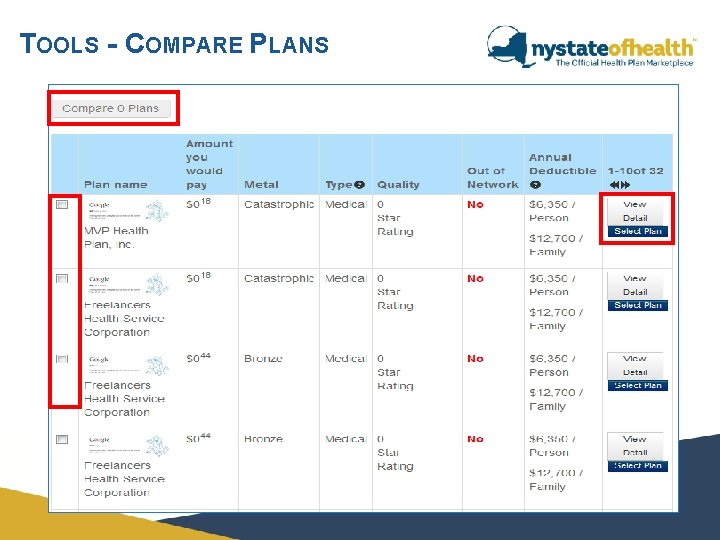
TOOLS - COMPARE PLANS
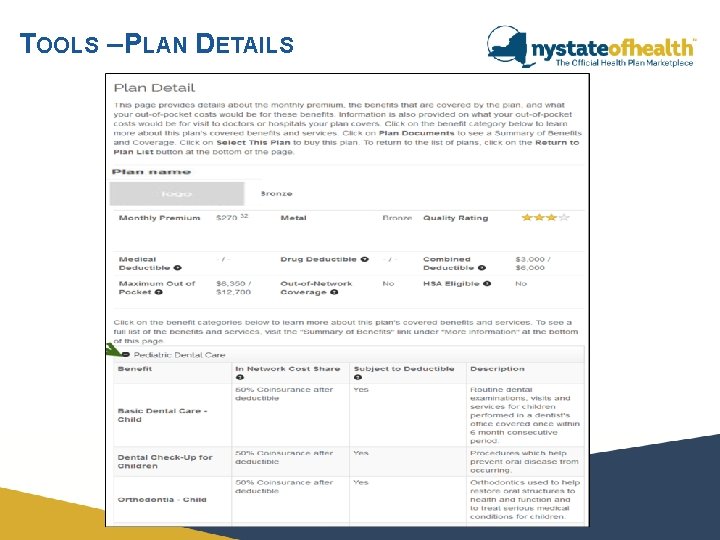
TOOLS – PLAN DETAILS
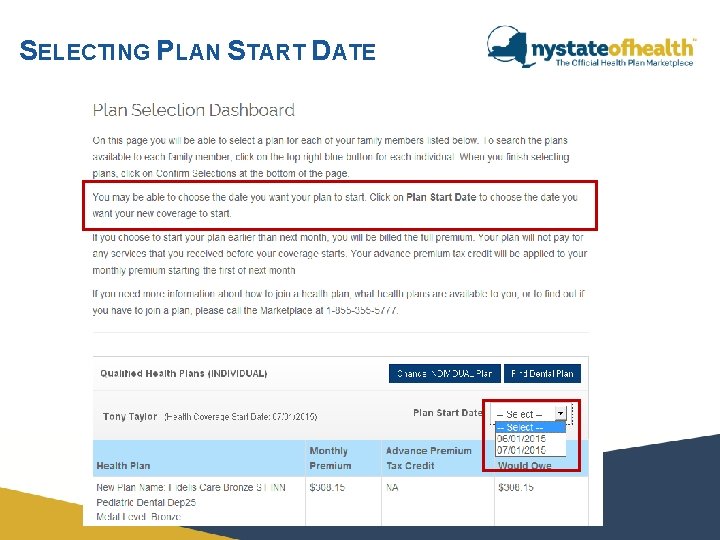
SELECTING PLAN START DATE
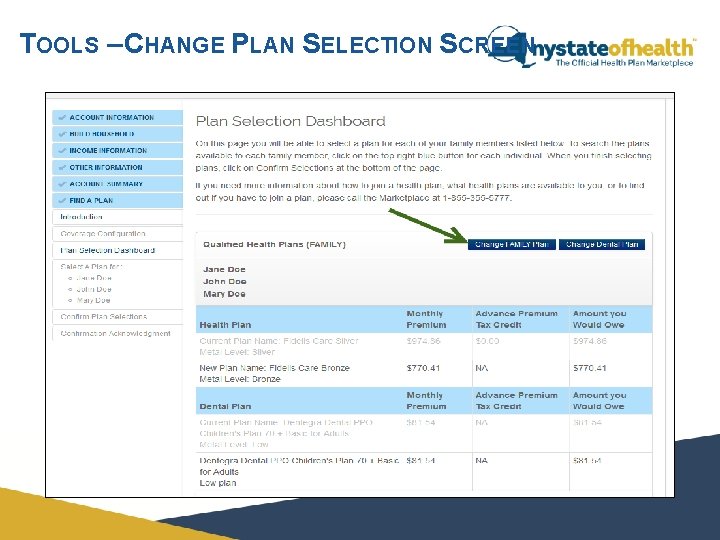
TOOLS – CHANGE PLAN SELECTION SCREEN
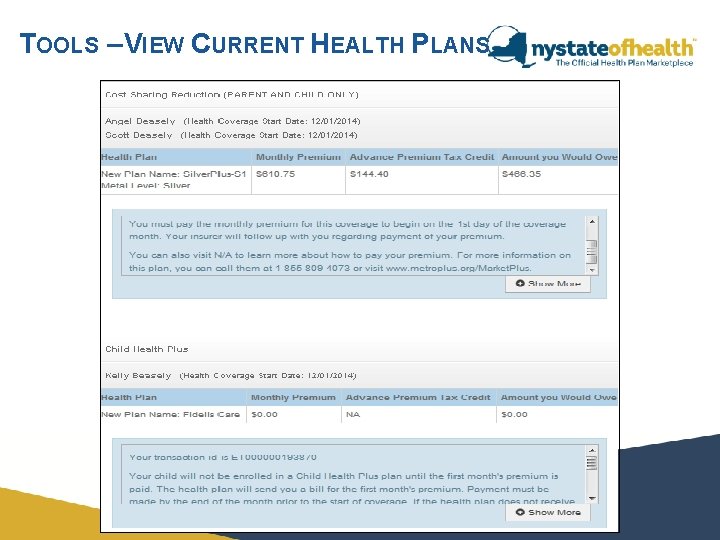
TOOLS – VIEW CURRENT HEALTH PLANS
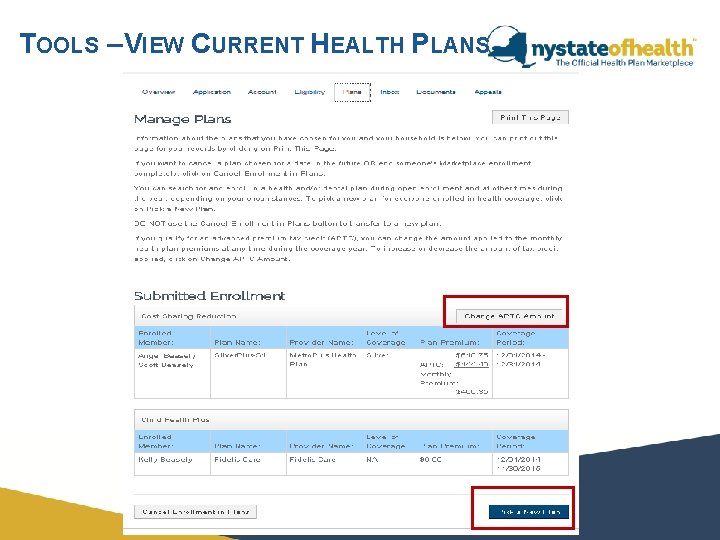
TOOLS – VIEW CURRENT HEALTH PLANS
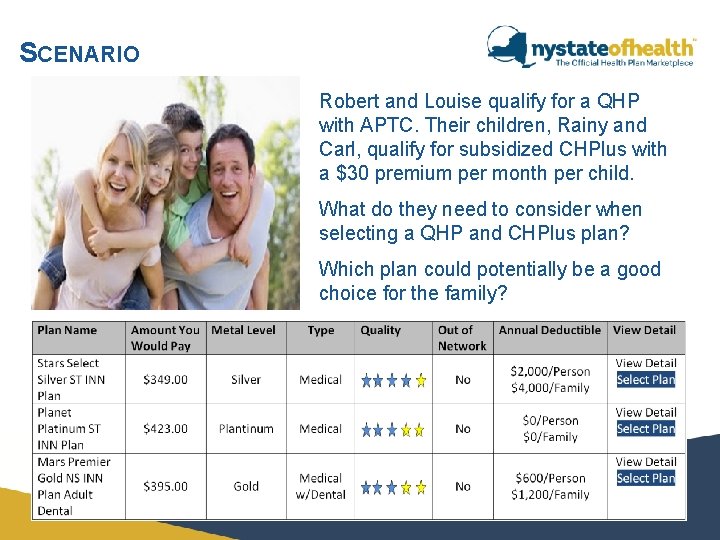
SCENARIO Robert and Louise qualify for a QHP with APTC. Their children, Rainy and Carl, qualify for subsidized CHPlus with a $30 premium per month per child. What do they need to consider when selecting a QHP and CHPlus plan? Which plan could potentially be a good choice for the family?
WHAT QUESTIONS DO YOU HAVE?