
Notes Receivable A written promise to pay Usually
Notes Receivable • A written promise to pay • Usually longer-term and more formal • Usually for a stated amount and a specified period • Either formally stated or implicit interest rate
Notes Receivable • A written promise to pay • Usually longer-term and more formal • Usually for a stated amount and a specified period • Either formally stated or implicit interest rate Implicit interest is when there is no formally stated interest rate, but the note is priced at a discount.
Notes Receivable • A written promise to pay • Usually longer-term and more formal • Usually for a stated amount and a specified period • Either formally stated or implicit interest rate Implicit interest is when there is no formally stated interest rate, but the note is priced at a discount. For example, a $1, 000, 1 -year note (with no stated interest rate) that sells for $900 has an implied interest rate of 11. 1%.
Notes Receivable Since notes tend to be longer-term, inflation whittles away the amount we can expect to recover from the note’s proceeds.
Notes Receivable Since notes tend to be longer-term, inflation whittles away the amount we can expect to recover from the note’s proceeds. To handle this, we generally carry long-term notes receivable on the balance sheet at their net present value.
Notes Receivable Since notes tend to be longer-term, inflation whittles away the amount we can expect to recover from the note’s proceeds. To handle this, we generally carry long-term notes receivable on the balance sheet at their net present value. Short-term notes can be carried at face value, since they will likely not suffer from inflation.
Valuing Notes Receivable To properly value long-term notes, we need the following information:
Valuing Notes Receivable To properly value long-term notes, we need the following information: • Stated interest rate • Date of issue • Interest payment schedule • Principal payment schedule (usually end of note term) • Market interest rate for similar risk note (discount rate)
Valuing Notes Receivable Using this information, do the following:
Valuing Notes Receivable Using this information, do the following: 1. Set up repayment timeline.
Valuing Notes Receivable Using this information, do the following: 1. Set up repayment timeline. 2. Plot actual cash inflows on timeline, using stated interest rate and face value of the note.
Valuing Notes Receivable Using this information, do the following: 1. Set up repayment timeline. 2. Plot actual cash inflows on timeline, using stated interest rate and face value of the note. 3. Discount plotted cash inflows using market equivalent-risk rate of interest (discount rate).
Valuing Notes Receivable Example: 4 year note; no stated interest; $10, 000 face value
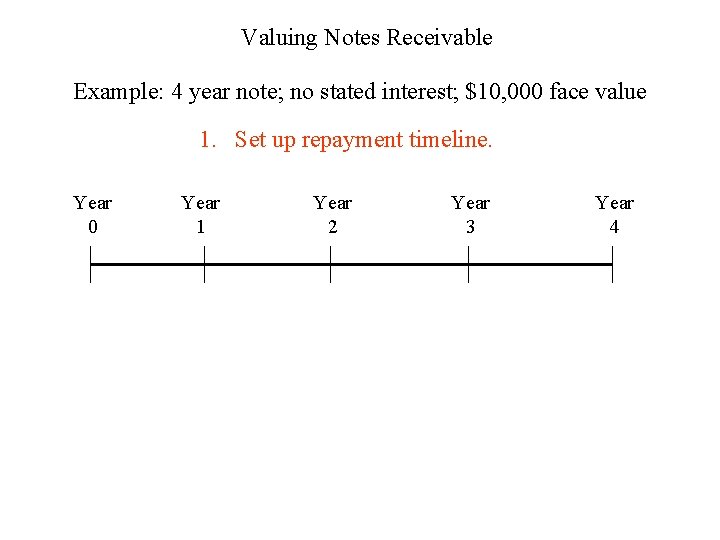
Valuing Notes Receivable Example: 4 year note; no stated interest; $10, 000 face value 1. Set up repayment timeline. Year 0 Year 1 Year 2 Year 3 Year 4
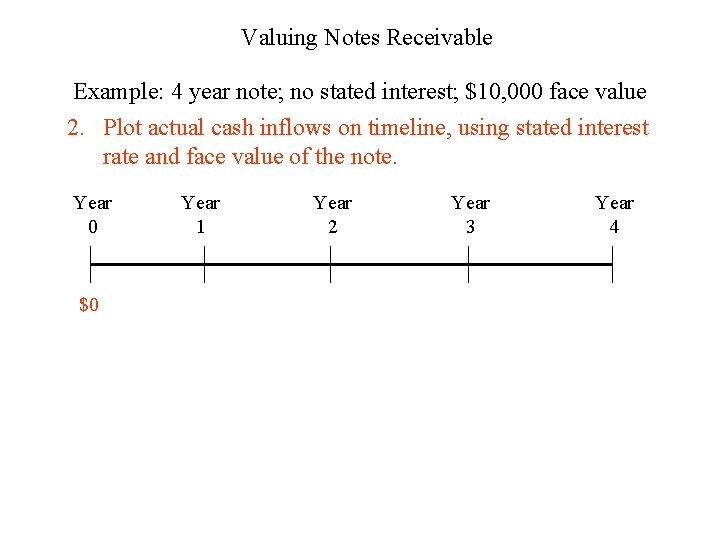
Valuing Notes Receivable Example: 4 year note; no stated interest; $10, 000 face value 2. Plot actual cash inflows on timeline, using stated interest rate and face value of the note. Year 0 $0 Year 1 Year 2 Year 3 Year 4
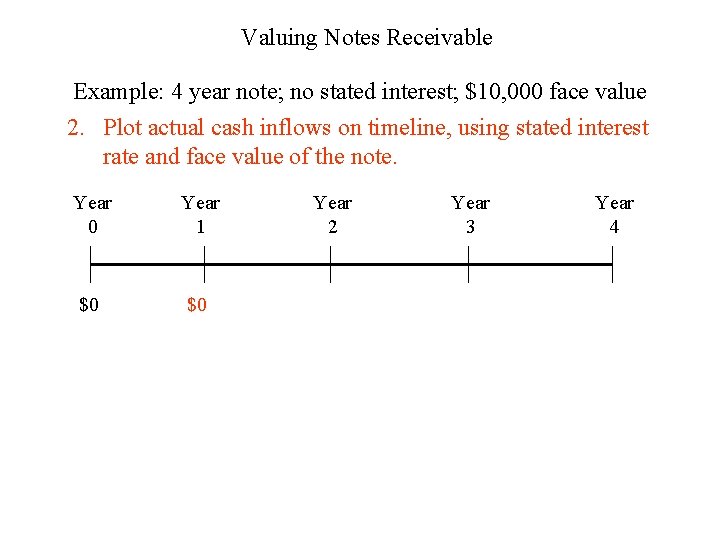
Valuing Notes Receivable Example: 4 year note; no stated interest; $10, 000 face value 2. Plot actual cash inflows on timeline, using stated interest rate and face value of the note. Year 0 Year 1 $0 $0 Year 2 Year 3 Year 4
Valuing Notes Receivable Example: 4 year note; no stated interest; $10, 000 face value 2. Plot actual cash inflows on timeline, using stated interest rate and face value of the note. Year 0 Year 1 Year 2 $0 $0 $0 Year 3 Year 4
Valuing Notes Receivable Example: 4 year note; no stated interest; $10, 000 face value 2. Plot actual cash inflows on timeline, using stated interest rate and face value of the note. Year 0 Year 1 Year 2 Year 3 $0 $0 Year 4
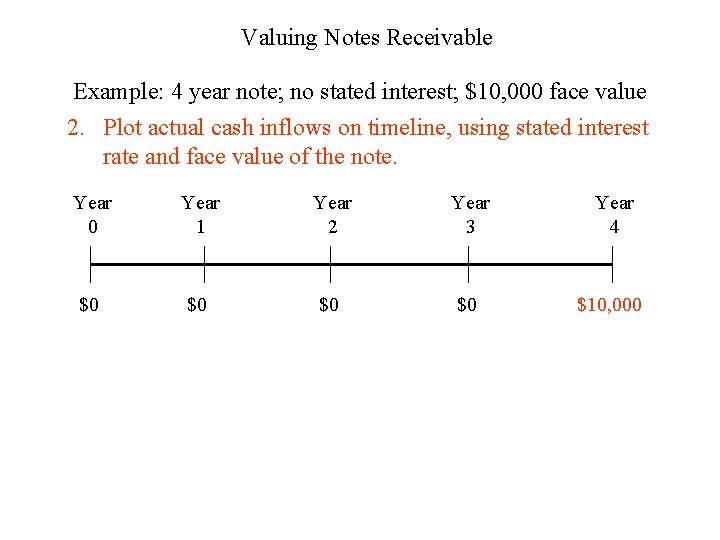
Valuing Notes Receivable Example: 4 year note; no stated interest; $10, 000 face value 2. Plot actual cash inflows on timeline, using stated interest rate and face value of the note. Year 0 Year 1 Year 2 Year 3 Year 4 $0 $0 $10, 000
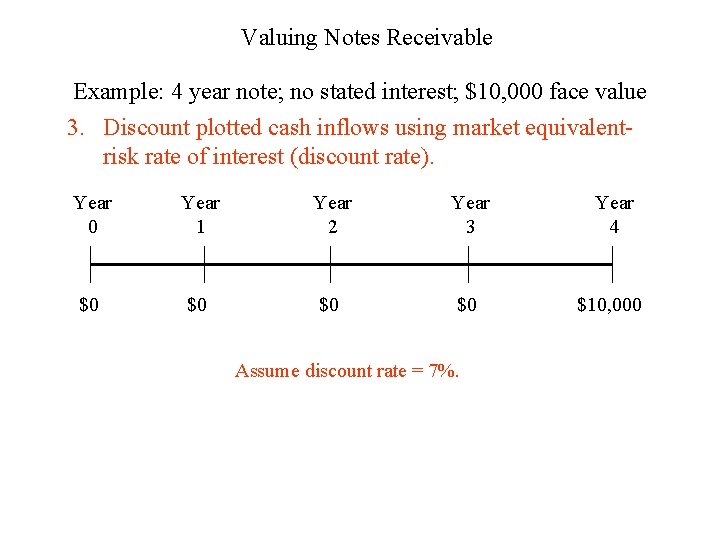
Valuing Notes Receivable Example: 4 year note; no stated interest; $10, 000 face value 3. Discount plotted cash inflows using market equivalentrisk rate of interest (discount rate). Year 0 Year 1 Year 2 Year 3 Year 4 $0 $0 $10, 000 Assume discount rate = 7%.
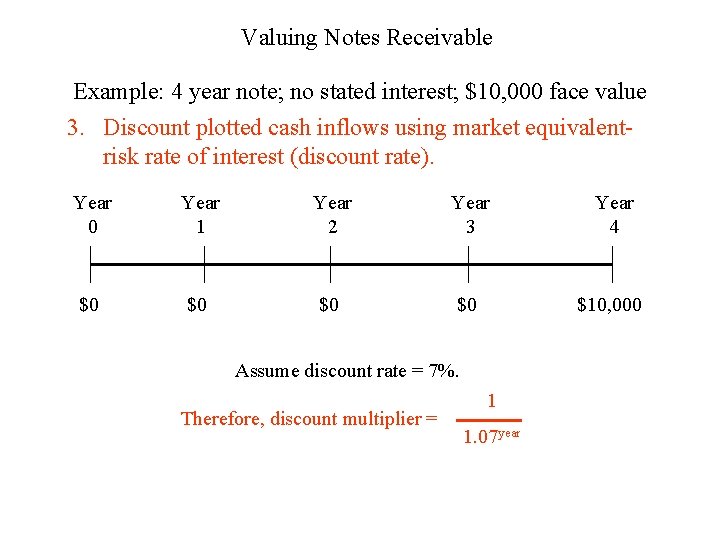
Valuing Notes Receivable Example: 4 year note; no stated interest; $10, 000 face value 3. Discount plotted cash inflows using market equivalentrisk rate of interest (discount rate). Year 0 Year 1 Year 2 Year 3 Year 4 $0 $0 $10, 000 Assume discount rate = 7%. Therefore, discount multiplier = 1 1. 07 year
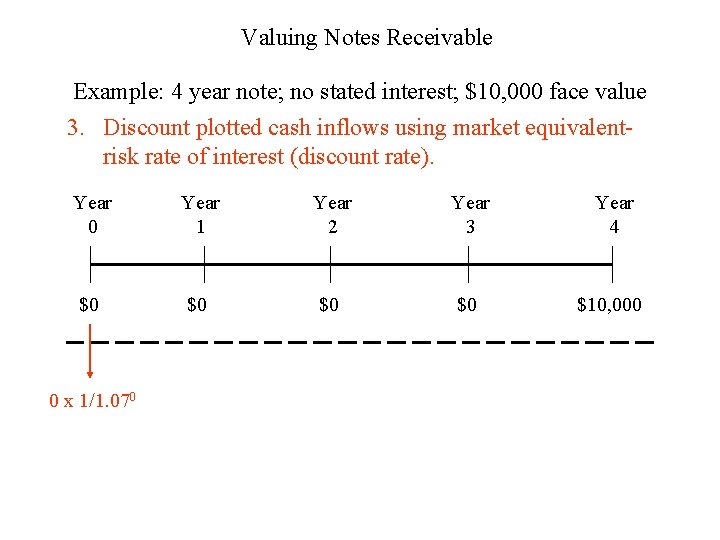
Valuing Notes Receivable Example: 4 year note; no stated interest; $10, 000 face value 3. Discount plotted cash inflows using market equivalentrisk rate of interest (discount rate). Year 0 Year 1 Year 2 Year 3 Year 4 $0 $0 $10, 000 0 x 1/1. 070
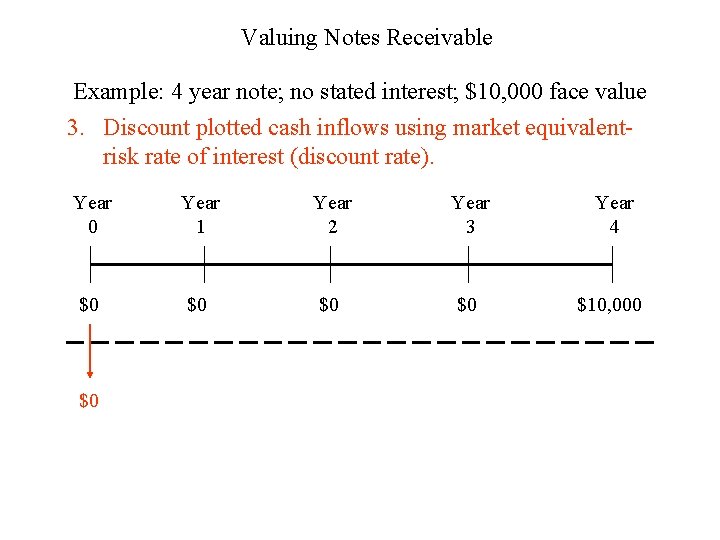
Valuing Notes Receivable Example: 4 year note; no stated interest; $10, 000 face value 3. Discount plotted cash inflows using market equivalentrisk rate of interest (discount rate). Year 0 Year 1 Year 2 Year 3 Year 4 $0 $0 $10, 000 $0
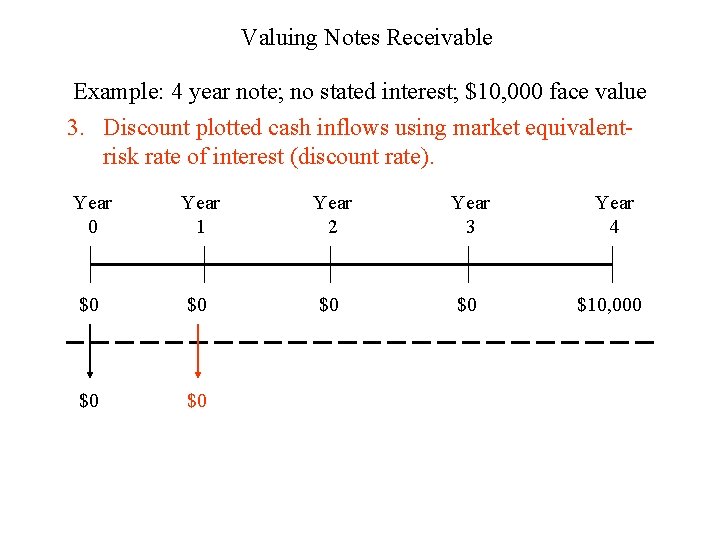
Valuing Notes Receivable Example: 4 year note; no stated interest; $10, 000 face value 3. Discount plotted cash inflows using market equivalentrisk rate of interest (discount rate). Year 0 Year 1 Year 2 Year 3 Year 4 $0 $0 $10, 000 $0 $0
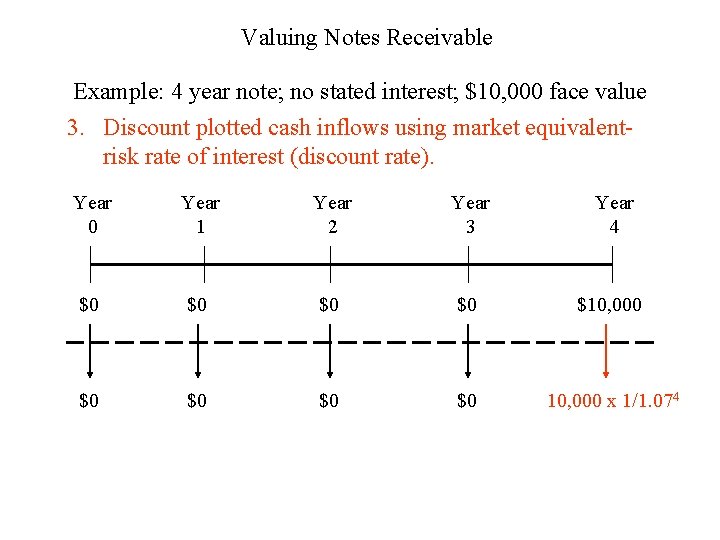
Valuing Notes Receivable Example: 4 year note; no stated interest; $10, 000 face value 3. Discount plotted cash inflows using market equivalentrisk rate of interest (discount rate). Year 0 Year 1 Year 2 Year 3 Year 4 $0 $0 $10, 000 $0 $0 10, 000 x 1/1. 074
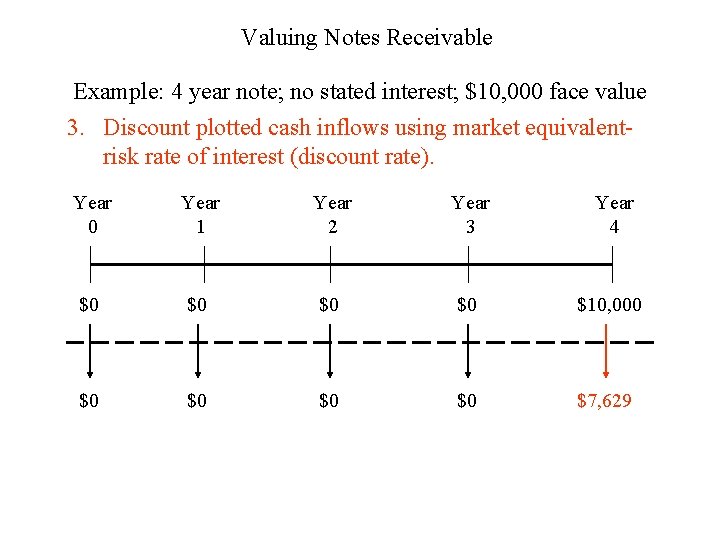
Valuing Notes Receivable Example: 4 year note; no stated interest; $10, 000 face value 3. Discount plotted cash inflows using market equivalentrisk rate of interest (discount rate). Year 0 Year 1 Year 2 Year 3 Year 4 $0 $0 $10, 000 $0 $0 $7, 629
Valuing Notes Receivable Example: 4 year note; no stated interest; $10, 000 face value The journal entry to record this note is:
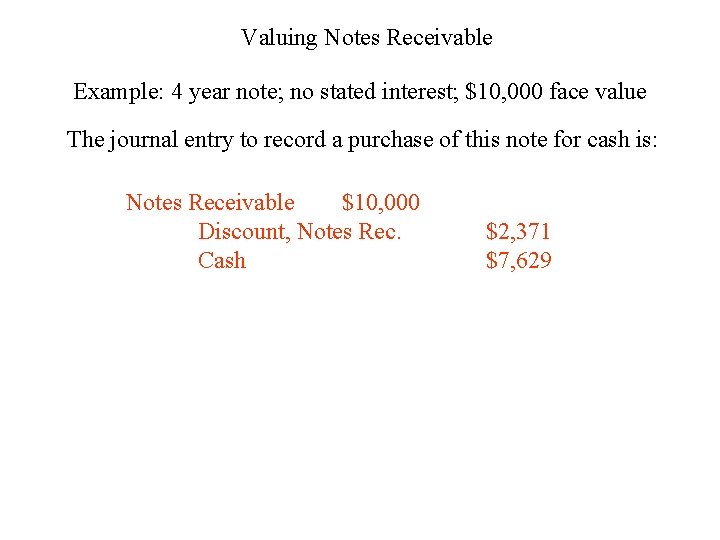
Valuing Notes Receivable Example: 4 year note; no stated interest; $10, 000 face value The journal entry to record a purchase of this note for cash is: Notes Receivable $10, 000 Discount, Notes Rec. Cash $2, 371 $7, 629
Valuing Notes Receivable Example: 4 year note; 9% stated interest; $10, 000 face value
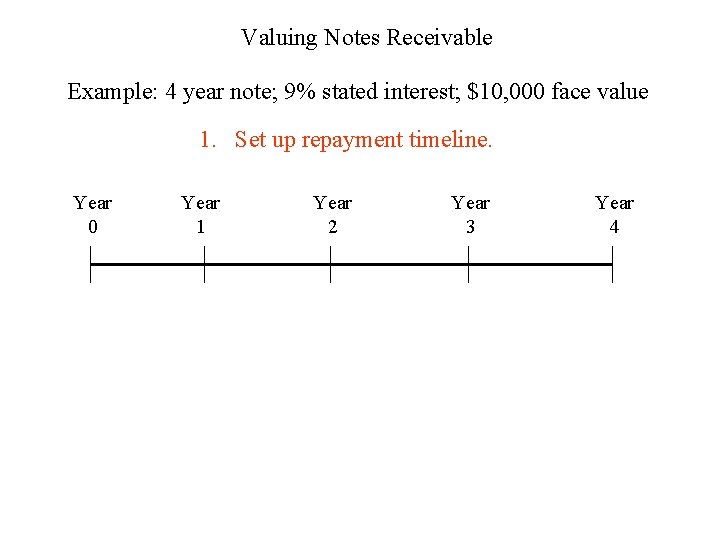
Valuing Notes Receivable Example: 4 year note; 9% stated interest; $10, 000 face value 1. Set up repayment timeline. Year 0 Year 1 Year 2 Year 3 Year 4
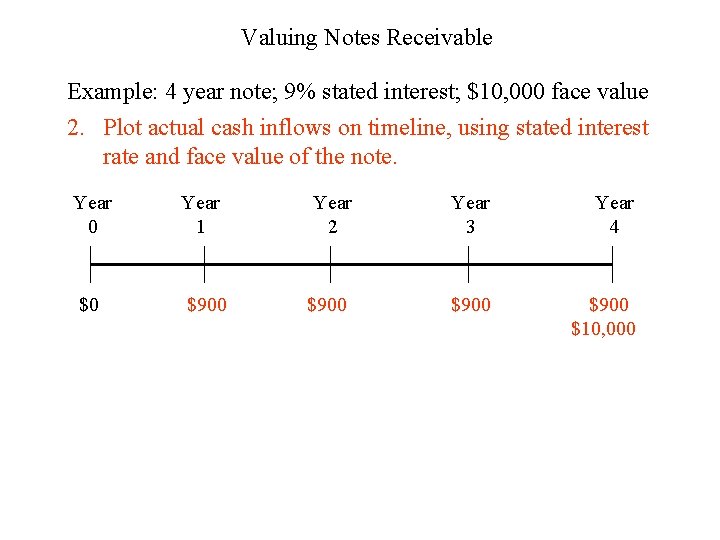
Valuing Notes Receivable Example: 4 year note; 9% stated interest; $10, 000 face value 2. Plot actual cash inflows on timeline, using stated interest rate and face value of the note. Year 0 Year 1 $0 $900 Year 2 Year 3 Year 4 $900 $10, 000
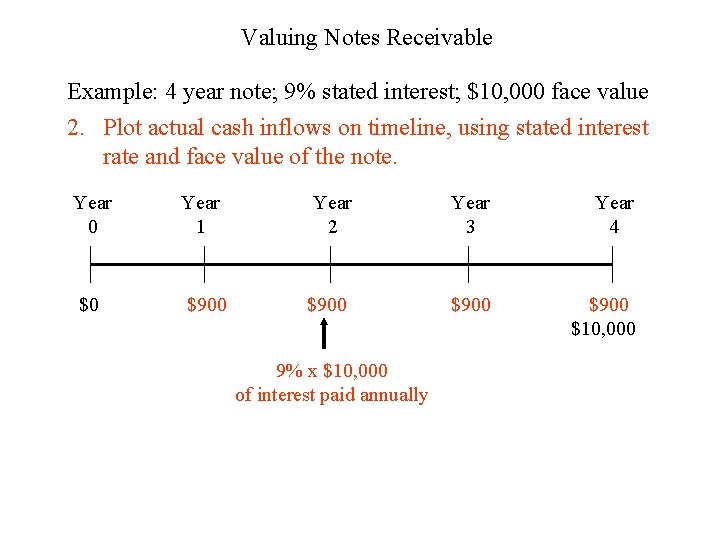
Valuing Notes Receivable Example: 4 year note; 9% stated interest; $10, 000 face value 2. Plot actual cash inflows on timeline, using stated interest rate and face value of the note. Year 0 Year 1 $0 $900 Year 2 Year 3 Year 4 $900 $10, 000 9% x $10, 000 of interest paid annually
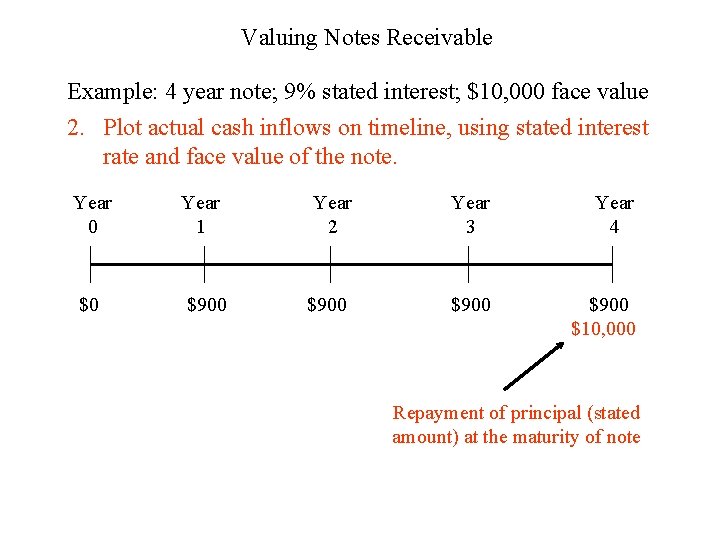
Valuing Notes Receivable Example: 4 year note; 9% stated interest; $10, 000 face value 2. Plot actual cash inflows on timeline, using stated interest rate and face value of the note. Year 0 Year 1 $0 $900 Year 2 Year 3 Year 4 $900 $10, 000 Repayment of principal (stated amount) at the maturity of note
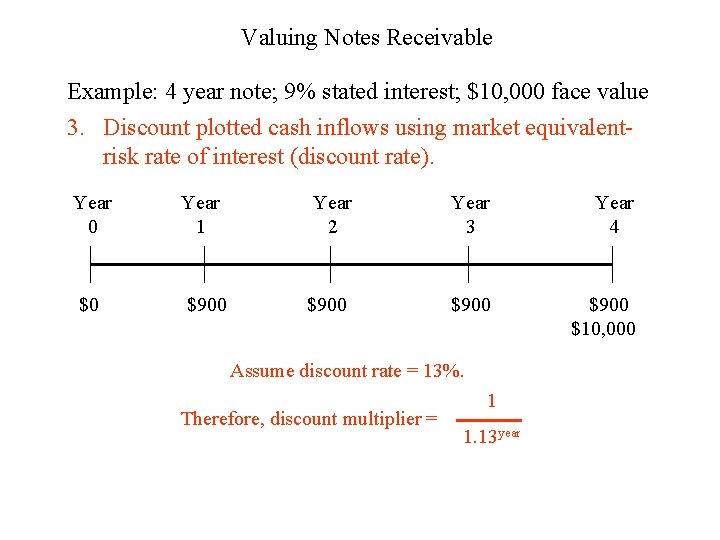
Valuing Notes Receivable Example: 4 year note; 9% stated interest; $10, 000 face value 3. Discount plotted cash inflows using market equivalentrisk rate of interest (discount rate). Year 0 Year 1 $0 $900 Year 2 Year 3 Year 4 $900 $10, 000 Assume discount rate = 13%. Therefore, discount multiplier = 1 1. 13 year
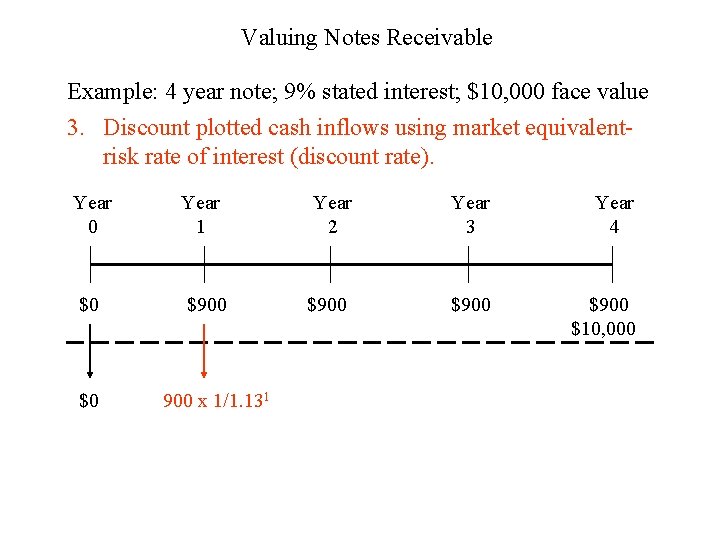
Valuing Notes Receivable Example: 4 year note; 9% stated interest; $10, 000 face value 3. Discount plotted cash inflows using market equivalentrisk rate of interest (discount rate). Year 0 Year 1 $0 $900 $0 900 x 1/1. 131 Year 2 Year 3 Year 4 $900 $10, 000
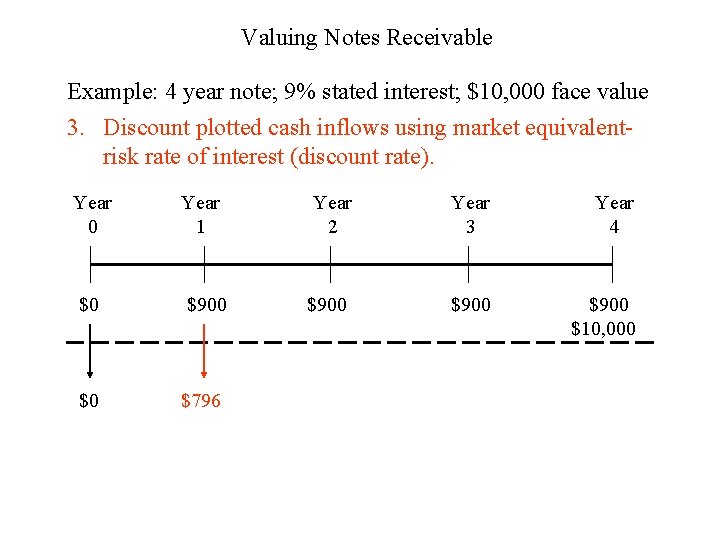
Valuing Notes Receivable Example: 4 year note; 9% stated interest; $10, 000 face value 3. Discount plotted cash inflows using market equivalentrisk rate of interest (discount rate). Year 0 Year 1 $0 $900 $0 $796 Year 2 Year 3 Year 4 $900 $10, 000
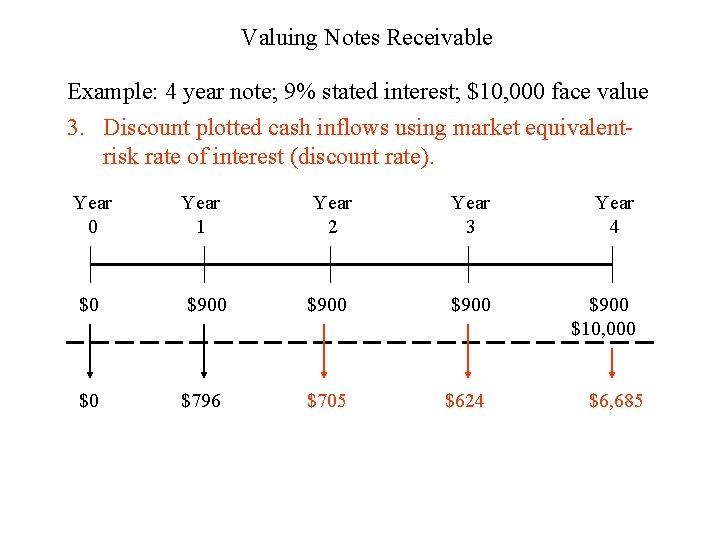
Valuing Notes Receivable Example: 4 year note; 9% stated interest; $10, 000 face value 3. Discount plotted cash inflows using market equivalentrisk rate of interest (discount rate). Year 0 Year 1 Year 2 Year 3 Year 4 $0 $900 $10, 000 $0 $796 $705 $624 $6, 685
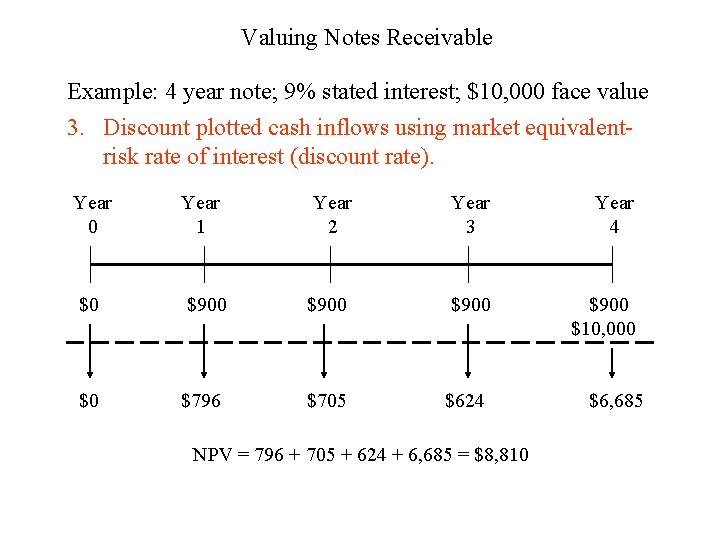
Valuing Notes Receivable Example: 4 year note; 9% stated interest; $10, 000 face value 3. Discount plotted cash inflows using market equivalentrisk rate of interest (discount rate). Year 0 Year 1 Year 2 Year 3 Year 4 $0 $900 $10, 000 $0 $796 $705 $624 NPV = 796 + 705 + 624 + 6, 685 = $8, 810 $6, 685
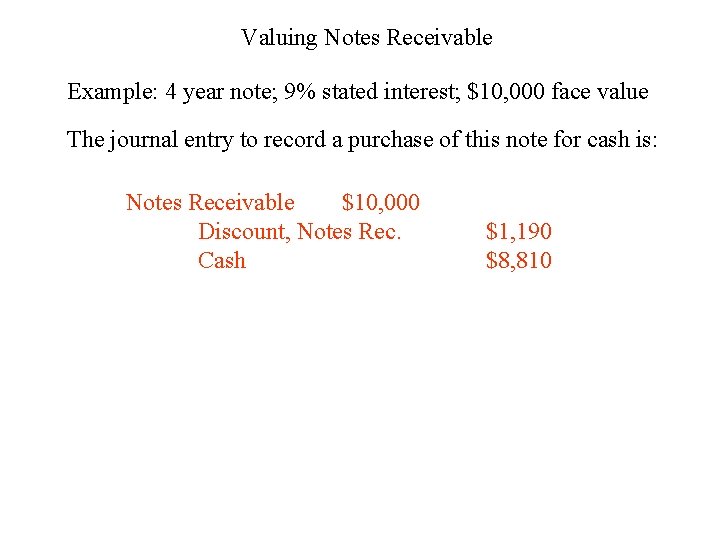
Valuing Notes Receivable Example: 4 year note; 9% stated interest; $10, 000 face value The journal entry to record a purchase of this note for cash is: Notes Receivable $10, 000 Discount, Notes Rec. Cash $1, 190 $8, 810
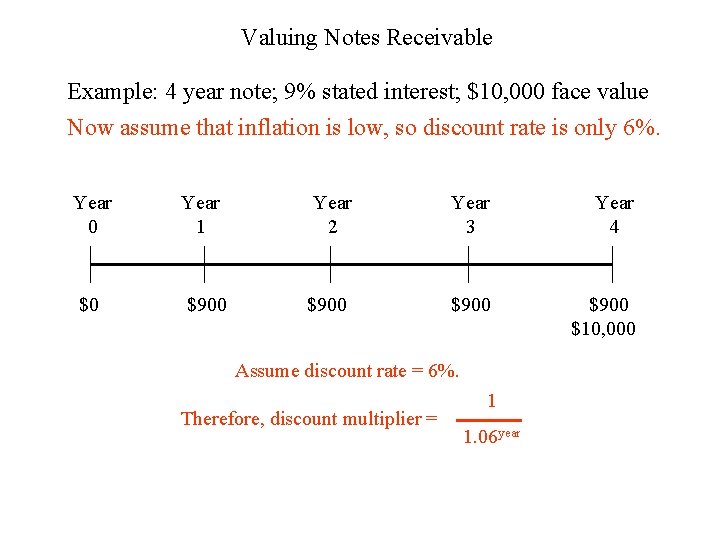
Valuing Notes Receivable Example: 4 year note; 9% stated interest; $10, 000 face value Now assume that inflation is low, so discount rate is only 6%. Year 0 Year 1 $0 $900 Year 2 Year 3 Year 4 $900 $10, 000 Assume discount rate = 6%. Therefore, discount multiplier = 1 1. 06 year
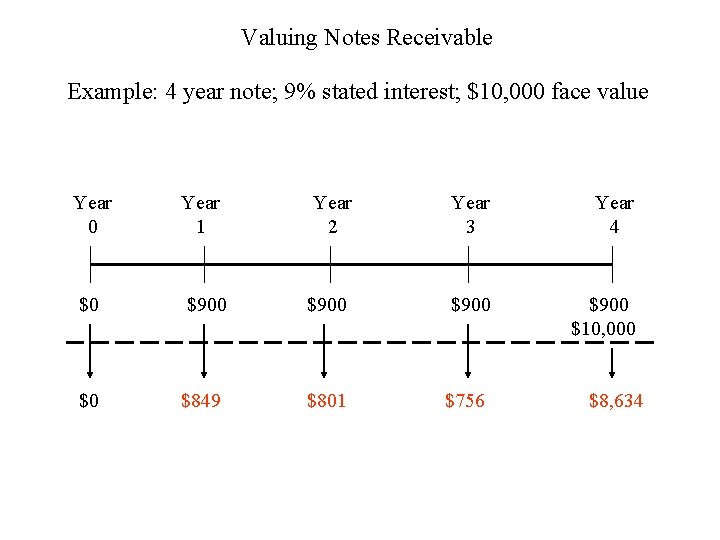
Valuing Notes Receivable Example: 4 year note; 9% stated interest; $10, 000 face value Year 0 Year 1 Year 2 Year 3 Year 4 $0 $900 $10, 000 $0 $849 $801 $756 $8, 634
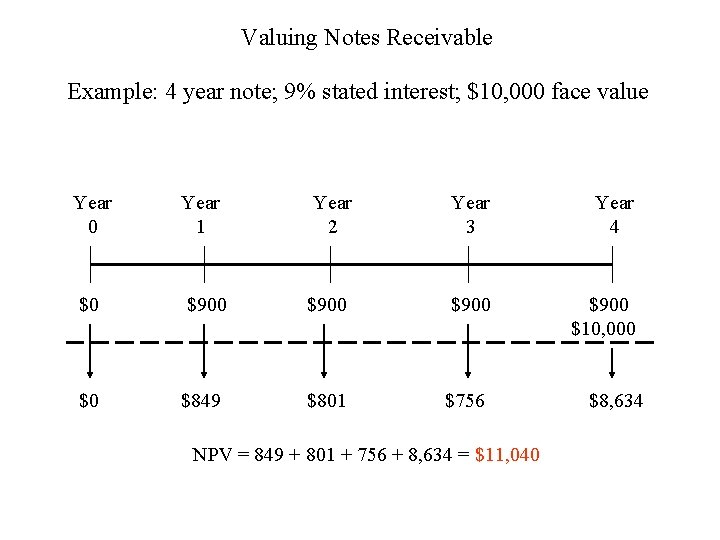
Valuing Notes Receivable Example: 4 year note; 9% stated interest; $10, 000 face value Year 0 Year 1 Year 2 Year 3 Year 4 $0 $900 $10, 000 $0 $849 $801 $756 NPV = 849 + 801 + 756 + 8, 634 = $11, 040 $8, 634
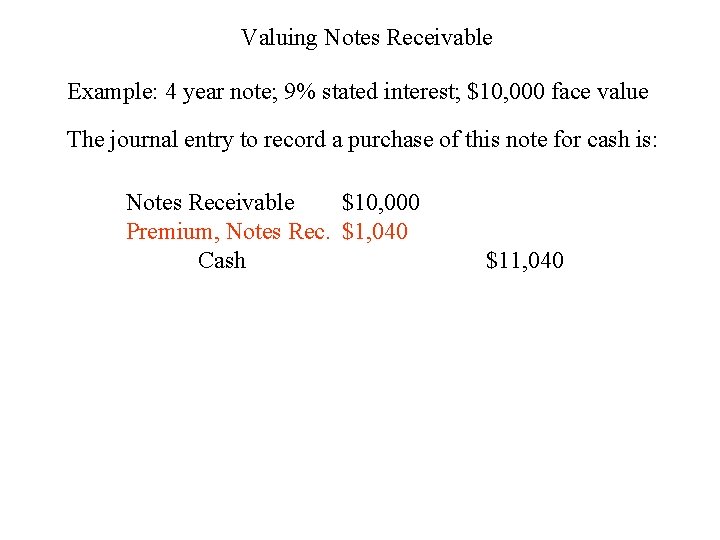
Valuing Notes Receivable Example: 4 year note; 9% stated interest; $10, 000 face value The journal entry to record a purchase of this note for cash is: Notes Receivable $10, 000 Premium, Notes Rec. $1, 040 Cash $11, 040
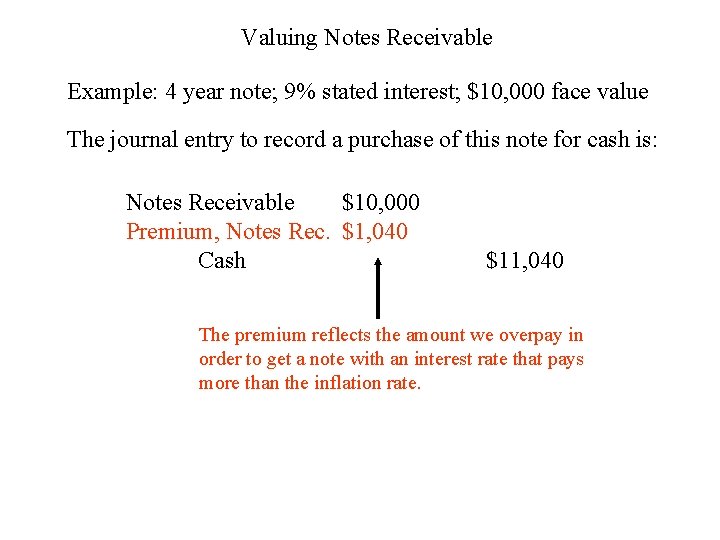
Valuing Notes Receivable Example: 4 year note; 9% stated interest; $10, 000 face value The journal entry to record a purchase of this note for cash is: Notes Receivable $10, 000 Premium, Notes Rec. $1, 040 Cash $11, 040 The premium reflects the amount we overpay in order to get a note with an interest rate that pays more than the inflation rate.
Notes Receivable Amortization of Discount
Notes Receivable Amortization of Discount Go back to our 13% interest rate example:
Notes Receivable Amortization of Discount Go back to our 13% interest rate example: Example: 4 year note; 9% stated interest; $10, 000 face value The journal entry to record a purchase of this note for cash is: Notes Receivable $10, 000 Discount, Notes Rec. Cash $1, 190 $8, 810
Notes Receivable Amortization of Discount At date of purchase, the balance sheet carries the note:
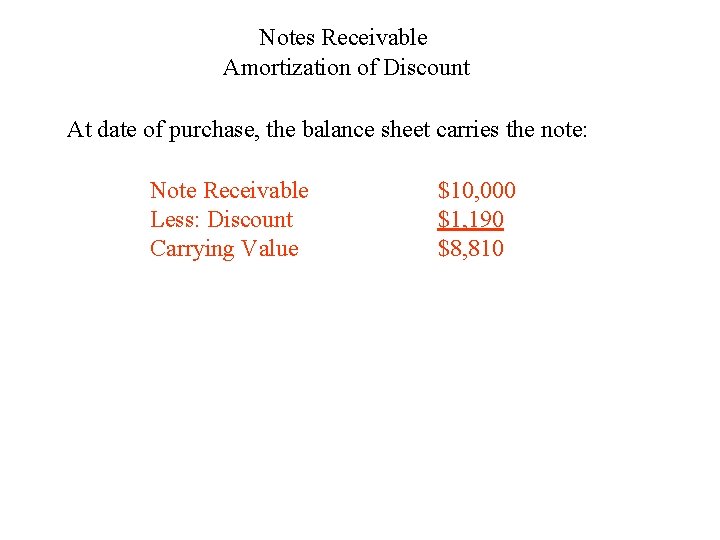
Notes Receivable Amortization of Discount At date of purchase, the balance sheet carries the note: Note Receivable Less: Discount Carrying Value $10, 000 $1, 190 $8, 810
Notes Receivable Amortization of Discount At date of purchase, the balance sheet carries the note: Note Receivable Less: Discount Carrying Value Amortization amount each year = $10, 000 $1, 190 $8, 810
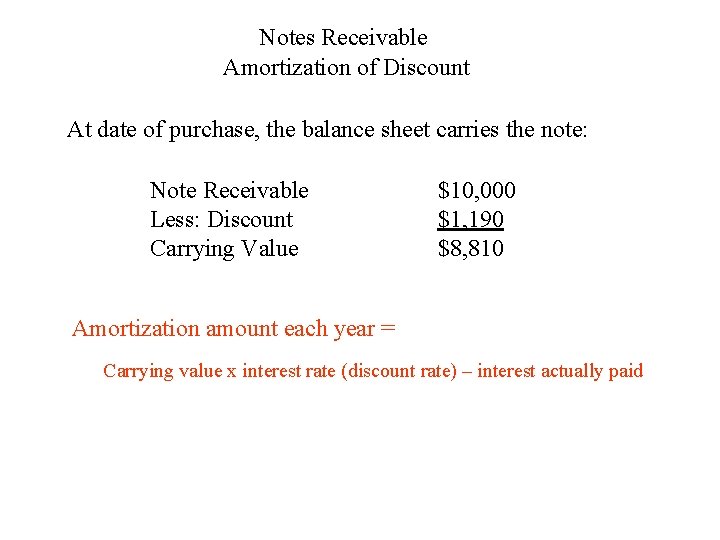
Notes Receivable Amortization of Discount At date of purchase, the balance sheet carries the note: Note Receivable Less: Discount Carrying Value $10, 000 $1, 190 $8, 810 Amortization amount each year = Carrying value x interest rate (discount rate) – interest actually paid
Notes Receivable Amortization of Discount At date of purchase, the balance sheet carries the note: Note Receivable Less: Discount Carrying Value $10, 000 $1, 190 $8, 810 Amortization amount each year = Carrying value x interest rate (discount rate) – interest actually paid Year 1 amortization =
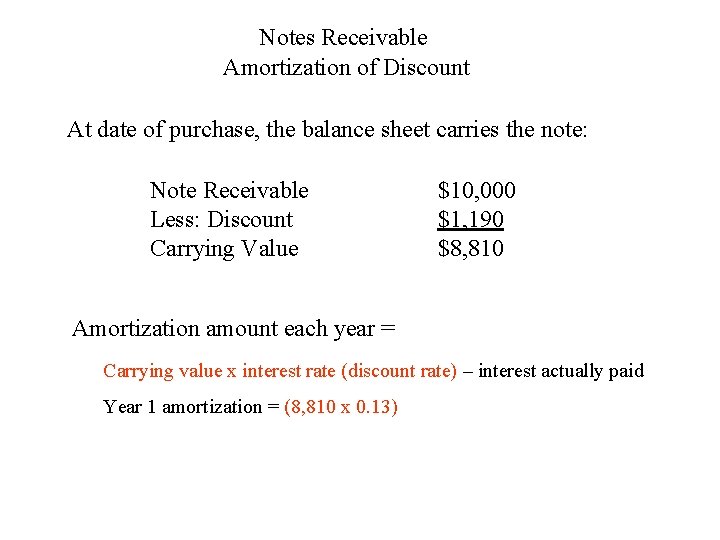
Notes Receivable Amortization of Discount At date of purchase, the balance sheet carries the note: Note Receivable Less: Discount Carrying Value $10, 000 $1, 190 $8, 810 Amortization amount each year = Carrying value x interest rate (discount rate) – interest actually paid Year 1 amortization = (8, 810 x 0. 13)
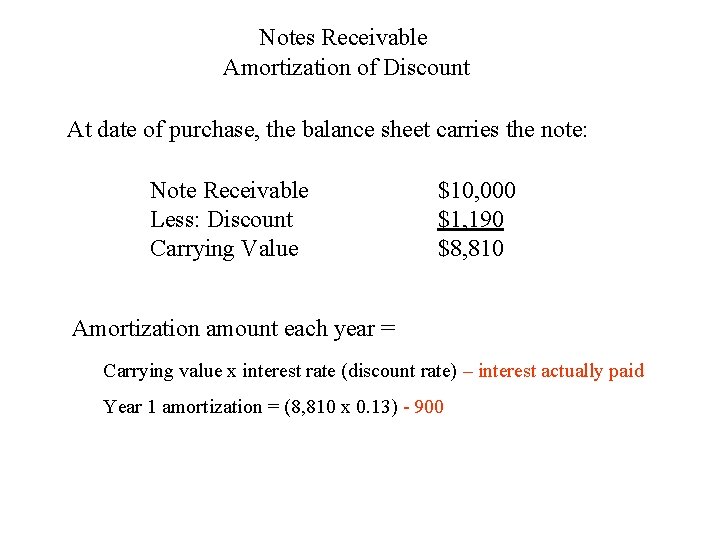
Notes Receivable Amortization of Discount At date of purchase, the balance sheet carries the note: Note Receivable Less: Discount Carrying Value $10, 000 $1, 190 $8, 810 Amortization amount each year = Carrying value x interest rate (discount rate) – interest actually paid Year 1 amortization = (8, 810 x 0. 13) - 900
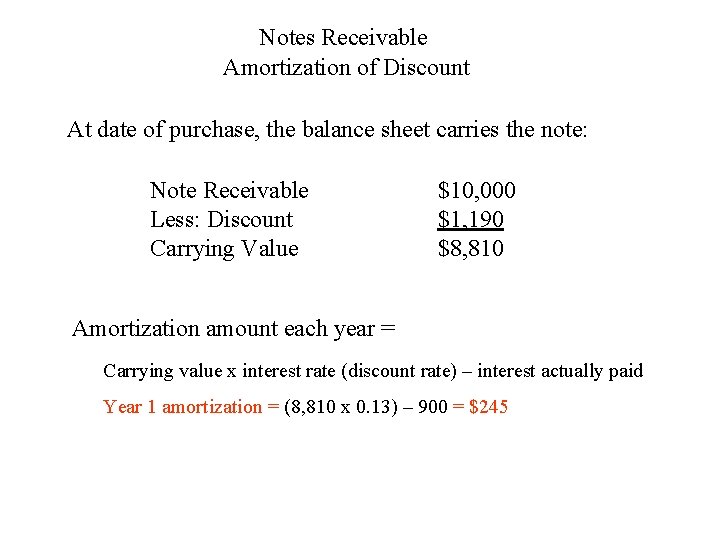
Notes Receivable Amortization of Discount At date of purchase, the balance sheet carries the note: Note Receivable Less: Discount Carrying Value $10, 000 $1, 190 $8, 810 Amortization amount each year = Carrying value x interest rate (discount rate) – interest actually paid Year 1 amortization = (8, 810 x 0. 13) – 900 = $245
Notes Receivable Amortization of Discount So, we can set up an annual amortization table:
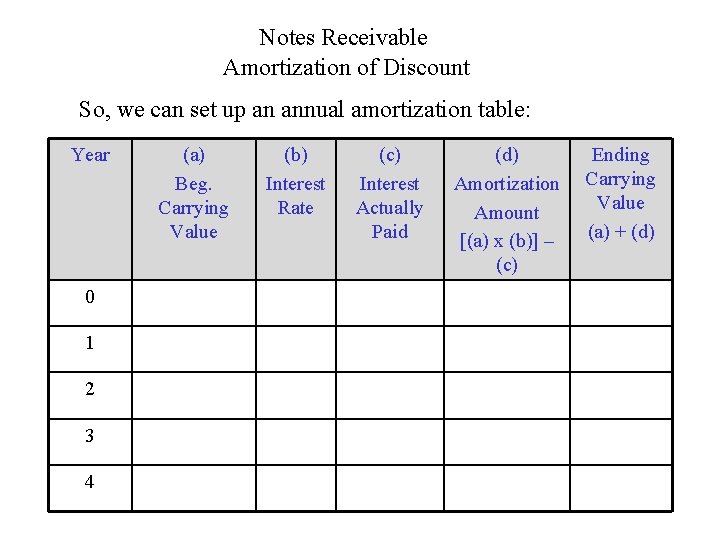
Notes Receivable Amortization of Discount So, we can set up an annual amortization table: Year 0 1 2 3 4 (a) Beg. Carrying Value (b) Interest Rate (c) Interest Actually Paid (d) Amortization Amount [(a) x (b)] – (c) Ending Carrying Value (a) + (d)
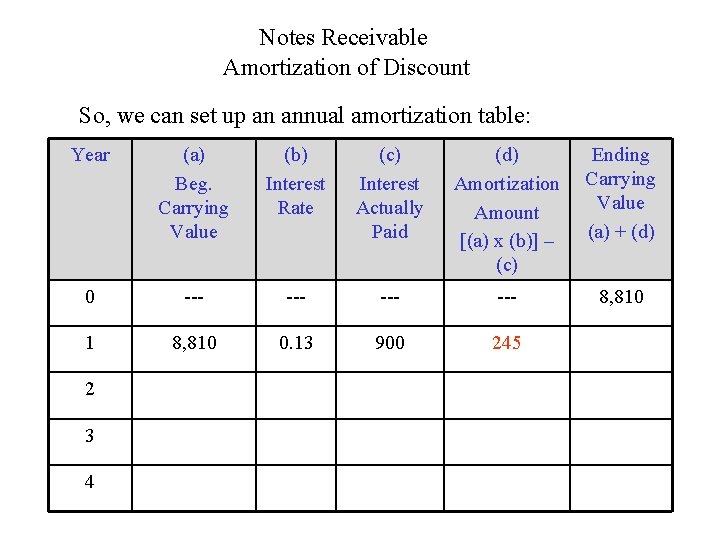
Notes Receivable Amortization of Discount So, we can set up an annual amortization table: Year (a) Beg. Carrying Value (b) Interest Rate (c) Interest Actually Paid (d) Amortization Amount [(a) x (b)] – (c) Ending Carrying Value (a) + (d) 0 --- --- 8, 810 1 8, 810 0. 13 900 245 2 3 4
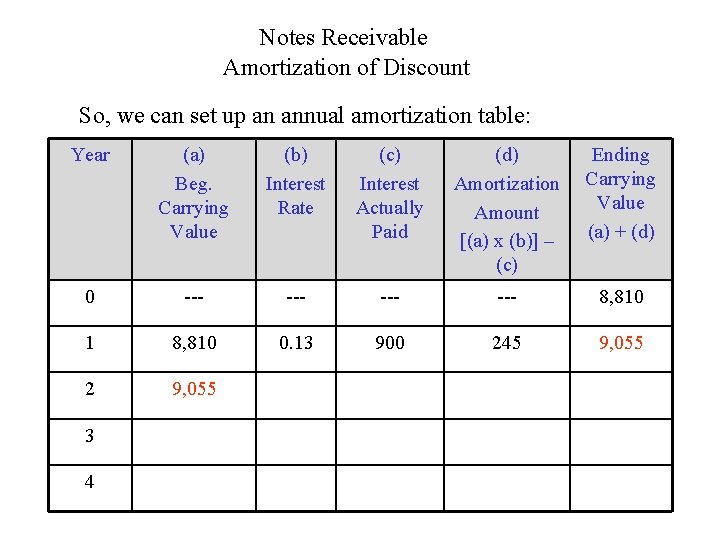
Notes Receivable Amortization of Discount So, we can set up an annual amortization table: Year (a) Beg. Carrying Value (b) Interest Rate (c) Interest Actually Paid (d) Amortization Amount [(a) x (b)] – (c) Ending Carrying Value (a) + (d) 0 --- --- 8, 810 1 8, 810 0. 13 900 245 9, 055 2 9, 055 3 4
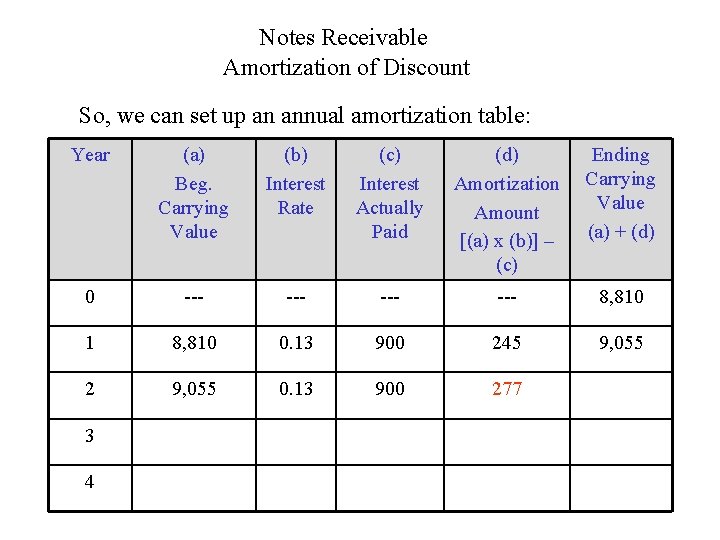
Notes Receivable Amortization of Discount So, we can set up an annual amortization table: Year (a) Beg. Carrying Value (b) Interest Rate (c) Interest Actually Paid (d) Amortization Amount [(a) x (b)] – (c) Ending Carrying Value (a) + (d) 0 --- --- 8, 810 1 8, 810 0. 13 900 245 9, 055 2 9, 055 0. 13 900 277 3 4
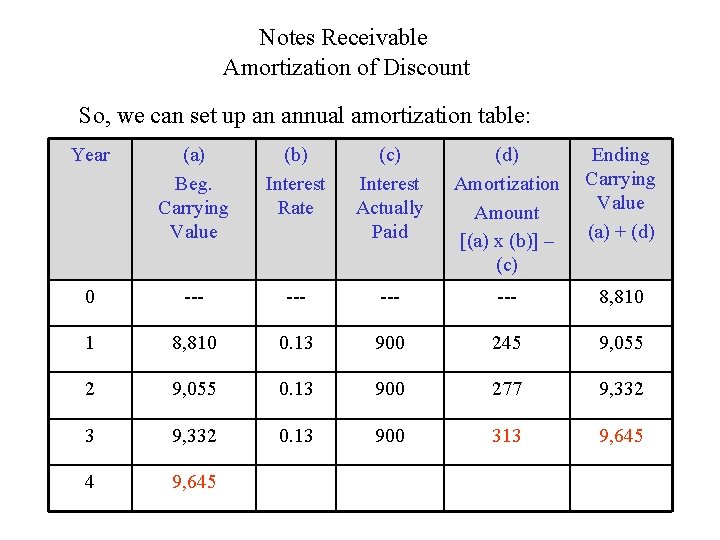
Notes Receivable Amortization of Discount So, we can set up an annual amortization table: Year (a) Beg. Carrying Value (b) Interest Rate (c) Interest Actually Paid (d) Amortization Amount [(a) x (b)] – (c) Ending Carrying Value (a) + (d) 0 --- --- 8, 810 1 8, 810 0. 13 900 245 9, 055 2 9, 055 0. 13 900 277 9, 332 3 9, 332 0. 13 900 313 9, 645 4 9, 645
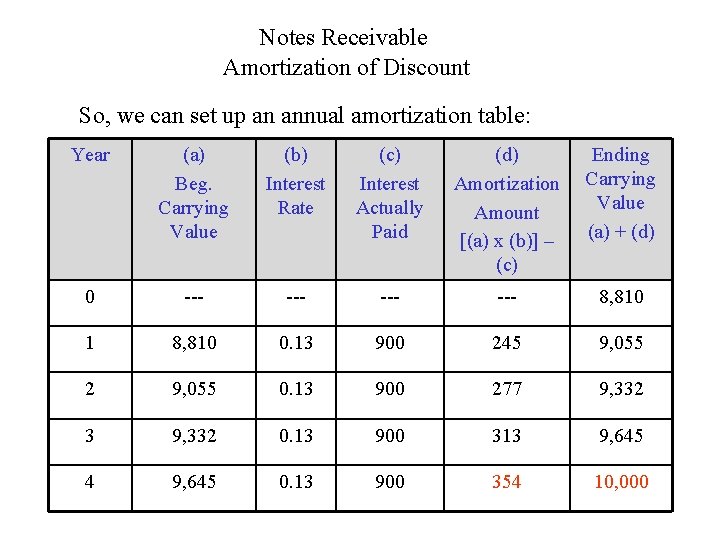
Notes Receivable Amortization of Discount So, we can set up an annual amortization table: Year (a) Beg. Carrying Value (b) Interest Rate (c) Interest Actually Paid (d) Amortization Amount [(a) x (b)] – (c) Ending Carrying Value (a) + (d) 0 --- --- 8, 810 1 8, 810 0. 13 900 245 9, 055 2 9, 055 0. 13 900 277 9, 332 3 9, 332 0. 13 900 313 9, 645 4 9, 645 0. 13 900 354 10, 000
Notes Receivable Amortization of Discount Actual interest revenue reported each year is equal to actual interest paid + the amount of discount amortized (or – the amount of premium amortized)
Notes Receivable Amortization of Discount Actual interest revenue reported each year is equal to actual interest paid + the amount of discount amortized (or – the amount of premium amortized) Journal entry to record receipt of year 1 interest:
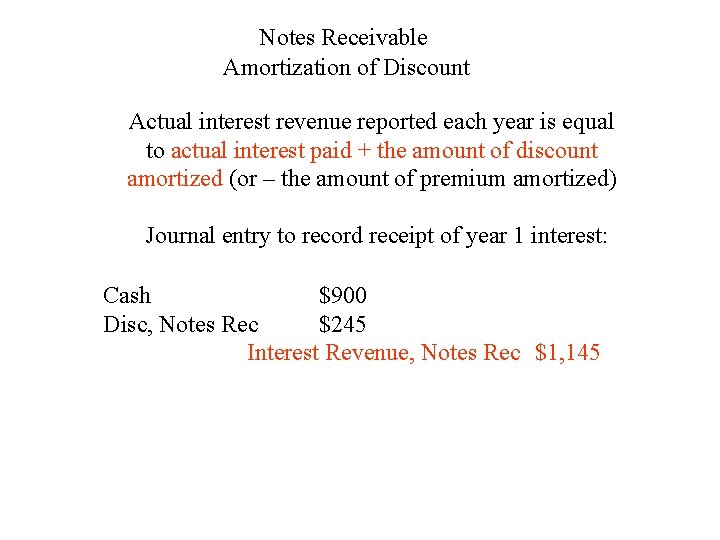
Notes Receivable Amortization of Discount Actual interest revenue reported each year is equal to actual interest paid + the amount of discount amortized (or – the amount of premium amortized) Journal entry to record receipt of year 1 interest: Cash $900 Disc, Notes Rec $245 Interest Revenue, Notes Rec $1, 145
- Slides: 65