
Not FDIC Insured May Lose Value No Bank
Not FDIC Insured | May Lose Value | No Bank Guarantee
Investing involves risk including possible loss of principal. Information is current as of the date of this material. Any opinions expressed herein are from a third party and are given in good faith, are subject to change without notice, and are considered correct as of the stated date of their issue. Merrill Lynch, Pierce, Fenner & Smith Incorporated is not a tax or legal advisor. Clients should consult a personal tax or legal advisor prior to making any tax or legal related investment decisions. Bank of America Corporation (“Bank of America”) is a financial holding company that, through its subsidiaries and affiliated companies, provides banking and investment products and other financial services. Merrill makes available products and services offered by Merrill Lynch, Pierce, Fenner & Smith Incorporated (“MLPF&S”), a registered broker-dealer and Member SIPC, and other subsidiaries of Bank of America Corporation. Merrill Lynch Life Agency is a licensed insurance agency and a wholly owned subsidiary of Bank of America Corporation. Merrill offers a broad range of brokerage, investment advisory and other services. There are important differences between brokerage and investment advisory services, including the type of advice and assistance provided, the fees charged, and the rights and obligations of the parties. It is important to understand the differences, particularly when determining which service or services to select. The views and opinions expressed in this presentation are not necessarily those of Bank of America Corporation; Merrill Lynch, Pierce, Fenner & Smith Incorporated; or any affiliates. Merrill has not participated in preparing this presentation and accepts no responsibility for the accuracy of the information contained herein. Nothing discussed or suggested in these materials should be construed as permission to supersede or circumvent any Bank of America, Merrill Lynch, Pierce, Fenner & Smith Incorporated policies, procedures, rules, and guidelines. Investment products offered through MLPF&S and insurance and annuity products offered through Merrill Lynch Life Agency Inc. : Are Not FDIC Insured May Lose Value Are Not Bank Guaranteed Are Not Insured by Any Federal Government Agency Are Not Deposits Are Not a Condition to Any Banking Service or Activity
Securing Social Security Today, Tomorrow & for the Future Presenter Name (Arial 14 pt. Bold) Title (Arial 14 pt. ) Presenter Name Title Month XX, 201 X (Arial 12 pt. )
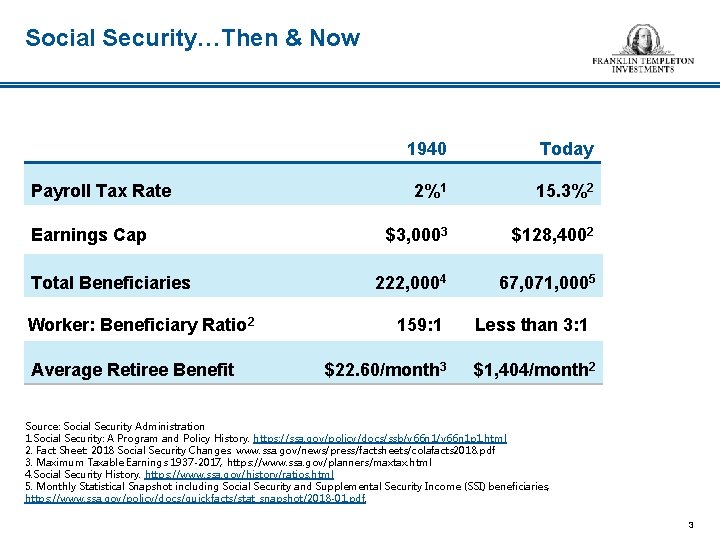
Social Security…Then & Now Payroll Tax Rate Earnings Cap Total Beneficiaries Worker: Beneficiary Ratio 2 Average Retiree Benefit 1940 Today 2%1 15. 3%2 $3, 0003 $128, 4002 222, 0004 67, 071, 0005 159: 1 $22. 60/month 3 Less than 3: 1 $1, 404/month 2 Source: Social Security Administration 1. Social Security: A Program and Policy History. https: //ssa. gov/policy/docs/ssb/v 66 n 1 p 1. html 2. Fact Sheet: 2018 Social Security Changes. www. ssa. gov/news/press/factsheets/colafacts 2018. pdf 3. Maximum Taxable Earnings 1937 -2017, https: //www. ssa. gov/planners/maxtax. html 4. Social Security History. https: //www. ssa. gov/history/ratios. html 5. Monthly Statistical Snapshot including Social Security and Supplemental Security Income (SSI) beneficiaries, https: //www. ssa. gov/policy/docs/quickfacts/stat_snapshot/2018 -01. pdf. 3
What is Social Security? A Government. Sponsored Lifetime Retirement Income Inflation-Adjusted 4
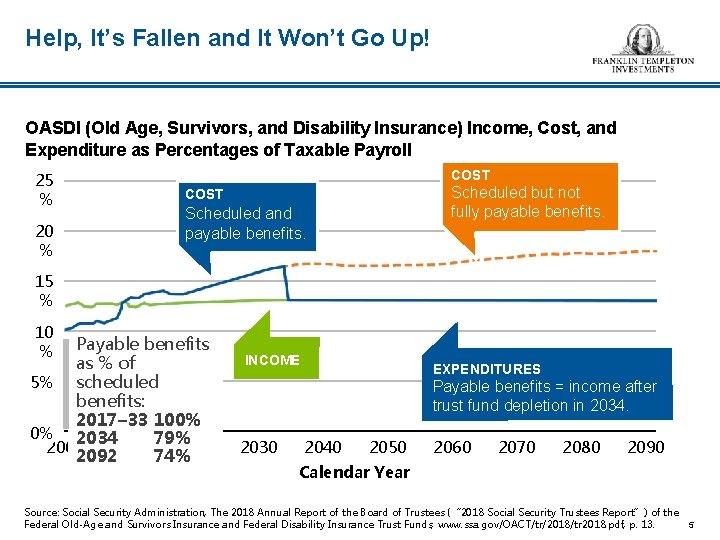
Help, It’s Fallen and It Won’t Go Up! OASDI (Old Age, Survivors, and Disability Insurance) Income, Cost, and Expenditure as Percentages of Taxable Payroll 25 % 20 % COST Scheduled but not fully payable benefits. COST Scheduled and payable benefits. 15 % 10 % Payable benefits as % of 5% scheduled benefits: 2017– 33 100% 0% 2034 79% 2000 2010 2020 2092 74% INCOME EXPENDITURES Payable benefits = income after trust fund depletion in 2034. 2030 2040 2050 2060 2070 2080 2090 Calendar Year Source: Social Security Administration, The 2018 Annual Report of the Board of Trustees (“ 2018 Social Security Trustees Report”) of the Federal Old-Age and Survivors Insurance and Federal Disability Insurance Trust Funds, www. ssa. gov/OACT/tr/2018/tr 2018. pdf, p. 13. 5
Social Security’s Financial Condition May Not Be as Dire as You Might Think “ For the 75 -year projection period, the actuarial deficit is 2. 84 percent of taxable payroll, 0. 01 percentage point larger than in last year’s report. ” 1 2018 Social Security Trustees Report 1. 2018 Social Security Trustee’s Report, page 4. 6
Choosing the RIGHT AGE TO FILE Is More Important Now… “ …for a 65 -year old couple of average health, there is a 50% chance one of them will live to age 93 and a 1 in 4 chance that one of them will see age 97… [C]laiming Social Security early. . . would lock them into smaller payouts for potentially 30 years or more. ” 1 LIMRA Secure Retirement Institute “ If you are in good health and you can afford to wait, my advice is that you should wait as long as possible. The greater is your guaranteed lifetime income, the easier it will be to organize your retirement budget, and the less you will worry about living ‘too long’. ” 2 Richard Thaler, Ph. D University of Chicago, NY Times columnist 1. LIMRA Secure Retirement Institute, “When Planning for Retirement, 90 is the New 70, ” January 20, 2016, http: //www. limra. com/Posts/PR/Industry_Trends_Blog/When_Planning _for_Retirement, _90_is_the_new_70. aspx. 2. Thaler, Richard H. , “Getting the Most Out of Social Security”: The New York Times, July 16, 2011, http: //www. nytimes. com/2011/07/17/business/economy/when-the-wait-for-social-security-checks-is-worth-it. html. 7
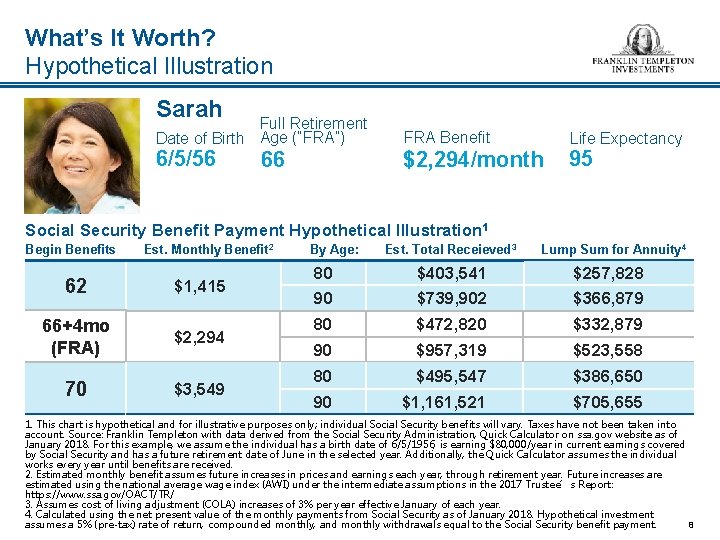
What’s It Worth? Hypothetical Illustration Sarah Full Retirement Date of Birth Age (“FRA”) 6/5/56 66 FRA Benefit $2, 294/month Life Expectancy 95 Social Security Benefit Payment Hypothetical Illustration 1 Begin Benefits Est. Monthly Benefit 2 62 $1, 415 66+4 mo (FRA) $2, 294 70 $3, 549 By Age: Est. Total Receieved 3 Lump Sum for Annuity 4 80 90 $403, 541 $739, 902 $257, 828 $366, 879 80 $472, 820 $332, 879 90 $957, 319 $523, 558 80 $495, 547 $386, 650 90 $1, 161, 521 $705, 655 1. This chart is hypothetical and for illustrative purposes only; individual Social Security benefits will vary. Taxes have not been taken into account. Source: Franklin Templeton with data derived from the Social Security Administration, Quick Calculator on ssa. gov website as of January 2018. For this example, we assume the individual has a birth date of 6/5/1956, is earning $80, 000/year in current earnings covered by Social Security and has a future retirement date of June in the selected year. Additionally, the Quick Calculator assumes the individual works every year until benefits are received. 2. Estimated monthly benefit assumes future increases in prices and earnings each year, through retirement year. Future increases are estimated using the national average wage index (AWI) under the intermediate assumptions in the 2017 Trustee’s Report: https: //www. ssa. gov/OACT/TR/ 3. Assumes cost of living adjustment (COLA) increases of 3% per year effective January of each year. 4. Calculated using the net present value of the monthly payments from Social Security as of January 2018. Hypothetical investment assumes a 5% (pre-tax) rate of return, compounded monthly, and monthly withdrawals equal to the Social Security benefit payment. 8
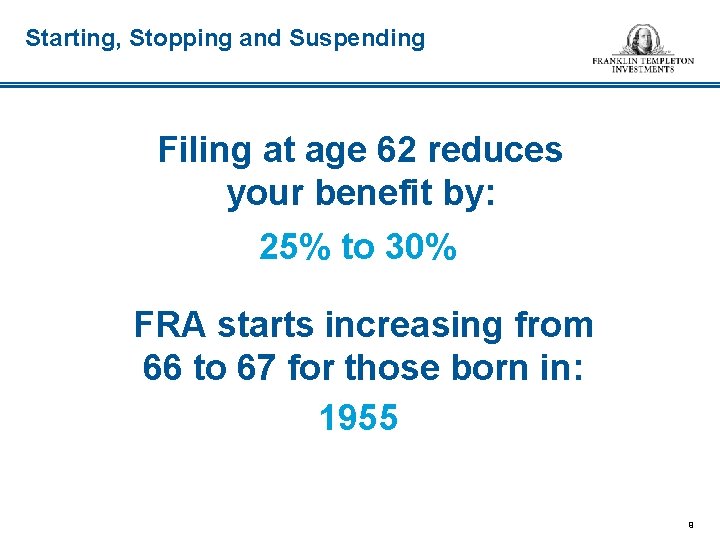
Starting, Stopping and Suspending Filing at age 62 reduces your benefit by: 25% to 30% FRA starts increasing from 66 to 67 for those born in: 1955 9
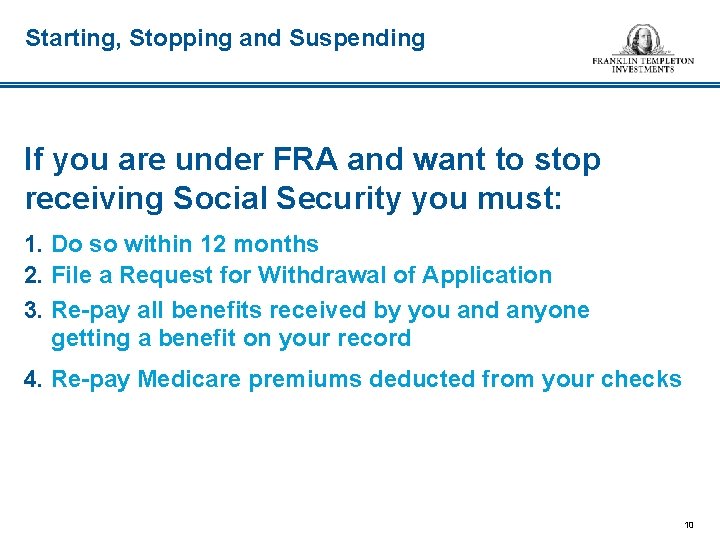
Starting, Stopping and Suspending If you are under FRA and want to stop receiving Social Security you must: 1. Do so within 12 months 2. File a Request for Withdrawal of Application 3. Re-pay all benefits received by you and anyone getting a benefit on your record 4. Re-pay Medicare premiums deducted from your checks 10
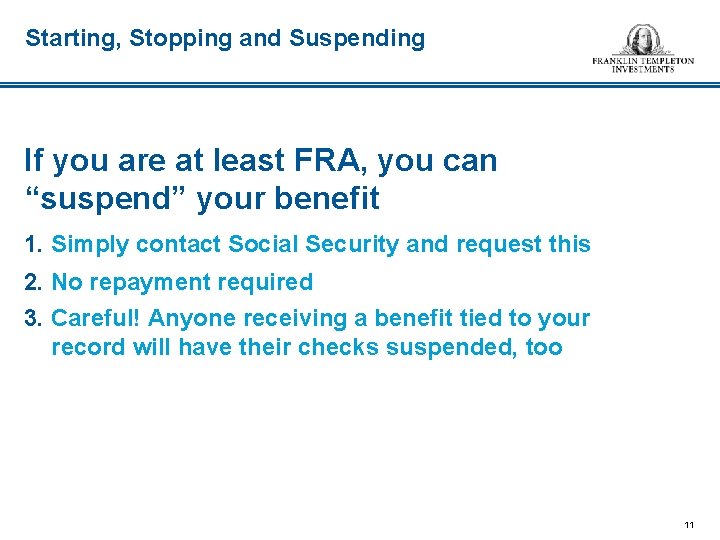
Starting, Stopping and Suspending If you are at least FRA, you can “suspend” your benefit 1. Simply contact Social Security and request this 2. No repayment required 3. Careful! Anyone receiving a benefit tied to your record will have their checks suspended, too 11
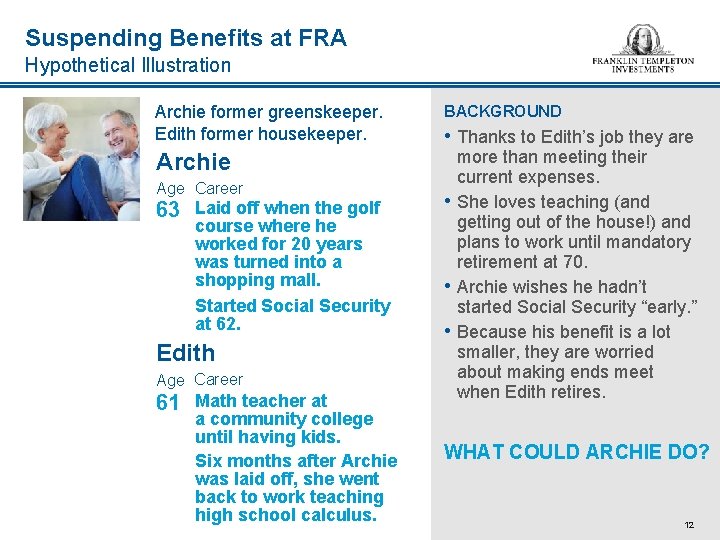
Suspending Benefits at FRA Hypothetical Illustration Archie former greenskeeper. Edith former housekeeper. Archie Age Career 63 Laid off when the golf course where he worked for 20 years was turned into a shopping mall. Started Social Security at 62. Edith Age Career 61 Math teacher at a community college until having kids. Six months after Archie was laid off, she went back to work teaching high school calculus. BACKGROUND • Thanks to Edith’s job they are more than meeting their current expenses. • She loves teaching (and getting out of the house!) and plans to work until mandatory retirement at 70. • Archie wishes he hadn’t started Social Security “early. ” • Because his benefit is a lot smaller, they are worried about making ends meet when Edith retires. WHAT COULD ARCHIE DO? 12
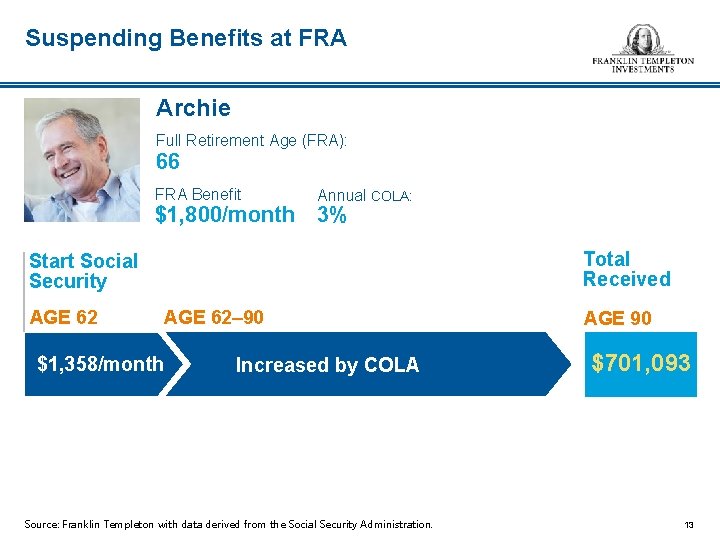
Suspending Benefits at FRA Archie Full Retirement Age (FRA): 66 FRA Benefit Annual COLA: $1, 800/month 3% Total Received Start Social Security AGE 62 $1, 358/month AGE 62– 90 Increased by COLA Source: Franklin Templeton with data derived from the Social Security Administration. AGE 90 $701, 093 13
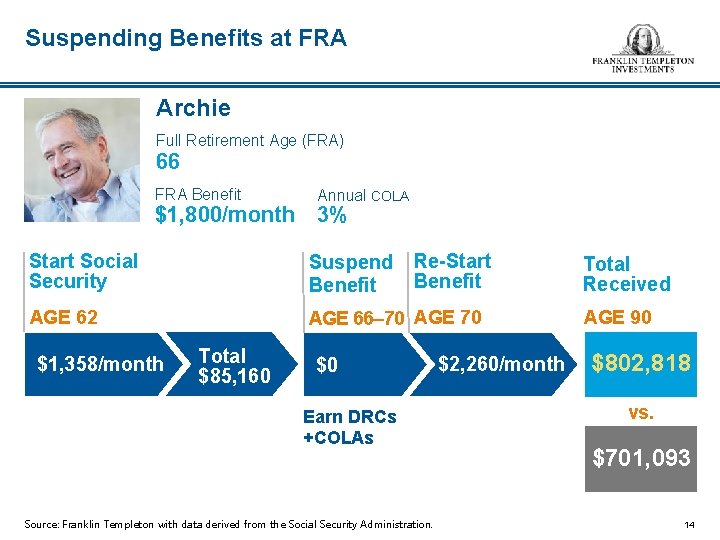
Suspending Benefits at FRA Archie Full Retirement Age (FRA) 66 FRA Benefit Annual COLA $1, 800/month 3% Re-Start Benefit Start Social Security Suspend Benefit AGE 62 AGE 66– 70 AGE 70 $1, 358/month Total $85, 160 $0 Earn DRCs +COLAs Source: Franklin Templeton with data derived from the Social Security Administration. $2, 260/month Total Received AGE 90 $802, 818 vs. $701, 093 14
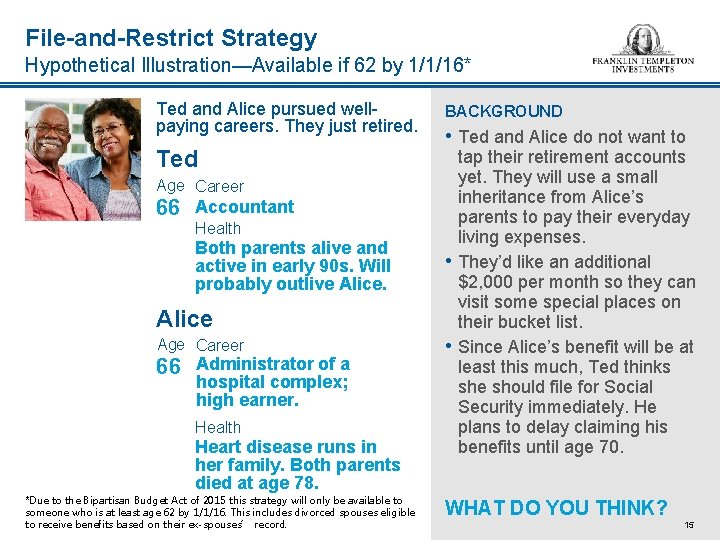
File-and-Restrict Strategy Hypothetical Illustration—Available if 62 by 1/1/16* Ted and Alice pursued wellpaying careers. They just retired. Ted Age Career 66 Accountant Health Both parents alive and active in early 90 s. Will probably outlive Alice Age Career 66 Administrator of a hospital complex; high earner. Health Heart disease runs in her family. Both parents died at age 78. *Due to the Bipartisan Budget Act of 2015 this strategy will only be available to someone who is at least age 62 by 1/1/16. This includes divorced spouses eligible to receive benefits based on their ex-spouses’ record. BACKGROUND • Ted and Alice do not want to tap their retirement accounts yet. They will use a small inheritance from Alice’s parents to pay their everyday living expenses. • They’d like an additional $2, 000 per month so they can visit some special places on their bucket list. • Since Alice’s benefit will be at least this much, Ted thinks she should file for Social Security immediately. He plans to delay claiming his benefits until age 70. WHAT DO YOU THINK? 15
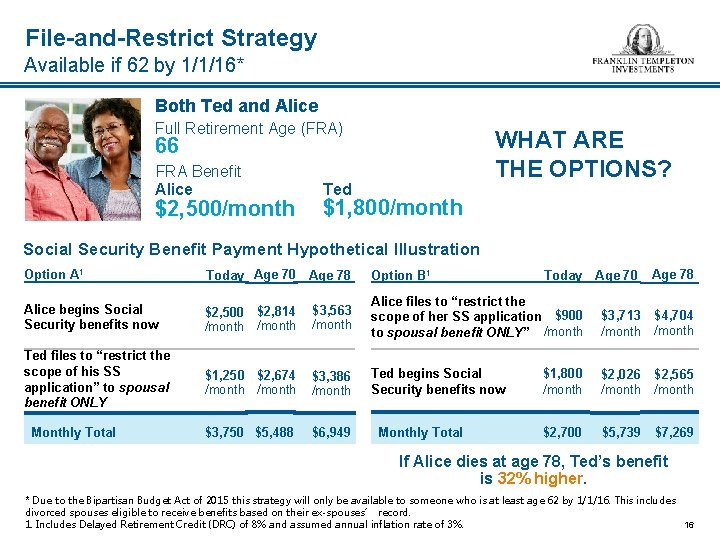
File-and-Restrict Strategy Available if 62 by 1/1/16* Both Ted and Alice Full Retirement Age (FRA) WHAT ARE THE OPTIONS? 66 FRA Benefit Alice $2, 500/month Ted $1, 800/month Social Security Benefit Payment Hypothetical Illustration Option A 1 Today Age 70 Age 78 70 Alice begins Social Security benefits now $2, 500 $2, 814 /month $3, 563 /month Alice files to “restrict the scope of her SS application” $900 to spousal benefit ONLY” /month $3, 713 /month $4, 704 /month Ted files to “restrict the scope of his SS application” to spousal benefit ONLY $1, 250 $2, 674 /month $3, 386 /month Ted begins Social Security benefits now $1, 800 /month $2, 026 /month $2, 565 /month $3, 750 $5, 488 $6, 949 $2, 700 $5, 739 $7, 269 Monthly Total Option B 1 Monthly Total Today Age 70 Age 78 If Alice dies at age 78, Ted’s benefit is 32% higher. * Due to the Bipartisan Budget Act of 2015 this strategy will only be available to someone who is at least age 62 by 1/1/16. This includes divorced spouses eligible to receive benefits based on their ex-spouses’ record. 1. Includes Delayed Retirement Credit (DRC) of 8% and assumed annual inflation rate of 3%. 16
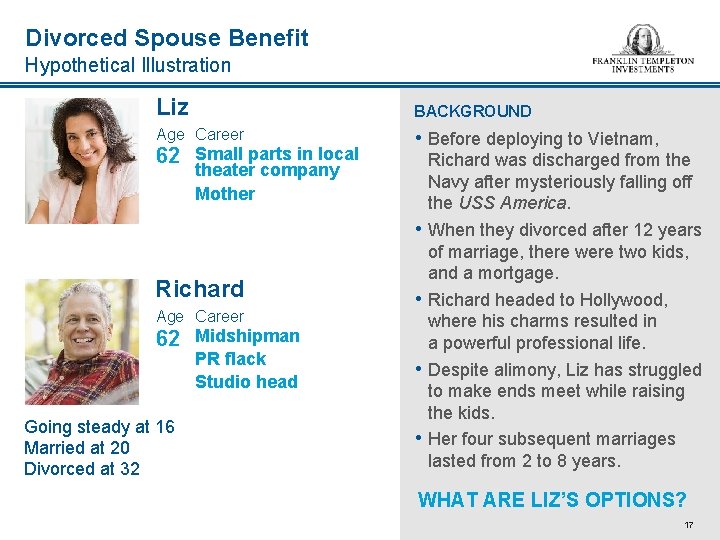
Divorced Spouse Benefit Hypothetical Illustration Liz BACKGROUND Age Career 62 Small parts in local theater company Mother • Before deploying to Vietnam, • Richard Age Career • 62 Midshipman PR flack Studio head Going steady at 16 Married at 20 Divorced at 32 • • Richard was discharged from the Navy after mysteriously falling off the USS America. When they divorced after 12 years of marriage, there were two kids, and a mortgage. Richard headed to Hollywood, where his charms resulted in a powerful professional life. Despite alimony, Liz has struggled to make ends meet while raising the kids. Her four subsequent marriages lasted from 2 to 8 years. WHAT ARE LIZ’S OPTIONS? 17
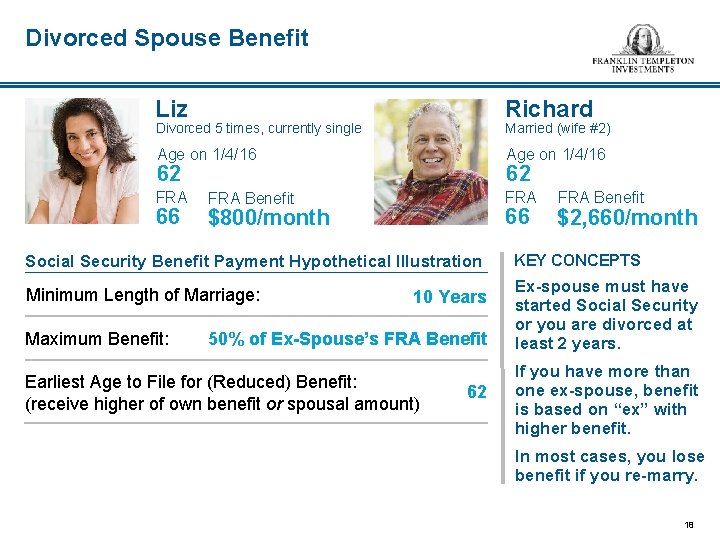
Divorced Spouse Benefit Liz Richard Age on 1/4/16 FRA Married (wife #2) Divorced 5 times, currently single 62 62 66 FRA Benefit 66 $800/month Social Security Benefit Payment Hypothetical Illustration Minimum Length of Marriage: Maximum Benefit: 10 Years 50% of Ex-Spouse’s FRA Benefit Earliest Age to File for (Reduced) Benefit: (receive higher of own benefit or spousal amount) 62 FRA Benefit $2, 660/month KEY CONCEPTS Ex-spouse must have started Social Security or you are divorced at least 2 years. If you have more than one ex-spouse, benefit is based on “ex” with higher benefit. In most cases, you lose benefit if you re-marry. 18
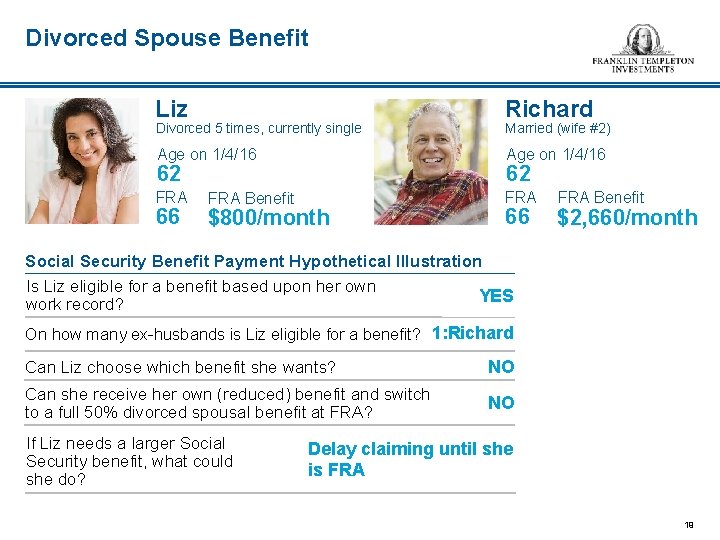
Divorced Spouse Benefit Liz Richard Age on 1/4/16 FRA Divorced 5 times, currently single 62 62 66 Married (wife #2) FRA Benefit $800/month 66 FRA Benefit $2, 660/month Social Security Benefit Payment Hypothetical Illustration Is Liz eligible for a benefit based upon her own YES work record? On how many ex-husbands is Liz eligible for a benefit? 1: Richard Can Liz choose which benefit she wants? NO Can she receive her own (reduced) benefit and switch to a full 50% divorced spousal benefit at FRA? NO If Liz needs a larger Social Security benefit, what could she do? Delay claiming until she is FRA 19
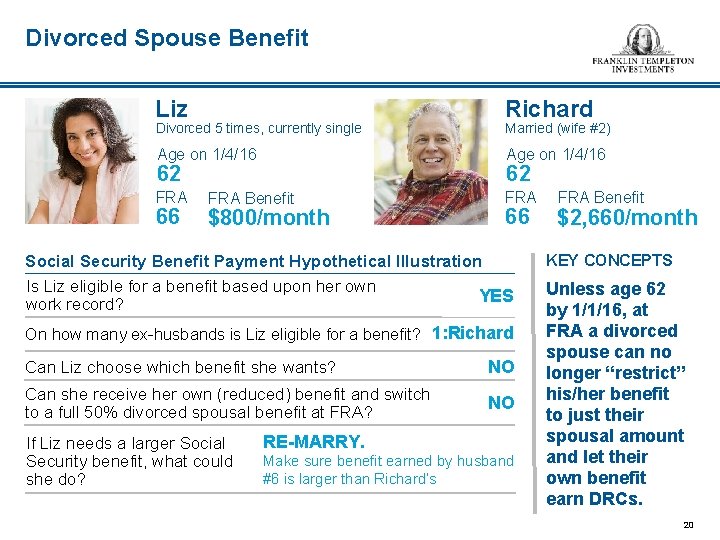
Divorced Spouse Benefit Liz Richard Age on 1/4/16 FRA Divorced 5 times, currently single 62 62 66 Married (wife #2) FRA Benefit $800/month 66 Social Security Benefit Payment Hypothetical Illustration Is Liz eligible for a benefit based upon her own YES work record? On how many ex-husbands is Liz eligible for a benefit? 1: Richard Can Liz choose which benefit she wants? NO Can she receive her own (reduced) benefit and switch to a full 50% divorced spousal benefit at FRA? NO If Liz needs a larger Social Security benefit, what could she do? RE-MARRY. Make sure benefit earned by husband #6 is larger than Richard’s FRA Benefit $2, 660/month KEY CONCEPTS Unless age 62 by 1/1/16, at FRA a divorced spouse can no longer “restrict” his/her benefit to just their spousal amount and let their own benefit earn DRCs. 20
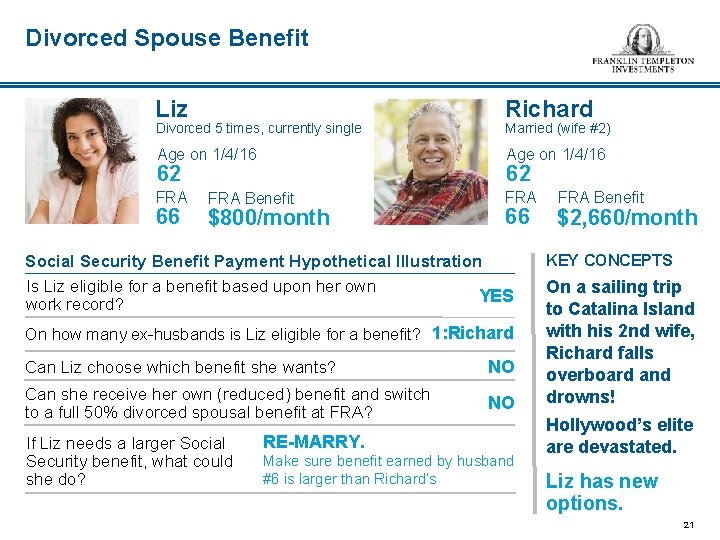
Divorced Spouse Benefit Liz Richard Age on 1/4/16 FRA Divorced 5 times, currently single 62 62 66 Married (wife #2) FRA Benefit $800/month 66 Social Security Benefit Payment Hypothetical Illustration Is Liz eligible for a benefit based upon her own YES work record? On how many ex-husbands is Liz eligible for a benefit? 1: Richard Can Liz choose which benefit she wants? NO Can she receive her own (reduced) benefit and switch to a full 50% divorced spousal benefit at FRA? NO If Liz needs a larger Social Security benefit, what could she do? RE-MARRY. Make sure benefit earned by husband #6 is larger than Richard’s FRA Benefit $2, 660/month KEY CONCEPTS On a sailing trip to Catalina Island with his 2 nd wife, Richard falls overboard and drowns! Hollywood’s elite are devastated. Liz has new options. 21
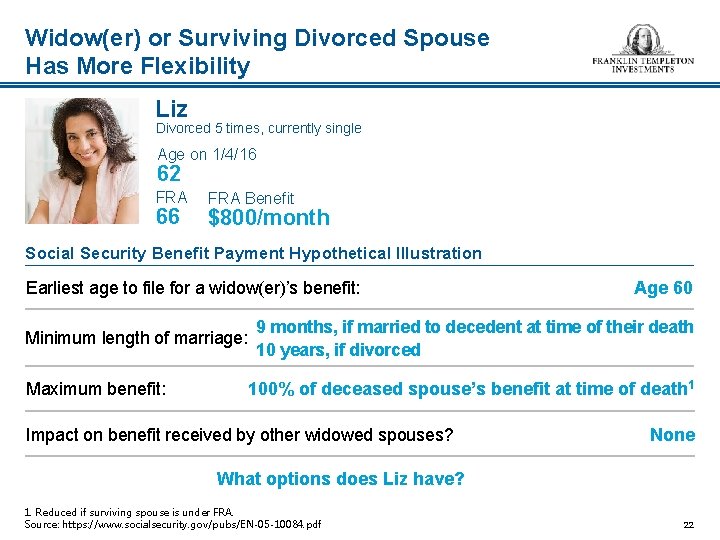
Widow(er) or Surviving Divorced Spouse Has More Flexibility Liz Divorced 5 times, currently single Age on 1/4/16 62 FRA 66 FRA Benefit $800/month Social Security Benefit Payment Hypothetical Illustration Earliest age to file for a widow(er)’s benefit: Minimum length of marriage: Maximum benefit: Age 60 9 months, if married to decedent at time of their death 10 years, if divorced 100% of deceased spouse’s benefit at time of death 1 Impact on benefit received by other widowed spouses? None What options does Liz have? 1. Reduced if surviving spouse is under FRA. Source: https: //www. socialsecurity. gov/pubs/EN-05 -10084. pdf 22
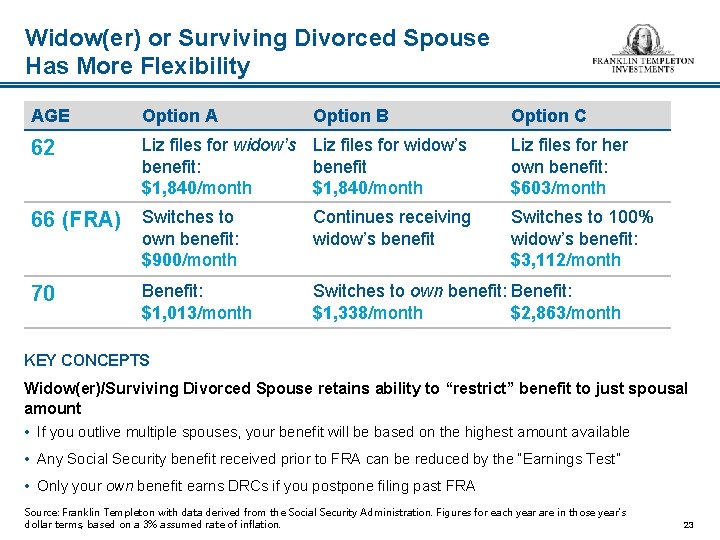
Widow(er) or Surviving Divorced Spouse Has More Flexibility AGE Option A 62 Liz files for widow’s benefit: benefit $1, 840/month 66 (FRA) Switches to own benefit: $900/month 70 Benefit: $1, 013/month Option B Continues receiving widow’s benefit Option C Liz files for her own benefit: $603/month Switches to 100% widow’s benefit: $3, 112/month Switches to own benefit: Benefit: $1, 338/month $2, 863/month KEY CONCEPTS Widow(er)/Surviving Divorced Spouse retains ability to “restrict” benefit to just spousal amount • If you outlive multiple spouses, your benefit will be based on the highest amount available • Any Social Security benefit received prior to FRA can be reduced by the “Earnings Test” • Only your own benefit earns DRCs if you postpone filing past FRA Source: Franklin Templeton with data derived from the Social Security Administration. Figures for each year are in those year's dollar terms, based on a 3% assumed rate of inflation. 23
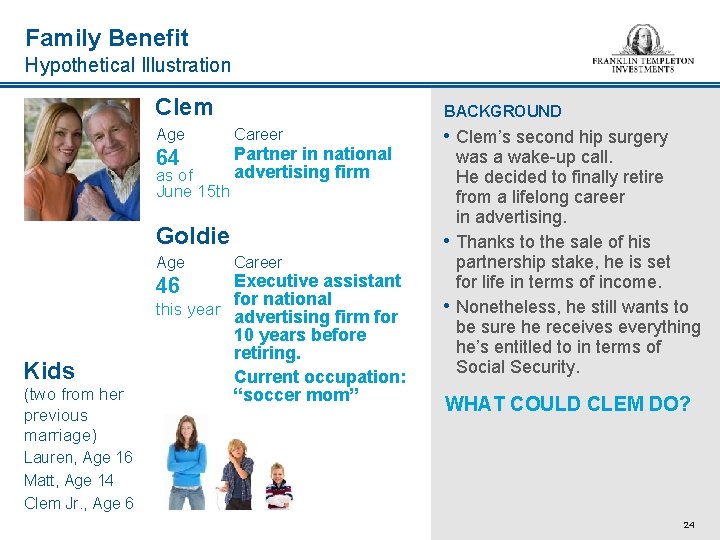
Family Benefit Hypothetical Illustration Clem BACKGROUND Age Career 64 Partner in national advertising firm as of June 15 th Goldie Age Executive assistant for national this year advertising firm for 10 years before retiring. Current occupation: “soccer mom” 46 Kids (two from her previous marriage) Career • Clem’s second hip surgery was a wake-up call. He decided to finally retire from a lifelong career in advertising. • Thanks to the sale of his partnership stake, he is set for life in terms of income. • Nonetheless, he still wants to be sure he receives everything he’s entitled to in terms of Social Security. WHAT COULD CLEM DO? Lauren, Age 16 Matt, Age 14 Clem Jr. , Age 6 24
Family Benefit Social Security Benefit Payment Hypothetical Illustration Clem files for Social Security to begin Impact on Family Benefit when Lauren turns 18? At age 66, Clem begins consulting part-time. He suspends his Social Security benefit so he can earn DRCs. What happens? 1. Reduced if surviving spouse is under FRA. Source: https: //www. socialsecurity. gov/pubs/EN-05 -10084. pdf 25
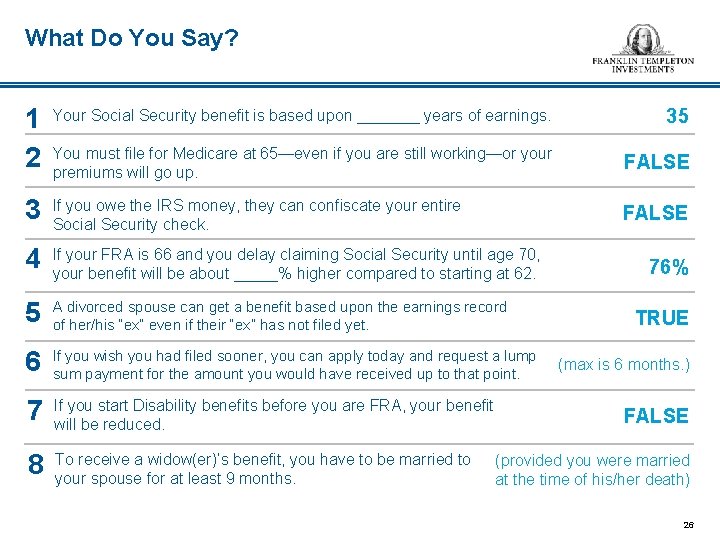
What Do You Say? 1 2 Your Social Security benefit is based upon _______ years of earnings. You must file for Medicare at 65—even if you are still working—or your premiums will go up. FALSE TRUE / FALSE 3 If you owe the IRS money, they can confiscate your entire Social Security check. FALSE TRUE / FALSE 4 If your FRA is 66 and you delay claiming Social Security until age 70, your benefit will be about _____% higher compared to starting at 62. 5 A divorced spouse can get a benefit based upon the earnings record of her/his “ex” even if their “ex” has not filed yet. 6 If you wish you had filed sooner, you can apply today and request a lump sum payment for the amount you would have received up to that point. 7 If you start Disability benefits before you are FRA, your benefit will be reduced. 8 To receive a widow(er)’s benefit, you have to be married to your spouse for at least 9 months. 35 34% 52% 76% TRUE / FALSE TRUE (max is 6 FALSE months. ) TRUE / FALSE (provided you were married TRUE / FALSE at the time of his/her death) 26
Franklin Templeton Distributors, Inc. One Franklin Parkway San Mateo, California 94403 -1906 franklintempleton. com The presenter’s comments, opinions and analyses are for informational purposes only and should not be considered individual investment advice or recommendations to invest in any security or to adopt any investment strategy. Opinions and analyses are rendered as of the date of the posting and may change without notice. Certified Financial Planner Board of Standards Inc. owns the certification marks CFP ®, CERTIFIED FINANCIAL PLANNER™, CFP ® (with plaque design) and CFP® (with flame design) in the U. S. , which it awards to individuals who successfully complete CFP Board’s initial and ongoing certification requirements. This communication is general in nature and provided for educational and informational purposes only. It should not be considered or relied upon as legal, tax or investment advice or an investment recommendation, or as a substitute for legal or tax counsel. How and when to claim Social Security benefits is a personal decision, and can depend on a number of factors—such as your financial and individual situation, health, family longevity, and tax and social security laws which can be complex and subject to frequent change. Any investment products or services named herein are for illustrative purposes only, and should not be considered an offer to buy or sell, or an investment recommendation for, any specific security, strategy or investment product or service. Always consult a qualified professional or your own independent financial advisor for personalized advice or investment recommendations tailored to your specific goals, individual situation, and risk tolerance. Franklin Templeton Investments (FTI) does not provide legal or tax advice. FTI is not responsible for content on the Social Security Administration’s website. Federal and state laws and regulations are complex and subject to change, which can materially impact your results. FTI cannot guarantee that such information is accurate, complete or timely; and disclaims any liability arising out of your use of, or any tax position taken in reliance on, such information. All financial decisions and investments involve risk, including possible loss of principal. © 2018 Franklin Templeton Investments. All rights reserved. ML 18 -007011 RSS CUPPT 09/18
- Slides: 28